
 Greenhouse and Smart Greenhouse Market | 2026-2036
Greenhouse and Smart Greenhouse Market Size, Share, and Industry Trends Forecast 2026-2036
Greenhouse and Smart Greenhouse Market Insights
The EU Green Deal is rebalancing capital allocation toward energy-efficient protected agriculture across member states. Certhon leverages its Dutch engineering heritage to dominate large-scale glasshouse integration in Europe. Netafim anchors precision irrigation within smart greenhouse portfolios through its drip-system expertise. Nexus Corporation extends its North American footprint via modular greenhouse structures tailored to commercial growers.
Greenhouse and smart greenhouse infrastructure comprises enclosed structures with transparent or translucent covering materials—glass, polycarbonate, or polyethylene—engineered to trap solar radiation and maintain controlled microclimates for plant cultivation, typically operating at 18-28°C with 60-80% relative humidity for optimal photosynthetic efficiency. Hydroponics technology leads the technology segment as commercial growers prioritize water-use efficiency and nutrient precision in recirculating systems. Soil-based cultivation retains volume dominance among agricultural producers transitioning gradually to substrate methods. Glasshouse installations command premium margins due to longevity and superior light transmission, while polycarbonate structures compete on cost and thermal insulation in semi-permanent configurations.
The EPA regulates agricultural runoff and energy consumption in US greenhouse operations, while REACH governs material safety for European covering and coating chemistries. EFSA standards on pesticide residues shape crop protection protocols inside controlled environments, directly influencing technology selection by commercial growers. Stakeholders must monitor evolving carbon-accounting rules for heated glasshouses, as regulatory compliance will determine market access and operating cost structures in key production zones.
Market Dynamics
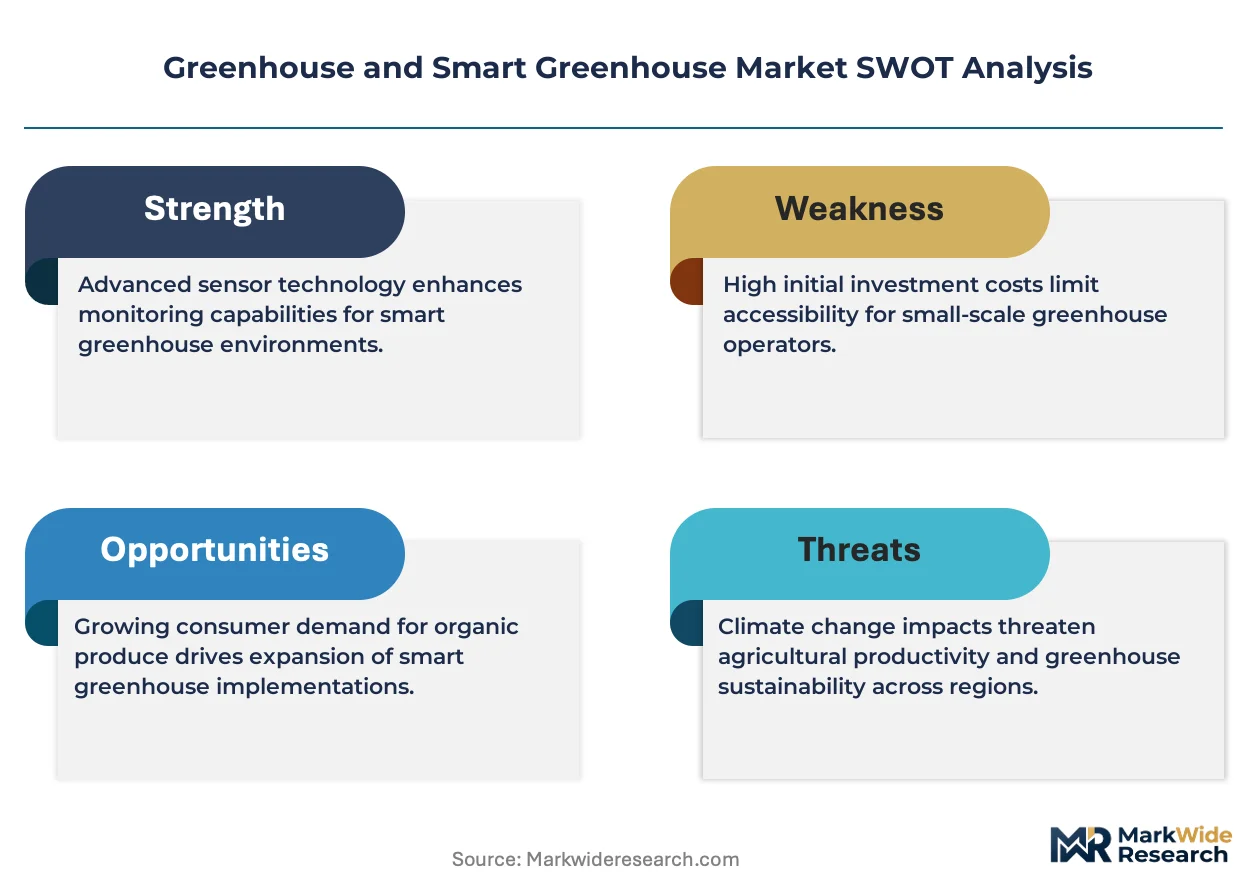
Sensor-integrated environmental control systems are displacing manual ventilation across glasshouse operations, compressing operational labor while tightening climate precision. This automation wave is redrawing capital allocation and vendor relationships throughout protected agriculture supply chains.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:The policy framework mandates 25% organic farming share and pesticide reduction targets, channeling subsidies toward climate-controlled protected cultivation in member states.
- Hydroponics recirculation technology:Water-stressed agricultural regions in Spain and Israel are retrofitting soil-based facilities with closed-loop nutrient delivery, cutting water use intensity by half versus conventional methods.
- Almería solar-thermal clusters:Concentrated greenhouse development in this Spanish province leverages abundant insolation to supply Northern European retail chains with year-round fresh produce.
Market Restraints
- Natural gas price volatility:Heated glasshouse operations in the Netherlands and Belgium face margin compression from fossil fuel input cost swings, forcing operational curtailments during price spikes.
- Polycarbonate supply concentration:Asian petrochemical producers dominate resin supply for semi-permanent greenhouse coverings, exposing European installers to freight cost and currency fluctuation risks.
- Light transmission limitations:Polyethylene film coverings degrade photon delivery versus glass alternatives, constraining crop photosynthetic efficiency in high-value floriculture applications.
Strategic Opportunities
- Morocco and Egypt underpenetrated zones:Proximity to European markets and favorable winter insolation profiles position North African nations for export-oriented greenhouse development.
- AI-driven predictive climate control:Machine learning algorithms converging with IoT sensor networks enable anticipatory environmental adjustments, reducing energy waste in Dutch Venlo-style installations.
- Carbon-accounting compliance services:Evolving EU emissions reporting rules for heated agriculture create white space for monitoring and verification technology providers serving glasshouse operators.
Industry Challenges
- Mechatronics technician scarcity:Automated greenhouse systems require maintenance staff fluent in both horticultural protocols and industrial control systems, a skill combination lacking in regional labor pools.
- Legacy soil-to-substrate conversion capex:Established agricultural producers face sunk-cost dilemmas when modernizing drainage and irrigation infrastructure for hydroponic migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greenhouse and Smart Greenhouse Market |
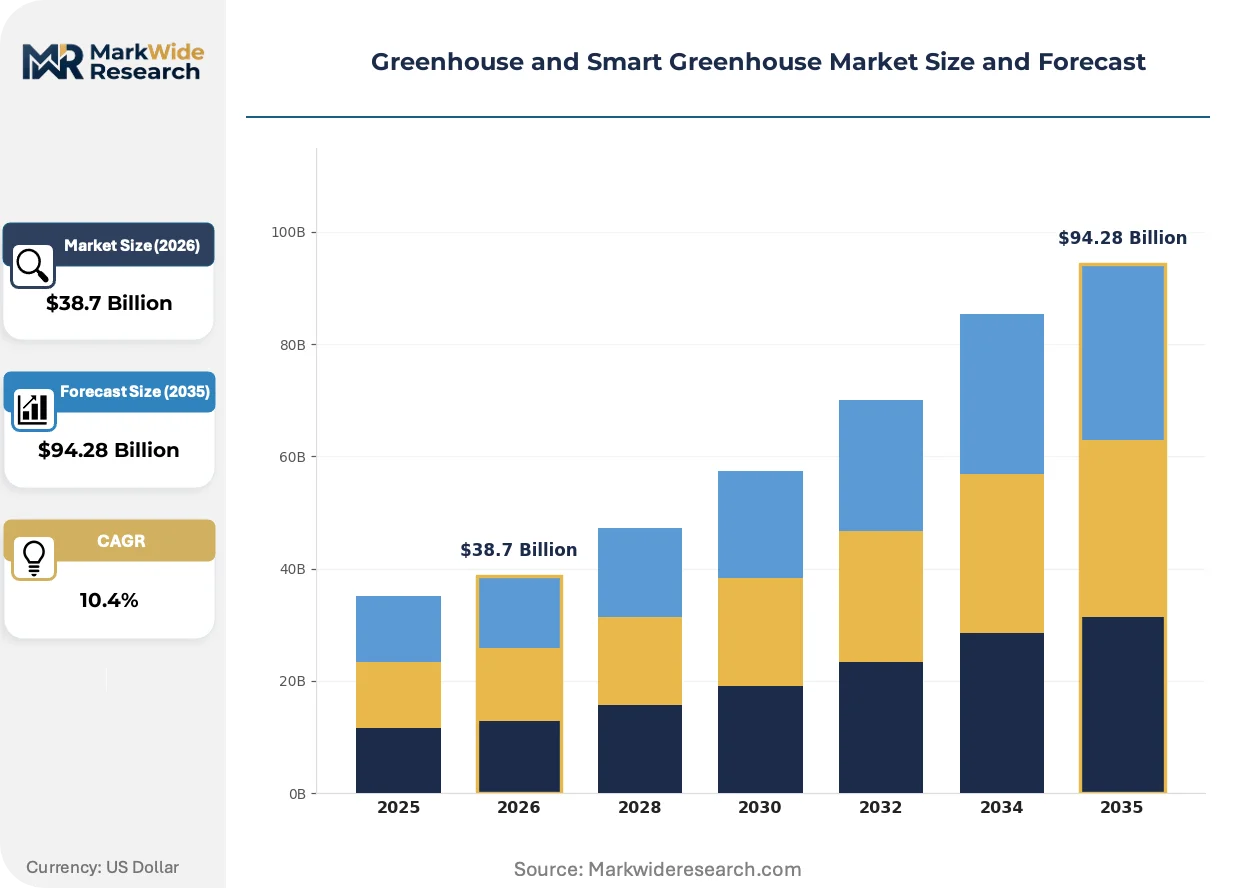
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $94.28 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glasshouse, Polycarbonate, Tunnel, Shadehouse Technology: Hydroponics, Aeroponics, Aquaponics, Soil-based Cultivation End User: Commercial Growers, Research Institutions, Home Gardeners, Agricultural Producers Installation: Permanent, Semi-permanent, Movable, Modular |
| Companies Covered | Nexus Corporation, Argus Control Systems Limited, Certhon, Rough Brothers Inc., GreenTech Agro LLC, Netafim, Heliospectra AB, LumiGrow, Sensaphone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greenhouse and Smart Greenhouse Market Trends and Innovations
Digital twin technology and edge computing architectures are rewiring how commercial growers monitor and intervene in crop environments. These shifts are compressing response latency and enabling predictive rather than reactive cultivation management.
Photoselective glass coatings are absorbing specific wavelength bands to manipulate plant morphology and flowering cycles. Dutch ornamental growers are retrofitting existing Venlo structures with these interference layers to delay or accelerate blooming for market timing. The technology is absorbing premium positioning in high-value floriculture while pressuring standard glass suppliers to demonstrate comparable spectral control.
REACH regulation amendments on polymer stabilizer chemistries are forcing covering material reformulation across European greenhouse manufacturing. ECHA substance restrictions on certain UV absorbers are accelerating fluoropolymer and acrylic alternative adoption. German and Dutch installers report extended procurement timelines as certification documentation requirements tighten for imported film and sheet products.
Direct contracting between supermarket chains and greenhouse consortia is shortening produce supply chains in Northern Europe. Retail procurement teams in Germany and the UK are bypassing traditional wholesale markets to secure year-round volume commitments from Spanish and Moroccan growers. This channel compression is concentrating volume among larger integrated operators while marginalizing smaller independent producers lacking scale for dedicated supply agreements.
Greenhouse and Smart Greenhouse Market Segmentation
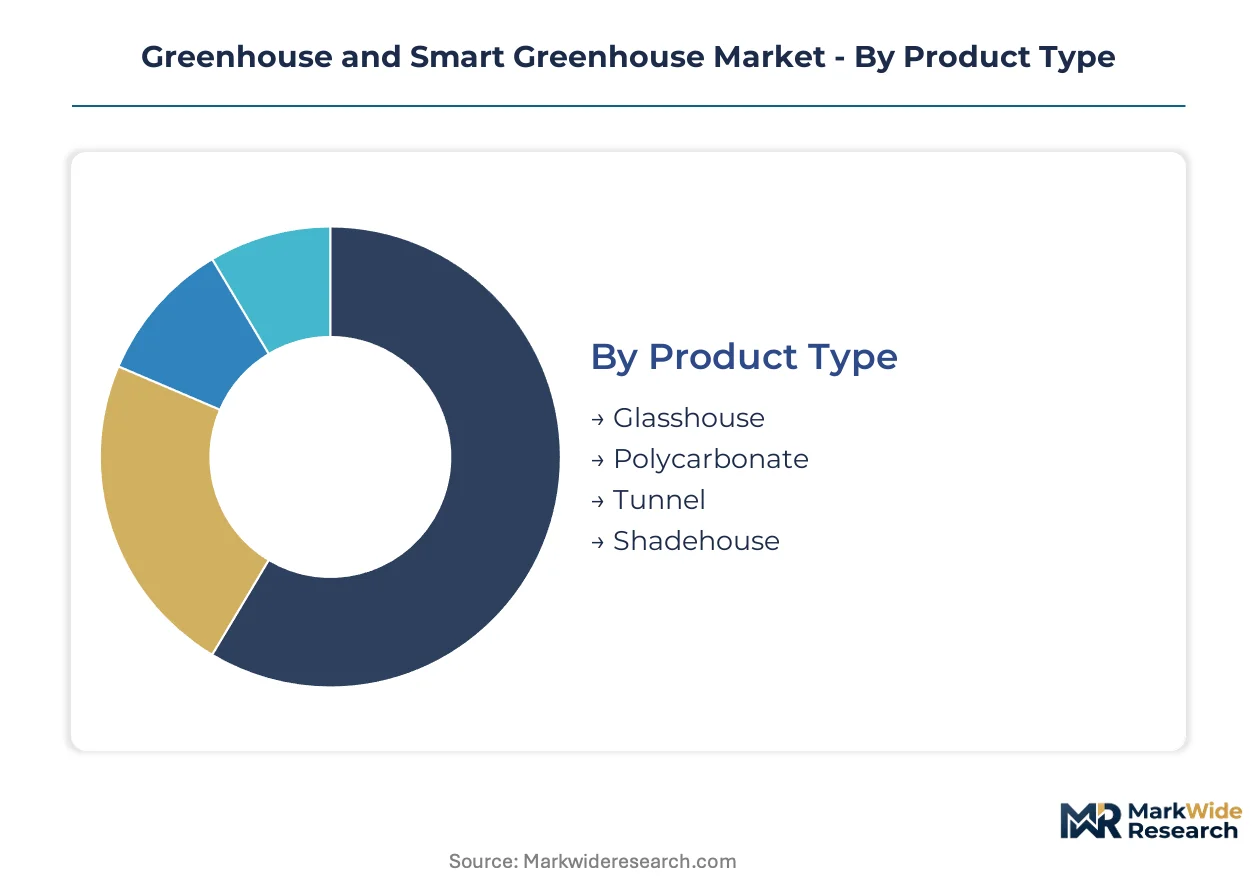
Greenhouse and smart greenhouse infrastructure fragments across structural materials, cultivation technologies, customer scale, and deployment permanence. Each dimension carries distinct margin profiles and capital intensity requirements that reshape vendor positioning and geographic expansion strategies.
Product Type:
Glasshouse structures command premium pricing and extended asset lifecycles, while polycarbonate and film-based alternatives compete on upfront cost and thermal efficiency trade-offs.
- Glasshouse:Engineered with tempered or laminated glass panels delivering 90%+ light transmission and 30-50 year structural lifespans. Dutch Venlo-style installations in the Netherlands and Belgium anchor demand, driven by EU carbon-accounting pressures favoring durable assets with lower replacement frequency.
- Polycarbonate:Twin-wall or multi-wall extruded sheets offering superior thermal insulation (U-values 40% lower than glass) at reduced weight. Spanish Almería province and Moroccan export clusters favor these structures for balancing capital efficiency with climate control in solar-thermal hybrid configurations.
- Tunnel:Curved polyethylene film structures supported by galvanized steel hoops, dominating seasonal vegetable production in Italy and Turkey where winter protection suffices without full environmental control.
- Shadehouse:Woven mesh or screen structures reducing solar intensity by 30-70%, prevalent in Israel and Jordan for nursery hardening and heat-sensitive crop protection where full enclosure is unnecessary.
Today's leader: Glasshouse. Tomorrow's challenger: Polycarbonate.
Technology:
Cultivation method selection hinges on water scarcity, labor cost, and crop value density, with recirculating systems gaining ground in water-stressed Mediterranean zones.
- Hydroponics:Closed-loop nutrient film or deep water culture systems eliminating soil media. Israel's Netafim-equipped facilities and Spain's Almería retrofit projects prioritize this technology for 50% water reduction versus conventional cultivation.
- Aeroponics:Root misting systems delivering nutrient aerosols with 95% water efficiency. Research institutions in the Netherlands and commercial leafy green producers in Singapore deploy these systems where land and water constraints are most acute.
- Aquaponics:Integrated fish-plant recirculating systems combining tilapia or catfish production with hydroponic vegetables. Emerging installations in Morocco and Egypt target export certification for integrated organic production.
- Soil-based Cultivation:Traditional substrate or native soil methods retaining volume dominance among Turkish and Italian tomato producers transitioning gradually to substrate systems.
Soil-based cultivation retains installed base dominance. Hydroponics climbs the fastest as water pricing and REACH-compliant input costs accelerate conversion.
End User:
Customer scale determines automation depth and procurement sophistication, with supermarket direct-contracting concentrating volume among integrated commercial operators.
- Commercial Growers:Large-scale enterprises supplying retail chains with year-round volume commitments. German REWE and UK Tesco direct contracts with Spanish and Moroccan greenhouse consortia exemplify this segment's procurement leverage.
- Research Institutions:Wageningen University and Israeli Volcani Institute facilities driving cultivar development and climate protocol optimization for licensed transfer to commercial operators.
- Home Gardeners:Hobby-scale polycarbonate or polyethylene hobby houses, concentrated in suburban UK and German markets with strong gardening retail channels.
- Agricultural Producers:Mid-scale family operations in Italy's Po Valley and Turkey's Antalya region modernizing from open-field to protected cultivation.
Commercial growers capture procurement volume concentration. Research institutions shape technology trajectories through protocol licensing.
Installation:
Permanence preferences reflect land tenure security, capital access, and crop rotation requirements across Mediterranean and Northern European production zones.
- Permanent:Concrete-foundation glasshouse or polycarbonate structures with fixed climate infrastructure. Dutch and Belgian operations favor these for multi-decade tomato and pepper production cycles.
- Semi-permanent:Ground-post or shallow foundation systems allowing 10-15 year deployment with eventual relocation. Spanish and Italian vegetable producers prefer this flexibility for land lease cycles.
- Movable:Rail-mounted or wheel-based structures enabling field rotation for soil health management. Emerging adoption in French salad green operations addressing soil-borne disease pressure.
- Modular:Prefabricated panel systems permitting phased expansion. Nexus Corporation's North American deployments and emerging Moroccan export projects utilize this approach for capital-efficient scaling.
Permanent installations anchor revenue stability. Modular configurations gain share fastest in capital-constrained expansion markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands pioneered modern glasshouse engineering during the post-war agricultural intensification era, establishing the technical protocols that now define climate-controlled cultivation across temperate zones worldwide.
Netherlands
Venlo-style glasshouse clusters dominate the Westland and Aalsmeer regions, supplying year-round tomatoes and ornamental flowers to German and British retail chains. The EU Green Deal's Farm to Fork Strategy channels national subsidies toward energy-efficient heating retrofits in existing installations. Wageningen University partnerships with commercial operators accelerate cultivar development and climate protocol optimization for licensed export to other European markets.
Spain
Almería province anchors Europe's largest concentration of solar-thermal hybrid greenhouse infrastructure, delivering fresh produce to Northern European supermarkets during winter months. National water pricing reforms under the EU Water Framework Directive accelerate hydroponic retrofitting in water-stressed southeastern provinces. The Poniente and Levante sub-regions concentrate polycarbonate structure fabrication serving both domestic expansion and Moroccan export-oriented projects.
United States
California's Salinas Valley and Florida's Immokalee region concentrate soil-to-substrate transitions among large-scale vegetable producers supplying domestic retail chains. EPA agricultural runoff regulations shape crop protection protocol selection inside controlled environments. Nexus Corporation's modular greenhouse deployments target the Great Lakes and Northeast regions where year-round local produce commands supermarket premium positioning.
Israel
The Arava and Jordan Valley regions deploy Netafim-equipped hydroponic systems achieving ninety-five percent water efficiency in desert conditions. National water scarcity mandates under the Israel Water Authority's quota system eliminate open-field cultivation for most export crops. Research institutions at the Volcani Center license climate protocols to commercial operators expanding into Jordanian and Egyptian joint ventures.
Morocco
The Souss-Massa and Oriental regions attract Dutch and Spanish greenhouse developers targeting European winter produce gaps through eight-hour ferry connections. EU association agreement tariff schedules favor Moroccan horticultural exports against Turkish and Egyptian competitors. Agadir's emerging greenhouse cluster concentrates polycarbonate fabrication and propagation nursery capacity for re-export to sub-Saharan African markets.
Greenhouse and Smart Greenhouse Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with full-system engineering commanding pricing multiples versus component supply. The vendor base stratifies into three tiers: Dutch glasshouse integrators with century-old engineering heritage, Israeli precision irrigation specialists leveraging drip-system expertise, and North American modular fabricators targeting capital-constrained expansion markets. Dominant competitive moves include strategic partnerships between structure engineers and climate control technology providers, plus geographic expansion through turnkey project contracting into underpenetrated North African and Middle Eastern zones.
Within the full-system integration tier, Certhon and Rough Brothers occupy positions exemplifying European and North American engineering heritage respectively. Netafim anchors the precision irrigation archetype through its drip-system expertise embedded across commercial greenhouse portfolios worldwide. Nexus Corporation represents the modular-fabrication vector targeting phased expansion scenarios in capital-constrained markets. These three anchors illustrate how competitive positioning fragments across technical specialization rather than consolidating around generalist provision.
| Leading Market Players |
|---|
| Nexus Corporation |
| Argus Control Systems Limited |
| Certhon |
| Rough Brothers Inc. |
| GreenTech Agro LLC |
| Netafim |
| Heliospectra AB |
| LumiGrow |
| Sensaphone |
| Others |
Pricing and Supply Chain Analysis
Family-owned Dutch glasshouse integrators anchor supply-side discipline through generational engineering heritage, translating into premium pricing power for Venlo-style installations while resisting margin erosion from modular competitors. Sovereign-backed Spanish polycarbonate fabricators in Almería leverage EU Green Deal subsidies to compress delivered costs for Mediterranean export clusters, forcing Northern European installers to absorb freight premiums or concede volume.
Pricing Analysis
Project-based turnkey contracting dominates structure procurement, with pricing stratifying across premium glasshouse, standard polycarbonate, and economy polyethylene film tiers. Price differentiation hinges on thermal performance certification under EU energy-efficiency standards and volume scale of retail chain offtake agreements. Cost compression in semi-permanent polycarbonate segments is intensifying because Asian resin supply volatility feeds through to European installers. Commercial growers supplying German supermarket chains exhibit highest price sensitivity, while Dutch ornamental specialists prioritize light-transmission metrics over capital outlay.
Supply Chain Analysis
EU local-content mandates under the Farm to Fork Strategy are reshaping sourcing patterns for greenhouse covering chemistries and climate-control electronics. Manufacturing concentrates in the Netherlands for glasshouse engineering, Spain for polycarbonate extrusion, and China for polyethylene resin and sensor hardware. Component dependencies include tempered glass from Belgian float-glass producers, polycarbonate resin from German petrochemical complexes, and IoT sensors from East Asian electronics clusters. Single-source vulnerability runs through Asian semiconductor supply for environmental control systems. Distribution runs through Dutch turnkey contractors for European projects and Spanish engineering firms for North African export deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal carbon-accounting rules for heated agriculture create durable demand for monitoring and verification technology. The Farm to Fork Strategy's pesticide reduction mandates channel capital toward climate-controlled protected cultivation infrastructure.
For Market Incumbents: Anticipate margin compression from modular greenhouse fabricators targeting capital-constrained North African expansion markets by deepening backward integration into climate-control software development. Prioritize certification investment for REACH-compliant covering materials as ECHA substance restrictions accelerate reformulation cycles. Channel control through direct retail chain contracting remains essential for volume retention against Spanish and Moroccan consortia.
For New Entrants and Emerging Players: Enter via Morocco's Souss-Massa and Oriental regions where EU association agreement tariff schedules favor horticultural exports against Turkish competitors. Target aquaponics integration for organic certification premiums in Egyptian joint ventures. Pursue go-to-market partnerships with Israeli precision irrigation specialists licensing desert cultivation protocols.
For Investors and Strategic Acquirers: Valuations sit cheapest among modular greenhouse fabricators lacking climate-control technology integration. Long-term viability favors vendors with software-defined environmental management capabilities spanning the projection horizon. Acquisition targets should demonstrate installed base in water-stressed Mediterranean zones with retrofit potential. Watch for inflection in EU carbon-border adjustment mechanism scope expansion to heated agriculture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Climate Software | Dutch glasshouse integrators capture recurring revenue from predictive environmental control algorithms. |
| REACH-Compliant Material Certification | Covering suppliers secure market access as ECHA restrictions eliminate non-compliant competitors. |
| Moroccan Turnkey Project Expansion | Spanish engineering firms leverage eight-hour ferry connections to European retail distribution. |
| Aquaponics Organic Certification | North African operators target premium positioning through integrated fish-plant production systems. |
| Direct Retail Chain Contracting | German and UK supermarket procurement teams consolidate volume among integrated greenhouse consortia. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Dutch glasshouse engineering executives, Spanish polycarbonate fabrication plant managers, Israeli precision irrigation R&D directors, Moroccan export-oriented growers, and German supermarket produce procurement leads with secondary validation. Trade data from Eurostat and UN Comtrade, EU regulatory filings under REACH and the Farm to Fork Strategy, patent databases for photoselective coating technologies, and commercial greenhouse operator SEC disclosures anchored supply-side assessment. Bottom-up project pipeline enumeration and top-down macroeconomic absorption modeling provided cross-checks.
Comparable-period anchoring linked projection assumptions to historical capacity installation rates across the analysis window, with segmentation modeling across structural material type, cultivation technology, customer scale tier, and installation permanence. CAGRs derived from regression against input cost indices and policy subsidy trajectories. Forecast inputs included natural gas price volatility assumptions for heated glasshouse operations and water pricing reform implementation timelines under the EU Water Framework Directive.
Inputs from regulatory agency documentation and commercial operator disclosures were available through the study window; gaps in real-time project financing commitment data introduce uncertainty bands around North African expansion scenarios. Forecasts reflect documented assumptions regarding carbon-accounting rule evolution and polymer resin supply stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
France Water Consumption Market
Environment & Sustainability
Water Purification Tablets Market
Environment & Sustainability
Point of Use Water Treatment Systems Market
Environment & Sustainability
Wheeled Bins Market
Environment & Sustainability
Waste Compactor Bins Market
Environment & Sustainability
Anti-Pollution Toner Market
Environment & Sustainability
Emission Trading Schemes Market
Environment & Sustainability
Environmental Consulting Services Market
Environment & Sustainability
E-Waste Management Market
Environment & Sustainability
Chile Water Consumption Market
Environment & Sustainability
North America Emission Monitoring System Market
Environment & Sustainability
Ecotoxicological Studies Market
Environment & Sustainability
Anti-Pollution Mask Market
Environment & Sustainability
Eco Funnel Market
Environment & Sustainability
Global Water Recycle and Reuse Market
Environment & Sustainability
GCC Industrial Waste Management Market