
 Polyvinyl Chloride Membranes Market | 2026-2036
Polyvinyl Chloride Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Polyvinyl Chloride Membranes Market Analytics
Chinese waterproofing manufacturers is realigning capacity toward reinforced and composite membrane grades. Weifang Chenhua Waterproof leverages integrated PVC resin sourcing to sustain cost competitiveness in flexible membrane exports. Carlisle SynTec Systems anchors North American demand through specialized roofing membrane distribution. GAF competes across multiple building envelope segments with calibrated product breadth.
Polyvinyl chloride membranes are synthetic polymer sheets formulated from PVC resin with plasticizers and stabilizers, typically manufactured by calendaring or extrusion to achieve thicknesses of 1.0–2.5 mm for waterproofing and barrier applications. These membranes function as impermeable separation layers in roofing systems, water treatment basins, and industrial containment structures where chemical resistance and dimensional stability prove critical. Flexible membranes dominate volume consumption in construction waterproofing where conformability to complex substrates commands premium positioning. Reinforced membranes lead value generation through embedded polyester or glass fiber scrim that extends service life in exposed roofing applications. Composite membrane technologies are displacing conventional single-ply systems in wastewater management where multi-layer barrier performance reduces permeation risk.
EPA stormwater regulations and OSHA workplace exposure limits shape formulation choices for membrane producers serving US infrastructure projects. REACH substance restrictions and CE marking requirements under the EU Construction Products Regulation govern market access for European membrane suppliers. China's GB standards for waterproofing materials and MEE environmental compliance protocols enforce quality thresholds in domestic production. Stakeholders must monitor evolving chemical substance restrictions and building energy codes that redefine membrane performance specifications across major demand centers.
Market Dynamics
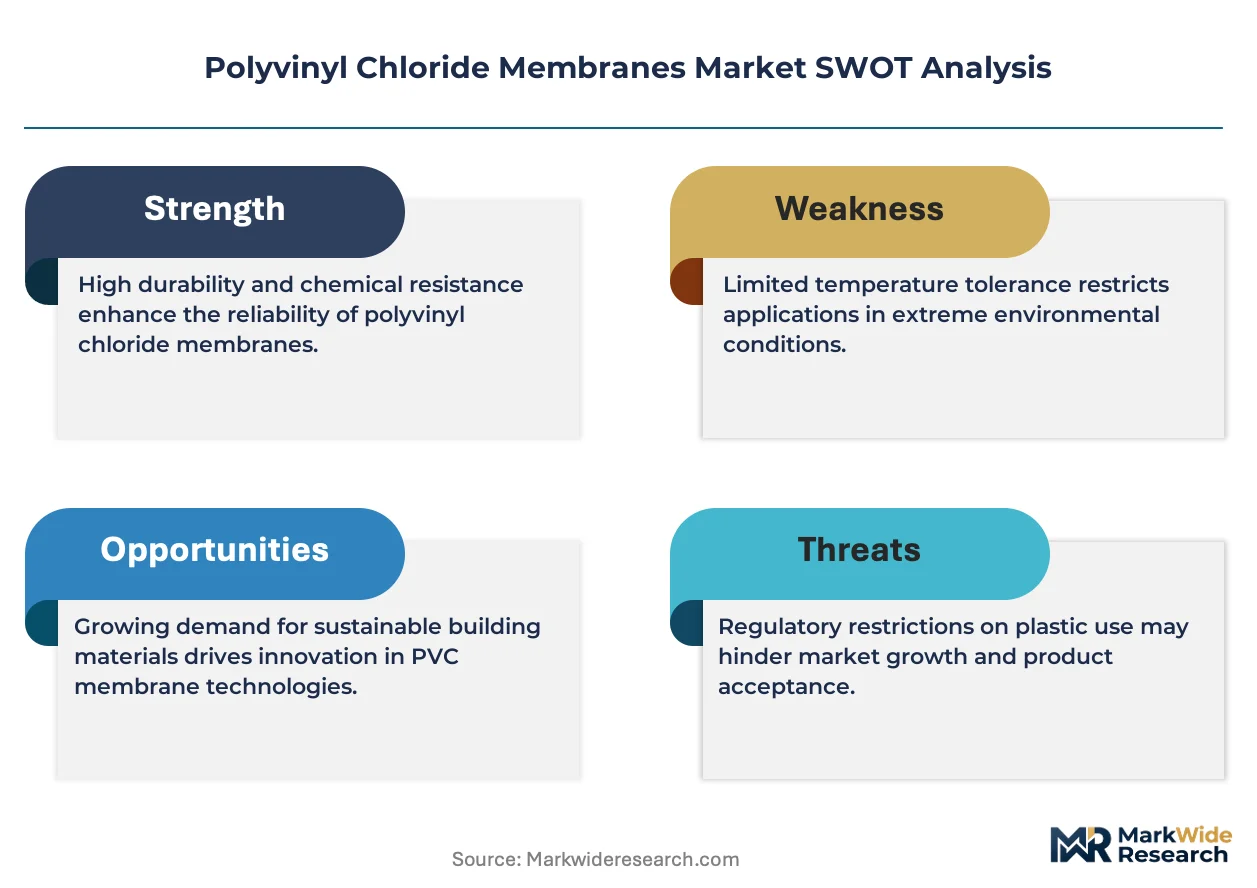
REACH substance restrictions and China's evolving environmental compliance protocols are compressing formulation flexibility for membrane producers while simultaneously creating tiered market access based on certification depth. This regulatory divergence is fragmenting competitive positioning between integrated resin producers and compound-dependent specialists.
Growth Catalysts
- Urban infrastructure investment:China's municipal water treatment expansion and underground utility tunnel construction generates sustained membrane demand for containment and waterproofing applications.
- REACH compliance premium:European building envelope specifications increasingly specify low-plasticizer migration grades, rewarding producers with advanced stabilizer technology and documented substance safety data.
- Reinforced membrane technology:Embedded polyester scrim systems extend service intervals in exposed roofing, creating lifecycle cost advantages that accelerate specification in commercial construction.
Market Restraints
- Plasticizer cost volatility:Phthalate and bio-based plasticizer input prices fluctuate with petrochemical feedstock cycles, compressing margin predictability for compounders without captive resin supply.
- Supply concentration in chlor-alkali:Membrane-grade PVC resin production clusters in coastal China and US Gulf Coast regions, exposing buyers to logistics disruption and tariff exposure.
- Thermoplastic polyolefin substitution:TPO membranes gain share in North American commercial roofing where welding speed and reflectivity specifications favor lighter-weight alternatives.
Strategic Opportunities
- India infrastructure buildout:Smart Cities Mission and Jal Jeevan Mission investments create first-mover positioning for waterproofing suppliers establishing local compounding partnerships.
- Green building certification alignment:LEED v4.1 and BREEAM standards reward low-VOC membrane systems, opening specification channels in premium commercial development.
- Digital specification platforms:Building information modeling integration allows membrane producers to embed performance data directly into architect workflow tools, compressing traditional distributor influence.
Industry Challenges
- Welding technician certification gaps:Automated seam welding equipment deployment outpaces qualified operator availability, creating installation quality variance in field-applied systems.
- Multi-standard compliance burden:Simultaneous GB standard, ASTM, and EN certification requirements extend product development timelines and testing expenditure for exporters serving multiple demand centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyvinyl Chloride Membranes Market |
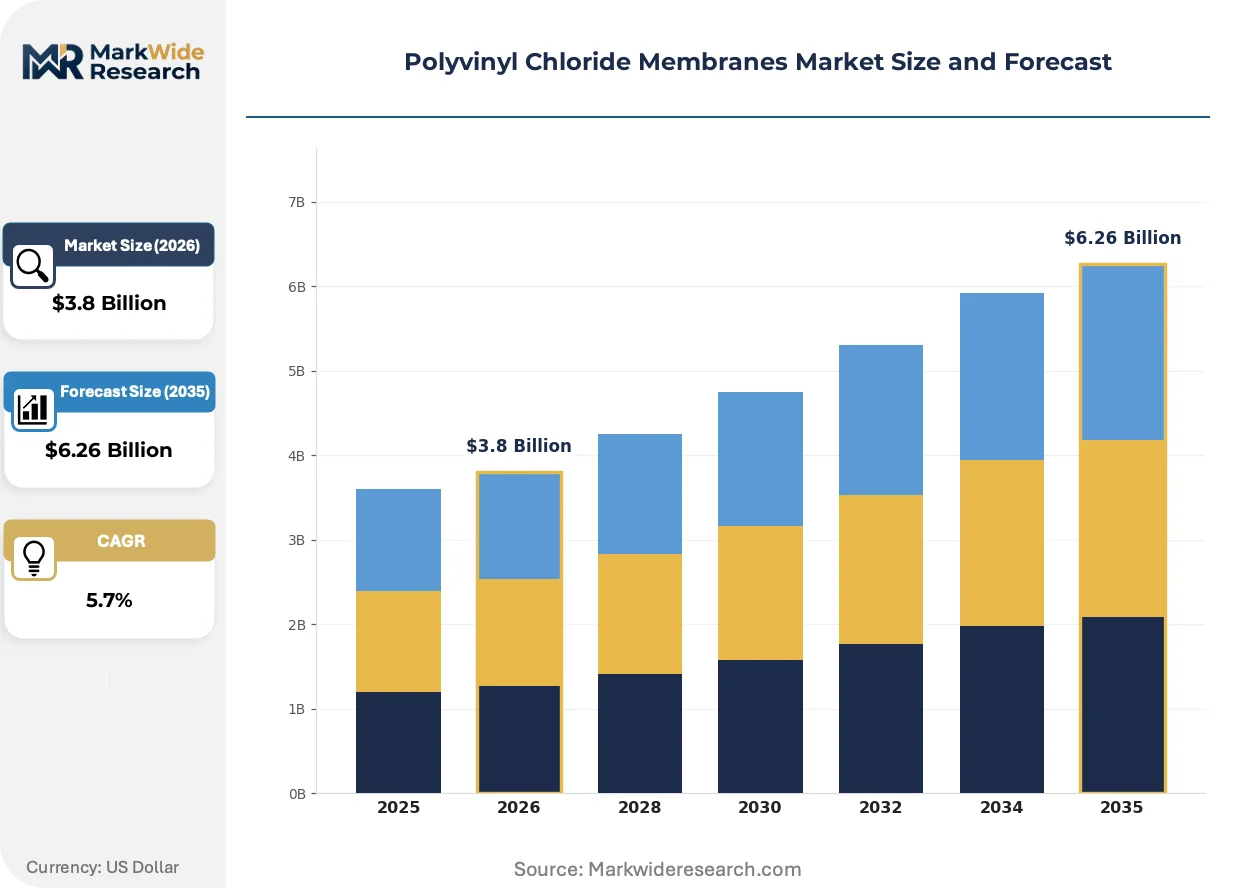
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Membranes, Rigid Membranes, Composite Membranes, Reinforced Membranes End User: Construction, Automotive, Medical, Industrial Application: Water Treatment, Wastewater Management, Roofing, Wall Cladding Technology: Extrusion, Injection Molding, Blow Molding, Calendaring |
| Companies Covered | Weifang Chenhua Waterproof Co., Ltd., Foshan HouDe Decoration Material Co., Ltd., Shandong Juhui Waterproof Materials Co., Ltd., Carlisle SynTec Systems, Cooley Group, Duro-Last, Inc., GAF, IB Roof, Premier Polyfilm Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyvinyl Chloride Membranes Market Evolving Landscape
Automated manufacturing and digital quality assurance systems are compressing defect rates while enabling mass customization of membrane thickness and reinforcement patterns. These capabilities are reshaping how producers compete on lead time versus inventory depth.
Robotic calendering lines with inline thickness profiling is automating quality control in flexible membrane production, reducing manual inspection labor while enabling real-time grade sorting. Commercial roofing contractors in Germany and the Netherlands are specifying these digitally certified rolls for warranty-backed installations. The technology is automating the link between production data and installation accountability, compressing dispute resolution cycles.
ECHA's expanding SVHC candidate list is forcing reformulation of legacy stabilizer packages, particularly calcium-zinc and organotin systems previously standard in European membrane grades. Producers with advanced R&D pipelines are accelerating barium-zinc and mixed metal stabilizer transitions ahead of authorization deadlines. Construction product manufacturers in France and Belgium face the most compressed compliance timelines due to national implementation of stricter substance notification requirements.
Specification authority is migrating from general contractors to architect-led design-build consortia, particularly in Nordic commercial construction where energy performance modeling drives membrane selection early in project development. This shift compresses traditional distributor influence and rewards producers with direct technical sales capabilities. Finland and Norway exhibit the most advanced procurement pattern evolution, with membrane performance data increasingly embedded in whole-building energy simulation software.
Polyvinyl Chloride Membranes Market Segmentation
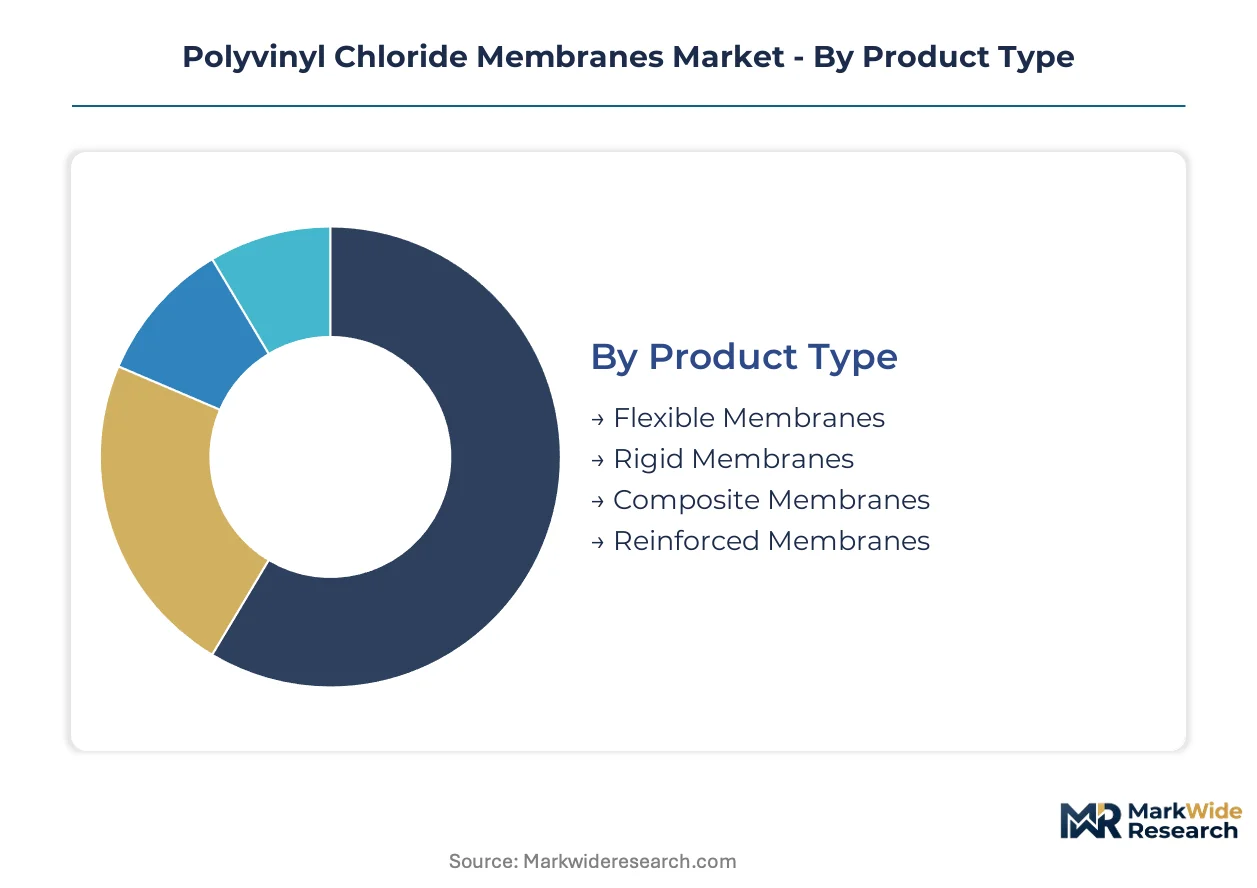
Segmentation in the PVC membranes market reveals how certification requirements, manufacturing complexity, and end-use performance demands create distinct competitive arenas. Producers must align formulation expertise with specific regulatory pathways to capture value in each segment cluster.
Product Type:
REACH substance restrictions and GB standards enforcement differentiate certification burdens across membrane grades, with reinforced and composite systems facing the most intensive documentation requirements for stabilizer safety and migration testing.
- Flexible Membranes:Polymer sheets with high plasticizer content (30-50 phr) achieve elongation exceeding 300% for complex substrate conformability. Waterproofing contractors in China's underground utility tunnel projects specify these grades for seam-welded containment systems where substrate irregularity demands material compliance.
- Reinforced Membranes:Embedded polyester or glass fiber scrim (typically 250-400 g/m²) delivers tensile strength above 1000 N/50mm for exposed roofing applications. Nordic commercial construction specifications increasingly require these systems for lifecycle warranty compliance under severe weather exposure.
- Composite Membranes:Multi-layer barrier constructions combining PVC with EPDM or TPO interlayers address permeation-critical wastewater containment. MEE environmental compliance protocols in China mandate these grades for municipal treatment basin upgrades.
- Rigid Membranes:Low-plasticizer formulations (under 15 phr) with high filler loading provide dimensional stability for industrial tank lining and chemical containment. Automotive battery housing applications in Germany and Japan drive specification for these chemically resistant grades.
Leading the category by volume: Flexible Membranes. Growing fastest: Reinforced Membranes.
End User:
Customer procurement sophistication varies sharply across end-use sectors, with construction buyers prioritizing installed-cost metrics while medical and automotive purchasers emphasize batch traceability and substance documentation.
- Construction:General contractors and roofing specialists purchase membrane systems as part of building envelope packages, with specification authority migrating toward architect-led consortia. China's Smart Cities Mission infrastructure awards favor suppliers with integrated waterproofing and insulation system capabilities.
- Industrial:Chemical processing and power generation facilities specify membrane containment for tank farms and cooling tower basins. OSHA workplace exposure limits in US infrastructure projects drive demand for low-VOC welding systems in field-applied installations.
- Automotive:Battery housing and interior barrier applications require flame-retardant grades meeting OEM material approval protocols. Supply agreements with European and Asian vehicle manufacturers demand IMDS documentation and full substance disclosure.
- Medical:Blood bag and dialysis equipment applications face the most stringent extractables testing under FDA and EMA biocompatibility frameworks. DEHP-free plasticizer migration specifications dominate procurement criteria for these life-critical uses.
Dominating procurement volume: Construction. Steepest specification upgrade trajectory: Medical.
Application:
Performance failure consequences range from warranty disputes in roofing to environmental liability in wastewater containment, creating tiered risk profiles that reshape supplier qualification requirements.
- Roofing:Single-ply and multi-ply membrane systems for commercial and industrial buildings require UV stabilizer packages and heat-welded seam integrity. German and Dutch contractors increasingly specify digitally certified rolls with inline thickness profiling data for warranty-backed installations.
- Water Treatment:Potable water reservoir and distribution system linings demand NSF/ANSI 61 certification in North America and equivalent WRAS approval in the United Kingdom. These grades face the most intensive extraction and taste/odor testing protocols.
- Wastewater Management:Anaerobic digester covers and aeration basin liners combine chemical resistance with gas-tight seam performance. Composite membrane technologies are displacing conventional single-ply systems where methane permeation risk drives specification.
- Wall Cladding:Rainscreen and facade barrier applications emphasize vapor permeability control and wind load resistance. CE marking under the EU Construction Products Regulation governs market access for European facade membrane suppliers.
Highest volume consumption: Roofing. Fastest technology transition: Wastewater Management.
Technology:
Capital intensity and quality assurance sophistication separate manufacturing methods, with calendaring and extrusion commanding premium positioning over molding processes limited to specialized geometries.
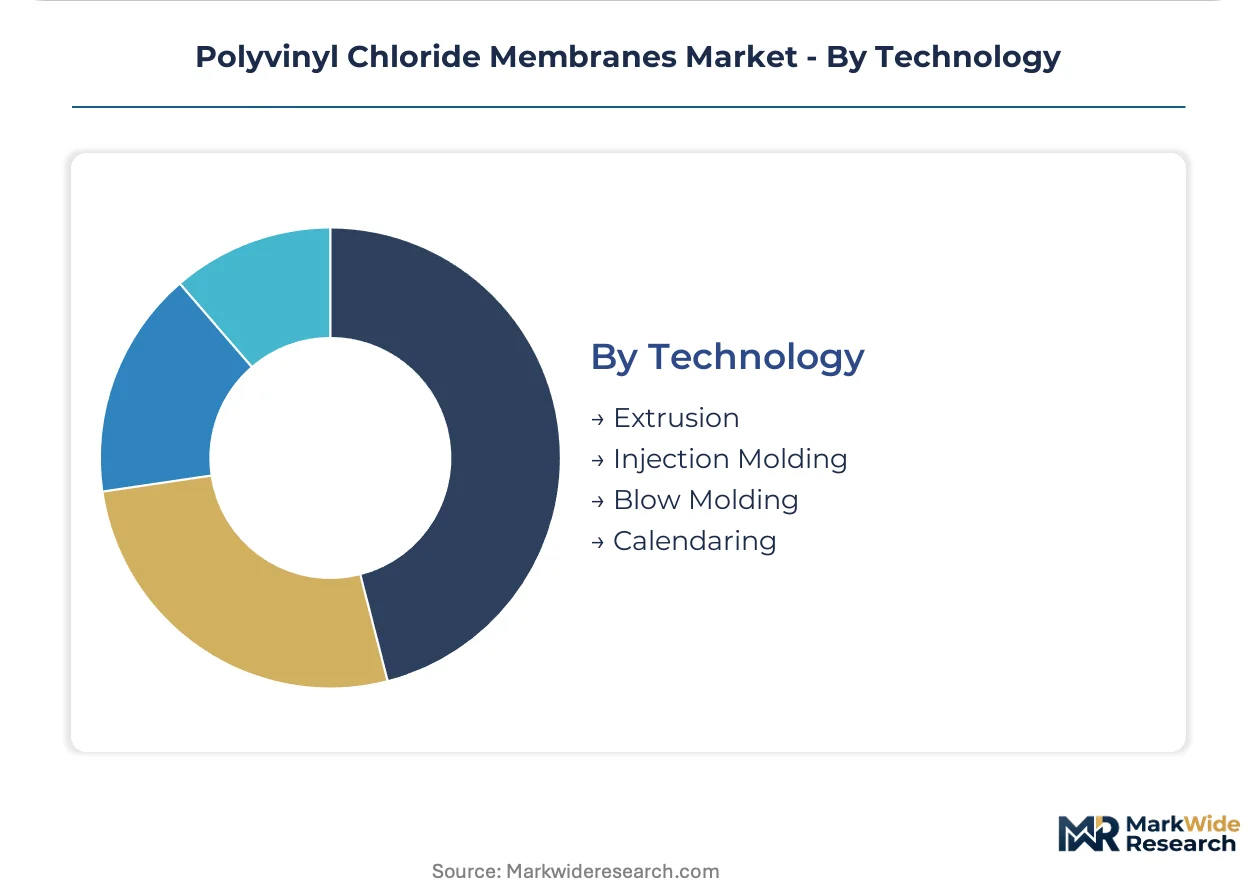
- Calendaring:Continuous rolling mills with multi-roll stacks produce uniform thickness sheets (1.0-2.5 mm) with precise surface finish control. Robotic calendering lines with inline thickness profiling automate quality control in flexible membrane production, reducing manual inspection labor.
- Extrusion:Single-screw and twin-screw extruders with flat die heads enable rapid width changes and custom color matching for architectural specifications. Flat die extrusion dominates North American commercial roofing membrane production for welding speed optimization.
- Blow Molding:Parison extrusion and inflation processes create seamless cylindrical or irregular hollow forms for tank liners and geomembrane applications. Limited to specialized containment geometries where seam elimination justifies higher unit costs.
- Injection Molding:High-pressure cavity filling produces rigid membrane fittings, penetration seals, and prefabricated detail components. Automotive and medical end uses drive precision molding investment for complex geometry production.
Leading by installed capacity: Calendaring. Expanding most quickly: Extrusion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chlor-alkali production clusters along China's eastern seaboard and the US Gulf Coast anchor resin supply for membrane manufacturing, concentrating formulation expertise near feedstock sources while dispersing fabrication capacity toward end-use demand centers.
China
Urban infrastructure investment through the Smart Cities Mission and underground utility tunnel construction sustains membrane consumption for waterproofing and containment systems. MEE environmental compliance protocols enforce GB standards for waterproofing materials, tightening quality thresholds for domestic producers. Weifang and Shandong province house integrated resin-to-membrane manufacturing complexes where producers leverage captive PVC sourcing for export competitiveness.
United States
Commercial roofing replacement cycles and EPA stormwater regulations drive specification of low-VOC membrane systems in building envelope applications. OSHA workplace exposure limits shape formulation choices for field-applied installations, particularly in infrastructure projects. The US Gulf Coast chlor-alkali corridor supplies membrane-grade resin while specialized distributors anchor North American demand through roofing membrane networks.
Germany
Nordic commercial construction specifications increasingly require reinforced membrane systems with lifecycle warranty compliance under severe weather exposure. REACH substance restrictions and CE marking under the EU Construction Products Regulation govern market access, with ECHA's expanding SVHC candidate list forcing stabilizer package reformulations. German and Dutch contractors specify digitally certified rolls with inline thickness profiling data for warranty-backed installations.
India
Smart Cities Mission and Jal Jeevan Mission investments create positioning opportunities for waterproofing suppliers establishing local compounding partnerships. BIS standards enforcement and state-level environmental clearances shape market entry requirements for membrane producers. Maharashtra and Gujarat industrial corridors concentrate demand from municipal water treatment expansion and commercial construction growth.
Japan
Automotive battery housing applications and industrial containment specifications drive demand for rigid, chemically resistant membrane grades. METI industrial standards and JIS certification requirements govern material approval protocols for OEM supply relationships. Kansai and Chubu manufacturing regions host precision molding operations for complex geometry membrane components serving automotive and medical end uses.
Polyvinyl Chloride Membranes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue composite membrane technologies and digital certification capabilities. The supplier base stratifies between integrated resin-to-membrane manufacturers and compound-dependent specialists, with regulatory certification depth determining tier placement. Three archetypes dominate: captive resin producers with cost-advantaged export positioning, formulation specialists with advanced stabilizer technology, and regional fabricators with localized specification relationships. Competitive moves concentrate on backward integration into resin supply and strategic partnerships for multi-standard certification coverage.
Among Chinese integrated producers, Weifang Chenhua Waterproof Co., Ltd. and Shandong Juhui Waterproof Materials Co., Ltd. exemplify the captive resin archetype with eastern seaboard manufacturing concentration. Carlisle SynTec Systems occupies a position within the North American specialized distribution tier, while GAF sits within the multi-segment building envelope supplier category. These named entities anchor commentary on geographic sourcing advantages and specification channel access without asserting specific strategic actions or market share positions.
| Leading Market Players |
|---|
| Weifang Chenhua Waterproof Co., Ltd. |
| Foshan HouDe Decoration Material Co., Ltd. |
| Shandong Juhui Waterproof Materials Co., Ltd. |
| Carlisle SynTec Systems |
| Cooley Group |
| Duro-Last, Inc. |
| GAF |
| IB Roof |
| Premier Polyfilm Ltd. |
| Others |
Value Network & Pricing Analysis
Robotic calendering lines with inline thickness profiling are compressing quality variance while simultaneously concentrating production economics among capital-intensive operators. This manufacturing transition rewards membrane producers with integrated resin supply and automated certification capabilities, widening cost spreads between captive producers and compound-dependent specialists.
Pricing Analysis
Warranty-backed installations bundle digital certification data with membrane rolls, unbundling traditional distributor service layers. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant reinforced grades with full substance documentation from flexible membrane commodities. Price differentiation hinges on certification depth and captive resin supply. Cost compression in flexible membrane tiers is intensifying because plasticizer input volatility squeezes compounders without upstream PVC control. Waterproofing contractors in China's municipal tunnel projects exhibit highest price sensitivity; Nordic commercial roofing specifiers prioritize lifecycle warranty compliance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for membrane roll returns and off-spec material reprocessing remain underdeveloped, creating working capital drag for distributors managing thickness variance claims. Chlor-alkali production clusters in coastal China and the US Gulf Coast anchor membrane-grade PVC resin supply. Raw material dependencies rest on ethylene feedstock cycles, chlorine availability, and plasticizer compound sourcing. Single-source vulnerability concentrates in Shandong province integrated complexes. Distribution runs through specialized roofing membrane networks and direct technical sales channels to architect-led consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory certification depth is forcing consolidation as compound-dependent specialists face margin compression from multi-standard compliance burdens. Smaller producers without captive resin supply or advanced stabilizer R&D pipelines are exiting as REACH substance restrictions tighten.
For Market Incumbents: Cement specification authority by embedding performance data directly into building information modeling platforms, compressing traditional distributor influence. Deepen backward integration into membrane-grade PVC resin production to sustain cost competitiveness against integrated Chinese exporters. Prioritize barium-zinc stabilizer transitions ahead of ECHA authorization deadlines to defend premium positioning in European commercial roofing.
For New Entrants and Emerging Players: Enter via local compounding partnerships in India's Maharashtra and Gujarat industrial corridors, targeting Jal Jeevan Mission water treatment infrastructure awards. Focus initial positioning on composite membrane technologies for wastewater management applications where MEE compliance mandates displace conventional single-ply systems. Pursue green building certification alignment as the primary specification channel into premium commercial development.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated resin-to-membrane manufacturers with eastern seaboard China positioning and established multi-standard certification coverage. Long-term viability favors producers with automated manufacturing footprints and direct architect-channel relationships over distributor-dependent regional fabricators. Monitor ECHA SVHC list expansion velocity as the critical inflection signal for stabilizer reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive PVC sourcing insulates margin from plasticizer volatility and tariff exposure. |
| Multi-Standard Certification Investment | Simultaneous GB, ASTM, and EN coverage unlocks specification across China, US, and European demand centers. |
| Digital Certification Platform Deployment | Inline thickness profiling data embedded in BIM workflows compresses warranty dispute resolution cycles. |
| Green Building Certification Alignment | LEED v4.1 and BREEAM compliance opens specification channels in premium Nordic commercial construction. |
| Composite Membrane Technology Development | Multi-layer barrier constructions address methane permeation risk in China's municipal wastewater upgrades. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with membrane plant managers, waterproofing procurement leads at general contractors, roofing distribution channel partners, and technical R&D directors at stabilizer suppliers combined with bottom-up and top-down triangulation. Secondary sources included ECHA substance restriction databases, MEE environmental compliance protocols, SEC 10-K filings from building materials suppliers, and customs records tracking PVC resin and membrane roll trade flows.
Granularity-level modeling deployed separate frameworks for flexible, reinforced, composite, and rigid membrane grades across construction, industrial, automotive, and medical end-use sectors. Segmentation dimensions included product type, application, technology, and regional production hub. CAGRs were derived from installed base analysis and replacement cycle modeling. Industry-specific forecast inputs incorporated urban infrastructure investment pipelines, REACH substance authorization timelines, and chlor-alkali capacity expansion announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH substance bans or chlor-alkali supply disruptions. Practitioners should monitor ECHA SVHC candidate list expansion, MEE enforcement intensity in Shandong province, and TPO membrane substitution rates in North American commercial roofing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Thermoplastic Polyolefin Membranes Market
Membrane Materials
Global Ultrafiltration Market
Membrane Materials
Global Transfer Membrane Market
Membrane Materials
Global Breathable Membranes Market
Membrane Materials
Bitumen Waterproofing Membrane Market
Membrane Materials
Industrial Solvent Separation Membranes Market
Membrane Materials
PTFE Membrane Market
Membrane Materials
Specialty Breathable Membranes Market
Membrane Materials
Inorganic Ion Exchange Materials Market
Membrane Materials
North America below Grade Waterproofing Membranes Market
Membrane Materials
Nanofiltration Membrane Market
Membrane Materials
Global Gas Separation Membranes Market
Membrane Materials
Polyvinyl Butyral (PVB) Films and Sheets Market
Membrane Materials
Membrane Separation Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
Reverse Osmosis Films Market