
 Surgical Monitors Market | 2026-2036
Surgical Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Monitors Market Analytics
The direct hospital procurement channel is narrowing as group purchasing organizations consolidate vendor panels across health systems. Stryker leverages its integrated surgical technologies portfolio to control capital equipment decisions at the system level. Eizo Corporation specializes in color-calibrated diagnostic displays that differentiate its offering in precision-dependent surgical workflows. Barco sustains technology leadership through advanced image processing engines designed for hybrid operating rooms.
Surgical monitors are medical-grade display systems engineered to render real-time video feeds from endoscopes, surgical cameras, and patient monitoring devices with luminance outputs exceeding 500 cd/m² and grayscale calibration for tissue differentiation. These systems serve as the visual interface between surgical teams and the anatomical field during minimally invasive procedures. The 4K product segment commands premium positioning as hospitals prioritize visualization clarity for laparoscopic and robotic-assisted surgery. OLED technology is gaining structural share where contrast ratio and black-level performance justify higher capital outlays against mature LCD alternatives. Wireless technology is expanding fastest in ambulatory surgical centers where infrastructure flexibility and rapid room turnover outweigh the latency tolerance of networked alternatives.
The FDA enforces medical device cybersecurity requirements under its post-market guidance, compelling manufacturers to embed threat mitigation into display system architectures. CE marking under the EU Medical Device Regulation mandates clinical evidence for surgical visualization claims, raising barriers for non-European entrants. ISO 13485 quality management certification has become table stakes for supply relationships with integrated delivery networks. Stakeholders must weigh the capital efficiency of display standardization against the clinical specificity of procedure-dedicated monitor configurations.
Market Dynamics
Group purchasing organizations are consolidating vendor panels across United States health systems, narrowing direct hospital procurement channels and forcing manufacturers to secure enterprise-level contracts rather than individual facility sales.
Growth Catalysts
- Minimally invasive surgical suite expansion:Hospital systems in Germany and Japan are modernizing aging operating room infrastructure, pulling demand for high-resolution visualization systems that support laparoscopic and robotic-assisted procedures.
- FDA cybersecurity guidance refinement:Post-market surveillance requirements are reshaping product development priorities, compelling manufacturers to embed threat mitigation architectures into display systems from the design phase.
- OLED technology maturation:Contrast ratio and black-level performance advantages are justifying premium capital outlays in precision-dependent surgical workflows where tissue differentiation demands exceed LCD capabilities.
Market Restraints
- Capital equipment replacement cycles:Extended depreciation schedules for LCD-based installations in United States ambulatory surgical centers delay upgrade decisions despite superior OLED performance metrics.
- EU Medical Device Regulation clinical evidence mandates:CE marking requirements for surgical visualization claims raise barriers for non-European entrants, concentrating supply relationships with established ISO 13485-certified manufacturers.
- Wireless latency tolerance thresholds:Networked alternatives face adoption ceilings in tertiary care settings where real-time image fidelity cannot accommodate transmission delays inherent to cable-free architectures.
Strategic Opportunities
- Ambulatory surgical center infrastructure flexibility:Wireless technology is expanding fastest in United States outpatient facilities where rapid room turnover and modular deployment outweigh latency constraints of hybrid operating environments.
- 4K visualization standardization:Premium positioning for ultra-high-definition product segments creates white space as Japanese health systems prioritize clarity investments for complex oncological resections.
- Integrated delivery network supply consolidation:Vendor panel consolidation enables manufacturers with integrated surgical technologies portfolios to control capital equipment decisions at the system level rather than facility-by-facility.
Industry Challenges
- Grayscale calibration expertise scarcity:Specialized biomedical engineering talent capable of maintaining luminance outputs exceeding 500 cd/m² across distributed monitor fleets commands premium compensation, constraining service scalability.
- Legacy PACS integration complexity:Picture archiving and communication systems in German university hospitals require customized middleware development to achieve seamless interoperability with next-generation display architectures.
- Dual certification timeline compression:Simultaneous FDA 510(k) clearance and EU MDR conformity assessment processes extend time-to-revenue for manufacturers targeting both United States and European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Monitors Market |
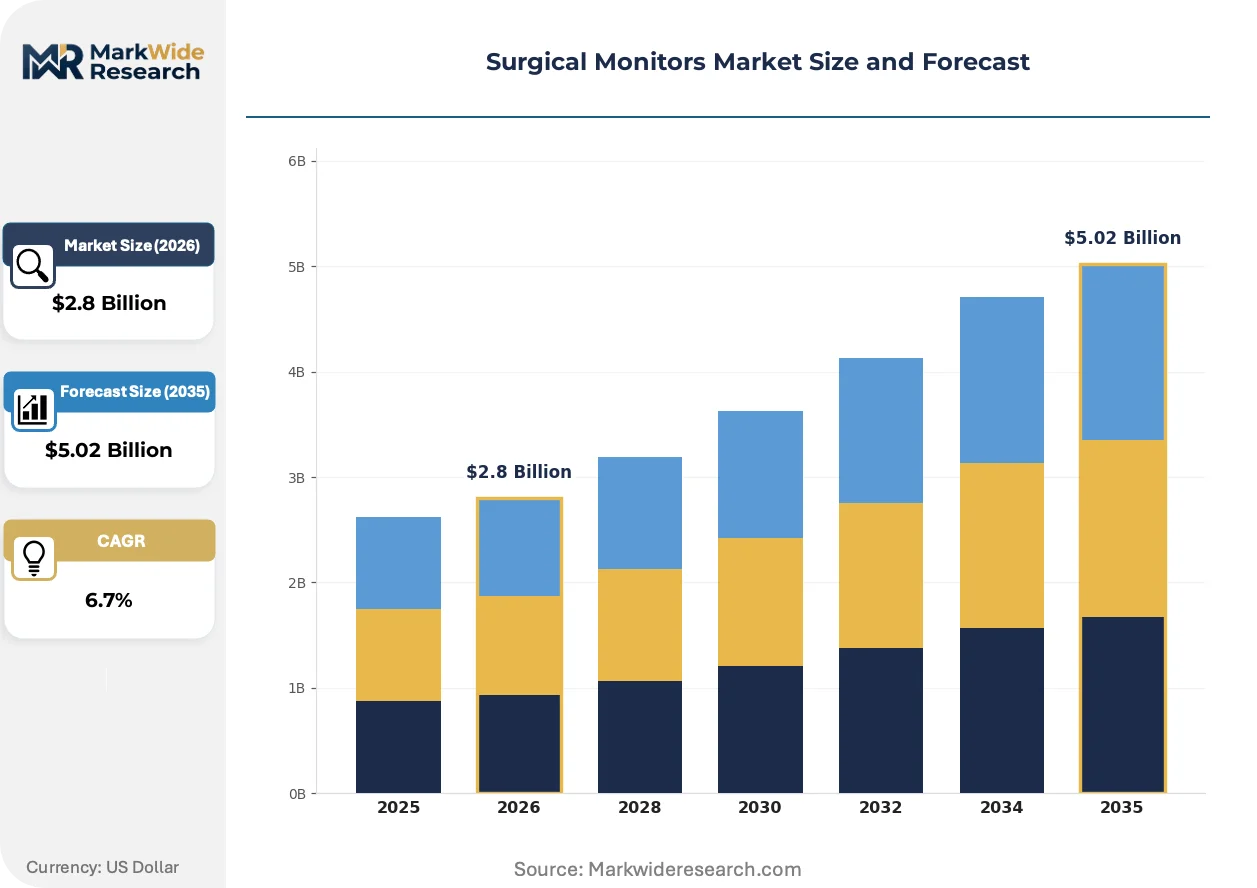
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, LED, OLED, 4K Technology: Digital, Analog, Wireless, Networked Application: Operating Room, Endoscopy, Surgery, Anesthesia End User: Hospitals, Ambulatory Care Centers, Clinics, Surgical Centers |
| Companies Covered | Stryker, Barco, Steris, Olympus Corporation, Sony Corporation, Eizo Corporation, LG Electronics, NDS Surgical Imaging, ADLINK Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Monitors Market Evolving Landscape
Display virtualization and software-defined imaging pipelines are displacing hardware-centric architectures, enabling surgical teams to route, process, and render video feeds through centralized compute resources rather than dedicated monitor electronics.
Software-defined visualization is virtualizing the traditional boundary between display hardware and image processing engines. Hybrid operating rooms in United States academic medical centers are piloting centralized GPU clusters that render surgical feeds to any endpoint screen. This architecture is virtualizing capital allocation decisions, allowing facilities to upgrade image processing capabilities without replacing physical monitors.
EU Medical Device Regulation post-market surveillance requirements are mandating continuous performance monitoring for surgical visualization systems. Manufacturers must now maintain clinical evidence repositories supporting claimed diagnostic accuracy throughout product lifecycles. High-risk device classifications in Germany and France are experiencing extended notified body review timelines, compressing competitive windows for new entrants.
Health system procurement departments are unbundling after-sales service contracts from capital equipment purchases. Group purchasing organizations in the United States are negotiating standalone technical service agreements with third-party biomedical engineering firms. This disintermediation is most visible in multi-hospital systems where standardized monitor fleets enable economies of scale in preventive maintenance programs.
Surgical Monitors Market Segmentation
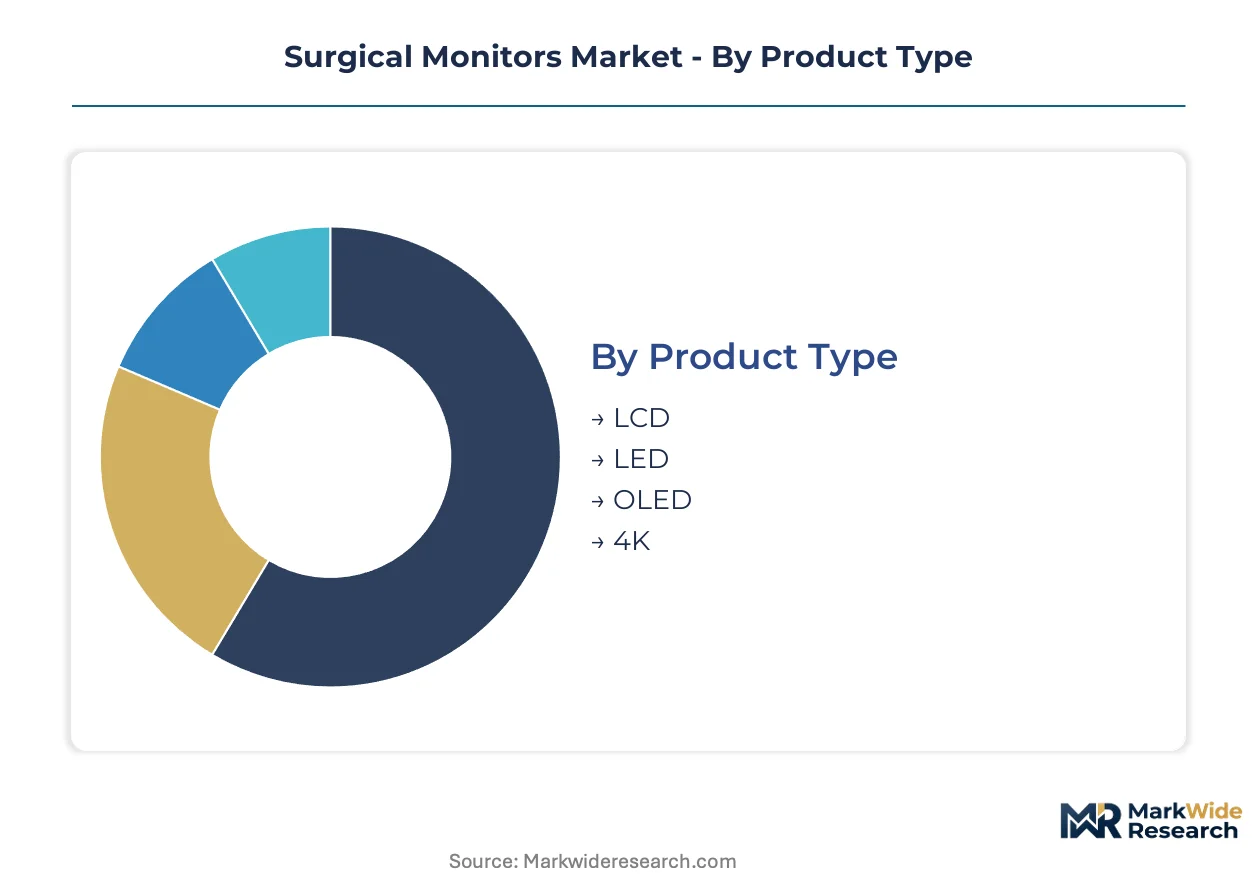
Surgical monitor segmentation reveals how capital allocation priorities diverge across facility types and procedural requirements. Technology choices and application contexts determine procurement patterns more than unit economics alone.
Product Type:
Cost tier differentiation separates commodity display hardware from premium visualization investments in modern surgical infrastructure.
- LCD:Mature liquid crystal display technology dominates installed bases in United States ambulatory surgical centers where extended depreciation schedules delay replacement decisions. Capital equipment replacement cycles constrain upgrade velocity despite superior alternatives entering the market.
- OLED:Organic light-emitting diode panels deliver contrast ratios and black-level performance that justify premium outlays in precision-dependent workflows across German university hospitals. Tissue differentiation demands in oncological resections drive procurement committees toward OLED specifications despite higher acquisition costs.
- LED:Light-emitting diode backlighting extends LCD performance envelopes with improved luminance stability for standard surgical applications.
- 4K:Ultra-high-definition resolution commands premium positioning as Japanese health systems prioritize visualization clarity investments for complex laparoscopic procedures.
LCD commands the established base. The steepest expansion runs through OLED.
Technology:
Signal transmission architecture determines infrastructure flexibility against real-time fidelity requirements in diverse care settings.
- Wireless:Radio-frequency transmission eliminates cable management constraints and enables rapid room reconfiguration in United States outpatient surgical facilities. Infrastructure flexibility and modular deployment priorities outweigh latency tolerance thresholds that constrain adoption in tertiary care environments.
- Networked:Internet protocol-based distribution supports centralized GPU clusters rendering surgical feeds to any endpoint screen in academic medical center pilot programs. Software-defined visualization architectures virtualize capital allocation decisions by decoupling image processing from physical display hardware.
- Digital:Native digital signal processing maintains bit-depth integrity through the imaging chain for diagnostic-grade applications.
- Analog:Legacy coaxial and VGA interfaces persist in older operating room installations requiring backward compatibility during phased modernization programs.
Networked systems are gaining share fastest in hybrid operating environments. Wireless climbs the fastest in ambulatory settings.
Application:
Procedural context dictates luminance specifications, color calibration requirements, and integration complexity with surgical navigation systems.
- Operating Room:Integrated surgical suites demand multi-input displays capable of simultaneous rendering from endoscopes, patient monitors, and navigation systems. German hospital systems modernizing aging infrastructure pull demand for high-resolution visualization supporting robotic-assisted procedures.
- Endoscopy:Gastrointestinal and pulmonary diagnostic procedures require specialized color calibration for mucosal tissue differentiation. Eizo Corporation's diagnostic display expertise concentrates competitive positioning in this precision-dependent segment.
- Surgery:General surgical applications span open and minimally invasive procedures with varying image latency tolerances.
- Anesthesia:Perioperative monitoring displays prioritize waveform clarity and alarm integration over high-definition video rendering.
Operating Room applications anchor capital expenditure. Endoscopy represents the fastest-growing trajectory.
End User:
Customer type determines procurement channel access, service contract structures, and standardization pressures across facility fleets.
- Hospitals:Integrated delivery networks consolidate vendor panels and negotiate enterprise-level contracts rather than individual facility sales. Group purchasing organization consolidation narrows direct procurement channels and forces manufacturers to secure system-level relationships.
- Ambulatory Care Centers:Outpatient surgical facilities prioritize wireless technology and rapid room turnover capabilities over the latency-sensitive architectures of tertiary institutions. United States health system procurement departments increasingly unbundle after-sales service from capital equipment purchases in this segment.
- Surgical Centers:Dedicated ambulatory surgery facilities balance infrastructure flexibility against reimbursement constraints in specialized procedure focus.
- Clinics:Smaller diagnostic and minor procedure settings deploy lower-specification displays with reduced integration requirements.
Hospitals command the established base. Ambulatory Care Centers gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics infrastructure underwrites Europe's distribution dominance for surgical visualization hardware. German hospital modernization programs pull premium display shipments through this gateway. Japanese port facilities at Yokohama and Kobe similarly anchor Asia-Pacific supply chains for high-resolution surgical monitors.
United States
Group purchasing organization consolidation across health systems narrows vendor access to enterprise-level contracts rather than individual facility sales. FDA cybersecurity guidance refinement compels manufacturers to embed threat mitigation architectures from initial design phases. Academic medical centers in Boston and the Research Triangle pilot software-defined visualization with centralized GPU clusters.
Germany
University hospitals in Bavaria and Baden-Württemberg prioritize OLED specifications for oncological resections demanding superior tissue differentiation. EU Medical Device Regulation clinical evidence mandates raise barriers for non-European entrants seeking CE marking. The Munich-Stuttgart industrial corridor hosts precision display calibration service providers supporting distributed monitor fleets.
Japan
Health system investments in complex laparoscopic procedures drive 4K visualization standardization across metropolitan Tokyo and Osaka medical districts. METI industrial policy supports domestic manufacturing of medical-grade display components. The Kansai region's electronics manufacturing base supplies color-calibration expertise for diagnostic-dependent surgical workflows.
China
Domestic hospital infrastructure expansion in the Yangtze River Delta and Pearl River Delta generates volume demand for surgical visualization systems. NMPA medical device registration requirements extend timeline-to-market for imported display technologies. Shanghai's biomedical engineering clusters develop localized middleware for PACS integration with next-generation monitor architectures.
Surgical Monitors Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply architecture. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with integrated surgical portfolios, precision display manufacturers with diagnostic-grade calibration expertise, and electronics fabricators leveraging scale advantages in panel production. Competitive positioning depends on securing enterprise-level procurement relationships and developing software-defined visualization architectures that decouple hardware refresh cycles from image processing capability upgrades.
Among diversified platform integrators, Stryker represents the system-level contract archetype controlling capital equipment decisions across integrated delivery networks. Barco exemplifies the specialized visualization technology tier with advanced image processing engines designed for hybrid operating room deployments. Eizo Corporation occupies a position within the precision display segment, leveraging color-calibrated diagnostic expertise to differentiate offerings in tissue-differentiation-dependent workflows.
| Leading Market Players |
|---|
| Stryker |
| Barco |
| Steris |
| Olympus Corporation |
| Sony Corporation |
| Eizo Corporation |
| LG Electronics |
| NDS Surgical Imaging |
| ADLINK Technology |
| Others |
Value Network & Pricing Analysis
The Munich-Stuttgart industrial corridor anchors European display calibration capacity, with precision service providers concentrated there feeding downstream pricing power to OEMs serving German university hospitals. This geographic concentration of biomedical engineering expertise enables premium-tier manufacturers to sustain margin structures against commoditized LCD alternatives flooding ambulatory markets.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations as group purchasing organizations consolidate vendor panels across United States health systems. Pricing stratifies across premium OLED specifications, standard 4K LCD deployments, and economy-tier LED backlit units for ambulatory settings. Cost compression in the LCD tier is intensifying because extended depreciation schedules delay replacement decisions despite superior OLED performance metrics. Ambulatory surgical centers exhibit highest price sensitivity, while German oncological resection suites demonstrate lowest sensitivity due to tissue differentiation demands.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwanese and South Korean electronics fabricators holding medical-grade panel capacity, supplemented by Japanese precision component specialists in the Kansai region. Raw material dependencies center on indium tin oxide for transparent electrodes, gallium nitride for LED backlighting, and specialized optical films for luminance calibration. Single-source vulnerability in OLED emitter material supply from Japanese chemical conglomerates poses structural risk. Distribution runs through Rotterdam's medical device logistics hub for European markets and Yokohama-Kobe port facilities for Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined visualization architectures threaten traditional hardware-centric business models, forcing incumbents to defend against disintermediation of their display electronics. Substitution pressure from centralized GPU clusters rendering to commodity endpoints demands strategic repositioning.
For Market Incumbents: Build switching-cost moats through deep integration with hospital PACS infrastructure and embedded cybersecurity architectures compliant with FDA post-market guidance. Secure enterprise-level contracts with integrated delivery networks before GPO consolidation completes. Prioritize ISO 13485 certification maintenance to defend against EU MDR-elevated barriers for non-European entrants. For New Entrants and Emerging Players: Pursue ambulatory surgical center wireless technology deployments where latency tolerance enables competitive entry against established tertiary-care incumbents. Target United States outpatient facilities prioritizing infrastructure flexibility over image fidelity. Lead with modular, rapid-deployment hardware configurations unbundled from long-term service contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision display calibration specialists with diagnostic-grade expertise transferable to surgical workflows. Long-term viability hinges on software-defined architecture transition enabling recurring revenue streams. Acquisition targets should demonstrate color-science IP and existing FDA 510(k) clearances. Monitor group purchasing organization vendor panel decisions as inflection indicators for competitive consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Compliance Pathway | Embedded threat mitigation architectures satisfy post-market surveillance requirements reshaping product development priorities. |
| CE Marking Under EU MDR | Clinical evidence mandates for surgical visualization claims raise barriers concentrating supply with ISO 13485-certified manufacturers. |
| Hospital System Partnership | Enterprise-level contracts with integrated delivery networks control capital equipment decisions at system level. |
| Software Companion Development | Centralized GPU cluster compatibility virtualizes capital allocation decisions decoupling processing from hardware refresh. |
| Reimbursement Strategy | Alignment with complex laparoscopic procedure coding in Japanese health systems drives 4K visualization prioritization. |
Research Methodology
The analysis maps LCD, OLED, LED, and 4K product segments, each validated through hospital procurement managers, biomedical engineering directors, GPO contracts specialists, and surgical visualization product managers. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR notified body assessments, hospital procurement databases, and group purchasing organization contract disclosures. Bottom-up unit demand modeling triangulated against top-down health system capital expenditure surveys.
Assumptions held fixed include FDA cybersecurity guidance refinement trajectory and EU MDR post-market surveillance enforcement intensity; variables tested spanned OLED technology maturation pace and wireless latency tolerance thresholds in tertiary settings. Segmentation dimensions modeled encompass display technology type, signal transmission architecture, procedural application context, and end-user facility category. CAGRs derived from procedure volume growth correlations and replacement cycle compression scenarios across German, Japanese, and United States hospital modernization programs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-based visualization platform entrants or hyperscaler healthcare divisions would shift outcomes beyond modeled ranges. Specific risk factors include accelerated software-defined architecture adoption, extended EU MDR notified body review timelines, and tariff exposure on Taiwanese panel imports. Quarterly review of GPO vendor panel announcements, FDA cybersecurity guidance updates, and OLED emitter material supply allocations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Face Shield Market
Medical Devices
Bioresorbable Coronary Scaffolds Market
Medical Devices
Oral Appliance Market
Medical Devices
Bone Allografts Market
Medical Devices
Global Keratometers Market
Medical Devices
Intubation Tubes Market
Medical Devices
X-Ray Positioning Devices Market
Medical Devices
Capsulotomy Market
Medical Devices
Peritoneal Catheter Systems Market
Medical Devices
Minimally Invasive Neurosurgical Devices Market
Medical Devices
Global Cardiopulmonary Resuscitation Device Market
Medical Devices
Ventricular Restoration Systems Market
Medical Devices
Water Bath Vaporizer Market
Medical Devices
PPG Biosensors Market
Medical Devices
Neurothrombectomy Devices Market
Medical Devices
Saudi Arabia Anesthesia Devices Market