
 Nasal Implant Market | 2026-2036
Nasal Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Nasal Implant Market Outlook
Recurring maintenance and revision service contracts is hardening as a distinct revenue layer in nasal implant portfolios. Stryker Corporation leverages its orthopedic service infrastructure to extend into post-implant monitoring programs. Medtronic anchors its competitive stance through deep channel control in ENT surgical suites across North America. Implantech Associates specializes in custom silicone carving kits that differentiate its offering for rhinoplasty specialists.
A nasal implant constitutes a biocompatible prosthesis, typically fabricated from medical-grade silicone, porous polyethylene, or autologous/cadaveric cartilage, designed to augment, reconstruct, or restore nasal structure and function following trauma, congenital deformity, or aesthetic modification. The device must meet ISO 10993 biocompatibility standards and withstand mechanical stress from nasal tissue dynamics while permitting vascular ingrowth where porous materials are employed. Silicone implants occupy the mature volume position due to decades of surgical familiarity and predictable explantation characteristics, though bio-absorbable formulations represent the fastest-expanding margin pool as resorbable polymers reduce long-term complication rates. Endoscopic delivery mode dominates functional restoration procedures, while injectable approaches capture growing interest in minimally invasive cosmetic corrections.
FDA 510(k) clearance pathways and the EU Medical Device Regulation govern market access thresholds, with the latter imposing stricter clinical evidence requirements for permanent implantable devices. The FDA's Center for Devices and Radiological Health maintains specific guidance on nasal and orbital implants regarding biocompatibility testing protocols. Surgeons and procurement officers must weigh evolving reimbursement policies against shifting material science capabilities as resorbable platforms challenge permanent implant economics.
Market Dynamics
The transition from permanent silicone implants to bio-absorbable polymer platforms is restructuring competitive advantage around complication-rate reduction rather than surgical familiarity alone.
Growth Catalysts
- EU Medical Device Regulation:Stricter clinical evidence requirements for permanent implants are accelerating manufacturer investment in resorbable material R&D pipelines.
- Ambulatory surgery centers:Transnasal delivery system adoption is expanding procedure volume outside traditional hospital settings across Germany and South Korea.
- Porous polyethylene:Vascular ingrowth capabilities in functional restoration applications are displacing silicone in trauma reconstruction segments.
Market Restraints
- Medical-grade silicone supply:Concentration among specialty chemical producers in Germany and Japan creates input cost volatility for permanent implant manufacturers.
- FDA 510(k) pathway friction:Biocompatibility testing protocol updates are extending clearance timelines for novel resorbable formulations.
- Autologous cartilage harvesting:Surgeon time intensity and donor site morbidity limit scalability of patient-specific reconstruction approaches.
Strategic Opportunities
- Brazil cosmetic surgery corridor:Underpenetrated demand for minimally invasive injectable approaches in Rio de Janeiro and São Paulo outpatient clinics.
- ISO 10993 harmonization:Emerging market regulators in Mexico and Turkey are adopting international biocompatibility standards, reducing duplicative testing burdens.
- Endoscopic-injectable convergence:Hybrid delivery platforms combining visualization precision with minimally invasive placement are opening revision procedure markets.
Industry Challenges
- Rhinoplasty specialist training:Steep learning curves for bio-absorbable implant carving and placement are constraining qualified surgeon supply in secondary markets.
- Legacy silicone explantation:Capsular contracture management protocols require capital-intensive revision infrastructure that resorbable platforms promise to obviate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nasal Implant Market |
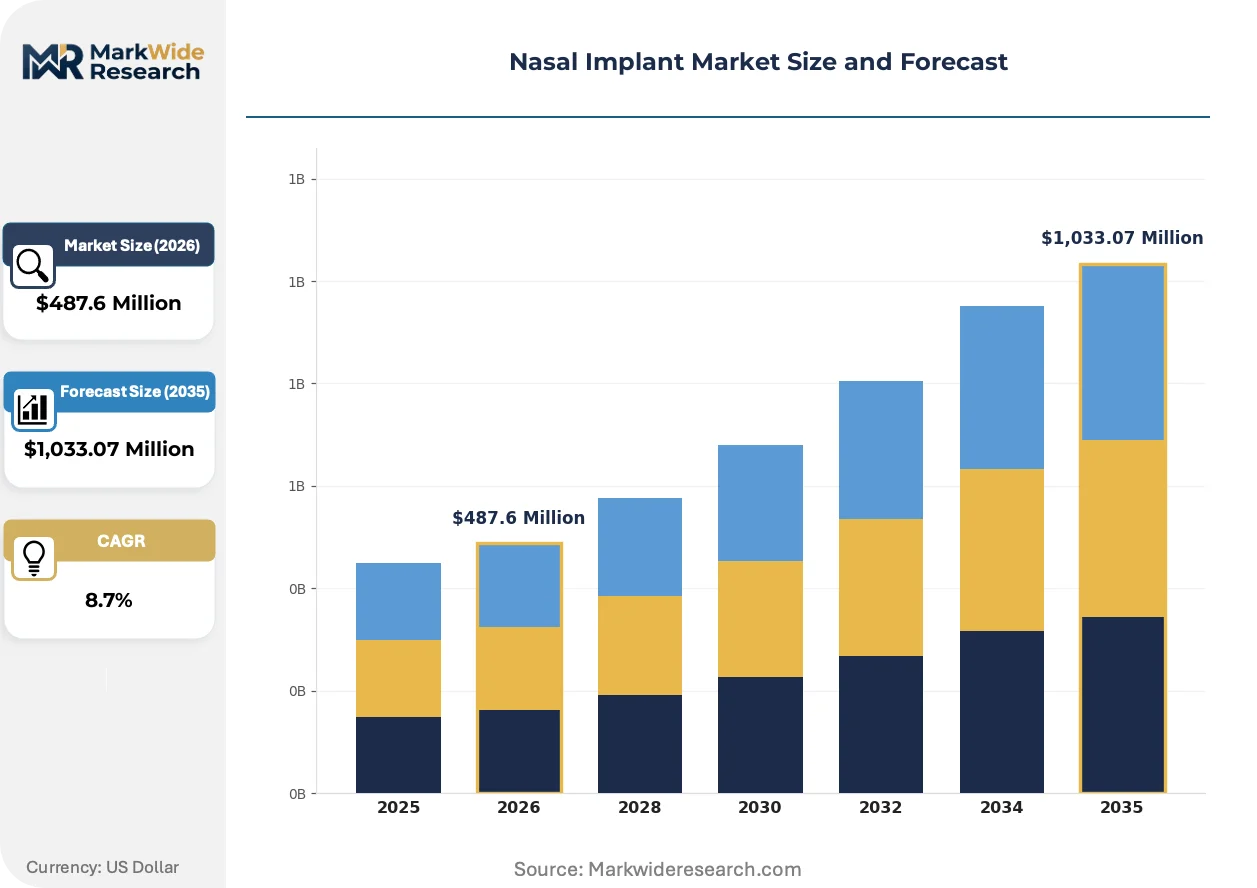
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Implants, Bone Implants, Cartilage Implants, Bio-absorbable Implants Delivery Mode: Endoscopic, Non-Endoscopic, Transnasal, Injectable End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Research Institutes Application: Cosmetic Surgery, Sinus Surgery, Trauma Repair, Functional Restoration |
| Companies Covered | Implantech Associates, Stryker Corporation, Zimmer Biomet Holdings, Johnson & Johnson, Ethicon, Intersect ENT, Medtronic, Sientra, Matrix Surgical USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nasal Implant Market Strategic Shifts
Material science breakthroughs in resorbable polymers and delivery mechanism miniaturization are compressing the traditional trade-off between implant permanence and biological integration.
3D-printed patient-specific bio-absorbable scaffolds are decentralizing production control from centralized manufacturing facilities to hospital-based point-of-care fabrication units. Academic medical centers in South Korea and Germany are piloting in-house polymer printing for complex congenital deformity cases. This capability is decentralizing supply chain power toward high-volume surgical departments with capital equipment budgets.
REACH substance restrictions on certain silicone catalyst residues are forcing European manufacturers to reformulate curing agents ahead of 2026 compliance deadlines. The regulation is compressing margins for implant producers dependent on legacy supply chains. German and Swiss manufacturers are responding with accelerated bio-absorbable platform launches to bypass permanent implant chemical scrutiny.
After-sales service unbundling is fragmenting traditional device-vendor relationships in North American ENT surgical suites. Procurement officers are separating implant supply contracts from post-operative monitoring and revision scheduling. This shift is most visible in United States ambulatory surgery centers negotiating direct-to-manufacturer pricing while outsourcing follow-up care to independent service organizations.
Nasal Implant Market Segmentation
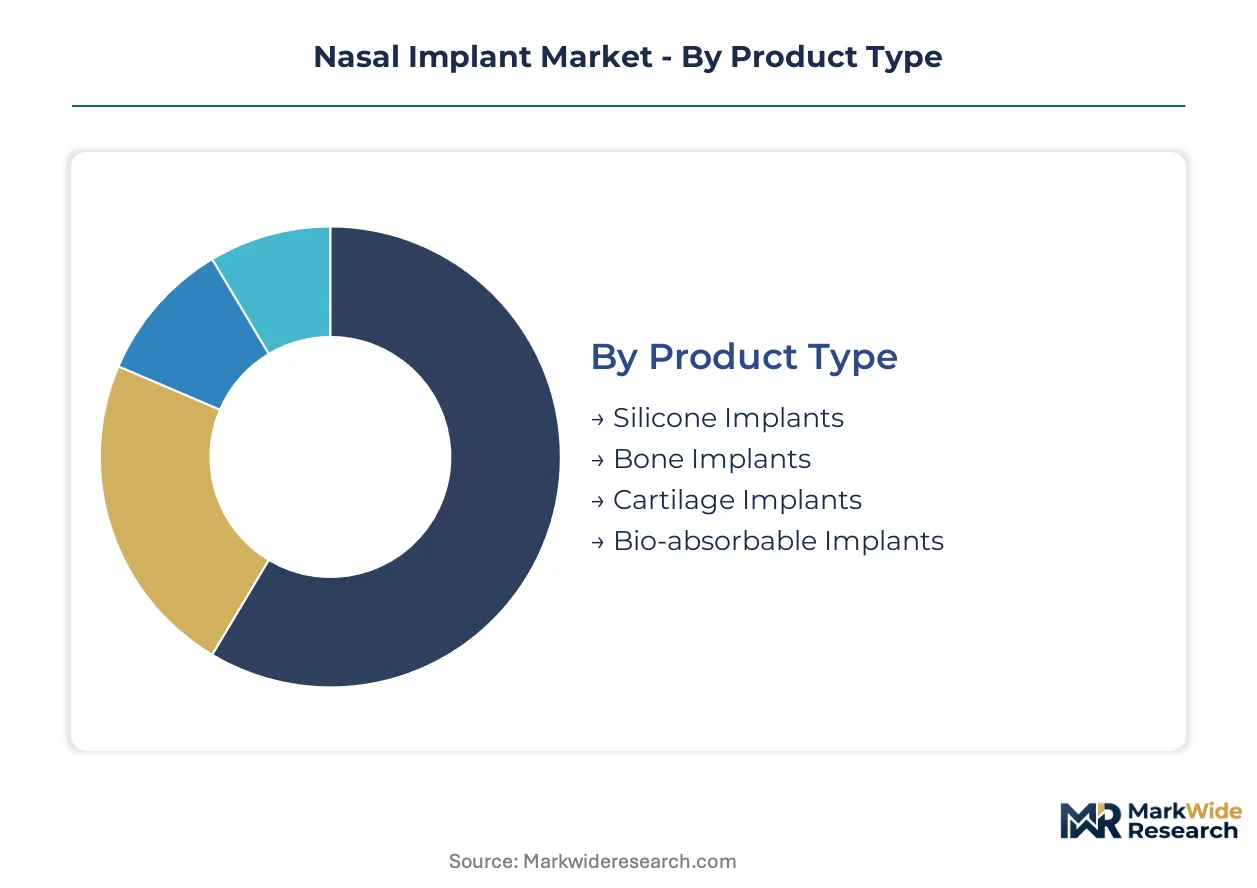
Segmentation in the nasal implant market reveals how material science capabilities, surgical venue economics, and procedure type requirements reshape procurement patterns. Manufacturers configure production lines and distribution networks around these divides, with each segment demanding distinct regulatory dossiers and surgeon training protocols.
Product Type:
Supply concentration in medical-grade silicone production centers in Germany and Japan directly shapes which implant categories dominate hospital formularies versus which face input cost volatility.
- Silicone Implants:Fabricated from medical-grade polydimethylsiloxane with Shore A durometer ratings optimized for nasal tissue compliance. Decades of surgical familiarity in South Korea and Brazil sustain volume leadership despite capsular contracture risks that drive revision demand. REACH substance restrictions on catalyst residues are forcing European manufacturers toward reformulated curing agents.
- Bio-absorbable Implants:Composed of resorbable polymers including polylactic acid and polyglycolic acid copolymers that hydrolyze over 12-24 months. Trauma reconstruction units in Germany are adopting these platforms to eliminate permanent foreign body complications and reduce long-term monitoring burdens. EU MDR clinical evidence requirements for permanent implants accelerate R&D investment in resorbable alternatives.
- Bone Implants:Derived from processed cadaveric or synthetic hydroxyapatite matrices for structural augmentation.
- Cartilage Implants:Autologous or cadaveric grafts requiring specialized carving instrumentation and extended operative time.
Silicone implants absorb the bulk of installed capacity; bio-absorbable implants are expanding most quickly.
Delivery Mode:
Procedure volume economics in ambulatory settings favor delivery technologies that compress operative time and reduce anesthesia requirements.
- Endoscopic:Fiber-optic visualization systems enabling precise implant placement through nasal cavity access. Functional restoration procedures in United States ENT surgical suites rely on this modality for trauma and congenital deformity cases where anatomical precision governs airway patency outcomes.
- Injectable:Minimally invasive approaches using resorbable polymer fillers or small-caliber delivery cannulas. Outpatient cosmetic clinics in Rio de Janeiro and São Paulo are piloting these techniques for dorsal augmentation without open rhinoplasty incisions.
- Transnasal:Specialized instrumentation for implant insertion through natural nasal passages.
- Non-Endoscopic:Traditional open surgical approaches requiring external columellar incisions.
Endoscopic delivery commands the highest procedure value; injectable approaches are gaining share fastest among cosmetic applications.
End User:
Capital equipment requirements and reimbursement rate differentials segment procurement authority across surgical venue types.
- Ambulatory Surgery Centers:Freestanding facilities with streamlined credentialing and direct-to-manufacturer contracting leverage. Transnasal delivery system adoption in Germany and South Korea is concentrating volume growth here as procurement officers unbundle implant supply from post-operative monitoring services.
- Hospitals:Academic medical centers with in-house 3D printing capabilities for patient-specific bio-absorbable scaffolds. Complex congenital deformity reconstruction in Seoul and Berlin hospitals is decentralizing production control toward point-of-care fabrication units.
- Specialty Clinics:Rhinoplasty-focused practices with dedicated carving instrumentation suites.
- Research Institutes:Preclinical and clinical trial sites evaluating novel resorbable formulations.
Hospitals retain the deepest implant portfolios; ambulatory surgery centers are climbing the fastest on procedure volume metrics.
Application:
Clinical outcome requirements and complication liability exposure vary sharply between aesthetic and functional indications.
- Cosmetic Surgery:Elective dorsal augmentation and tip refinement procedures where patient satisfaction metrics and revision rates determine practice economics. Brazil's outpatient clinic corridor shows underpenetrated demand for minimally invasive approaches in Rio de Janeiro and São Paulo.
- Functional Restoration:Airway patency reconstruction following trauma or congenital deformity. Porous polyethylene vascular ingrowth capabilities are displacing silicone in United States trauma centers where implant stability and tissue integration govern long-term outcomes.
- Trauma Repair:Acute nasal fracture management requiring immediate structural support.
- Sinus Surgery:Combined functional endoscopic sinus surgery with implant placement for orbital or skull base defects.
Cosmetic surgery commands the highest margin per procedure; functional restoration is expanding most quickly on trauma reconstruction demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese chemical producers supply medical-grade silicone to fabrication facilities worldwide, while surgical demand concentrates in cosmetic surgery corridors across Brazil, South Korea, and select United States metropolitan markets.
United States
FDA 510(k) clearance pathways govern market access for permanent and resorbable implant platforms, with the Center for Devices and Radiological Health maintaining specific biocompatibility testing guidance for nasal and orbital devices. Ambulatory surgery centers in Texas and Florida are unbundling implant supply contracts from post-operative monitoring services, compressing traditional vendor relationships. Trauma reconstruction units in Baltimore and Philadelphia trauma centers are adopting porous polyethylene platforms for vascular ingrowth capabilities.
Germany
EU Medical Device Regulation clinical evidence requirements for permanent implants are accelerating manufacturer investment in resorbable polymer R&D pipelines. REACH substance restrictions on silicone catalyst residues are forcing reformulation of curing agents ahead of 2026 compliance deadlines. Academic medical centers in Berlin and Munich are piloting in-house 3D printing of patient-specific bio-absorbable scaffolds for complex congenital deformity cases.
Brazil
Cosmetic surgery demand concentrates in Rio de Janeiro and São Paulo outpatient clinics, with underpenetrated corridors showing growing interest in minimally invasive injectable approaches. ANVISA regulates medical device registration through risk-based classification pathways. Private clinic networks in São Paulo's Jardins district are negotiating direct-to-manufacturer pricing for dorsal augmentation procedures.
South Korea
MFDS oversees medical device approval with streamlined pathways for bio-absorbable formulations meeting ISO 10993 standards. Seoul-based academic medical centers are decentralizing production control through hospital-based point-of-care fabrication units for custom scaffold printing. Gangnam district cosmetic surgery clusters are expanding transnasal delivery system adoption outside traditional hospital settings.
Japan
PMDA regulatory frameworks emphasize long-term safety surveillance for permanent implantable devices, creating favorable conditions for resorbable platform market entry. Medical-grade silicone supply concentration among domestic specialty chemical producers generates input cost stability for domestic manufacturers. Osaka and Tokyo metropolitan surgical suites maintain preference for endoscopic delivery modalities in functional restoration procedures.
Nasal Implant Market Competitive Environment
Top-tier vendors anchor premium implant portfolios and deep ENT surgical suite channel control, while mid-tier specialists carve position through material science differentiation and regional fabrication proximity. Orthopedic conglomerates leverage existing service infrastructure to extend into post-implant monitoring programs. Pure-play silicone carvers defend position through rhinoplasty specialist relationships and custom instrumentation suites. Competitive moves concentrate on backward integration into polymer supply and strategic partnerships with ambulatory surgery center networks.
Among diversified medical technology conglomerates, Stryker Corporation and Medtronic occupy positions that exemplify channel control and service infrastructure extension strategies. Within the specialist fabrication tier, Implantech Associates represents the custom silicone carving archetype for rhinoplasty-focused practices. These three entities collectively illustrate the competitive divide between scale-driven platform consolidation and specialist-driven customization capabilities.
| Leading Market Players |
|---|
| Implantech Associates |
| Stryker Corporation |
| Zimmer Biomet Holdings |
| Johnson & Johnson |
| Ethicon |
| Intersect ENT |
| Medtronic |
| Sientra |
| Matrix Surgical USA |
| Others |
Value Chain & Pricing Dynamics
Bio-absorbable polymer platform transitions are compressing cost structures for European manufacturers while simultaneously concentrating supply power among German and Japanese specialty chemical producers with certified medical-grade silicone capabilities. This dual dynamic creates asymmetric pricing pressure across implant tiers.
Pricing Analysis
Cost-down pressure on permanent silicone tiers accelerates because REACH substance restrictions force reformulation investments ahead of compliance deadlines. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared resorbable platforms from CE-marked permanent implants and unbundled commodity silicone. Procurement officers at United States ambulatory surgery centers exhibit highest price sensitivity through direct-to-manufacturer contracting, while academic medical centers with in-house 3D printing capabilities show lowest sensitivity due to point-of-care fabrication control.
Supply Chain Analysis
ISO 10993 biocompatibility certification gates access to hospital formularies and creates qualification backlogs for new polymer entrants. Medical-grade silicone supply concentrates in Germany and Japan, while resorbable polymer feedstocks draw from United States and South Korean chemical producers. Single-source vulnerability persists for high-purity polydimethylsiloxane precursors. Distribution runs through orthopedic and ENT surgical suite channel partners with established GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nasal implant market functions as a cost-of-compliance story where EU Medical Device Regulation clinical evidence requirements erect barrier-to-entry moats favoring manufacturers with resorbable R&D pipelines and established regulatory dossiers.
For Market Incumbents: To counter bio-absorbable platform disruption from specialized polymer startups, anchor position through backward integration into medical-grade silicone supply and accelerated CE marking for next-generation resorbable scaffolds. Deepen channel control in United States ambulatory surgery centers through unbundled service contracts that separate implant supply from post-operative monitoring. For New Entrants and Emerging Players: Begin with minimally invasive injectable approaches in Brazil's Rio de Janeiro and São Paulo outpatient corridor, where underpenetrated demand for dorsal augmentation without open rhinoplasty creates white-space opportunity. Partner with Gangnam district cosmetic surgery clusters for transnasal delivery system pilot programs. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier fabrication specialists possessing ISO 10993-certified polymer capabilities and established surgeon training protocols, given EU MDR acceleration of resorbable platform adoption. Monitor ANVISA registration pathway streamlining in Brazil as inflection indicator for Latin American market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements accelerate resorbable platform investment ahead of permanent implant scrutiny. |
| Hospital System Partnership | Academic medical centers in Seoul and Berlin decentralize production through point-of-care 3D printing capabilities. |
| Reimbursement Strategy | Ambulatory surgery centers in Texas and Florida unbundle implant supply from post-operative monitoring services. |
| FDA Submission | Biocompatibility testing protocol updates extend clearance timelines for novel resorbable formulations. |
| Software Companion Development | Post-implant monitoring programs leverage orthopedic service infrastructure for revision scheduling optimization. |
Study Parameters
Document review covered FDA 510(k) clearance databases, EU Medical Device Regulation guidance documents, and REACH substance restriction filings, complemented by interviews with ENT surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from ISO 10993 biocompatibility standards, ANVISA registration records, and MFDS approval pathways. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue allocations.
Cross-referencing historical adoption curves against surgeon panel input informed the analytical framework across the projection horizon. Segmentation dimensions modeled include material type, delivery mode, surgical venue, and application indication. CAGRs derived from compound growth mechanics applied to base-year value estimates, incorporating trauma reconstruction demand trajectories and cosmetic procedure elasticity assumptions.
Underlying measurement precision varies by segment; bio-absorbable implant forecasts carry tighter precision than silicone tiers due to concentrated manufacturer visibility. Forecasts reflect documented assumptions regarding regulatory pathway timelines and surgeon training scalability. A model refresh is warranted upon material change in EU MDR enforcement posture or REACH compliance deadline adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Biodegradable Stents Market
Medical Devices
Phakic Intraocular Lenses (IOL) Market
Medical Devices
C-Arms Devices Market
Medical Devices
Trial Prostheses Market
Medical Devices
Medical Device and Accessories Market
Medical Devices
Mexico Electrocardiograph (ECG) Market
Medical Devices
Dialysis Disposable Devices Market
Medical Devices
Chest Drainage Devices Market
Medical Devices
Global Healthcare Nanotechnology (Nanomedicine) Market
Medical Devices
Spain Diabetes Devices Market
Medical Devices
Global Operating Microscopes Market
Medical Devices
Balloon Catheters for Bile Stone Removal Market
Medical Devices
Alexandrite Gemstone Lasers Market
Medical Devices
Implant-Borne Prosthetics Market
Medical Devices
Global Adult and Pediatric Hemoconcentrators Market
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market