
 Manufacturing on Demand for Medical Market | 2026-2036
Manufacturing on Demand for Medical Market Size, Share, and Industry Trends Forecast 2026-2036
Manufacturing on Demand for Medical Market Insights
Buyer concentration among hospital networks and large medical device OEMs is expanding, pulling volume toward contracted on-demand suppliers with validated quality systems. Protolabs leverages its digital quoting engine and domestic U.S. manufacturing footprint to serve urgent surgical instrument orders. Xometry competes through its distributed supplier network, matching hospital buyers with CNC machining and additive capacity across multiple ISO-certified facilities. SyBridge Technologies anchors complex injection molding programs for diagnostic housings, sustaining tool-transfer capabilities that reduce OEM qualification timelines.
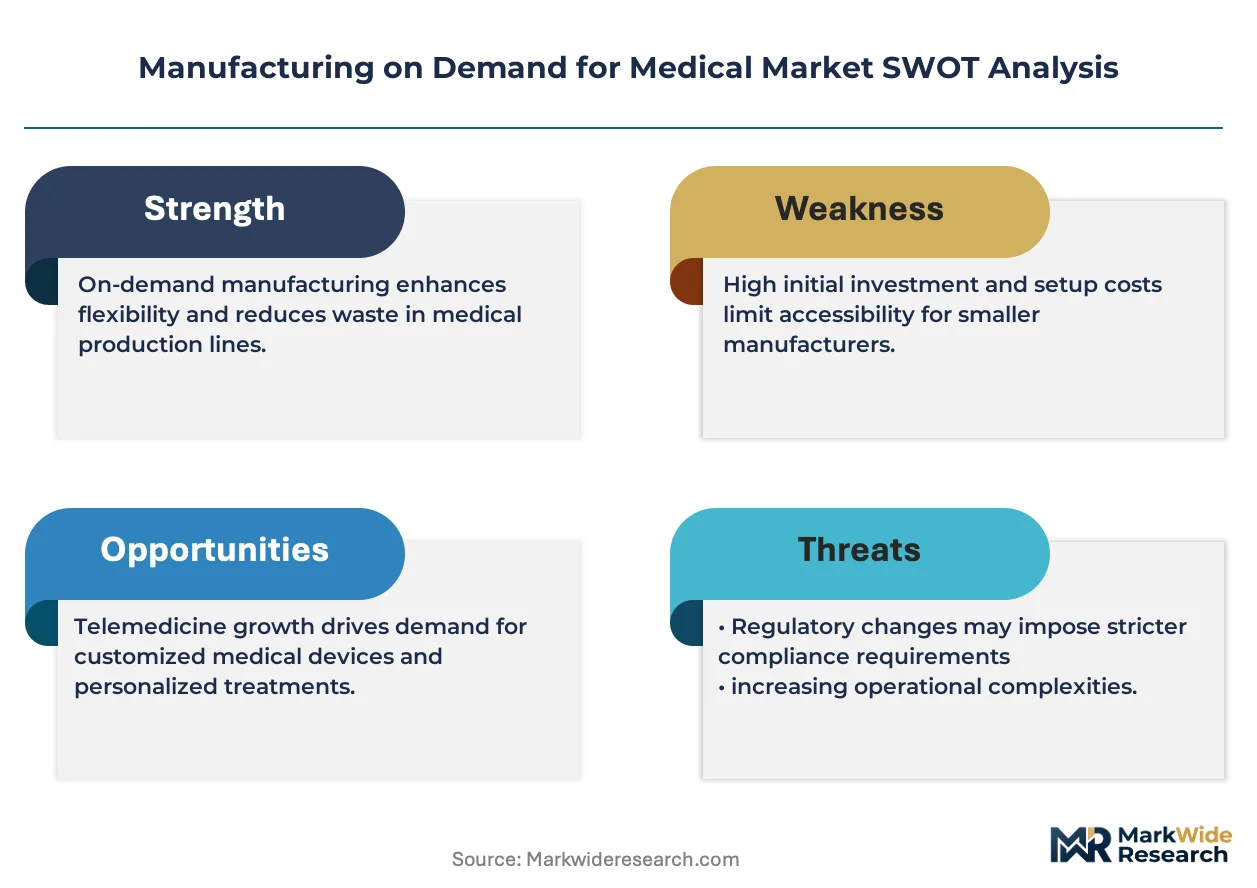
Manufacturing on Demand for Medical encompasses digitally triggered, low-to-medium volume production of regulated medical components, typically executed through additive, subtractive, or formative processes with material traceability and process validation under ISO 13485. Parts must meet biocompatibility standards such as ISO 10993, with surface finish and dimensional tolerances specified for sterilization compatibility and patient contact. Custom implants and surgical instruments lead current revenue pools, reflecting high margins on patient-specific geometries and accelerated surgical workflows. 3D printing in titanium and PEEK is growing fastest among technology segments, driven by orthopedic and cranio-maxillofacial applications where conventional tooling economics fail. Diagnostic devices remain the most mature product category, with price pressure from high-volume Asian contract manufacturers compressing margins for Western on-demand suppliers.
FDA enforces 21 CFR Part 820 quality system requirements on U.S.-based on-demand producers, while EU MDR and CE marking obligations govern market access across European member states. Japan's PMDA imposes additional clinical and manufacturing site inspections on foreign suppliers, creating compliance layering that favors vertically integrated domestic platforms. Stakeholders must monitor how FDA's evolving guidance on additive manufacturing validation and EU MDR post-market surveillance requirements reshape supplier qualification burdens and capital deployment priorities.
Market Dynamics
Hospital procurement consolidation and FDA additive manufacturing validation guidance are compressing supplier qualification timelines while concentrating volume among ISO 13485-certified on-demand platforms with validated quality systems.
Growth Catalysts
- EU MDR compliance deadlines:Device manufacturers face accelerated recertification timelines under the 2017/745 regulation, pulling production toward validated European on-demand suppliers with established technical documentation capabilities.
- Titanium additive manufacturing:Orthopedic implant producers are adopting electron beam melting for patient-specific cranial plates, enabling geometries impossible through conventional CNC machining.
- Baden-Württemberg cluster density:Stuttgart-Tübingen medical device ecosystems concentrate precision machining and polymer processing expertise within 50-kilometer supplier networks.
Market Restraints
- PEEK resin supply concentration:Solvay and Victrex control 80% of implant-grade polyetheretherketone polymer supply, exposing on-demand molders to price volatility and allocation risk.
- Japan PMDA manufacturing site inspections:Foreign on-demand suppliers face 12-18 month qualification timelines for direct hospital sales, favoring domestic Japanese production platforms.
- Surface finish limitations:As-printed titanium roughness values of 10-15 μm Ra exceed orthopedic articulating surface requirements, necessitating secondary CNC finishing that erodes additive cost advantages.
Strategic Opportunities
- Brazil ANVISA pathway acceleration:Streamlined registration for Class II devices manufactured under ISO 13485 creates first-mover positioning for on-demand suppliers in Latin America's largest medical device market.
- Point-of-care sterilization integration:Combining on-demand production with hospital-based ethylene oxide or vaporized hydrogen peroxide systems collapses supply chain lead times for urgent surgical instrument replacement.
- AI-driven generative design:Topology optimization software converging with additive constraints is enabling mass-customized implant libraries that reduce surgical planning time.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization studies require 16-24 weeks at accredited laboratories, compressing product development windows for patient-specific devices.
- Post-processing equipment capex:Hot isostatic pressing and precision grinding investments of $2-4 million per facility strain mid-cap on-demand suppliers serving orthopedic OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manufacturing on Demand for Medical Market |
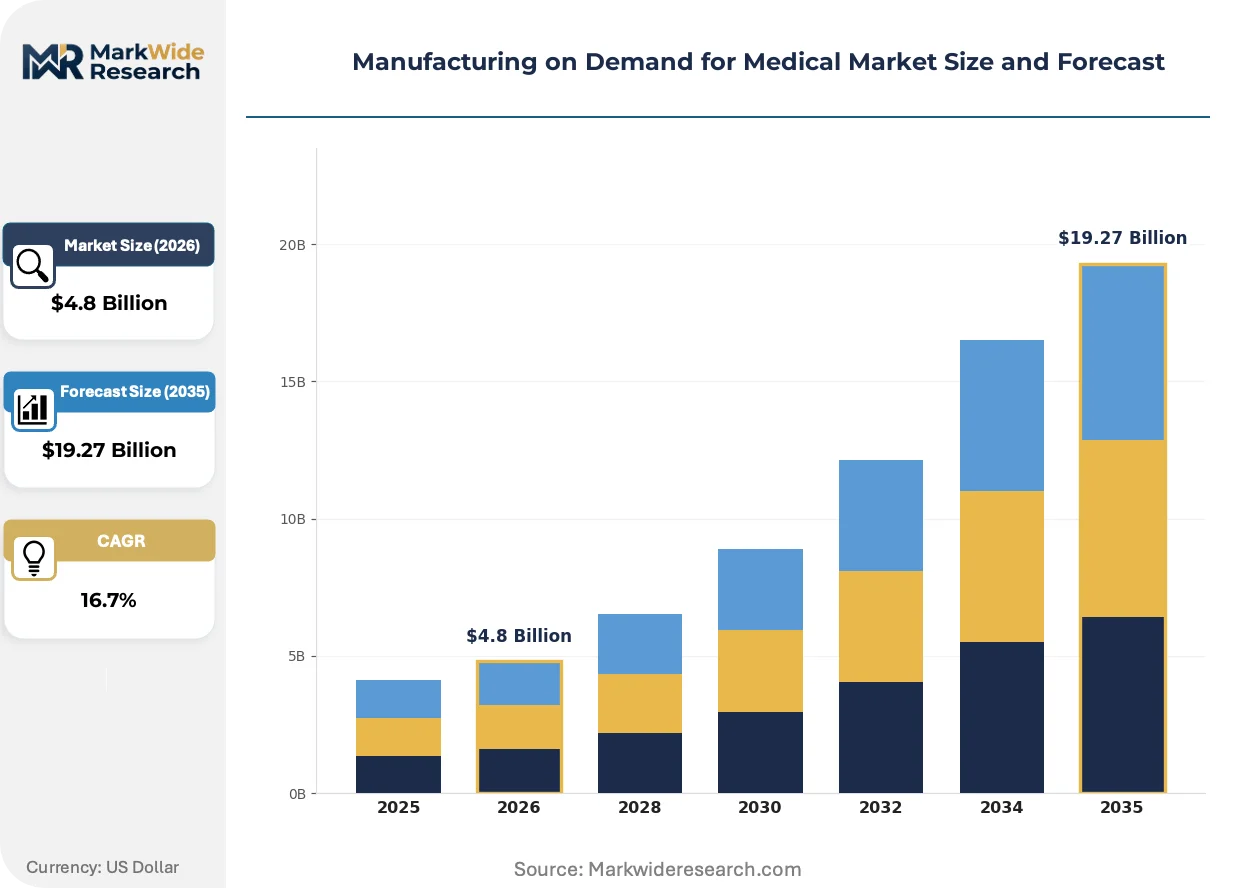
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custom Implants, Surgical Instruments, Prosthetics, Diagnostic Devices, Wearable Sensors Technology: 3D Printing, CNC Machining, Laser Sintering, Injection Molding, Bioprinting End User: Hospitals, Research Institutes, Rehabilitation Centers, Medical Device Manufacturers, Clinical Labs Application: Orthopedics, Cardiology, Dental Devices, Neurology Equipment, Wound Care |
| Companies Covered | SyBridge Technologies, Quickparts, Protolabs, Xometry, Jabil, Fathom Manufacturing, Igus, Fictiv, Prototek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manufacturing on Demand for Medical Market Trends and Innovations
Digitally triggered production workflows are collapsing traditional tooling economics while regulatory agencies impose validation requirements that favor platforms with embedded quality systems and material traceability infrastructure.
Multi-axis CNC machining with in-process probing is integrating real-time dimensional feedback for surgical instrument finishing, enabling tolerances of ±5 μm on reamer and drill geometries. Academic medical centers in Massachusetts and Bavaria are adopting these platforms for same-day instrument modification. The technology is integrating quality documentation directly into production records, compressing FDA 510(k) submission preparation.
FDA's 2017 guidance on additive manufacturing validation and 2023 updates to 21 CFR Part 820 software validation requirements are mandating process parameter lockdowns for titanium and PEEK implant production. Device manufacturers must demonstrate layer-wise thermal monitoring equivalence across machines and sites. Orthopedic OEMs with captive additive capacity are responding by centralizing production at single validated facilities rather than distributed on-demand networks.
Hospital materials management departments are consolidating vendor lists from 200+ machining suppliers to 8-12 contracted on-demand platforms with blanket purchase agreements and consignment inventory arrangements. This concentration displaces spot-buying through distributor catalogs. The shift is most advanced in German hospital networks and US integrated delivery networks with centralized procurement functions.
Manufacturing on Demand for Medical Market Segmentation
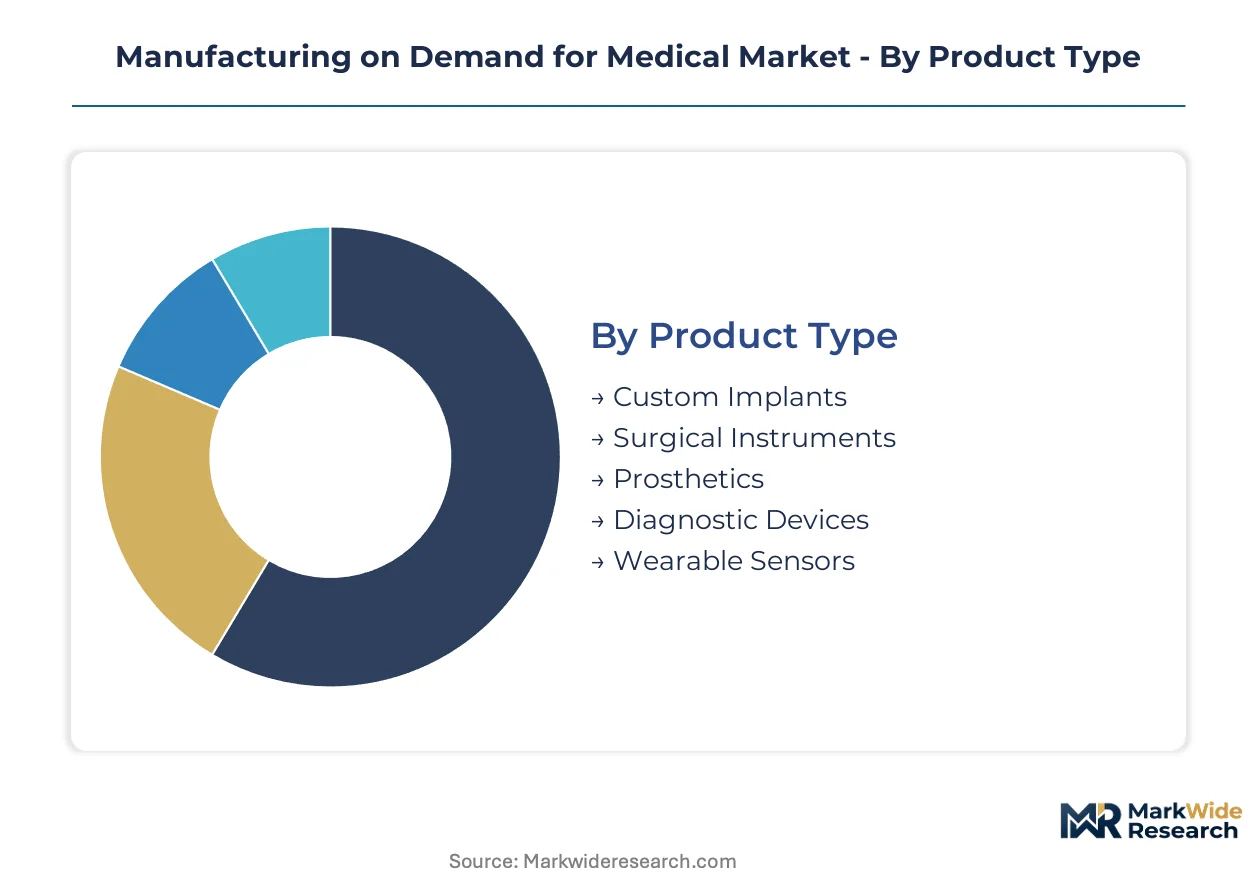
Manufacturing on Demand for Medical Market segmentation reveals divergent margin profiles across product categories, with patient-specific geometries commanding premium pricing while diagnostic devices face commoditization pressure from high-volume Asian contract manufacturers. Technology selection and end-user procurement consolidation are reshaping competitive boundaries within each segment.
Product Type:
Volume concentrates in standardized diagnostic housings, while premium economics cluster around patient-specific geometries with regulatory validation requirements.
- Custom Implants:Titanium and PEEK geometries produced through electron beam melting or precision CNC machining, with layer-wise thermal monitoring documentation required for FDA 510(k) submissions. German orthopedic OEMs in Baden-Württemberg dominate demand for cranial and spinal patient-specific devices, driven by EU MDR technical documentation burdens that favor validated on-demand suppliers.
- Surgical Instruments:Patient-specific reamers, drills, and cutting guides machined to ±5 μm tolerances with in-process probing documentation. Massachusetts academic medical centers are expanding same-day instrument modification programs, compressing traditional 6-8 week procurement cycles for urgent replacement orders.
- Prosthetics:Silicone and polymer limb components with surface finish specifications for patient skin contact.
- Diagnostic Devices:Injection-molded housings and fluidic cartridges facing margin compression from high-volume Asian manufacturers.
- Wearable Sensors:Flexible polymer substrates with biocompatibility certification under ISO 10993.
Today's leader: Custom Implants. Tomorrow's challenger: Surgical Instruments.
Technology:
Process selection maps directly to regulatory validation burden and capital intensity, with additive platforms requiring $2-4 million post-processing investments per facility.
- 3D Printing:Powder bed fusion in titanium and PEEK enabling topologically optimized geometries impossible through subtractive methods. FDA's evolving additive manufacturing validation guidance is mandating process parameter lockdowns, pushing orthopedic OEMs toward centralized single-facility production rather than distributed networks.
- CNC Machining:Multi-axis mills with real-time dimensional feedback for surgical instrument finishing to ±5 μm tolerances. Bavarian precision machining clusters anchor European demand, with Stuttgart-Tübingen supplier networks concentrating within 50-kilometer radii.
- Laser Sintering:Polyamide and TPU production for prosthetic sockets and wearable sensor housings.
- Injection Molding:High-volume diagnostic device production with tool-transfer capabilities reducing OEM qualification timelines.
- Bioprinting:Extrusion-based deposition of cell-laden bioinks for research-stage tissue engineering applications.
3D Printing captures the steepest expansion trajectory as orthopedic applications outgrow conventional tooling economics.
End User:
Procurement consolidation is collapsing vendor lists from 200-plus machining suppliers to 8-12 contracted platforms with blanket purchase agreements.
- Hospitals:Integrated delivery networks with centralized materials management functions, advancing consignment inventory arrangements with ISO 13485-certified on-demand suppliers. German hospital networks lead this concentration, displacing spot-buying through distributor catalogs.
- Medical Device Manufacturers:OEMs outsourcing patient-specific production while retaining captive additive capacity for core implant lines.
- Research Institutes:Academic medical centers in Massachusetts and Bavaria adopting same-day instrument modification platforms.
- Rehabilitation Centers:Prosthetic fitting facilities with direct digital scanning-to-manufacture workflows.
- Clinical Labs:Diagnostic consumable procurement facing price pressure from high-volume contract manufacturers.
Hospitals are consolidating fastest; Medical Device Manufacturers retain the highest contract values per relationship.
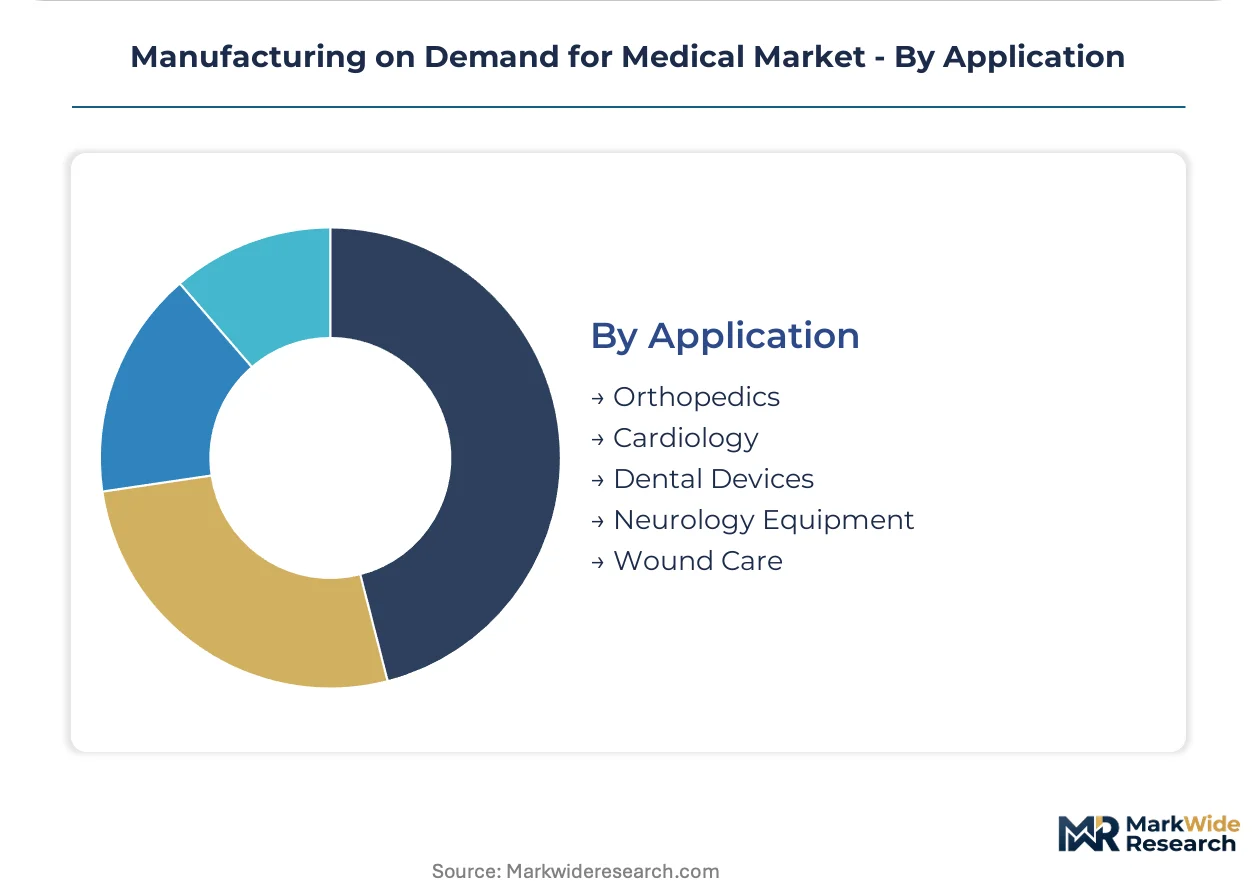
Application:
Orthopedic and cranio-maxillofacial applications command the widest margins, while wound care faces reimbursement compression.
- Orthopedics:Spinal fusion cages, hip acetabular cups, and knee tibial trays in titanium and PEEK, with electron beam melting enabling patient-specific porous structures for osseointegration. Surface finish limitations of 10-15 μm Ra on as-printed titanium necessitate secondary CNC finishing for articulating surfaces.
- Cardiology:Structural heart device components and catheter-based delivery systems requiring biocompatibility validation under ISO 10993.
- Dental Devices:Custom abutments and surgical guides with shorter regulatory pathways than implantable orthopedics.
- Neurology Equipment:Deep brain stimulation lead fixtures and cranial fixation systems with precision tolerance requirements.
- Wound Care:Negative pressure therapy components and advanced dressing substrates facing reimbursement pressure.
Orthopedics anchors current revenue; Dental Devices offer the shortest path to commercialization for new entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision engineering talent clusters in southern Germany and Massachusetts anchor the industry's workforce concentration, with Baden-Württemberg and Bavaria housing Europe's densest medical device manufacturing ecosystems. These regions supply the ISO 13485-certified engineers and quality specialists that validate on-demand production platforms.
United States
Massachusetts academic medical centers and Texas hospital networks drive demand for patient-specific surgical instruments with same-day modification capabilities. FDA's 21 CFR Part 820 quality system requirements enforce process validation standards that favor domestic suppliers with established technical documentation infrastructure. The Greater Boston corridor concentrates additive manufacturing expertise for orthopedic applications.
Germany
EU MDR compliance deadlines accelerate recertification timelines, pulling production toward validated on-demand suppliers with established technical documentation capabilities. The country's national pharmaceutical regulator enforces post-market surveillance requirements that reshape supplier qualification burdens. Stuttgart-Tübingen medical device ecosystems concentrate precision machining and polymer processing expertise within 50-kilometer supplier networks.
Japan
PMDA manufacturing site inspections impose 12-18 month qualification timelines for foreign on-demand suppliers seeking direct hospital sales. The country's national pharmaceutical regulator favors vertically integrated domestic platforms with captive additive capacity. Tokyo-Osaka industrial corridors anchor captive production networks for orthopedic OEMs.
Switzerland
Swissmedic certification requirements for implant-grade devices sustain premium positioning for precision machining suppliers serving cranial and spinal applications. The country's national pharmaceutical regulator maintains stringent clinical evaluation standards that filter market entrants. Basel-Zurich medical technology clusters concentrate electron beam melting expertise for titanium patient-specific geometries.
Brazil
ANVISA pathway acceleration for Class II devices manufactured under ISO 13485 creates first-mover positioning for on-demand suppliers in Latin America's largest medical device market. The country's national pharmaceutical regulator streamlines registration processes that reduce time-to-market for validated foreign suppliers. São Paulo state anchors diagnostic device manufacturing with expanding procurement from hospital networks.
Manufacturing on Demand for Medical Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: digital-native platforms with automated quoting engines, precision machining specialists with captive tool-transfer capabilities, and diversified contract manufacturers with vertical integration into regulatory consulting. Consolidation pressure concentrates volume among ISO 13485-certified platforms with validated quality systems. Competitive moves center on strategic partnerships with hospital procurement networks and geographic expansion into Brazil and Japanese markets.
Within the digital-native platform tier, Protolabs and Xometry exemplify divergent network architectures—one leveraging domestic manufacturing footprints for urgent surgical instrument orders, the other deploying distributed supplier networks across multiple ISO-certified facilities. SyBridge Technologies anchors the precision molding specialist archetype. These three occupy positions that span the spectrum from rapid-turn prototyping to complex injection molding programs with tool-transfer capabilities reducing OEM qualification timelines.
| Leading Market Players |
|---|
| SyBridge Technologies |
| Quickparts |
| Protolabs |
| Xometry |
| Jabil |
| Fathom Manufacturing |
| Igus |
| Fictiv |
| Prototek |
| Others |
Pricing and Supply Chain Analysis
ISO 13485-certified engineering talent clusters in Baden-Württemberg and Massachusetts create labor-cost differentials that spread pricing tiers across premium validated production and economy-grade diagnostic components. German precision machinists command wage premiums that feed into patient-specific implant pricing, while Asian contract manufacturers compress margins on standardized diagnostic housings through lower technical labor costs.
Pricing Analysis
Bundled validation services separate premium pricing from unbundled spot-buy machining. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification grade and sterilization compatibility documentation. Pricing pressure stems from high-volume Asian contract manufacturers in diagnostic device categories. Hospital procurement committees show highest price sensitivity on replacement surgical instruments, while orthopedic OEMs absorb premiums for patient-specific geometries with accelerated surgical workflows.
Supply Chain Analysis
Freight costs for implant-grade titanium powder and PEEK resin concentrate supply chain decisions near Baden-Württemberg machining clusters and Massachusetts academic medical centers. Raw material dependencies center on Solvay and Victrex for implant-grade PEEK, titanium sponge from US and Japanese suppliers, and precision cutting tools from Swiss and German manufacturers. Single-source vulnerability in PEEK resin exposes molders to allocation risk. Distribution runs through hospital GPO contracts and OEM direct procurement channels with consignment inventory arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU MDR compliance costs in Europe and streamlined ANVISA pathways in Brazil, with regulatory qualification timelines creating cost differentials that favor early entrants in Latin America.
For Market Incumbents: Hedge against PEEK resin supply concentration by securing long-term offtake agreements with Solvay and Victrex before allocation events. Incumbents should anchor tool-transfer capabilities in Baden-Württemberg to defend against Asian contract manufacturers encroaching on diagnostic device categories. ISO 13485 certification investment remains the priority lever for retaining hospital network contracts. For New Entrants and Emerging Players: AI-driven generative design platforms offer a technology-first wedge into surgical instrument modification programs at Massachusetts academic medical centers. New entrants should target Brazil's Class II device registration pathway as the most penetrable geography, leveraging ISO 13485 manufacturing to accelerate ANVISA approval. Direct hospital sales partnerships bypass established distributor markups. For Investors and Strategic Acquirers: Hospital procurement networks are the most active acquirer in this space, consolidating vendor lists from 200-plus suppliers to single-digit contracted platforms. Long-term viability favors mid-cap specialists with captive additive capacity and validated quality systems. Watch FDA additive manufacturing validation guidance updates as the signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Validates quality systems for EU MDR compliance and hospital procurement eligibility. |
| Tool-Transfer Capability Buildout | Reduces OEM qualification timelines for diagnostic housing programs at SyBridge Technologies. |
| Hospital System Partnership | Secures blanket purchase agreements with German integrated delivery networks. |
| PEEK Resin Supply Agreement | Mitigates allocation risk from Solvay and Victrex concentration. |
| Point-of-Care Sterilization Integration | Collapses lead times for urgent surgical instrument replacement at Massachusetts medical centers. |
Research Methodology
Coverage spans the United States, Germany, Japan, Switzerland, and Brazil, with primary inputs from each region combining structured interviews with hospital procurement managers, orthopedic OEM supply chain directors, biomedical engineers, and GPO contracts managers. Secondary validation draws from FDA 510(k) filings, EU MDR technical documentation databases, ANVISA registration records, and hospital procurement databases. Bottom-up demand modeling triangulates against top-down market sizing across technology and product segments.
Granularity-level modeling disaggregates volume and value across the projection horizon by product type, technology platform, end-user category, and application area, with additional dimensioning by regional regulatory cluster and certification tier. CAGRs derive from segment-level growth trajectory analysis incorporating technology adoption curves and procurement consolidation patterns. Forecast inputs include electron beam melting capacity expansion timelines and EU MDR recertification deadline impacts.
The model holds under stable regulatory enforcement intensity; deviation in FDA additive manufacturing validation guidance or PEEK resin supply disruption would shift capacity deployment assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Refrigerated Incubators Market
Medical Equipment
Nuclear Medicine Equipment Market
Medical Equipment
Single-Coated Medical Tape Market
Medical Equipment
North America Medical Automation Market
Medical Equipment
Hospital-at-Home Equipment Rental Market
Medical Equipment
Global Examination Lights Market
Medical Equipment
Durable Medical Equipment Market
Medical Equipment
Clinical Microscopes Market
Medical Equipment
ECG Equipment Market
Medical Equipment
Global Countertop Platelet Incubator Market
Medical Equipment
Global Radiation Therapy Equipment Market
Medical Equipment
Minor Surgical Lights Market
Medical Equipment
Medical Linear Accelerators (MLA) Market
Medical Equipment
Global Medical Carts Market
Medical Equipment
Cryochambers Market
Medical Equipment
Global Medical Refrigerators Market