
 Global Medical Carts Market | 2026-2036
Global Medical Carts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Carts Market Foresight
Hospital-grade powered mobility is unwinding legacy expectations for medical cart performance. Capsa Healthcare leverages its specialized manufacturing footprint to sustain leadership in configurable medication delivery systems. Ergotron Inc. anchors the computer workstation segment through ergonomic design standards that differentiate its electric lift platforms. Advantech Co. Ltd competes on embedded computing integration, extending its industrial technology portfolio into clinical environments.
Medical carts are wheeled transport systems engineered from aluminum or polymer composites, typically incorporating electrical isolation, antimicrobial surfaces, and load ratings exceeding 100 kilograms to support point-of-care equipment mobility. Their primary function is to position diagnostic, therapeutic, and documentation tools at the patient bedside while maintaining IEC 60601-1 electrical safety compliance. Crash carts dominate emergency response workflows with established replacement cycles, while computer carts represent the fastest-expanding category as hospitals deploy mobile EHR access. Medication carts concentrate margin pools through barcode verification and locking drawer configurations that command premium positioning.
The FDA classifies powered medical carts as Class I or II devices depending on therapeutic function, while IEC 60601-1 third edition mandates leakage current limits and grounding integrity for all electrical configurations. The EU MDR requires notified body involvement for carts with integrated drug delivery or patient monitoring modules, tightening market access for non-European manufacturers. Stakeholders must monitor evolving cybersecurity guidance from the FDA for wireless-enabled carts and assess whether battery chemistry regulations from the EU REACH framework will constrain lithium-ion supply chains.
Market Dynamics
Hospital infrastructure modernization is compressing replacement cycles for legacy medical carts while simultaneously demanding IT-integrated, powered configurations that satisfy IEC 60601-1 third edition electrical safety mandates.
Growth Catalysts
- Acute Care Infrastructure Renewal:Hospital systems in the United States, Germany, and Japan are retiring fixed workstation installations in favor of mobile EHR access platforms.
- EU MDR Compliance Thresholds:Notified body requirements for carts with integrated drug delivery modules are filtering out marginal suppliers and concentrating procurement among certified manufacturers.
- Lithium-Ion Battery Chemistry:Energy density improvements in medical-grade power systems are extending runtime specifications for crash carts and medication delivery units.
Market Restraints
- Aluminum and Polymer Composite Input Costs:Volatility in lightweight material supply chains is pressuring gross margins for configurable cart manufacturers.
- Notified Body Bottlenecks:EU MDR certification delays for powered configurations with patient monitoring modules are extending time-to-market for non-European suppliers.
- Fixed Wall-Mounted Workstations:Hardwired diagnostic display installations in renovated ICU environments compete for capital allocation against mobile alternatives.
Strategic Opportunities
- India's Hospital Accreditation Expansion:NABH certification requirements for emergency preparedness are standardizing crash cart specifications across tier-2 and tier-3 cities.
- Barcode Verification Convergence:Integration of medication dispensing carts with hospital pharmacy information systems is opening premium configuration tiers.
- Cybersecurity Guidance Tailwinds:FDA premarket guidance for wireless-enabled medical devices is creating differentiation for manufacturers with embedded security architectures.
Industry Challenges
- IEC 60601-1 Third Edition Testing Capacity:Limited third-party laboratory availability for leakage current and grounding integrity validation is extending product launch timelines.
- Legacy Fleet Integration Complexity:Hybrid environments combining powered carts with non-powered legacy units complicate maintenance training and spare parts logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Carts Market |
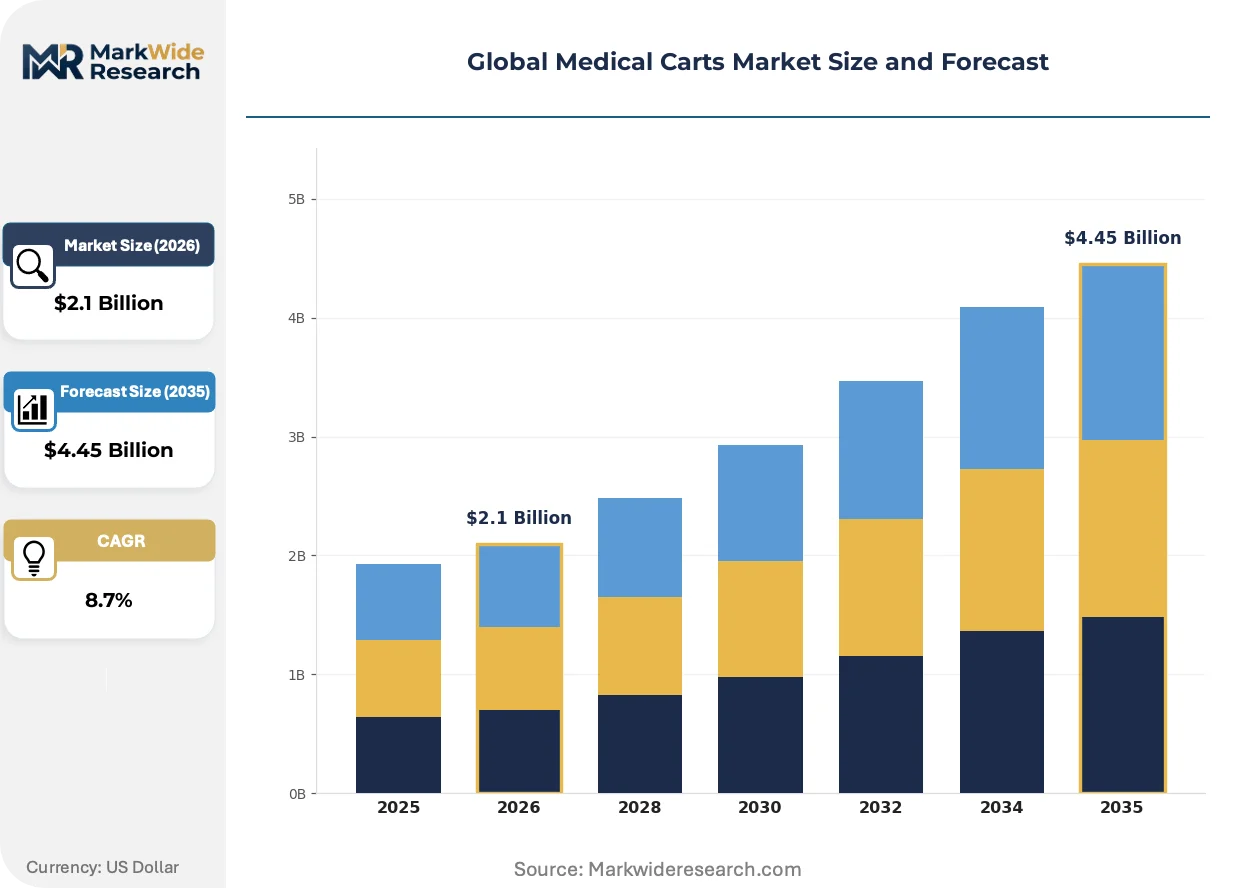
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication Carts, Anesthesia Carts, Crash Carts, Utility Carts, Computer Carts Technology: Wireless, Bluetooth, RFID, Touchscreen, Battery-Operated Application: Patient Monitoring, Surgical Assistance, Emergency Response, Inventory Management, Vital Signs Recording End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Long-Term Care Facilities |
| Companies Covered | Advantech Co. Ltd, Capsa Healthcare, Ergotron Inc, ITD Gmbh, AFC Industries, Harloff Manufacturing Co., Jaco Inc., Medline Industries LP, GCX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Carts Market Shifts & Advancements
Electronics packaging and power system engineering are compressing the physical footprint of medical carts while expanding their functional scope at the patient bedside.
Embedded computing modules are replacing discrete PC towers in medication cart configurations. Hospital IT departments are specifying these integrated architectures for new construction projects. This consolidation is miniaturizing cart chassis dimensions while maintaining full EHR functionality.
EU REACH framework scrutiny of lithium-ion battery chemistries is elevating documentation requirements for powered cart manufacturers. Industrial consequences include supplier qualification audits and alternative chemistry evaluations. German hospital procurement offices are prioritizing vendors with established EU battery supply chain traceability.
Consolidated vendor contracts are displacing unit-by-unit purchasing for crash cart and computer workstation categories. Group purchasing organizations are capturing volume allocation decisions previously managed at individual facility level. This concentration is most visible in United States health system networks exceeding ten acute care hospitals.
Global Medical Carts Market Segmentation
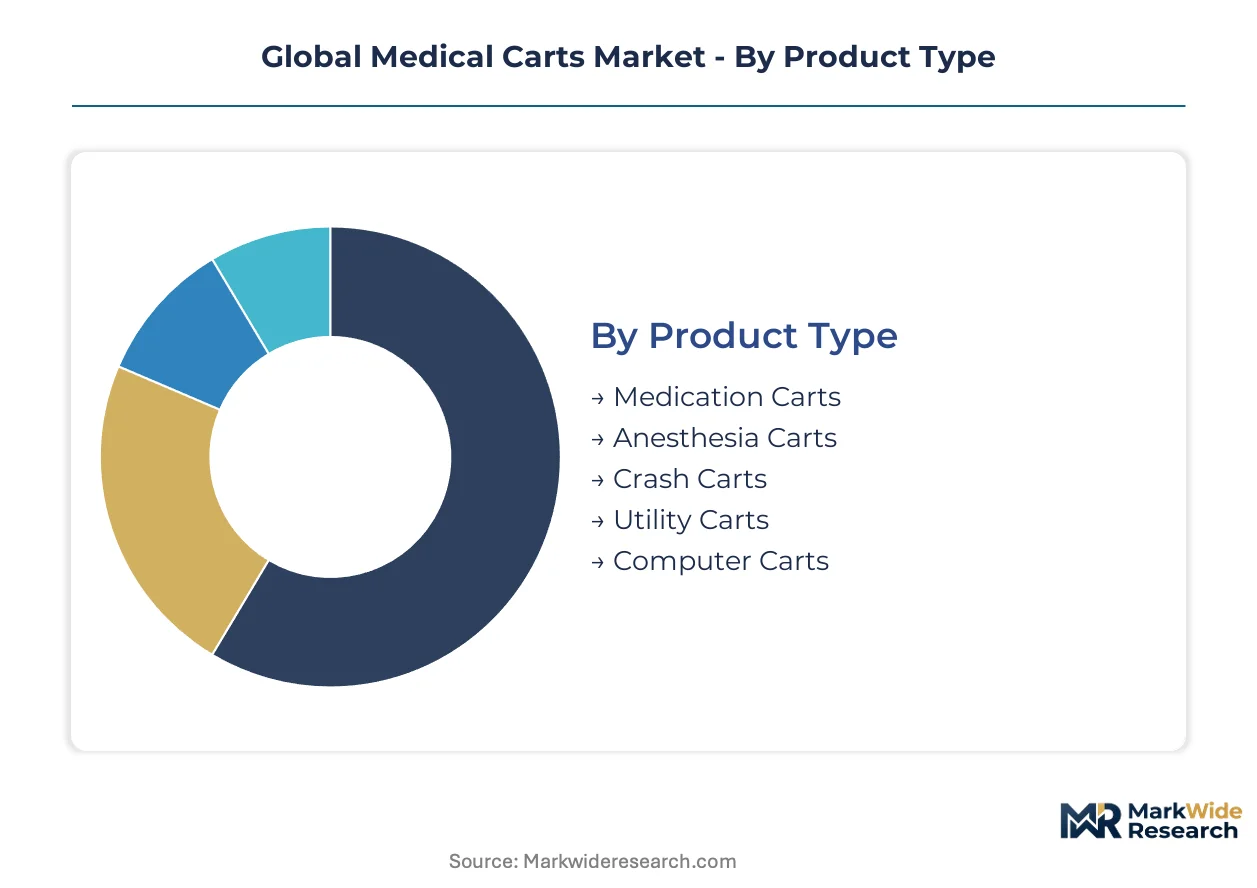
Medical cart procurement follows distinct technical and regulatory pathways that shape supplier qualification requirements. Segmentation reveals where IEC 60601-1 compliance thresholds filter vendor participation and where integrated IT capabilities command premium positioning.
Product Type:
FDA Class I and II designations diverge sharply across product categories, with powered configurations triggering stricter electrical safety validation protocols.
- Crash Carts:Emergency resuscitation systems built from aluminum framing with defibrillator mounting brackets and oxygen tank restraints. Hospital systems in the United States and Germany maintain scheduled replacement cycles for these units as accreditation standards tighten. Established demand concentration in acute care settings drives volume procurement through group purchasing organizations.
- Computer Carts:Mobile EHR access platforms integrating electric lift mechanisms and antimicrobial work surfaces. Procurement in Japan's hospital modernization programs prioritizes these configurations for nursing station decentralization. IEC 60601-1 third edition compliance for leakage current limits has become a mandatory specification threshold.
- Medication Carts:Locking drawer systems with barcode scanner mounts for pharmacy integration.
- Anesthesia Carts:Procedure-specific configurations supporting perioperative medication organization.
- Utility Carts:General-purpose transport units for supplies and equipment without integrated power systems.
Crash Carts handle the majority of throughput; Computer Carts are climbing the fastest on share.
Technology:
Connectivity specifications now determine hospital IT department approval workflows, with wireless architectures facing heightened cybersecurity scrutiny from the FDA.
- Battery-Operated:Lithium-ion power systems enabling full-shift mobility without tethering to wall outlets. German procurement offices demand EU REACH framework documentation for battery chemistry traceability. Runtime specifications exceeding twelve hours differentiate premium configurations in intensive care deployments.
- RFID:Automated identification modules for medication cart inventory tracking and access control. Japan's METI guidelines for medical device interoperability favor these integrations in new hospital construction. Reduced manual documentation burden drives adoption in nursing workflow optimization initiatives.
- Wireless:Wi-Fi and cellular connectivity for real-time EHR synchronization and telemetry.
- Bluetooth:Short-range pairing with peripheral diagnostic devices and wearables.
- Touchscreen:Integrated display interfaces replacing external monitor dependencies.
Battery-Operated configurations anchor current procurement volumes; RFID is gaining share fastest as pharmacy integration requirements spread.
Application:
Clinical workflow intensity shapes durability specifications and replacement frequency across use cases.
- Emergency Response:Rapid-deployment configurations for resuscitation and trauma stabilization. United States hospital accreditation standards mandate specific drawer layouts and medication stocking protocols. Replacement cycles compress to five-year intervals in high-utilization emergency departments.
- Patient Monitoring:Telemetry integration platforms supporting continuous vital signs surveillance. Demand concentrates in Japan's aging acute care infrastructure where bedside observation requirements intensify. IEC 60601-1 grounding integrity validation is mandatory for these electrical configurations.
- Surgical Assistance:Perioperative supply organization and instrument transport.
- Inventory Management:Supply chain visibility tools for pharmacy and materials management.
- Vital Signs Recording:Dedicated documentation stations for routine assessment workflows.
Emergency Response commands the highest unit velocity; Patient Monitoring shows the steepest expansion trajectory as telemetry integration spreads.
End User:
Capital allocation authority and technical specification complexity vary substantially across facility types.
- Hospitals:Multi-department procurement with dedicated biomedical engineering oversight for IEC 60601-1 validation. Health system networks exceeding ten facilities in the United States consolidate purchasing through centralized supply chain functions. Powered and IT-integrated configurations dominate new construction specifications.
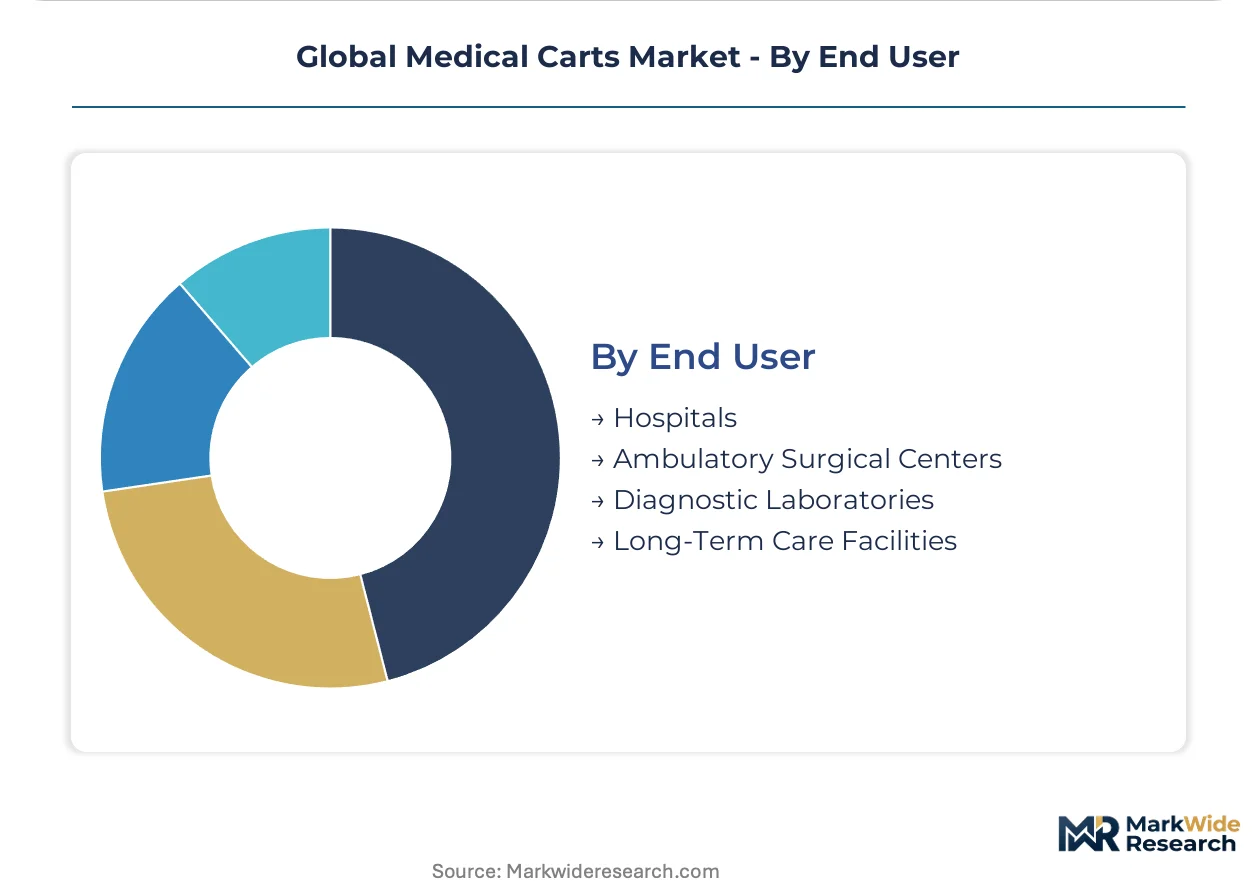
- Ambulatory Surgical Centers:Procedure-focused units with compressed footprint requirements and simplified electrical configurations. Germany's outpatient surgery expansion programs drive standardization of anesthesia cart specifications. Lower capital thresholds favor leasing arrangements over direct purchase.
- Diagnostic Laboratories:Specimen transport and workstation mobility for processing environments.
- Long-Term Care Facilities:Medication administration and basic supply transport with minimal power integration.
Hospitals absorb the dominant procurement volume; Ambulatory Surgical Centers are expanding most quickly as outpatient migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in medical carts track regulatory certification density rather than manufacturing labor costs. Countries with streamlined FDA-equivalent pathways and established notified body relationships capture disproportionate procurement volume from hospital systems seeking supply security.
United States
Hospital system consolidation across the Midwest and Southeast is centralizing procurement decisions for powered cart configurations. The FDA's Class II device designation for medication delivery carts mandates 510(k) clearance pathways that filter supplier participation. Texas Medical Center in Houston and the Cleveland Clinic corridor in Ohio represent concentrated demand nodes where health networks exceed ten facilities.
Germany
Acute care infrastructure renewal in Bavaria and North Rhine-Westphalia is accelerating replacement cycles for legacy fixed workstations. EU MDR notified body requirements for powered configurations with patient monitoring modules extend certification timelines for non-European suppliers. The Munich-Stuttgart industrial corridor hosts specialized fabricators serving hospital procurement offices prioritizing EU REACH battery chemistry documentation.
Japan
Nursing station decentralization in Tokyo and Osaka metropolitan hospitals is driving specification of electric lift computer carts. METI guidelines for medical device interoperability favor RFID-integrated configurations in new hospital construction. The Chubu region around Nagoya concentrates manufacturing partnerships between domestic hospital groups and component suppliers.
India
NABH accreditation expansion across tier-2 cities in Maharashtra and Karnataka is standardizing crash cart specifications for emergency preparedness. The CDSCO's medical device rules align with international electrical safety standards while permitting phased compliance timelines. Hyderabad and Pune emerging as procurement coordination hubs for hospital networks consolidating supplier contracts.
United Kingdom
NHS trust consolidation in England is shifting medication cart procurement toward framework agreements with certified manufacturers. MHRA recognition of EU MDR certificates post-Brexit maintains market access for continental suppliers while requiring UK responsible person designation. The Greater Manchester and West Midlands hospital networks represent volume concentration points for IT-integrated configurations.
Global Medical Carts Market Competitive Landscape
Concentration sits with specialized manufacturers holding established IEC 60601-1 third edition validation capabilities and notified body relationships. The vendor base stratifies across three tiers: integrated healthcare technology conglomerates with diversified portfolios, mid-scale specialists in configurable medication delivery systems, and regional fabricators serving price-sensitive procurement segments. Dominant competitive moves include strategic partnerships with hospital IT departments for embedded computing integration and geographic expansion through distributor relationships in emerging accreditation markets.
Among North American specialists, Capsa Healthcare and Ergotron Inc exemplify divergent positioning archetypes within the powered mobility segment. Advantech Co. Ltd anchors the embedded computing integration tier, representing the industrial technology crossover strategy into clinical environments. These three entities collectively illustrate how certification density and IT partnership depth separate procurement winners from commodity suppliers.
| Leading Market Players |
|---|
| Advantech Co. Ltd |
| Capsa Healthcare |
| Ergotron Inc |
| ITD Gmbh |
| AFC Industries |
| Harloff Manufacturing Co. |
| Jaco Inc. |
| Medline Industries LP |
| GCX Corporation |
| Others |
Supply & Pricing Matrix
Multi-year framework agreements with group purchasing organizations lock in both supply access and price visibility for hospital systems across the United States, Germany, and Japan. These contracts bundle IEC 60601-1 certified configurations with predictable aftermarket service tiers, insulating procurement offices from aluminum and polymer composite volatility while constraining margin expansion for manufacturers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across certification-grade tiers. Price differentiation separates FDA Class II medication carts with barcode verification from basic utility configurations, with premium positioning tied to embedded computing integration and EU MDR notified body certification. Cost compression in standard aluminum-framed units is intensifying because of volatility in lightweight material supply chains. Ambulatory surgical centers exhibit highest price sensitivity due to compressed capital thresholds, while hospital networks exceeding ten facilities leverage volume scale for preferential tier access.
Supply Chain Analysis
China and Germany anchor aluminum extrusion and precision polymer composite fabrication for medical-grade chassis components. Lithium-ion cell production draws from South Korean and Japanese suppliers subject to EU REACH framework documentation requirements. Single-source vulnerability concentrates in battery chemistry traceability audits demanded by German procurement offices. Distribution runs through specialized medical device distributors with notified body relationships, bypassing general industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams from preventive maintenance contracts and IEC 60601-1 recertification services are expanding faster than hardware unit sales, transforming vendor economics toward recurring-revenue models.
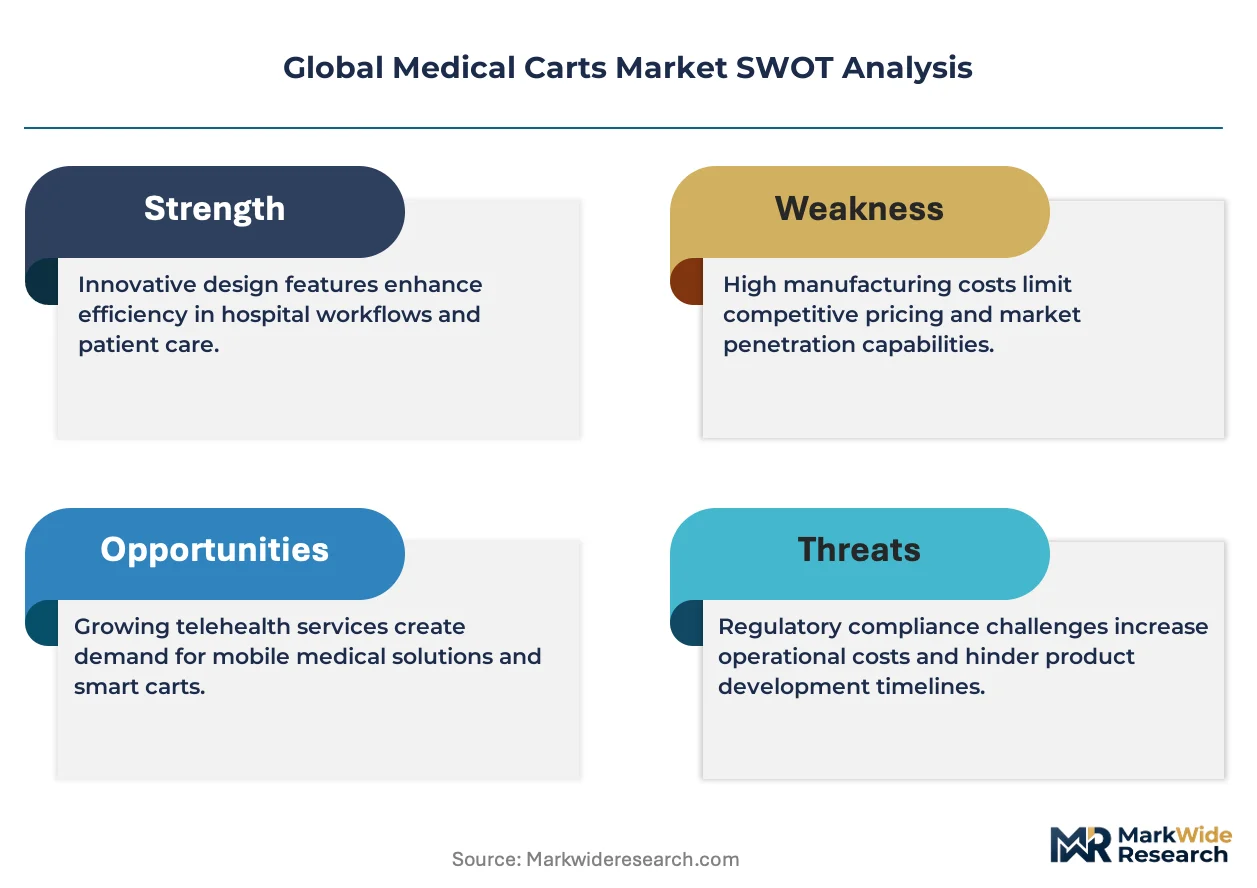
For Market Incumbents: Consolidate certification density advantages by deepening notified body relationships across EU MDR and FDA pathways, and acquire specialized battery supply chain traceability capabilities to defend against REACH documentation disruption. Capacity addition in the Munich-Stuttgart corridor secures proximity to German hospital procurement offices prioritizing EU battery chemistry documentation. For New Entrants and Emerging Players: Aftermarket service coverage gaps in India's tier-2 and tier-3 cities present white-space targets where NABH accreditation expansion standardizes crash cart specifications without established incumbent service networks. Penetrable segments concentrate in emergency response configurations for Maharashtra and Karnataka hospital networks, with go-to-market leverage through CDSCO-aligned compliance consulting bundled with unit sales. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale specialists with embedded computing integration capabilities and established IEC 60601-1 third edition validation footprints. Long-term viability over a five-to-ten year window favors manufacturers with hospital IT department partnerships for EHR synchronization architectures. The signal to watch is FDA premarket guidance finalization for wireless-enabled medical device cybersecurity requirements.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body engagement filters out marginal suppliers in Germany. |
| Hospital System Partnership | Cleveland Clinic and Texas Medical Center corridors consolidate procurement decisions. |
| Software Companion Development | Embedded computing modules replace discrete PC towers in Japan's nursing station decentralization. |
| Backward Integration into Battery Supply | EU REACH documentation requirements favor captive lithium-ion chemistry traceability. |
| Reimbursement Strategy | METI interoperability guidelines in Japan shape RFID-integrated configuration demand. |
Research Methodology
A spread of perspectives from hospital purchasing committees, biomedical engineering directors, GPO contracts managers, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary fieldwork with these stakeholders combined with secondary validation from FDA 510(k) filings, EU MDR notified body databases, hospital procurement contracts, and CMS Medicare reimbursement data. Bottom-up unit demand modeling and top-down market sizing triangulated on value estimates across the analysis window.
Segmentation dimensions modeled include product type, power configuration, application intensity, and end-user facility scale across the projection horizon. CAGRs were derived from installed base replacement cycle analysis and new construction penetration assumptions. Forecast inputs incorporated IEC 60601-1 third edition compliance adoption curves and lithium-ion battery chemistry substitution elasticity under REACH scrutiny.
Forecasts assume regulatory continuity in FDA Class II device pathways and EU MDR notified body frameworks; material policy shifts would require re-modeling of certification timeline assumptions and supply chain qualification requirements. Recalibration cycles align with material shifts in hospital infrastructure renewal spending and cybersecurity guidance finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Benchtop Platelet Agitator Market
Medical Equipment
Autopsy Saw Market
Medical Equipment
Manufacturing on Demand for Medical Market
Medical Equipment
Global Mobile Operating Tables Market
Medical Equipment
Irradiation Apparatus Market
Medical Equipment
Medical Linear Accelerators (MLA) Market
Medical Equipment
Europe Nuclear Medicine Equipment Market
Medical Equipment
Medical X-Ray Generators Market
Medical Equipment
Global Medical Equipment Calibration Market
Medical Equipment
Blood Banking Equipment Market
Medical Equipment
Proctologic Table Market
Medical Equipment
Electric Bed Market
Medical Equipment
Medical Filter Market
Medical Equipment
Global Capnography Equipment Market
Medical Equipment
Medical Equipment Maintenance Market
Medical Equipment
South Africa Radiotherapy Market