
 Connected (Smart) Street Lighting Market | 2026-2036
Connected (Smart) Street Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Connected (Smart) Street Lighting Market Outlook
REACH energy efficiency mandates is rebalancing the cost-of-entry calculus for European vendors by tightening material compliance and lifecycle documentation requirements. Signify Holding leverages its vertically integrated LED manufacturing to sustain margin pressure from regulatory compliance costs. Itron Inc. anchors its competitive position through deep integration with utility AMI networks. Telensa Limited differentiates via specialized wireless mesh architectures purpose-built for street-scale deployments.
Connected street lighting denotes networked luminaire systems incorporating sensors, communication modules, and remote management software to enable adaptive illumination, traffic monitoring, and environmental sensing, typically operating at 4000K correlated color temperature with dimming capabilities down to ten percent of nominal flux. The technology segment splits across LED, solar, hybrid, and wireless variants, with LED occupying the dominant installed base while solar-hybrid configurations represent the fastest-growing niche in off-grid and peri-urban corridors. The control system dimension spans centralized, decentralized, automated, and manual architectures, where decentralized platforms are gaining traction among municipalities seeking resilience against single-point network failures.
The EU Green Deal and F-Gas Regulation shape product specifications across European markets, while the EPA's ENERGY STAR program and FCC Part 15 rules govern US equipment certification and radio emission compliance. ECHA substance restrictions further constrain driver electronics and housing materials, pushing manufacturers toward halogen-free flame retardants and recycled aluminum enclosures. Stakeholders must monitor evolving cybersecurity mandates for critical infrastructure as national regulators begin embedding IoT security requirements into procurement frameworks.
Market Dynamics
The EU Green Deal's binding energy efficiency mandates are compressing municipal upgrade timelines while forcing vendors to absorb compliance costs through supply chain restructuring rather than price premiums.
Growth Catalysts
- REACH substance restrictions:ECHA's tightening controls on halogenated flame retardants are accelerating material transitions toward recycled aluminum housings and bio-based potting compounds in driver electronics.
- Utility concession models:Germany's Stadtwerke and municipal utilities are bundling street lighting into 15-20 year energy service contracts that finance LED retrofits through guaranteed savings clauses.
- Photovoltaic-wind hybrid nodes:Solar-hybrid luminaires with integrated small wind turbines are penetrating peri-urban corridors and off-grid industrial zones where grid extension costs exceed standalone system economics.
Market Restraints
- Semiconductor supply concentration:Driver IC and RF module production clusters in Taiwan and South Korea create vulnerability to geopolitical disruption and foundry allocation constraints.
- Copper and rare earth volatility:Magnet materials for wind-hybrid generators and copper windings in LED drivers face price swings tied to concentrated mining jurisdictions.
- F-Gas Regulation phase-down:EU restrictions on fluorinated greenhouse gases are eliminating certain thermal management solutions for extreme climate luminaires before solid-state alternatives achieve cost parity.
Strategic Opportunities
- India's Smart Cities Mission:The Ministry of Housing and Urban Affairs is channeling PLI scheme incentives toward domestic LED fixture assembly and city-scale IoT backbone deployment.
- Multi-sensor convergence:Air quality, acoustic, and thermal imaging modules are integrating into single-node street furniture, creating data monetization channels for municipal revenue diversification.
- Performance contracting:Energy Service Companies are assuming full O&M liability for 10-15 year terms, transferring technology obsolescence risk from cash-constrained municipalities to private balance sheets.
Industry Challenges
- Cybersecurity certification backlog:National regulators are embedding IEC 62443 requirements into procurement frameworks faster than testing laboratories can clear device evaluations, delaying contract awards.
- Legacy HPS inventory stranding:Municipal warehouses hold depreciated high-pressure sodium assets with residual book value, complicating accelerated replacement schedules and audit compliance.
- RF spectrum fragmentation:Mesh network deployments face interference management complexity where neighboring jurisdictions adopt incompatible sub-GHz or 2.4 GHz protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected (Smart) Street Lighting Market |
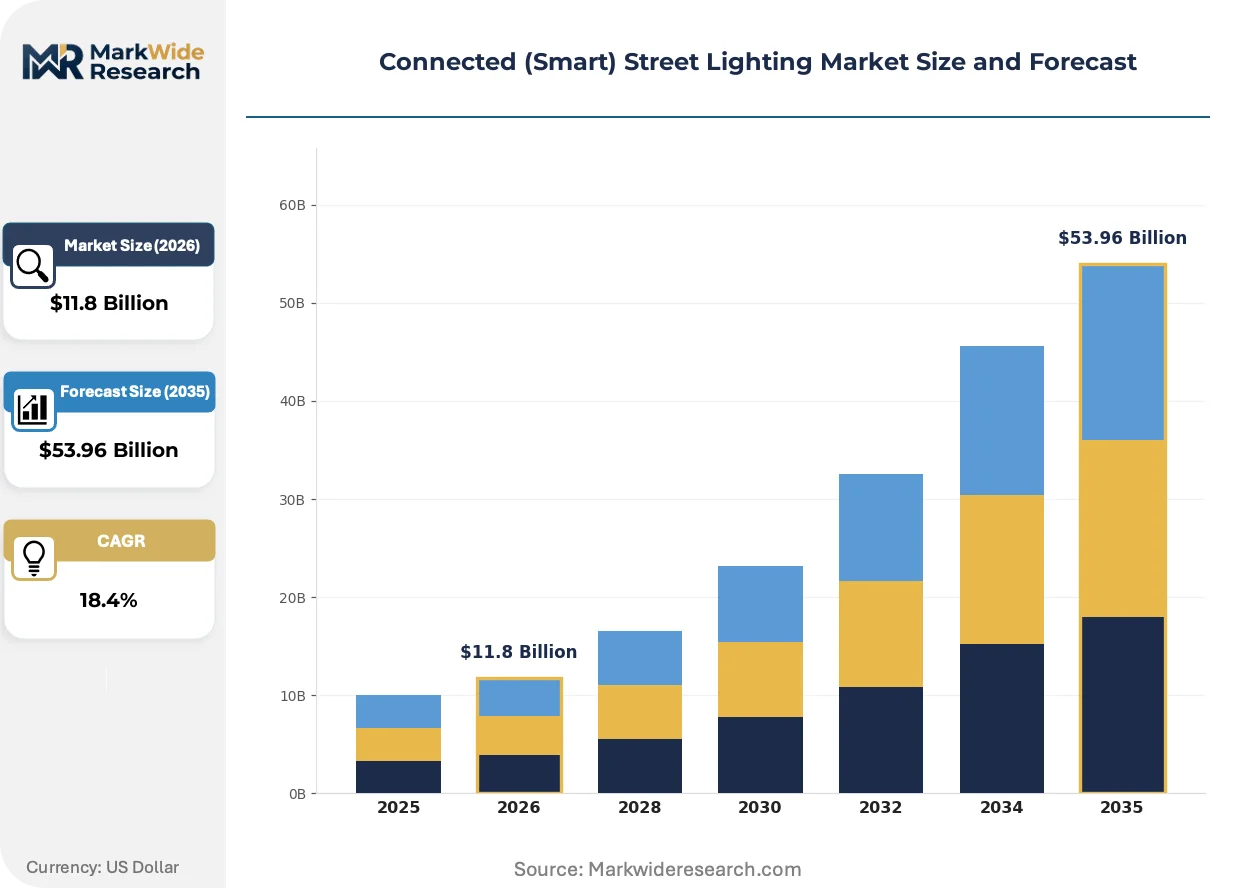
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $53.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LED, Solar, Hybrid, Wireless Control System: Centralized, Decentralized, Automated, Manual End User: Municipalities, Private Companies, Transportation Agencies, Utilities Installation Type: New, Retrofit, Upgrades, Smart City Projects |
| Companies Covered | Signify Holding, Itron Inc., Telensa Limited, CIMCON Lighting, InteliLIGHT (Flashnet SA), Acuity Brands Inc., Sensus, a Xylem Brand, gridComm, TVILIGHT Projects BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected (Smart) Street Lighting Market Strategic Shifts
Adaptive control architectures are displacing static scheduling across municipal portfolios, while material compliance and data governance requirements are reshaping vendor qualification criteria.
LiDAR-enabled luminaires are integrating vehicle trajectory mapping and pedestrian flow analytics into standard street furniture, enabling real-time dimming adjustments based on actual presence detection rather than time-clock assumptions. German transport authorities are mandating these capabilities for new arterial installations. The technology is integrating traffic management, public safety, and environmental monitoring into unified municipal data platforms that compress departmental silos.
The EU AI Act's risk classification framework is imposing documentation burdens on computer-vision-enabled lighting systems that perform biometric inference or behavioral analysis. Manufacturers must maintain technical files demonstrating conformity with fundamental rights impact assessments. French procurement templates now require explicit AI Act compliance attestations for smart city tenders exceeding threshold values.
Municipal buyers are consolidating vendor relationships around full-lifecycle service agreements that unbundle hardware capex from software subscriptions and energy savings guarantees. Danish municipalities are piloting 20-year concession structures where contractors retain fixture ownership and assume technology refresh obligations. This reconfiguration is most visible in Nordic markets where public sector accounting standards treat operating leases more favorably than capital expenditures on municipal balance sheets.
Connected (Smart) Street Lighting Market Segmentation
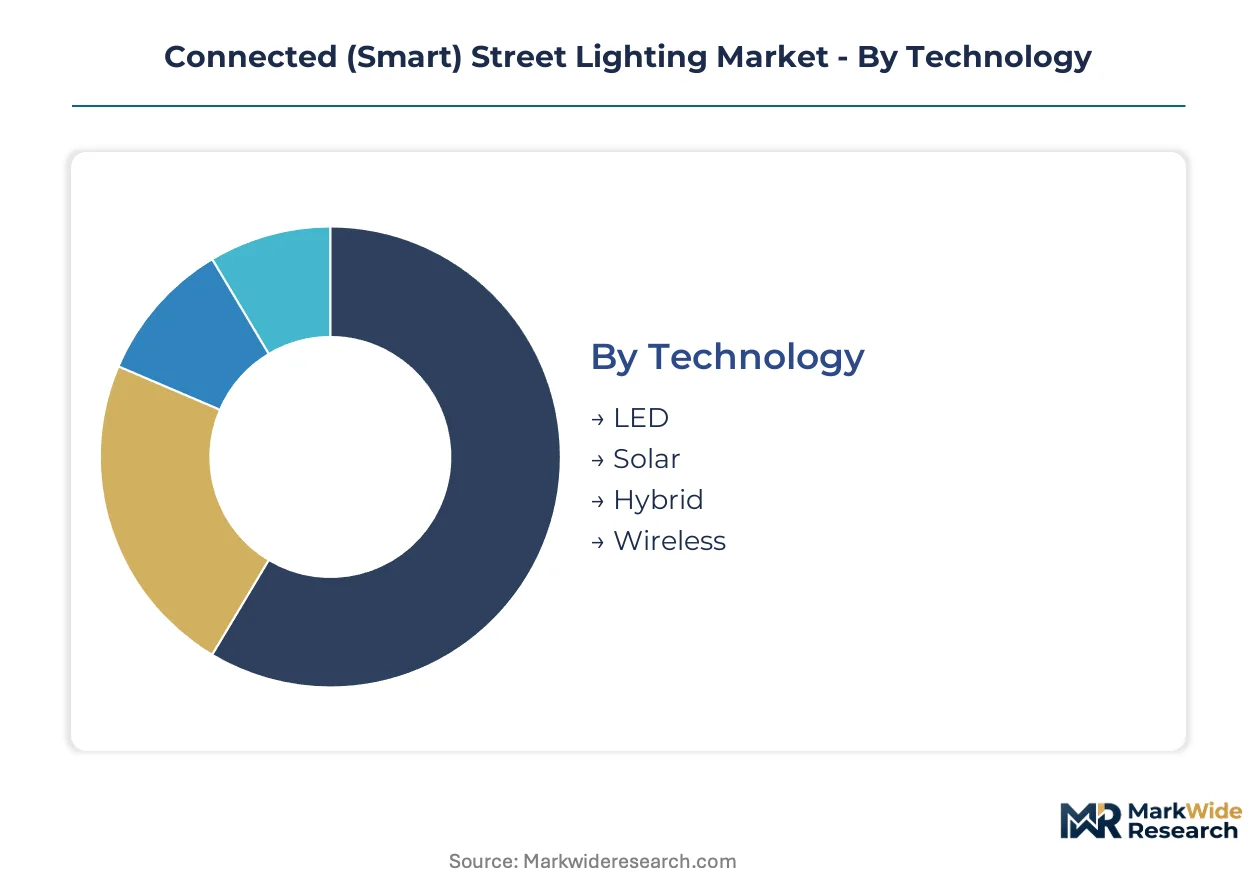
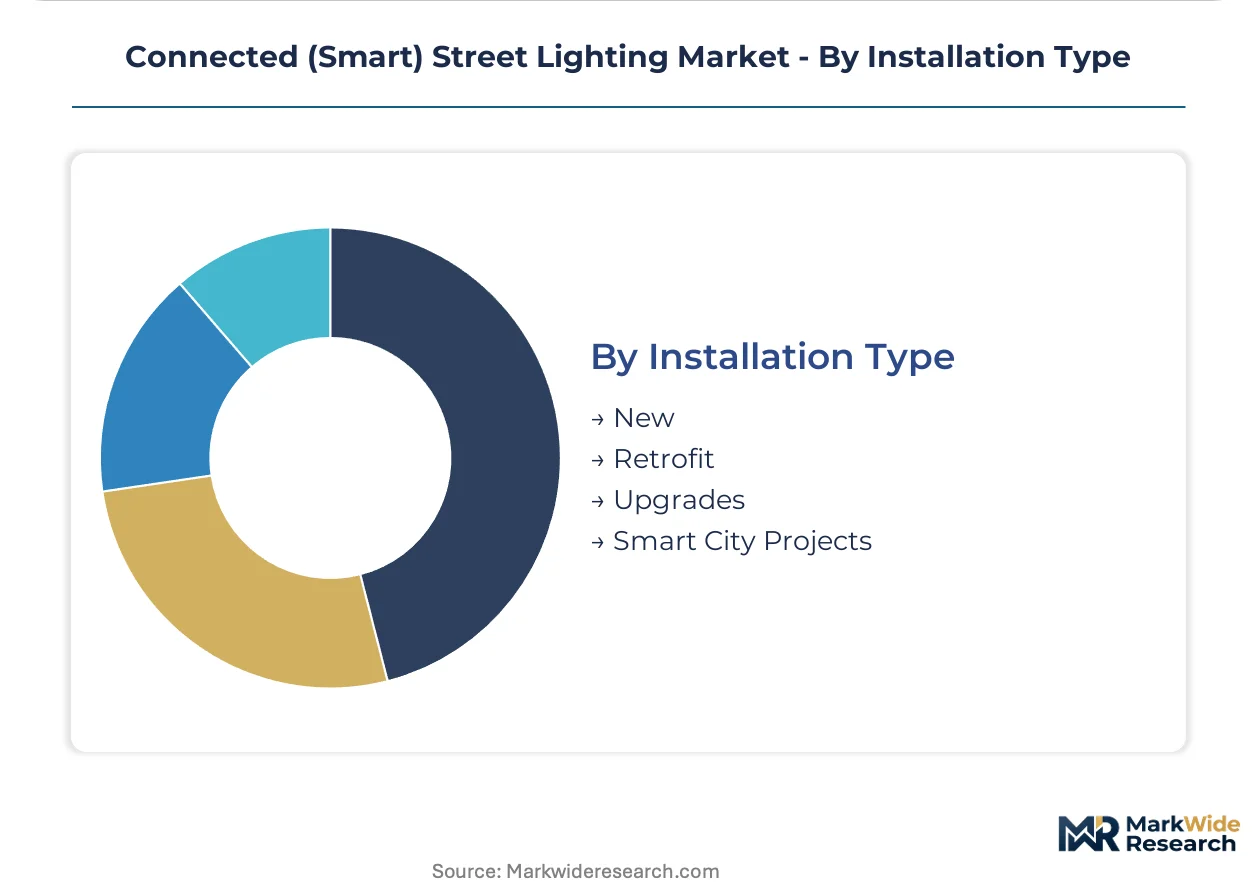
Technology and control system configurations determine procurement economics and lifecycle value for municipal buyers. Installation type segmentation reveals divergent capital deployment patterns between legacy retrofit corridors and greenfield smart city developments.
Technology:
LED dominates installed volume while solar-hybrid commands premium pricing in off-grid applications.
- LED:Solid-state luminaires operating at 4000K correlated color temperature with dimming to ten percent nominal flux form the backbone of utility concession contracts. German Stadtwerke and municipal utilities bundle these into 15-20 year energy service agreements with guaranteed savings clauses.
- Solar:Photovoltaic-integrated poles with battery storage serve peri-urban corridors and grid-extension-limited industrial zones where standalone economics exceed infrastructure buildout costs. India's Smart Cities Mission channels PLI scheme incentives toward domestic assembly of these configurations.
- Hybrid:Combined photovoltaic-small wind turbine nodes penetrate off-grid industrial estates and remote logistics hubs where wind resources supplement solar intermittency.
- Wireless:Radio-frequency networked luminaires bypass trenching requirements in historic districts and bridge-deck installations where physical cabling disrupts protected structures.
Mature deployment sits with LED. Newer deployment is concentrated in solar-hybrid configurations gaining share fastest in peri-urban and off-grid corridors.
Control System:
Resilience requirements are tilting municipal specifications toward distributed intelligence architectures.
- Centralized:Hub-and-spoke management platforms with gateway concentrators enable citywide dimming schedules and fault alerting from single operations centers. Danish municipalities favor these for consolidated oversight of dense urban portfolios.
- Decentralized:Edge-computing luminaires with autonomous decision capability maintain service during network partition events. French transport authorities mandate these for arterial installations requiring continuity under cyber disruption.
- Automated:Presence-detection algorithms trigger real-time flux adjustments based on LiDAR trajectory mapping and pedestrian flow analytics rather than time-clock assumptions.
- Manual:Override interfaces persist in ceremonial districts and event venues requiring deliberate lighting choreography for cultural programming.
Centralized platforms anchor legacy deployments. Automated control is climbing the fastest as German authorities mandate adaptive capabilities for new arterial installations.
End User:
Procurement authority fragmentation creates divergent vendor qualification pathways across buyer types.
- Municipalities:City lighting departments with constrained capital budgets favor performance contracting structures where Energy Service Companies assume O&M liability and technology obsolescence risk.
- Private Companies:Corporate campus and logistics park operators prioritize rapid deployment with minimal civil works, driving specification toward wireless mesh and solar-hybrid nodes.
- Transportation Agencies:German KBA and state road authorities enforce LiDAR-enabled presence detection for traffic safety compliance on federal highways.
- Utilities:Germany's Stadtwerke dominate upgrade cycles through concession models bundling street lighting into integrated energy service contracts.
Municipal procurement sustains volume leadership. Utility-led deployment is expanding most quickly as concession financing structures proliferate across European markets.
Installation Type:
Asset replacement timing determines technology leapfrog potential versus stranded inventory constraints.
- New:Greenfield smart city developments in India's mission cities and Nordic municipal pilots specify multi-sensor convergence with air quality, acoustic, and thermal imaging modules from initial deployment.
- Retrofit:LED driver and control module upgrades to existing poles preserve civil infrastructure while accelerating energy savings realization in budget-constrained German and French municipalities.
- Upgrades:Sensor augmentation and software refreshes extend functional lifecycles of recently deployed LED networks without fixture replacement.
- Smart City Projects:Integrated IoT backbone deployments consolidate lighting, traffic management, and environmental monitoring into unified municipal data platforms.
Retrofit installation carries volume concentration. Smart city project deployment shows the steepest expansion trajectory as data monetization channels diversify municipal revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates demand through utility-led concession models that bundle street lighting into long-term energy service contracts. Municipal procurement patterns diverge sharply across regulatory jurisdictions, with EU Green Deal mandates compressing upgrade timelines in member states while India's Smart Cities Mission channels infrastructure investment toward integrated IoT deployments.
Germany
Stadtwerke and municipal utilities dominate deployment through 15-20 year energy service contracts with guaranteed savings clauses. The EU Green Deal's binding energy efficiency mandates accelerate LED retrofit timelines across federal states. Bavaria and North Rhine-Westphalia host dense concentrations of pilot-to-citywide expansions where LiDAR-enabled presence detection is becoming standard for arterial installations.
France
Transport authorities mandate decentralized control architectures for traffic safety continuity under cyber disruption scenarios. The EU AI Act's risk classification framework imposes documentation burdens on computer-vision-enabled lighting systems performing behavioral analysis. French procurement templates now require explicit AI Act compliance attestations for smart city tenders, with Île-de-France municipalities piloting 20-year concession structures.
India
The Ministry of Housing and Urban Affairs channels PLI scheme incentives toward domestic LED fixture assembly and city-scale IoT backbone deployment. BIS certification requirements shape product specifications for public procurement. Maharashtra and Gujarat lead state-level implementation under the Smart Cities Mission, with peri-urban corridors favoring solar-hybrid configurations where grid extension costs exceed standalone economics.
United States
EPA ENERGY STAR program and FCC Part 15 rules govern equipment certification and radio emission compliance for municipal deployments. California and New York Metro areas drive specification toward multi-sensor convergence with air quality and acoustic monitoring modules. The Pacific Northwest shows concentrated activity in performance contracting structures where Energy Service Companies assume full O&M liability.
Denmark
Nordic public sector accounting standards treat operating leases more favorably than capital expenditures, accelerating 20-year concession pilots where contractors retain fixture ownership. Danish municipalities favor centralized hub-and-spoke management platforms for consolidated oversight of dense urban portfolios. Copenhagen anchors regional adoption of full-lifecycle service agreements that unbundle hardware capex from software subscriptions.
Connected (Smart) Street Lighting Market Competitive Environment
European producers anchor one tier through deep integration with utility networks and regulatory compliance capabilities; Asia-Pacific specialists hold manufacturing scale advantages in driver electronics and RF modules. The vendor base stratifies across three tiers: vertically integrated lighting conglomerates with captive LED manufacturing, utility-aligned controls specialists with AMI network integration, and wireless mesh pure-plays with purpose-built street-scale architectures. Consolidation pressure intensifies as municipalities consolidate vendor relationships around full-lifecycle service agreements. Strategic moves center on concession financing partnerships and multi-sensor platform augmentation.
Within the integrated lighting tier, Signify Holding exemplifies European compliance-forward positioning through vertically structured LED manufacturing. Among utility-aligned controls specialists, Itron Inc. and Sensus occupy positions defined by deep AMI network integration. Telensa Limited represents the wireless mesh pure-play archetype with specialized architectures for street-scale deployments. These three anchors illustrate how competitive positioning stratifies across technical specialization rather than geographic coverage alone.
| Leading Market Players |
|---|
| Signify Holding |
| Itron Inc. |
| Telensa Limited |
| CIMCON Lighting |
| InteliLIGHT (Flashnet SA) |
| Acuity Brands Inc. |
| Sensus, a Xylem Brand |
| gridComm |
| TVILIGHT Projects BV |
| Others |
Value Chain & Pricing Dynamics
Utility-backed concession operators and private-equity-rolled-up lighting specialists anchor supply discipline through captive LED manufacturing and long-term energy service contracting, compressing margin buffers for component vendors while sustaining pricing power on full-lifecycle service bundles.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent retrofit timelines from planned procurement cycles, with German Stadtwerke paying premiums for guaranteed savings clauses while spot-market municipalities negotiate discounts on inventory-heavy standard LED fixtures. Three-tier pricing structure across premium LiDAR-enabled systems, standard networked luminaires, and economy retrofit drivers reflects certification tier and software subscription bundling. Cost compression in the economy tier is intensifying because REACH compliance documentation burdens smaller vendors disproportionately. Municipal procurement departments with constrained capital budgets exhibit highest price sensitivity, whereas transportation agencies with federal safety mandates demonstrate lowest elasticity.
Supply Chain Analysis
Driver IC and RF module production rests on Taiwanese foundry capacity and South Korean packaging specialists, with magnet materials for wind-hybrid generators drawing from Chinese rare earth processing and Chilean copper concentrate. LED chip epitaxy feeds from Japanese and German specialty substrate producers, while recycled aluminum enclosure fabrication concentrates in Italian and Spanish extrusion mills. Single-source vulnerability in semiconductor foundry allocation creates disruption exposure during geopolitical tension episodes. Distribution runs through utility procurement consortia and municipal cooperative purchasing agreements rather than open wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as full-lifecycle service contracting forces sub-scale vendors to exit or sell, with cybersecurity certification backlogs accelerating the winnowing.
For Market Incumbents: To counter margin erosion from REACH compliance documentation and ECHA substance restriction audits, deepen backward integration into halogen-free flame retardant compounding and recycled aluminum sourcing, while anchoring channel control through exclusive Stadtwerke concession partnerships that lock out competitors for 15-20 year terms. For New Entrants and Emerging Players: Energy Service Companies with municipal balance sheet access represent the most penetrable channel partner type for bypassing incumbent utility relationships, targeting peri-urban solar-hybrid corridors in India's Smart Cities Mission states where domestic PLI scheme incentives reduce landed cost disadvantages, and positioning around rapid-deployment wireless mesh architectures that minimize civil works disruption. For Investors and Strategic Acquirers: French AI Act compliance attestations becoming mandatory for smart city tenders exceeding threshold values is the leading indicator that regulatory qualification assets will command acquisition premiums over pure technology plays, framing long-term viability around 5-10 year concession finance structuring capabilities and multi-sensor data platform integration rather than hardware manufacturing scale.| Strategic Initiative | Industry Significance |
|---|---|
| Concession Financing Partnership | Stadtwerke bundling street lighting into energy service contracts transfers technology obsolescence risk from municipalities. |
| Multi-Sensor Platform Augmentation | Air quality and acoustic module integration creates data monetization channels for Danish municipal revenue diversification. |
| REACH Compliance Investment | ECHA substance restriction documentation capabilities qualify vendors for EU Green Deal-mandated retrofit procurement. |
| Wireless Mesh Architecture Specialization | Purpose-built street-scale RF protocols bypass trenching requirements in German historic districts and bridge installations. |
| Cybersecurity Certification Acceleration | IEC 62443 evaluation clearance removes procurement delays that strand competitors in French transport authority tenders. |
Study Parameters
Independent corroboration across municipal lighting department procurement officers, utility concession contract managers, and Energy Service Company operations directors underwrites the qualitative findings, with secondary validation drawing from EU Green Deal implementation reports, ECHA substance restriction databases, and BIS certification filings for Indian Smart Cities Mission deployments, combining bottom-up project pipeline tracking with top-down regulatory impact assessment.
Rate-of-change decomposition across technology segments, control system architectures, and installation type categories structures the analytical framework, with LED retrofit velocity, solar-hybrid penetration curves, and decentralized control adoption rates modeled separately across the projection horizon, deriving CAGRs from utility concession contract award timelines and municipal capital budget cycle analysis.
Several conditions sit outside the modeled scope, including unannounced national cybersecurity mandate accelerations and raw material tariff regime shifts, with forecasts reflecting assumptions on stable semiconductor foundry allocation and continued ECHA enforcement intensity, and a small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
India Lighting Market
Lighting
Inspection Lighting Fixture Market
Lighting
Dimmer and Color Tunable Market
Lighting
Hazardous Lighting Market
Lighting
Bacteriological Light Market
Lighting
South America Outdoor LED Lighting Market
Lighting
Eye-Illuminating Gadgets Market
Lighting
Indicator Lights Market
Lighting
COB Photo Light Market
Lighting
Tritium Light Source Market
Lighting
Vintage Bulb Market
Lighting
Connected Lighting Platform Market
Lighting
GCC Smart Lighting Market
Lighting
Smart Lights Market
Lighting
LED Eye Protection Lamp Market
Lighting
Asia-Pacific Lighting Control Market