
 Display Light Control Film Market | 2026-2036
Display Light Control Film Market Size, Share, and Industry Trends Forecast 2026-2036
Display Light Control Film Market Outlook
Optical engineering talent scarcity in thin-film deposition is unwinding capacity expansion timelines across the industry. 3M leverages its multi-layer optical film patents to sustain premium positioning in polarizer substrates. Nitto Denko Corporation anchors Japanese supply chains through integrated adhesive-polarizer manufacturing. LG Chem competes aggressively in OLED-compatible diffuser films for automotive tier-one suppliers.
Display light control film comprises micro-structured or nano-composite polymer layers engineered to manipulate polarization, diffusion, reflection, or conductivity with optical clarity exceeding 90% transmittance. These films modulate ambient and emitted light in flat-panel displays, smart windows, and controlled-illumination systems to enhance visibility, reduce power consumption, or enable privacy switching. Polarizers currently dominate value capture due to irreplaceable function in LCD stacks and sustained volume across consumer electronics refurbishment cycles. Diffusers represent the fastest-expanding category as OLED and mini-LED backlight architectures require precision haze control for uniformity. Transparent conductors face margin compression from silver nanowire and metal mesh alternatives, though indium tin oxide coatings retain incumbency in medical device displays where certification barriers deter substitution.
Japan's METI enforces JIS standards for display component recyclability and hazardous substance limits that filter imported film specifications. South Korea's MFDS imposes biocompatibility testing on films integrated into diagnostic equipment touch panels. China's SAMR and GB standard updates on display energy efficiency are forcing reformulation of reflective films to meet standby power thresholds. Stakeholders must monitor divergence between Asian national standards and IEC baseline harmonization efforts to avoid duplicate certification burdens.
Market Dynamics
The Display Light Control Film Market faces acute optical engineering talent scarcity in thin-film deposition, which is elongating capacity expansion timelines and compressing margins for manufacturers attempting to scale micro-structured polymer production.
Growth Catalysts
- Automotive Display Integration:OEM procurement of glare-reducing polarizer stacks for curved dashboard screens is accelerating as vehicle electrification prioritizes energy-efficient cabin electronics.
- China's GB Energy Standards:SAMR-mandated standby power thresholds for display modules are forcing reflective film reformulation, creating replacement demand across consumer electronics refurbishment cycles.
- OLED Backlight Architectures:Mini-LED and quantum dot diffusion requirements are expanding precision haze control specifications for tier-one automotive suppliers.
Market Restraints
- Indium Supply Concentration:Transparent conductor margins face sustained compression from silver nanowire and metal mesh alternatives, with indium tin oxide coatings retaining incumbency only in certified medical device displays.
- East Asian Manufacturing Cluster Risk:Production gravity centers on South Korea, Japan, and coastal China, exposing supply chains to concentrated geopolitical disruption and shipping chokepoint vulnerability.
- Biocompatibility Certification Friction:South Korea's MFDS imposes extended testing timelines on films integrated into diagnostic equipment touch panels, delaying market entry for non-incumbent suppliers.
Strategic Opportunities
- Smart Window Applications:Privacy-switching electrochromic films represent underpenetrated demand in commercial building retrofits, with architectural glass manufacturers seeking polymer-layer integration partners.
- Japanese Recyclability Mandates:METI-enforced JIS standards for display component material recovery are filtering imported specifications, creating certification-barrier moats for compliant domestic suppliers.
- Medical Device Differentiation:Diagnostic equipment manufacturers are specifying optical clarity exceeding 90% transmittance combined with antimicrobial surface properties, opening premium positioning for specialized film stack providers.
Industry Challenges
- Multi-Layer Optical Film IP Complexity:Patent thickets around polarizer substrate architectures are forcing licensing negotiations or costly workarounds for entrants attempting backward integration into adhesive-polarizer manufacturing.
- Deposition Equipment Lead Times:Vacuum coating and roll-to-roll nanoimprint lithography systems face 18-24 month delivery schedules, constraining capacity additions despite confirmed purchase orders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Display Light Control Film Market |
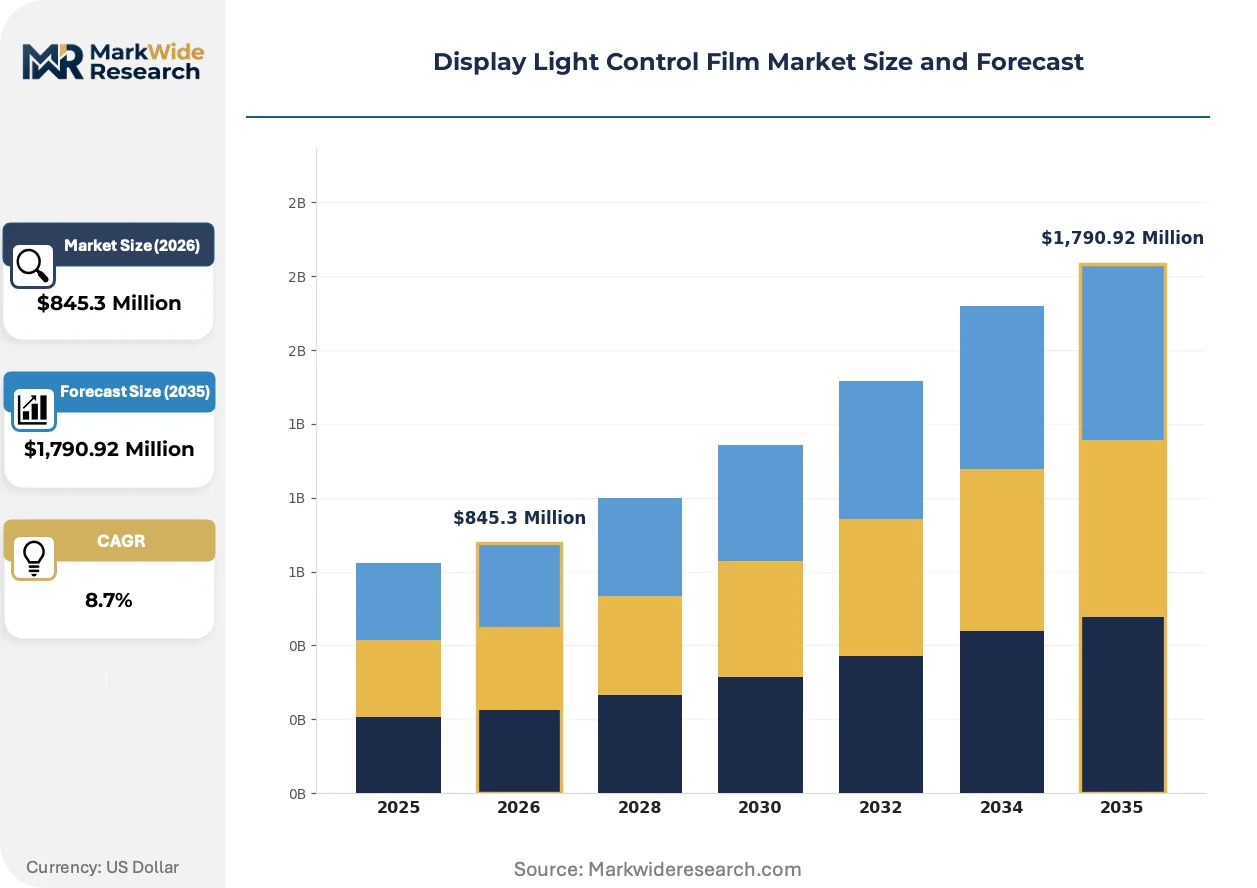
| Market Size in 2026 | $845.3 Million |
| Market Size in 2035 | $1,790.92 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polarizers, Diffusers, Transparent Conductors, Reflectors End User: Consumer Electronics, Automotive Displays, Commercial Signage, Medical Devices Technology: LCD, OLED, DLP, E-Paper Application: Displays, Smart Windows, Lighting Control, Privacy Screens |
| Companies Covered | 3M, Nitto Denko Corporation, LG Chem, Mitsubishi Chemical Corporation, Toray Industries, Inc., BenQ Materials Corp., Kolon Industries, Inc., American Polarizers, Inc., Fusion Optix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Display Light Control Film Market Strategic Shifts
Nano-composite polymer architectures are actively restructuring competitive positioning in display light control, with three convergent developments reshaping how films manipulate polarization, diffusion, and conductivity across end-use verticals.
Micro-structured diffuser films engineered for OLED-compatible backlight uniformity are miniaturizing feature dimensions below 5 microns to match mini-LED pitch densities. Automotive tier-one suppliers are specifying these layers for curved dashboard displays at accelerated procurement cycles. This dimensional compression is miniaturizing the addressable market for legacy extruded diffuser sheets while expanding precision roll-to-roll nanoimprint lithography capacity requirements.
Japan's METI has tightened JIS standards for display component hazardous substance limits and end-of-life recyclability, filtering imported film specifications through material disclosure mandates. Manufacturers must now document full polymer chain-of-custody to maintain supply relationships with Japanese OEMs. Medical device displays face the most stringent enforcement, with PMDA-aligned biocompatibility testing layered atop optical performance certification.
Automotive OEMs are consolidating procurement of complete optical stack assemblies rather than discrete film layers, compressing supplier tiers and favoring integrated adhesive-polarizer-diffuser manufacturers. This specification shift is displacing standalone film vendors from tier-one supply relationships. The restructuring is most visible in South Korea and Germany, where Hyundai-Kia and Volkswagen Group procurement organizations have adopted stack-level supplier qualification protocols.
Display Light Control Film Market Segmentation
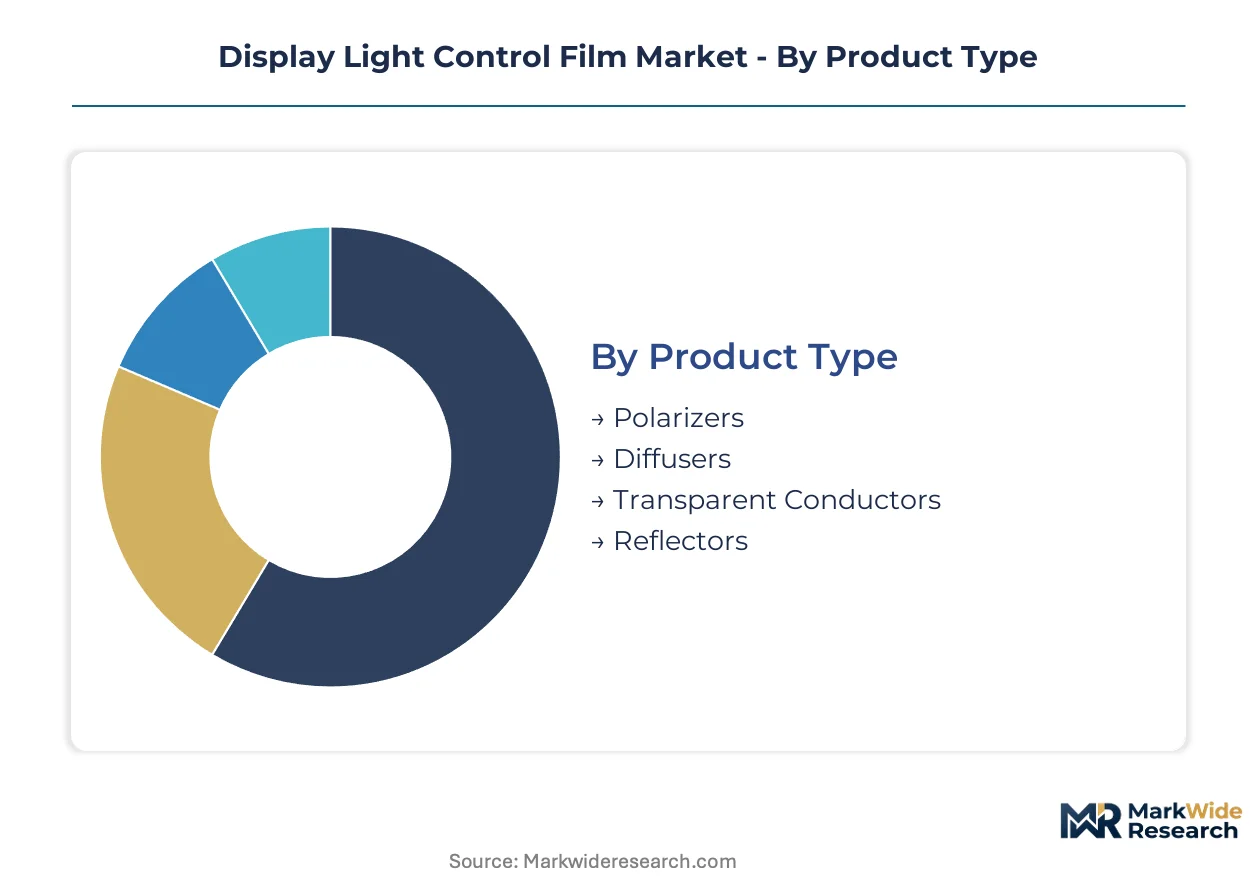
Segmentation in display light control film reveals how optical performance requirements fragment procurement channels. Automotive tier-one suppliers source complete stack assemblies while consumer electronics OEMs purchase discrete film layers through refurbishment distributors.
Product Type:
Polarizers move through direct OEM contracts and display stack integrators, while diffusers and transparent conductors split between tier-one automotive suppliers and refurbishment distributors.
- Polarizers:Multi-layer optical films engineered from stretched polyvinyl alcohol with iodine or dye absorption axes. LCD stack integrators in South Korea and Japan consume the majority volume for television and monitor refurbishment cycles. SAMR-mandated standby power thresholds in China are forcing reformulation of reflective polarizer variants.
- Diffusers:Micro-structured polymer layers with precision haze control below 5-micron feature dimensions. Automotive curved dashboard specifications from Hyundai-Kia and Volkswagen Group procurement are accelerating mini-LED-compatible procurement. Roll-to-roll nanoimprint lithography capacity constraints elongate delivery timelines for qualified suppliers.
- Transparent Conductors:Indium tin oxide coatings and silver nanowire alternatives for touch panel integration.
- Reflectors:Metallized polymer films for backlight recycling in edge-lit display architectures.
By volume, polarizers lead. By growth pace, diffusers are climbing the fastest.
End User:
Cost tier stratification separates medical device certification premiums from automotive stack assembly consolidation and consumer electronics refurbishment economics.
- Consumer Electronics:Television, monitor, and smartphone refurbishment cycles drive recurring demand for replacement polarizer and diffuser films. Chinese coastal manufacturing clusters process the majority of global volume through Shenzhen and Dongguan distribution hubs.
- Automotive Displays:Curved dashboard and center console integration requires complete optical stack assemblies rather than discrete layers. Tier-one suppliers in Germany and South Korea have adopted stack-level qualification protocols that compress supplier tiers.
- Commercial Signage:Large-format outdoor and retail display applications.
- Medical Devices:Diagnostic equipment touch panels requiring PMDA-aligned biocompatibility testing and optical clarity exceeding 90% transmittance.
Consumer electronics commands the volume base. Automotive displays show the steepest expansion trajectory.
Technology:
Application maturity separates established LCD refurbishment economics from emerging OLED stack complexity and nascent E-Paper optical requirements.
- LCD:Mature backlight architectures using edge-lit or direct-lit configurations with polarizer-diffuser-reflector film stacks. Refurbishment demand concentrates in Chinese and Vietnamese assembly operations serving global television replacement markets.
- OLED:Self-emissive panels requiring precision diffuser films for mini-LED hybrid architectures and quantum dot color conversion layers. Automotive specifications for curved form factors are accelerating compatible film procurement from tier-one suppliers.
- DLP:Projection display systems using micromirror arrays with specialized optical films.
- E-Paper:Reflective display technologies for low-power signage and e-reader applications.
LCD retains volume leadership. OLED is gaining share fastest among growth technologies.
Application:
Customer type fragmentation separates display OEM technical specifications from architectural glass manufacturer partnership requirements and lighting system integrator procurement patterns.
- Displays:Flat-panel television, monitor, smartphone, and automotive screen integration representing the core volume base. Procurement channels split between direct OEM supply and refurbishment distributors depending on product lifecycle stage.
- Smart Windows:Privacy-switching electrochromic and polymer-dispersed liquid crystal films for commercial building retrofits. Architectural glass manufacturers in Germany and Japan seek integrated polymer-layer partners for facade system specifications.
- Lighting Control:Optical films for LED luminaire diffusion and glare reduction in commercial and residential fixtures.
- Privacy Screens:Micro-louvered films for confidential viewing angle restriction in financial and healthcare settings.
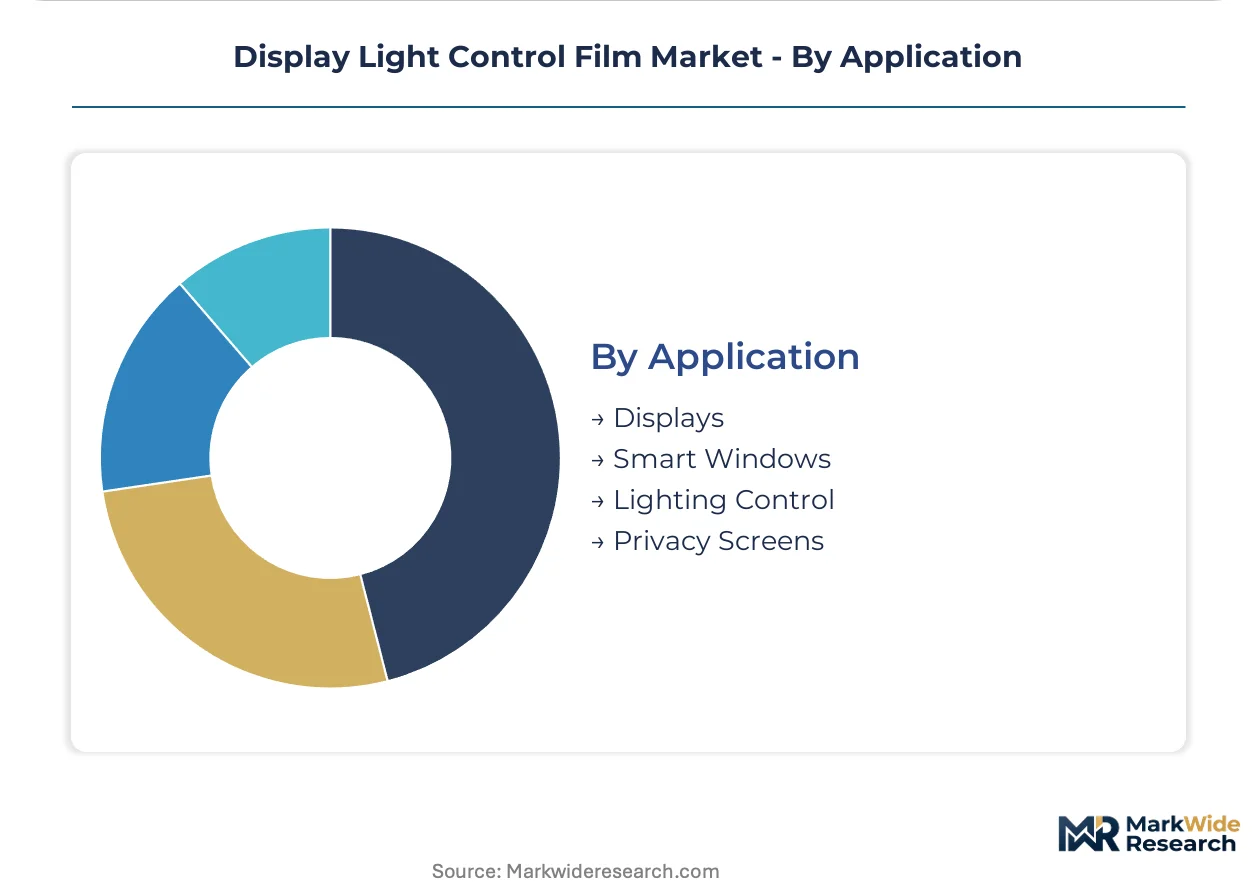
Displays dominate current volume. Smart windows represent the most rapid emergence trajectory among non-display applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for display light control film diverge sharply by geography. Japanese and South Korean manufacturers prioritize complete optical stack assemblies for automotive integration, while Chinese coastal clusters process discrete film layers for consumer electronics refurbishment at scale.
China
Shenzhen and Dongguan distribution hubs handle the majority of global polarizer and diffuser refurbishment volume for television and monitor replacement markets. SAMR-enforced GB standards on display energy efficiency are forcing reformulation of reflective films to meet standby power thresholds. Coastal manufacturing clusters in Guangdong and Jiangsu provinces are absorbing qualified film imports while domestic deposition capacity scales.
Japan
Automotive tier-one suppliers in Nagoya and Osaka prefectures specify precision haze control films for curved dashboard displays from domestic integrated manufacturers. METI-enforced JIS standards for hazardous substance limits and end-of-life recyclability filter imported specifications through material disclosure mandates. Kanto region optical film specialists maintain supply relationships with domestic OEMs through documented polymer chain-of-custody compliance.
South Korea
Hyundai-Kia procurement organizations have adopted stack-level supplier qualification protocols that compress tiers and favor integrated adhesive-polarizer-diffuser manufacturers. MFDS biocompatibility testing requirements extend timelines for films integrated into diagnostic equipment touch panels. Seoul Capital Area and Busan-Ulsan clusters anchor domestic supply chains for OLED-compatible precision films.
Germany
Volkswagen Group procurement has shifted to complete optical stack assemblies rather than discrete film layers, displacing standalone vendors from tier-one relationships. Bavaria and Baden-Württemberg automotive suppliers source mini-LED-compatible diffuser films for curved instrument panel specifications. KBA vehicle type approval processes indirectly shape display component certification requirements for imported film stacks.
United States
Medical device manufacturers specify optical clarity exceeding 90% transmittance combined with antimicrobial surface properties for diagnostic equipment touch panels. FDA device classification pathways create certification moats for qualified film stack providers serving regulated healthcare applications. Midwest and Northeast corridor assembly operations import qualified polarizer substrates primarily from East Asian suppliers.
Display Light Control Film Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in display light control film supply. Patent thickets around multi-layer optical film architectures constrain backward integration attempts by mid-scale entrants. Three archetypes dominate: diversified chemical conglomerates with captive film deposition capacity, precision optics specialists focused on automotive qualification, and refurbishment distributors serving consumer electronics replacement cycles. Competitive moves concentrate on capacity expansion through roll-to-roll nanoimprint lithography systems and strategic partnerships with automotive tier-one suppliers for stack-level integration.
Among diversified chemical conglomerates, 3M and LG Chem exemplify integrated positioning through multi-layer optical film patent portfolios and captive adhesive-polarizer manufacturing. Nitto Denko Corporation anchors the precision optics specialist tier with Japanese supply chain integration. These three occupy positions that reflect distinct geographic and capability specializations rather than direct substitutability.
| Leading Market Players |
|---|
| 3M |
| Nitto Denko Corporation |
| LG Chem |
| Mitsubishi Chemical Corporation |
| Toray Industries, Inc. |
| BenQ Materials Corp. |
| Kolon Industries, Inc. |
| American Polarizers, Inc. |
| Fusion Optix |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four-month delivery schedules for vacuum coating and roll-to-roll nanoimprint lithography systems concentrate pricing power with incumbent equipment holders while compressing margins for capacity-constrained manufacturers attempting to scale micro-structured polymer production.
Pricing Analysis
Long-term offtake contracts dominate procurement between automotive tier-one suppliers and integrated adhesive-polarizer-diffuser manufacturers, while spot purchasing persists in consumer electronics refurbishment channels. Price differentiation separates medical-grade certified films with PMDA-aligned biocompatistry testing from standard commercial grades, with volume scale and customization level as secondary tiering factors. Cost compression in transparent conductor categories is intensifying because silver nanowire alternatives erode indium tin oxide margins. Consumer electronics refurbishment distributors exhibit the highest price sensitivity, whereas medical device OEMs prioritize optical clarity and certification compliance over unit economics.
Supply Chain Analysis
Inventory buffers at Japanese automotive tier-one suppliers typically extend to ninety days for qualified precision haze control films, reflecting deposition equipment lead-time exposure. Manufacturing concentration centers on South Korea, Japan, and coastal China, with raw material dependencies spanning stretched polyvinyl alcohol, iodine absorption compounds, and indium for transparent conductor coatings. Single-source vulnerability in roll-to-roll nanoimprint lithography equipment creates chokepoint risk for capacity expansion. Distribution runs through direct OEM contracts for automotive stack assemblies and Shenzhen-Dongguan refurbishment hubs for consumer electronics replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where automotive OEM consolidation of complete optical stack procurement is collapsing supplier tiers and privileging integrated manufacturers over discrete film vendors.
For Market Incumbents: Fortify patent positions around multi-layer optical film architectures through licensing enforcement against backward-integrating entrants attempting captive adhesive-polarizer manufacturing. Expand roll-to-roll nanoimprint lithography capacity in South Korean and Japanese clusters before equipment lead times elongate further, securing qualification protocols with Hyundai-Kia and Volkswagen Group procurement organizations.
For New Entrants and Emerging Players: Lead with smart window applications for commercial building retrofits, where architectural glass manufacturers in Germany and Japan seek integrated polymer-layer partners for facade system specifications. Target privacy-switching electrochromic films as the most penetrable white-space segment, leveraging partnerships with building automation integrators as the primary go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials consolidation play because automotive tier-one supplier qualification protocols are compressing vendor counts and creating certification-barrier moats for integrated manufacturers. Acquisition targets should display captive deposition capacity and established relationships with Japanese OEMs through documented polymer chain-of-custody compliance. The signal to watch is METI enforcement intensity for JIS recyclability standards filtering imported specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive-Polarizer Manufacturing | Captures stack-level procurement consolidation by Hyundai-Kia and Volkswagen Group. |
| Roll-to-Roll Nanoimprint Lithography Capacity Expansion | Addresses eighteen-to-twenty-four-month equipment lead times constraining qualified supplier output. |
| Smart Window Partnership with Architectural Glass Manufacturers | Opens underpenetrated commercial building retrofit demand in Germany and Japan. |
| Medical Device Certification Investment | Creates premium positioning through PMDA-aligned biocompatibility testing and antimicrobial surface properties. |
| Japanese JIS Recyclability Compliance Program | Builds certification-barrier moats against imported film competitors through METI-mandated material disclosure. |
Study Parameters
Desk research of customs and trade data, SEC filings from diversified chemical conglomerates, and METI regulatory disclosure databases preceded structured interviews with automotive tier-one supplier procurement officers, optical film plant managers, and medical device biomedical engineers. Primary fieldwork with deposition equipment manufacturers and roll-to-roll lithography specialists was cross-validated against secondary sources including GB standard update bulletins from SAMR and JIS recyclability enforcement guidance. Bottom-up volume modeling across product type and end-use segments was triangulated with top-down value estimates derived from confirmed purchase order pipelines.
Variance decomposition across the projection horizon separates volume growth from mix-shift effects and pricing trajectory assumptions. Segmentation dimensions modeled include film type, end-use vertical, display technology architecture, and regional manufacturing cluster. CAGRs were synthesized from confirmed capacity expansion timelines, OEM procurement cycle visibility, and regulatory compliance cost trajectories. Forecast inputs incorporated SAMR-mandated standby power threshold implementation pace and automotive curved dashboard specification adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained East Asian manufacturing cluster stability or indium supply continuity would require recalibration. Forecasts reflect documented assumptions regarding equipment lead-time normalization and regulatory harmonization progress between Asian national standards and IEC baselines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Lighting Management System Market
Lighting
Lighting Control Components Market
Lighting
Hazardous Location LED Lighting Market
Lighting
COB Photo Light Market
Lighting
Global Plasma Lamp Market
Lighting
Smart Lights Market
Lighting
Global Machine Vision Lighting Market
Lighting
LED Eye Protection Desk Lamp Market
Lighting
LED Eye Protection Lamp Market
Lighting
Vintage Bulb Market
Lighting
Global Commercial Lighting Market
Lighting
Illuminating Signs Market
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Smart Lamp Market
Lighting
Dimmers Market
Lighting
Solar Spotlights Market