
 Smart Lights Market | 2026-2036
Smart Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Lights Market Insights
Chinese LED module production is consolidating as domestic fabs scale automated die-attachment and phosphor-coating lines. Signify Holding leverages its Interact IoT platform to anchor large commercial installations across Europe and North America. Acuity Brands competes through nLight networked controls that extend into building management system integration. ams-OSRAM specializes in high-performance LED emitters and sensors that differentiate premium architectural fixtures.
Smart lights encompass solid-state luminaires with embedded connectivity, sensors, and programmable drivers enabling automated dimming, color tuning, and energy metering. These systems typically integrate 2700K-6500K correlated color temperature ranges with occupancy detection thresholds below 30% ambient light levels for daylight harvesting. LED product types dominate installed value owing to lumen-per-watt efficiency above 150 lm/W and declining phosphor-converted white chip costs. IoT technology architectures represent the fastest-expanding connectivity layer as mesh networks enable campus-scale deployment with sub-100ms latency for real-time control. Commercial application segments concentrate margin pools where building automation integration commands 40-60% service attach rates.
The EU Ecodesign Directive and REACH substance restrictions shape product compliance requirements for circadian lighting and mercury-free designs. The US DOE SSL program and FCC Part 15 rules govern wireless emission standards and efficacy benchmarks for connected luminaires. China's GB standards and MIIT IoT security protocols mandate domestic certification for networked lighting deployed in government-backed smart city projects. Stakeholders must monitor evolving cybersecurity requirements for building-connected devices as regulatory scope expands beyond energy efficiency into data governance.
Market Dynamics
Building automation integration is compressing procurement cycles as facility managers consolidate lighting controls under unified IoT platforms rather than standalone retrofit projects.
Growth Catalysts
- EU Ecodesign Directive:Mandatory efficiency benchmarks are forcing replacement of legacy fluorescent installations across German and French commercial portfolios.
- Daylight harvesting algorithms:Sensor-integrated luminaires now automate dimming responses to ambient light levels, cutting HVAC-lighting interaction costs in high-rise offices.
- China:Government-backed smart city infrastructure spending in Shenzhen and Chengdu is embedding networked street lighting as standard municipal procurement.
Market Restraints
- Phosphor-converted white LED chip pricing:Concentrated supply from domestic Chinese fabs creates input cost volatility for fixture assemblers outside Asia.
- Legacy DALI protocol incompatibility:Existing building control infrastructure requires expensive gateway hardware to interface with wireless mesh networks.
- Mercury-free design mandates:REACH substance restrictions eliminate certain phosphor formulations, constraining color-rendering options for architectural specifications.
Strategic Opportunities
- India:Commercial building stock remains underpenetrated by connected controls, with BIS certification opening pathways for imported IoT-enabled fixtures.
- Circadian lighting specifications:Healthcare and education sectors are specifying tunable-white systems that adjust correlated color temperature across the waking day.
- Power-over-Ethernet convergence:IT infrastructure managers are routing both data and low-voltage DC power through single cable runs, collapsing electrical and network contracting scopes.
Industry Challenges
- Cybersecurity competency gaps:Fixture manufacturers lack embedded systems security expertise to meet evolving FCC Part 15 and MIIT IoT protocol requirements for building-connected devices.
- Integration complexity:BACnet and Modbus interoperability testing extends commissioning timelines for campus-scale deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Lights Market |
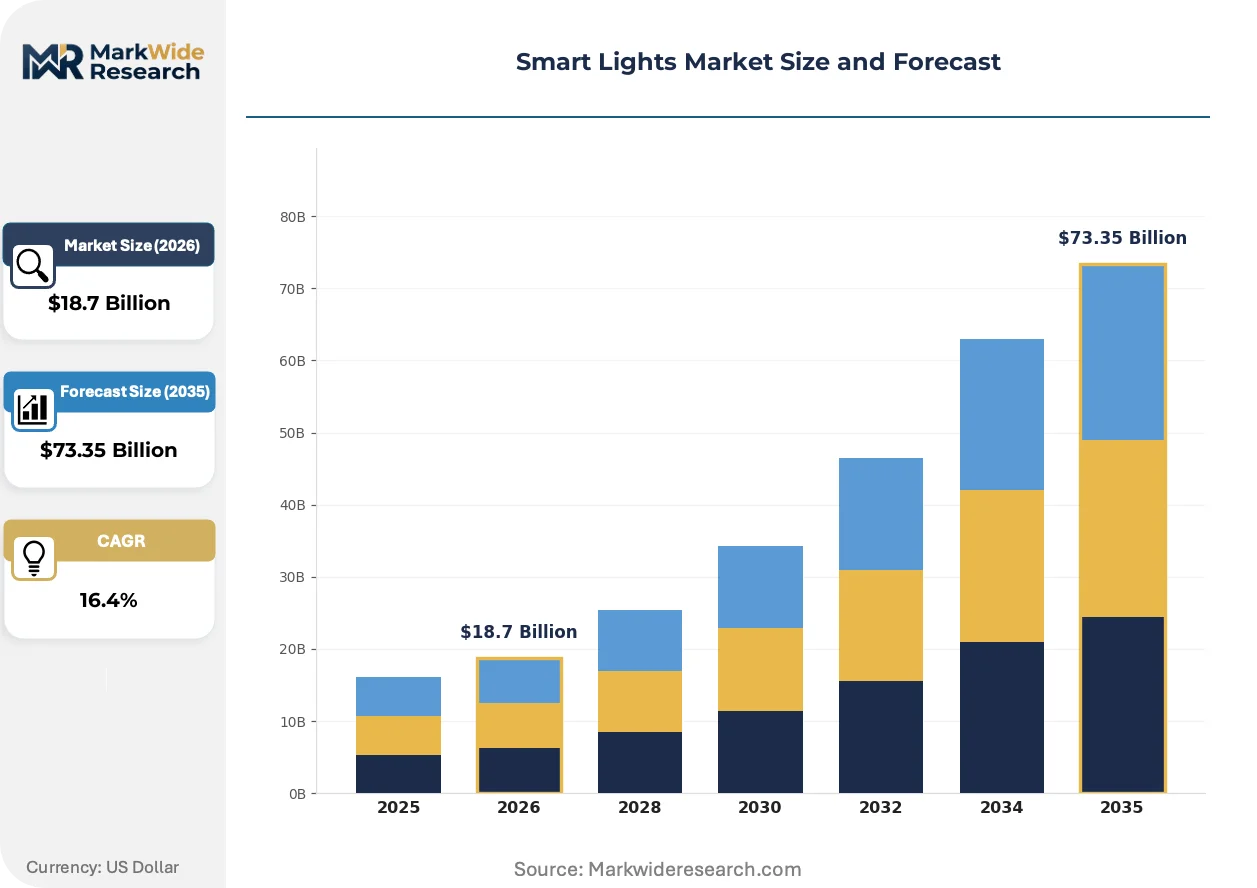
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, Smart Bulbs, Smart Panels Technology: Bluetooth, Wi-Fi, Zigbee, IoT Application: Residential, Commercial, Industrial, Outdoor Control Method: Mobile App, Voice Control, Remote Control, Automation |
| Companies Covered | Signify Holding, Acuity Brands, Legrand, ams-OSRAM, Panasonic Holdings Corporation, Lutron Electronics, Hubbell, Zumtobel Group, LEDVANCE GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Lights Market Trends and Innovations
Human-centric lighting specifications are displacing purely efficiency-driven procurement as building owners prioritize occupant wellness metrics alongside energy cost reduction.
Li-Fi visible light communication is converging with LED luminaire architectures to deliver high-bandwidth data transmission through existing lighting infrastructure. Corporate campuses in the Netherlands and Japan are piloting desk-level connectivity that eliminates RF spectrum congestion. This convergence is compressing the traditional separation between IT infrastructure and lighting capital planning.
China's GB standards for networked lighting security are mandating domestic encryption protocols for government-backed smart city deployments. Fixture vendors must maintain parallel firmware branches to satisfy diverging national cybersecurity frameworks. Commercial segments in Beijing and Shanghai are experiencing the earliest compliance-driven procurement shifts.
Lighting-as-a-service contracting is unbundling capital expenditure from operational control, with energy service companies retaining ownership of installed luminaire assets. Facility managers in Nordic countries are transferring performance risk to vendors through guaranteed lux-hour delivery contracts. This model compresses traditional equipment sales cycles while extending vendor balance sheet exposure.
Smart Lights Market Segmentation
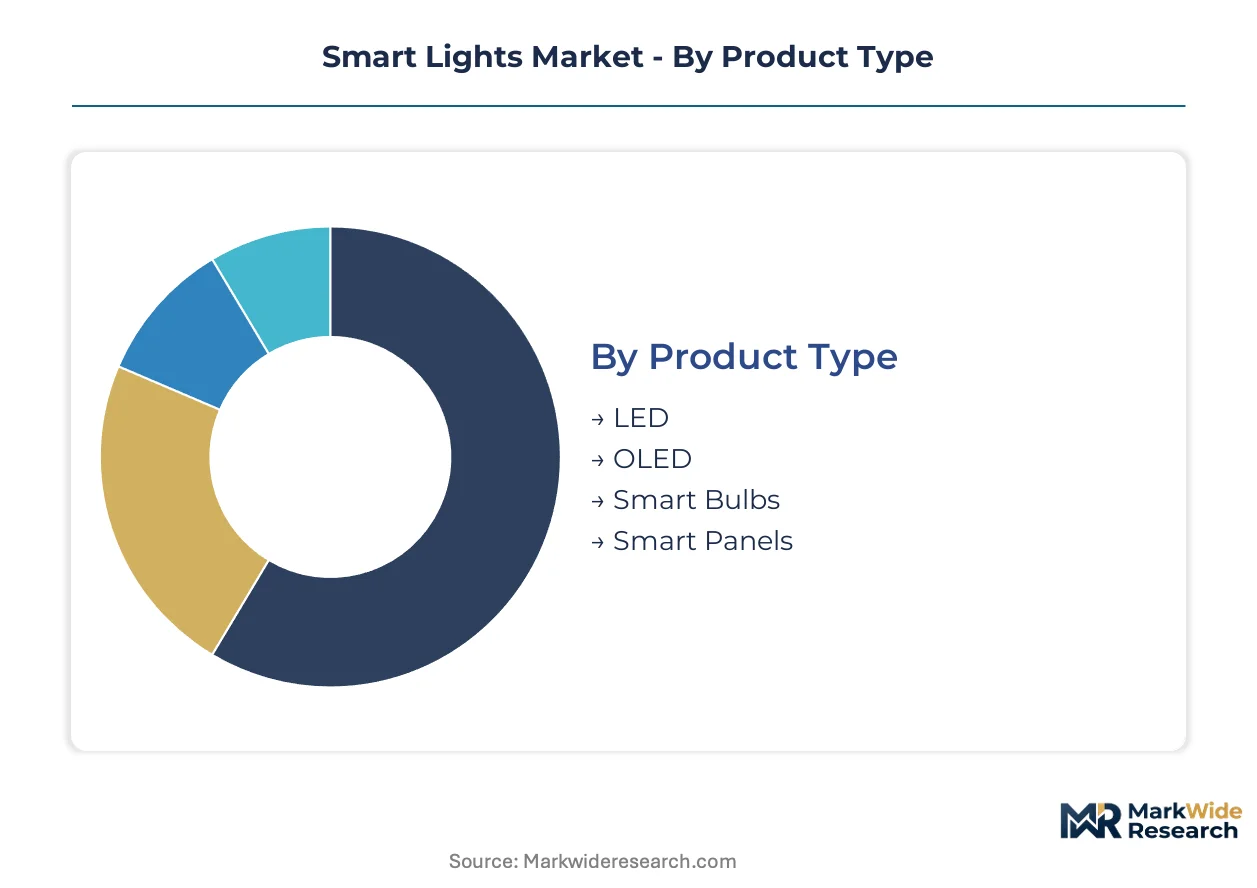
Segmentation in smart lighting reveals how procurement decisions fragment across technical specifications, connectivity protocols, and installation contexts. Buyers prioritize different performance thresholds depending on whether they manage single-family retrofits or campus-scale building automation systems.
Product Type:
Cost tier separates commodity replacements from architectural specification-grade luminaires.
- LED:Phosphor-converted white chips deliver lumen-per-watt efficiency above 150 lm/W, with die-attachment automation in Chinese fabs compressing unit costs. Commercial building retrofits in Germany and France concentrate demand as EU Ecodesign Directive mandates eliminate legacy fluorescent stock.
- Smart Bulbs:Integrated drivers and wireless radios enable direct consumer replacement without fixture modification. Residential channel volumes in Shenzhen and Chengdu climb fastest where domestic manufacturing scale supports aggressive retail pricing.
- OLED:Thin-film organic emitters enable transparent and flexible form factors for premium architectural applications. Boutique hospitality projects in Tokyo and Milan specify these for statement fixtures where glare-free surface illumination commands design premiums.
- Smart Panels:Modular ceiling tiles embed arrays of addressable LEDs with integrated sensors for daylight harvesting. Corporate headquarters in Nordic countries deploy these under lighting-as-a-service contracts that transfer performance risk to vendors.
LED leads volumes today; Smart Bulbs is gaining share fastest.
Technology:
Volume scale and latency tolerance determine protocol selection across deployment sizes.
- IoT:Mesh network architectures enable campus-scale deployment with sub-100ms latency for real-time control integration. Signify Holding's Interact platform anchors large commercial installations across Europe and North America through this layer.
- Zigbee:Low-power IEEE 802.15.4 specification supports dense sensor networks with multi-year battery life. Industrial facilities in the Netherlands pilot this for predictive maintenance integration alongside lighting control.
- Bluetooth:Ubiquitous smartphone compatibility drives residential adoption without dedicated hub hardware. Japanese consumers prefer this for apartment-scale deployments where infrastructure minimization matters.
- Wi-Fi:Existing IT infrastructure absorption eliminates gateway costs for smaller commercial sites. US office fit-outs under 10,000 square feet default to this for rapid commissioning without facilities team training.
IoT dominates commercial attach rates; Zigbee shows steepest expansion trajectory in industrial applications.
Application:
Customer type and procurement authority shape specification complexity and service attach rates.
- Commercial:Building automation integration commands 40-60% service attach rates as facility managers consolidate controls under unified platforms. Acuity Brands competes through nLight networked controls that extend into building management system integration.
- Residential:Voice control compatibility and mobile app simplicity drive consumer channel turnover. China's smart city infrastructure spending has limited direct impact here, though domestic LED cost structures benefit retail pricing globally.
- Industrial:Harsh-environment sealing and vibration resistance specifications dominate procurement criteria. German automotive manufacturing plants specify these for 24-hour production environments where failure costs exceed premium fixture pricing.
- Outdoor:Municipal procurement cycles and smart city funding availability concentrate demand geographically. Government-backed projects in Chengdu embed networked street lighting as standard infrastructure deployment.
Commercial commands margin concentration today; Outdoor is climbing the fastest on smart city capital deployment.
Control Method:
Maturity of user interface expectations and IT infrastructure integration depth segment buyer preferences.
- Automation:Sensor-integrated daylight harvesting and occupancy detection thresholds below 30% ambient light levels eliminate manual intervention. High-rise offices in Singapore deploy these to cut HVAC-lighting interaction costs through algorithmic dimming responses.
- Voice Control:Natural language processing integration with Alexa and Google Home ecosystems drives residential penetration. US consumer channel volumes concentrate here for retrofit convenience without smartphone dependency.
- Mobile App:Granular scene programming and energy metering visibility appeal to technically engaged homeowners. Nordic countries show highest per-capita adoption where energy consciousness intersects with digital literacy.
- Remote Control:Dedicated hardware interfaces persist in hospitality and aged-care facilities where smartphone assumptions fail. French hospital networks specify these for patient room control where universal accessibility mandates apply.
Automation leads specification rates in new construction; Voice Control is expanding most quickly in residential retrofit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in lighting compliance costs is redirecting manufacturing investment toward jurisdictions with streamlined certification pathways. Chinese fabs exploit scale advantages in automated die-attachment while European assemblers absorb REACH substance testing overhead. This divergence concentrates module production in Asia and specification-grade fixture assembly near end markets.
China
Shenzhen and Chengdu smart city deployments embed networked street lighting as standard municipal procurement. MIIT IoT security protocols mandate domestic encryption for government-backed projects, creating compliance moats for local vendors. Yangtze River Delta fabs automate phosphor-coating lines at scale that compresses unit costs for export markets.
Germany
Commercial building retrofits concentrate in Frankfurt and Munich as facility managers pursue HVAC-lighting integration savings. The EU Ecodesign Directive eliminates legacy fluorescent stock across industrial portfolios. Bavarian automotive plants specify harsh-environment luminaires for 24-hour production lines where failure costs exceed premium fixture pricing.
United States
Office fit-outs under 10,000 square feet default to Wi-Fi-enabled controls for rapid commissioning without facilities training. FCC Part 15 wireless emission standards govern connected luminaire deployments. Greater Boston corporate campuses pilot Li-Fi visible light communication through existing LED infrastructure to eliminate RF spectrum congestion.
Japan
Apartment-scale residential deployments favor Bluetooth protocols that minimize infrastructure requirements. METI efficiency benchmarks shape commercial procurement specifications. Kansai region hospitality projects specify OLED fixtures for statement installations where glare-free surface illumination commands design premiums.
India
Commercial building stock remains underpenetrated by connected controls across Mumbai and Delhi-NCR office towers. BIS certification opens pathways for imported IoT-enabled fixtures. Telangana government smart city funding is embedding networked street lighting in Hyderabad municipal procurement cycles.
Smart Lights Market Competitive Landscape
Chinese producers anchor one tier through automated LED module manufacturing at scale; European specialists hold specification-grade fixture assembly through design-engineering proximity to architectural clients. The vendor base splits between consolidated platform players with unified IoT software stacks and fragmented hardware assemblers sourcing commoditized emitters. Two strategic archetypes dominate: building automation integrators bundling controls under unified platforms, and component specialists supplying high-performance emitters and sensors to third-party fixture brands. Competitive moves concentrate on M&A to acquire mesh networking IP and strategic partnerships to collapse electrical and IT contracting scopes.
Among diversified electrical conglomerates, Signify Holding, Legrand, and Panasonic Holdings Corporation exemplify the platform-integrated archetype. These entities occupy positions spanning luminaire manufacturing through IoT software layers, enabling building automation consolidation that commands 40-60% service attach rates in commercial specifications. Their geographic footprints mirror end-market concentration, with European and North American presences anchoring specification-grade procurement and Asian manufacturing bases capturing module cost advantages.
| Leading Market Players |
|---|
| Signify Holding |
| Acuity Brands |
| Legrand |
| ams-OSRAM |
| Panasonic Holdings Corporation |
| Lutron Electronics |
| Hubbell |
| Zumtobel Group |
| LEDVANCE GmbH |
| Others |
Pricing and Supply Chain Analysis
Automated phosphor-coating lines in Yangtze River Delta fabs simultaneously compress LED module unit costs and consolidate production among scaled domestic manufacturers, reshaping margin distribution between Asian emitters and Western fixture assemblers. This production-method transition feeds directly into pricing power asymmetries across the value chain.
Pricing Analysis
Distributor margins in the commercial channel absorb 25-35 point markups before facility managers see landed costs, while direct-to-OEM volumes for smart city contractors trade at steeper discounts. Three-tier pricing structure across specification-grade architectural, standard commercial retrofit, and economy residential replacement levels separates buyers by certification burden and after-sales service bundling. Cost compression in the economy tier intensifies as Shenzhen fabs automate die-attachment, while specification-grade pricing holds firm due to REACH compliance testing overhead. Municipal procurement teams show lowest price sensitivity where smart city funding buffers capital constraints; residential retrofit consumers exhibit highest elasticity to retail price movements.
Supply Chain Analysis
Refurbishment flows for failed LED drivers and sensor modules remain underdeveloped, creating stranded asset risk in early-deployment commercial buildings. Module production concentrates in China, South Korea, and Taiwan, while specification-grade fixture assembly localizes near German and US architectural clients. Phosphor-converted white chips, gallium nitride wafers, and ceramic substrates feed from concentrated Asian chemical processing. Single-source vulnerability in rare-earth phosphor formulations exposes European assemblers to supply disruption. Distribution runs through electrical wholesale networks for commercial volumes and direct-to-retail for residential smart bulbs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in smart lighting rests on phosphor-cost deflation from Chinese manufacturing scale and the shift toward lighting-as-a-service contracts that capture recurring revenue streams from previously transactional hardware sales.
For Market Incumbents: Deploy certification investment as the priority lever. Pursue backward integration into sensor module production to reduce dependency on ams-OSRAM and similar component specialists. Capture channel control through direct contracting relationships with facility management platforms, defending against pure-play IoT software entrants eroding the controls layer. For New Entrants and Emerging Players: Mid-market commercial buildings in India represent the most penetrable buyer archetype, where BIS certification gaps and underdeveloped local manufacturing create import pathways for networked fixture vendors. Target hospitality circadian-lighting specifications in Japan and Nordic healthcare facilities where tunable-white premiums justify new supplier qualification. Pursue white-label partnerships with established electrical distributors to bypass direct sales infrastructure buildout. For Investors and Strategic Acquirers: Valuations sit cheapest among component specialists with high-performance emitter IP but limited platform integration. Long-term viability favors vendors controlling both mesh networking software and luminaire hardware across the analysis window. Acquisition targets should demonstrate MIIT or FCC Part 15 certification progress. Monitor municipal procurement cycle acceleration in Chengdu and Hyderabad as inflection indicators for outdoor segment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified IoT software stacks command 40-60% service attach rates in commercial specifications. |
| Backward Integration | In-house phosphor-coating capacity insulates margin from Chinese fab pricing volatility. |
| Certification Investment | MIIT encryption protocol compliance opens government-backed smart city procurement in Shenzhen. |
| Lighting-as-a-Service Launch | Guaranteed lux-hour contracts transfer performance risk and extend vendor balance sheet exposure. |
| Li-Fi Technology Development | Visible light communication pilots in Netherlands corporate campuses collapse IT and lighting capital planning. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with facility managers, lighting controls engineers, municipal procurement officers, and electrical distribution channel heads with secondary validation. Regulatory filings with the FCC Part 15 database, EU Ecodesign Directive implementation reports, MIIT IoT security protocol documentation, and commercial building energy audit datasets anchored the secondary layer. Bottom-up fixture shipment tallies and top-down construction spending allocation models triangulated market sizing.
Segment-weighting approaches applied differential growth assumptions across product type, connectivity protocol, and application vertical throughout the forecast period. The analytical framework modeled LED versus OLED technology splits, IoT versus Zigbee versus Bluetooth penetration curves, and commercial versus residential versus outdoor demand trajectories. CAGRs derived from regression analysis against construction spending, regulatory mandate timelines, and smart city capital deployment announcements. Input variables included phosphor-converted white chip cost curves, DALI-to-wireless gateway adoption rates, and lighting-as-a-service contract penetration.
Underlying measurement precision varies by segment; outdoor municipal deployments carry tighter precision than fragmented residential retrofit due to concentrated procurement visibility. Forecasts reflect documented assumptions regarding EU Ecodesign Directive enforcement timing, Chinese smart city funding continuity, and cybersecurity protocol evolution. Practitioners should monitor phosphor supply concentration, REACH substance restriction expansion, and FCC Part 15 enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Programmable Stage Lighting Market
Lighting
Intelligent Lighting Market
Lighting
Display Light Control Film Market
Lighting
LED Solar Lighting Market
Lighting
Tritium Light Source Market
Lighting
UAE Smart Lighting Market
Lighting
North America Outdoor Lighting Market
Lighting
Hazardous Lighting Market
Lighting
Europe Decorative Lighting Market
Lighting
Asia-Pacific Hazardous Lighting Market
Lighting
Hazardous Location LED Lighting Market
Lighting
Lighting Fixture Market
Lighting
Intelligent Lighting Controls Market
Lighting
Digital Light Processing Technology Market
Lighting
Architectural Lighting Market
Lighting
Cleanroom Lighting Market