
 Photocell Market | 2026-2036
Photocell Market Size, Share, and Industry Trends Forecast 2026-2036
Photocell Market Analytics
Municipal lighting is recalibrating photocell demand as cities replace manual switching with automated photoelectric controls. SICK AG leverages its sensor engineering depth to dominate industrial automation channels where precision light detection governs process safety. Vishay Intertechnology anchors the supply base through broad semiconductor manufacturing scale and established distribution across Asian production hubs.
A photocell converts incident light into electrical resistance or current variation, typically employing cadmium sulfide or silicon-based photoconductive layers with spectral response ranges from ultraviolet to near-infrared wavelengths; the device serves as the core sensing element in automatic switching systems for outdoor illumination and photovoltaic array tracking. Smart Photocells now lead product architecture evolution by embedding microcontrollers that enable wireless commissioning and dimming integration, while Analog Photocells retain volume dominance in cost-sensitive municipal tenders across emerging economies. Photodiode technology occupies the premium tier where fast response times and linear output characteristics justify higher unit costs in security and scientific instrumentation.
EPA energy efficiency mandates and FCC electromagnetic compatibility standards shape product certification requirements for photocells deployed in US infrastructure, while EU RoHS restrictions on hazardous substances constrain material selection for cadmium-based photoresistors sold into European lighting markets. India's BIS certification and China's GB standards add further compliance layers for manufacturers seeking access to high-growth Asian municipal programs. Stakeholders must monitor evolving interoperability protocols between photocell nodes and centralized smart city management platforms.
Market Dynamics
The photocell market is reconfiguring around embedded microcontroller architectures that displace discrete analog sensing in municipal lighting infrastructure. Smart city procurement mandates now favor wireless-commissionable photoelectric controls over legacy dusk-to-dawn switches.
Growth Catalysts
- India's Smart Cities Mission:Urban municipalities automate street lighting networks using photoelectric sensors with dimming integration. Central government funding accelerates deployment timelines across Tier-1 and Tier-2 cities.
- REACH compliance deadlines:European RoHS restrictions on cadmium-based photoresistors force material transitions to silicon alternatives. Component suppliers retool manufacturing lines to maintain EU market access.
- Photodiode spectral precision:Scientific instrumentation and security systems demand fast-response light detection with linear output characteristics. Research laboratories and perimeter monitoring networks upgrade sensing resolution.
Market Restraints
- Cadmium sulfide supply volatility:Environmental restrictions on heavy metal extraction concentrate raw material sourcing in limited jurisdictions. Price instability ripples through photoresistor manufacturing cost structures.
- Foundry capacity allocation:Semiconductor fabrication for silicon photodiodes competes with automotive and consumer electronics demand. Photocell-specific wafer runs face queue prioritization challenges at Asian contract manufacturers.
- LED driver compatibility gaps:Legacy analog photocells exhibit signal mismatch with modern pulse-width modulation dimming protocols. Retrofit projects require additional interface electronics or complete control replacement.
Strategic Opportunities
- Brazilian municipal infrastructure:Federal energy efficiency programs fund automated lighting controls in underserved urban corridors. Photocell vendors establish local distribution partnerships to capture tender volumes.
- LiDAR convergence:Photodiode arrays integrate with time-of-flight sensing modules for autonomous vehicle and drone navigation. Automotive tier-1 suppliers source high-speed optical detectors for environmental perception stacks.
- China's dual carbon policy:Provincial mandates for intelligent building management create demand for daylight harvesting sensors. Photocell-integrated luminaire controllers qualify for green building certification subsidies.
Industry Challenges
- Firmware certification timelines:Smart photocells with embedded wireless stacks require FCC and CE radio equipment approvals. Multi-protocol support extends validation cycles before commercial release.
- Legacy infrastructure integration:Decades-old street lighting cabinets lack standardized mounting dimensions or electrical interfaces. Field technicians face hardware adaptation complexity during upgrade deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photocell Market |
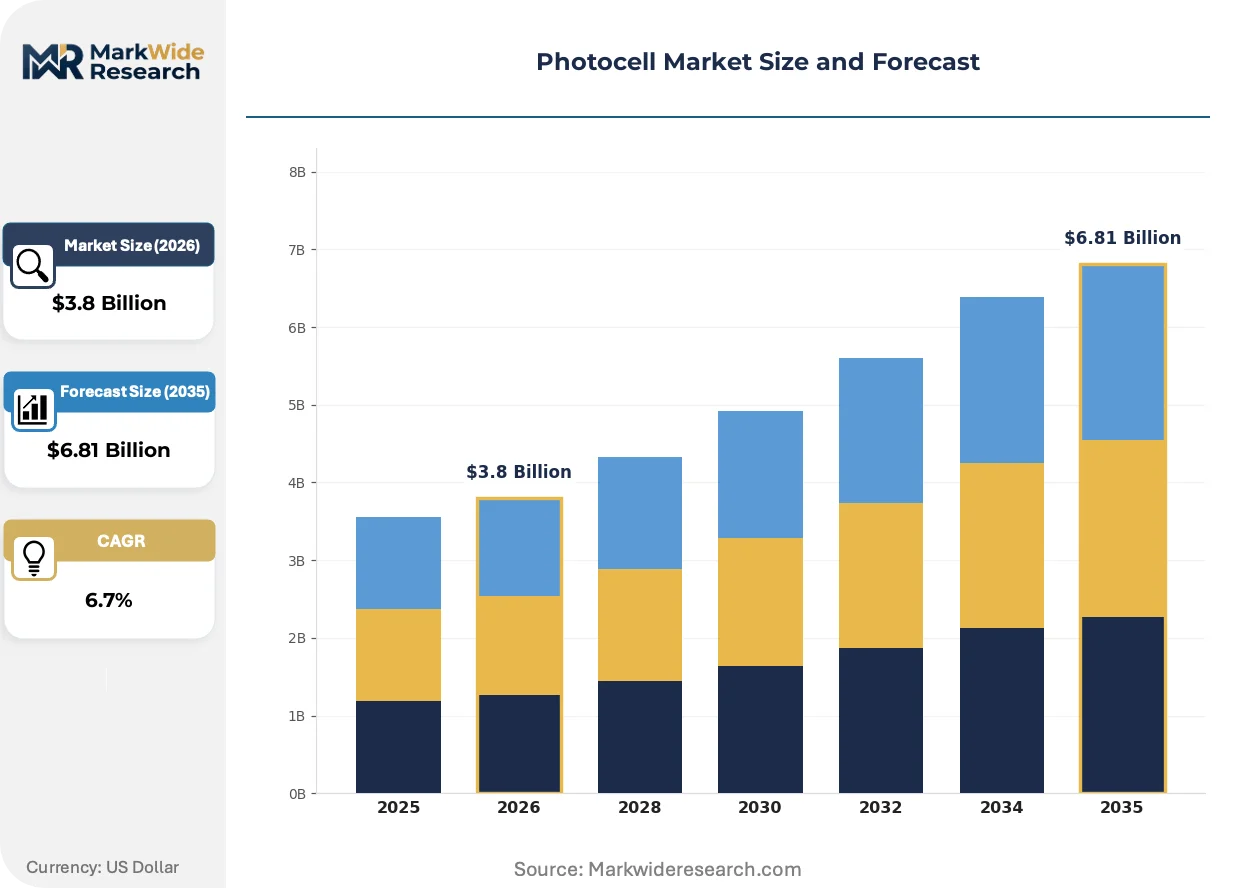
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Photocells, Digital Photocells, Smart Photocells, Adjustable Photocells Application: Street Lighting, Solar Lighting, Indoor Lighting, Security Systems Technology: Photoresistor, Phototransistor, Photodiode, Smart Sensors End User: Residential, Commercial, Industrial, Municipal |
| Companies Covered | Banner Engineering Corp., Keyence Corporation, SICK AG, Hamamatsu Photonics, Vishay Intertechnology, Autonics Corporation, Schneider Electric, Longjoin Electronics, Pepperl+Fuchs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photocell Market Evolving Landscape
Photocell architecture is bifurcating between premium smart nodes with edge computing capability and stripped-down analog units for cost-constrained tenders. Component suppliers must serve divergent performance requirements without fragmenting production scale.
Silicon photodiode technology is integrating avalanche multiplication structures for single-photon sensitivity in quantum sensing and medical imaging applications. Research institutions and defense contractors adopt these detectors for low-light spectroscopy and secure communications. The technology is compressing the performance gap between discrete optical sensors and full imaging arrays.
EPA energy efficiency mandates for federal building retrofits tighten photoelectric control specifications for outdoor luminaires. Manufacturers redesign spectral response curves to minimize false triggering from artificial light sources. US municipal procurement departments now require documented compliance with DesignLights Consortium technical requirements.
Buyer consolidation among national lighting distributors is compressing supplier negotiation leverage. Large-scale electrical contractors bundle photocell procurement with luminaire and pole packages. India's state electricity boards centralize tender awards through e-procurement platforms that favor vendors with established BIS certification records.
Photocell Market Segmentation
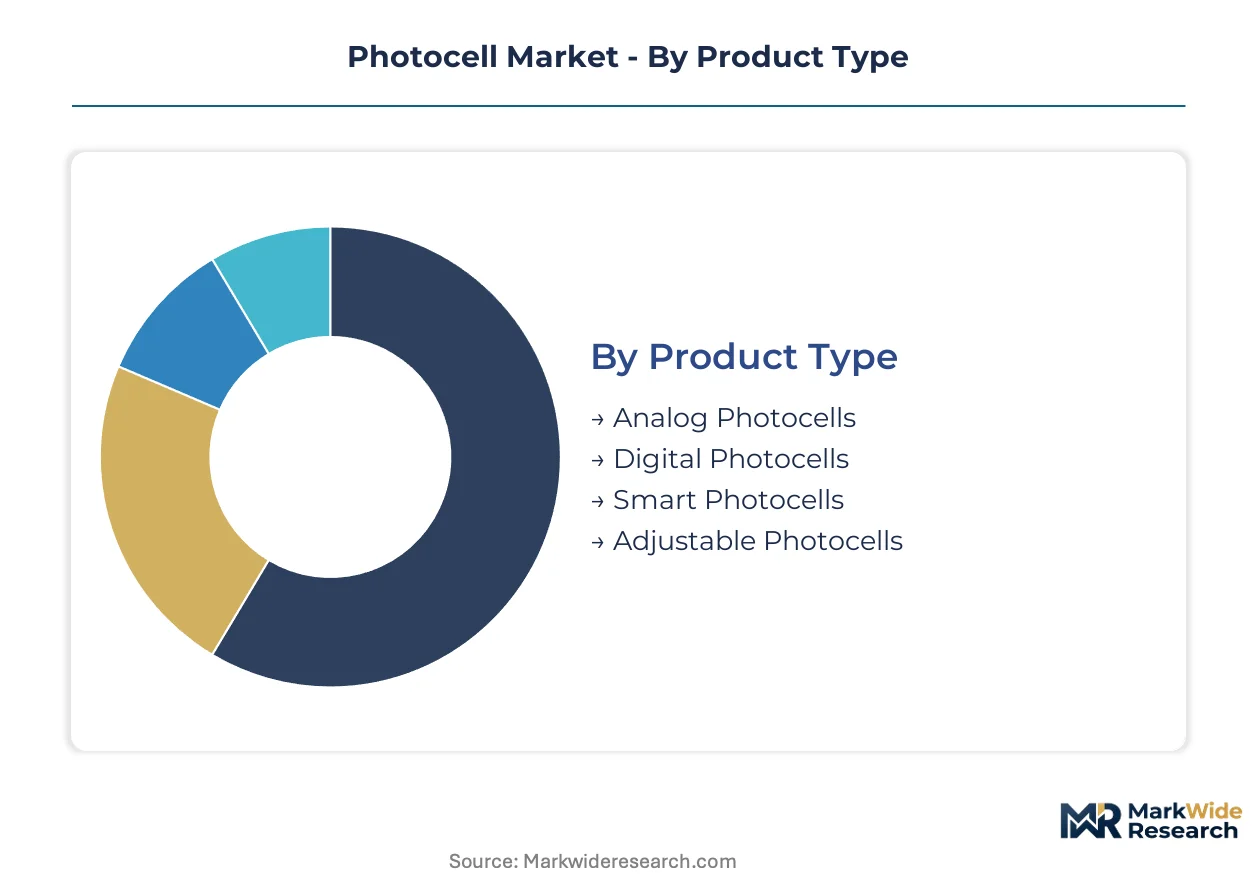
Photocell purchasing behavior diverges sharply between cost-driven municipal tenders and performance-oriented industrial specifications. Component suppliers must maintain parallel product architectures to serve these divergent buyer value chains without fragmenting manufacturing scale.
Product Type:
Cost sensitivity and connectivity requirements separate buyers across this dimension.
- Analog Photocells:Discrete photoresistor circuits with no embedded processing deliver resistance-variable output proportional to incident light. Municipal street lighting departments in India and Brazil specify these units for high-volume dusk-to-dawn controls where unit economics dominate procurement scoring.
- Smart Photocells:Microcontroller-integrated nodes with wireless commissioning stacks and dimming protocol translation enable remote configuration and energy management platform integration. China's provincial smart building mandates and India's Smart Cities Mission specifications favor these units for centralized lighting network orchestration.
- Digital Photocells:Binary threshold detectors with solid-state output stages provide improved noise immunity over analog variants for commercial parking structure applications.
- Adjustable Photocells:Potentiometer-equipped units allow field calibration of switching thresholds for specialized agricultural and horticultural lighting control systems.
Analog Photocells lead volumes today; Smart Photocells are gaining share fastest.
Application:
Installation environment and duty cycle requirements drive specification divergence.
- Street Lighting:Hardened enclosures with IP66 ingress protection and wide temperature operating ranges withstand decades of outdoor exposure. India's state electricity boards and Brazil's federal energy efficiency programs channel procurement through centralized e-tender platforms with BIS and INMETRO certification requirements.
- Solar Lighting:Ultra-low standby current draw and precise dawn-detection algorithms maximize battery conservation in off-grid luminaire systems deployed across rural India and distributed Brazilian municipalities.
- Indoor Lighting:Compact form factors and neutral aesthetic housings serve daylight harvesting integration in China's green building certification programs.
- Security Systems:Fast response photodiode-based detectors trigger perimeter illumination and camera activation for facility protection networks.
Street Lighting anchors current deployment volumes; Solar Lighting shows steepest expansion trajectory.
Technology:
Speed, linearity, and spectral precision requirements stratify component selection.
- Photodiode:Silicon p-n junction devices with nanosecond response times and linear photocurrent output serve scientific instrumentation, LiDAR time-of-flight modules, and high-speed security detection where signal fidelity justifies premium unit costs.
- Photoresistor:Cadmium sulfide or cadmium selenide photoconductive layers exhibit resistance modulation across orders of magnitude with simple two-terminal interfacing. REACH and RoHS restrictions in Europe are forcing material transitions to silicon alternatives for EU market access.
- Phototransistor:Bipolar devices with internal gain provide amplified output for moderate-speed switching applications in consumer electronics and basic industrial controls.
- Smart Sensors:System-in-package architectures combining optical sensing, signal conditioning, and communication protocol stacks enable edge-computing functionality for networked lighting infrastructure.
Photoresistor technology dominates shipment volumes; Photodiode segments command premium pricing expansion.
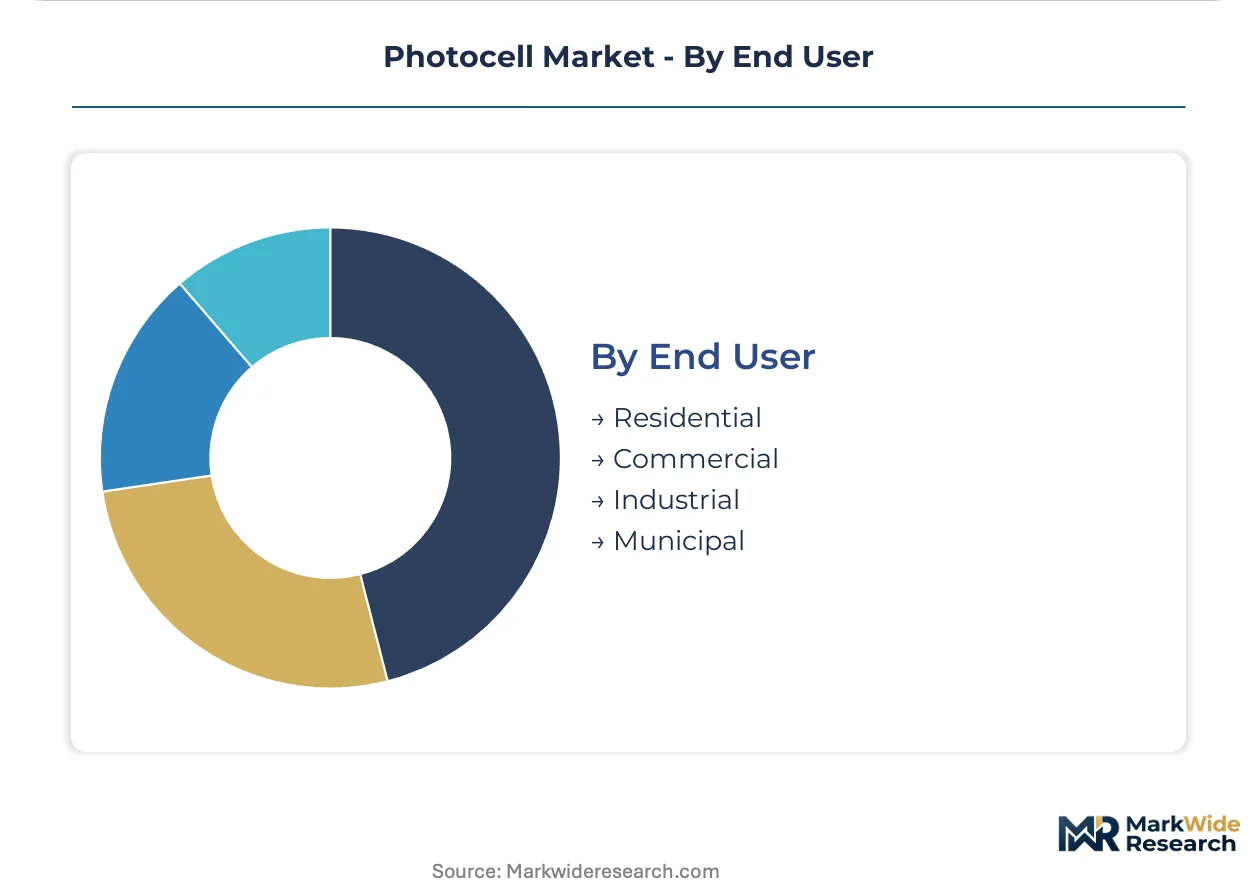
End User:
Procurement centralization and technical specification authority vary dramatically across buyer types.
- Municipal:Government agencies with centralized tender processes and multi-year maintenance contracts prioritize lowest total cost of ownership and documented compliance with national certification schemes.
- Industrial:Facility engineering departments specify ruggedized photoelectric controls for process safety, machine guarding, and automated material handling systems requiring precision light detection.
- Commercial:Property developers and facility managers balance aesthetic integration with energy code compliance for retail, hospitality, and office building retrofits.
- Residential:Homeowners and small contractors purchase through electrical wholesale and retail channels with minimal technical specification beyond basic dusk-to-dawn functionality.
Municipal procurement generates largest volume concentration; Industrial segments sustain highest margin structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage shapes photocell sourcing patterns as manufacturers relocate production to jurisdictions with lower environmental compliance costs. REACH restrictions in Europe accelerate cadmium sulfide phase-outs while Asian production hubs absorb displaced capacity. Municipal procurement centralization in emerging economies concentrates demand in specific urban corridors.
United States
Federal building retrofit mandates and smart city infrastructure programs drive photocell deployment across municipal networks. EPA energy efficiency standards and FCC electromagnetic compatibility requirements govern product certification for outdoor luminaire controls. California's Title 24 energy code and Texas municipal utility programs anchor demand concentration on the coasts and in the Southwest.
China
Provincial dual carbon targets and intelligent building management mandates accelerate daylight harvesting sensor installation. GB standards and MIIT regulations establish technical benchmarks for networked lighting controls. The Yangtze River Delta and Pearl River Delta manufacturing clusters host component fabrication and luminaire assembly operations serving domestic and export markets.
India
The Smart Cities Mission channels central government funding into automated street lighting networks across Tier-1 and Tier-2 urban municipalities. BIS certification requirements and CEA technical standards regulate photoelectric control procurement through centralized e-tender platforms. Maharashtra and Karnataka state electricity boards lead deployment volumes in western and southern corridors.
Germany
Industrial automation demand and precision instrumentation requirements sustain premium photodiode consumption. REACH compliance deadlines and RoHS substance restrictions force material transitions away from cadmium-based photoresistors. Bavaria and Baden-Württemberg host machine-building clusters that integrate photoelectric sensing into process safety systems.
Brazil
Federal energy efficiency programs fund automated lighting controls in underserved urban infrastructure corridors. ANVISA and INMETRO certification frameworks govern product market access for imported and domestically manufactured components. São Paulo and Rio de Janeiro metropolitan regions concentrate municipal tender volumes and distribution partnerships.
Photocell Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with component suppliers competing on certification breadth and luminaire integrators competing on installation scale. The vendor base organizes around three tiers: multinational semiconductor houses with distribution depth, regional electrical component specialists with local certification expertise, and contract manufacturers serving private-label municipal procurement. Consolidation pressure operates through backward integration into optical sensing materials and forward integration into wireless control module assembly.
Among German precision sensor manufacturers, SICK AG exemplifies the industrial automation archetype with deep sensor engineering heritage. Vishay Intertechnology anchors the broad semiconductor manufacturing tier with established Asian production footprint and distribution scale. Japanese optoelectronics specialists Hamamatsu Photonics occupy the scientific instrumentation tier where spectral precision commands premium positioning. These three represent divergent competitive vectors: industrial process integration, commodity scale manufacturing, and research-grade performance specialization.
| Leading Market Players |
|---|
| Banner Engineering Corp. |
| Keyence Corporation |
| SICK AG |
| Hamamatsu Photonics |
| Vishay Intertechnology |
| Autonics Corporation |
| Schneider Electric |
| Longjoin Electronics |
| Pepperl+Fuchs |
| Others |
Value Network & Pricing Analysis
Optoelectronics engineering talent concentration in Taiwan and South Korea compresses smart photocell production costs while widening spreads between premium microcontroller-integrated nodes and economy analog units. Labor-cost differentials between Asian semiconductor fabrication hubs and European sensor assembly operations translate directly into three-tier pricing stratification across municipal procurement tiers.
Pricing Analysis
Distributor margin layers absorb 15-25 point markups between contract manufacturers and municipal tender winners, with direct-to-OEM channels commanding steeper volume discounts. Pricing stratifies across premium smart nodes, standard digital units, and economy analog tiers driven by certification grade and wireless protocol complexity. Cost compression in the analog segment intensifies as Indian and Brazilian e-procurement platforms prioritize lowest-unit-cost scoring. Municipal buyers exhibit extreme price sensitivity; industrial automation purchasers tolerate premium positioning for photodiode precision.
Supply Chain Analysis
Single-source vulnerability sits with China-based cadmium sulfide refiners facing REACH-driven export restrictions to European markets. Raw material sourcing draws from Chinese rare earth processing, Malaysian semiconductor packaging, and German precision optics finishing. Semiconductor wafer fabrication rests on Taiwan and South Korea foundry capacity allocation competing with automotive chip demand. Tariff exposure on photoresistor components shipped from Asia to Brazil and India elevates landed costs. Distribution runs through national electrical wholesale networks with BIS and INMETRO certification gating market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH cadmium restrictions and India's Smart Cities Mission funding timelines accelerate demand inflection. Compliance-driven replacement cycles and green building certification mandates create sustained procurement velocity.
For Market Incumbents: Extend wireless protocol certification breadth to capture India's centralized e-tender platforms requiring multi-standard interoperability. Deepen backward integration into silicon photodiode wafer sourcing to offset foundry queue prioritization risks from automotive chip demand. Defend margin structures by embedding firmware update services into long-term municipal maintenance contracts.
For New Entrants and Emerging Players: Photodiode array miniaturization for LiDAR integration offers a technology-first wedge into automotive tier-1 supplier qualification programs. Target Brazilian federal energy efficiency corridors where ANVISA certification gaps delay established vendor deployments. Pursue daylight harvesting sensor partnerships with Chinese green building certification consultancies as the fastest penetrable application vector.
For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, seeking sensor engineering depth for process safety integration. Five-to-ten year viability hinges on smart city infrastructure spend durability and semiconductor supply chain regionalization. Acquisition target archetypes include regional specialists with BIS or INMETRO certification moats. Monitor LiDAR module procurement acceleration from autonomous vehicle programs as the critical demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Protocol Certification Expansion | Multi-standard interoperability unlocks India's Smart Cities Mission tender participation. |
| Backward Integration into Silicon Photodiodes | In-house wafer sourcing insulates margins from Taiwan foundry queue competition. |
| LiDAR Module Partnership Development | Photodiode array precision qualifies components for automotive perception stack integration. |
| Brazilian Distribution Partnership Establishment | ANVISA-compliant local presence captures federal energy efficiency program volumes. |
| Green Building Certification Alignment | Daylight harvesting sensor integration qualifies for China's dual carbon subsidy mechanisms. |
Research Methodology
Bottom-up municipal tender modeling reconciled against top-down semiconductor shipment tracking forms the analytical core of this study. Primary interviews with street lighting procurement officers, luminaire OEM engineering directors, and optoelectronics distribution channel managers combine with secondary validation from BIS certification databases, INMETRO regulatory filings, and customs trade records. The approach triangulates volume estimates across product architecture tiers and geographic deployment corridors.
Input-output matrices map photoresistor and photodiode component flows through foundry, packaging, and luminaire integration stages across the projection horizon. Segmentation dimensions include product type, application environment, technology platform, and end-user procurement centralization. CAGRs derive from installation run-rate analysis in India's state electricity board programs and China's provincial building mandates. Forecast inputs incorporate REACH compliance timeline acceleration and FCC radio equipment approval cycle durations.
The model holds under stable regulatory enforcement intensity; deviation in cadmium sulfide restriction implementation pace or smart city funding allocation would shift volume trajectories. Forecasts reflect documented assumptions on tender award seasonality and foundry capacity expansion schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
North America Outdoor Lighting Market
Lighting
Vintage Bulb Market
Lighting
Lighting Product Market
Lighting
Circadian Lighting Market
Lighting
Illuminating Signs Market
Lighting
Global Machine Vision Lighting Market
Lighting
Softbox Lighting Kit Market
Lighting
Lighting Management System Market
Lighting
North America Smart Lighting Market
Lighting
Europe Lighting Control Systems Market
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Lamps and Lighting Market
Lighting
UV Lamps Market
Lighting
Global Lighting Control System Market
Lighting
Industrial Lighting Market
Lighting
Flexible Lighting Foils Market