
 LED Eye Protection Lamp Market | 2026-2036
LED Eye Protection Lamp Market Size, Share, and Industry Trends Forecast 2026-2036
LED Eye Protection Lamp Market Insights
Blue-light hazard certification upgrades is redrawing competitive positioning in the LED eye protection lamp space. Signify leverages its photobiological safety testing infrastructure to anchor premium positioning across European and Asian markets. Xiaomi competes on manufacturing scale and direct-to-consumer channel control, sustaining price accessibility without sacrificing flicker-free performance benchmarks. Dyson differentiates through thermal management engineering and adjustable arm mechanics, occupying the design-forward tier where consumers prioritize longevity over upfront cost.
An LED eye protection lamp is a solid-state lighting fixture engineered to minimize retinal photochemical hazard through controlled spectral output below 450 nanometers, flicker frequencies stabilized above 3125 Hz, and glare indices maintained below 19 UGR. Its primary commercial purpose is to reduce visual fatigue and accommodative stress during sustained near-work tasks in domestic, educational, and professional environments. Desk lamps dominate volume shipments due to universal workspace applicability, while smart lighting technology captures disproportionate margin pools as consumers prioritize app-based circadian programming and occupancy sensing. Educational institutions represent the fastest-growing end user segment as school systems retrofit classrooms with eye-care standards.
China's SAMR enforces GB/T 9473 and GB 7000.1 compliance for illuminance uniformity and blue-light risk group classification, effectively filtering uncertified imports from domestic retail channels. The EU RoHS directive and REACH substance restrictions constrain phosphor and solder compositions, pushing manufacturers toward lead-free driver architectures and mercury-free LED packages. Ecodesign regulations under the EU Green Deal are tightening minimum efficacy thresholds and standby power limits. Stakeholders must monitor how fragmented national certification regimes reshape sourcing strategies and whether dual-carbon policy acceleration in China forces upstream chip suppliers toward lower-emission gallium nitride foundry processes.
Market Dynamics
Photobiological hazard certification is compressing uncertified manufacturers out of retail channels while concentrating volume among vertically integrated producers with in-house testing infrastructure. China's SAMR enforcement of GB/T 9473 is filtering import competition and reshaping sourcing decisions for European and North American distributors.
Growth Catalysts
- GB/T 9473 illuminance uniformity mandates:China's SAMR tightened compliance verification in 2024, forcing lamp manufacturers to upgrade optical engineering capabilities and photometric testing equipment.
- Educational institution retrofit cycles:School systems in Shanghai, Beijing, and Shenzhen are replacing fluorescent classroom fixtures with flicker-free LED eye protection units to meet revised student vision health guidelines.
- Home office permanence:Sustained remote work arrangements in knowledge-worker households are expanding the addressable base for task lighting with circadian programming features.
Market Restraints
- GaN epitaxy wafer cost volatility:Upstream gallium nitride substrate prices fluctuate with power semiconductor demand, squeezing margins for lamp producers without captive LED chip supply.
- Phosphor supply concentration:Rare-earth phosphor production clusters in Jiangxi and Fujian provinces create geographic single-point vulnerability for manufacturers dependent on high-CRI formulations.
- REACH substance restrictions:ECHA constraints on cadmium-containing quantum dots are blocking certain narrow-band red phosphor technologies from EU market entry.
Strategic Opportunities
- Occupancy-sensing convergence:Integration of millimeter-wave presence detection with tunable white LED engines enables automatic circadian rhythm matching for healthcare and hospitality verticals.
- India BIS certification gap:Domestic manufacturers with ISI mark capabilities can capture share in underpenetrated tier-two and tier-three cities before multinational brands complete localization.
- EU Ecodesign standby power limits:Tightening maximum off-state consumption thresholds under the Green Deal create first-mover advantage for zero-standby driver architectures.
Industry Challenges
- Photobiological safety testing talent scarcity:Certified IEC 62471 assessors command premium compensation, constraining R&D throughput for mid-tier manufacturers without dedicated metrology departments.
- Dual-carbon compliance timeline compression:China's MEE acceleration of carbon intensity benchmarks for gallium nitride foundries is forcing lamp producers to requalify alternative chip suppliers on shortened schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Eye Protection Lamp Market |
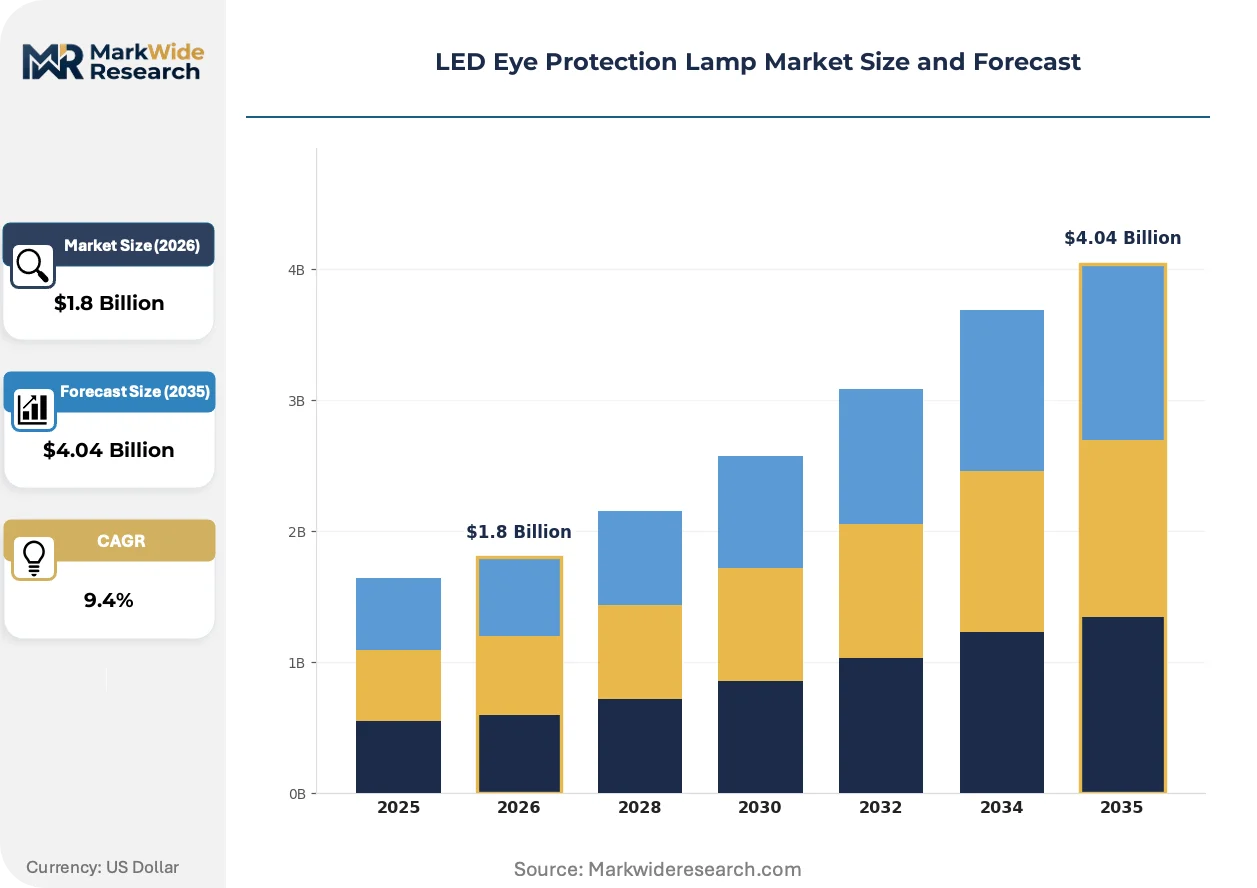
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desk Lamps, Floor Lamps, Clip-on Lights, Wall-mounted Lamps Technology: Smart Lighting, Adjustable Color Temperature, Flicker-free, UV Protection End User: Home Users, Offices, Educational Institutions, Healthcare Facilities Distribution Channel: Online Retail, Specialty Stores, Mass Retailers, Direct Sales |
| Companies Covered | Philips Lighting (Signify), BenQ Corporation, Dyson Ltd., Lumie, Humanscale Corporation, Herman Miller, Inc., OttLite Technologies, Inc., Xiaomi Corporation, Osram, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Eye Protection Lamp Market Trends and Innovations
Spectral engineering and smart control architectures are fragmenting the product landscape into health-certified premium tiers and connected-lifestyle segments. Manufacturers must now optimize simultaneously for photobiological safety metrics and software ecosystem integration.
Full-spectrum LED phosphor formulations with enhanced cyan gap filling are bifurcating the mid-market into health-optimized and cost-optimized product lines. Educational procurement departments in Japan's METI-supervised school districts are specifying melanopic ratio compliance above luminous efficacy. This technology compression is forcing legacy manufacturers to abandon single-peak blue-pump architectures entirely.
REACH authorization requirements for nickel-containing alloys in lamp arm assemblies are extending supplier qualification timelines by eight to fourteen months. European OEMs are shifting toward aluminum-magnesium extrusions and carbon-fiber-reinforced polymers to bypass substance restriction bottlenecks. Desk lamp categories with adjustable mechanical joints face disproportionate material substitution pressure compared to fixed-position panel designs.
Parental purchasing decisions in China's tier-one cities now prioritize GB/T 9473 certification grades over lumen-per-watt specifications. E-commerce platforms are surfacing blue-light risk group classifications in search ranking algorithms, displacing price-sorting as the default discovery mechanism. This certification-driven preference shift is most visible in Shanghai and Hangzhou, where household education expenditure concentrates in eye-care product categories.
LED Eye Protection Lamp Market Segmentation
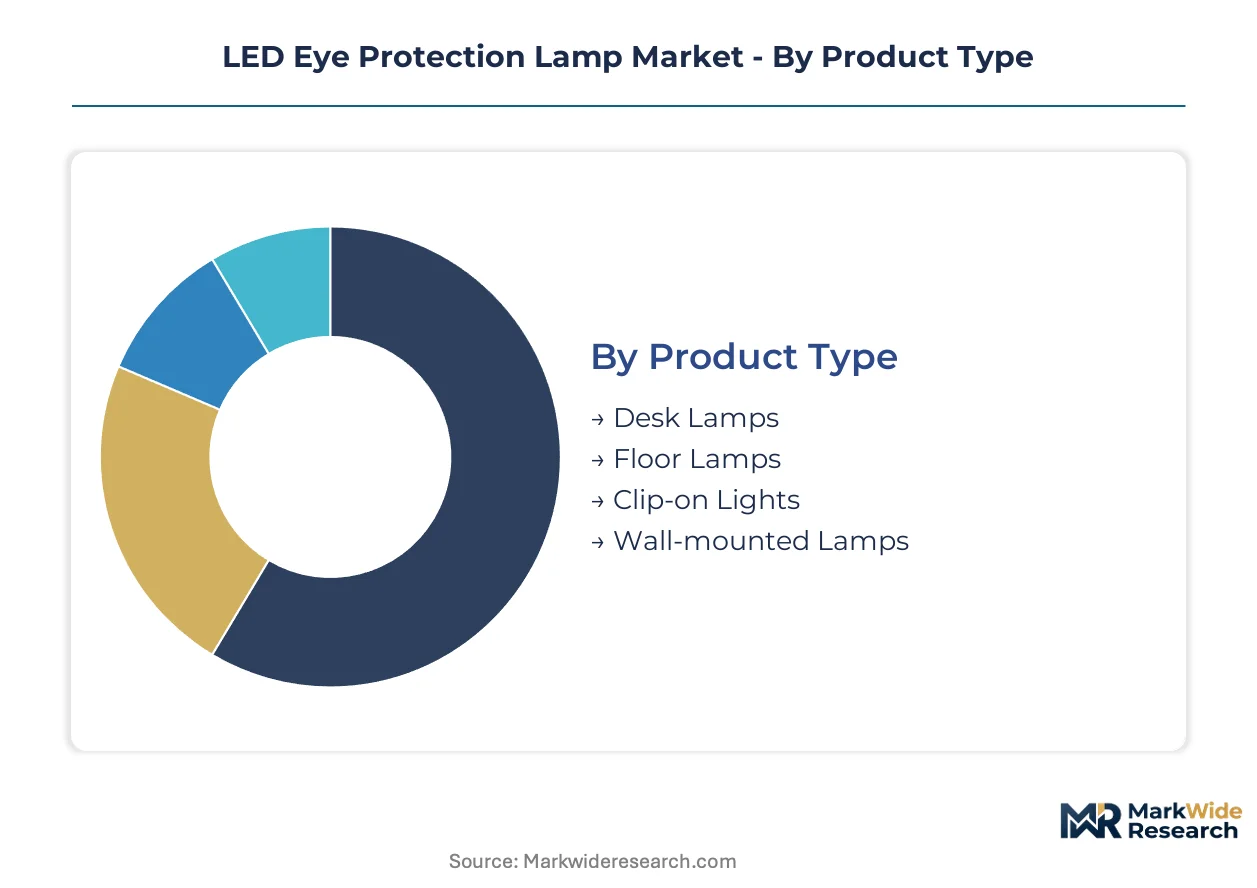
LED eye protection lamp segmentation reveals how certification requirements and channel economics reshape product development priorities. Manufacturers must align technical specifications with the purchasing authority of each end-use environment.
Product Type:
Channel mix varies sharply by fixture form factor, with desk and floor lamps flowing through divergent retail pathways despite shared optical engineering standards.
- Desk Lamps:Task-optimized fixtures with adjustable arm mechanics and base-stabilized optical engines dominate e-commerce volume. Shanghai and Beijing households drive replacement cycles as GB/T 9473 compliance becomes a visible search filter on domestic platforms.
- Floor Lamps:Vertical illumination systems with diffused panel architectures serve living-room reading environments. Specialty lighting retailers in Shenzhen and Guangzhou capture disproportionate margin on adjustable-height models with circadian programming.
- Clip-on Lights:Portable fixtures with clamp-based mounting target dormitory and shared workspace applications.
- Wall-mounted Lamps:Fixed-position architectural units integrate with built-in cabinetry in premium residential renovations.
Desk lamps dominate installed base. Floor lamps are where expansion concentrates.
Technology:
Cost tier stratification separates premium-certified optical systems from baseline flicker compliance, with smart connectivity commanding the widest margin spreads.
- Smart Lighting:App-enabled systems with millimeter-wave occupancy sensing and cloud-based circadian programming. Healthcare facilities in Japan's METI-supervised districts specify melanopic ratio compliance above raw luminous output.
- Adjustable Color Temperature:Tunable white engines with cyan-gap-filled phosphor formulations span 2700K to 6500K. Educational procurement in China's tier-one cities prioritizes spectral continuity over single-peak blue-pump architectures.
- Flicker-free:Driver architectures stabilizing output above 3125 Hz eliminate perceptible modulation.
- UV Protection:Encapsulant and diffuser materials blocking sub-400nm emission for photobiological risk group compliance.
Smart lighting captures premium pricing. Flicker-free represents the baseline for channel access.
End User:
Application-specific requirements fragment procurement authority across household, institutional, and clinical decision-makers with divergent compliance thresholds.
- Educational Institutions:Classroom retrofit programs in Shanghai, Beijing, and Shenzhen drive volume procurement of uniform-illuminance fixtures. Revised student vision health guidelines mandate GB/T 9473 Grade AA compliance for new installations.
- Home Users:Individual purchasers prioritizing blue-light risk group classifications over lumen-per-watt specifications. Parental expenditure concentrates in Hangzhou and Nanjing where household education spending flows to eye-care categories.
- Offices:Corporate procurement departments specifying UGR below 19 for open-plan environments.
- Healthcare Facilities:Clinical settings requiring IEC 62471-certified risk group assessment for patient-facing illumination.
Educational institutions drive volume procurement. Home users are climbing the fastest as certification visibility reshapes e-commerce discovery.
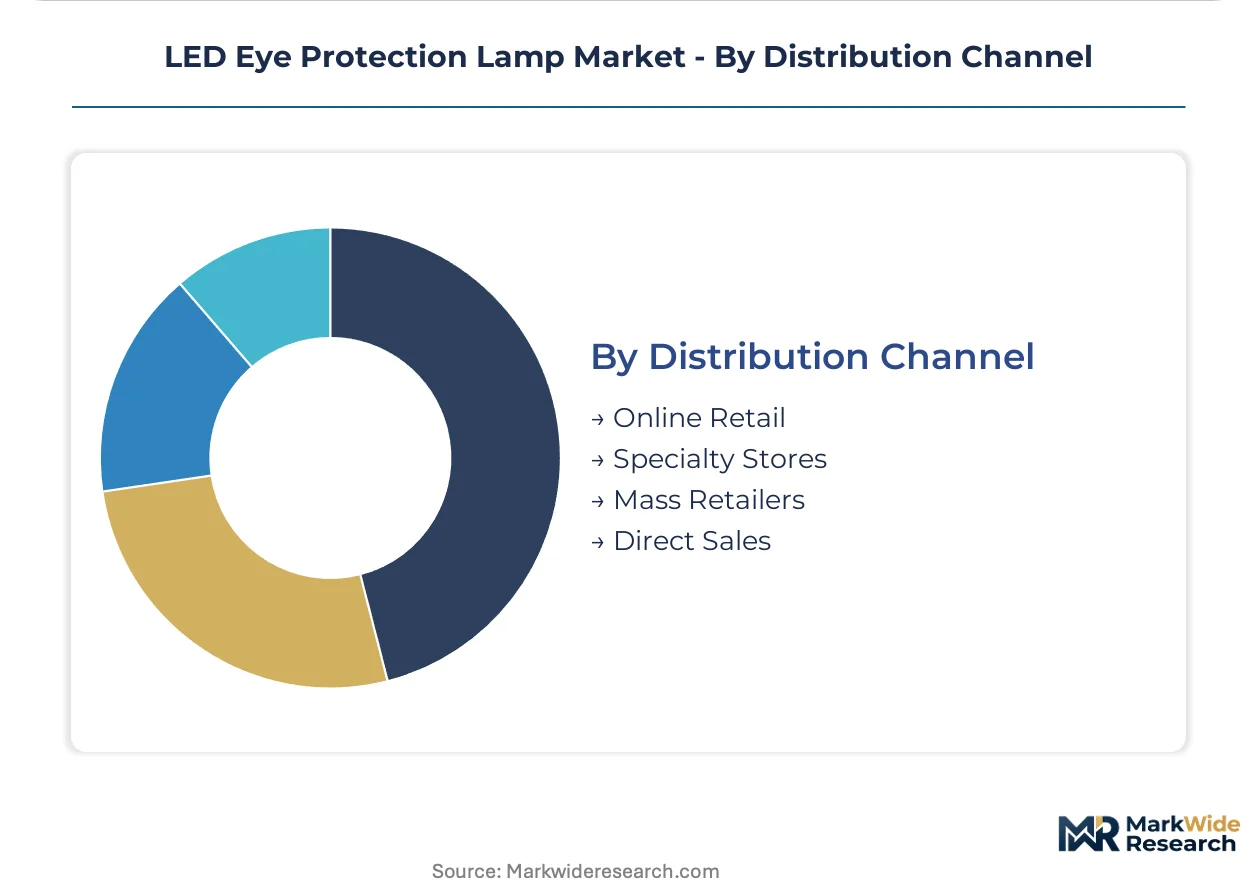
Distribution Channel:
Volume concentration and margin extraction split across platform economics, with certification visibility algorithms displacing price-sorting in digital channels.
- Online Retail:Domestic e-commerce platforms surface GB/T 9473 grades in search rankings. Xiaomi and similar direct-to-consumer brands leverage manufacturing scale without specialty retail markup.
- Specialty Stores:Photometric demonstration environments in tier-one cities allow side-by-side flicker and uniformity testing. European distributors filter uncertified imports through in-house photobiological safety verification.
- Mass Retailers:Big-box channels in India's tier-two cities stock ISI-marked products ahead of multinational localization.
- Direct Sales:Specification-grade contracts for institutional retrofit projects bypass retail margin entirely.
Online retail commands household volume. Specialty stores anchor premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in LED eye protection lamps tilt heavily toward net-exporting manufacturing clusters in East Asia, while North American and European markets absorb finished goods through distributor networks that enforce divergent certification regimes. Trade volumes concentrate in corridors linking Chinese production bases to destination markets with strict photobiological safety standards.
China
Domestic demand from Shanghai and Beijing households drives premium-tier procurement as parental expenditure shifts toward GB/T 9473-certified fixtures. SAMR enforcement of illuminance uniformity mandates in 2024 forced manufacturers to upgrade optical testing infrastructure. The Yangtze River Delta manufacturing cluster around Hangzhou and Suzhou supplies both domestic e-commerce platforms and export orders bound for European specialty retailers.
United States
Knowledge-worker households in California and New York Metro sustain replacement cycles for home office task lighting with circadian programming features. FDA jurisdiction over photobiological safety claims intersects with FCC equipment authorization for smart-connected models. West Coast distributor networks filter imports through in-house IEC 62471 verification before channel placement.
Germany
Corporate procurement departments in Bavaria and North Rhine-Westphalia specify UGR below 19 for open-plan office retrofits under workplace safety regulations. ECHA REACH restrictions on nickel-containing alloys extend supplier qualification timelines for adjustable-arm fixtures. The Baden-Württemberg industrial corridor hosts specification-grade lighting distributors that anchor premium positioning across Central European markets.
Japan
METI-supervised school districts in Kanto and Kansai specify melanopic ratio compliance for classroom retrofit programs above raw luminous efficacy benchmarks. JIS standards for LED luminaires create certification friction for imported products without local testing partnerships. Tokyo-based specialty retailers demonstrate flicker-free performance through side-by-side photometric testing environments.
India
BIS ISI mark requirements filter uncertified imports from domestic retail channels in Maharashtra and Karnataka. Tier-two city penetration lags as multinational brands complete localization timelines. The Delhi-NCR corridor concentrates distributor warehousing for northern Indian markets ahead of anticipated classroom retrofit program announcements.
LED Eye Protection Lamp Market Competitive Landscape
Listed leaders compete with private specialists across certification infrastructure and channel control dimensions, producing a tiered structure where scale-driven platforms coexist with design-forward premium houses. Vertical integration into LED chip sourcing separates cost-optimized volume producers from specification-grade competitors dependent on qualified supplier networks. Two dominant archetypes emerge: direct-to-consumer manufacturing platforms leveraging captive assembly capacity, and heritage lighting houses with in-house photobiological safety testing infrastructure. Competitive moves concentrate on M&A to secure distribution reach and strategic partnerships to fast-track regulatory clearance in fragmented national markets.
Among heritage lighting houses with testing infrastructure, Signify anchors the premium tier across European and Asian markets through photobiological safety certification capabilities. Xiaomi occupies a position at the scale-driven end, competing on manufacturing throughput and direct-to-consumer channel control without specialty retail markup. Dyson sits within the design-forward archetype, where thermal management engineering and adjustable arm mechanics command price premiums from longevity-focused purchasers.
| Leading Market Players |
|---|
| Philips Lighting (Signify) |
| BenQ Corporation |
| Dyson Ltd. |
| Lumie |
| Humanscale Corporation |
| Herman Miller, Inc. |
| OttLite Technologies, Inc. |
| Xiaomi Corporation |
| Osram |
| Others |
Pricing and Supply Chain Analysis
Long-term phosphor supply contracts anchor cost visibility for lamp manufacturers serving GB/T 9473-certified segments, locking in rare-earth access from Jiangxi and Fujian producers while buffering against gallium nitride wafer spot-market volatility. This contract structure concentrates procurement leverage among vertically integrated players with captive LED chip supply, squeezing mid-tier assemblers into price-taking positions.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with GB/T 9473 Grade AA certification and IEC 62471 risk group classification commanding 40-60% spreads over uncertified alternatives. Price differentiation hinges on photobiological safety testing infrastructure ownership and smart connectivity integration. Cost compression in the economy tier intensifies because Xiaomi and similar direct-to-consumer platforms bypass specialty retail markup. Educational procurement departments show lowest price sensitivity, prioritizing melanopic ratio compliance and uniformity metrics over per-unit cost.
Supply Chain Analysis
Just-in-time inventory preferences dominate among European and North American distributors qualifying Chinese-manufactured fixtures through in-house IEC 62471 verification, while strategic stockpiling of rare-earth phosphors concentrates among tier-one domestic brands anticipating SAMR enforcement tightening. Manufacturing draws from China, Taiwan, and South Korea for LED chips, with phosphor formulations resting on europium and terbium supply from Jiangxi province. Single-source vulnerability in gallium nitride epitaxy wafers creates structural risk as power semiconductor demand competes for substrate allocation. Distribution runs through e-commerce platforms for household volume and specialty lighting retailers for premium specification-grade placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as certification-driven procurement splits the market between health-optimized premium tiers and connected-lifestyle segments, creating niches for specialists with targeted testing infrastructure or software ecosystem integration.
For Market Incumbents: Shield premium positioning by deepening captive LED chip supply and expanding in-house IEC 62471 testing capacity before SAMR enforcement tightens further. Acquire regional distributors in Germany and Japan to anchor specification-grade channel control against emerging direct-to-consumer platforms. Certification investment represents the critical defensive lever as e-commerce algorithms surface blue-light risk classifications. For New Entrants and Emerging Players: Cloud-based circadian programming services represent an under-developed layer where incumbents under-serve healthcare and hospitality verticals seeking occupancy-sensing integration without full hardware replacement. India's tier-two cities offer the most penetrable geography ahead of multinational ISI mark completion. Pursue white-label partnerships with existing LED chip foundries to bypass capital-intensive vertical integration. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with SAMR-certified testing infrastructure and established supplier relationships in the Yangtze River Delta manufacturing cluster. Long-term viability favors assets with backward integration into phosphor formulation or gallium nitride chip sourcing. Watch for inflection when China's MEE accelerates carbon intensity benchmarks forcing requalification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Photobiological Safety Certification Investment | GB/T 9473 and IEC 62471 testing infrastructure anchors premium channel access against uncertified imports. |
| Backward Integration into LED Chip Supply | Captive gallium nitride sourcing buffers margin compression from power semiconductor demand competition. |
| Smart Lighting Platform Development | Millimeter-wave occupancy sensing and cloud circadian programming capture healthcare hospitality verticals. |
| Regional Distribution Acquisition | Specialty retailer networks in Germany and Japan filter imports through in-house verification before placement. |
| Phosphor Formulation Partnership | Rare-earth supply agreements with Jiangxi and Fujian producers lock in high-CRI formulations for educational procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SAMR certification databases, EU Ecodesign regulatory filings, and trade flow records from Chinese customs authorities. Primary interviews engaged optical engineering directors at lamp manufacturers, procurement managers at educational institutions in Shanghai and Shenzhen, and specialty lighting distributors in Germany and Japan. Secondary validation drew from GB standards documentation, IEC technical committee publications, and LED chip supplier disclosures. Bottom-up unit economics triangulated against top-down market sizing across desk, floor, and architectural fixture categories.
Segmentation dimensions modeled include fixture form factor, technology tier, end-use environment, and distribution channel across the projection horizon. CAGRs were derived from install-base replacement cycles, classroom retrofit program announcements, and household penetration curves for circadian-programmable products. Forecast inputs incorporated phosphor cost trajectories, gallium nitride wafer supply forecasts, and certification timeline assumptions for India BIS and EU REACH compliance.
Forecasts assume regulatory continuity in China's SAMR enforcement, EU Ecodesign standby power limits, and Japan METI melanopic ratio specifications; material policy shifts would require re-modeling. Revision becomes warranted when gallium nitride substrate allocation to lighting applications falls below threshold levels or when e-commerce platform algorithms materially alter certification visibility rankings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Ambient Lighting Market
Lighting
LED Solar Lighting Market
Lighting
Graphene Lighting Market
Lighting
Smart Lights Market
Lighting
Display Light Control Film Market
Lighting
Smart Lamp Market
Lighting
Xenon Lights Market
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Dimmer and Color Tunable Market
Lighting
Hazardous Lighting Market
Lighting
Lamps and Lighting Market
Lighting
High Bay Lighting Market
Lighting
Fluorescent Lighting Market
Lighting
North America Outdoor Lighting Market
Lighting
Architectural Lighting Market
Lighting
Global Headlight Control Module Market