
 Cleanroom Lighting Market | 2026-2036
Cleanroom Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Cleanroom Lighting Market Analysis
Modular fixture architecture is decoupling housing, driver, and optical components into separately specifiable subsystems, letting buyers mix IP ratings, lumen packages, and control protocols without replacing entire units. Signify Holding leverages its Lumileds heritage to dominate high-efficacy LED engine supply for ISO-classified environments. Wipro Lighting anchors South Asian project demand through localized manufacturing and BIS certification depth. Kenall Manufacturing specializes in sealed gasketed housings that sustain washdown cycles in biopharma suites.
Cleanroom lighting denotes sealed luminaire assemblies engineered to prevent particulate shedding, maintain specified lux levels, and withstand aggressive sanitization protocols in controlled environments; typical specifications include IP65+ ingress protection, smooth non-porous surfaces, and CRI exceeding 85 for inspection accuracy. LED product type now leads value contribution due to mercury-free compliance and dimming compatibility with building automation systems. Semiconductor manufacturing application represents the fastest-growing demand pool as wafer fabs multiply in Taiwan, South Korea, and the United States. Surface mounted installation type occupies the largest share in retrofit contexts where suspended hardware risks particle generation.
FDA cGMP guidelines and the EU MDR impose particulate-count and material-traceability requirements that directly shape luminaire material selection and validation documentation. ISO 14644 cleanroom classification standards govern minimum illumination levels and fixture surface finishes across pharmaceutical and electronics facilities worldwide. REACH and RoHS restrictions on hazardous substances are forcing fluorescent-to-LED conversions in European installations. Stakeholders must monitor evolving energy-efficiency thresholds in building codes and the pace of F-Gas Regulation enforcement to time portfolio transitions and geographic prioritization decisions.
Market Dynamics
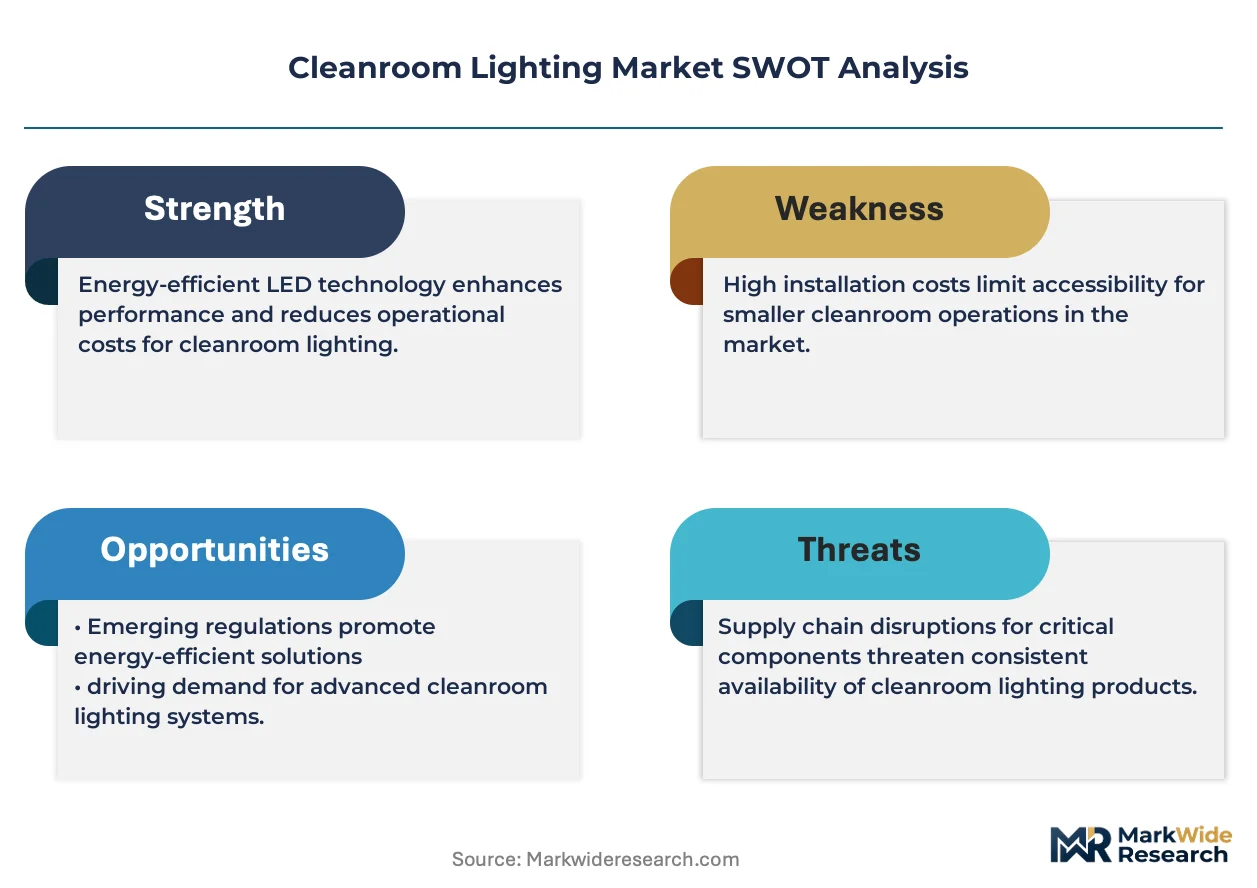
Modular fixture architecture is fragmenting the cleanroom lighting supply chain by decoupling housings, LED engines, and drivers into separately specifiable subsystems, forcing incumbent integrated manufacturers to defend their positions against component specialists.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbons and mercury-containing fluorescent luminaires is compelling pharmaceutical plants across Germany and France to accelerate LED retrofit timelines.
- Semiconductor fabrication:Wafer fabs in Taiwan and South Korea are scaling ISO 5-classified cleanroom construction, creating concentrated demand for sealed gasketed fixtures with washdown compatibility.
- LED efficacy thresholds:Advances in chip-on-board thermal management are extending luminaire lifespans beyond 100,000 hours in continuous-operation biopharma suites.
Market Restraints
- Driver component concentration:Specialty-grade constant-current drivers for cleanroom applications rely on a narrow supplier base concentrated in East Asian electronics corridors.
- Validation documentation burden:FDA cGMP and EU MDR traceability requirements impose multi-month qualification timelines for new fixture introductions in sterile manufacturing environments.
- Aluminum housing cost volatility:Extruded aluminum enclosures face input price swings that compress margin predictability for fixture assemblers serving project-driven markets.
Strategic Opportunities
- United States CHIPS Act incentives:Domestic semiconductor fabrication subsidies are triggering cleanroom construction across Arizona, Texas, and Ohio, opening new geographic demand pools.
- Human-centric lighting convergence:Tunable white LED systems paired with circadian rhythm controls are penetrating biopharma R&D facilities seeking enhanced operator alertness.
- Wireless control integration:Bluetooth mesh and DALI-2 protocols are enabling fixture-level energy monitoring without conduit penetration in sealed ceiling assemblies.
Industry Challenges
- Cleanroom certification timeline:ISO 14644-1 particulate validation for new fixture designs requires extended third-party testing cycles that delay revenue recognition.
- Legacy fluorescent infrastructure:Existing T8 and T5 ballast circuits in mature pharmaceutical plants complicate LED retrofit electrical integration without full ceiling replacement.
- Specialized installation labor scarcity:Technicians trained in sealed-gasket assembly and cleanroom protocol compliance command premium wages that inflate project delivery costs.
Report Scope
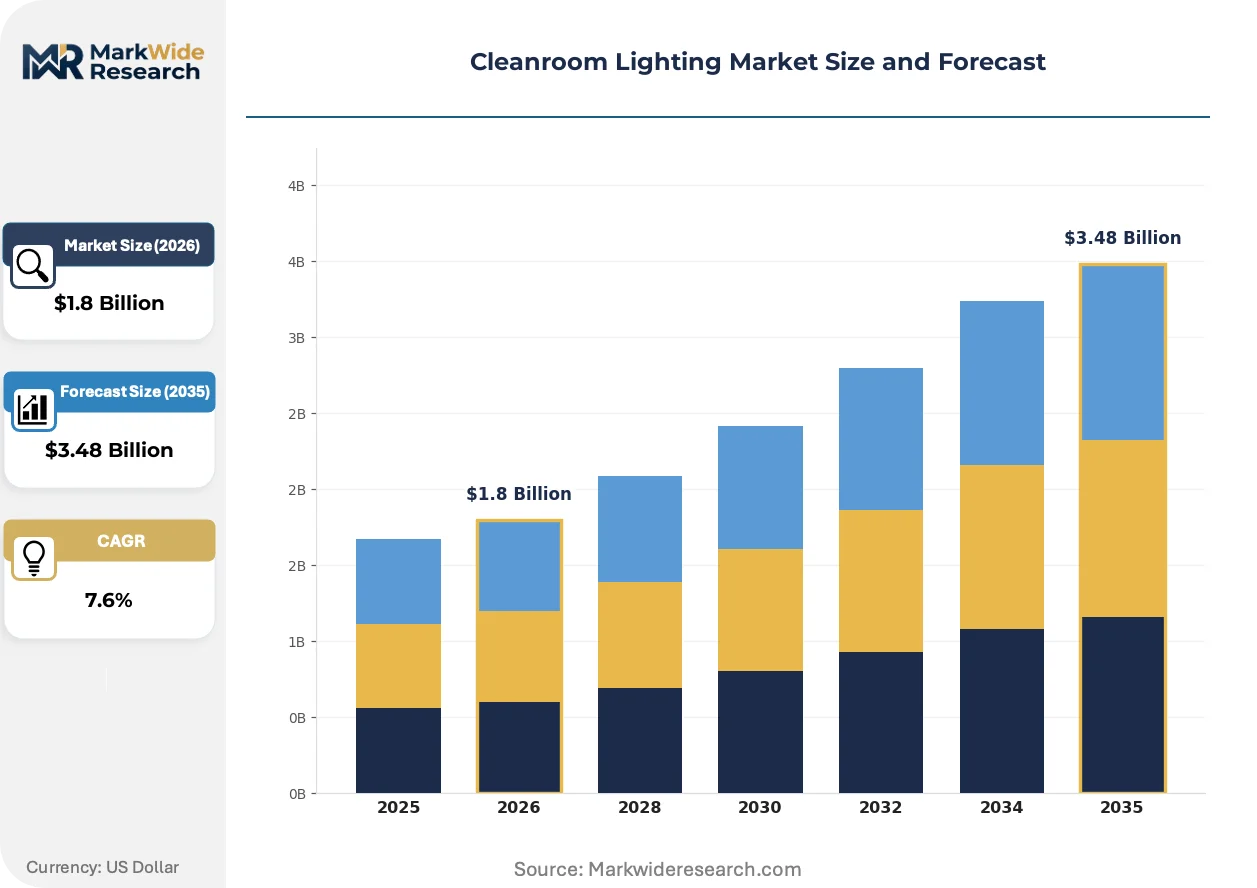
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cleanroom Lighting Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, Incandescent, High-Intensity Discharge Application: Pharmaceuticals, Biotechnology, Semiconductor Manufacturing, Aerospace End User: Hospitals, Research Laboratories, Electronics Facilities, Manufacturing Plants Installation Type: Suspended, Recessed, Surface Mounted, Portable |
| Companies Covered | Signify Holding, Wipro Lighting, Crompton Greaves Consumer Electricals Limited, Acuity Brands, Kenall Manufacturing, Eaton Corporation, Terra Universal, LUG Light Factory, Zumtobel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cleanroom Lighting Market Emerging Trajectories
Cleanroom lighting is undergoing rapid technical diversification as solid-state sources, smart controls, and modular architectures converge to displace legacy fluorescent systems across regulated manufacturing environments.
Chip-on-board LED arrays with integrated thermal vias are electrifying fixture design by eliminating discrete package shadows and enabling higher lumen density in compact sealed housings. Biopharma suite operators in Switzerland and Singapore are specifying these engines for color-critical inspection tasks. The technology is compressing optical component counts while raising minimum efficacy thresholds for competitive positioning.
REACH substance restrictions and RoHS hazardous material limits are forcing material substitutions in European pharmaceutical installations. Luminaire manufacturers must now validate alternative phosphor formulations and solder alloys to maintain CE marking compliance. German and French cleanroom contractors are prioritizing suppliers with pre-documented material traceability to accelerate project handover.
Specification authority is migrating from electrical contractors to facility qualification teams armed with particulate-count validation protocols. Turnkey project procurement in Taiwanese semiconductor corridors now bundles lighting with HVAC and filtration under single-source cleanroom envelope contracts. This consolidation is marginalizing standalone fixture distributors in high-specification electronics manufacturing clusters.
Cleanroom Lighting Market Segmentation
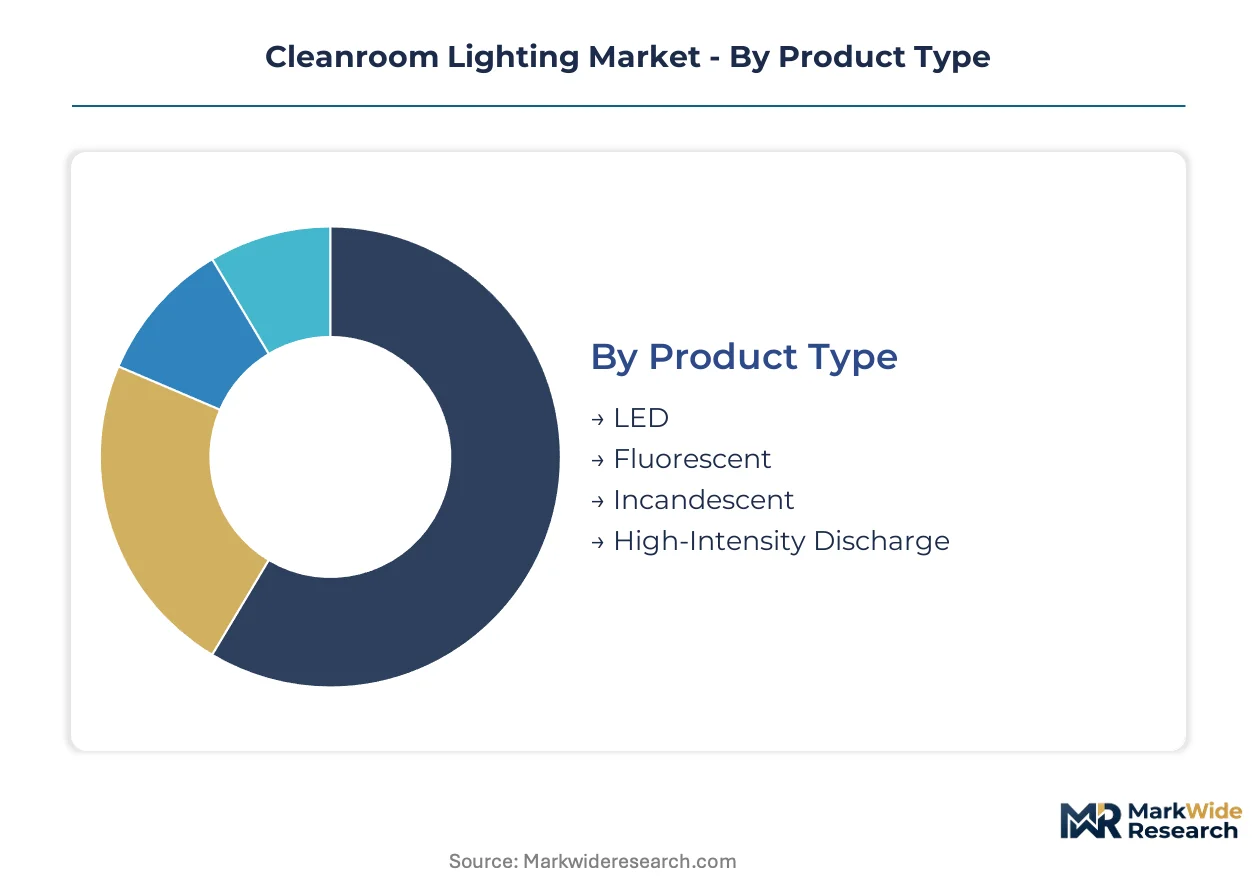
Cleanroom lighting procurement follows distinct technical and operational logics across product generations, facility types, and mounting configurations. Segment boundaries matter because upgrade cycles, regulatory compliance timelines, and installation constraints vary sharply across these dimensions.
Product Type:
Replacement-cycle timing diverges sharply across source technologies, with mercury-phaseout regulations compressing fluorescent retrofit windows while LED platforms extend service intervals.
- LED:Solid-state assemblies with chip-on-board thermal architecture deliver efficacy above 150 lm/W and lifespans exceeding 100,000 hours in continuous semiconductor fab operations. Taiwan wafer fabs are specifying these for ISO 5 cleanrooms to eliminate particulate-shedding fluorescent failures. Demand concentrates most acutely where REACH and RoHS restrictions have already banned mercury-containing alternatives.
- Fluorescent:T5 and T8 tube systems with electronic ballasts retain installed base in mature pharmaceutical plants but face accelerated phase-out under EU F-Gas Regulation timelines. German cleanroom contractors now treat these as legacy maintenance categories rather than new specification targets.
- Incandescent:Tungsten-filament sources survive in niche color-matching applications requiring near-perfect CRI but constitute minimal new procurement volume.
- High-Intensity Discharge:Metal halide and sodium vapor systems serve high-bay aerospace assembly environments where lumen density requirements exceed LED economics at extreme mounting heights.
LED sits at the top of the volume ranking, with fluorescent retrofit demand climbing the fastest as regulatory deadlines approach.
Application:
Facility-level contamination protocols and inspection precision requirements create tiered performance thresholds that segment procurement budgets and certification burdens.
- Semiconductor Manufacturing:Wafer fabs in South Korea and the United States demand ISO 14644-1 Class 5-7 environments with sealed gasketed fixtures sustaining repeated washdown cycles. CHIPS Act subsidies are triggering construction surges across Arizona and Texas.
- Pharmaceuticals:Sterile fill-finish suites and API production lines require FDA cGMP-validated luminaires with documented material traceability and smooth non-porous surfaces.
- Biotechnology:Cell culture and gene therapy facilities specify tunable white systems for circadian rhythm management in R&D operator environments.
- Aerospace:Satellite assembly cleanrooms prioritize portable and surface-mounted options where overhead suspension risks particulate generation from hardware vibration.
Semiconductor manufacturing commands the steepest expansion trajectory, while pharmaceuticals retains the largest installed base requiring systematic LED conversion.
End User:
Operational intensity and contamination sensitivity differentiate procurement authority across facility types, with some end users bundling lighting into envelope contracts and others retaining standalone specification control.
- Electronics Facilities:Memory and logic chip foundries in Hsinchu and Pyeongtaek are driving demand for modular fixture architectures that decouple housings from LED engines.
- Manufacturing Plants:Multi-product pharmaceutical sites face complex legacy fluorescent infrastructure that complicates electrical integration without full ceiling replacement.
- Research Laboratories:Biopharma R&D suites specify human-centric lighting with Bluetooth mesh controls for fixture-level energy monitoring.
- Hospitals:Sterile processing departments and compounding pharmacies require IP65+ ingress protection and CRI exceeding 85 for inspection accuracy.
Electronics facilities anchor current volume, with research laboratories expanding most quickly as gene therapy development scales.
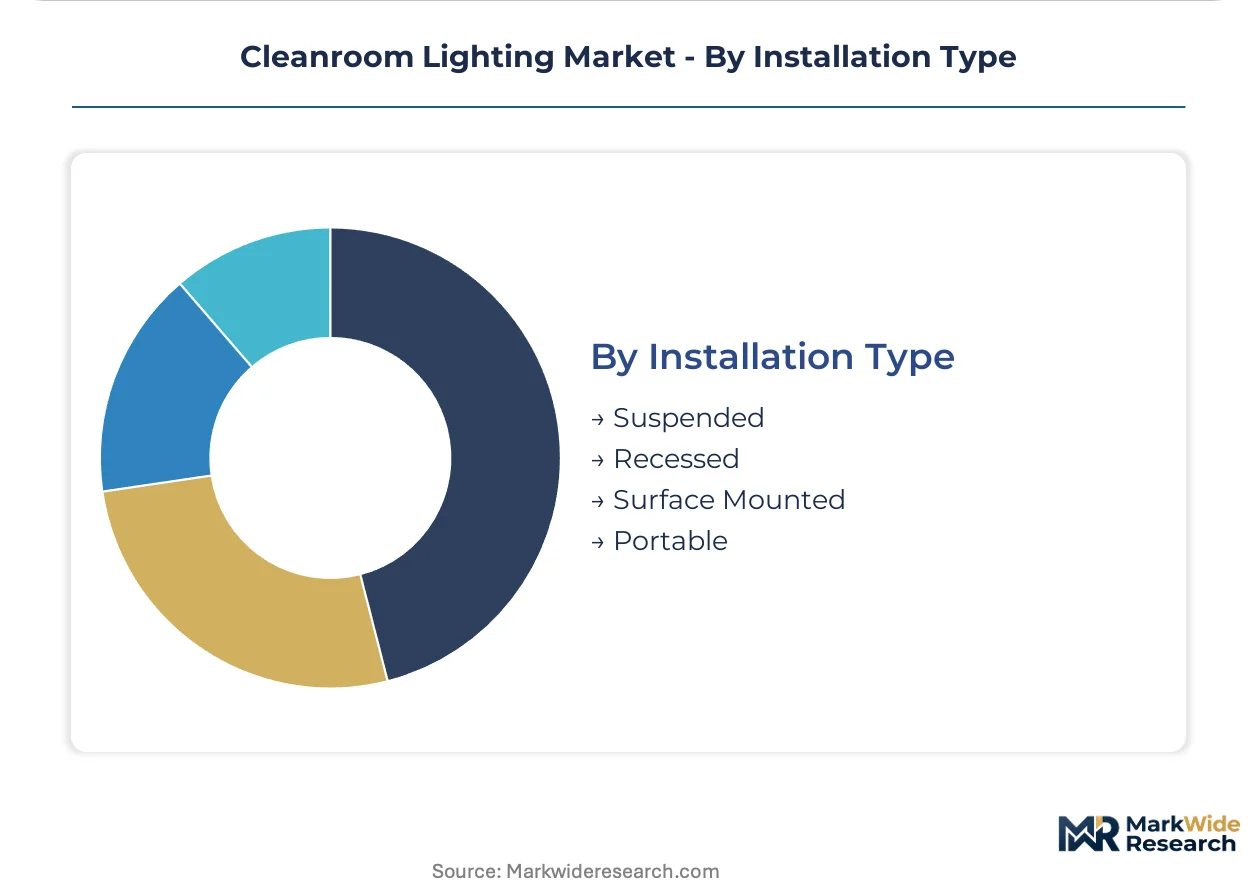
Installation Type:
Mounting geometry directly impacts particulate generation risk and maintenance accessibility, with retrofit contexts favoring options that minimize ceiling penetration.
- Surface Mounted:Direct-ceiling attachment eliminates suspension hardware that can shed particles through vibration or corrosion, dominating pharmaceutical retrofit specifications.
- Recessed:T-bar integration with sealed gaskets preserves cleanroom envelope integrity in new semiconductor construction where ceiling grids are purpose-built.
- Suspended:Cable or rod mounting serves high-bay aerospace applications where ceiling heights exceed 8 meters and localized task illumination is required.
- Portable:Mobile units with battery backup support temporary cleanroom configurations and validation testing where permanent installation is impractical.
Surface mounted leads by volume, with recessed systems gaining share fastest in greenfield semiconductor fab construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cleanroom lighting industry traces its commercial origins to post-war pharmaceutical manufacturing corridors in Switzerland and Germany, where sterile production protocols first demanded sealed, washable luminaire architectures that would later define global standards.
United States
CHIPS Act subsidies are accelerating wafer fab construction across Arizona, Texas, and Ohio, each requiring ISO 5-classified cleanroom envelopes with sealed gasketed fixtures. FDA cGMP guidelines impose material-traceability requirements that extend fixture qualification timelines. The Phoenix-Tucson corridor hosts multiple greenfield semiconductor facilities specifying recessed LED assemblies with washdown compatibility.
Germany
EU F-Gas Regulation enforcement is compelling pharmaceutical plants in Baden-Württemberg and Bavaria to complete fluorescent-to-LED retrofits before statutory deadlines. REACH substance restrictions drive material substitution validation for phosphor formulations and solder alloys. The Rhine-Main biopharma cluster demands documented compliance packages that prioritize suppliers with pre-certified material traceability.
South Korea
Memory and logic chip foundries in Pyeongtaek and Yongin are scaling ISO 5 cleanroom construction with modular fixture architectures that decouple housings from LED engines. MFDS pharmaceutical manufacturing guidelines align with FDA standards for sterile suite illumination. The Seoul Capital Area concentrates demand for high-efficacy chip-on-board thermal management systems.
Taiwan
Semiconductor fabrication facilities in Hsinchu Science Park and Tainan Science Park are deploying sealed lighting assemblies for sub-ISO 5 environments where particulate shedding risks wafer contamination. Turnkey procurement now bundles lighting with HVAC under single-source cleanroom envelope contracts. The island's electronics corridors represent the densest concentration of specialized sealed fixture demand globally.
Switzerland
Swissmedic regulations for sterile pharmaceutical manufacturing drive specification authority toward facility qualification teams armed with particulate-count validation protocols. Biopharma suite operators in Basel and Geneva are specifying tunable white LED systems for circadian rhythm management in R&D environments. The country's precision manufacturing heritage supports premium-tier fixture sourcing for color-critical inspection tasks.
Cleanroom Lighting Market Vendor Landscape
The competitive structure tilts toward integrated lighting conglomerates with heritage LED engine capabilities and specialized cleanroom fixture manufacturers with deep regulatory documentation expertise. Tiered positioning separates premium suppliers with pre-validated material traceability from mid-market assemblers serving retrofit-driven pharmaceutical accounts. Three archetypes dominate: diversified electrical giants leveraging luminaire scale, regional specialists anchoring geographic certification requirements, and component-agnostic modular system integrators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players position for CHIPS Act-driven construction cycles.
Among diversified electrical conglomerates, Signify Holding and Eaton Corporation exemplify scale-driven archetypes with heritage capabilities in solid-state lighting engines. Wipro Lighting occupies a position within the regional specialist tier, leveraging localized manufacturing depth and BIS certification to anchor South Asian project demand. Kenall Manufacturing represents the specialized fixture archetype, with sealed gasketed housing expertise aligned to biopharma washdown requirements.
| Leading Market Players |
|---|
| Signify Holding |
| Wipro Lighting |
| Crompton Greaves Consumer Electricals Limited |
| Acuity Brands |
| Kenall Manufacturing |
| Eaton Corporation |
| Terra Universal |
| LUG Light Factory |
| Zumtobel Group |
| Others |
Supply Flow & Price Mechanics
Chip-on-board LED thermal management advances are compressing component counts while concentrating production among East Asian electronics corridors, simultaneously lowering unit economics and tightening supply control among specialized foundries serving ISO-classified environments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA cGMP-validated fixtures with full material traceability from CE-marked commercial-grade units and uncertified retrofit alternatives. Price differentiation hinges on certification grade and volume scale, with pharmaceutical qualification packages commanding substantial premiums over semiconductor fab specifications. Cost compression in the economy tier is intensifying because aluminum housing input volatility squeezes assembler margins. Contract research laboratories exhibit the highest price sensitivity, while sterile fill-finish operators prioritize compliance over unit cost.
Supply Chain Analysis
Specialized installation labor scarcity in Taiwan, South Korea, and Germany is inflating project delivery costs and extending lead times for sealed-gasket assembly work. Constant-current driver production draws from a narrow supplier base concentrated in East Asian electronics corridors, while extruded aluminum enclosures and chip-on-board LED engines feed from Taiwanese and South Korean foundries. Single-source vulnerability in specialty-grade driver components threatens fixture availability during demand surges. Distribution runs through turnkey cleanroom envelope contractors in semiconductor corridors and electrical distributors in pharmaceutical retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between EU F-Gas enforcement timelines and US CHIPS Act construction cycles creates geographic-arbitrage opportunities, with European retrofit urgency offering faster payback periods than greenfield American fab projects.
For Market Incumbents: To counter modular fixture specialists decoupling housings from LED engines, integrated manufacturers should deepen backward integration into chip-on-board thermal management and expand captive driver production capacity in Taiwan. Certification investment in pre-validated FDA cGMP documentation packages accelerates pharmaceutical qualification timelines and defends premium positioning against component-agnostic assemblers. For New Entrants and Emerging Players: Enter via human-centric lighting convergence in Swiss and Singaporean biopharma R&D facilities, where circadian rhythm controls remain underpenetrated relative to semiconductor fab demand. Wireless control integration using Bluetooth mesh protocols offers the most penetrable technical wedge, as incumbent fixture portfolios lag in fixture-level energy monitoring capabilities. Channel partnerships with HVAC contractors bundling cleanroom envelope contracts provide faster access than standalone electrical distribution. For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with BIS certification depth but limited geographic footprint, as scale premiums concentrate among diversified conglomerates. The five-to-ten-year viability window favors acquisition targets with pre-established material traceability systems aligned to REACH and RoHS compliance. Watch for inflection signals in CHIPS Act facility commissioning timelines, which would trigger step-function demand for sealed gasketed fixtures in Arizona and Texas construction corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Engine Production | Captive chip-on-board thermal management supply secures margin control against component specialists in Taiwan. |
| Pre-Validated FDA cGMP Documentation Investment | Pre-certified material traceability accelerates sterile suite qualification timelines in German pharmaceutical plants. |
| Bluetooth Mesh Control Platform Launch | Fixture-level energy monitoring without ceiling penetration addresses biopharma R&D operator requirements in Basel. |
| Turnkey Cleanroom Envelope Partnership | HVAC contractor bundling in Hsinchu Science Park captures specification authority migrating from electrical distributors. |
| Geographic Capacity Expansion in Arizona | Localized assembly presence near CHIPS Act fab construction reduces logistics exposure to aluminum housing cost volatility. |
Methodological Framework
Coverage spans the United States, Germany, South Korea, Taiwan, and Switzerland, with primary inputs from each market combining structured interviews with cleanroom facility engineers, pharmaceutical qualification managers, semiconductor fab procurement leads, lighting manufacturer product directors, and turnkey HVAC contractors. Secondary validation draws from FDA cGMP guidance documents, EU F-Gas Regulation enforcement notices, ISO 14644-1 certification databases, SEC filings of diversified electrical conglomerates, and trade customs data for LED engine and aluminum enclosure imports. Bottom-up demand aggregation across facility construction pipelines and top-down supply-side capacity assessments were triangulated to establish market sizing.
Segmentation modeling proceeded at product type, application, end user, and installation type granularity, with additional dimensioning by cleanroom classification tier and regional regulatory cluster. CAGRs were derived from regression analysis of historical facility construction permits against luminaire specification rates, incorporating semiconductor fab capital expenditure cycles and pharmaceutical retrofit regulatory deadlines as exogenous variables. Chip-on-board thermal management adoption curves and REACH substance restriction phase-in timelines served as industry-specific forecast inputs across the projection horizon.
Inputs from regulatory filing databases and facility construction permit registries were available through the study window; gaps in real-time procurement data from private pharmaceutical operators introduce uncertainty bands around retrofit demand timing. Forecasts reflect assumptions regarding F-Gas enforcement consistency and CHIPS Act subsidy disbursement velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
High-End Lighting Market
Lighting
Human Centric Lighting Market
Lighting
Portable Lamps Market
Lighting
Asia-Pacific Hazardous Lighting Market
Lighting
Digital Light Processing Technology Market
Lighting
Saudi Arabia Smart Lighting Market
Lighting
COB Photo Light Market
Lighting
UV Lamps Market
Lighting
Smart Lamp Market
Lighting
North America Street Lighting Market
Lighting
Lighting As a Service (Laas) Market
Lighting
Explosion Proof Lighting Market
Lighting
Eye-Illuminating Gadgets Market
Lighting
Street Lighting Market
Lighting
Photocell Market
Lighting
Studio Lighting Equipment Market