
 Africa Algae Protein Market | 2026-2036
Africa Algae Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Algae Protein Market Outlook
South Africa's expanding spirulina cultivation infrastructure is reshaping supply availability for the continent. Cyanotech Corporation leverages its microalgae technology leadership to serve African nutraceutical distributors. DSM sustains R&D intensity in chlorella-derived protein isolates for regional food manufacturers. Live Spirulina SA anchors domestic production with controlled-environment farms near Cape Town.
Africa algae protein comprises dried and processed biomass from cyanobacteria and eukaryotic microalgae, typically containing 50-70% crude protein by dry weight with complete essential amino acid profiles; manufacturers cultivate strains in open ponds or photobioreactors before spray-drying or solvent extraction for food-grade concentrates. Spirulina dominates current volume due to established cultivation protocols and lower production costs, while chlorella commands premium positioning in dietary supplements because of its higher chlorophyll content and perceived detoxification benefits. Powder form leads distribution through bulk ingredient channels, though tablet formulations gain traction in direct-to-consumer nutraceutical segments across urban African markets.
Kenya's Bureau of Standards and South Africa's Department of Health enforce algae protein safety thresholds that determine import eligibility and domestic manufacturing licenses. The African Union's continental free trade protocols reduce cross-border tariff barriers for processed algae ingredients between member states. Stakeholders must monitor evolving national food additive classifications that could reclassify algae extracts from novel food status to established ingredient categories, altering registration requirements and speed-to-market timelines.
Market Dynamics
Algae protein supply in Africa is concentrating around controlled-environment cultivation facilities that reduce contamination risk and stabilize output quality for food-grade certification. This infrastructure shift is redrawing competitive boundaries between open-pond operators and photobioreactor-based producers.
Growth Catalysts
- Kenya's algae-specific quality guidelines:The Bureau of Standards streamlined import certification timelines, reducing clearance delays for spirulina biomass entering Mombasa port.
- Functional foods sector expansion:Nigerian domestic brands are formulating algae protein into baked goods and beverages as cost-competitive alternatives to imported soy isolates.
- Photobioreactor automation:Closed-system cultivation is digitizing quality control protocols, enabling real-time monitoring of pH and nutrient density that open ponds cannot match.
Market Restraints
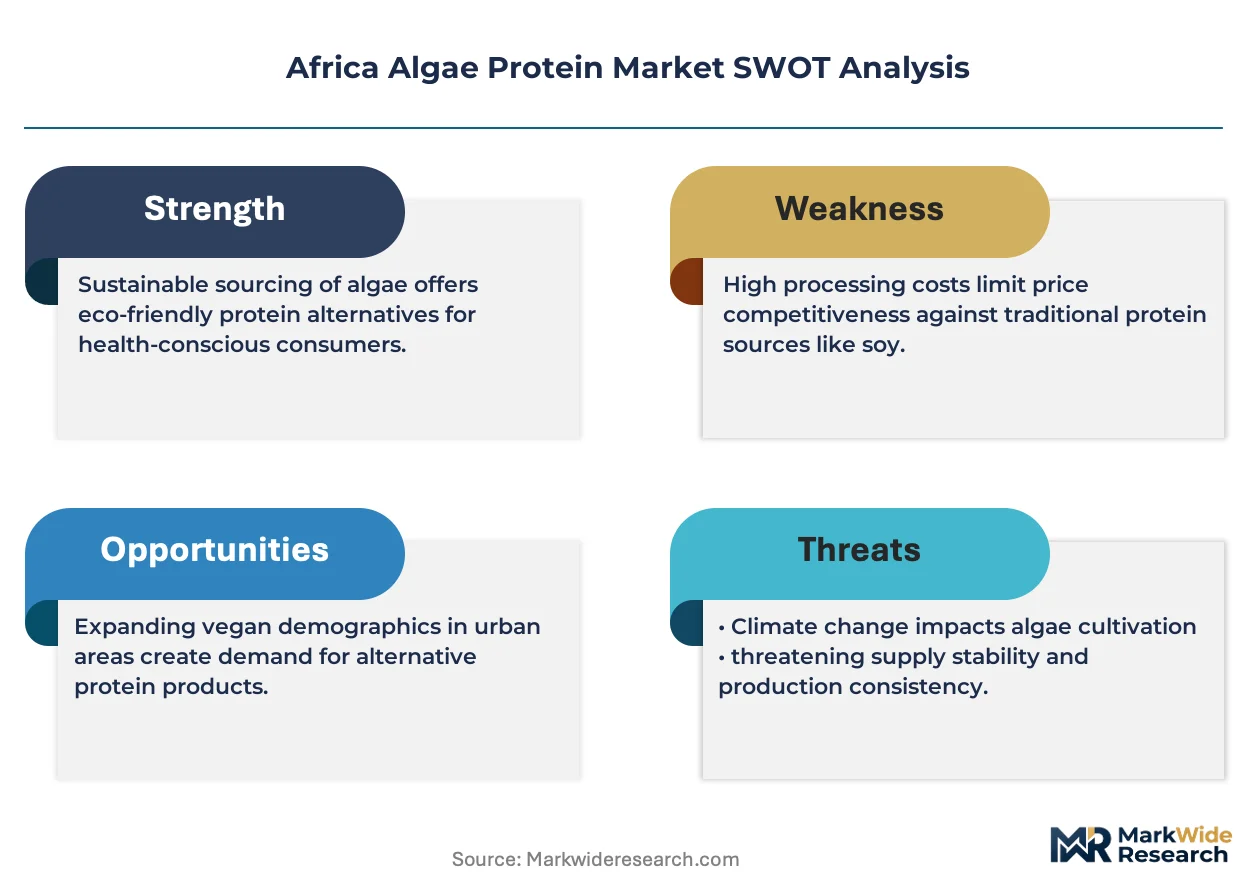
- Energy cost volatility:Grid instability across South Africa and Nigeria forces producers to rely on diesel generators, inflating per-kilogram drying costs by unpredictable margins.
- Single-source supply risk:Spirulina strain banking concentrates in Cape Town biorepositories, creating genetic uniformity vulnerability if contamination events occur.
- Soy protein substitution:Established oilseed crushing infrastructure in Egypt and Morocco supplies cheaper commodity isolates that undercut algae on price-per-protein-unit.
Strategic Opportunities
- East African Community integration:Tanzania and Uganda offer underexploited high-altitude cultivation zones with natural temperature moderation for chlorella production.
- Direct-to-consumer tablet channels:Urban pharmacies and wellness retailers in Lagos and Nairobi are bypassing bulk ingredient distributors to capture margin from finished nutraceuticals.
- African Union free trade protocols:Reduced cross-border tariffs between member states enable regional hub-and-spoke distribution models centered on South African processing capacity.
Industry Challenges
- Phycologist talent scarcity:Universities in Ghana and Senegal graduate fewer than twenty specialized algae cultivation technicians annually, constraining facility expansion timelines.
- Food additive reclassification risk:National regulators may shift algae extracts from novel food status to established ingredient categories, forcing costly re-registration of existing product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Algae Protein Market |
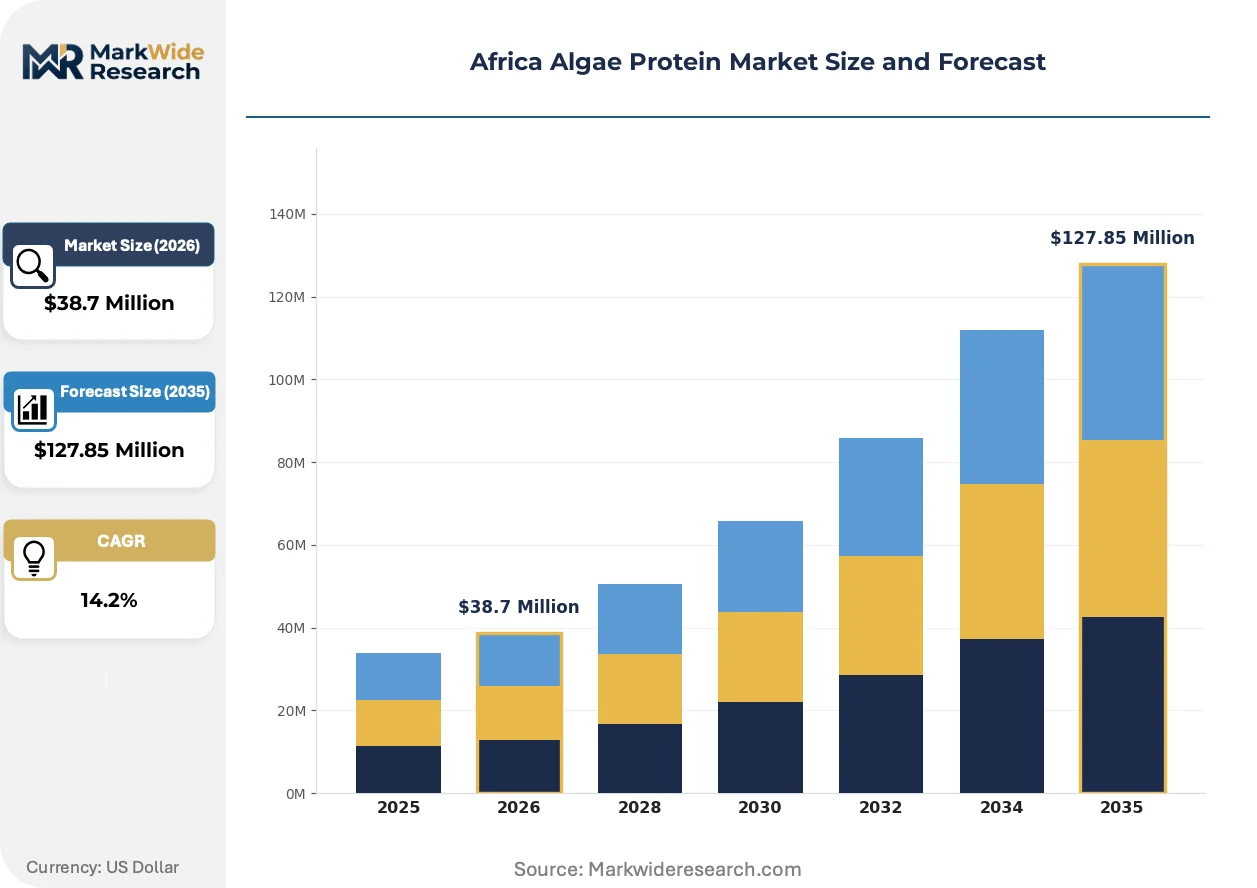
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $127.85 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spirulina, Chlorella, Seaweed, Kelp End User: Food & Beverage, Nutraceuticals, Animal Feed, Cosmetics Form: Powder, Liquid, Extract, Tablet Application: Dietary Supplements, Functional Foods, Beauty Products, Animal Nutrition |
| Companies Covered | Corbion N.V., BASF SE, Cyanotech Corporation, DSM, DuPont, Cargill, Incorporated, Live Spirulina SA, Soaring Free Superfoods, Biodelta Neutraceuticals, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Algae Protein Market Strategic Shifts
Automation and regulatory harmonization are compressing production timelines while reshaping how algae protein reaches African consumers. Three developments warrant particular attention.
Photobioreactor control systems are digitizing cultivation monitoring across South African facilities. DSM and regional equipment suppliers are installing sensor arrays that track dissolved oxygen and CO2 uptake in real time. This precision is reducing batch failure rates and enabling predictive harvest scheduling that open-pond operators cannot replicate.
Kenya's Bureau of Standards introduced algae-specific quality guidelines that streamline import certification for food-grade biomass. The framework establishes maximum heavy metal thresholds and microbiological limits that determine eligibility for domestic manufacturing licenses. South African exporters are accelerating documentation alignment to maintain preferential access to East African markets.
Urban African consumers are gravitating toward tablet-form nutraceuticals over bulk powders, compressing the traditional ingredient-distributor channel. Direct procurement from controlled-environment farms near Cape Town allows Lagos and Nairobi wellness retailers to bypass intermediaries. This disintermediation is fragmenting buyer power and rewarding producers with finished-product capabilities.
Africa Algae Protein Market Segmentation
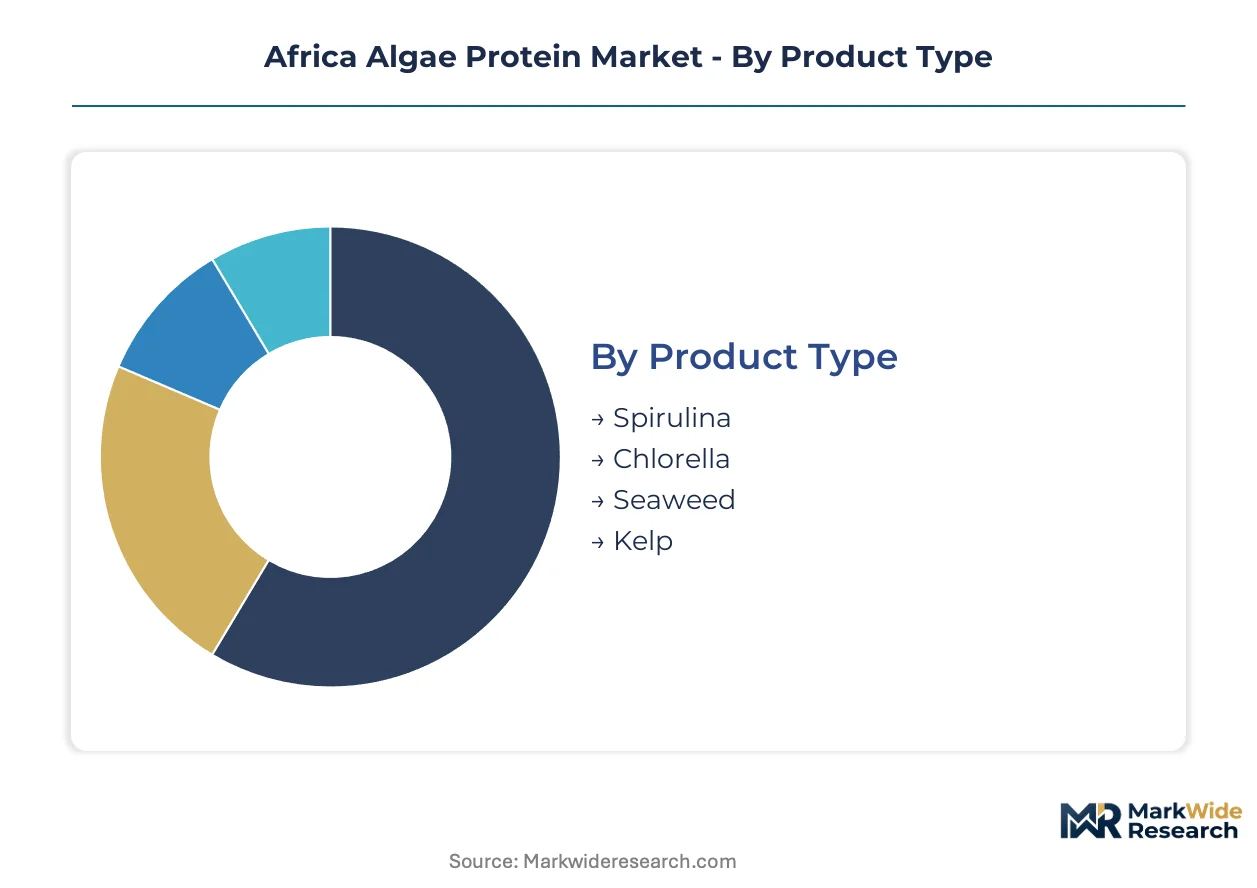
Algae protein segmentation in Africa reflects divergent maturity levels across strain technologies and downstream processing capabilities. Product type and form distinctions determine which producers capture food-grade certification versus commodity feed margins.
Product Type:
Mature cultivation protocols separate established biomass categories from emerging strain development across African facilities.
- Spirulina:Cyanobacteria biomass containing 60-70% crude protein with established open-pond cultivation protocols across South African and Kenyan facilities. Nigerian functional food manufacturers source spirulina concentrates as cost-competitive alternatives to imported soy isolates for baked goods and beverage formulations.
- Chlorella:Eukaryotic microalgae with higher chlorophyll content and thicker cell walls requiring mechanical processing for bioavailability. South African nutraceutical distributors pay premium positioning for chlorella in detoxification supplements, though photobioreactor production costs limit volume expansion.
- Seaweed:Macroalgae protein concentrates harvested from coastal cultivation zones with lower protein density but established supply chains.
- Kelp:Brown macroalgae species processed for hydrocolloid and protein co-products in limited East African pilot operations.
Spirulina handles the majority of throughput; chlorella is expanding most quickly on share.
End User:
Customer concentration varies by margin structure and regulatory compliance burden across African markets.
- Food & Beverage:Formulators integrating algae protein into baked goods, pasta, and dairy alternatives. Kenyan Bureau of Standards guidelines streamline import certification for food-grade spirulina entering Mombasa port.
- Nutraceuticals:Dietary supplement manufacturers requiring heavy metal testing and microbiological certification. Lagos and Nairobi wellness retailers bypass bulk distributors through direct procurement from Cape Town controlled-environment farms.
- Animal Feed:Compound feed producers seeking protein alternatives to oilseed meals.
- Cosmetics:Skincare formulators leveraging algae bioactive compounds for topical applications.
Food & Beverage commands the largest volume commitment; Nutraceuticals shows the steepest margin expansion.
Form:
Processing intensity determines which producers capture finished-product premiums versus commodity ingredient margins.
- Powder:Spray-dried biomass distributed through bulk ingredient channels with 50-70% protein concentration. South African facilities near Cape Town anchor regional supply for export to East African Community markets under reduced tariff protocols.
- Liquid:Suspension concentrates for beverage integration requiring cold-chain logistics.
- Extract:Solvent-processed protein isolates with enhanced digestibility profiles.
- Tablet:Compressed nutraceutical formats capturing direct-to-consumer margins in urban pharmacies. Nairobi and Lagos retailers fragment buyer power through disintermediation of traditional distributor channels.
Powder dominates cross-border trade volumes; Tablet formats are climbing the fastest in value contribution.
Application:
End-use specifications dictate cultivation system selection and certification pathways.
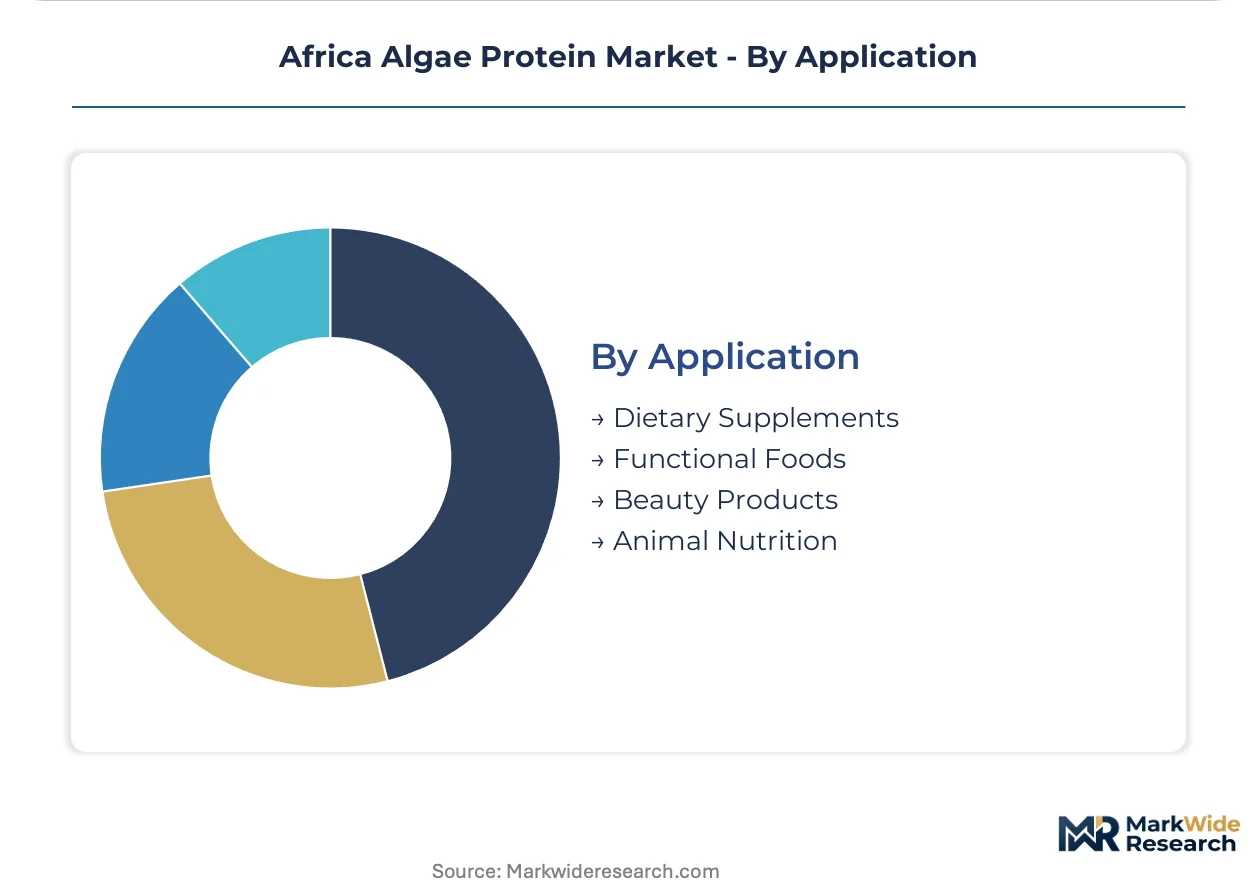
- Dietary Supplements:Tablet and capsule formulations requiring GMP-compliant processing. Photobioreactor automation enables real-time pH monitoring that satisfies South African Department of Health safety thresholds.
- Functional Foods:Protein fortification of traditional and processed foods. Nigerian domestic brands formulate algae into cost-competitive alternatives to imported isolates for mass-market distribution.
- Beauty Products:Topical formulations leveraging algae antioxidant properties.
- Animal Nutrition:Feed-grade biomass with relaxed contamination limits versus human food standards.
Dietary Supplements absorbs the bulk of premium biomass; Functional Foods is gaining share fastest through local brand adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across African markets. South African nutraceutical distributors favor tablet-form spirulina for pharmacy channels, while Nigerian food manufacturers prioritize bulk powder for baked goods fortification. East African Community members import processed biomass through Mombasa under streamlined certification frameworks.
South Africa
Spirulina cultivation concentrates near Cape Town where controlled-environment farms supply nutraceutical tablets to Lagos and Nairobi retailers. The Department of Health enforces heavy metal thresholds that determine manufacturing license eligibility. Photobioreactor automation is digitizing quality protocols at facilities serving export markets.
Nigeria
Domestic functional food brands formulate algae protein into beverages and baked goods as soy isolate alternatives. The National Agency for Food and Drug Administration and Control oversees novel food classifications affecting registration timelines. Lagos-based wellness retailers bypass bulk distributors through direct procurement from South African producers.
Kenya
Spirulina biomass enters Mombasa port under Bureau of Standards guidelines that reduced clearance delays for food-grade imports. The regulator established maximum microbiological limits streamlining domestic manufacturing licenses. Nairobi pharmacies are fragmenting buyer power through direct tablet sourcing from Cape Town farms.
Egypt
Oilseed crushing infrastructure supplies cheaper commodity soy isolates that undercut algae protein on price-per-protein-unit. The national food safety authority maintains additive classifications that treat algae extracts as novel foods requiring extended registration. Cairo compound feed producers represent latent demand for feed-grade biomass with relaxed contamination standards.
Tanzania
High-altitude cultivation zones offer natural temperature moderation for chlorella production expansion. East African Community integration protocols enable tariff-free movement of processed ingredients to regional hub facilities. Arusha and Dodoma agricultural zones remain underexploited for photobioreactor deployment serving supplement manufacturers.
Africa Algae Protein Market Competitive Environment
Capability concentration sits with technology-integrated producers; scale advantage sits with diversified ingredient conglomerates. The market structures around three tiers: multinational life-science conglomerates with global R&D platforms, regional controlled-environment specialists with food-grade certification, and commodity open-pond operators serving feed markets. Dominant competitive moves include strategic partnerships between technology licensors and African distributors, plus portfolio diversification into finished tablet formulations.
Among multinational life-science conglomerates, DSM and BASF SE occupy positions exemplifying integrated R&D-to-distribution platforms. Cyanotech Corporation anchors the technology-specialist tier with microalgae cultivation systems. Live Spirulina SA represents regional controlled-environment production with Cape Town-based facilities serving export markets.
| Leading Market Players |
|---|
| Corbion N.V. |
| BASF SE |
| Cyanotech Corporation |
| DSM |
| DuPont |
| Cargill, Incorporated |
| Live Spirulina SA |
| Soaring Free Superfoods |
| Biodelta Neutraceuticals |
| Others |
Value Chain & Pricing Dynamics
Mombasa port clearance corridors anchor continental cost dynamics for spirulina biomass entering East African markets, compressing margins for open-pond operators while rewarding photobioreactor-based producers with certification premiums that downstream buyers in Lagos and Nairobi pharmacies willingly absorb.
Pricing Analysis
Price spreads between South African photobioreactor output and Kenyan open-pond biomass reach three-tier pricing structure across premium, standard, and economy levels, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from Egyptian soy isolate competition that undercuts algae on price-per-protein-unit. Food-grade nutraceutical buyers show lowest price sensitivity; compound feed manufacturers exhibit highest.
Supply Chain Analysis
Contract manufacturing concentrates with Live Spirulina SA and DSM regional processing facilities holding controlled-environment capacity. Geographic supply concentrates in South Africa, Kenya, and Tanzania. Raw material dependencies include CO2 feedstock, nutrient media formulations, and diesel backup power. Single-source strain banking in Cape Town biorepositories creates genetic uniformity vulnerability. Distribution runs through regional hub-and-spoke models centered on South African processing capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kenya's algae-specific quality guidelines represent a regulatory inflection that accelerates market formalization, creating first-mover advantages for producers achieving Bureau of Standards certification before competitor facility expansion.
For Market Incumbents: Build regulatory certification moats by securing Bureau of Standards alignment ahead of Kenyan guideline expansion and investing in photobioreactor automation that digitizes quality protocols beyond open-pond replication. Anchor capacity addition in Cape Town controlled-environment farms to defend against East African Community import substitution. Channel control through direct tablet supply to Lagos and Nairobi wellness retailers limits distributor margin capture.
For New Entrants and Emerging Players: Tanzania's high-altitude cultivation zones around Arusha and Dodoma represent the most penetrable entry point for chlorella production expansion with natural temperature moderation. Nigerian functional food manufacturers seeking domestic protein alternatives offer white-space demand for bulk powder supply. Go-to-market through direct procurement partnerships with Lagos-based domestic brands bypasses established distributor relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational life-science conglomerates seeking to divest non-core algae cultivation assets. Long-term viability over the projection horizon hinges on regulatory harmonization across African Union member states. Watch Kenya's Bureau of Standards guideline adoption velocity as inflection indicator for regional certification standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Photobioreactor Automation Investment | DSM sensor arrays reduce batch failure rates through real-time dissolved oxygen monitoring. |
| Direct-to-Consumer Tablet Launch | Lagos and Nairobi pharmacies fragment buyer power through Cape Town farm procurement. |
| East African Community Hub Expansion | Tanzania high-altitude zones enable tariff-free chlorella movement to regional processors. |
| Regulatory Certification Acceleration | Kenya Bureau of Standards alignment streamlines Mombasa port clearance timelines. |
| Backward Integration into Strain Banking | Cape Town biorepository diversification mitigates single-source genetic uniformity risk. |
Study Parameters
Initial hypotheses were tested against primary input from algae cultivation facility managers, nutraceutical procurement leads at Lagos and Nairobi distributors, Bureau of Standards regulatory affairs officers, and compound feed formulators, then refined against secondary validation from Kenya Bureau of Standards guideline documents, South African Department of Health safety threshold filings, East African Community tariff protocol records, and customs biomass import data. Bottom-up facility capacity estimates and top-down regional demand projections were triangulated.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling strain type, end-use sector, form factor, and geographic regulatory cluster as segmentation dimensions. CAGRs were derived from recursive least-squares fitting to historical trajectory data. Forecast inputs included photobioreactor automation adoption curves and Kenyan guideline implementation timelines.
Stress conditions across diesel price volatility, grid instability duration, and novel food reclassification probability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization velocity and strain productivity improvements. Quarterly review of Bureau of Standards certification queue depth and Mombasa port clearance velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biotechnology
Europe Plant Growth Regulators Market
Agricultural Biotechnology
Agroscience Market
Agricultural Biotechnology
Europe Agriculture Biotech Market
Agricultural Biotechnology
South America Feed Phytogenics Market
Agricultural Biotechnology
Global Animal Biotechnology Market
Agricultural Biotechnology
Duckweed Protein Market
Agricultural Biotechnology
Animal Brucella Antibody ELISA Kits Market
Agricultural Biotechnology
Brazil Veterinary Vaccines Market
Agricultural Biotechnology
Global Plant Hormones Market
Agricultural Biotechnology
Ruminant Vaccines Market
Agricultural Biotechnology
Agricultural Biotechnology Market
Agricultural Biotechnology
Microarray in Agriculture Market
Agricultural Biotechnology
Plant-Based Vaccines Market
Agricultural Biotechnology
Asia-Pacific Agriculture Biotech Market
Agricultural Biotechnology
Global Poultry Vaccines Market
Agricultural Biotechnology
GMO Crops and Seeds Market