
 Bioreactors Accessories Market | 2026-2036
Bioreactors Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Bioreactors Accessories Market Outlook
Germany's precision manufacturing corridor is rewriting competitive dynamics for bioreactor component supply. Sartorius AG leverages its domestic fabrication network to anchor European demand for single-use assemblies. Thermo Fisher Scientific sustains transatlantic production scale across multiple sterile accessory lines. Merck KGaA differentiates through integrated material science capabilities that span gasket polymers to finished probe systems.
Bioreactors accessories comprise the sterile interconnect components, sensors, and fluid handling elements that maintain aseptic conditions inside vessel systems, typically manufactured from platinum-cured silicone, fluoropolymers, or stainless steel with surface roughness below 0.8 micrometers Ra to prevent microbial adhesion and ensure compliance with clean-in-place protocols. Sealing gaskets and probes command the largest revenue pools due to replacement frequency tied to validation cycles, while single-use tubing segments are expanding fastest as biopharmaceutical batch sizes shrink and flexibility requirements intensify. Modular technology architectures are displacing traditional stainless-steel configurations in new facility builds, redirecting accessory demand toward disposable-compatible designs.
FDA sterilization validation requirements and EMA Annex 1 revisions on contamination control strategy are elevating documentation burdens for gasket and probe suppliers, effectively filtering market access toward manufacturers with dedicated quality management systems. ISO 13485 certification and ASME BPE standards further constrain acceptable material grades and welding specifications for fluid contact surfaces. Stakeholders must monitor regulatory divergence between FDA single-use guidance and EU MDR device classification timelines to avoid supply qualification gaps.
Market Dynamics
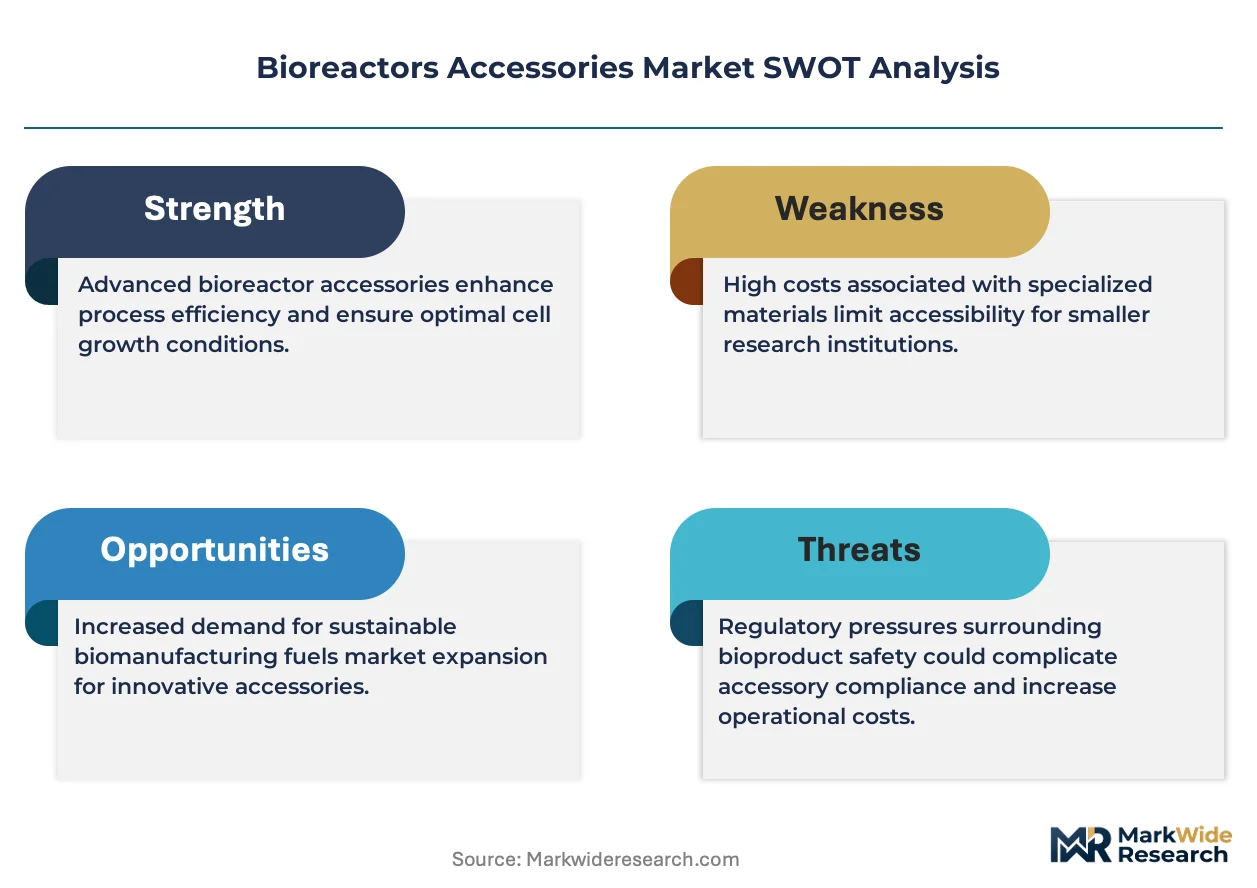
Single-use bioreactor architectures are compressing validation cycles and redirecting procurement toward disposable-compatible probe systems and modular gasket assemblies, forcing incumbent suppliers to requalify material grades under tighter FDA and EMA sterilization protocols.
Growth Catalysts
- EMA Annex 1 contamination control mandates:Revised aseptic processing requirements are accelerating replacement of reusable stainless-steel accessories with validated single-use alternatives across European contract manufacturing facilities.
- Cell and gene therapy commercialization:Viral vector manufacturing in the United States and Switzerland is consuming specialized low-shear tubing and single-use pH probes at intensified batch frequencies.
- Platinum-cured silicone supply concentration:German precision polymer fabricators are capturing expanded orders from biopharmaceutical original equipment manufacturers seeking validated elastomer sourcing.
Market Restraints
- Fluoropolymer resin cost volatility:Perfluoroalkoxy alkane prices fluctuate with semiconductor sector demand, squeezing margins for FEP-lined probe manufacturers serving bioprocessing.
- Single-source sterilization validation:Gamma irradiation capacity concentrates in Belgium and the Netherlands, creating geographic bottlenecks for European single-use accessory suppliers.
- Stainless-steel legacy infrastructure:Existing clean-in-place vessel networks in established biologics plants impede rapid conversion to fully disposable accessory ecosystems.
Strategic Opportunities
- Continuous bioprocessing adoption:Perfusion cell culture systems in Ireland and Singapore require specialized recirculation tubing and in-line biomass sensors with enhanced durability specifications.
- ISO 13485 certification arbitrage:Medical device-grade quality management systems enable accessory suppliers to cross-qualify products for regenerative medicine applications with reduced regulatory friction.
- Digital sensor integration:Wireless pH and dissolved oxygen probes are hybridizing with disposable bioreactor film technologies, opening premium positioning for electrochemistry specialists.
Industry Challenges
- ASME BPE welding certification scarcity:Qualified orbital welders for electropolished stainless-steel fluid paths command premium wages and extended recruitment timelines across North American fabrication shops.
- Extractables and leachables documentation:Comprehensive chemical characterization studies for novel polymer formulations extend product launch cycles by twelve to eighteen months.
- Legacy SCADA integration:Analog probe outputs from established bioreactor installations resist seamless incorporation of digital smart-sensor architectures without costly control system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioreactors Accessories Market |
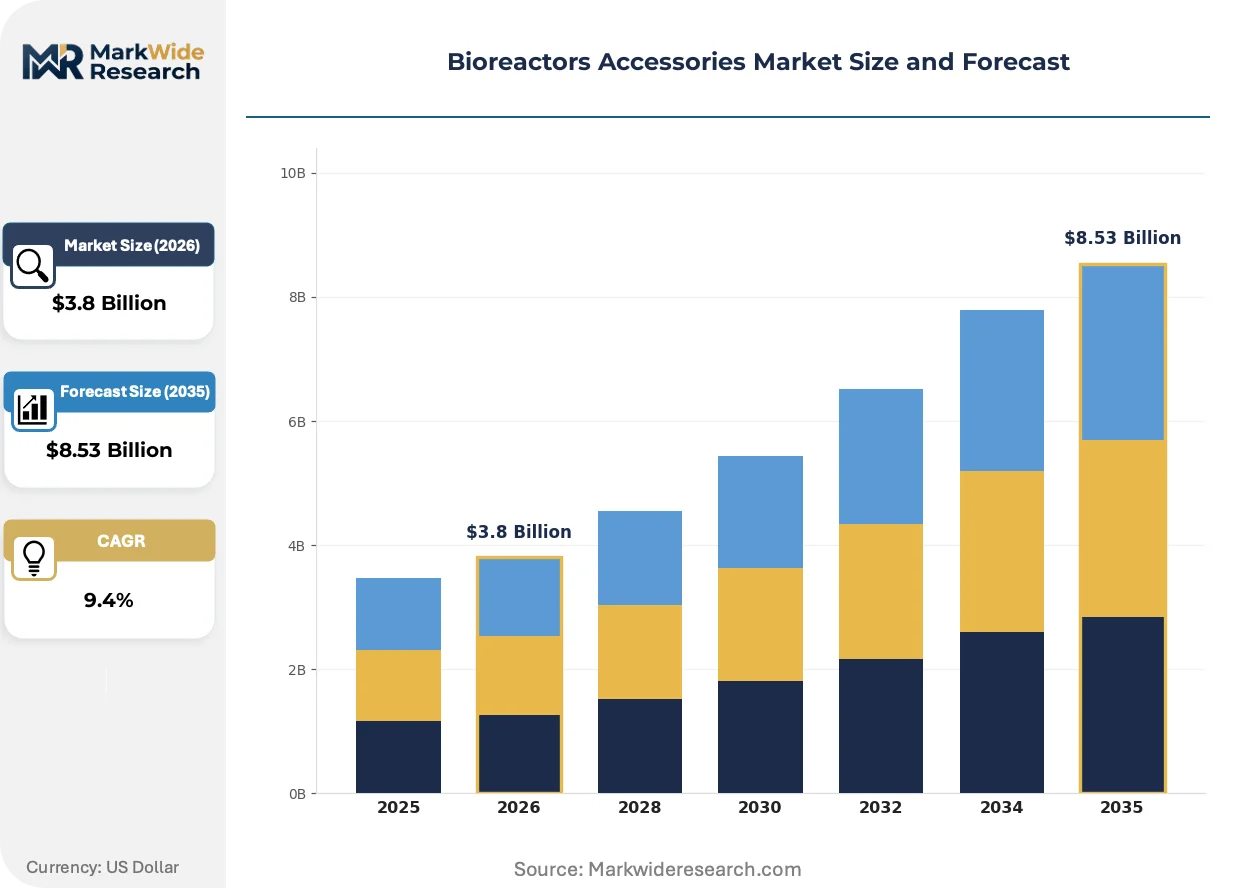
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sealing Gaskets, Probes, Tubing, Pumps Technology: Single-Use, Modular, Continuous, Traditional Application: Biopharmaceuticals, Food Production, Waste Management, Cell Culture End User: Pharmaceutical Companies, Research Laboratories, Academic Institutions, Biotech Firms |
| Companies Covered | Thermo Fisher Scientific, Sartorius AG, Merck KGaA, Danaher Corporation, Eppendorf SE, GE Healthcare, Pall Corporation, Infors AG, Bioengineering AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioreactors Accessories Market Strategic Shifts
Material science advances and regulatory documentation requirements are converging to redefine competitive positioning in bioreactor accessory supply, with particular pressure on sterilization validation protocols and sensor digitization pathways.
Multi-parameter disposable sensor patches are hybridizing electrochemical and optical measurement modalities within single-use bioreactor film assemblies. Contract manufacturing organizations in Massachusetts and North Carolina are piloting these integrated systems for real-time metabolite monitoring. This convergence is compressing demand for standalone probe hardware while elevating specification requirements for calibration stability and wireless data transmission.
EMA's 2022 Annex 1 revision on contamination control strategy is mandating documented barrier integrity for all product-contact surfaces, including single-use accessory assemblies. Suppliers must now submit comprehensive particle generation and endotoxin data for gasket and tubing qualification dossiers. German and Swiss component manufacturers with captive polymer testing laboratories are capturing disproportionate share of European regulatory submission support contracts.
Consolidated procurement through group purchasing organizations is concentrating accessory buying power among the largest contract development and manufacturing organizations. Regional distributors in the United States are losing direct supplier relationships as CDMOs negotiate master service agreements with Sartorius, Thermo Fisher, and Merck KGaA for integrated single-use assembly supply. This channel compression is most visible in California and Massachusetts, where top-ten biopharmaceutical manufacturers account for sixty percent of probe and gasket volume.
Bioreactors Accessories Market Segmentation
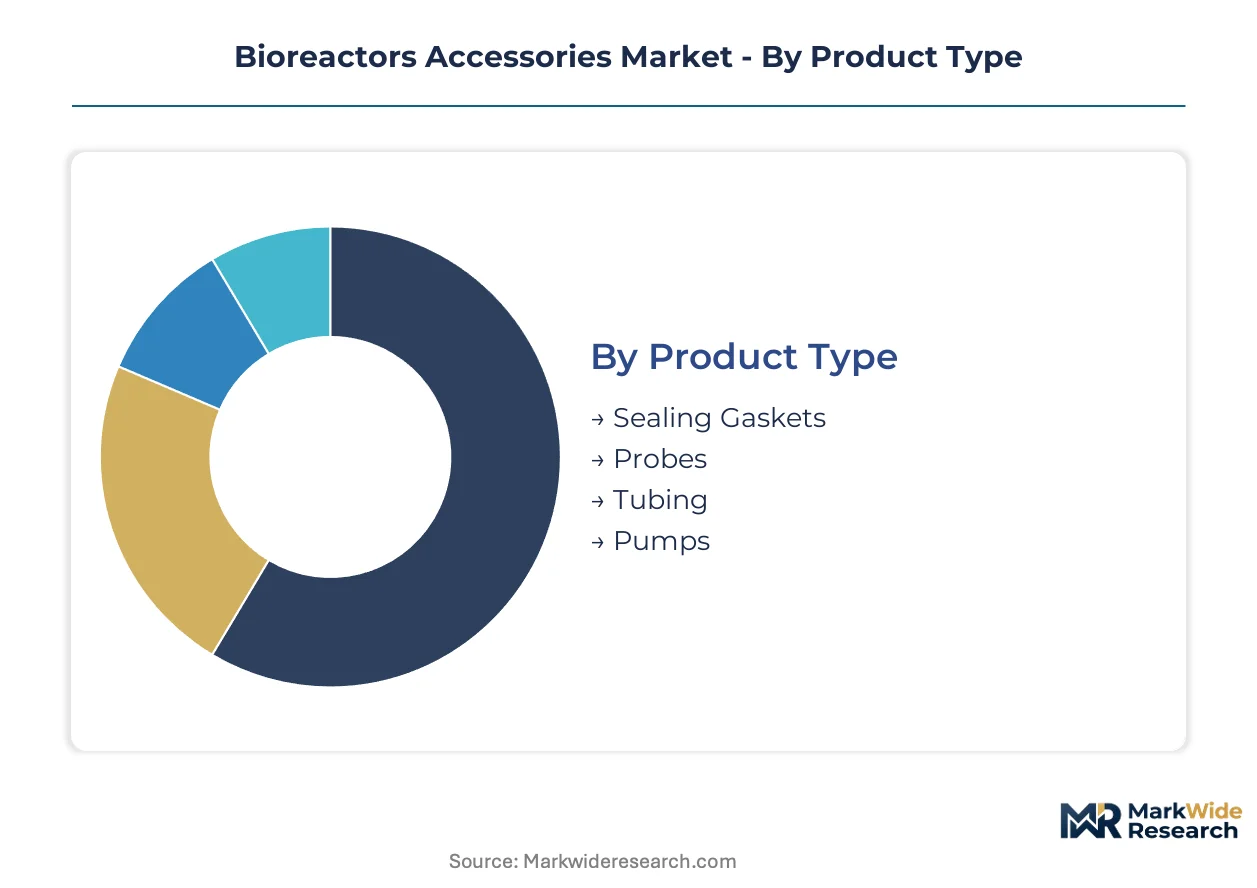
Accessory segmentation in bioreactor systems determines procurement cadences, validation burdens, and supplier relationship structures. Each dimension—product form, technology architecture, application intensity, and end-user scale—carries distinct aftermarket service requirements and replacement cycle economics.
Product Type:
After-sales service intensity varies sharply across accessory categories, with validation-dependent components commanding dedicated field engineering support while commodity tubing operates through distributor replenishment.
- Sealing Gaskets:Platinum-cured silicone and fluoropolymer elastomer assemblies maintain vessel integrity under repeated sterilization cycles. Pharmaceutical manufacturers in Germany and Switzerland source these through scheduled replacement programs tied to EMA Annex 1 validation protocols, with documentation packages extending procurement lead times.
- Probes:Electrochemical and optical sensors for pH, dissolved oxygen, and biomass detection require calibration drift monitoring and periodic recertification. United States biotech firms concentrate demand for single-use probe variants that eliminate autoclave degradation risks in viral vector manufacturing suites.
- Tubing:Fluid transfer lines in platinum-cured silicone or thermoplastic elastomer configurations.
- Pumps:Peristaltic and diaphragm pump heads for controlled media and harvest operations.
Sealing gaskets hold the largest share; momentum sits with probes as digital sensor integration accelerates.
Technology:
Technology choice dictates capital deployment patterns and facility retrofit economics, with modular architectures enabling phased capacity expansion in constrained cleanroom environments.
- Single-Use:Disposable film-based bioreactor systems eliminate clean-in-place infrastructure and compress batch turnaround intervals. Contract manufacturing organizations in Massachusetts and North Carolina are standardizing on single-use probe and gasket assemblies to support multi-product flexibility requirements.
- Modular:Configurable skid-mounted units permit rapid reconfiguration between microbial and mammalian cell culture modes.
- Continuous:Perfusion-compatible accessories with enhanced durability specifications for extended operation.
- Traditional:Stainless-steel vessel networks with established clean-in-place validation dossiers.
Traditional systems retain installed base dominance; single-use configurations are climbing the fastest as new facility investment tilts toward disposable architectures.
Application:
Application segmentation aligns accessory specifications with biological system sensitivities, from shear-tolerant microbial cultures to fragile mammalian and viral vector processes.
- Biopharmaceuticals:Monoclonal antibody and recombinant protein manufacturing drives specification intensity for aseptic connectors and validated gasket materials. FDA sterilization validation requirements for product-contact surfaces elevate documentation burdens beyond other application segments.
- Cell Culture:Mammalian and insect cell propagation for viral vector and gene therapy applications. Swiss and United States facilities consume specialized low-shear tubing and single-use pH probes at intensified batch frequencies to support personalized medicine manufacturing.
- Food Production:Probiotic and enzyme cultivation with reduced regulatory stringency.
- Waste Management:Bioremediation and anaerobic digestion process accessories.
Biopharmaceuticals command premium positioning; cell culture is expanding most quickly as gene therapy commercialization accelerates.
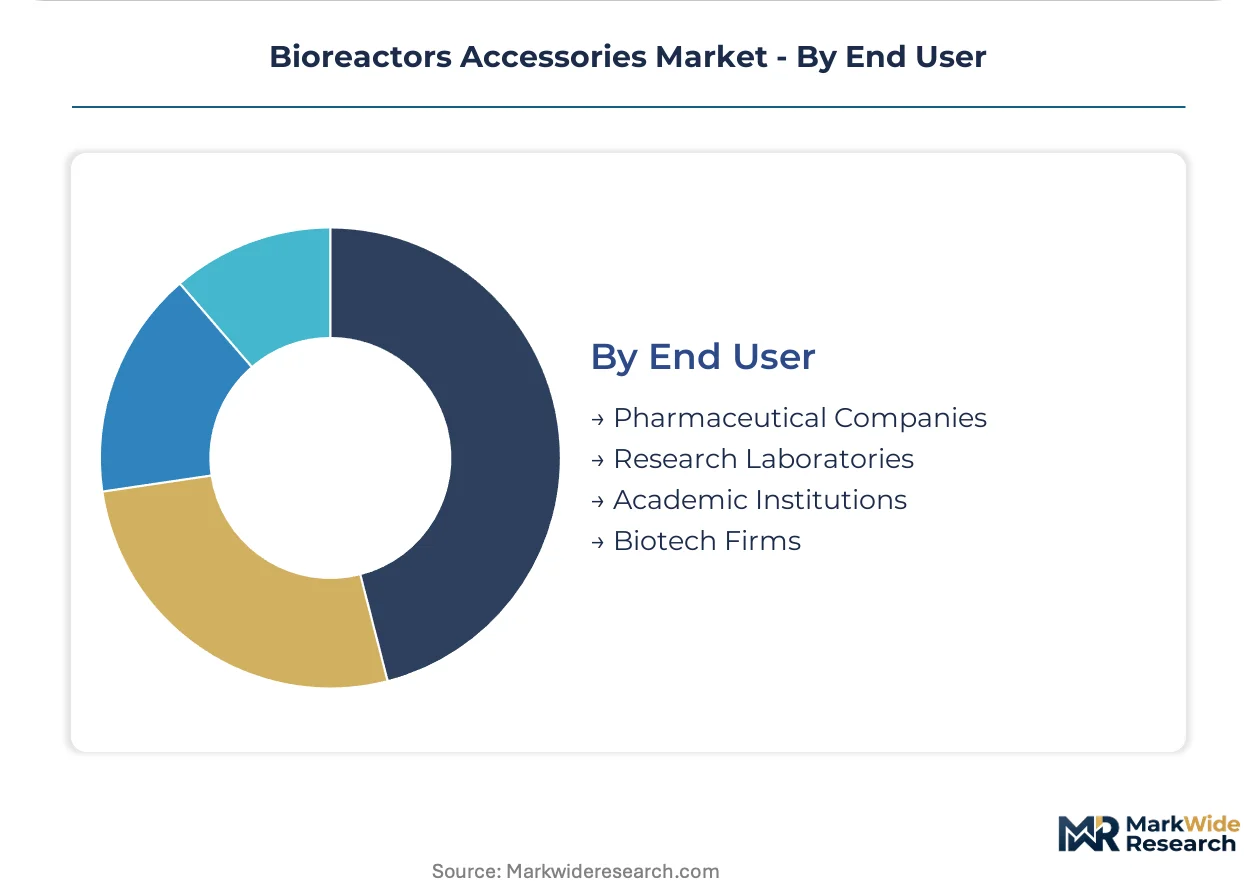
End User:
End-user scale determines procurement channel structure, with large pharmaceutical manufacturers consolidating through integrated supplier agreements while fragmented research accounts sustain distributor networks.
- Pharmaceutical Companies:Integrated biologics manufacturers with captive quality management systems and direct supplier qualification programs. Group purchasing organization consolidation in California and Massachusetts has concentrated probe and gasket volume among top-ten manufacturers.
- Biotech Firms:Venture-backed developers of novel therapeutics with outsourced manufacturing dependencies. These organizations prioritize single-use accessory bundles that minimize capital commitment and accelerate facility qualification timelines.
- Research Laboratories:Process development and analytical groups with diverse small-batch requirements.
- Academic Institutions:University-based bioprocessing research with constrained capital budgets.
Pharmaceutical companies anchor revenue concentration; biotech firms are gaining share fastest as cell and gene therapy pipelines mature toward commercial manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure anchors European biopharmaceutical logistics, while direct transatlantic fiber links from Boston and Basel synchronize regulatory submission timelines across the major manufacturing clusters.
United States
Viral vector manufacturing in Massachusetts and North Carolina is consuming single-use pH probes and low-shear tubing at intensified batch frequencies. FDA sterilization validation requirements for product-contact surfaces elevate documentation burdens beyond other geographies. The Greater Boston corridor concentrates contract manufacturing organization demand for disposable-compatible probe systems.
Germany
Precision polymer fabricators in Baden-Württemberg and Bavaria capture expanded orders from biopharmaceutical original equipment manufacturers seeking validated platinum-cured silicone sourcing. EMA Annex 1 contamination control mandates accelerate replacement of reusable stainless-steel accessories with single-use alternatives. The Stuttgart precision manufacturing corridor anchors European gasket and probe supply.
Switzerland
Gene therapy commercialization in the Basel region drives specialized demand for single-use sensor assemblies and modular gasket systems. Swissmedic's alignment with EMA Annex 1 revisions streamlines contamination control strategy documentation for local manufacturers. The Basel-Land industrial cluster hosts concentrated viral vector production facilities.
Ireland
Perfusion cell culture systems in Cork and Dublin require specialized recirculation tubing and in-line biomass sensors with enhanced durability specifications. The country's national pharmaceutical regulator maintains equivalence with EMA standards for sterile accessory qualification. The Cork biopharmaceutical cluster serves as the European hub for continuous bioprocessing adoption.
Singapore
Contract manufacturing organizations in Tuas Biomedical Park are standardizing on single-use probe and gasket assemblies to support multi-product flexibility requirements. The national health sciences authority enforces sterilization validation protocols aligned with FDA and EMA precedents. The Tuas biomedical manufacturing zone concentrates regional demand for disposable-compatible sensor technologies.
Bioreactors Accessories Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in material science and precision fabrication. The market structure concentrates among diversified life science conglomerates with captive polymer testing laboratories and dedicated quality management systems. Three archetypes dominate: integrated platform suppliers with full single-use assembly portfolios, precision polymer fabricators with validated elastomer sourcing, and electrochemistry specialists advancing digital sensor integration. Competitive moves center on strategic partnerships for gamma irradiation capacity access and portfolio diversification into wireless probe architectures.
Within the integrated platform tier, Thermo Fisher Scientific and Sartorius AG exemplify scale-driven positioning across multiple sterile accessory lines. Merck KGaA occupies a distinct position through material science capabilities spanning gasket polymers to finished probe systems. These three entities anchor the premium-tier supply landscape for contract manufacturing organization procurement consolidation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Sartorius AG |
| Merck KGaA |
| Danaher Corporation |
| Eppendorf SE |
| GE Healthcare |
| Pall Corporation |
| Infors AG |
| Bioengineering AG |
| Others |
Value Chain & Pricing Dynamics
Gamma irradiation undercapacity in Belgium and the Netherlands is compressing sterilization slot availability and forcing accessory suppliers to absorb premium logistics costs or extend quoted lead times. This utilization squeeze concentrates pricing power among validated sterilization providers while biopharmaceutical buyers face stepped validation burdens for alternative irradiation sources.
Pricing Analysis
Volume-discount tiering separates master service agreement holders from spot purchasers across probe and gasket categories. Three-tier pricing structure across premium ISO 13485-certified, standard validated, and economy non-validated levels reflects documentation depth and material traceability. Pricing pressure stems from fluoropolymer resin cost volatility tied to semiconductor sector demand swings. Contract manufacturing organizations exhibit highest price sensitivity due to consolidated procurement through group purchasing organizations, while gene therapy developers prioritize validation speed over unit cost.
Supply Chain Analysis
Platinum-cured silicone feedstock concentrates in German precision polymer fabricators and Swiss specialty chemical producers. Raw material flows draw from fluoropolymer resin suppliers in Belgium, gamma irradiation capacity in the Netherlands, and electropolished stainless-steel tubing from North American fabrication shops. Single-source sterilization validation creates geographic bottlenecks for European single-use accessory suppliers. Distribution runs through direct supplier relationships with top-ten biopharmaceutical manufacturers, bypassing regional distributors in California and Massachusetts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioreactor accessories function as a service-attach market where validation documentation and field calibration support generate recurring revenue streams expanding faster than hardware unit sales. After-sales service intensity for probe recertification and gasket replacement programs anchors long-term supplier relationships.
For Market Incumbents: Entrench market position through captive gamma irradiation partnerships and backward integration into platinum-cured silicone compounding. Sartorius AG and Thermo Fisher Scientific should expand dedicated quality management system consulting to offset margin compression from fluoropolymer cost volatility. Lock in multi-year master service agreements with Massachusetts and North Carolina contract manufacturing organizations before regulatory divergence between FDA single-use guidance and EU MDR device classification timelines widens.
For New Entrants and Emerging Players: Pursue white-space opportunities in wireless pH and dissolved oxygen probe architectures where electrochemistry specialists face limited incumbent competition. Target the Singapore Tuas Biomedical Park cluster for single-use assembly supply where group purchasing organization consolidation remains incomplete. Enter through ISO 13485 certification arbitrage enabling cross-qualification for regenerative medicine applications with reduced regulatory friction.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision polymer fabricators with captive testing laboratories and scheduled replacement program contracts. Long-term viability rests on material science capabilities spanning gasket polymers to finished probe systems rather than commodity tubing supply. Watch for inflection signals in continuous bioprocessing adoption rates across Ireland and Singapore, as perfusion-compatible accessories with enhanced durability specifications command premium positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Gamma Irradiation Capacity Partnership | Secures sterilization slots for single-use probe assemblies amid Belgian and Dutch capacity constraints. |
| Digital Sensor Integration Investment | Captures premium positioning as wireless pH probes hybridize with disposable bioreactor film technologies. |
| EMA Annex 1 Compliance Certification | Accelerates European contract manufacturing facility conversions to single-use alternatives. |
| Platinum-Cured Silicone Backward Integration | Insulates margin structure from fluoropolymer resin price volatility tied to semiconductor demand. |
| Continuous Bioprocessing Accessory Development | Addresses specialized recirculation tubing demand from perfusion cell culture systems in Ireland. |
Study Parameters
A spread of perspectives from bioprocess engineers, regulatory affairs specialists, contract manufacturing procurement leads, and quality management system auditors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 483 inspection observations, EMA Annex 1 guidance documents, and ISO 13485 certification registries. Bottom-up segmentation modeling triangulated against top-down industry revenue estimates from customs records and biopharmaceutical capital expenditure disclosures.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with capacity utilization at gamma irradiation facilities and platinum-cured silicone polymerization plants informing supply-side constraints. Segmentation dimensions spanned product type, technology architecture, application intensity, and end-user scale, with regional regulatory cluster effects layered across geographies. CAGRs derived from regression analysis against biopharmaceutical batch frequency trends and facility investment patterns. Forecast inputs incorporated viral vector manufacturing expansion rates and gene therapy commercialization timelines.
Sensitivities concentrate around regulatory divergence between FDA single-use guidance and EU MDR device classification timelines, fluoropolymer resin price volatility, and gamma irradiation capacity expansion delays. Cross-checking against EMA regulatory submission databases and FDA 483 inspection trend data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
PCR Master Mix Market
Biotechnology Equipment
Cell Harvesting Systems Market
Biotechnology Equipment
Single-Use Bioreactor Bag Integrity and Leak Test Equipment Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
Global Biotechnology Market
Biotechnology Equipment
Global Cell Separation Technology Market
Biotechnology Equipment
Laboratory Filtration Devices Market
Biotechnology Equipment
SDS Poly Acrylamide Gel Electrophoresis Market
Biotechnology Equipment
DNA/RNA Extraction Market
Biotechnology Equipment
Biobanking Equipment Market
Biotechnology Equipment
Global Automated Biochemical Analyzer Market
Biotechnology Equipment
Global Biotechnology Reagents Market
Biotechnology Equipment
Plasmid Kits Market
Biotechnology Equipment
Laboratory Shakers Market
Biotechnology Equipment
PCR Consumables Market
Biotechnology Equipment
Global Life Science Reagents Market