
 IoT in Chemical Industry Market | 2026-2036
IoT in Chemical Industry Market Size, Share, and Industry Trends Forecast 2026-2036
IoT in Chemical Industry Market Analysis
IEC 61508 functional safety certification for process industries is collapsing the vendor pool eligible for hazardous area IoT deployments. Siemens AG leverages its TÜV-certified safety instrumented systems to dominate European retrofit programs. Honeywell International Inc. sustains channel control through its Experion distributed control platform integrated with wireless sensor networks. ABB Ltd anchors Asian project pipelines with Ability Smart Sensor portfolios calibrated for corrosive chemical environments.
IoT in chemical industry denotes networked sensor-actuator ecosystems operating across temperatures from minus forty to four hundred degrees Celsius, transmitting real-time pressure, flow, and composition data to centralized or edge-located analytics engines for process optimization and hazard prevention. Predictive maintenance applications command premium pricing due to unplanned downtime costs exceeding two million dollars per incident at ethylene crackers. Smart sensors represent the most mature revenue pool, while edge computing deployments at remote petrochemical complexes represent the fastest-expanding segment as latency requirements harden for emergency shutdown systems. Big data analytics platforms extract margin from batch-to-batch yield variation at specialty chemical producers.
The EPA enforces Risk Management Plan amendments that mandate continuous release monitoring, forcing facilities toward connected gas detection architectures. OSHA process safety management inspections now probe digital record-keeping integrity, elevating demand for tamper-evident IoT data logging. ECHA REACH substance tracking requirements extend IoT traceability from raw material receipt through finished goods dispatch. Buyers must weigh cloud versus on-premise data residency as chemical security anti-terrorism standards tighten scrutiny of externally hosted operational technology data streams.
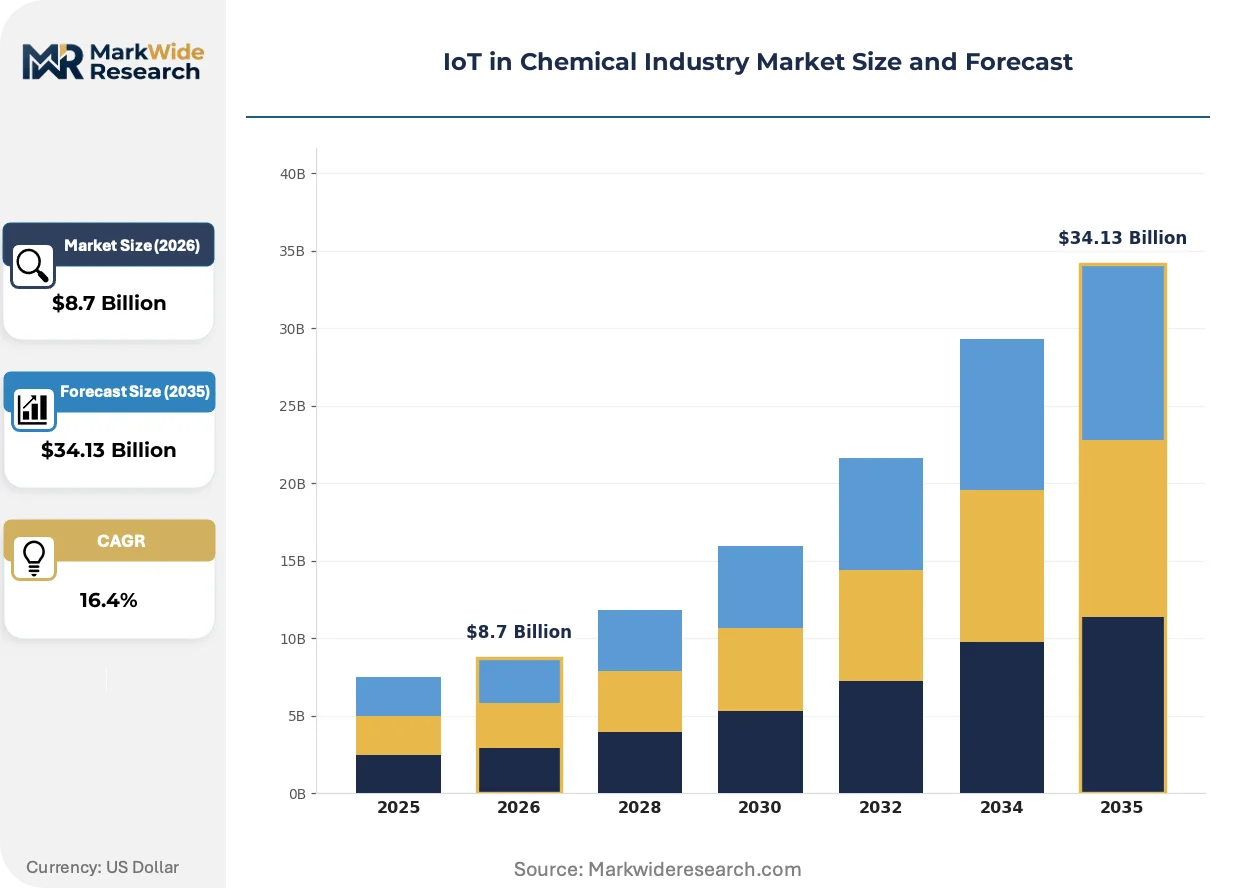
Market Dynamics
Sensor-to-cloud integration is compressing upgrade cycles for legacy distributed control systems as REACH substance tracking mandates force real-time data lineage from raw material intake through finished goods dispatch.
Growth Catalysts
- EU Green Deal carbon accounting:Chemical producers in Germany and the Netherlands must deploy continuous emissions monitoring to satisfy tightening verification protocols for Scope 1 and Scope 2 reporting.
- Predictive maintenance at ethylene crackers:Unplanned downtime costs exceeding two million dollars per incident drive premium pricing for vibration and thermal anomaly detection systems.
- Edge computing latency requirements:Emergency shutdown systems at remote petrochemical complexes now demand sub-50-millisecond response times that cloud architectures cannot satisfy.
Market Restraints
- IEC 61508 certification scarcity:Functional safety validation for hazardous area deployments collapses the vendor pool to TÜV-certified suppliers, extending procurement timelines by eight to fourteen months.
- Corrosive environment sensor degradation:Hydrogen sulfide and chlorine vapor exposure in specialty chemical zones accelerates replacement cycles beyond standard industrial IoT warranties.
- Legacy protocol fragmentation:Proprietary fieldbus architectures from 1990s-era installations resist seamless integration with IP-based wireless sensor networks without expensive gateway layers.
Strategic Opportunities
- Digital twin implementations in Germany:BASF and Bayer facilities anchor large-scale virtual commissioning projects that reduce physical prototyping for new production lines.
- 5G private network convergence:Ultra-reliable low-latency communication is supplanting Wi-Fi for mobile worker safety systems and autonomous inspection robotics in flammable atmospheres.
- OSHA digital record-keeping mandates:Process safety management inspections now probe data integrity, elevating demand for tamper-evident blockchain logging in US Gulf Coast refineries.
Industry Challenges
- Functional safety engineering talent scarcity:TÜV-certified system architects command premium compensation that mid-sized system integrators struggle to match against industrial automation conglomerates.
- Cloud versus on-premise data residency:Chemical Facility Anti-Terrorism Standards tighten scrutiny of externally hosted operational technology streams, forcing redundant architecture investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT in Chemical Industry Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Sensors, Asset Management, Predictive Maintenance, Process Automation Technology: Wireless Communication, Cloud Computing, Edge Computing, Big Data Analytics Application: Supply Chain Management, Quality Control, Environmental Monitoring, Energy Optimization End User: Chemicals Manufacturers, Pharmaceutical Companies, Agriculture Sector, Oil Refineries |
| Companies Covered | Siemens AG, ABB Ltd, Honeywell International Inc., General Electric, Emerson Electric Co, Rockwell Automation, Inc., Yokogawa Electric Corporation, Schneider Electric SE, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT in Chemical Industry Market Emerging Trajectories
WirelessHART and ISA100.11a protocols are converging with 5G private networks to enable sensor density levels that wired installations cannot economically achieve in sprawling refinery complexes.
Silicon carbide-based temperature sensors are supplanting platinum resistance thermometers in furnace monitoring applications above 400 degrees Celsius. Specialty chemical producers in Germany and Belgium are adopting these devices to eliminate thermowell failures that trigger unplanned shutdowns. The shift is compressing maintenance windows from quarterly to annual intervals while expanding continuous monitoring coverage to previously inaccessible reactor zones.
EPA Risk Management Plan amendments now mandate continuous release monitoring for regulated toxic substances above threshold quantities. Facilities must install connected gas detection architectures that transmit real-time concentration data to local emergency response agencies. Ethylene and propylene producers on the US Gulf Coast are accelerating retrofit timelines to meet compliance deadlines, prioritizing wireless mesh networks over hardwired alternatives to minimize hot-work permits in classified areas.
Buyer procurement committees now require outcome-based service contracts that tie vendor payments to measurable uptime improvements rather than hardware delivery. Specialty chemical producers in Switzerland and the Netherlands are unbundling sensor hardware from analytics software licenses, selecting best-of-breed combinations through competitive tender processes. This pattern is most visible among mid-sized batch manufacturers seeking to reduce vendor lock-in while accessing predictive algorithms developed across multiple industrial verticals.
IoT in Chemical Industry Market Segmentation
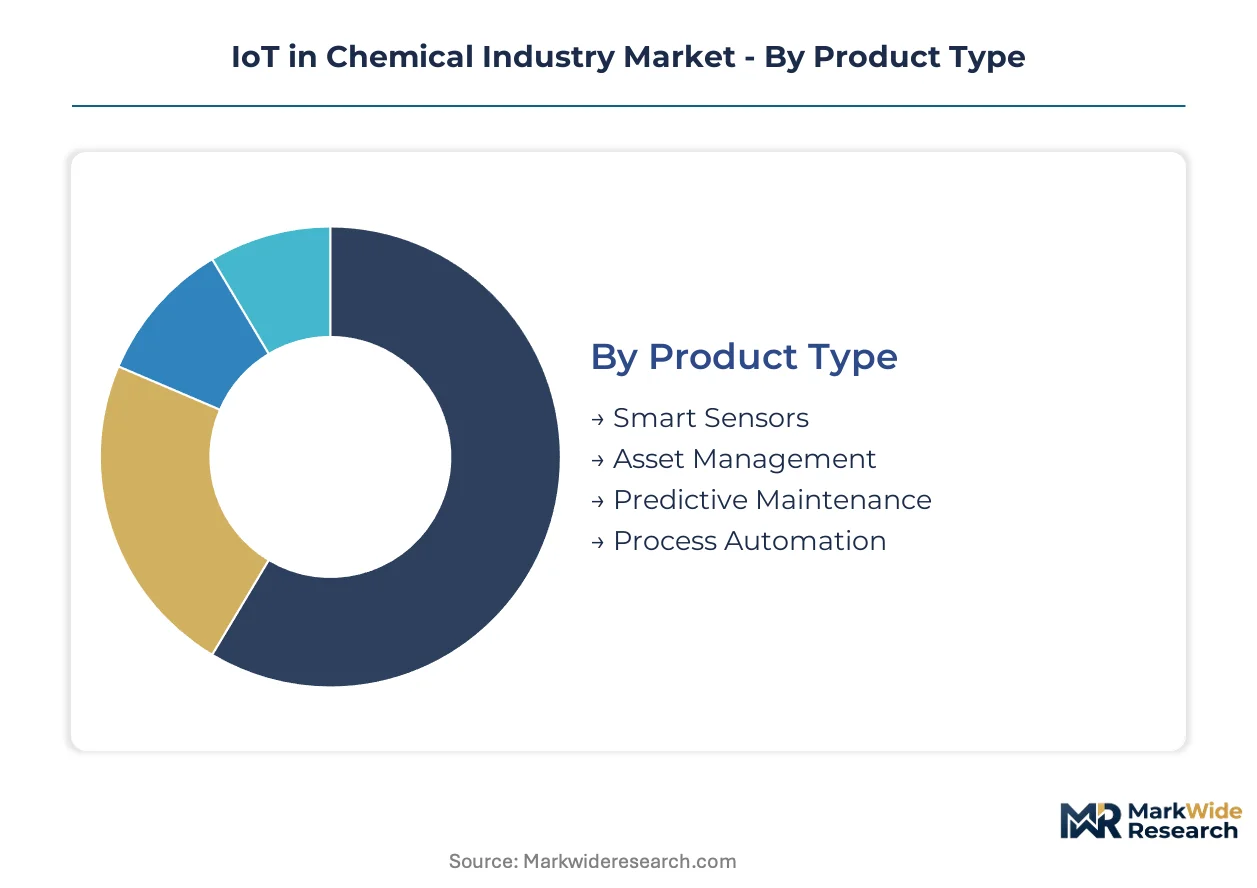
Chemical facilities deploy IoT architectures across heterogeneous operational layers, from corrosive reactor zones to remote storage terminals. Regulatory mandates fragment procurement requirements by hazard classification, compressing vendor selection to certified specialists.
Product Type:
EU ATEX directives and IEC 61508 functional safety standards stratify hardware eligibility by explosive atmosphere classification, collapsing supplier pools for zone-zero deployments.
- Smart Sensors:Platinum resistance thermometers and silicon carbide temperature probes transmit pressure, flow, and composition data across minus forty to four hundred degrees Celsius operating ranges. German BASF and Bayer facilities anchor dense deployments in furnace monitoring and reactor zone applications where thermowell failures previously triggered unplanned shutdowns.
- Predictive Maintenance:Vibration and thermal anomaly detection systems command premium pricing at ethylene crackers where single downtime incidents exceed two million dollars. US Gulf Coast refineries prioritize these deployments to satisfy EPA Risk Management Plan amendments mandating continuous equipment integrity monitoring.
- Asset Management:Digital twin implementations virtualize physical asset performance for commissioning and lifecycle optimization.
- Process Automation:Safety instrumented systems integrate sensor-actuator loops for emergency shutdown execution.
Smart Sensors handle the majority of throughput; Predictive Maintenance is the fastest mover on share.
Technology:
Latency tolerance thresholds diverge sharply between centralized analytics and safety-critical control loops, forcing architecture bifurcation.
- Edge Computing:Sub-fifty-millisecond response requirements for emergency shutdown systems at remote petrochemical complexes drive localized processing deployment. These architectures bypass cloud dependency to satisfy Chemical Facility Anti-Terrorism Standards scrutiny of externally hosted operational technology data streams.
- Big Data Analytics:Batch-to-batch yield variation extraction at specialty chemical producers in Switzerland and the Netherlands demands high-throughput pattern recognition across historical process parameters. Unbundled software licensing from sensor hardware accelerates competitive tender access to cross-vertical algorithms.
- Wireless Communication:WirelessHART and ISA100.11a protocols converge with 5G private networks for sensor density in sprawling refinery complexes.
- Cloud Computing:Centralized platforms host non-time-critical optimization analytics with data residency compliance overhead.
Edge Computing commands the steepest expansion trajectory; Big Data Analytics captures the highest margin per deployment.
Application:
REACH substance tracking mandates force real-time data lineage from raw material intake through finished goods dispatch, concentrating investment in traceability-intensive workflows.
- Environmental Monitoring:Connected gas detection architectures transmit real-time concentration data to local emergency response agencies under EPA Risk Management Plan amendments. Ethylene and propylene producers on the US Gulf Coast accelerate retrofit timelines, prioritizing wireless mesh networks to minimize hot-work permits in classified areas.
- Supply Chain Management:ECHA REACH requirements extend IoT traceability from raw material receipt through finished goods dispatch at Belgian and Dutch chemical ports. Container-level sensor deployment tracks temperature excursions and tampering across multimodal chemical logistics.
- Quality Control:In-line spectroscopic sensors verify batch composition against specification thresholds.
- Energy Optimization:Scope 1 and Scope 2 carbon accounting under EU Green Deal protocols drives continuous emissions monitoring verification.
Environmental Monitoring absorbs the largest compliance-driven capital allocation; Supply Chain Management is climbing the fastest as traceability mandates tighten.
End User:
Process safety management inspection intensity varies by subsector, elevating digital record-keeping investments where OSHA and EPA scrutiny concentrates.
- Chemicals Manufacturers:Continuous emissions monitoring and hazardous area sensor density dominate capital allocation for EU Green Deal compliance. German facilities lead digital twin implementations for virtual commissioning of new production lines.
- Oil Refineries:Flammable atmosphere classification across cracking and reforming units demands TÜV-certified safety instrumented systems with extended procurement timelines. OSHA process safety management inspections probe digital record-keeping integrity, elevating tamper-evident blockchain logging demand.
- Pharmaceutical Companies:Batch record integrity and cleanroom environmental monitoring satisfy FDA and EMA validation requirements.
- Agriculture Sector:Fertilizer and agrochemical blending operations deploy intermediate-tier monitoring for storage and dispensing accuracy.
Chemicals Manufacturers represent the dominant installed base; Oil Refineries are gaining share fastest on regulatory enforcement intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement committees at multinational chemical conglomerates concentrate IoT upgrade spending in Germany, the United States, and China. These three markets absorb the majority of hazardous area sensor deployments and digital twin commissioning contracts. Facility operators in each geography face distinct regulatory compliance timelines that compress vendor selection windows.
United States
Ethylene and propylene producers on the US Gulf Coast accelerate wireless mesh network retrofits to satisfy EPA Risk Management Plan amendments. OSHA process safety management inspections now probe digital record-keeping integrity, elevating demand for tamper-evident data logging architectures. Houston and Port Arthur refining clusters anchor connected gas detection deployments that transmit real-time concentration data to local emergency response agencies.
Germany
BASF and Bayer facilities in Ludwigshafen and Leverkusen drive large-scale digital twin implementations for virtual commissioning of new production lines. EU Green Deal carbon accounting mandates force continuous emissions monitoring verification across Scope 1 and Scope 2 reporting. The country's TÜV-certified safety instrumented systems vendor pool dominates European retrofit programs for zone-zero hazardous area classifications.
China
State-owned petrochemical complexes in Ningbo and Dalian deploy edge computing architectures to satisfy sub-50-millisecond emergency shutdown latency requirements. The country's dual carbon goals compress upgrade cycles for legacy distributed control systems at coal-to-chemical facilities. Domestic sensor manufacturers compete with European imports for refinery automation contracts in the Yangtze River Delta.
Netherlands
Rotterdam chemical port operators extend IoT traceability from raw material receipt through finished goods dispatch to satisfy ECHA REACH substance tracking requirements. Antwerp-Rotterdam-Amsterdam cluster facilities prioritize wireless sensor density for tank farm monitoring and multimodal logistics tracking. Dutch specialty chemical producers unbundle sensor hardware from analytics software licenses through competitive tender processes.
Saudi Arabia
SABIC-affiliated complexes in Jubail Industrial City deploy 5G private networks for autonomous inspection robotics in flammable atmospheres. The kingdom's downstream expansion programs anchor predictive maintenance investments at ethylene crackers where unplanned downtime costs exceed two million dollars per incident. SABIC and partner facilities import TÜV-certified safety systems amid domestic engineering talent scarcity.
IoT in Chemical Industry Market Vendor Landscape
Player mix skews toward diversified industrial automation conglomerates with certified safety portfolios and mid-sized system integrators with regional project expertise. Market structure concentrates around vendors holding IEC 61508 functional safety validation for hazardous area deployments. Two strategic archetypes dominate: TÜV-certified full-stack providers bundling hardware, software, and commissioning services; and best-of-breed sensor specialists capturing unbundled procurement contracts from mid-sized batch manufacturers. Competitive moves center on strategic partnerships for 5G private network integration and geographic expansion through local system integrator channel relationships.
Within the certified full-stack tier, Siemens AG and ABB Ltd exemplify vendors leveraging safety instrumented system portfolios to dominate European and Asian retrofit programs respectively. Honeywell International Inc. occupies a position anchoring North American channel control through integrated distributed control platforms. These three industrial automation conglomerates represent the primary competitive set for large-scale digital twin implementations and predictive maintenance contracts at ethylene crackers and refinery complexes.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Honeywell International Inc. |
| General Electric |
| Emerson Electric Co |
| Rockwell Automation, Inc. |
| Yokogawa Electric Corporation |
| Schneider Electric SE |
| Mitsubishi Electric Corporation |
| Others |
Supply Flow & Price Mechanics
Eight-to-fourteen-month procurement timelines for IEC 61508-certified safety instrumented systems concentrate pricing power with TÜV-validated vendors while compressing margin flexibility for mid-sized system integrators competing against industrial automation conglomerates in hazardous area deployments.
Pricing Analysis
Cost-plus contracts indexed to silicon carbide sensor substrate pricing dominate equipment procurement for furnace monitoring applications above 400 degrees Celsius. Three-tier pricing structure across IEC 61508 SIL-3 certified, SIL-2 compliant, and non-certified hardware levels captures differentiation through functional safety validation depth and ATEX zone-zero suitability. Pricing pressure stems from REACH compliance deadlines accelerating competitive tender processes among Dutch and Belgian specialty chemical producers. Mid-sized batch manufacturers exhibit highest price sensitivity through unbundled hardware-software procurement, while ethylene cracker operators prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies prevail for standard WirelessHART sensor modules, whereas strategic stockpiling of silicon carbide temperature probes and TÜV-certified safety controllers buffers against fourteen-month lead-time volatility in European retrofit programs. Manufacturing concentration centers on Germany for functional safety engineering, China for wireless communication hardware, and Japan for high-temperature sensing substrates. Supply chain risk hinges on single-source vulnerability for TÜV-certified system architects amid talent scarcity across mid-sized integrators. Distribution runs through authorized channel partners holding hazardous area commissioning credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capital expenditure cycles in chemical processing are recovering from downstream demand troughs, with EU Green Deal carbon accounting mandates and EPA Risk Management Plan amendments synchronizing upgrade waves across German and US Gulf Coast facilities.
For Market Incumbents: Fortify certification moats by accelerating TÜV SIL-3 validation for edge computing architectures at remote petrochemical complexes. Deepen backward integration into silicon carbide sensor substrate production to offset raw material cost volatility. Channel control through certified system integrator networks defends against unbundled procurement patterns spreading among Dutch specialty chemical producers.
For New Entrants and Emerging Players: Lead with 5G private network integration capabilities for autonomous inspection robotics in flammable atmospheres, targeting SABIC-affiliated complexes in Jubail Industrial City where domestic engineering talent scarcity creates procurement gaps. White-space concentration exists in predictive maintenance algorithms for batch-to-batch yield variation at Swiss and Netherlands mid-tier producers. Partner with established safety instrumented system vendors for co-certification rather than pursuing independent IEC 61508 validation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across edge computing deployments at remote petrochemical complexes as latency requirements harden for emergency shutdown systems. Long-term viability favors vendors with integrated hardware-software-commissioning stacks capable of outcome-based service contracts. Acquisition targets should demonstrate TÜV certification pipelines and established relationships with German chemicals manufacturers. Watch for inflection when REACH substance tracking mandates extend beyond EU member states into Asian export markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Substrates | Captive silicon carbide supply secures margin against platinum price volatility in furnace monitoring. |
| 5G Private Network Deployment | Ultra-reliable low-latency communication enables sensor density beyond wired economics in refinery complexes. |
| Digital Twin Implementation | Virtual commissioning at BASF and Bayer facilities reduces physical prototyping for new production lines. |
| Outcome-Based Service Contracting | Vendor payments tied to uptime improvements align incentives with ethylene cracker operational priorities. |
| TÜV Certification Pipeline Investment | SIL-3 validation for edge architectures defends vendor pool position against procurement timeline compression. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant managers at ethylene crackers and refineries, procurement leads at specialty chemical producers, TÜV-certified system integrators, and technical R&D directors for sensor manufacturers. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings for industrial automation conglomerates, EPA Risk Management Plan amendment documentation, and ECHA REACH substance tracking guidance. Bottom-up equipment shipment analysis triangulated against top-down capital expenditure surveys across the analysis window.
Across the modeling period, value projections incorporated segmentation by product type, technology architecture, application workflow, and end-user subsector, with additional dimensioning by ATEX zone classification and functional safety integrity level. CAGRs were derived from historical deployment trajectories at BASF, Bayer, and US Gulf Coast facilities, calibrated against regulatory compliance deadline schedules and unplanned downtime cost benchmarks at ethylene crackers. Forecast inputs included WirelessHART and ISA100.11a protocol adoption curves, 5G private network infrastructure capex disclosures, and silicon carbide sensor replacement cycle compression.
Forecasts assume regulatory continuity in EU REACH, EPA Risk Management Plan, and OSHA process safety management regimes; material policy shifts would require re-modeling deployment timelines and certification requirements. Specific risk factors include IEC 61508 standard revision, Chemical Facility Anti-Terrorism Standards data residency enforcement, and EU Green Deal carbon accounting protocol changes. Revision becomes warranted when TÜV-certified engineering talent scarcity crosses thresholds that extend procurement timelines beyond facility upgrade windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Cellular IoT Module Market
Internet of Things (IoT)
Smart Home M2M Market
Internet of Things (IoT)
IIOT Gateway for Utility Market
Internet of Things (IoT)
Global Narrowband IoT Market
Internet of Things (IoT)
IoT Application Enablement Market
Internet of Things (IoT)
IoT Technology Market
Internet of Things (IoT)
Lora and Lorawan IoT Connectivity Market
Internet of Things (IoT)
Non-Terrestrial IoT Gateway Hardware and Software Market
Internet of Things (IoT)
LTE IoT Market
Internet of Things (IoT)
Global Embedded Security for Internet of Things Market
Internet of Things (IoT)
North America IoT Device Market
Internet of Things (IoT)
North America Industrial IoT Market
Internet of Things (IoT)
Automotive Internet of Things (IoT) Market
Internet of Things (IoT)
Cellular Machine to Machine Market
Internet of Things (IoT)
Internet of Things (IoT) Platform Market
Internet of Things (IoT)
Global IoT in Smart Cities Market