
 Connected Bottles Market | 2026-2036
Connected Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Bottles Market Analytics
Buyer concentration across corporate wellness programs is restructuring procurement patterns for connected bottles, with Fortune 500 employers consolidating vendor relationships into single-source contracts. Hidrate Inc. leverages its hospital system partnerships to anchor clinical hydration monitoring deployments. Thermos L.L.C. competes through retail channel control and licensed brand extensions in mass-market distribution. Moikit, LLC specializes in open-platform API architecture that allows enterprise clients to embed hydration data into existing employee health portals.
Connected bottles are sensor-enabled beverage containers integrating accelerometers, capacitive liquid sensors, and wireless transceivers to track fluid intake, temperature, and consumption timing, with data relayed via Bluetooth or NFC to companion mobile applications for hydration analytics. Smart Water Bottles dominate current volume due to straightforward utility and lower price positioning, while Smart Beverage Containers capture premium margin pools through wine and coffee-specific preservation technologies. IoT Connectivity segments are expanding fastest as cloud-based hydration dashboards gain traction among healthcare providers managing renal and diabetic patient populations.
FDA digital health guidance shapes clinical-grade connected bottle validation requirements, while FCC Part 15 regulations govern radio frequency emissions for Bluetooth and NFC modules in the United States. The EU Green Deal and REACH substance restrictions are pressuring manufacturers to eliminate certain plastics and heavy metals from sensor housings, redirecting R&D toward glass and stainless steel architectures. Stakeholders must monitor evolving cybersecurity standards for IoT medical devices as hydration data increasingly flows into electronic health records and insurance risk scoring models.
Market Dynamics
FDA digital health guidance is compressing certification timelines for clinical-grade hydration monitors, forcing manufacturers to restructure validation workflows around 510(k) premarket notification pathways.
Growth Catalysts
- Bluetooth Low Energy protocol refinements:Extended battery life in sensor modules enables continuous monitoring deployments in hospital systems across the United States and Germany.
- Corporate wellness mandates:Fortune 500 employers in Japan are consolidating vendor contracts into single-source hydration management platforms.
- Cloud-based hydration dashboards:Healthcare providers managing diabetic populations in the United States are integrating connected bottle data into electronic health records.
Market Restraints
- Sensor component concentration:Capacitive liquid sensor manufacturing concentrates in East Asian foundries, exposing supply chains to geopolitical friction.
- REACH substance restrictions:The EU Green Deal is eliminating certain plastics from sensor housings, forcing material transitions with 18-24 month qualification periods.
- Smartphone dependency:Companion app requirements exclude demographic segments without consistent mobile data access, particularly aging populations in rural Germany.
Strategic Opportunities
- Renal patient monitoring:Dialysis centers in Japan are piloting prescription-connected bottle programs with reimbursement pathway development.
- Open-platform API architecture:Enterprise clients are embedding hydration telemetry into existing employee health portals without proprietary system replacement.
- Insurance risk scoring integration:Life underwriters in the United States are testing hydration data as a behavioral input for policy pricing models.
Industry Challenges
- 510(k) validation timelines:Clinical-grade connected bottles face 14-18 month FDA review cycles for fluid intake measurement accuracy claims.
- Cybersecurity standard evolution:IoT medical device frameworks from NIST and ISO are shifting mid-development, forcing firmware architecture redesigns.
- Legacy EHR interoperability:Hydration data formats lack universal standards, requiring custom HL7 FHIR mapping for each hospital system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Bottles Market |
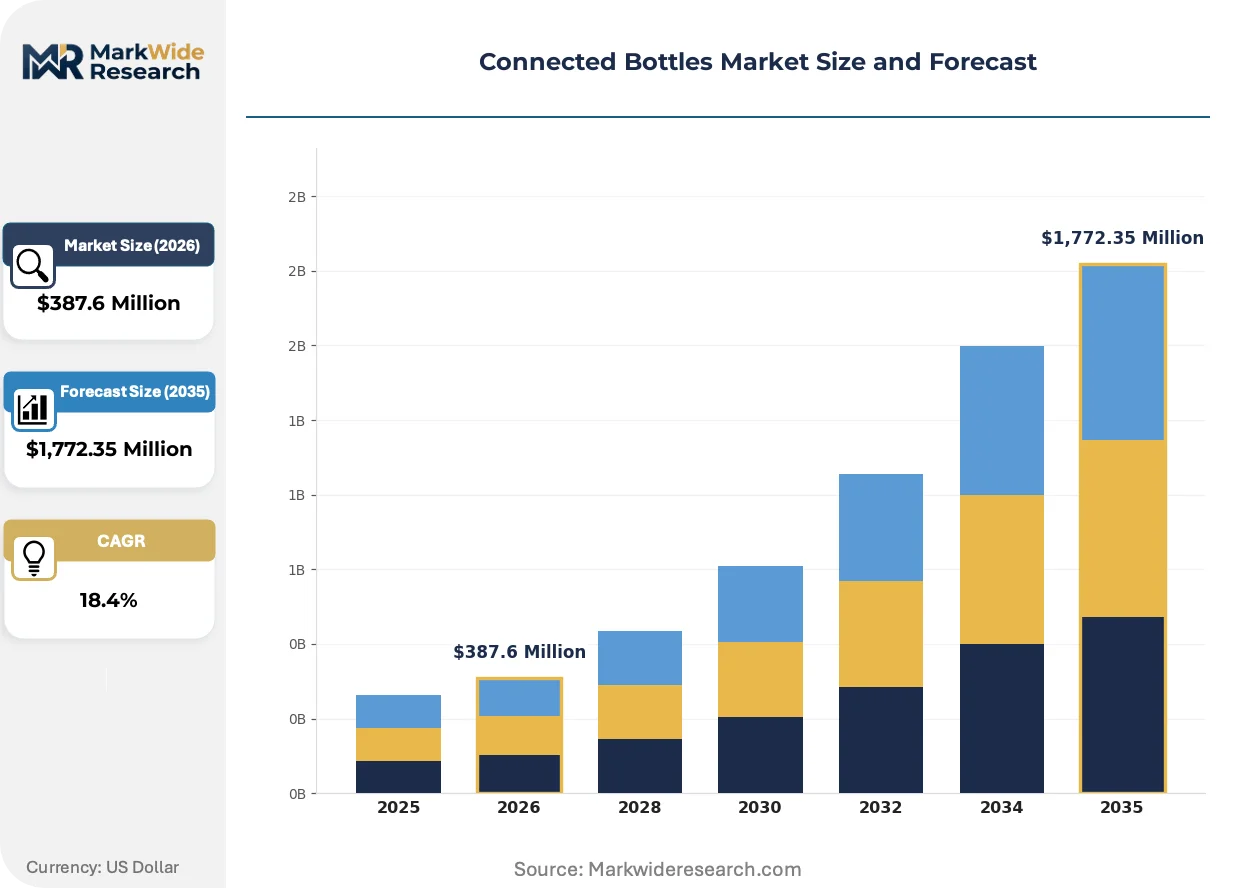
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Water Bottles, Infusion Bottles, Hydration Reminder Bottles, Smart Beverage Containers Technology: Bluetooth, NFC, RFID, IoT Connectivity End User: Consumers, Fitness Enthusiasts, Healthcare Providers, Corporate Wellness Programs Usage Scenario: Indoor Use, Outdoor Activities, Sports, Travel |
| Companies Covered | Hidrate Inc., HydraCoach, Inc., Thermos L.L.C., Caktus, Inc., Ecomo, Trago, Inc., Open-2, Moikit, LLC, Kuvée, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Bottles Market Evolving Landscape
Sensor miniaturization and edge computing architectures are compressing form factors while expanding real-time analytics capabilities. Three developments are restructuring competitive positioning.
Solid-state capacitive sensing is electrifying liquid measurement accuracy in compact bottle bases. Hospital systems in the United States are adopting these modules for inpatient fluid balance tracking. The technology is electrifying differentiation between clinical-grade and consumer-tier product lines.
REACH substance restrictions and EU Green Deal implementation are accelerating glass and stainless steel sensor housing development. Manufacturers are abandoning polycarbonate architectures to maintain CE marking eligibility. Wine and coffee preservation segments are most affected, with premium brands redesigning around metal-to-sensor sealing interfaces.
Employer procurement consolidation is compressing vendor selection cycles from multi-year pilots to 90-day proof-of-concept mandates. Corporate wellness administrators in Japan and Germany are replacing departmental point solutions with enterprise-wide platform contracts. This pattern is most visible in technology and financial services verticals with existing wearable ecosystem investments.
Connected Bottles Market Segmentation
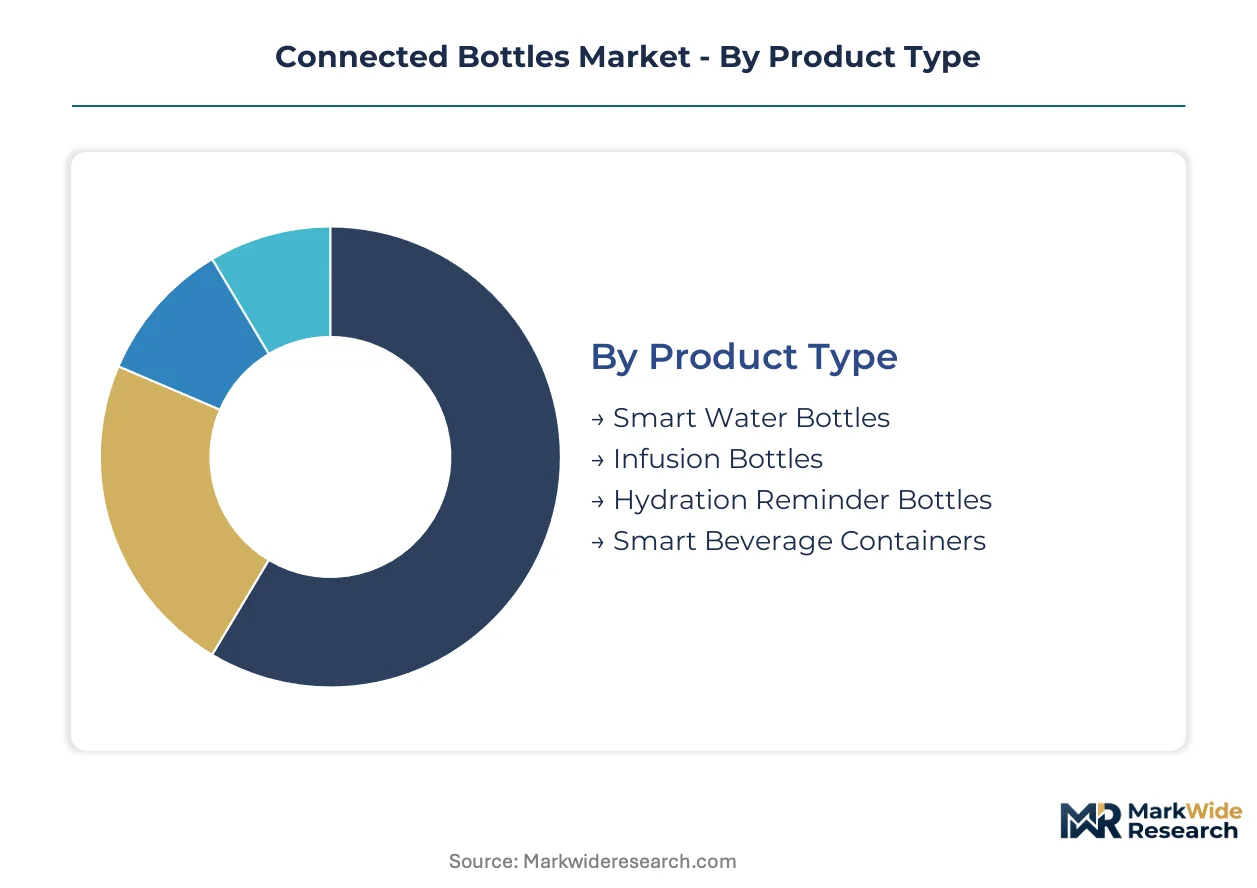
Segmentation in connected bottles determines regulatory pathways, margin structures, and procurement specifications. Product type dictates FDA 510(k) requirements versus consumer-grade certification. Technology choice shapes battery life, data security protocols, and hospital system interoperability.
Product Type:
FDA 510(k) premarket notification applies to clinical-grade hydration monitors, while FCC Part 15 governs consumer-tier radio frequency emissions. CE marking under EU MDR distinguishes prescription devices from wellness products.
- Smart Water Bottles:Accelerometer and capacitive liquid sensors track intake volume and timing through companion mobile applications. Corporate wellness programs in the United States consolidate procurement around these units for employee hydration mandates. Bluetooth Low Energy modules enable 6-12 month battery life without recharging.
- Smart Beverage Containers:Temperature preservation systems with vacuum insulation and precision thermal sensors maintain wine and coffee serving conditions. Premium pricing reflects materials compliance with REACH substance restrictions and EU Green Deal packaging directives. Glass and stainless steel architectures dominate redesign efforts.
- Infusion Bottles:Chambered compartments release flavor additives on schedule, appealing to fitness enthusiasts seeking electrolyte management.
- Hydration Reminder Bottles:LED and haptic alerts prompt consumption at programmed intervals, targeting aging demographics in Germany with medication timing integration.
Leading the category by volume: Smart Water Bottles. Growing fastest: Smart Beverage Containers.
Technology:
Radio protocol selection determines hospital deployment feasibility, cybersecurity audit scope, and insurance reimbursement eligibility. Power consumption and transmission range vary substantially across architectures.
- Bluetooth:Low Energy protocol refinements extend sensor module battery life to 18-24 months in continuous monitoring configurations. Hospital systems in Germany and the United States standardize on Bluetooth 5.x for inpatient fluid balance tracking. FCC Part 15 certification applies to all United States deployments.
- IoT Connectivity:Cloud-based hydration dashboards integrate with electronic health records through HL7 FHIR mapping. Healthcare providers managing diabetic populations in the United States prioritize this segment for remote patient monitoring programs. NIST cybersecurity frameworks govern firmware architecture.
- NFC:Near-field pairing enables tap-to-sync data transfer without persistent radio transmission, reducing electromagnetic interference concerns in clinical settings.
- RFID:Passive tag integration supports inventory management and loss prevention in institutional procurement environments.
Bluetooth dominates current procurement volumes. IoT Connectivity exhibits the steepest expansion trajectory as renal and diabetic monitoring applications mature.
End User:
Buyer type structures pricing tiers, contract duration, and data ownership terms. Enterprise procurement compresses vendor selection cycles while clinical deployments extend validation timelines.
- Healthcare Providers:Dialysis centers in Japan pilot prescription-connected bottle programs with reimbursement pathway development. FDA 510(k) validation requirements add 14-18 months to product launch timelines. HL7 FHIR interoperability demands custom mapping for each hospital system deployment.
- Corporate Wellness Programs:Fortune 500 employers consolidate vendor relationships into single-source contracts spanning 3-5 years. Technology and financial services verticals in Japan and Germany lead adoption with existing wearable ecosystem investments. Procurement administrators demand open-platform API architecture.
- Fitness Enthusiasts:Wearable ecosystem integration drives replacement cycles and brand loyalty in consumer channels.
- Consumers:Mass-market retail distribution competes on price positioning and licensed brand extensions.
Healthcare Providers command premium pricing tiers. Corporate Wellness Programs are gaining share fastest through procurement consolidation.
Usage Scenario:
Durability requirements, ingress protection ratings, and temperature operating ranges segment by deployment environment. Material selection and sensor sealing interfaces vary accordingly.
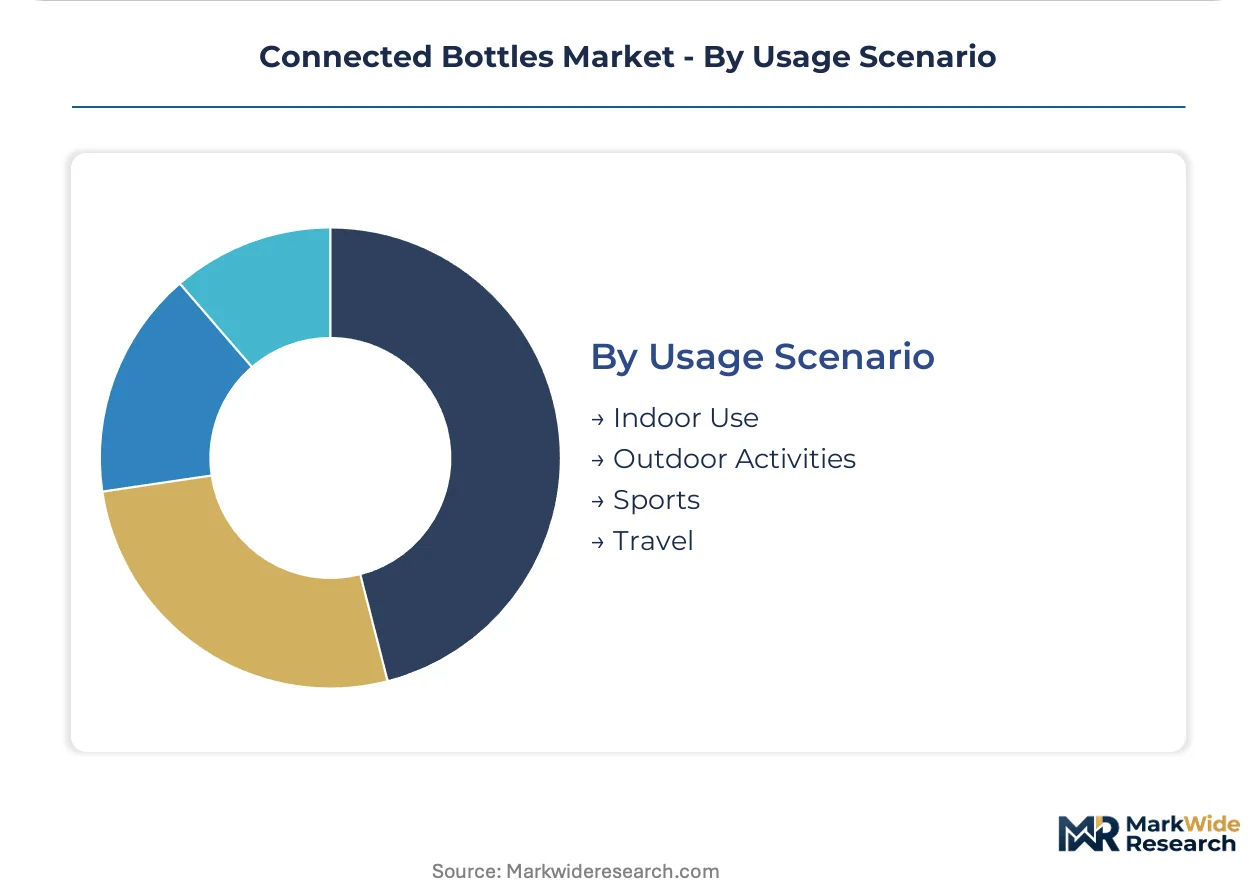
- Sports:Impact-resistant housings with IP67 ratings withstand repetitive motion and perspiration exposure. Fitness enthusiasts in the United States drive volume through specialty retail and direct-to-consumer channels. Accelerometer calibration accommodates dynamic movement artifacts.
- Outdoor Activities:Extended temperature ranges and solar charging compatibility support multi-day expedition use cases. Germany's aging rural populations face smartphone dependency barriers for companion app requirements.
- Indoor Use:Office and home environments prioritize aesthetic design and desktop footprint minimization.
- Travel:TSA-compliant empty bottle configurations and leak-proof sealing address airline carry-on restrictions.
Sports applications anchor current shipment volumes. Outdoor Activities are climbing fastest as expedition and adventure tourism segments recover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capacitive liquid sensor foundries in Taiwan and South Korea anchor component supply chains for connected bottle manufacturers serving clinical and consumer segments worldwide.
United States
Corporate wellness mandates at Fortune 500 employers and FDA 510(k) pathway development for clinical hydration monitors drive procurement concentration. FCC Part 15 governs Bluetooth and NFC radio frequency emissions for all connected bottle deployments. Boston and San Francisco Bay Area health technology clusters host pilot programs integrating connected bottle data into electronic health records for diabetic patient management.
Germany
Aging demographics and REACH substance restrictions on sensor housing materials reshape product design requirements for the EU market. EU MDR CE marking distinguishes prescription-grade hydration monitors from wellness products. Munich and Stuttgart industrial corridors concentrate R&D facilities transitioning polycarbonate architectures to glass and stainless steel compliance.
Japan
Dialysis center pilots for prescription-connected bottle programs and METI digital health reimbursement frameworks accelerate clinical adoption. Corporate wellness consolidation in technology and financial services verticals compresses vendor selection cycles. Tokyo and Osaka metropolitan areas anchor enterprise procurement decision-making for hydration management platforms.
United Kingdom
NHS digital health integration trials and GDPR-compliant data architecture requirements shape product validation for healthcare deployments. CSRD reporting obligations extend to corporate wellness program administrators evaluating vendor ESG credentials. London health technology clusters pilot cloud-based hydration dashboards for remote patient monitoring applications.
South Korea
MFDS medical device classification pathways and MFDS digital health sandbox programs enable accelerated clinical validation for hydration monitoring technologies. Semiconductor foundry concentration in Gyeonggi Province supports sensor module manufacturing for export markets. Seoul Capital Area corporate headquarters drive enterprise procurement of employee wellness platforms with wearable ecosystem integration.
Connected Bottles Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue clinical-grade certification and open-platform enterprise integration. The vendor base distributes across three tiers: hospital system specialists, retail channel incumbents, and API-first platform developers. Strategic archetypes include clinical validation leaders, mass-market distributors, and enterprise software integrators. Competitive moves center on FDA 510(k) premarket notification acceleration and single-source corporate contract consolidation.
Within the clinical-specialist archetype, Hidrate Inc. exemplifies hospital system partnership strategies, while Thermos L.L.C. occupies a position reflecting retail channel control and licensed brand extension capabilities. Moikit, LLC represents the open-platform tier, anchoring enterprise API architecture that enables hydration data embedding without proprietary system replacement. These three companies illustrate the competitive segmentation between clinical validation, consumer distribution, and enterprise software integration vectors.
| Leading Market Players |
|---|
| Hidrate Inc. |
| HydraCoach, Inc. |
| Thermos L.L.C. |
| Caktus, Inc. |
| Ecomo |
| Trago, Inc. |
| Open-2 |
| Moikit, LLC |
| Kuvée |
| Others |
Value Network & Pricing Analysis
Fortune 500 corporate wellness administrators anchor procurement volume and impose contract-based long-term offtake structures that compress spot-market pricing variability. Their single-source consolidation mandates favor vendors with captive sensor module production and direct hospital system partnerships, rewarding backward integration into capacitive liquid sensor manufacturing.
Pricing Analysis
Smart Water Bottles capture volume share at lower per-unit price points while Smart Beverage Containers command premium-mid-economy pricing differentiation through wine and coffee preservation technologies. FDA 510(k) certification tier and REACH-compliant material grade separate clinical-grade from consumer-tier price bands. Cost compression in the standard tier intensifies as East Asian foundry output expands. Corporate wellness programs exhibit lowest price sensitivity due to mandate-driven procurement, while mass-market retail consumers drive hardest bargain pressure.
Supply Chain Analysis
Trans-Pacific freight cost volatility and semiconductor logistics constraints elevate landed costs for sensor modules originating in Taiwan and South Korea. Capacitive liquid sensor foundries and Bluetooth Low Energy chip fabrication concentrate in these jurisdictions, with battery cell supply drawing from Japan and China. Single-source vulnerability in East Asian component manufacturing exposes manufacturers to geopolitical friction. Distribution runs through hospital system GPO contracts, retail channel partnerships, and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected bottle manufacturing is becoming a vertical-integration race as clinical-grade certification requirements and sensor supply concentration force players to pursue captive component production or exclusive foundry arrangements.
For Market Incumbents: To counter emerging API-first platform developers, Thermos L.L.C. and Hidrate Inc. should deepen backward integration into capacitive sensor manufacturing and secure exclusive capacity allocations at Taiwanese foundries. Hospital system partnership exclusivity clauses and FDA 510(k) validation acceleration represent critical defensive levers.
For New Entrants and Emerging Players: Rural aging demographics in Germany present an underserved buyer archetype with smartphone-dependency barriers that offline-first hydration reminder bottles could address. Dialysis center prescription programs in Japan offer the most penetrable clinical entry point. Open-platform API licensing to corporate wellness administrators provides a capital-efficient go-to-market angle.
For Investors and Strategic Acquirers: The window for entry favors clinical validation specialists with FDA submission momentum and existing HL7 FHIR interoperability capabilities. Long-term viability hinges on reimbursement pathway development for renal and diabetic monitoring applications. Watch for METI digital health framework expansions and CMS remote patient monitoring code additions as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Clinical-grade hydration monitors require 14-18 month validation cycles for fluid intake accuracy claims. |
| Backward Integration into Sensor Manufacturing | Captive capacitive liquid sensor production insulates against Taiwan and South Korea foundry concentration risks. |
| Open-Platform API Development | Enterprise clients embed hydration telemetry into existing employee health portals without proprietary replacement. |
| REACH-Compliant Material Transition | Glass and stainless steel sensor housings maintain CE marking eligibility under EU Green Deal implementation. |
| Hospital System Partnership Expansion | Dialysis centers in Japan pilot prescription-connected bottle programs with reimbursement pathway development. |
Research Methodology
FDA 510(k) premarket notification databases, FCC Part 15 equipment authorization records, and EU MDR CE marking registries formed the secondary backbone for regulatory pathway mapping. Primary interviews with connected bottle product managers, hospital biomedical engineers, corporate wellness procurement administrators, and capacitive sensor foundry operations directors validated technical specifications and demand patterns. Customs records from Taiwan and South Korea anchored component trade flow analysis. Bottom-up and top-down triangulation reconciled shipment data with end-user deployment surveys.
Bottom-up modeling aggregated unit economics across Bluetooth, IoT Connectivity, NFC, and RFID technology segments, while top-down validation checked aggregate market size against healthcare IT spending patterns and corporate wellness budget allocations. Segmentation dimensions included product type, radio protocol, end-user archetype, and usage scenario. CAGRs were derived from regression analysis of historical adoption curves in adjacent wearable health device categories, with FDA review cycle duration and reimbursement code expansion timelines as industry-specific forecast inputs.
Revisions become necessary when FDA digital health guidance shifts validation requirements, REACH substance restrictions expand to additional sensor housing materials, or NIST cybersecurity frameworks mandate firmware architecture redesigns mid-development. Stakeholders should weight assumptions against their own operating context and regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT at Workplace Market
Internet of Things (IoT)
Global IoT Devices Market
Internet of Things (IoT)
Global Pervasive Computing Technology Market
Internet of Things (IoT)
South Africa IoT Market
Internet of Things (IoT)
Middle East and Africa IoT Node and Gateway Market
Internet of Things (IoT)
IoT in Automotive Market
Internet of Things (IoT)
North America and Europe IoT Gateway Market
Internet of Things (IoT)
Smart Home M2M Market
Internet of Things (IoT)
IoT in Manufacturing Market
Internet of Things (IoT)
Smart Pool Systems Market
Internet of Things (IoT)
Global IoT Solutions and Services Market
Internet of Things (IoT)
Automotive Internet of Things (IoT) Market
Internet of Things (IoT)
Consumer IoT Market
Internet of Things (IoT)
Qatar Internet of Things (IoT) Market
Internet of Things (IoT)
Cellular M2M Market
Internet of Things (IoT)
Narrowband-Internet of Things (NB-IoT) Market