
 Narrowband IoT Enterprise Application Market | 2026-2036
Narrowband IoT Enterprise Application Market Size, Share, and Industry Trends Forecast 2026-2036
Narrowband IoT Enterprise Application Market Foresight
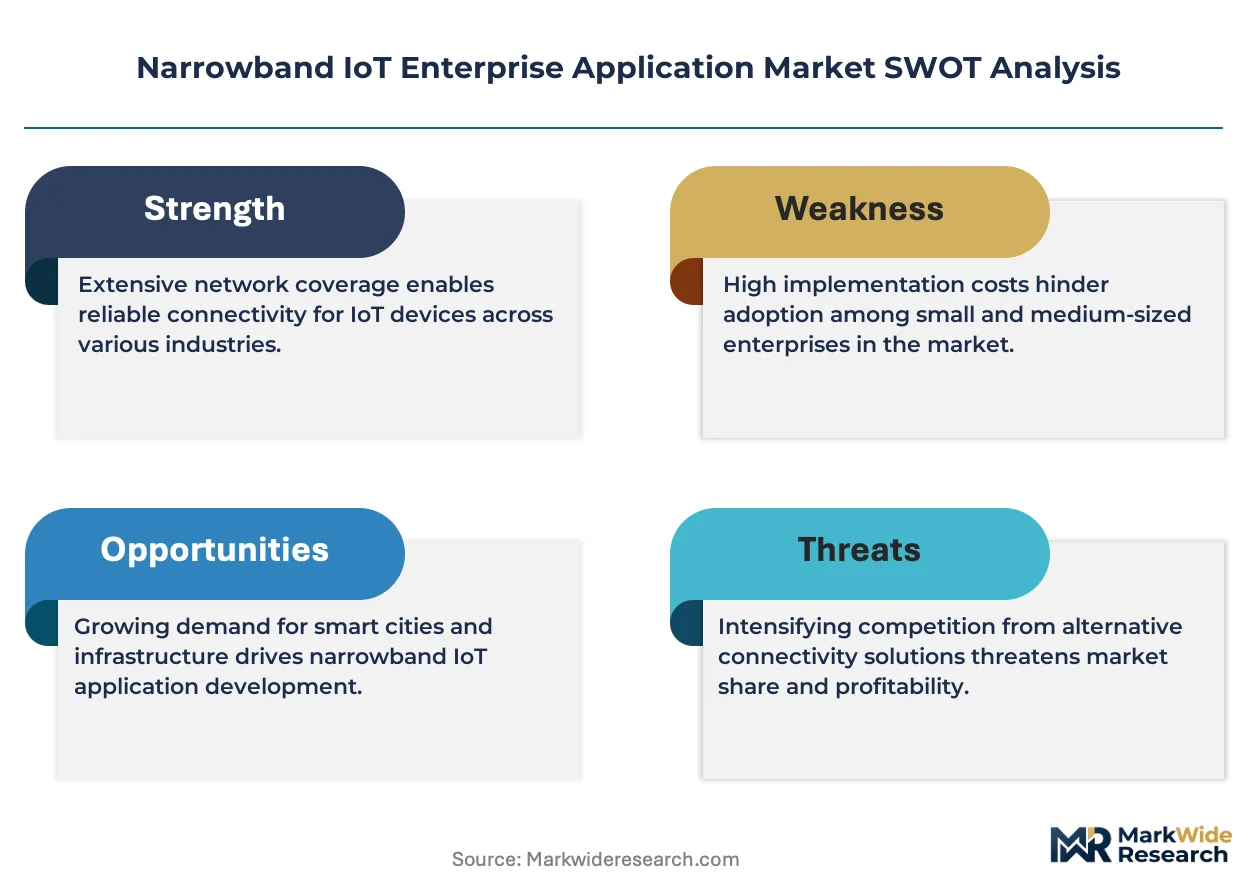
A shortage of RF systems engineers with 3GPP protocol expertise is unwinding deployment timelines for enterprise NB-IoT networks. Huawei Technologies Co., Ltd. anchors its position through captive semiconductor design for baseband modems. Nokia Corporation differentiates via end-to-end network infrastructure spanning radio access to core management platforms. Ericsson AB competes through specialized network slicing capabilities that isolate enterprise traffic from consumer mobile loads.
Narrowband IoT enterprise applications deploy low-power wide-area cellular connectivity operating in licensed spectrum below 1 GHz with 200 kHz channel bandwidth and uplink rates near 62.5 kbps, purpose-built for intermittent data transmission from distributed sensors and actuators. Smart metering leads volume deployment among application types as utilities prioritize automated revenue collection and grid visibility. Manufacturing end users represent the fastest-expanding vertical as predictive maintenance and environmental monitoring migrate from wired to wireless instrumentation. Hybrid cloud deployment models capture disproportionate margin pools by balancing real-time edge processing with centralized analytics governance.
The FCC governs spectrum allocation and device certification for unlicensed and licensed LPWAN operation in the United States, while ETSI harmonizes radio equipment standards across European member states and the EU AI Act increasingly shapes automated decision-making in connected enterprise systems. China's MIIT mandates domestic encryption standards for IoT devices accessing critical infrastructure networks. Stakeholders must weigh regulatory fragmentation against the cost of region-specific product variants when scaling cross-border deployments.
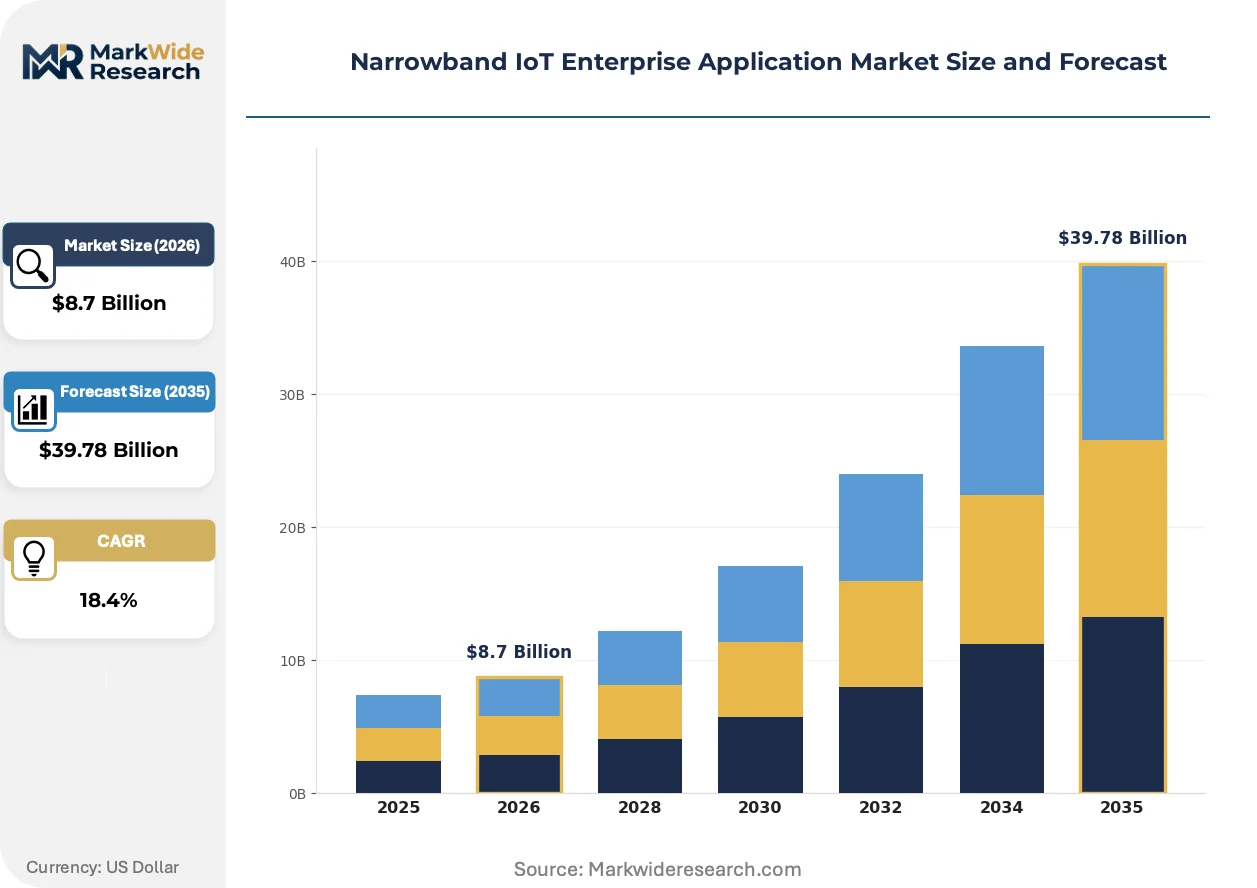
Market Dynamics
Carrier consolidation around 3GPP Release 13 standardization is compressing equipment vendor margins while accelerating deployment velocity for utility-scale smart metering networks. This structural force redirects value capture toward systems integrators capable of bridging fragmented radio access layer with enterprise IT infrastructure.
Growth Catalysts
- China MIIT domestic encryption mandates:State-mandated security protocols for critical infrastructure IoT create captive demand for certified module suppliers serving state-backed smart city procurement frameworks.
- Smart metering deployment acceleration:Utilities across multiple geographies prioritize automated revenue collection and distribution grid visibility, driving volume orders for NB-IoT-enabled electricity and gas meters.
- 3GPP Release 13 standard maturation:Harmonized radio specifications reduce interoperability testing burdens, shortening enterprise network commissioning cycles from months to weeks.
Market Restraints
- RF systems engineer scarcity:Specialized 3GPP protocol expertise concentrates in semiconductor hubs, unwinding deployment timelines for enterprise network builds lacking qualified integration teams.
- Licensed spectrum access costs:Sub-1 GHz band licensing fees impose recurring operational expenditures that erode business case economics for low-margin sensor applications.
- LoRaWAN substitution threat:Unlicensed LPWAN alternatives capture price-sensitive deployments where cellular reliability requirements fall below critical infrastructure thresholds.
Strategic Opportunities
- Manufacturing predictive maintenance expansion:Environmental monitoring and vibration sensing applications migrate from wired instrumentation to wireless NB-IoT endpoints, opening industrial verticals beyond utilities.
- Hybrid cloud orchestration services:Edge-to-core data pipeline management creates margin pools for systems integrators balancing real-time processing with centralized analytics governance.
- Germany BSI cybersecurity certification:Federal cybersecurity standards for critical infrastructure IoT shape procurement rules across EU member states, favoring pre-certified module vendors.
Industry Challenges
- Multi-regional certification complexity:FCC Part 15 and ETSI EN 301 559 testing requirements diverge on spurious emission limits, forcing region-specific hardware variants that fragment production scale.
- Legacy SCADA integration friction:Decades-old industrial control systems lack native IP connectivity, requiring protocol gateway layers that add latency and failure points to NB-IoT sensor deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Narrowband IoT Enterprise Application Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Asset Tracking, Smart Metering, Smart Cities, Healthcare Monitoring End User: Utilities, Manufacturing, Transportation, Agriculture Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Technology: Bluetooth, Wi-Fi, Zigbee, Cellular |
| Companies Covered | Nokia Corporation, China Mobile Limited, Huawei Technologies Co., Ltd., AT&T Inc., Deutsche Telekom AG, Ericsson AB, Vodafone Group Plc, Telstra Corporation Limited, Qualcomm Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Narrowband IoT Enterprise Application Market Shifts & Advancements
Network slicing architectures are fragmenting the radio access layer into isolatable enterprise-grade service tiers, compressing the traditional boundary between carrier infrastructure and private operational technology networks.
Baseband modem functionality is decomposing from discrete chipsets into software-defined implementations running on commodity ARM cores. Semiconductor vendors including Huawei Technologies Co., Ltd. accelerate this transition through captive design of integrated modem-plus-application processor silicon. Manufacturing end users adopt these consolidated modules fastest, as predictive maintenance sensor nodes demand both connectivity and local edge inference within strict power budgets.
EU AI Act automated decision-making provisions are reshaping connected enterprise system governance. The regulation imposes documentation and human oversight requirements on sensor-driven industrial processes that trigger autonomous actuation. Smart metering deployments across European utilities face the steepest compliance burden, as remote disconnect and demand-response algorithms fall within scope of high-risk AI system classification.
Buyer concentration among national utility monopolies is consolidating procurement leverage, forcing module vendors toward multi-year framework agreements with price-down escalators. Direct carrier relationships are displacing traditional distribution channels for volume smart metering orders. This pattern concentrates most visibly in China, where State Grid Corporation procurement tenders specify carrier-locked NB-IoT modules with domestic encryption compliance as non-negotiable technical requirements.
Narrowband IoT Enterprise Application Market Segmentation
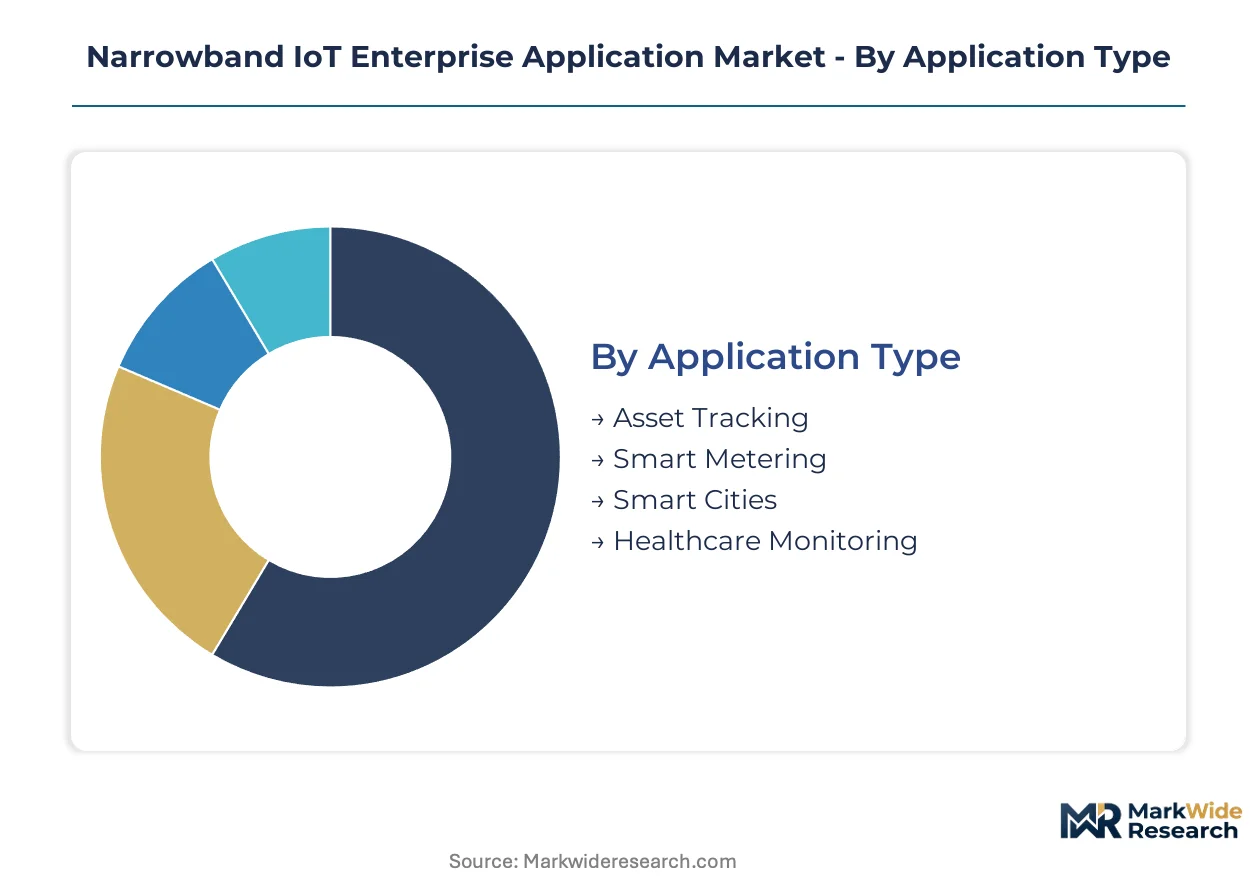
NB-IoT enterprise deployments fragment across application maturity and infrastructure ownership models. Channel strategy diverges sharply between utility-led volume procurement and industrial spot-buying patterns.
Application Type:
Carrier-direct procurement dominates smart metering and smart cities, while systems integrators capture asset tracking and healthcare monitoring through value-added resale.
- Smart Metering:Electricity and gas utilities deploy standardized NB-IoT modules for automated revenue collection and distribution grid visibility. State Grid Corporation procurement tenders in China specify carrier-locked modules with domestic encryption compliance as mandatory technical requirements.
- Smart Cities:Municipal sensor networks for environmental monitoring and waste management operate under state-backed procurement frameworks. MIIT mandates shape module certification requirements for critical infrastructure access across Chinese urban deployments.
- Asset Tracking:Logistics operators source through industrial distributors serving fleet management retrofit markets.
- Healthcare Monitoring:Medical device OEMs integrate NB-IoT connectivity through specialized IoT module vendors serving regulated health applications.
By volume, Smart Metering leads. By growth pace, Smart Cities is expanding most quickly.
End User:
Cost tier stratification separates capital-intensive utility deployments from price-sensitive agricultural sensor networks.
- Utilities:National electricity and gas distribution operators commission multi-year framework agreements with price-down escalators. Germany's BSI cybersecurity certification shapes procurement rules across EU member states for critical infrastructure IoT.
- Manufacturing:Predictive maintenance and environmental monitoring applications migrate from wired instrumentation to wireless NB-IoT endpoints. Vibration sensing and condition monitoring drive fastest vertical expansion beyond traditional utility applications.
- Transportation:Fleet operators prioritize low-cost connectivity for non-critical cargo tracking where cellular reliability requirements fall below infrastructure thresholds.
- Agriculture:Precision farming deployments face margin pressure from LoRaWAN substitution in soil moisture and livestock monitoring applications.
By installed base, Utilities dominates. By expansion trajectory, Manufacturing shows the steepest climb.
Deployment Model:
Customer type determines infrastructure ownership — regulated utilities favor on-premises control while mid-market industrial users adopt managed services.
- Hybrid Cloud:Edge-to-core data pipeline management balances real-time processing with centralized analytics governance. Manufacturing predictive maintenance applications adopt this model fastest as sensor nodes demand both connectivity and local edge inference within strict power budgets.
- Private Cloud:Critical infrastructure operators isolate enterprise traffic from consumer mobile loads through dedicated network slices. EU AI Act automated decision-making provisions impose documentation requirements on sensor-driven industrial processes triggering autonomous actuation.
- Public Cloud:Smart city municipalities leverage carrier-managed platforms for non-sensitive environmental monitoring.
- On-Premises:Legacy SCADA integration requirements drive utilities toward gateway-controlled private infrastructure.
By margin capture, Hybrid Cloud leads. By deployment velocity, Public Cloud is gaining share fastest.
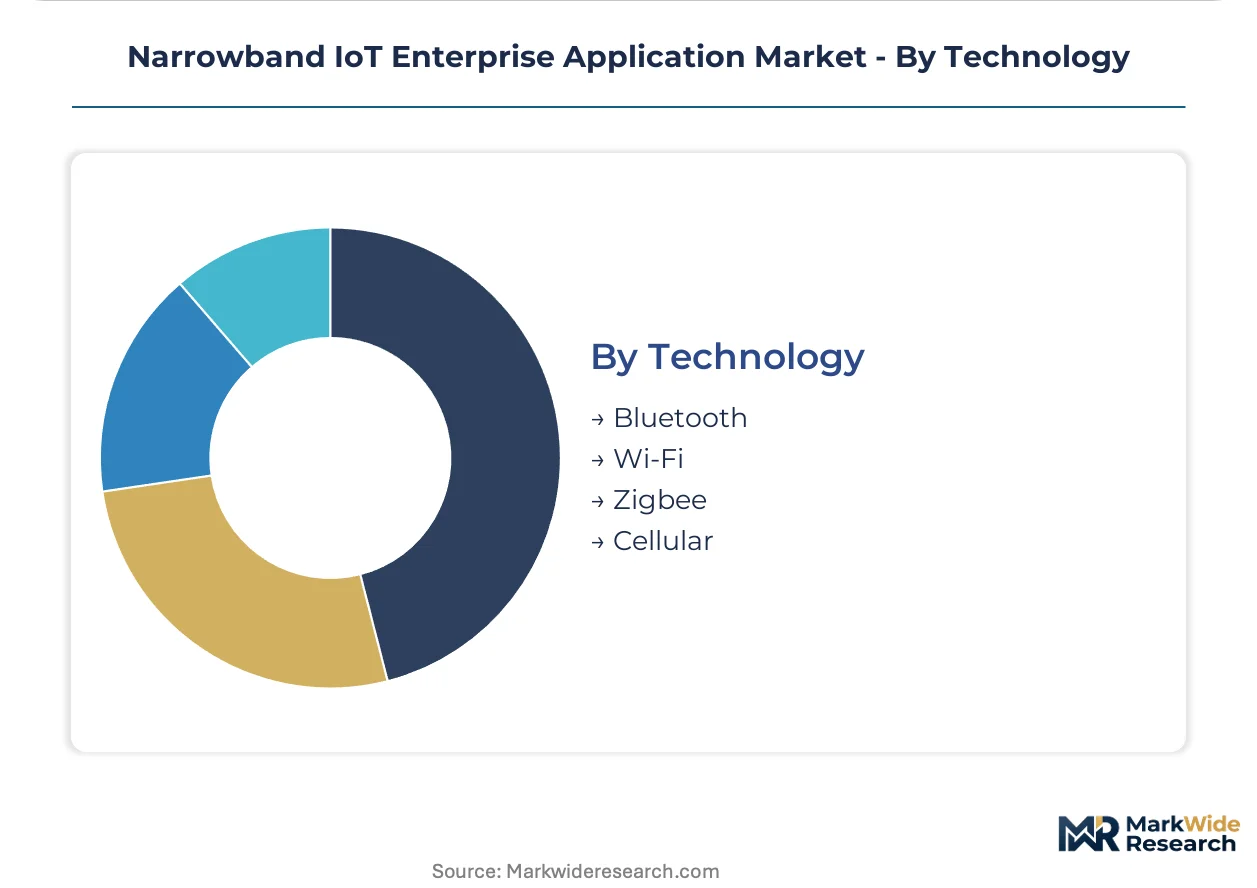
Technology:
Maturity curves separate licensed spectrum cellular from unlicensed alternatives competing on price.
- Cellular:NB-IoT operates in licensed sub-1 GHz spectrum with 200 kHz channel bandwidth and uplink rates near 62.5 kbps. 3GPP Release 13 standard maturation reduces interoperability testing burdens, shortening enterprise network commissioning cycles.
- Bluetooth:Short-range connectivity serves indoor asset tracking and healthcare wearable applications requiring proximity-based data exchange.
- Wi-Fi:High-bandwidth local area networks support video-capable surveillance and industrial gateway aggregation points.
- Zigbee:Mesh networking protocols capture building automation and smart lighting deployments with self-healing topology requirements.
By enterprise revenue concentration, Cellular leads. By unit volume in consumer-adjacent applications, Bluetooth shows the fastest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the dominant geography through state-backed smart city mandates and domestic encryption requirements that shape procurement frameworks for carrier-scale NB-IoT rollouts. Regulatory fragmentation across major economies forces module vendors toward region-specific hardware variants. Deployment velocity concentrates where licensed spectrum access aligns with critical infrastructure investment cycles.
China
State Grid Corporation procurement tenders specify carrier-locked NB-IoT modules with domestic encryption compliance as mandatory technical requirements. MIIT mandates shape certification requirements for critical infrastructure access across urban deployments. The Yangtze River Delta cluster hosts the densest concentration of module fabrication and systems integration capacity serving state-backed smart city frameworks.
Germany
Utilities prioritize automated revenue collection and distribution grid visibility through multi-year framework agreements with price-down escalators. BSI cybersecurity certification for critical infrastructure IoT shapes procurement rules across EU member states. Industrial sensor deployment concentrates in Baden-Württemberg's manufacturing belt where predictive maintenance applications migrate from wired to wireless instrumentation.
United States
FCC Part 15 governs spectrum allocation and device certification for licensed LPWAN operation while utilities accelerate smart metering deployment for grid visibility. FERC regulatory frameworks influence utility capital allocation toward automated metering infrastructure. The Pacific Northwest corridor hosts concentrated utility pilot programs testing NB-IoT integration with legacy SCADA systems.
Japan
METI industrial policy supports manufacturing predictive maintenance applications migrating from wired instrumentation to wireless NB-IoT endpoints. JIS standards harmonize radio equipment specifications for enterprise IoT deployments. The Chubu region around Nagoya anchors automotive supplier adoption of vibration sensing and condition monitoring applications.
Australia
Telstra Corporation's carrier-scale rollouts support municipal sensor networks for environmental monitoring and waste management under state-level procurement frameworks. The country's national communications regulator shapes spectrum allocation for licensed LPWAN operation. New South Wales hosts the most advanced utility smart metering pilots testing hybrid cloud orchestration for edge-to-core data pipelines.
Narrowband IoT Enterprise Application Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Narrowband IoT Enterprise Application Market. The integrated tier captures value through captive semiconductor design and end-to-end network infrastructure spanning radio access to core management platforms. Specialist competitors concentrate on network slicing capabilities and hybrid cloud orchestration services. Dominant competitive moves include strategic partnerships bridging fragmented radio access layers with enterprise IT infrastructure, and geographic expansion through carrier-direct relationships displacing traditional distribution channels.
Within the integrated infrastructure tier, Huawei Technologies Co., Ltd. and Nokia Corporation exemplify contrasting approaches to value capture. Huawei Technologies Co., Ltd. anchors a position through captive semiconductor design for baseband modems. Nokia Corporation occupies a position differentiated via end-to-end network infrastructure spanning radio access to core management platforms. Ericsson AB sits within the specialized capabilities segment, representing network slicing architectures that isolate enterprise traffic from consumer mobile loads.
| Leading Market Players |
|---|
| Nokia Corporation |
| China Mobile Limited |
| Huawei Technologies Co., Ltd. |
| AT&T Inc. |
| Deutsche Telekom AG |
| Ericsson AB |
| Vodafone Group Plc |
| Telstra Corporation Limited |
| Qualcomm Incorporated |
| Others |
Supply & Pricing Matrix
Carrier-scale module fabrication in China's Yangtze River Delta creates pronounced scale economies that compress unit costs while simultaneously concentrating supply-side bargaining power among a handful of integrated silicon vendors. This concentration shapes pricing floors for NB-IoT enterprise modules, where volume procurement frameworks from State Grid Corporation and similar national utilities extract year-over-year price concessions that ripple through component tiers.
Pricing Analysis
China-to-Europe price spreads of 15-25% reflect divergent certification burdens and logistics costs rather than underlying silicon differentiation. Three-tier pricing structure across BSI-certified premium modules, standard 3GPP-compliant units, and economy-grade unlicensed alternatives dominates enterprise procurement. Pricing pressure stems from LoRaWAN substitution in agricultural and non-critical asset tracking segments where cellular reliability premiums go unrecovered. Agricultural sensor networks exhibit highest price sensitivity, while German utilities under BSI mandates show lowest elasticity due to cybersecurity compliance requirements.
Supply Chain Analysis
Inventory cycles for baseband modem chipsets currently stretch 18-24 weeks as foundry capacity allocation prioritizes higher-margin 5G smartphone silicon over legacy NB-IoT designs. Supply concentrates in China for module assembly, Taiwan for baseband semiconductor fabrication, and Germany for BSI-certified systems integration. Raw material dependencies include gallium arsenide substrates, ceramic filter components, and lithium primary cells for endpoint power. Single-source vulnerability around Huawei's captive modem silicon creates procurement risk for Western equipment vendors. Distribution runs through carrier-direct frameworks for utility-scale orders and industrial distributors for spot-buy manufacturing applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NB-IoT enterprise applications sit in early-cycle expansion as manufacturing predictive maintenance applications migrate from wired instrumentation faster than prior forecast trajectories anticipated. 3GPP Release 13 standard maturation removes interoperability friction that previously gated industrial adoption.
For Market Incumbents: Secure multi-year framework agreements with national utility monopolies before procurement leverage consolidates further. Lock in semiconductor supply through backward integration into baseband modem design or exclusive foundry partnerships. Carrier-direct relationships displace traditional distribution channels fastest in China and Germany, threatening margin capture for vendors dependent on systems integrator intermediation.
For New Entrants and Emerging Players: Hybrid cloud orchestration services represent the most penetrable white space, as incumbent infrastructure vendors under-serve edge-to-core data pipeline management for mid-market manufacturing users. Target predictive maintenance applications in Japan's Chubu automotive supplier belt and Baden-Württemberg's industrial corridor where wireless sensor retrofit demand outpaces qualified integration capacity. Lead with managed services wrapping connectivity, edge inference, and SCADA gateway integration rather than competing on module hardware.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors systems integrators with certified cybersecurity credentials and carrier-neutral orchestration platforms. Long-term viability hinges on escaping commodity module manufacturing into recurring software and services revenue. Acquisition targets should demonstrate BSI or MIIT certification pipelines and established utility procurement relationships. Watch for inflection when manufacturing verticals exceed utilities in quarterly module shipment volumes, signaling segment diversification.
| Strategic Initiative | Industry Significance |
|---|---|
| BSI Cybersecurity Certification Investment | German federal standards shape procurement rules across EU member states for critical infrastructure IoT. |
| Carrier-Direct Procurement Framework | State Grid Corporation tenders specify carrier-locked modules with domestic encryption as mandatory requirements. |
| Hybrid Cloud Orchestration Platform | Edge-to-core data pipeline management captures margin pools from manufacturing predictive maintenance demand. |
| Software-Defined Baseband Transition | Modem functionality decomposing onto commodity ARM cores reduces silicon dependency and accelerates customization. |
| Network Slicing Capability Development | Ericsson's specialized architectures isolate enterprise traffic from consumer mobile loads, creating service differentiation. |
Research Methodology
A spread of perspectives from RF systems engineers, utility procurement directors, carrier network planners, and industrial IoT integration specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with semiconductor vendor technical leads and secondary validation through 3GPP release documentation, FCC Part 15 filings, ETSI EN 301 559 standards, and MIIT regulatory notices. Customs data on module shipments, carrier capex disclosures, and utility AMI deployment announcements provided volume anchors. Bottom-up unit economics triangulated against top-down addressable market sizing.
Segmentation dimensions modeled include application type, end-user vertical, deployment architecture, and geographic regulatory cluster across the projection horizon. CAGRs derive from fitted adoption curves calibrated to smart metering deployment trajectories and manufacturing sensor penetration benchmarks. Forecast inputs incorporate carrier spectrum auction timelines, BSI certification queue lengths, and SCADA integration project durations.
Forecasts assume regulatory continuity in FCC Part 15, ETSI harmonization, and MIIT domestic encryption regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Wireless Connected Devices Market
Internet of Things (IoT)
IoT Development Kit Market
Internet of Things (IoT)
Satellite IoT Market
Internet of Things (IoT)
Maritime Internet of Things Market
Internet of Things (IoT)
IoT Data Management Market
Internet of Things (IoT)
UK IoT Software Market
Internet of Things (IoT)
Airport Internet of Things Market
Internet of Things (IoT)
Global IoT Engineering Services Market
Internet of Things (IoT)
North America IoT Software Market
Internet of Things (IoT)
Global Narrowband IoT Market
Internet of Things (IoT)
Global 5G Industrial IOT Market
Internet of Things (IoT)
Cellular M2M Market
Internet of Things (IoT)
Enterprise IoT Market
Internet of Things (IoT)
Global IoT Based Asset Tracking and Monitoring Market
Internet of Things (IoT)
5G Internet of Things Market
Internet of Things (IoT)
North America Narrowband-Internet of Things (NB-IoT) Market