
 Asia-Pacific IoT Device Market | 2026-2036
Asia-Pacific IoT Device Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific IoT Device Market Insights
Subscription-based device management is pivoting how vendors monetize IoT hardware across the Asia-Pacific region. Samsung Electronics leverages its semiconductor foundry capacity to sustain captive chip supply for connected appliances. Xiaomi anchors its expansion through hyperlocal manufacturing partnerships that compress last-mile costs. Huawei competes aggressively on 5G-integrated module design, though geopolitical headwinds constrain its access to select national procurement channels.
Asia-Pacific IoT devices encompass networked endpoints with embedded sensors, microcontrollers, and radio transceivers operating across sub-1 GHz to 6 GHz spectra, designed to collect, transmit, and act upon environmental or operational data with minimal human intervention. Smart Sensors dominate unit shipments in industrial settings where predictive maintenance protocols demand continuous vibration, temperature, and pressure telemetry. LPWAN connectivity is displacing cellular in agricultural and utility deployments where battery life must exceed ten years and data payloads remain below fifty bytes per transmission. Wearable Devices represent the fastest-growing margin pool as health-monitoring integrations deepen employer-sponsored wellness program penetration.
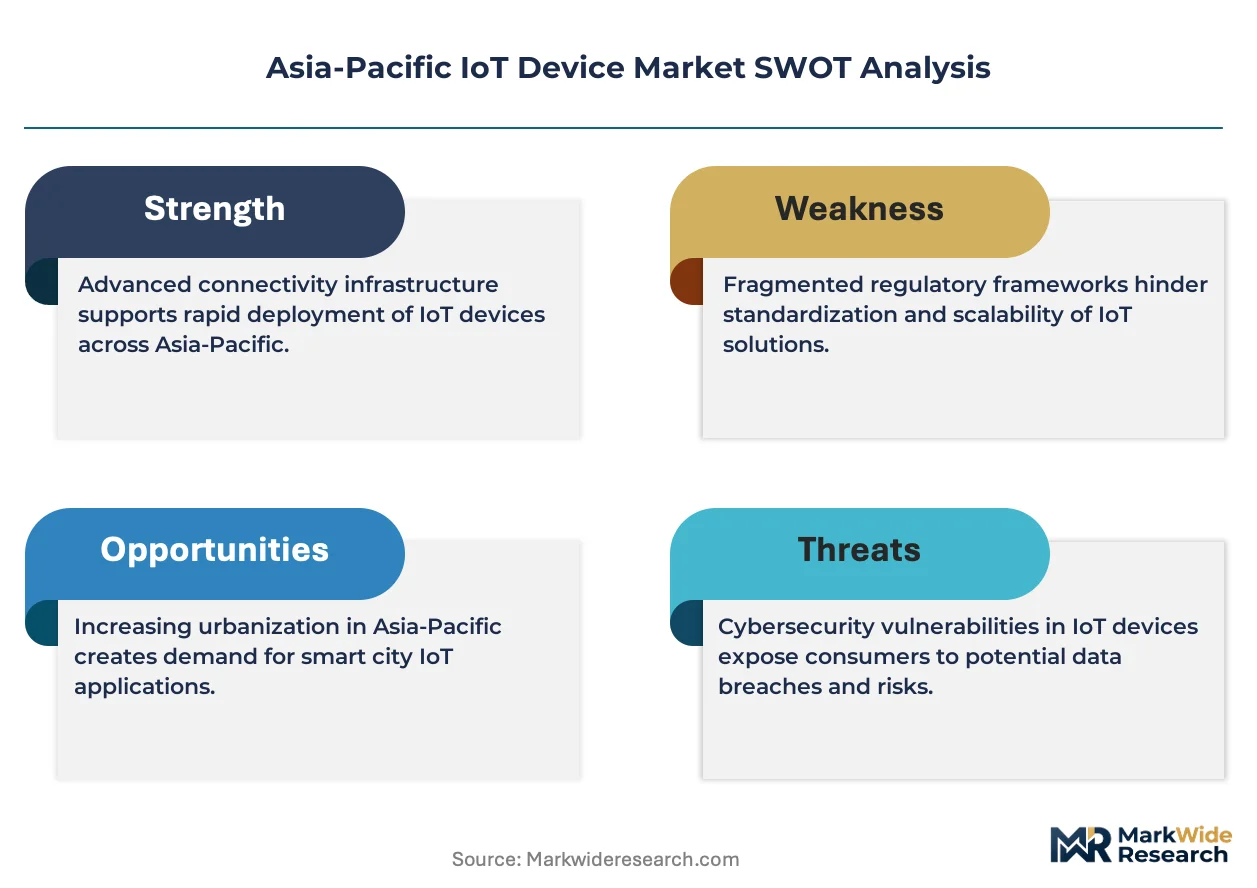
Japan's METI enforces JIS standards for IoT cybersecurity architecture, while China's SAMR administers GB certification mandates for radio-frequency equipment market entry. India's TRAI governs spectrum allocation for unlicensed LPWAN bands, directly shaping rural connectivity economics for agricultural sensor networks. Stakeholders must monitor evolving cross-border data-localization statutes that threaten cloud-dependent device orchestration models.
Market Dynamics
LPWAN spectrum allocation is redrawing connectivity economics across the Asia-Pacific region, compressing deployment costs for agricultural and utility sensor networks while forcing module vendors to reconfigure radio architectures around sub-GHz licensing frameworks.
Growth Catalysts
- India's PLI scheme for electronics manufacturing:Production-linked incentives are drawing module assembly into Gujarat and Tamil Nadu industrial corridors, shortening supply chains for domestic OEMs.
- Smart city infrastructure mandates:Southeast Asian metros are embedding sensor networks into traffic management and waste collection systems, creating anchored demand for environmental monitoring hardware.
- Edge AI chip integration:On-device inference capabilities are expanding addressable use cases for predictive maintenance in Japan's precision manufacturing sector.
Market Restraints
- Geopolitical module supply fragmentation:Restrictions on 5G-integrated component sourcing are forcing procurement teams to dual-source radio chipsets from Korean and Taiwanese foundries.
- TRAI spectrum auction pricing:India's unlicensed band fee structures are elevating total cost of ownership for rural agricultural sensor deployments below ten-thousand-unit scale.
- Silicon carbide substrate scarcity:Power-efficient microcontroller substrates face twelve-month lead times, throttling shipment volumes for battery-optimized endpoints.
Strategic Opportunities
- Vietnam's industrial zone digitization:Manufacturing foreign direct investment is outpacing local sensor vendor capacity, opening white space for predictive maintenance service bundles.
- Health-monitoring wearable integration:Employer-sponsored wellness programs in Australia are subsidizing biometric device procurement, expanding margin pools beyond consumer retail.
- China's dual carbon metering mandates:GB standards for energy consumption telemetry are compelling commercial building retrofits, creating retrofit-focused hardware demand.
Industry Challenges
- Cross-border data localization compliance:Divergent cloud storage statutes across ASEAN member states are fragmenting device orchestration architectures and elevating legal review costs.
- Legacy OT system integration:Industrial sensor deployments in Japan's steel and chemical sectors require protocol translation layers that extend implementation timelines by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific IoT Device Market |
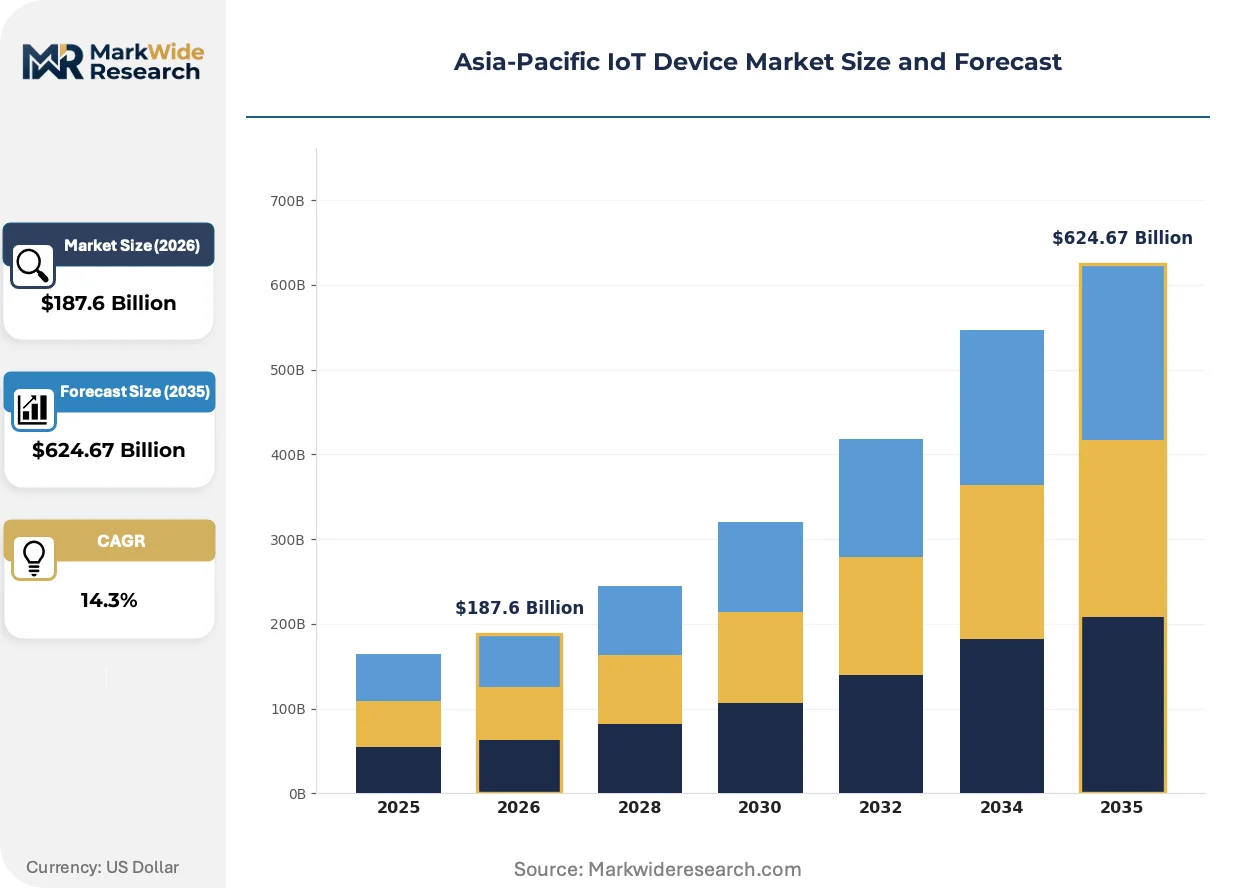
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $624.67 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smart Sensors, Gateways, Wearable Devices, Smart Home Appliances Application: Industrial Automation, Healthcare, Smart Cities, Agriculture Connectivity Technology: Wi-Fi, Bluetooth, Zigbee, LPWAN End User: Manufacturing, Retail, Transportation, Utilities |
| Companies Covered | Lenovo, Intel, Samsung Electronics, ASUS, LG Electronics, Huawei, Xiaomi, Alibaba Cloud, Apple, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific IoT Device Market Trends and Innovations
Hardware-software decoupling is accelerating across the Asia-Pacific IoT stack, enabling subscription-based feature activation and compressing upgrade cycles for deployed endpoints.
Software-defined radio architectures are modularizing connectivity module design, allowing single hardware SKUs to address multiple regional spectrum certifications through firmware configuration. Agricultural OEMs in Thailand and Indonesia are adopting these platforms to simplify procurement across heterogeneous national licensing environments. This modularizing approach is collapsing the traditional eighteen-month hardware redesign cycle into quarterly firmware release schedules.
China's SAMR has tightened GB certification timelines for radio-frequency equipment, compressing market entry windows from nine months to five months for compliant submissions. Manufacturers with pre-certified module platforms are capturing shelf space faster than competitors pursuing de novo approvals. India's industrial sensor vendors are responding by front-loading certification investments before product finalization.
After-sales service unbundling is disrupting traditional hardware-margin models across Australian and Japanese enterprise accounts. Buyers are separating device procurement from managed connectivity contracts, pressuring vendors to compete on pure hardware cost while monetizing through recurring platform fees. This shift is most visible in smart building deployments across Sydney and Melbourne commercial real estate portfolios.
Asia-Pacific IoT Device Market Segmentation
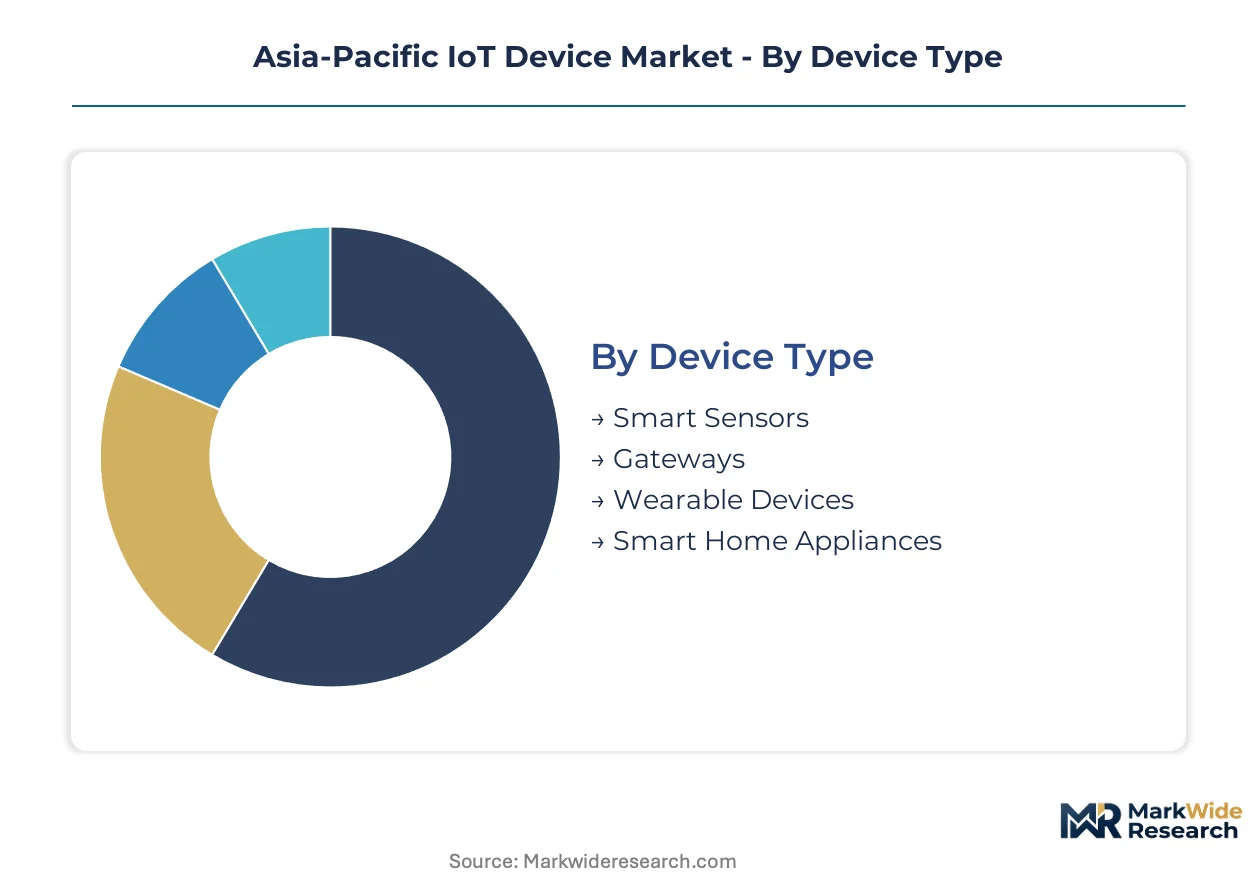
Device classification in the Asia-Pacific IoT market determines procurement economics, certification pathways, and integration complexity for buyers across divergent national regulatory environments. Segment boundaries are blurring as software-defined architectures enable single hardware platforms to serve multiple application contexts through firmware reconfiguration.
Device Type:
Buyers prioritize power budget, data granularity, and edge processing capability when selecting device categories for deployment.
- Smart Sensors:Embedded microelectromechanical systems capture vibration, temperature, and pressure telemetry with sub-milliwatt power draw. Demand concentrates in Japan's precision manufacturing corridors where predictive maintenance protocols mandate continuous equipment monitoring. METI's JIS cybersecurity standards elevate procurement scrutiny for industrial-grade units.
- Wearable Devices:Biometric monitoring endpoints integrate photoplethysmography and accelerometer arrays for employer-sponsored wellness programs. Australia's commercial real estate and healthcare sectors are absorbing volume fastest as building operators subsidize workforce health monitoring deployments.
- Gateways:Edge aggregation nodes translate heterogeneous sensor protocols into unified data streams.
- Smart Home Appliances:Connected white goods with embedded telemetry for energy consumption reporting.
Volume sits with Smart Sensors; growth tilts toward Wearable Devices.
Application:
Deployment context shapes connectivity requirements, regulatory exposure, and service revenue potential for hardware vendors.
- Industrial Automation:Factory-floor sensor networks enable real-time production optimization and predictive maintenance scheduling. China's GB standards for energy consumption telemetry are compelling retrofit demand across manufacturing facilities in Guangdong and Jiangsu provinces. Dual carbon metering mandates tighten hardware specification requirements.
- Smart Cities:Municipal infrastructure deployments span traffic management, waste collection, and environmental monitoring systems. Southeast Asian metros including Bangkok, Jakarta, and Ho Chi Minh City are anchoring procurement volume through sovereign infrastructure mandates. LPWAN spectrum allocation in unlicensed bands compresses connectivity economics for large-scale sensor grids.
- Healthcare:Remote patient monitoring and clinical asset tracking applications.
- Agriculture:Soil moisture and microclimate sensing for precision irrigation in water-stressed regions.
Procurement scale favors Industrial Automation; expansion velocity favors Smart Cities.
Connectivity Technology:
Spectrum licensing costs and battery life requirements dominate technology selection for Asia-Pacific deployments.
- LPWAN:Sub-GHz unlicensed and licensed narrowband protocols deliver decade-plus battery life for sparse data transmission. India's TRAI governs spectrum fees for agricultural sensor networks below ten-thousand-unit scale, directly shaping total cost of ownership economics. Module vendors are reconfiguring radio architectures around heterogeneous national licensing frameworks.
- Wi-Fi:High-throughput local area connectivity for smart home and enterprise environments with reliable power access.
- Bluetooth:Short-range personal area networking for wearable device pairing and indoor positioning.
- Zigbee:Mesh topology protocols for building automation and smart lighting control systems.
Deployment breadth rests with LPWAN; margin capture concentrates in Wi-Fi for premium enterprise accounts.
End User:
Organizational scale and technical integration maturity determine purchasing process complexity and contract structure preferences.
- Manufacturing:Discrete and process industries deploy sensor networks for quality control and supply chain visibility. Vietnam's industrial zone digitization is outpacing local vendor capacity, creating white space for predictive maintenance service bundles. Foreign direct investment flows are accelerating hardware procurement timelines.
- Utilities:Electricity, water, and gas distribution operators monitor grid assets and consumption patterns.
- Transportation:Fleet management and logistics optimization applications across road, rail, and maritime modes.
- Retail:Inventory tracking, cold chain monitoring, and customer experience analytics deployments.
Contract value aggregates in Manufacturing; recurring revenue potential concentrates in Utilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of LPWAN modules and sensor assemblies consumed across Asia-Pacific, while India and Southeast Asian nations absorb hardware for smart city and industrial digitization deployments. Domestic production capacity in India and Vietnam is expanding through government incentive programs, though component-level dependencies on Chinese and Taiwanese foundries persist.
China
GB standards for IoT interoperability and dual carbon metering mandates are driving hardware procurement across commercial building retrofits and manufacturing facilities. SAMR administers compressed five-month certification timelines for radio-frequency equipment, advantaging vendors with pre-certified module platforms. Guangdong and Jiangsu provinces anchor industrial sensor demand as manufacturing digitization accelerates.
Japan
Precision manufacturing corridors in Nagoya and Osaka deploy continuous vibration and temperature telemetry for predictive maintenance protocols. METI enforces JIS cybersecurity architecture standards that elevate procurement scrutiny for industrial-grade units. Edge AI chip integration is expanding addressable use cases across Japan's automotive and electronics assembly sectors.
India
PLI scheme incentives are drawing module assembly into Gujarat and Tamil Nadu industrial corridors, shortening supply chains for domestic OEMs. TRAI governs spectrum allocation for unlicensed LPWAN bands, directly shaping rural connectivity economics for agricultural sensor networks below ten-thousand-unit scale. Manufacturing foreign direct investment is outpacing local sensor vendor capacity.
Australia
Employer-sponsored wellness programs are subsidizing biometric wearable procurement across Sydney and Melbourne commercial real estate portfolios. After-sales service unbundling is separating device procurement from managed connectivity contracts, pressuring vendors to compete on pure hardware cost. Health-monitoring integrations are expanding margin pools beyond consumer retail channels.
Vietnam
Industrial zone digitization is accelerating hardware procurement timelines as manufacturing foreign direct investment flows expand. Foreign-owned factories in northern provinces are deploying predictive maintenance sensor networks faster than local vendor capacity can supply. White space exists for bundled predictive maintenance services targeting discrete manufacturing operations.
Asia-Pacific IoT Device Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Asia-Pacific IoT device market, creating a tiered structure where semiconductor foundries and integrated electronics conglomerates occupy distinct competitive positions. The vendor base spans captive chip producers, hyperlocal manufacturing specialists, and cloud-integrated platform operators. Three archetypes dominate: foundry-integrated conglomerates with captive silicon supply, regionally focused hardware assemblers leveraging local incentive schemes, and connectivity-module specialists competing on radio architecture flexibility. Capacity expansion into India and Vietnam industrial corridors and strategic partnerships around software-defined radio platforms represent the dominant competitive moves reshaping positioning.
Among foundry-integrated conglomerates, Samsung Electronics and Huawei occupy positions defined by semiconductor self-sufficiency and 5G-integrated module design capabilities respectively. Xiaomi exemplifies the hyperlocal manufacturing archetype through partnerships that compress last-mile distribution economics across diverse national markets. Intel represents the module-specialist positioning, with its offerings sitting within connectivity technology tiers where firmware-configurable radio architectures address heterogeneous regional licensing frameworks.
| Leading Market Players |
|---|
| Lenovo |
| Intel |
| Samsung Electronics |
| ASUS |
| LG Electronics |
| Huawei |
| Xiaomi |
| Alibaba Cloud |
| Apple |
| Others |
Pricing and Supply Chain Analysis
Software-defined radio migration is collapsing module redesign cycles from eighteen months to quarterly firmware releases while simultaneously concentrating cost advantages with vendors holding pre-certified platform portfolios. This technology shift feeds pricing power toward firmware-configurable suppliers and away from de novo hardware designers.
Pricing Analysis
Margin tightening in standard-grade LPWAN modules reflects India's TRAI spectrum fee structures elevating total cost of ownership for sub-ten-thousand-unit agricultural deployments. Three-tier pricing structure across premium certified, standard compliant, and economy unlicensed tiers separates procurement economics by certification grade and volume scale. Cost compression accelerates as Chinese SAMR compresses GB certification timelines from nine to five months, advantaging pre-certified vendors. Manufacturing buyers in Vietnam's industrial zones exhibit highest price sensitivity; Japanese precision manufacturing corridors show lowest sensitivity due to METI cybersecurity compliance premiums.
Supply Chain Analysis
Silicon carbide substrate supply rests on Taiwanese and Japanese specialty material producers, with twelve-month lead times throttling power-efficient microcontroller shipments. Module assembly draws from China, Vietnam, and India as PLI schemes reshape regional production footprints. Radio chipset sourcing hinges on Korean and Taiwanese foundries amid geopolitical fragmentation risks. Distribution runs through electronics manufacturing service providers anchoring in Guangdong and Tamil Nadu industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific IoT device manufacturing is consolidating around firmware-configurable platform holders as certification compression and silicon scarcity eliminate sub-scale hardware designers.
For Market Incumbents: Acquire pre-certified software-defined radio module platforms to compress competitor entry windows under SAMR's five-month approval timelines. Defend margin position by deepening captive silicon supply arrangements before Korean foundry allocation tightens further. Lock long-term substrate contracts with Taiwanese silicon carbide producers to isolate from twelve-month lead time volatility. For New Entrants and Emerging Players: Enter via Vietnam's industrial zone digitization white space where manufacturing FDI outpaces local predictive maintenance vendor capacity. Target bundled sensor-plus-service offerings for discrete manufacturing foreign-owned factories in northern provinces. Anchor go-to-market through electronics manufacturing service partnerships in Tamil Nadu to leverage India's PLI scheme logistics advantages. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to foundry-integrated conglomerates seeking firmware-configurable radio capabilities. Long-term viability favors asset-light designers with certification front-loading discipline over capital-heavy pure-play hardware assemblers. Watch SAMR certification timeline compression as inflection signal for platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Platform Acquisition | Compresses competitor entry windows under SAMR's compressed five-month GB certification timelines. |
| Silicon Carbide Substrate Contracting | Isolates production from Taiwanese and Japanese specialty material twelve-month lead time constraints. |
| India PLI Scheme Manufacturing Expansion | Captures production-linked incentives in Gujarat and Tamil Nadu industrial corridors. |
| Predictive Maintenance Service Bundling | Addresses white space in Vietnam's industrial zones where FDI outpaces local vendor capacity. |
| Pre-Certification Investment Front-Loading | Positions for SAMR's compressed approval timelines before product finalization cycles complete. |
Research Methodology
Document review covered customs trade databases, SAMR certification filings, and TRAI spectrum allocation records, complemented by interviews with module vendor product managers, electronics manufacturing service procurement leads, and industrial sensor network deployment engineers. Secondary validation drew from METI JIS standard publications, semiconductor foundry capex disclosures, and smart city infrastructure procurement announcements. Bottom-up unit shipment estimates triangulated against top-down regional demand aggregation.
Unit and value projections across the analysis window segmented by device type, connectivity technology, application vertical, and national regulatory cluster. CAGRs derived from fitted growth curves calibrated to PLI scheme incentive trajectories and GB standard implementation timelines. Forecast inputs incorporated TRAI spectrum fee structure evolution and silicon carbide substrate supply constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical module supply fragmentation and cross-border data localization statute divergence. Projections reflect assumptions around certification timeline stability and foundry capacity allocation continuity. A small set of triggers—SAMR regulatory acceleration, TRAI fee restructuring, and substrate supply shocks—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Market
Internet of Things (IoT)
Wifi IoT Market
Internet of Things (IoT)
IoT Software Market
Internet of Things (IoT)
Global IoT Connectivity Market
Internet of Things (IoT)
Automotive Internet of Things (IoT) Market
Internet of Things (IoT)
Global Internet of Things Technology Market
Internet of Things (IoT)
North America IoT Device Market
Internet of Things (IoT)
IoT Data Management Market
Internet of Things (IoT)
Internet of Things (IoT) in Utilities Market
Internet of Things (IoT)
Internet of Things (IoT) Platform Market
Internet of Things (IoT)
Connected Bottles Market
Internet of Things (IoT)
IoT for Cold Chain Monitoring Market
Internet of Things (IoT)
Consumer IoT Market
Internet of Things (IoT)
IoT Communication Protocol Market
Internet of Things (IoT)
Global IOT Connectivity Management Platform (CMP) Market
Internet of Things (IoT)
Smart Sprinkler Controller Market