
 Global IoT in Smart Cities Market | 2026-2036
Global IoT in Smart Cities Market Size, Share, and Industry Trends Forecast 2026-2036
Global IoT in Smart Cities Market Foresight
Sensor manufacturing clusters in South Korea and Taiwan are restructuring supply chains for edge-computing nodes destined for urban deployments. Cisco Systems leverages its networking heritage to dominate secure municipal backbones, while Huawei Technologies competes aggressively on 5G-integrated smart pole systems across Middle Eastern and Southeast Asian contracts. Siemens anchors its position through building-automation-to-grid vertical integration, giving it captive demand from energy management segments.
IoT in smart cities encompasses networked sensor arrays, communication gateways, and analytics platforms that collect, transmit, and process real-time urban data through protocols including LoRaWAN, NB-IoT, and MQTT at latency thresholds under 50 milliseconds for critical safety applications. The primary purpose is optimizing resource allocation, reducing operational expenditure, and enabling predictive maintenance across municipal infrastructure. Smart lighting and traffic management within solution offerings capture disproportionate margin pools due to their mature procurement standards and measurable ROI frameworks, while environmental monitoring represents the fastest-expanding category as heat island and air quality mandates tighten. Cloud-based deployment dominates current installations, though edge computing is displacing centralized architectures where sub-second response times matter for public safety and autonomous vehicle coordination.
The FCC in the United States governs spectrum allocation for unlicensed IoT bands, directly determining which communication protocols cities can deploy at scale, while the EU AI Act and GDPR impose algorithmic transparency and data residency requirements that reshape vendor qualification criteria across European tenders. ISO 37120 and IEC 62040 standards provide the technical baselines for interoperability and power resilience that procurement officers embed into RFP specifications. Stakeholders must monitor how national cybersecurity certifications fragment into non-mutually-recognized regimes, as this divergence threatens to partition vendor addressable markets and inflate compliance costs for platform providers seeking multi-country deployment scale.
Market Dynamics
Municipal procurement officers now prioritize latency-critical edge architectures over cloud-first designs, compressing vendor qualification timelines and fragmenting deployment standards across jurisdictions.
Growth Catalysts
- EU Green Deal mandates:Binding decarbonization targets for urban heat islands are accelerating sensor deployments for microclimate monitoring and adaptive street lighting retrofits across German and French municipalities.
- Autonomous vehicle corridors:Dedicated V2X infrastructure investments in Singapore and Dubai are generating captive demand for sub-50 millisecond communication nodes integrated into traffic signal networks.
- NB-IoT spectrum harmonization:Standardized narrowband allocations by regulators in India and Brazil are reducing modem certification costs for mass-scale smart metering rollouts.
Market Restraints
- Semiconductor foundry concentration:Edge-computing node production depends on mature-node capacity at Taiwanese and South Korean fabs, exposing procurement timelines to automotive sector demand surges.
- GDPR algorithmic transparency:The EU AI Act's explainability requirements for predictive policing and traffic optimization systems are extending vendor validation cycles by twelve to eighteen months.
- LoRaWAN substitution pressure:Cellular LPWAN protocols are displacing unlicensed alternatives in revenue-critical applications, eroding hardware margins for gateway manufacturers.
Strategic Opportunities
- Indonesian archipelago digitization:The Nusantara capital relocation and associated smart city buildout represent greenfield demand for integrated water, energy, and mobility platforms without legacy system encumbrance.
- Digital twin convergence:Municipal infrastructure modeling is integrating real-time IoT feeds with building information management systems, opening subscription revenue streams for analytics providers.
- US IIJA broadband funding:Federal middle-mile fiber investments are enabling last-mile sensor networks in underserved metropolitan areas previously excluded by backhaul economics.
Industry Challenges
- Embedded systems cybersecurity certification:Fragmented national regimes for critical infrastructure protection in Saudi Arabia, Australia, and Japan are forcing redundant product variants and inflating R&D overhead.
- Intergenerational protocol integration:Legacy SCADA and proprietary building automation networks resist standard MQTT and CoAP migration, requiring costly protocol translation layers in brownfield deployments.
- Edge AI talent scarcity:Municipal IT departments lack personnel capable of optimizing TensorFlow Lite models for constrained sensor nodes, creating implementation bottlenecks for computer vision safety applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IoT in Smart Cities Market |
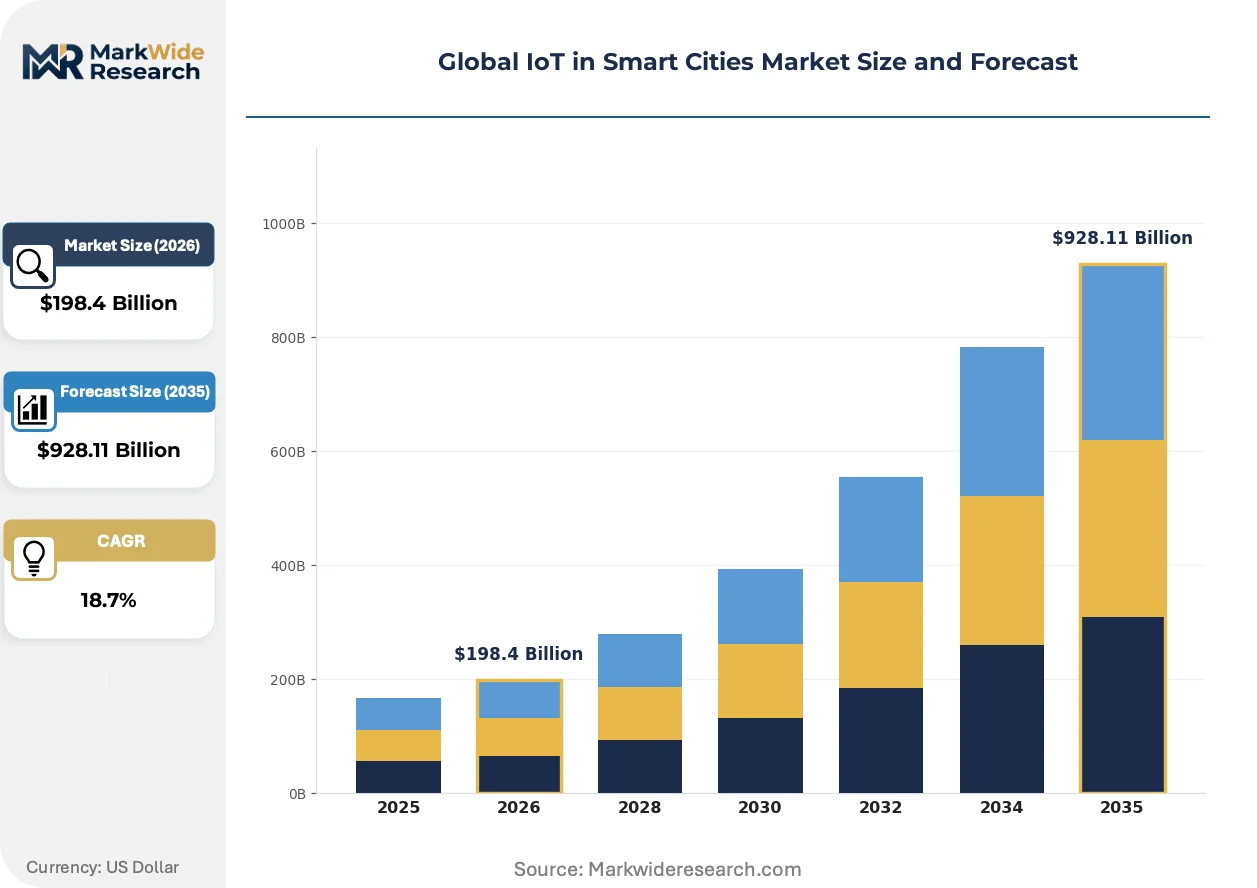
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $928.11 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Asset Tracking, Smart Lighting, Traffic Management, Public Safety Systems, Environmental Monitoring Deployment Type: Cloud-Based, Edge Computing, Hybrid, On-Premise Application Area: Smart Parking, Waste Management, Energy Management, Water Distribution, Intelligent Transportation End User: Government Authorities, Infrastructure Providers, Utility Companies, Transportation Operators, Security Agencies |
| Companies Covered | Cisco Systems, Inc., IBM Corporation, Microsoft Corporation, Huawei Technologies Co., Ltd., Siemens AG, Schneider Electric SE, Intel Corporation, Hitachi, Ltd., Tech Mahindra Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IoT in Smart Cities Market Shifts & Advancements
Three concurrent shifts are restructuring competitive advantage: silicon-level security integration, regulatory-driven data sovereignty architectures, and procurement model evolution toward performance-guaranteed service contracts.
Confidential computing enclaves in ARM Cortex-M33 and RISC-V microcontroller cores are integrating hardware-isolated execution environments for cryptographic key management. Water utilities in the Netherlands and wastewater authorities in California are mandating these secure elements for critical infrastructure sensor nodes. This capability is integrating tamper-resistant telemetry into previously cost-constrained environmental monitoring categories.
The EU AI Act's risk-based classification system is compelling algorithmic impact assessments for predictive maintenance platforms deployed in public transit networks. Vendors serving Barcelona, Vienna, and Copenhagen must now document training data provenance and model drift monitoring protocols. Transportation agencies are responding by bifurcating procurement between explainable rule-based systems for safety-critical functions and opaque neural networks for demand forecasting.
Performance-based service contracts are displacing capital expenditure procurement for smart street lighting in Brazilian and Mexican municipalities. Contractors now assume energy savings risk and hardware refresh obligations, capturing fifteen-year revenue streams in exchange for upfront infrastructure investment. This shift concentrates vendor selection criteria on balance sheet capacity and energy modeling accuracy rather than luminaire specifications alone.
Global IoT in Smart Cities Market Segmentation
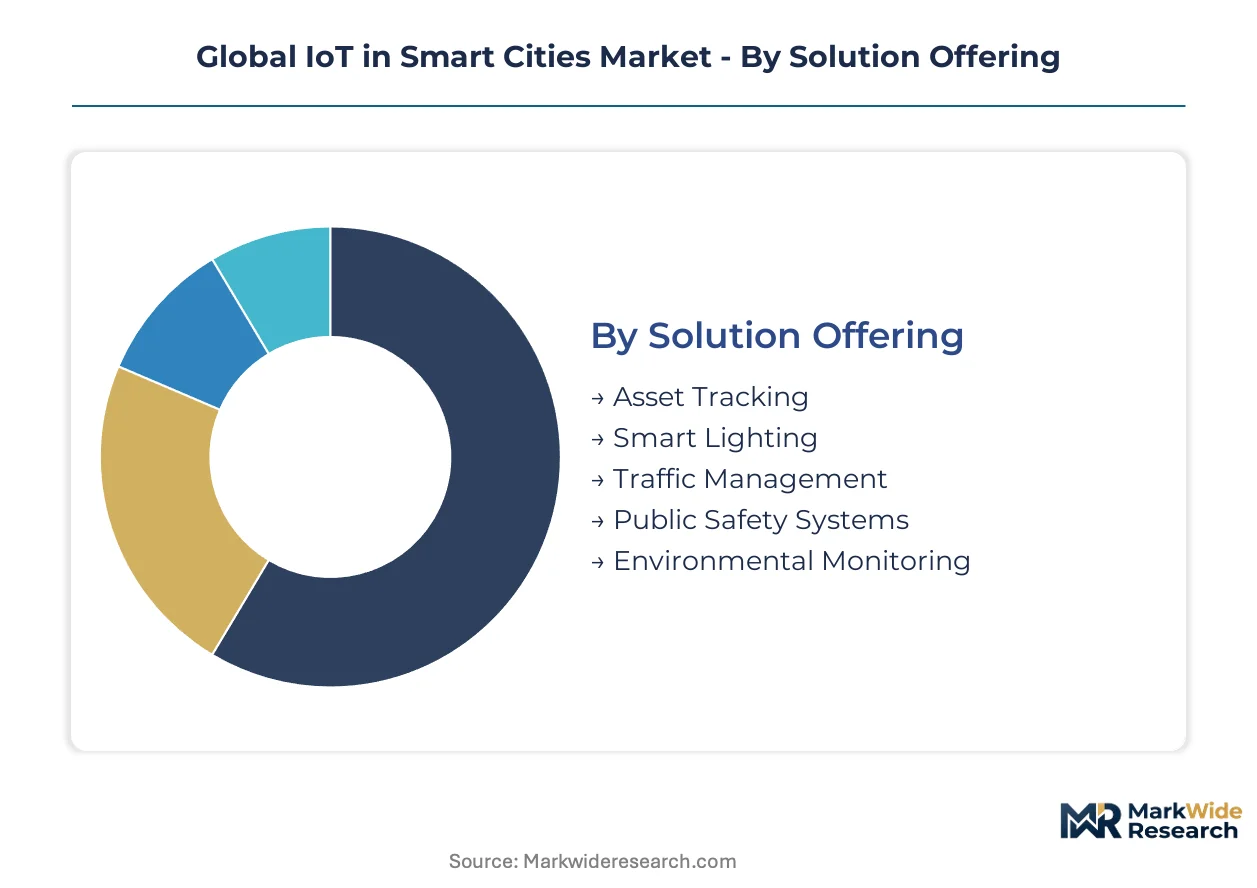
Segmentation in the Global IoT in Smart Cities Market reveals how procurement priorities diverge across latency requirements, data sovereignty mandates, and legacy infrastructure constraints. Municipal buyers select architectures based on specific application criticality rather than pursuing uniform technology stacks.
Solution Offering:
Standardization dominates mature categories with established ROI frameworks, while emerging applications demand bespoke sensor configurations and integration services.
- Smart Lighting:LED luminaires with integrated occupancy sensors and adaptive dimming algorithms reduce municipal energy expenditure. German and French municipalities under EU Green Deal mandates are retrofitting street networks with photoelectric controls and centralized management platforms.
- Traffic Management:Signal coordination systems process vehicle flow data through edge nodes to optimize intersection timing. Singapore and Dubai are deploying dedicated V2X infrastructure requiring sub-50 millisecond response thresholds for autonomous vehicle corridors.
- Environmental Monitoring:Air quality and microclimate sensors feed heat island mitigation algorithms.
- Public Safety Systems:Acoustic gunshot detection and computer vision platforms integrate with emergency dispatch networks.
- Asset Tracking:Geolocation tags monitor municipal equipment location and utilization rates.
Most installed capacity flows through Smart Lighting. Expansion is steepest in Environmental Monitoring.
Deployment Type:
Cost tier differentiation separates capital-intensive edge architectures from subscription-based cloud services with lower upfront expenditure.
- Cloud-Based:Centralized data lakes aggregate telemetry from distributed sensor networks through cellular or fiber backhaul. Brazilian and Mexican municipalities favor this model for smart street lighting procurement with performance-guaranteed service contracts.
- Edge Computing:Localized processing nodes execute inference on constrained devices without round-trip latency to distant data centers. Netherlands water utilities mandate hardware-isolated execution environments for cryptographic key management in critical infrastructure nodes.
- Hybrid:Tiered architectures route routine analytics to cloud platforms while retaining time-sensitive processing at the network periphery.
- On-Premise:Fully localized server installations address data residency requirements under GDPR and national cybersecurity certifications.
Cloud deployments hold the largest installed base. Edge configurations are gaining share fastest in public safety and transportation applications.
Application Area:
Volume concentration clusters around utilities with predictable procurement cycles, while customer type differentiation separates enterprise-grade platforms from municipal self-service deployments.
- Energy Management:Grid-interactive building automation systems balance load across distributed generation assets. Siemens leverages vertical integration from building controls through utility-scale platforms to capture captive demand in this segment.
- Intelligent Transportation:Multi-modal coordination platforms integrate traffic signals, transit priority systems, and pedestrian crossing management. Barcelona, Vienna, and Copenhagen transportation agencies bifurcate procurement between explainable rule-based systems and neural network demand forecasting under EU AI Act requirements.
- Water Distribution:Pressure monitoring and leak detection networks reduce non-revenue water losses.
- Smart Parking:Occupancy sensors and dynamic pricing algorithms optimize curb utilization.
- Waste Management:Fill-level sensors route collection vehicles through optimized paths.
Energy Management carries the heaviest deployment volume. Intelligent Transportation is climbing the fastest as V2X infrastructure investments accelerate.
End User:
Maturity-based segmentation separates early adopters with dedicated smart city offices from laggards relying on traditional procurement departments without technical evaluation capacity.
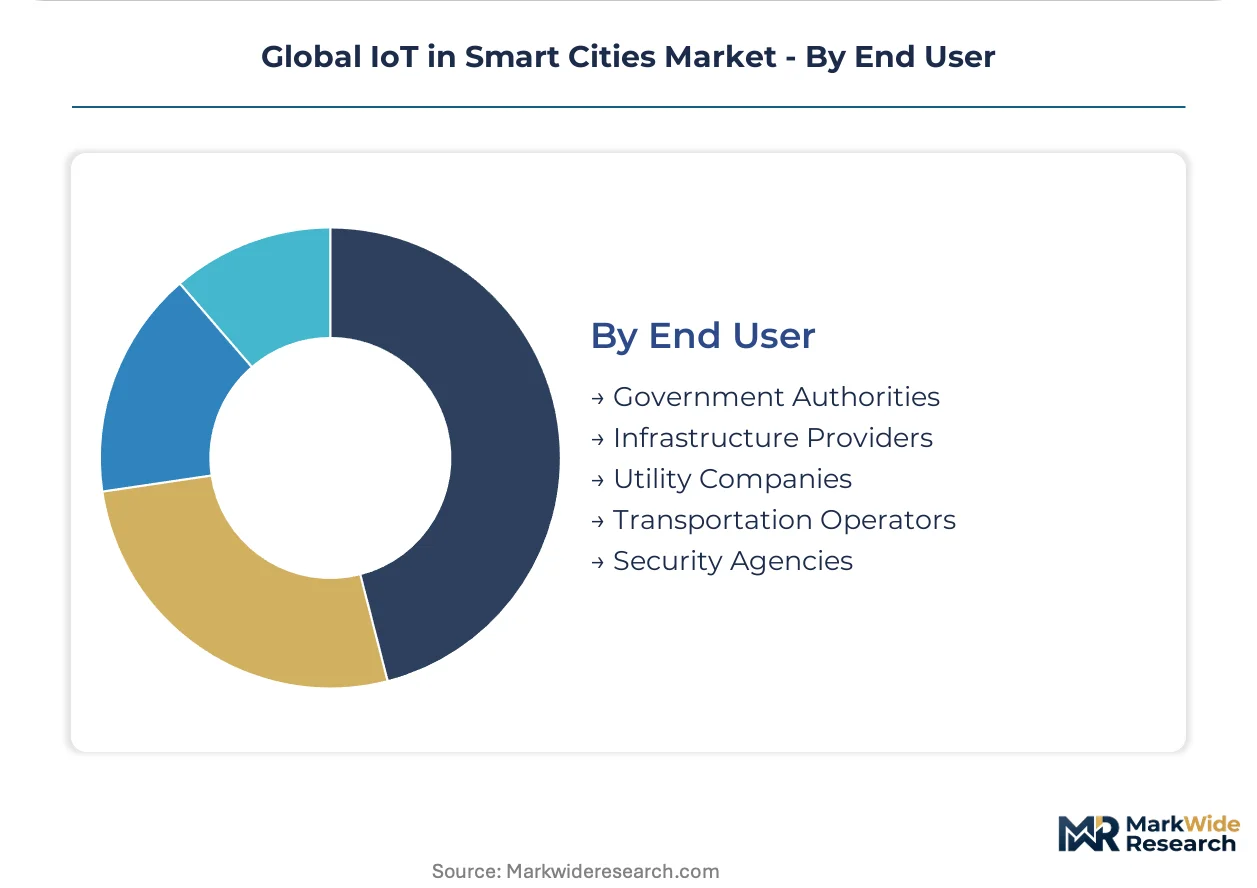
- Government Authorities:Municipal departments issue RFPs embedding ISO 37120 and IEC 62040 standards for interoperability and power resilience. FCC spectrum allocation decisions in the United States directly determine which communication protocols cities can deploy at scale.
- Utility Companies:Electricity, water, and wastewater operators procure sensor networks with fifteen-year asset life assumptions and cybersecurity certification requirements. Fragmented national regimes in Saudi Arabia, Australia, and Japan force redundant product variants.
- Infrastructure Providers:Private concession holders finance, build, and operate smart city systems under long-term service agreements.
- Transportation Operators:Transit agencies deploy fleet telematics and passenger information systems.
- Security Agencies:Law enforcement entities acquire predictive policing and emergency response platforms.
Utility Companies represent the largest procurement volume. Government Authorities are expanding most quickly as federal funding programs in Germany and the United States accelerate integrated platform deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing IoT deployment capital toward jurisdictions with harmonized certification frameworks and federal co-funding mechanisms. South Korean and Taiwanese sensor manufacturing clusters now supply edge-computing nodes to municipal buyers seeking faster procurement cycles than GDPR-constrained European tenders permit.
United States
FCC spectrum allocations for unlicensed IoT bands determine protocol viability for municipal scale deployments. The Infrastructure Investment and Jobs Act channels middle-mile fiber investments into last-mile sensor networks across underserved metropolitan areas. Chicago and Atlanta are deploying integrated mobility platforms with sub-50 millisecond latency requirements for traffic signal coordination.
Germany
Federal smart city funding programs under the EU Green Deal accelerate integrated energy and mobility platform procurement. KBA cybersecurity certifications for critical infrastructure reshape vendor qualification timelines for predictive policing systems. Munich and Hamburg are retrofitting street networks with photoelectric controls and heat island mitigation sensors.
Singapore
Autonomous vehicle corridor investments generate captive demand for V2X infrastructure with dedicated sub-50 millisecond communication nodes. The Land Transport Authority mandates edge-computing architectures for traffic signal networks serving autonomous bus fleets. The Jurong Lake District serves as a testbed for digital twin convergence with real-time IoT feed integration.
United Arab Emirates
Dubai's smart pole system deployments prioritize 5G-integrated infrastructure for public safety and environmental monitoring applications. MOHAP data residency requirements influence cloud architecture decisions for healthcare-integrated municipal platforms. Masdar City anchors demand for microclimate monitoring arrays serving adaptive building management systems.
Indonesia
The Nusantara capital relocation creates greenfield demand for integrated water, energy, and mobility platforms without legacy system encumbrance. National cybersecurity certification regimes for critical infrastructure protection extend vendor validation cycles for foreign platform providers. The new capital zone is procuring edge-computing nodes for autonomous waste collection and smart grid coordination.
Global IoT in Smart Cities Market Competitive Landscape
US networking heritage anchors one tier of municipal backbone provision; German industrial automation specialists hold building-to-grid vertical integration positions. The vendor base separates into three distinct tiers: full-stack platform providers, component-specialized gateway manufacturers, and regional system integrators with captive municipal relationships. Dominant competitive moves include strategic partnerships for edge AI talent acquisition and geographic expansion through performance-guaranteed service contract structures.
Within the networking infrastructure tier, Cisco Systems occupies a position exemplifying secure municipal backbone dominance. Huawei Technologies represents the 5G-integrated smart pole system archetype across Middle Eastern and Southeast Asian contracts. Siemens anchors the building-automation-to-grid vertical integration model, capturing captive demand from energy management segments through in-house production of distributed control systems.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| IBM Corporation |
| Microsoft Corporation |
| Huawei Technologies Co., Ltd. |
| Siemens AG |
| Schneider Electric SE |
| Intel Corporation |
| Hitachi, Ltd. |
| Tech Mahindra Limited |
| Others |
Supply & Pricing Matrix
Silicon wafer costs for ARM Cortex-M33 and RISC-V microcontroller cores flow from Taiwanese foundries through three-tier pricing structures separating premium secure-element nodes from standard environmental sensors and economy-grade legacy replacements. Municipal procurement officers in Germany and France absorb tier premiums for GDPR-compliant hardware-isolated execution environments, while Brazilian and Mexican municipalities negotiate performance-guaranteed service contracts that compress upfront capital expenditure into fifteen-year operational leases.
Pricing Analysis
Distributor margins for LoRaWAN and NB-IoT gateway hardware compress as cellular LPWAN protocols displace unlicensed alternatives in revenue-critical applications. Three-tier pricing structure across premium, standard, and economy levels differentiates by cybersecurity certification grade and latency specification, with EU AI Act-compliant explainable systems commanding tier premiums. Price erosion runs through economy-tier environmental monitoring sensors as South Korean manufacturing clusters expand mature-node capacity. Utility companies demonstrate lowest price sensitivity due to fifteen-year asset life assumptions, while municipal governments in emerging markets prioritize lowest total cost of ownership.
Supply Chain Analysis
Dual-sourcing requirements for edge-computing nodes now mandate qualification of secondary suppliers beyond dominant Taiwanese and South Korean fab capacity, with municipal buyers in Saudi Arabia and Australia embedding redundant vendor clauses into critical infrastructure tenders. Semiconductor foundry output draws from 28nm and 40nm mature-node processes, ceramic substrate packaging, and cryptographic secure-element IP. Single-source vulnerability concentrates in Taiwanese wafer fabrication exposed to automotive sector demand surges. Distribution runs through authorized component distributors serving system integrators with captive municipal relationships, supplemented by direct OEM procurement for volume platform deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-based classification system compounds procurement complexity for predictive policing and traffic optimization platforms, accelerating vendor consolidation around explainable algorithmic architectures. Federal funding programs in Germany and the United States amplify demand for integrated mobility and energy platforms with embedded compliance documentation.
For Market Incumbents: Lock in long-term service contract structures with fifteen-year energy savings guarantees to capture recurring revenue streams and raise balance sheet barriers against challengers. Deepen backward integration into secure-element semiconductor sourcing to insulate margin positions from foundry capacity constraints. Prioritize certification investment for KBA and FCC cybersecurity regimes to accelerate qualification timelines relative to fragmented national competitors.
For New Entrants and Emerging Players: Begin with greenfield smart city deployments in Indonesia's Nusantara capital relocation zone, where absence of legacy SCADA and proprietary building automation networks eliminates protocol translation cost disadvantages. Target edge AI talent acquisition partnerships with Netherlands technical universities to address municipal IT capability gaps in TensorFlow Lite optimization. Pursue direct-to-utility sales models bypassing established system integrator channels in underserved US metropolitan areas enabled by IIJA middle-mile fiber investments.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented national cybersecurity certification regimes force redundant R&D overhead across non-mutually-recognized compliance frameworks. Platform providers with multi-country deployment scale face margin compression from compliance duplication, favoring acquisition of regional specialists with pre-qualified product variants. Watch for inflection where EU AI Act explainability mandates bifurcate procurement toward rule-based systems for safety-critical functions, disadvantaging opaque neural network platforms. Deviation in spectrum harmonization timelines for NB-IoT allocations across India and Brazil would shift the outlook materially.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Talent Partnership | Addresses municipal IT capability gaps in TensorFlow Lite model optimization for constrained sensor nodes. |
| Secure-Element Hardware Integration | Meets Netherlands water utility mandates for tamper-resistant telemetry in critical infrastructure deployments. |
| Performance-Guaranteed Service Contract | Captures fifteen-year revenue streams in Brazilian and Mexican smart street lighting procurement. |
| Digital Twin Platform Convergence | Integrates real-time IoT feeds with building information management systems in Singapore's Jurong Lake District. |
| NB-IoT Spectrum Harmonization | Reduces modem certification costs for mass-scale smart metering rollouts in Indian and Brazilian markets. |
Research Methodology
Direct dialogue with municipal procurement officers, smart city program directors, edge AI engineering leads, and utility infrastructure planners combined with secondary validation from FCC spectrum allocation filings, EU AI Act regulatory texts, and ISO 37120 standard documentation. Customs data for sensor component trade flows, SEC disclosures from networking infrastructure providers, and hyperscaler municipal cloud capex reports anchored supply-side assessment. Bottom-up deployment tallies across German federal funding programs and top-down market sizing triangulated to produce convergent estimates.
Segmented outputs across solution offering, deployment architecture, application area, and end-user category structured the analytical framework across the projection horizon. CAGRs derived from logistic diffusion modeling of technology adoption curves, with inputs including EU Green Deal mandate compliance timelines and autonomous vehicle corridor infrastructure investment schedules. Edge computing displacement rates for public safety applications and NB-IoT modem certification cost curves informed technology transition assumptions.
Caveats apply where semiconductor foundry capacity allocation shifts or GDPR algorithmic transparency enforcement intensity could materially shift the outlook. Forecasts embed assumptions regarding spectrum harmonization progress and federal funding program continuity without certainty of legislative renewal. Deviation in EU AI Act implementation timelines across member states would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Cellular IoT Module Market
Internet of Things (IoT)
Wifi IoT Market
Internet of Things (IoT)
Global Pervasive Computing Technology Market
Internet of Things (IoT)
Global Machine-To-Machine (M2M) Connections Market
Internet of Things (IoT)
IoT in Chemical Industry Market
Internet of Things (IoT)
IoT Application Development Services Market
Internet of Things (IoT)
Industrial IoT Platform Market
Internet of Things (IoT)
Smart Sound and Gateway Market
Internet of Things (IoT)
IoT Application Enablement Market
Internet of Things (IoT)
IoT Gateway Hardware and Software Market
Internet of Things (IoT)
IoT Operating System Market
Internet of Things (IoT)
Marine Internet of Things Market
Internet of Things (IoT)
Private Narrowband IoT Market
Internet of Things (IoT)
Global Internet of Things Technology Market
Internet of Things (IoT)
IoT in Retail Market
Internet of Things (IoT)
Qatar Internet of Things (IoT) Market