
 Global Machine-To-Machine (M2M) Connections Market | 2026-2036
Global Machine-To-Machine (M2M) Connections Market Size, Share, and Industry Trends Forecast 2026-2036
Global Machine-To-Machine (M2M) Connections Market Foresight
Chinese module producers is consolidating output at Shenzhen and Dongguan electronics corridors to capture economies of scale in cellular modem fabrication. Vodafone Group leverages its multi-national roaming infrastructure to serve cross-border fleet operators with unified SIM provisioning. Intel Corporation sustains R&D intensity in low-power wide-area chipsets that extend battery life for remote agricultural sensors. Deutsche Telekom AG anchors European connectivity through its integrated IoT platform and dedicated network core investments.
Machine-to-machine connections denote autonomous data exchange between networked devices via embedded cellular, satellite, or low-power radio modules operating on licensed and unlicensed spectrum bands, typically transmitting telemetry, status alerts, or control commands without human intervention. These linkages enable real-time asset monitoring, automated meter reading, and predictive equipment maintenance across distributed industrial and commercial infrastructures. Cellular connections dominate current revenue pools due to carrier-grade reliability and ubiquitous coverage, while LoRaWAN deployments are expanding fastest among smart city and utility applications where private spectrum and long-range propagation offset subscription costs. The managed services deployment model captures disproportionate margin as system integrators bundle connectivity, security, and analytics into outcome-based contracts for risk-averse facility managers.
The Federal Communications Commission governs spectrum allocation and device certification for M2M hardware entering the United States, while the European Telecommunications Standards Institute harmonizes cross-border interoperability through its M2M service layer specifications. China's Ministry of Industry and Information Technology enforces GB standards and network access licenses that shape product design cycles for vendors targeting domestic deployments. Stakeholders must monitor evolving national security reviews of foreign-manufactured modules and pre-position compliant supply chains before procurement windows narrow.
Market Dynamics
5G network densification and edge computing deployment are compressing latency thresholds below 10 milliseconds, enabling real-time industrial control loops that cellular M2M previously could not support. This technical inflection is redirecting capital from legacy 3G/4G module inventories toward software-defined radio architectures and containerized network functions.
Growth Catalysts
- FCC spectrum reallocation:The Federal Communications Commission's 3.5 GHz CBRS and 6 GHz unlicensed expansions are opening private LTE/5G networks for manufacturing campuses and port logistics yards seeking dedicated connectivity without carrier dependency.
- Predictive maintenance systems:German industrial OEMs are embedding cellular modules directly into rotating equipment and hydraulic systems, generating recurring telemetry revenue streams that offset hardware margin compression.
- LoRaWAN propagation economics:Smart city deployments across utility metering and environmental monitoring are exploiting sub-GHz spectrum to achieve 15-kilometer range with decade-long battery autonomy, displacing cellular in cost-sensitive infrastructure.
Market Restraints
- Semiconductor fabrication concentration:Advanced cellular baseband silicon depends on TSMC and Samsung foundry capacity concentrated in Taiwan and South Korea, exposing module vendors to geopolitical supply disruptions and allocation rationing.
- EU AI Act compliance friction:Automated decision-making systems embedded in M2M gateways now face mandatory risk classification, documentation burdens, and human oversight requirements that extend product development cycles by 8-14 months.
- Satellite IoT substitution:Low-earth-orbit constellations from Swarm and Astrocast are capturing maritime and remote agricultural telemetry previously served by cellular roaming, compressing addressable market boundaries for terrestrial carriers.
Strategic Opportunities
- India smart grid electrification:The country's central electricity regulator mandates AMI-2.0 meter deployment across 250 million connections by 2027, creating module demand volumes that domestic electronics manufacturing incentives under PLI schemes are positioning to capture.
- Digital twin convergence:M2M sensor streams fused with physics-based simulation models are enabling closed-loop optimization in process industries, with chemical and steel producers piloting edge-to-cloud architectures that bundle connectivity with analytics outcomes.
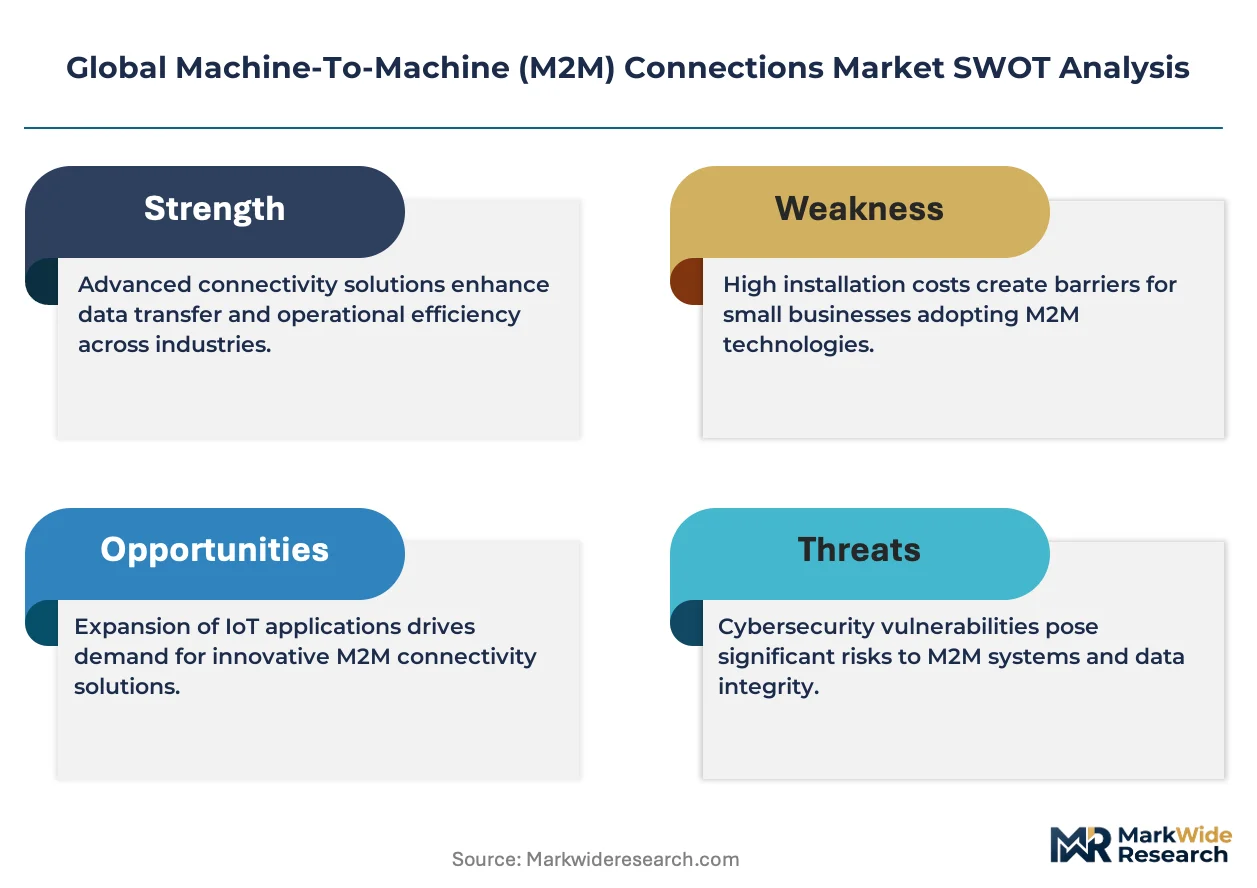
- CSRD disclosure mandates:The European Union's Corporate Sustainability Reporting Directive requires granular Scope 1-3 emissions tracking, driving demand for connected asset monitoring that M2M providers can embed into compliance-as-a-service offerings.
Industry Challenges
- Embedded systems security certification:IEC 62443-4-2 component-level certification for industrial cybersecurity requires 18-24 month validation timelines that delay revenue recognition and strain R&D budgets for mid-tier module vendors.
- Legacy SCADA integration complexity:Brownfield industrial facilities operate proprietary protocols from the 1990s; protocol translation gateways add 15-25% to deployment costs and introduce failure points that erode reliability guarantees.
- Radio-frequency engineering talent scarcity:Compound semiconductor design and antenna optimization expertise concentrates in Shenzhen, Munich, and San Diego corridors, forcing non-coastal vendors into compensation wars or outsourced development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Machine-To-Machine (M2M) Connections Market |
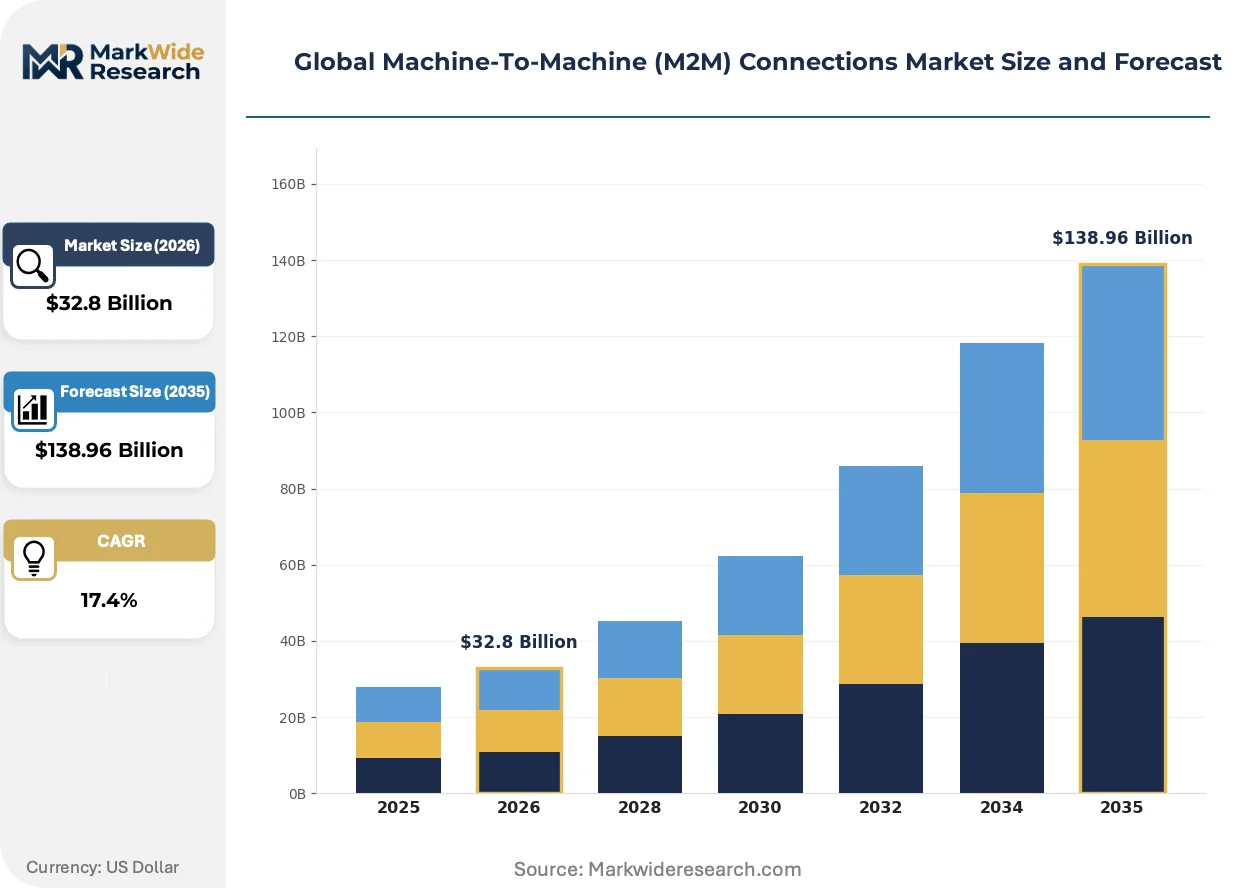
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $138.96 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Connection Type: Cellular, Satellite, Wi-Fi, Ethernet, LoRaWAN, Zigbee Industry Vertical: Manufacturing, Transportation, Energy, Agriculture, Smart Cities, Logistics Deployment Model: Public Network, Private Network, Hybrid Network, Managed Services End User Type: Original Equipment Manufacturers, System Integrators, Service Providers, Facility Managers |
| Companies Covered | Vodafone Group, Intel Corporation, AT&T Intellectual Property, Verizon Communications Inc., Texas Instruments Incorporated, Cisco Systems, Inc., Deutsche Telekom AG, Sierra Wireless, Huawei Technologies Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Machine-To-Machine (M2M) Connections Market Shifts & Advancements
Containerized network functions and AI-driven radio resource management are dissolving the boundary between connectivity hardware and cloud software, transforming M2M from a commoditized pipe into a programmable platform layer.
Software-defined radio modules with field-upgradable firmware are automating spectrum agility and protocol migration for fleet operators managing heterogeneous vehicle ages. Logistics providers in Germany and the Netherlands are deploying these units across 10,000+ vehicle pools to future-proof against 2G/3G sunsets without hardware swaps. This capability is automating the obsolescence risk that previously forced four-year replacement cycles, extending asset depreciation schedules and compressing total cost of ownership calculations for procurement committees.
The EU AI Act's risk-based classification system is mandating algorithmic transparency for M2M gateways executing automated decisions in critical infrastructure. Industrial OEMs serving energy and water utilities must now document training data provenance and maintain human-in-the-loop override capabilities. German and French facility operators are responding by demanding pre-certified edge gateways from system integrators, shifting compliance liability upstream and favoring vendors with established notified body relationships.
Consumption patterns among agricultural cooperatives are rotating from subscription-based cellular toward private LoRaWAN networks with capex amortization over seven-year depreciation schedules. Brazilian and Australian grain belt operators are deploying tower infrastructure and solar-powered gateways to eliminate per-message metering uncertainty. This behavioral pivot is fragmenting demand between carrier-dependent and carrier-avoidant deployment models, forcing module vendors to maintain dual product architectures without scale concentration in either channel.
Global Machine-To-Machine (M2M) Connections Market Segmentation
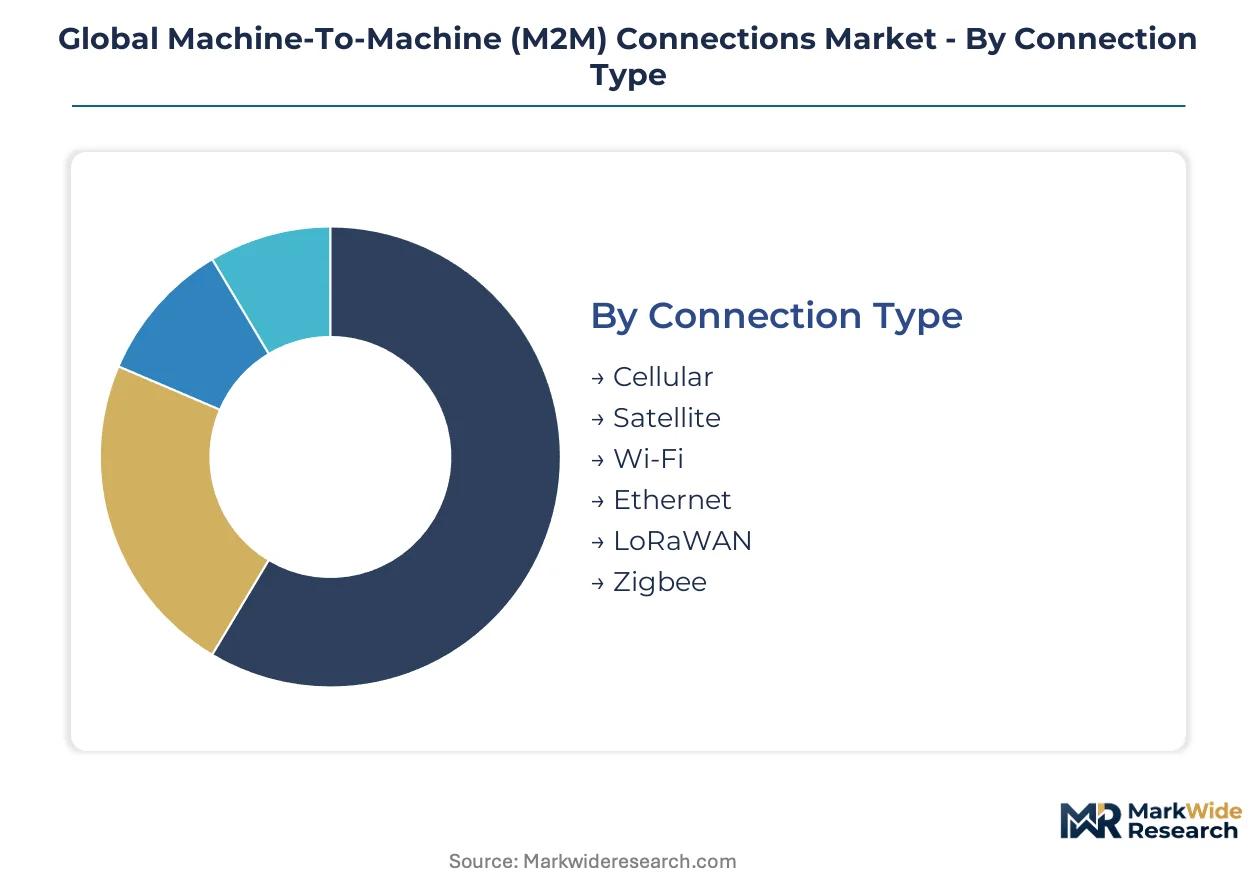
Segmentation in M2M connections reveals how connectivity requirements diverge across latency sensitivity, coverage constraints, and operational control needs. Procurement committees weight these dimensions differently when specifying modules for fleet telematics versus agricultural sensor grids.
Connection Type:
Standardization dominates at the protocol layer while customization proliferates in antenna configuration and power management subsystems.
- Cellular:Licensed spectrum modules deliver carrier-grade reliability through 4G LTE and 5G NR basebands with SIM-based authentication. German automotive OEMs specify these for over-the-air firmware updates in connected vehicles, prioritizing roaming agreements that span manufacturing footprints across Poland, Hungary, and Mexico.
- Satellite:Low-earth-orbit transceivers provide connectivity beyond terrestrial infrastructure using proprietary constellations. Maritime container tracking across Pacific shipping lanes and remote mining operations in Western Australia drive procurement volumes where cellular backhaul remains economically unviable.
- Wi-Fi:Unlicensed 2.4 GHz and 5 GHz modules enable high-throughput local data aggregation in controlled environments.
- Ethernet:Wired connectivity persists in factory automation where electromagnetic interference demands shielded physical layers.
- LoRaWAN:Sub-GHz spread-spectrum protocols achieve kilometer-range propagation with milliwatt power budgets.
- Zigbee:Mesh-networking stacks optimize for building automation with self-healing topology capabilities.
Leading the category by volume: Cellular. Growing fastest: LoRaWAN.
Industry Vertical:
Margin structures vary sharply across verticals, with energy and logistics commanding premium pricing for mission-critical uptime guarantees while agriculture operates on stripped-down hardware economics.
- Manufacturing:Predictive maintenance systems embed vibration and thermal sensors into rotating equipment, streaming telemetry to edge gateways for real-time anomaly detection. German industrial OEMs in Baden-Württemberg specify IP67-rated cellular modules for hydraulic press monitoring, with FCC Part 15 compliance mandatory for exported machinery.
- Transportation:Fleet telematics platforms consolidate GPS positioning, engine diagnostics, and driver behavior analytics through unified connectivity backbones. Cross-border operators in the Netherlands and Belgium leverage Vodafone's multi-national roaming infrastructure to eliminate SIM-swapping at frontiers.
- Energy:AMI-2.0 smart meters and grid sensors demand cryptographic security modules and decade-long field lifespans.
- Agriculture:Soil moisture and weather stations prioritize battery autonomy over bandwidth in Brazilian soybean belts.
- Smart Cities:Municipal utility metering and environmental monitoring exploit LoRaWAN's unlicensed spectrum economics.
- Logistics:Cold-chain monitoring and warehouse robotics require sub-100-millisecond latency for automated guided vehicle coordination.
Volume concentration: Manufacturing. Steepest expansion trajectory: Smart Cities.
Deployment Model:
Control requirements determine whether enterprises absorb capital expenditure for private infrastructure or outsource operational complexity to managed service contracts.
- Public Network:Carrier subscription models deliver immediate geographic coverage without spectrum licensing overhead. Brazilian agricultural cooperatives and Australian grain belt operators favor this approach for seasonal deployments where infrastructure ownership proves uneconomical.
- Private Network:Dedicated LTE/5G infrastructure using CBRS or licensed spectrum eliminates contention and enables deterministic latency. Port logistics yards in Rotterdam and manufacturing campuses in Shenzhen deploy these for automated crane operations and robotic welding cells.
- Hybrid Network:Traffic steering between cellular and unlicensed links optimizes cost and reliability.
- Managed Services:System integrators bundle connectivity, security patching, and analytics platforms under outcome-based contracts.
Current revenue share leader: Public Network. Fastest adoption gain: Managed Services.
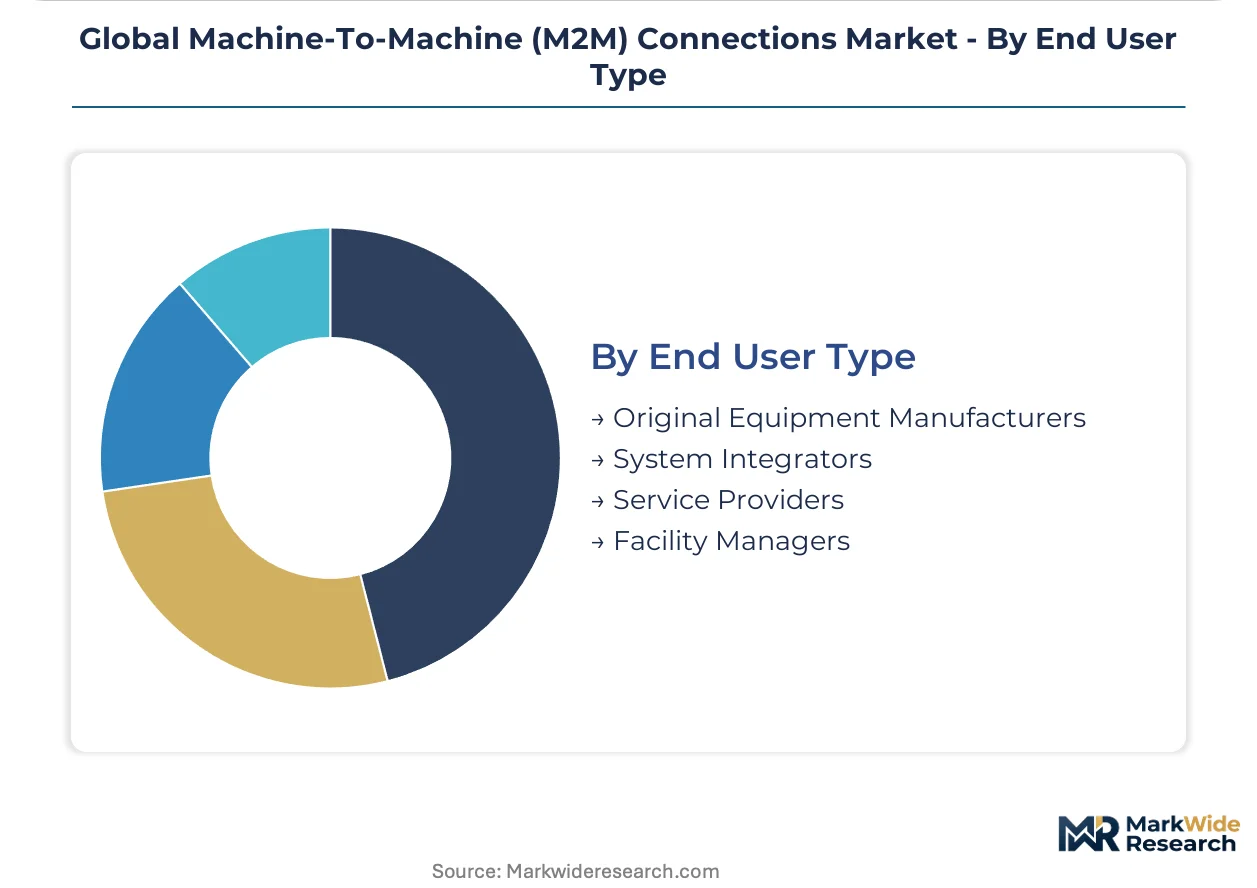
End User Type:
Technical sophistication and procurement authority fragment across this axis, with OEMs embedding modules at design stage while facility managers retrofit connectivity into depreciated assets.
- Original Equipment Manufacturers:Module selection occurs during product development cycles, with cellular basebands integrated into industrial pumps, HVAC systems, and medical devices. German pump manufacturers in North Rhine-Westphalia specify Quectel and Fibocom modules with pre-certified regulatory bundles for EU, US, and Australian markets.
- System Integrators:These firms aggregate heterogeneous sensor protocols and normalize data streams for enterprise platforms. French water utilities contract Schneider Electric and similar integrators for AMI deployments that must comply with EU AI Act risk classifications for automated leak detection.
- Service Providers:Telecommunications carriers and MVNOs monetize connectivity through subscription tiers.
- Facility Managers:Brownfield retrofit projects demand protocol translation gateways and minimal disruption installation.
Dominant procurement volume: Original Equipment Manufacturers. Most rapid expansion: System Integrators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics corridor anchors cellular module fabrication for global M2M deployments, with Dongguan and Taipei foundries feeding component supply chains across three continents.
United States
FCC spectrum reallocations in the 3.5 GHz CBRS band are accelerating private LTE/5G network adoption at manufacturing campuses and port logistics yards. The Commission's Part 15 device certification requirements shape hardware design cycles for vendors targeting federal and defense-adjacent deployments. San Diego and Austin anchor RF engineering talent clusters where antenna optimization and compound semiconductor design concentrate.
Germany
Industrial OEMs in Baden-Württemberg and North Rhine-Westphalia embed cellular modules into predictive maintenance systems for hydraulic presses and rotating equipment. The EU AI Act mandates risk classification and human oversight for automated decision-making gateways serving energy and water utilities. Munich hosts Europe's densest concentration of industrial cybersecurity certification bodies under IEC 62443 frameworks.
China
MIIT enforces GB standards and network access licenses that compress product design cycles for domestic deployments. Shenzhen and Dongguan electronics corridors concentrate cellular modem fabrication at scale, with module vendors backward-integrating into baseband silicon sourcing. The Yangtze River Delta smart city pilots are displacing cellular with LoRaWAN in utility metering applications.
India
CEA mandates for AMI-2.0 smart meter deployment across 250 million electricity connections by 2027 are creating module demand volumes that PLI manufacturing incentives position domestic producers to capture. TRAI spectrum allocations in sub-GHz bands support private utility network deployments. Karnataka and Gujarat electronics manufacturing clusters are attracting module assembly investments from global vendors.
Brazil
Agricultural cooperatives in the Mato Grosso and Rio Grande do Sul grain belts are rotating from subscription cellular toward private LoRaWAN networks with capex amortization over seven-year depreciation schedules. ANATEL certification requirements for radio equipment create compliance friction for imported modules. São Paulo anchors system integrator activity serving smart city and utility verticals.
Global Machine-To-Machine (M2M) Connections Market Competitive Landscape
Global majors compete with regional champions across roaming infrastructure and module fabrication, producing a tiered structure where scale-driven connectivity providers, semiconductor specialists, and integrated telecom operators occupy distinct competitive positions. The market fragments across three archetypes: carrier-grade connectivity aggregators, low-power chipset designers, and vertical-integrated module fabricators. Consolidation pressure operates through strategic partnerships for cross-border roaming agreements and capacity expansion in Shenzhen-based electronics corridors.
Among carrier-grade connectivity aggregators, Vodafone Group and Deutsche Telekom AG exemplify the integrated platform archetype, bundling multi-national roaming with dedicated network core investments. Intel Corporation occupies a position within the semiconductor tier, anchoring R&D intensity in low-power wide-area chipsets. These three entities represent the dominant competitive vectors—roaming infrastructure, silicon innovation, and integrated service delivery—without any single archetype commanding unified market control.
| Leading Market Players |
|---|
| Vodafone Group |
| Intel Corporation |
| AT&T Intellectual Property |
| Verizon Communications Inc. |
| Texas Instruments Incorporated |
| Cisco Systems, Inc. |
| Deutsche Telekom AG |
| Sierra Wireless |
| Huawei Technologies Co. Ltd |
| Others |
Supply & Pricing Matrix
AMI-2.0 meter mandates across India's 250 million electricity connections are forcing module vendors to absorb certification costs while maintaining cellular baseband performance tiers, compressing margins for non-integrated fabricators and accelerating tier consolidation among price-sensitive procurement committees.
Pricing Analysis
Extended warranty and firmware-update bundling separate premium cellular modules from stripped-down LoRaWAN units in agricultural deployments. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and geographic coverage scope, with IEC 62443-4-2 cybersecurity validation commanding 20-40% uplifts. Cost compression in the economy tier is intensifying because Brazilian and Australian grain cooperatives are amortizing private network capex over seven-year schedules, bypassing per-message cellular metering entirely. System integrators exhibit the least price sensitivity due to outcome-based contract structures, while facility managers in brownfield retrofits drive the hardest unit-cost negotiations.
Supply Chain Analysis
RF engineering talent scarcity in Shenzhen, Munich, and San Diego corridors is constraining antenna optimization capacity and forcing module vendors into compensation wars or outsourced development partnerships. Advanced cellular baseband silicon draws from TSMC and Samsung foundry capacity concentrated in Taiwan and South Korea, with compound semiconductor substrates and SIM authentication chips as critical feedstocks. Single-source vulnerability in sub-6 GHz filter components exposes vendors to allocation rationing during geopolitical disruptions. Distribution runs through direct OEM partnerships for embedded modules and carrier-provisioned channels for subscription-based connectivity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated platform providers as EU AI Act compliance burdens and 18-24 month IEC 62443 certification timelines force mid-tier module vendors toward strategic exits or acquisition.
For Market Incumbents: Cement roaming infrastructure advantages through multi-national SIM provisioning partnerships that lock in cross-border fleet operators, while deepening backward integration into baseband silicon sourcing to offset TSMC allocation exposure. Prioritize pre-certified edge gateway portfolios that shift EU AI Act liability upstream toward system integrators serving French and German utilities. For New Entrants and Emerging Players: Software-defined radio modules with field-upgradable firmware represent the most penetrable wedge, targeting logistics providers managing 10,000+ heterogeneous vehicle pools in Germany and the Netherlands seeking 2G/3G sunset protection without hardware swaps. Private LoRaWAN network deployment in Brazilian and Australian agricultural belts offers a carrier-avoidant entry path with seven-year amortization economics. For Investors and Strategic Acquirers: The window for entry favors vertically integrated module fabricators with captive Shenzhen manufacturing and established notified body relationships for EU cybersecurity certification. Long-term viability hinges on positioning for digital twin convergence in process industries, with chemical and steel producers piloting edge-to-cloud bundles. Watch satellite IoT substitution rates in maritime and remote agricultural telemetry as the inflection signal for terrestrial carrier addressable market compression.| Strategic Initiative | Industry Significance |
|---|---|
| Private 5G Network Deployment | FCC CBRS allocations enable manufacturing campuses in Detroit and Houston to bypass carrier dependency for automated crane operations. |
| Software-Defined Radio Module Launch | Field-upgradable firmware automates spectrum agility for German fleet operators managing 2G/3G/4G/5G heterogeneous vehicle ages. |
| Cybersecurity Certification Investment | IEC 62443-4-2 validation in Munich shortens procurement cycles for energy utilities under EU AI Act risk classifications. |
| Backward Integration into Baseband Silicon | Captive sourcing from Yangtze River Delta foundries insulates against TSMC allocation rationing during geopolitical disruptions. |
| Managed Services Platform Expansion | Outcome-based contracts bundling connectivity, security patching, and analytics capture disproportionate margin from risk-averse facility managers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with IoT platform architects, cellular module procurement leads at German industrial OEMs, FCC spectrum policy specialists, and system integrators serving French water utilities. FCC Part 15 device certification databases, MIIT network access license registries, and ETSI M2M service layer specifications provided standardized compliance tracking. Bottom-up module shipment data triangulated against top-down carrier subscription revenue disclosures.
Data-stream reconciliation across connection type, industry vertical, deployment model, and end user type dimensions produced volume and value estimates throughout the forecast period. CAGRs were derived from regression analysis of historical module pricing trajectories and projected 5G network densification curves. Industry-specific inputs included AMI-2.0 deployment timelines from India's Central Electricity Authority and LoRaWAN gateway installation data from Brazilian agricultural cooperative filings.
Several conditions sit outside the modeled scope, including unannounced satellite IoT constellation launches, abrupt FCC spectrum reallocation decisions, and geopolitical disruptions to Taiwan or South Korean foundry operations. Forecasts reflect documented assumptions regarding 5G NR rollout pacing and EU AI Act enforcement consistency. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Lora and Lorawan IoT Connectivity Market
Internet of Things (IoT)
Global IOT Gateway Market
Internet of Things (IoT)
Global IoT Solutions and Services Market
Internet of Things (IoT)
Global Military IoT Market
Internet of Things (IoT)
Mobile-Connecting Smart Objects Market
Internet of Things (IoT)
IoT Monetization Market
Internet of Things (IoT)
Europe IoT Device Market
Internet of Things (IoT)
Non-Terrestrial IoT Gateway Hardware and Software Market
Internet of Things (IoT)
Global IoT Routers Market
Internet of Things (IoT)
IoT Software Market
Internet of Things (IoT)
Massive Machine Type Communication Market
Internet of Things (IoT)
Marine Internet of Things Market
Internet of Things (IoT)
Connected IoT Devices Market
Internet of Things (IoT)
IoT Application Development Services Market
Internet of Things (IoT)
5G IIOT Market
Internet of Things (IoT)
Global Embedded Security for Internet of Things Market