
 IoT Gateway Hardware and Software Market | 2026-2036
IoT Gateway Hardware and Software Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Gateway Hardware and Software Market Foresight
Multi-source procurement for cellular modems and security chipsets is shifting toward qualified secondary vendors as supply continuity concerns persist. Cisco Systems, Inc. anchors its position through captive silicon partnerships and enterprise channel density. Advantech Co., Ltd. specializes in ruggedized edge gateways for industrial automation environments. NXP Semiconductors dominates automotive-grade gateway silicon with ASIL-certified processing platforms.
IoT gateway hardware and software comprises embedded computing platforms that bridge field devices to cloud or on-premises infrastructure, typically integrating protocol translation, local analytics, and cryptographic security functions within a fanless or industrial enclosure rated for extended temperature ranges. Edge gateways lead hardware shipments by volume, though multi-service gateways command wider software attach rates and recurring revenue potential. On the technology dimension, LoRaWAN competes aggressively in utility and agriculture telemetry, while Ethernet retains dominance in factory-floor deployments where deterministic latency matters. Smart cities and healthcare represent the fastest-growing end-user categories, driven by video analytics convergence and remote patient monitoring infrastructure.
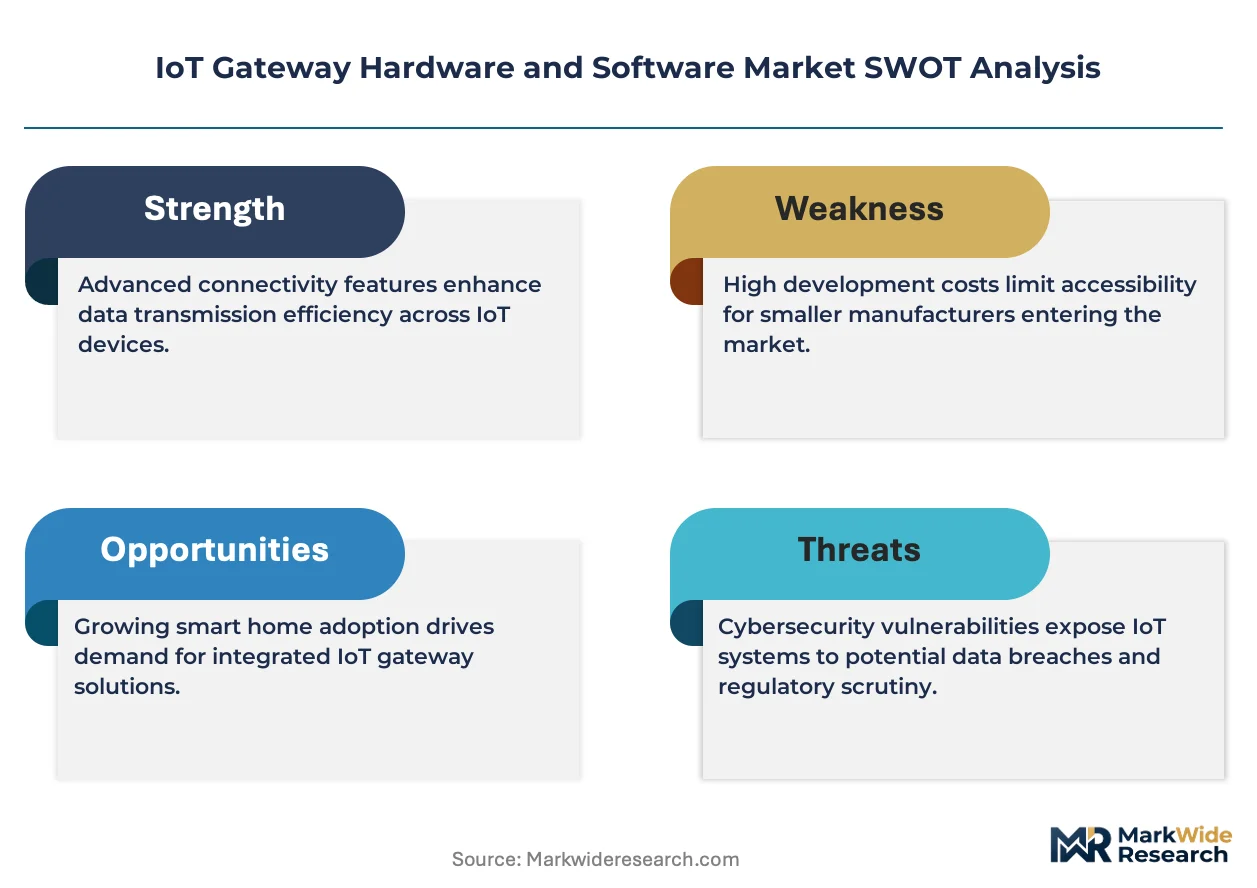
FCC equipment authorization rules shape radio module selection for US-bound products, while ETSI EN 303 645 and IEC 62443 establish baseline cybersecurity expectations across European and industrial markets. The EU Cyber Resilience Act will extend mandatory vulnerability disclosure and update obligations to gateway firmware, tightening compliance scope for vendors serving European industrial automation buyers. Stakeholders must monitor whether regional certification fragmentation accelerates platform specialization or favors modular hardware architectures with swappable radio and security modules.
Market Dynamics
Cellular modem supply concentration and the EU Cyber Resilience Act's firmware mandates are forcing gateway vendors to redesign hardware architectures around swappable radio modules and automated patch pipelines.
Growth Catalysts
- EU AI Act edge deployment rules:German automotive OEMs now require on-premise inference capabilities, pulling high-specification gateways into production lines.
- Smart city video analytics convergence:Municipal infrastructure budgets in France and Spain are redirecting toward edge gateways that preprocess surveillance feeds before cloud transmission.
- LoRaWAN utility telemetry expansion:Water and electricity distribution operators across Italy and Poland are replacing manual meter reading with long-range gateway networks.
Market Restraints
- Security chipset supply concentration:Qualified secondary vendors struggle to match NXP and Infineon automotive-grade volumes, creating allocation bottlenecks.
- ETSI EN 303 645 compliance costs:Baseline cybersecurity certification adds engineering overhead that compresses margins on economy-tier gateway SKUs.
- Ethernet deterministic latency requirements:Factory-floor buyers reject packet-switched alternatives, limiting wireless substitution in industrial automation.
Strategic Opportunities
- Healthcare remote patient monitoring:Dutch and Belgian hospital networks seek HIPAA-equivalent edge gateways for continuous vital sign streaming.
- EU Green Deal energy efficiency mandates:Building automation retrofits in Nordic countries create demand for gateways integrating HVAC and lighting control.
- 5G RedCap module convergence:Mid-band cellular gateways combining reduced capability 5G with LoRaWAN are displacing dual-radio legacy units in agricultural telemetry.
Industry Challenges
- Embedded Linux security patching:Gateway vendors lack DevOps pipelines to deliver CVE fixes within the 24-hour windows demanded by IEC 62443-4-2.
- Multi-protocol integration complexity:OPC-UA, MQTT, and Modbus coexistence in single-gateway deployments requires scarce firmware engineering specialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Gateway Hardware and Software Market |
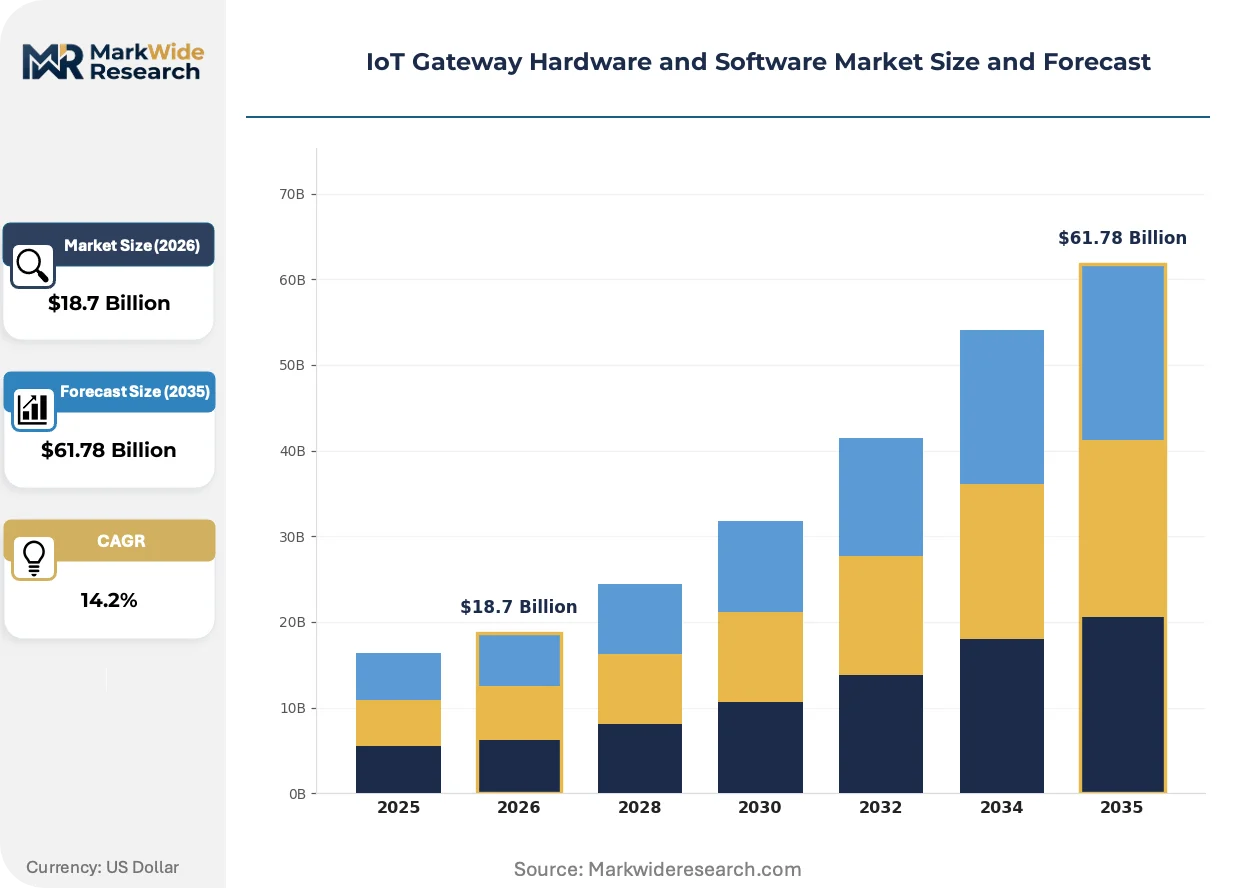
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Edge Gateways, Cloud Gateways, Multi-Service Gateways, Cellular Gateways Technology: Wi-Fi, Zigbee, LoRaWAN, Ethernet End User: Smart Home, Industrial Automation, Healthcare, Smart Cities Application: Data Aggregation, Device Management, Network Integration, Security Monitoring |
| Companies Covered | Cisco Systems, Inc., Advantech Co., Ltd., Intel Corporation, Qualcomm Technologies, Inc., Dell Technologies, Huawei Technologies Co., Ltd., NXP Semiconductors, Texas Instruments Incorporated, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Gateway Hardware and Software Market Shifts & Advancements
Gateway hardware architectures are fragmenting into modular, certification-swappable platforms as vendors confront divergent regional radio and security mandates.
Containerized edge runtime environments are modularizing gateway software stacks. Automotive Tier-1 suppliers in Stuttgart and Munich are deploying Kubernetes-based workloads directly onto ASIL-certified silicon. This architecture is modularizing the boundary between safety-critical and non-critical processing, compressing hardware SKU counts while expanding software attach rates.
GDPR data sovereignty enforcement is hardening cross-border gateway deployment rules. French cloud providers now mandate EU-resident edge nodes for sensitive industrial telemetry. German machinery exporters are responding by certifying gateway firmware through BSI-approved evaluation facilities rather than self-attestation.
Buyer preference is consolidating around subscription-based firmware maintenance. Industrial automation procurement teams in Turin and Barcelona are unbundling hardware CAPEX from security patch subscriptions. This shift is most visible among automotive suppliers facing CSRD supply chain disclosure requirements.
IoT Gateway Hardware and Software Market Segmentation
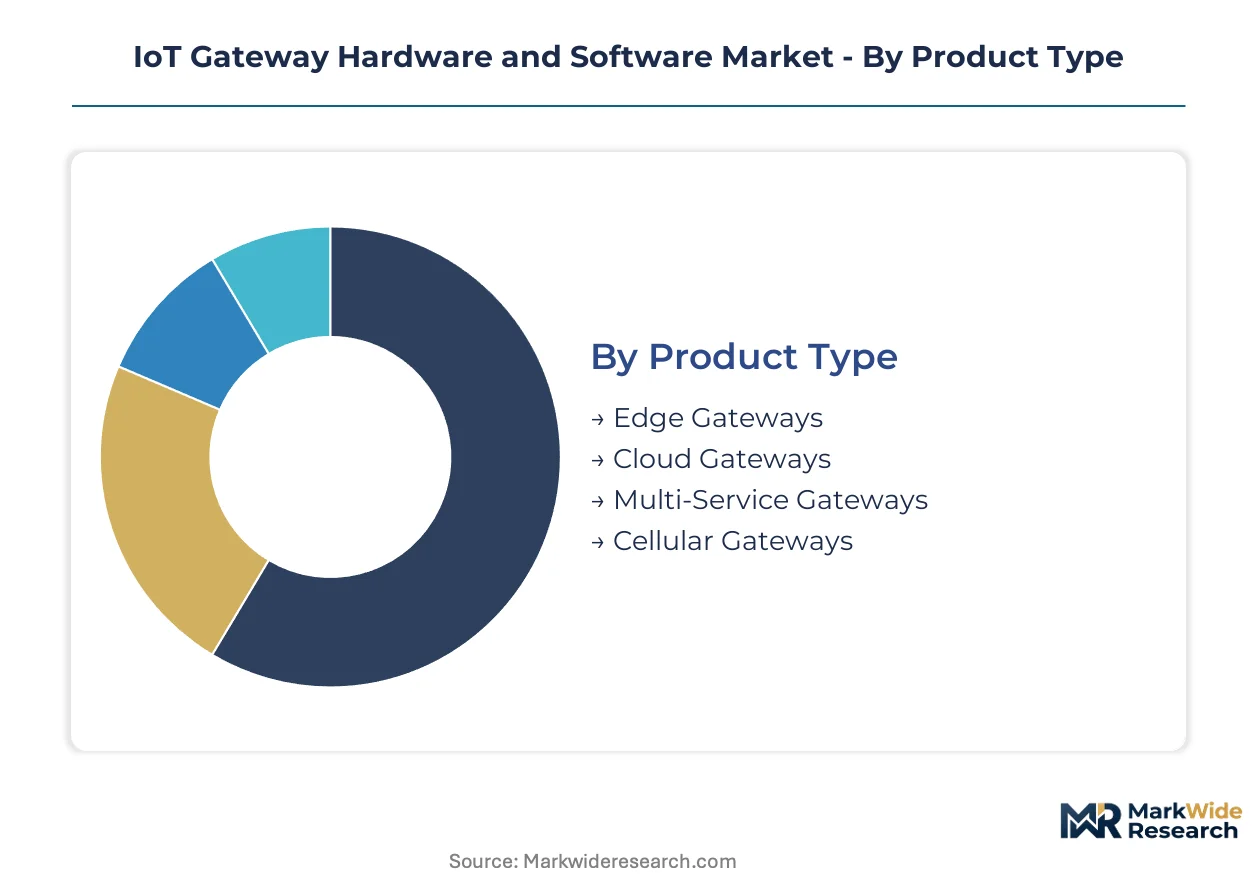
IoT gateway procurement patterns diverge sharply across deployment contexts. Factory-floor buyers prioritize deterministic latency and protocol translation depth, while municipal and healthcare purchasers weigh data sovereignty compliance and firmware maintenance terms more heavily.
Product Type:
Hardware enclosure specifications and software attach rates separate buyers by total cost of ownership horizons and operational environment severity.
- Edge Gateways:Fanless industrial enclosures integrate protocol translation, local analytics, and cryptographic security within extended temperature-rated hardware. German automotive OEMs in Stuttgart and Munich now require on-premise inference capabilities, pulling high-specification units into production lines.
- Multi-Service Gateways:Modular architectures support swappable radio modules and containerized runtime environments. Containerized edge runtime environments are modularizing gateway software stacks, with automotive Tier-1 suppliers deploying Kubernetes-based workloads directly onto ASIL-certified silicon.
- Cloud Gateways:Bridge field devices to cloud infrastructure with limited local processing. Dutch hospital networks seek HIPAA-equivalent configurations for continuous vital sign streaming.
- Cellular Gateways:Embedded cellular modems enable wide-area connectivity without fixed infrastructure. 5G RedCap module convergence is displacing dual-radio legacy units in agricultural telemetry across Italy and Poland.
Volume sits with Edge Gateways; growth tilts toward Multi-Service Gateways.
Technology:
Latency tolerance and spectrum licensing costs drive technology selection across utility, factory, and building automation contexts.
- Ethernet:Deterministic latency and packet-switched reliability dominate factory-floor deployments. Factory-floor buyers in Turin reject wireless alternatives where millisecond-level synchronization matters for robotic coordination.
- LoRaWAN:Unlicensed spectrum operation enables long-range, low-power telemetry networks. Water and electricity distribution operators across Italy and Poland are replacing manual meter reading with gateway networks spanning rural distribution zones.
- Wi-Fi:High-throughput local area connectivity supports video analytics preprocessing. French municipal infrastructure budgets redirect toward edge gateways that preprocess surveillance feeds before cloud transmission.
- Zigbee:Mesh networking protocol optimized for building automation sensor density. Nordic building automation retrofits create demand for gateways integrating HVAC and lighting control under EU Green Deal mandates.
Deployment breadth favors Ethernet; expansion velocity clusters with LoRaWAN.
End User:
Regulatory exposure and supply chain disclosure requirements reshape procurement criteria across verticals.
- Industrial Automation:Ruggedized hardware with IEC 62443 certification and automated patch pipelines. Automotive suppliers face CSRD supply chain disclosure requirements, unbundling hardware CAPEX from security patch subscriptions.
- Smart Cities:Video analytics convergence and cross-departmental data sharing protocols. Spanish municipal budgets prioritize edge preprocessing to reduce cloud transmission costs for surveillance infrastructure.
- Healthcare:Continuous patient monitoring with GDPR-aligned data residency guarantees. Belgian hospital networks mandate EU-resident edge nodes for sensitive telemetry under French cloud provider requirements.
- Smart Home:Consumer-grade connectivity with simplified installation and mobile app management. ETSI EN 303 645 baseline cybersecurity certification adds engineering overhead that compresses margins on economy-tier SKUs.
Revenue concentration remains with Industrial Automation; steepest expansion trajectory emerges in Healthcare.
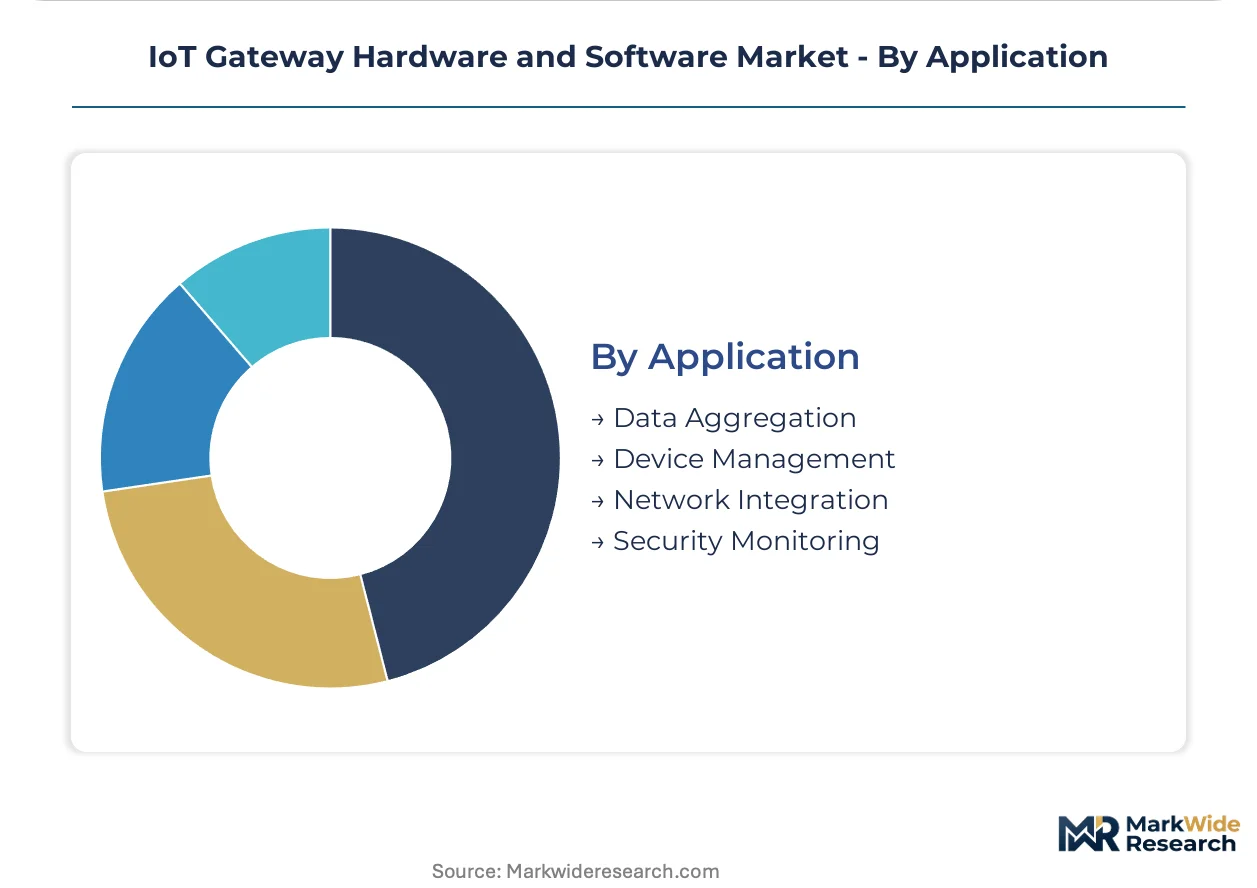
Application:
Functional depth requirements separate buyers by IT-OT integration maturity and security operations staffing levels.
- Device Management:Firmware orchestration, certificate lifecycle management, and remote configuration deployment. EU Cyber Resilience Act mandates extend mandatory vulnerability disclosure and update obligations to gateway firmware.
- Security Monitoring:Intrusion detection, anomaly classification, and encrypted tunnel termination. Gateway vendors lack DevOps pipelines to deliver CVE fixes within 24-hour windows demanded by IEC 62443-4-2.
- Data Aggregation:Protocol normalization and time-series buffering for upstream analytics. OPC-UA, MQTT, and Modbus coexistence requires scarce firmware engineering specialization.
- Network Integration:Bridging heterogeneous fieldbus and IP networks with QoS enforcement. German machinery exporters certify firmware through BSI-approved evaluation facilities rather than self-attestation.
Deployment scale clusters with Data Aggregation; capability investment flows toward Security Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gateway procurement concentrates in Germany, where automotive OEMs in Stuttgart and Munich require ASIL-certified inference hardware for production line deployment. The EU Cyber Resilience Act and GDPR enforcement are hardening certification requirements across European industrial clusters.
Germany
Automotive and machinery OEMs in Baden-Württemberg and Bavaria drive high-specification gateway procurement for factory-floor inference. The EU AI Act mandates on-premise processing for sensitive industrial data, compelling BSI-approved firmware certification. Stuttgart-based Tier-1 suppliers deploy Kubernetes workloads onto ASIL-certified silicon for safety-critical applications.
United States
FCC equipment authorization rules shape radio module selection for industrial and smart city deployments. The IRA energy efficiency incentives accelerate building automation retrofits in California and Texas. Dallas-Fort Worth industrial parks demand deterministic Ethernet gateways for robotic coordination systems.
France
Municipal infrastructure budgets redirect toward edge preprocessing for surveillance analytics under CNIL data residency guidance. The EU Green Deal mandates HVAC integration in commercial building retrofits across Île-de-France. Lyon and Marseille smart city deployments prioritize gateways with automated patch pipelines for IEC 62443 compliance.
Italy
Water and electricity distribution operators replace manual meter reading with LoRaWAN gateway networks spanning rural zones. ETSI EN 303 645 baseline cybersecurity certification adds engineering overhead for economy-tier SKUs. Turin automotive suppliers unbundle hardware CAPEX from security patch subscriptions under CSRD disclosure requirements.
Netherlands
Hospital networks in Amsterdam and Rotterdam seek HIPAA-equivalent edge gateways for continuous vital sign streaming. GDPR enforcement compels EU-resident edge nodes for sensitive healthcare telemetry. Eindhoven semiconductor clusters drive demand for modular hardware with swappable radio modules.
IoT Gateway Hardware and Software Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors confront divergent regional radio and security mandates. The vendor base organizes around three tiers: captive silicon integrators with enterprise channel density, ruggedized industrial specialists, and modular platform architects. Two strategic archetypes predominate: semiconductor vendors controlling automotive-grade processing platforms, and system integrators bundling hardware with subscription firmware maintenance. Competitive intensity centers on automated patch pipeline development and BSI-approved certification pathways.
Within the captive silicon tier, Cisco Systems, Inc. and NXP Semiconductors exemplify divergent approaches to supply continuity. Cisco anchors enterprise channel density through captive silicon partnerships, while NXP occupies a position in automotive-grade gateway silicon with ASIL-certified processing platforms. Advantech Co., Ltd. represents the ruggedized industrial specialist archetype, serving factory-floor deployments with extended temperature-rated enclosures.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Advantech Co., Ltd. |
| Intel Corporation |
| Qualcomm Technologies, Inc. |
| Dell Technologies |
| Huawei Technologies Co., Ltd. |
| NXP Semiconductors |
| Texas Instruments Incorporated |
| STMicroelectronics |
| Others |
Supply & Pricing Matrix
German automotive OEM procurement teams now mandate BSI-approved firmware certification under EU AI Act edge deployment rules, forcing gateway vendors to absorb third-party evaluation costs that compress margins on non-certified economy-tier units while widening spreads for ASIL-certified premium configurations.
Pricing Analysis
Volume concentrates in edge gateways where subscription-based firmware maintenance is unbundling from hardware CAPEX, while margins concentrate in multi-service gateways with containerized runtime environments. Pricing stratifies across ASIL-certified automotive tiers, IEC 62443-compliant industrial tiers, and economy SKUs serving smart home deployments. Cost compression in economy tiers intensifies because ETSI EN 303 645 baseline cybersecurity certification adds engineering overhead that vendors struggle to recover. Healthcare buyers in the Netherlands and Belgium exhibit lowest price sensitivity due to HIPAA-equivalent data residency requirements, while smart home distributors in Southern Europe drive hardest bargain on unit economics.
Supply Chain Analysis
Multi-source procurement mandates from industrial automation buyers in Germany and Italy are forcing qualification of secondary cellular modem vendors beyond Qualcomm and MediaTek dominant positions. Gateway silicon concentrates in Taiwan, South Korea, and the Netherlands, with automotive-grade security chipsets drawing from NXP's Eindhoven fabs and Infineon's Dresden capacity. Single-source vulnerability in ASIL-certified processing platforms creates allocation bottlenecks during automotive production ramps. Distribution runs through enterprise channel partners in Stuttgart and Munich for factory-floor deployments, while cloud service providers in France and the Netherlands direct procurement for healthcare and smart city verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IoT gateway market functions as a cost-of-compliance story where EU Cyber Resilience Act firmware mandates create a barrier-to-entry moat favoring vendors with automated patch pipelines and BSI-approved certification pathways.
For Market Incumbents: Acquire automated DevOps pipeline capabilities to deliver CVE fixes within IEC 62443-4-2 windows, while consolidating channel control through captive silicon partnerships that lock out modular competitors. NXP and Cisco positions face substitution threat from containerized runtime environments deploying on ASIL-certified silicon; defend by deepening firmware engineering specialization for OPC-UA, MQTT, and Modbus multi-protocol integration. For New Entrants and Emerging Players: Direct-to-cloud gateway configurations for Dutch and Belgian hospital networks offer the most penetrable white-space, as HIPAA-equivalent data residency requirements have slowed incumbent response times. Target 5G RedCap module convergence in Italian and Polish agricultural telemetry, where dual-radio legacy unit displacement creates hardware refresh cycles without entrenched vendor relationships. For Investors and Strategic Acquirers: The window for entry favors modular platform architects with swappable radio module architectures, as regional certification fragmentation accelerates demand for hardware flexibility across FCC, ETSI, and BSI jurisdictions. Watch automated patch pipeline development velocity as the inflection signal distinguishing viable acquisition targets from compliance-lagged legacy vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Patch Pipeline Development | EU Cyber Resilience Act mandates 24-hour CVE response windows for IEC 62443-4-2 certified deployments. |
| BSI-Approved Firmware Certification | German machinery exporters now require third-party evaluation facilities rather than self-attestation for EU AI Act compliance. |
| 5G RedCap Module Integration | Mid-band cellular gateways displace dual-radio legacy units in Italian and Polish agricultural telemetry networks. |
| Containerized Runtime Environment Deployment | Stuttgart-based Tier-1 suppliers deploy Kubernetes workloads directly onto ASIL-certified silicon for safety-critical applications. |
| Multi-Protocol Firmware Engineering | OPC-UA, MQTT, and Modbus coexistence in single-gateway deployments requires scarce specialization that commands premium pricing. |
Research Methodology
Document review covered SEC filings from gateway hardware vendors, ETSI and IEC standardization documents, and EU regulatory guidance on the Cyber Resilience Act and AI Act, complemented by interviews with industrial automation procurement directors, automotive Tier-1 supplier platform engineers, healthcare IT security officers, and smart city infrastructure planners. Secondary validation drew from FCC equipment authorization databases, BSI certification registries, and customs trade data on cellular modem imports. Bottom-up unit shipment estimates from factory-floor deployments in Germany and Italy were triangulated against top-down market sizing from subscription revenue disclosures.
Cross-referencing historical certification timelines against expert panel input on regulatory implementation velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include gateway product type, connectivity technology, end-user vertical, and application function, with additional weighting for regional regulatory cluster intensity. CAGRs were derived from slope analysis of disclosed subscription attach rates and disclosed ASIL-certified silicon volume commitments. Industry-specific inputs encompassed LoRaWAN network deployment pace from Italian utility operators and 5G RedCap module availability schedules from semiconductor vendors.
Inputs from BSI evaluation facility records and EU regulatory guidance documents were available through the study window; gaps in real-time CVE patch delivery performance metrics from private vendor pipelines introduce uncertainty bands around compliance cost estimates. Forecasts reflect assumptions on regulatory enforcement consistency and cellular modem supply allocation stability. Deviation in EU Cyber Resilience Act implementation timelines or automotive-grade security chipset foundry capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Services Market
Internet of Things (IoT)
Europe IoT Market
Internet of Things (IoT)
Global Embedded Security for Internet of Things Market
Internet of Things (IoT)
IoT in Manufacturing Market
Internet of Things (IoT)
North America Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
IoT Smart Poles Market
Internet of Things (IoT)
Global Open IoT Platform Market
Internet of Things (IoT)
Global IoT in Smart Cities Market
Internet of Things (IoT)
Middle East and Africa IoT Node and Gateway Market
Internet of Things (IoT)
Internet of Things (IoT) in Utilities Market
Internet of Things (IoT)
Asia-Pacific Massive IoT Market
Internet of Things (IoT)
Global Satellite Enabled IoT Software Market
Internet of Things (IoT)
IoT Data Governance Market
Internet of Things (IoT)
Global 5G Industrial IOT Market
Internet of Things (IoT)
Global Agile IoT Market
Internet of Things (IoT)
IoT Communication Technologies Market