
 IoT Application Enablement Market | 2026-2036
IoT Application Enablement Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Application Enablement Market Foresight
Embedded systems engineering talent scarcity is unwinding deployment timelines for complex edge-to-cloud integrations. Tata Consultancy Services anchors its competitive stance through deep manufacturing vertical expertise and global delivery scale. EPAM Systems differentiates via high-velocity application development frameworks tailored to regulated industries. SoftServe competes by blending IoT platform engineering with dedicated data science pods for healthcare and retail clients.
IoT Application Enablement encompasses middleware, platform tools, and integration services that abstract device connectivity, data ingestion, and application logic deployment across distributed sensor networks. These systems typically support sub-100ms latency thresholds for edge-triggered actions while normalizing telemetry from heterogeneous protocols into unified data models for enterprise software consumption. Cloud-based deployment leads in revenue contribution due to elastic scalability and reduced capital overhead, though edge computing represents the fastest-expanding configuration as latency-sensitive use cases multiply in autonomous systems and precision manufacturing. Platform-as-a-Service solutions command the deepest margin pools because they lock in recurring subscription revenue and reduce customer switching through proprietary device management and API ecosystems.
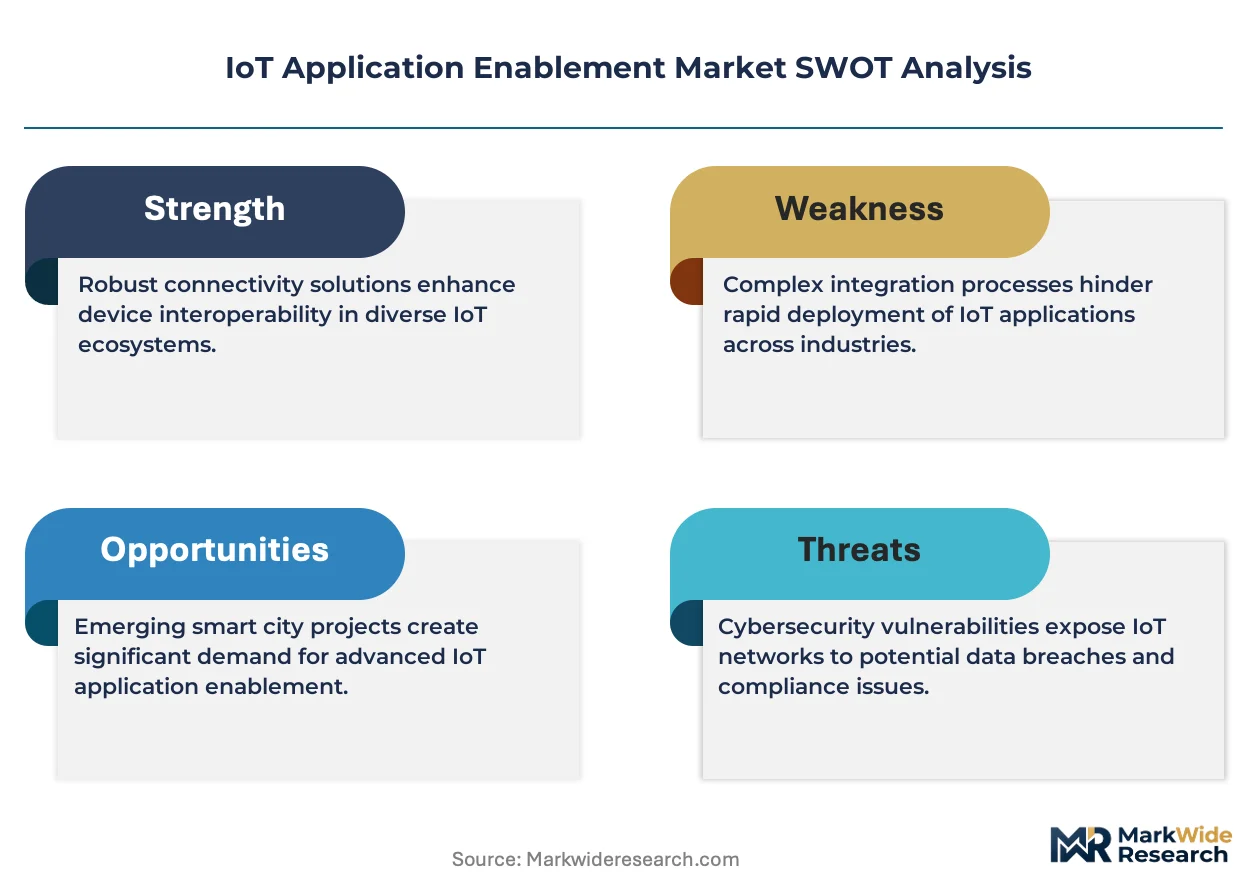
FCC guidelines on spectrum allocation for unlicensed IoT networks shape connectivity protocol availability and device certification pathways in the United States. FDA cybersecurity guidance for connected medical devices imposes pre-market validation requirements that filter vendor eligibility in healthcare segments. GDPR and the EU AI Act collectively mandate data residency controls and algorithmic transparency documentation that increase platform engineering costs but create compliance-based differentiation for prepared providers. Stakeholders must weigh the trade-off between vertical platform depth and horizontal scalability when allocating R&D budgets across emerging connectivity standards and evolving regulatory perimeters.
Market Dynamics
The EU AI Act and GDPR compliance deadlines are forcing platform vendors to re-architect data pipelines and embed algorithmic accountability by default, compressing product roadmaps and raising engineering costs across European deployments.
Growth Catalysts
- Industrial IoT mandates:Federal infrastructure digitization programs in the United States are accelerating enterprise procurement of application enablement layers for predictive maintenance and asset tracking.
- Edge computing convergence:Latency-sensitive autonomous systems and precision manufacturing workflows are pulling compute closer to sensors, expanding addressable platform configurations.
- GDPR data residency:European enterprises must localize telemetry processing, creating sustained demand for region-homed platform instances and sovereign cloud partnerships.
Market Restraints
- Embedded systems talent scarcity:Shortages of firmware engineers and edge-to-cloud integration specialists are extending deployment timelines and inflating professional services costs.
- Protocol fragmentation:Proliferation of connectivity standards across unlicensed spectrum allocations complicates device certification and platform interoperability.
- Substitution by hyperscalers:AWS IoT Core, Azure IoT Hub, and Google Cloud IoT are bundling enablement capabilities into broader cloud contracts, compressing standalone platform margins.
Strategic Opportunities
- Healthcare cybersecurity compliance:FDA pre-market validation requirements for connected medical devices filter vendor eligibility, creating compliance-based moats for prepared platform providers.
- Retail data science pods:Dedicated analytics teams embedded within IoT platform engagements unlock recurring revenue through outcome-based optimization contracts.
- Manufacturing vertical depth:Deep integration with ERP and MES systems in discrete and process manufacturing segments reduces customer switching and extends contract tenures.
Industry Challenges
- Edge-to-cloud integration complexity:Heterogeneous sensor protocols and sub-100ms latency requirements strain engineering teams and delay production deployments.
- Algorithmic transparency documentation:EU AI Act mandates for explainable AI increase platform engineering overhead and require specialized compliance personnel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Application Enablement Market |
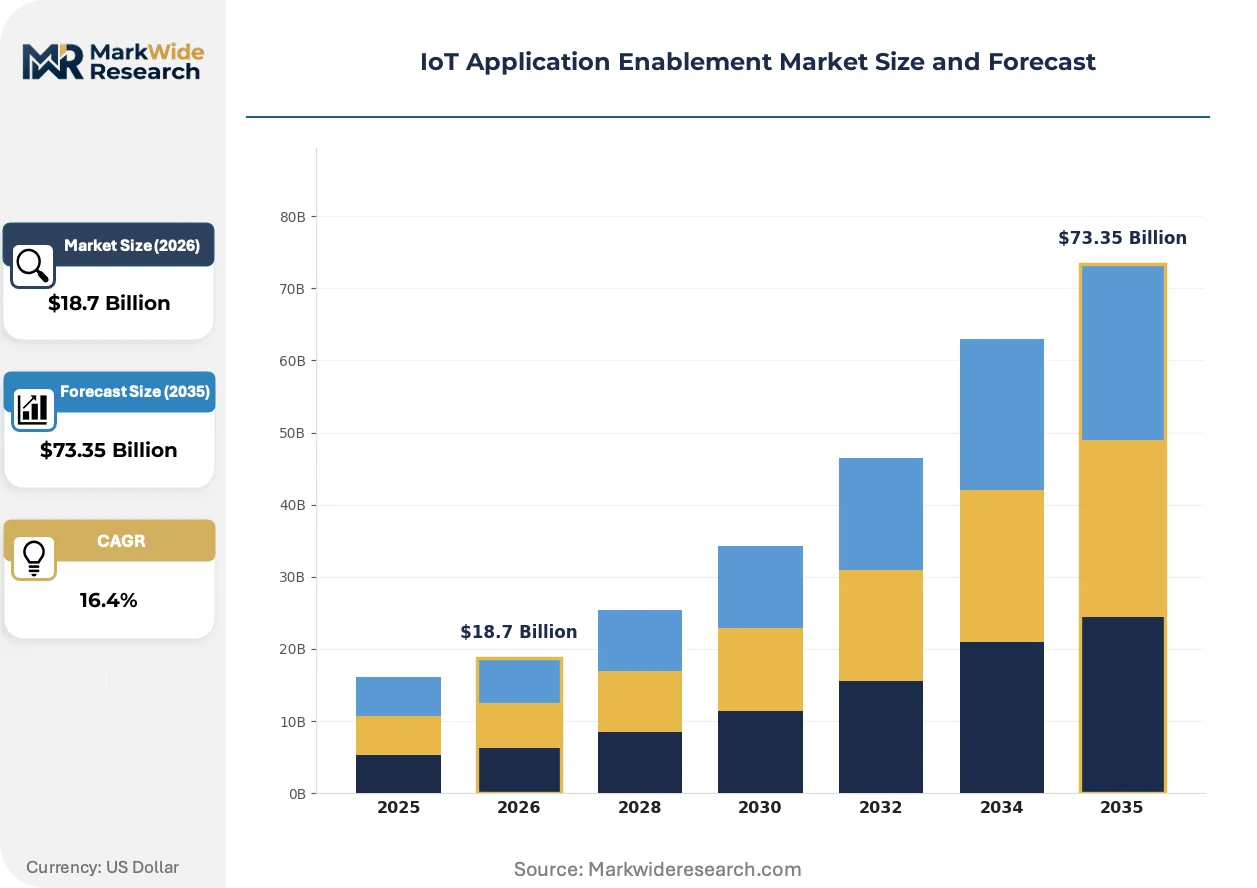
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, Edge Computing End User: Healthcare, Manufacturing, Transportation, Retail Solution: Platform-as-a-Service, Data Analytics, Application Development, Device Management Technology: Machine Learning, Blockchain, APIs, Connectivity Protocols |
| Companies Covered | Cognizant, Capgemini Engineering, Tata Consultancy Services, HARMAN, SoftServe, EPAM Systems, Infosys, Azilen Technologies, Wipro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Application Enablement Market Shifts & Advancements
Platform architecture decisions are increasingly governed by latency requirements and regulatory perimeters rather than cost optimization alone, reshaping vendor R&D allocation and partnership strategies.
Digital twin implementations are supplanting static asset monitoring dashboards in heavy manufacturing and energy infrastructure. Siemens, GE, and Schneider Electric are deploying these virtual replicas at scale across turbine fleets and distribution networks. This technology is supplanting traditional SCADA-centric visualization layers with simulation-driven operational intelligence that compresses maintenance cycles and extends asset lifecycles.
The EU AI Act's risk-based classification system mandates algorithmic impact assessments for high-risk IoT applications including biometric identification and critical infrastructure monitoring. Platform vendors must now maintain technical documentation, human oversight protocols, and conformity assessment procedures that were previously voluntary. Healthcare and transportation segments in Germany, France, and the Netherlands are restructuring procurement criteria to prioritize vendors with pre-certified compliance frameworks.
Enterprise buyers are consolidating vendor relationships around integrated platform-as-a-service stacks that bundle device management, data ingestion, and application logic deployment. Discrete manufacturers in the United States are shifting from best-of-breed point solutions toward single-voltage contracts with API ecosystem depth. This concentration pattern is most visible in automotive and aerospace supply chains, where tier-one suppliers demand unified telemetry pipelines feeding both operational dashboards and regulatory audit trails.
IoT Application Enablement Market Segmentation
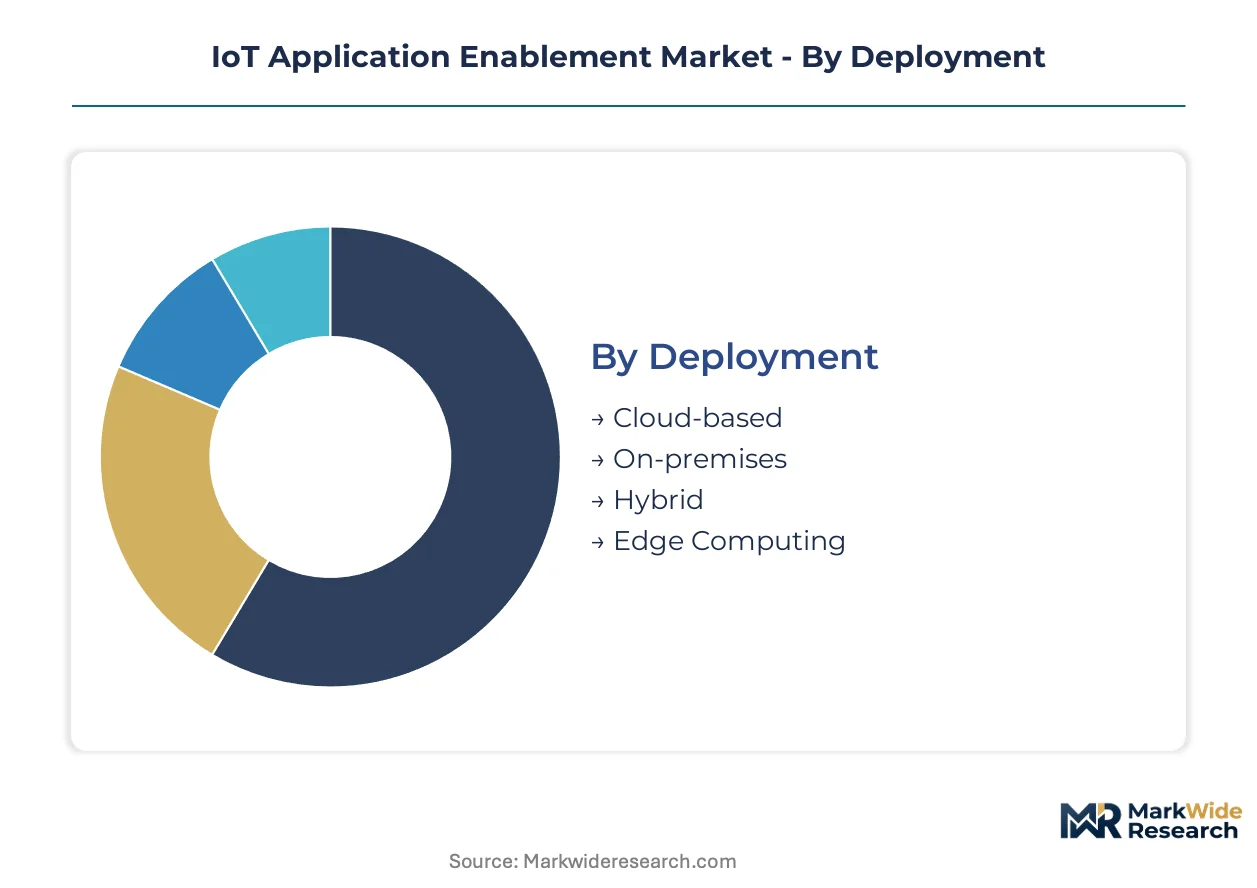
IoT Application Enablement platforms fragment across deployment architectures, end-use verticals, solution stacks, and underlying technologies. Each dimension carries distinct margin profiles, regulatory exposure, and talent requirements that reshape vendor positioning.
Deployment:
Domestic infrastructure mandates in the United States and data residency requirements in Germany and France are pulling cloud and edge configurations in divergent directions, while hybrid models serve export-oriented manufacturers with distributed operations.
- Cloud-based:Elastic compute pools abstract device management and data ingestion through multi-tenant architectures. United States federal infrastructure digitization programs are accelerating procurement of cloud-homed application enablement layers for predictive maintenance and asset tracking across defense and energy contractors.
- Edge Computing:Sub-100ms latency thresholds for autonomous systems and precision manufacturing workflows demand localized processing. German automotive suppliers and Japanese robotics manufacturers are deploying edge-native platforms to avoid telemetry round-trips to distant cloud regions.
- On-premises:Air-gapped installations serve defense, critical infrastructure, and healthcare providers with strict data sovereignty requirements. These deployments carry higher capital overhead but eliminate third-party access risks.
- Hybrid:Split architectures route sensitive telemetry to local instances while pushing analytics workloads to cloud regions. This configuration dominates among multinational manufacturers with ERP integration requirements spanning multiple jurisdictions.
Cloud-based configurations command the established base. The steepest expansion runs through Edge Computing.
End User:
Regulatory intensity varies sharply across verticals, with FDA pre-market validation in healthcare and EU AI Act algorithmic accountability in transportation creating divergent compliance cost structures.
- Manufacturing:Discrete and process manufacturers deploy platforms to unify predictive maintenance with MES and ERP systems. United States aerospace and automotive supply chains are consolidating around single-vendor contracts with API ecosystem depth.
- Healthcare:Connected medical devices require FDA cybersecurity validation and HIPAA-compliant data pipelines. Pre-certified platform providers are capturing procurement preference as hospital systems restructure vendor relationships around integrated stacks.
- Transportation:Fleet management and autonomous vehicle telemetry platforms face EU AI Act risk classification for biometric identification and critical infrastructure monitoring. German and Dutch logistics operators are prioritizing vendors with algorithmic impact assessment documentation.
- Retail:Inventory optimization and customer analytics drive adoption among grocery and apparel chains. Dedicated data science pods embedded within platform engagements are unlocking recurring revenue through outcome-based optimization contracts.
Manufacturing retains the largest installed base. Healthcare is climbing the fastest as cybersecurity compliance filters reshape vendor eligibility.
Solution:
Margin pools concentrate in recurring subscription revenue, with platform-as-a-service offerings locking in customers through proprietary device management and API ecosystems.
- Platform-as-a-Service:Bundled device management, data ingestion, and application logic deployment through proprietary cloud instances. These solutions generate the deepest recurring revenue streams and highest switching costs.
- Data Analytics:Telemetry normalization and predictive modeling services that translate sensor feeds into operational intelligence. Demand concentrates in energy infrastructure and precision agriculture.
- Application Development:High-velocity frameworks for regulated industries, including pre-validated modules for FDA and EMA compliance pathways. EPAM Systems anchors competitive positioning in this segment.
- Device Management:Firmware orchestration, over-the-air updates, and certificate lifecycle management for heterogeneous sensor populations. Protocol fragmentation across unlicensed spectrum allocations complicates interoperability.
Platform-as-a-Service dominates current revenue contribution. Data Analytics is expanding most quickly as outcome-based pricing models mature.
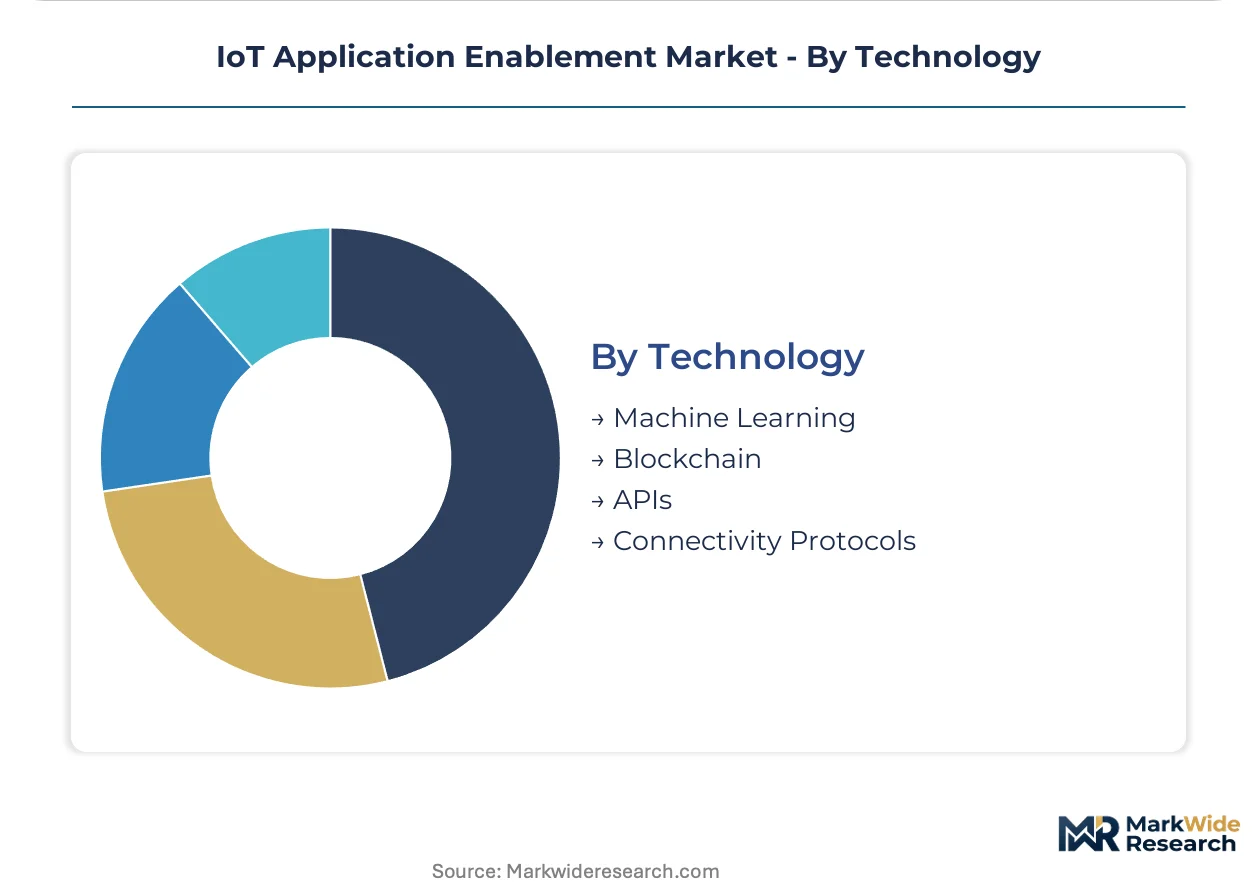
Technology:
Engineering talent scarcity is compressing deployment timelines for complex integrations, particularly where machine learning pipelines must meet sub-100ms latency thresholds.
- Machine Learning:Edge-triggered inference models for predictive maintenance and anomaly detection. EU AI Act documentation requirements for algorithmic transparency are increasing engineering overhead.
- APIs:Standardized interfaces connecting telemetry pipelines to enterprise software. Manufacturing buyers are demanding unified APIs feeding both operational dashboards and regulatory audit trails.
- Connectivity Protocols:LoRaWAN, NB-IoT, and private 5G implementations for unlicensed and licensed spectrum. FCC guidelines in the United States and ETSI standards in Europe shape device certification pathways.
- Blockchain:Immutable audit trails for supply chain provenance and regulatory compliance. Adoption remains concentrated in pharmaceutical cold chain and high-value asset tracking.
APIs and Connectivity Protocols constitute the mature foundation. Machine Learning is gaining share fastest as autonomous systems multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC spectrum allocation guidelines anchor United States demand, while EU AI Act compliance deadlines reshape European procurement criteria. Federal infrastructure digitization programs and data residency mandates are pulling regional deployment strategies in divergent directions.
United States
Industrial IoT mandates from federal infrastructure programs are accelerating enterprise procurement of application enablement layers. FCC guidelines on unlicensed spectrum shape connectivity protocol availability and device certification pathways. Defense contractors in Virginia and energy infrastructure operators in Texas are consolidating around single-vendor platform contracts with API ecosystem depth.
Germany
Automotive suppliers and robotics manufacturers demand sub-100ms latency thresholds for precision manufacturing workflows. EU AI Act algorithmic accountability requirements and GDPR data residency rules compress product roadmaps for platform vendors. Industrial clusters in Bavaria and Baden-Württemberg are deploying edge-native platforms to localize telemetry processing.
China
MIIT standards for industrial internet platforms are driving state-backed digitization across manufacturing bases. GB standards and dual carbon goals shape energy monitoring and predictive maintenance adoption patterns. Yangtze River Delta electronics manufacturers and Pearl River Delta logistics operators are building proprietary platform stacks with sovereign cloud integration.
Japan
METI smart factory initiatives are pulling IoT platform adoption into discrete manufacturing supply chains. JIS standards and PMDA cybersecurity guidance for connected medical devices filter vendor eligibility in healthcare segments. Automotive and robotics clusters in Aichi Prefecture and Kansai region are demanding unified telemetry pipelines feeding operational dashboards.
India
PLI scheme incentives for electronics manufacturing are expanding IoT platform deployments across contract fabrication facilities. BIS certification requirements and CEA grid modernization programs shape industrial connectivity adoption. Karnataka's technology corridor and Gujarat's industrial zones are emerging as concentration points for edge-to-cloud integration services.
IoT Application Enablement Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with global systems integrators commanding premium positioning through vertical expertise while mid-tier specialists compete on deployment velocity. The vendor base spans three strategic tiers: hyperscaler-aligned platforms, manufacturing-focused integrators, and healthcare-specialized compliance providers. Consolidation pressure is intensifying as AWS IoT Core, Azure IoT Hub, and Google Cloud IoT bundle enablement capabilities into broader cloud contracts. M&A activity targets embedded systems engineering talent, while strategic partnerships with sovereign cloud providers address European data residency requirements.
Within the manufacturing vertical tier, Tata Consultancy Services and Wipro represent scale-driven delivery archetypes with global footprint. EPAM Systems occupies a position exemplifying high-velocity application development frameworks for regulated industries. SoftServe sits within the healthcare-retail specialization vector, blending platform engineering with embedded data science capabilities. These three anchors illustrate how competitive positioning fragments across vertical depth, geographic delivery scale, and compliance-ready development velocity.
| Leading Market Players |
|---|
| Cognizant |
| Capgemini Engineering |
| Tata Consultancy Services |
| HARMAN |
| SoftServe |
| EPAM Systems |
| Infosys |
| Azilen Technologies |
| Wipro |
| Others |
Supply & Pricing Matrix
Hyperscaler cloud bundles substituting for standalone platform licenses simultaneously reshape supply geography toward concentrated cloud regions and compress pricing economics for independent vendors. Platform-as-a-Service providers face margin erosion as AWS IoT Core, Azure IoT Hub, and Google Cloud IoT absorb enablement capabilities into broader enterprise contracts.
Pricing Analysis
United States-based deployments command 15-25% premiums over equivalent European instances due to FCC certification overhead and federal compliance requirements. Pricing stratifies across premium certified tiers, standard SaaS subscriptions, and economy project-based engagements, with differentiation driven by FDA pre-market validation status and vertical integration depth. Cost compression in the economy tier intensifies because hyperscaler bundling eliminates standalone procurement for price-sensitive mid-market buyers. Discrete manufacturers exhibit the sharpest price sensitivity, while healthcare providers prioritize certification grade over unit cost.
Supply Chain Analysis
Firmware engineering talent scarcity in India, Germany, and the United States chokes platform development velocity and extends professional services delivery timelines. The supply chain draws from embedded systems specialists, cloud infrastructure providers, and sovereign cloud partners, with single-source vulnerability concentrated in edge-to-cloud integration expertise. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and hyperscaler marketplace listings, with channel control shifting toward consolidated platform-as-a-Service stacks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IoT Application Enablement functions as a service-attach opportunity where recurring subscription revenue from device management and API ecosystems expands faster than hardware-centric deployment fees. Platform vendors must architect for compliance-as-a-service layers that lock in customer retention through regulatory audit trail automation.
For Market Incumbents: Compound defensive positioning through backward integration into embedded systems engineering talent pools and certification investment in FDA pre-market validation pathways. Hyperscaler bundling threatens standalone margin structures, making vertical depth in manufacturing ERP integration the priority lever for contract renewal extension. For New Entrants and Emerging Players: FDA 510(k) fast-track certification unlocks healthcare procurement preference where cybersecurity compliance filters vendor eligibility. White-space concentrates in edge-native configurations for German automotive suppliers and retail data science pods for grocery chains, with outcome-based pricing as the dominant go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertical specialists with pre-certified compliance frameworks over horizontal generalists. Long-term viability hinges on recurring revenue depth and sovereign cloud partnership density, with hyperscaler acquisition appetite serving as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies device management, data ingestion, and application logic deployment through proprietary API ecosystems that increase switching costs. |
| Regulatory Certification Investment | FDA pre-market validation and EU AI Act algorithmic impact assessment documentation create compliance-based moats in healthcare and transportation segments. |
| Embedded Systems Talent Acquisition | Firmware engineering and edge-to-cloud integration specialists compress deployment timelines and enable sub-100ms latency configurations for autonomous systems. |
| Sovereign Cloud Partnership | GDPR data residency requirements in Germany and France demand region-homed platform instances that independent vendors cannot provision independently. |
| Vertical Application Development | High-velocity frameworks for regulated industries, including pre-validated modules for FDA and EMA compliance pathways, accelerate customer time-to-value. |
Research Methodology
Initial hypotheses were tested against primary input from platform engineering directors, healthcare IT procurement officers, manufacturing operations executives, and embedded systems specialists and refined through secondary validation. Primary research combined structured interviews with secondary analysis of SEC filings, hyperscaler capex disclosures, FDA 510(k) clearance databases, and EU AI Act conformity assessment documentation. Bottom-up segmentation modeling triangulated against top-down market sizing across deployment architectures, end-use verticals, and solution stacks.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within each segmentation dimension modeled: deployment configuration, end-use vertical, solution type, and underlying technology layer. CAGRs were derived from fitted growth curves anchored to observable adoption patterns in industrial IoT mandates and edge computing convergence trends. Forecast inputs incorporated FCC spectrum allocation guidelines, EU AI Act compliance deadlines, and embedded systems talent availability indices.
Underlying assumptions cover sustained federal infrastructure digitization program funding, stable hyperscaler bundling intensity, and gradual EU AI Act enforcement escalation, with deviation risk concentrated in regulatory timeline acceleration and talent scarcity deepening. Practitioners should keep alternative scenarios live as sovereign cloud partnership requirements and algorithmic transparency documentation burdens evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global IOT Gateway Market
Internet of Things (IoT)
North America IoT Software Market
Internet of Things (IoT)
IoT in Retail Market
Internet of Things (IoT)
Airline IoT Market
Internet of Things (IoT)
North America Industrial IoT Market
Internet of Things (IoT)
GCC Indoor LBS Market
Internet of Things (IoT)
Global Narrowband IoT Market
Internet of Things (IoT)
IoT Device Management Platform Market
Internet of Things (IoT)
Connected IoT Devices Market
Internet of Things (IoT)
Smart Tracker Market
Internet of Things (IoT)
Global Agile IoT Market
Internet of Things (IoT)
Global Internet of Behaviors Market
Internet of Things (IoT)
IoT Solutions Market
Internet of Things (IoT)
Global Satellite Enabled IoT Software Market
Internet of Things (IoT)
North America and Europe IoT Gateway Market
Internet of Things (IoT)
Europe IoT Services Market