
 Global Pervasive Computing Technology Market | 2026-2036
Global Pervasive Computing Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pervasive Computing Technology Market Foresight
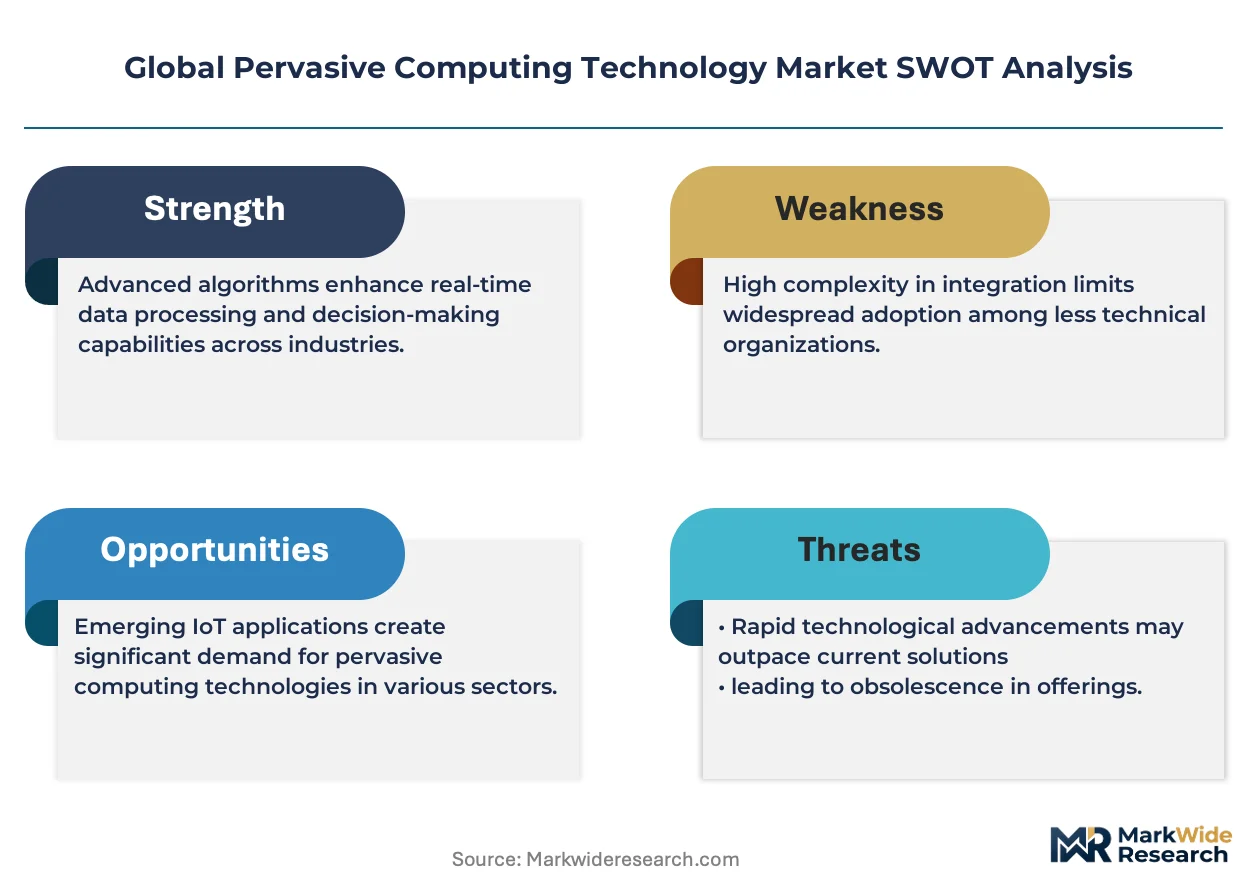
Healthcare delivery is decoupling from traditional facility-bound models as ambient sensing and remote patient monitoring penetrate clinical workflows. Cisco Systems dominates enterprise-grade networking infrastructure for distributed care environments, while Intel Corporation anchors semiconductor supply for edge-enabled medical devices. Qualcomm specializes in low-power wireless modems that sustain continuous biometric data streams across heterogeneous device fleets.
Pervasive computing technology encompasses embedded microprocessors, wireless communication protocols, and context-aware software layers that enable continuous, invisible computation throughout physical environments. These systems typically operate on sub-watt power budgets with latency thresholds under 50 milliseconds to support real-time responsiveness in safety-critical applications. Wireless sensor networks and edge computing deployment models currently lead commercial traction, while context-aware computing represents the fastest-expanding margin pool as enterprises prioritize predictive automation over reactive monitoring. RFID applications in transportation management retain mature, cost-optimized economics, though smart home deployments are accelerating fastest among consumer-facing segments.
The EU AI Act, GDPR, and CE marking frameworks collectively constrain algorithmic transparency and data residency for devices deployed across European healthcare and public safety networks. FDA guidance on software as a medical device and HIPAA interoperability rules similarly shape product architecture decisions for US market access. Japan's METI standards for industrial IoT security and South Korea's MFDS digital health certification pathways add further compliance layering for vendors targeting Asia-Pacific expansion. Stakeholders must monitor regulatory divergence between privacy-first European frameworks and performance-oriented Asian standards when architecting cross-border deployment strategies.
Market Dynamics
Ambient intelligence deployment in healthcare networks is restructuring procurement priorities, with hospital systems now prioritizing continuous biometric monitoring over discrete diagnostic equipment purchases.
Growth Catalysts
- EU AI Act compliance mandates:Healthcare providers across Germany, France, and Italy must replace legacy monitoring systems with algorithmically transparent devices, accelerating hardware refresh cycles.
- Industrial automation in South Korea:Smart factory deployments under METI-aligned standards are integrating pervasive sensing layers for predictive maintenance and worker safety monitoring.
- Edge AI chip architectures:Sub-watt neural processing units enable battery-powered ambient sensors that operate for years without maintenance, opening remote and mobile applications.
Market Restraints
- Advanced node semiconductor scarcity:Taiwan-based foundry concentration creates supply vulnerability for edge AI chips below 7nm, forcing design compromises on latency performance.
- GDPR data residency requirements:European healthcare networks must maintain biometric data within jurisdictional boundaries, complicating cloud-edge hybrid architectures.
- Interoperability protocol fragmentation:Competing wireless standards between Thread, Zigbee, and proprietary industrial protocols increase integration costs for multi-vendor deployments.
Strategic Opportunities
- Japan's aging-in-place infrastructure:Government-subsidized smart home retrofits for elderly populations create demand for non-intrusive fall detection and medication adherence systems.
- Digital therapeutics convergence:FDA-cleared software-as-medical-device pathways enable pharmaceutical companies to bundle ambient monitoring with drug therapies for chronic condition management.
- 5G RedCap modems:Reduced capability 5G variants bridge the gap between high-bandwidth and LPWAN protocols, simplifying connectivity architecture for mid-tier industrial deployments.
Industry Challenges
- Embedded systems security engineering:Shortage of firmware developers with hardware-level cryptography expertise delays product launches for regulated medical and automotive applications.
- CE-MDR technical documentation:European medical device regulation requires extensive clinical evidence for ambient monitoring algorithms, extending certification timelines to 18-24 months.
- Legacy SCADA integration:Industrial facilities struggle to bridge decades-old control systems with modern IP-based sensor networks without operational disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pervasive Computing Technology Market |
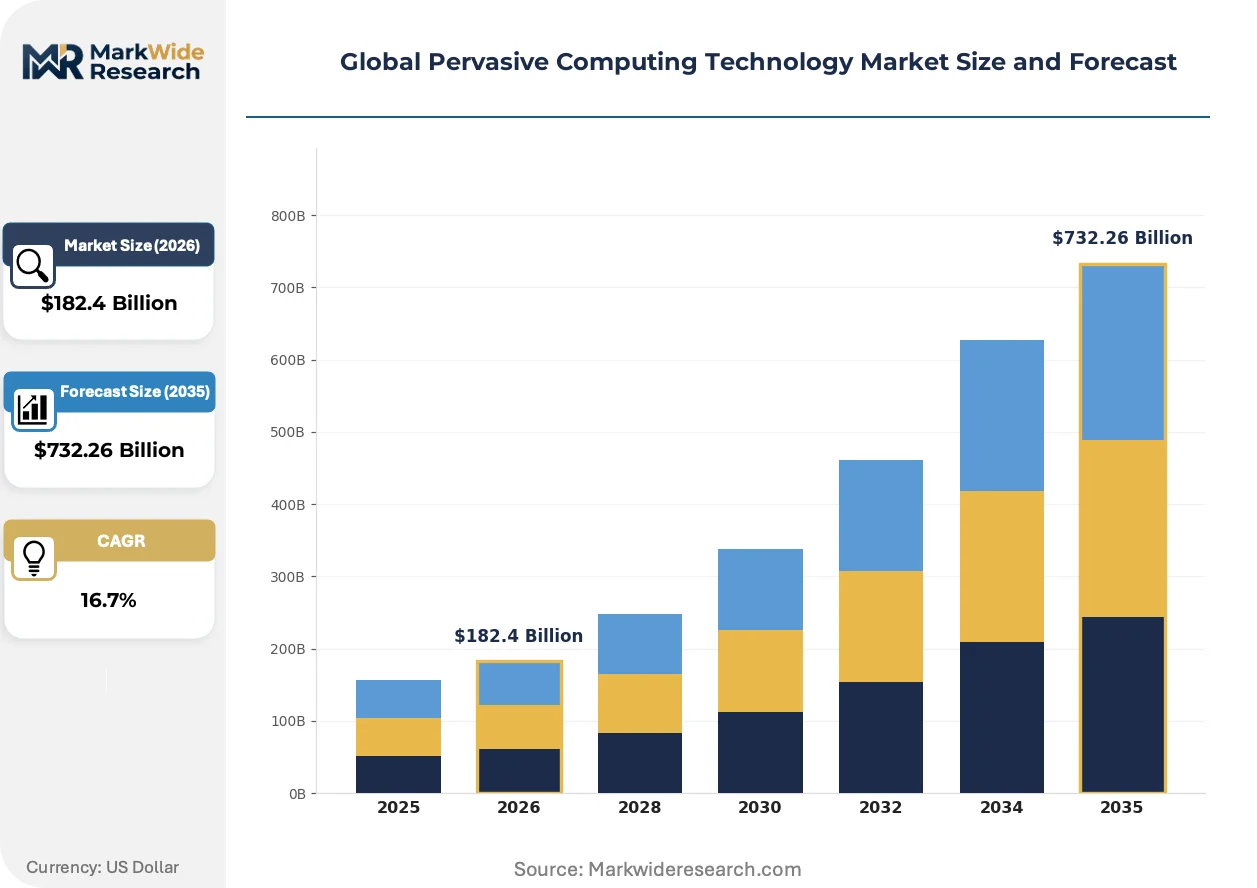
| Market Size in 2026 | $182.4 Billion |
| Market Size in 2035 | $732.26 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wireless Sensor Networks, RFID, Embedded Systems, Context-Aware Computing, Distributed Computing Application: Smart Homes, Wearable Devices, Environmental Monitoring, Transportation Management, Public Safety End User: Consumer Electronics Companies, Telecommunication Providers, Government Agencies, Transportation Operators, Environmental Organizations Deployment Model: Cloud-Based, Edge Computing, Fog Computing, On-Premises, Hybrid Systems |
| Companies Covered | Huawei Technologies Co. Ltd., Cisco Systems, Inc., Microsoft Corporation, Robert Bosch GmbH, SAP SE, Intel Corporation, Dell Technologies Inc., Qualcomm, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pervasive Computing Technology Market Shifts & Advancements
Federated learning architectures and on-device inference are redistributing computational workloads away from centralized cloud infrastructure toward distributed edge nodes.
Ultra-wideband positioning chips are consolidating indoor location accuracy to sub-10 centimeter precision, enabling spatial-aware automation in warehouses and hospitals. German automotive suppliers and Japanese electronics manufacturers are embedding these chips into asset tags and wearable devices at accelerating volumes. This consolidation is compressing the addressable market for legacy Bluetooth beacon systems while opening new revenue pools in real-time location services.
The EU AI Act's risk-based classification system is forcing algorithmic documentation and human-in-the-loop requirements for high-risk pervasive computing deployments. Device manufacturers serving European healthcare and public safety networks must now maintain technical files demonstrating bias mitigation and performance validation. South Korean and Japanese regulators are observing these European precedents, suggesting potential convergence in Asia-Pacific certification requirements.
Hospital procurement departments are unbundling hardware purchases from ongoing algorithm licensing, treating predictive analytics as separate subscription services. This disintermediation of software from sensor hardware is pressuring traditional device vendors to restructure pricing models. The shift is most visible in US health systems responding to Medicare reimbursement changes that reward outcome metrics over equipment ownership.
Global Pervasive Computing Technology Market Segmentation
Pervasive computing technology fragments across multiple technical and commercial dimensions, with each segmentation axis revealing distinct upgrade cycles and procurement patterns. Understanding these categories exposes where capital deployment concentrates and which technology layers command pricing power.
Technology:
Hardware refresh cycles in enterprise and industrial settings are compressing as edge AI capabilities mature, forcing organizations to evaluate which technology layers justify immediate replacement versus staged migration.
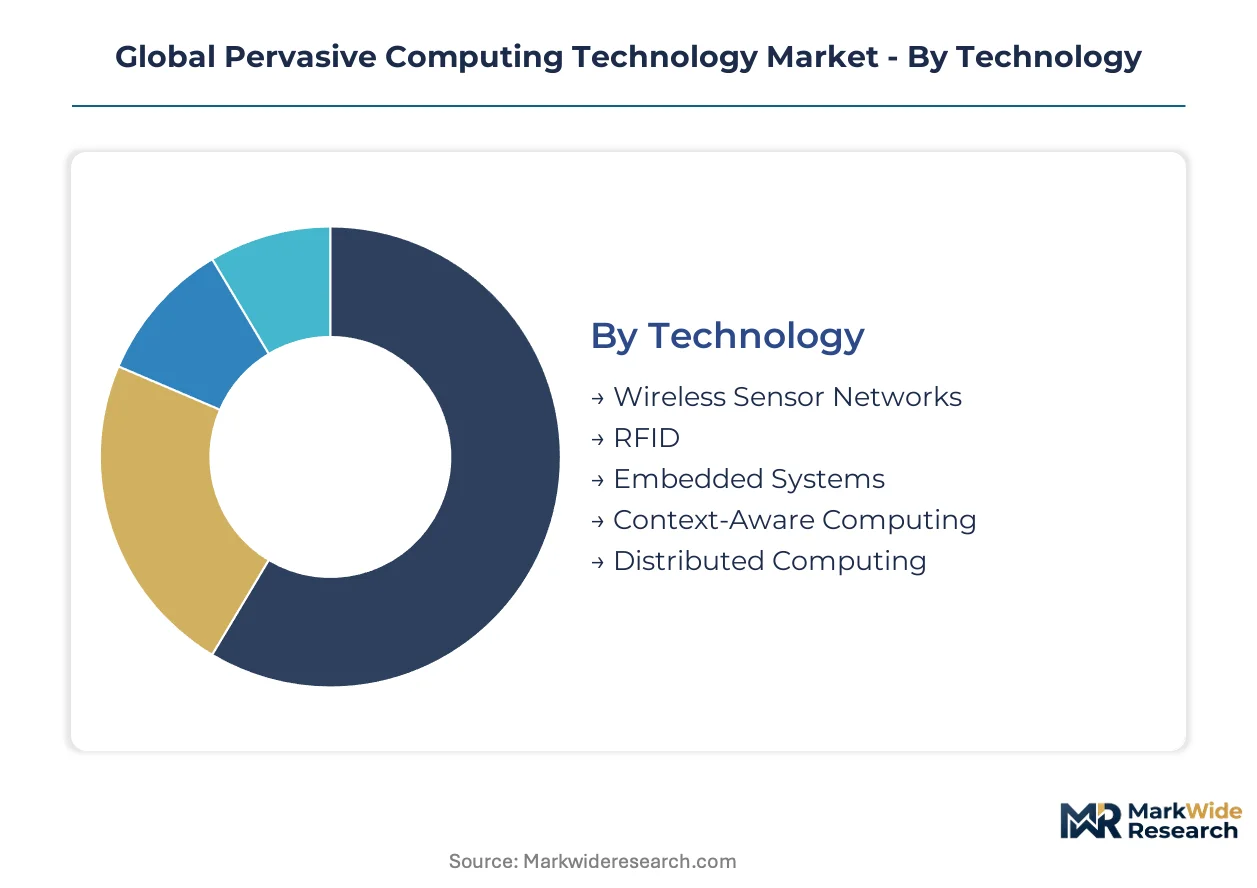
- Wireless Sensor Networks:Mesh architectures of battery-powered nodes communicate through low-power protocols to aggregate environmental and operational data. German automotive suppliers and Japanese electronics manufacturers deploy these networks for predictive maintenance, with GDPR data residency requirements complicating cross-border fleet management.
- Context-Aware Computing:Software layers interpret sensor fusion outputs to trigger automated responses based on location, activity, and environmental conditions. South Korean smart city infrastructure projects and US health systems prioritize this capability for ambient intelligence, though algorithmic transparency mandates under the EU AI Act extend certification timelines.
- RFID:Passive and active radio-frequency identification systems track assets through electromagnetic interrogation.
- Embedded Systems:Dedicated microcontrollers execute fixed functions within power-constrained device envelopes.
- Distributed Computing:Workload partitioning across networked nodes enables scalable processing without centralized infrastructure.
Wireless Sensor Networks sits at the top of the volume ranking, with Context-Aware Computing climbing the fastest.
Application:
Cost-tier differentiation separates premium deployments with full regulatory certification from economy implementations targeting consumer convenience.
- Smart Homes:Residential ecosystems integrate climate control, security, and appliance automation through unified platforms. Japan's government-subsidized aging-in-place retrofits concentrate demand for fall detection and medication adherence systems, while South Korean apartment developers bundle pervasive sensing as standard amenities.
- Wearable Devices:Body-worn sensors capture biometric streams for health monitoring and workplace safety applications. FDA-cleared software-as-medical-device pathways in the US and MFDS digital health certification in South Korea are restructuring how pharmaceutical companies bundle these devices with chronic disease therapies.
- Environmental Monitoring:Distributed sensors track air quality, water conditions, and ecological parameters for regulatory compliance and research.
- Transportation Management:Fleet tracking and logistics optimization systems leverage RFID and GPS fusion for supply chain visibility.
- Public Safety:Emergency response networks and critical infrastructure protection systems deploy pervasive sensing for threat detection.
Transportation Management holds the largest installed base, though Smart Homes is expanding most quickly as residential automation penetrates middle-income demographics.
End User:
Procurement sophistication varies sharply across customer types, with regulated industries demanding extensive documentation while consumer-facing buyers prioritize interoperability and price.
- Consumer Electronics Companies:Device manufacturers integrate pervasive computing modules into smartphones, tablets, and home appliances. These buyers face margin pressure from semiconductor scarcity at advanced nodes below 7nm, forcing design compromises on latency performance.
- Government Agencies:Public sector procurement spans defense, civilian infrastructure, and regulatory enforcement applications. European healthcare networks under GDPR and the EU AI Act must maintain biometric data within jurisdictional boundaries, complicating vendor selection for cloud-edge hybrid architectures.
- Telecommunication Providers:Network operators deploy pervasive infrastructure as platform services for enterprise customers.
- Transportation Operators:Logistics and transit authorities leverage tracking systems for fleet optimization and passenger safety.
- Environmental Organizations:Research institutions and advocacy groups deploy monitoring networks for ecological assessment and policy support.
Government Agencies command the longest sales cycles, with Consumer Electronics Companies driving the steepest volume expansion.
Deployment Model:
Geographic concentration of cloud infrastructure versus edge hardware manufacturing shapes regional preferences for centralized versus distributed architectures.
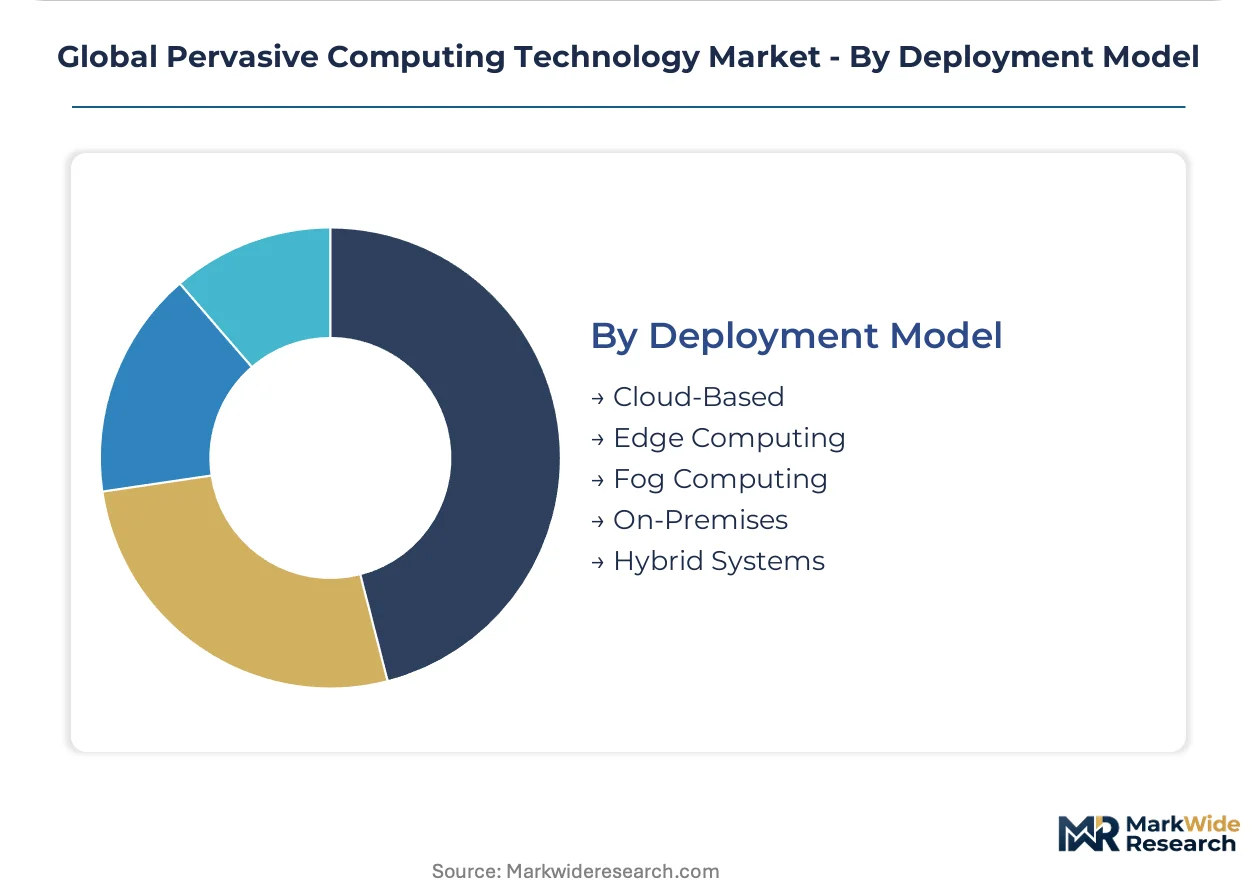
- Edge Computing:Processing occurs at or near data sources to minimize latency and bandwidth consumption. Industrial automation in South Korea under METI-aligned standards and German smart factory deployments favor this model for predictive maintenance and worker safety monitoring requiring sub-50 millisecond response thresholds.
- Hybrid Systems:Architectures dynamically partition workloads between cloud, edge, and on-premises resources based on latency, cost, and compliance requirements. US health systems responding to Medicare reimbursement changes favor this flexibility for outcome-based care models that reward continuous monitoring over equipment ownership.
- Cloud-Based:Centralized data centers host computation and storage for multi-tenant application delivery.
- Fog Computing:Intermediate layers between edge devices and cloud infrastructure enable localized coordination.
- On-Premises:Dedicated infrastructure within organizational boundaries satisfies strict data sovereignty and security requirements.
Edge Computing leads deployment discussions, while Hybrid Systems is gaining share fastest as organizations seek regulatory flexibility without sacrificing responsiveness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial corridor anchors pervasive computing deployment through smart factory retrofits and automotive supplier networks. The EU AI Act and CE-MDR frameworks reshape procurement across European manufacturing and healthcare sectors. German industrial clusters in Bavaria and Baden-Württemberg integrate edge-enabled sensors for predictive maintenance under METI-influenced security standards.
United States
Hospital systems in Texas and California accelerate ambient intelligence adoption for remote patient monitoring and clinical workflow automation. FDA software-as-medical-device guidance and HIPAA interoperability rules constrain cloud-edge hybrid architectures for biometric data processing. The Boston-Cambridge corridor hosts concentrated R&D activity for federated learning architectures in healthcare applications.
Japan
Government-subsidized aging-in-place programs in Tokyo and Osaka prefectures drive demand for non-intrusive fall detection and medication adherence systems. METI industrial IoT security standards mandate encryption protocols for factory sensor networks. The Chubu region around Nagoya anchors automotive supplier integration of ultra-wideband positioning chips into asset tracking systems.
South Korea
Smart factory deployments under MFDS digital health certification pathways integrate pervasive sensing for worker safety and predictive maintenance. Seoul Capital Area apartment developers bundle ambient intelligence as standard amenities in new construction. Busan-Ulsan industrial complexes deploy 5G RedCap modems to bridge high-bandwidth and LPWAN protocol requirements.
China
Yangtze River Delta manufacturing clusters advance industrial automation through edge AI chip deployment for sub-50 millisecond response thresholds. MIIT standards for wireless communication protocols shape domestic procurement preferences for sensor networks. Pearl River Delta electronics manufacturers concentrate production of ultra-wideband positioning chips for regional smart city infrastructure.
Global Pervasive Computing Technology Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors bridge hardware-software gaps in regulated healthcare and industrial deployments. The vendor base stratifies across three tiers: diversified technology conglomerates with full-stack capabilities, specialized semiconductor suppliers focused on edge AI architectures, and regional system integrators serving localized compliance requirements. Portfolio diversification and technology licensing represent the primary competitive vectors as firms expand beyond core competencies into adjacent sensing and analytics layers.
Within the diversified technology tier, Cisco Systems, Microsoft Corporation, and Intel Corporation exemplify contrasting strategic positions. Cisco Systems anchors enterprise-grade networking infrastructure for distributed care environments. Microsoft Corporation occupies a position spanning cloud platforms and edge software layers. Intel Corporation represents semiconductor supply concentration for sub-watt neural processing units in battery-constrained medical devices.
| Leading Market Players |
|---|
| Huawei Technologies Co. Ltd. |
| Cisco Systems, Inc. |
| Microsoft Corporation |
| Robert Bosch GmbH |
| SAP SE |
| Intel Corporation |
| Dell Technologies Inc. |
| Qualcomm |
| IBM Corporation |
| Others |
Supply & Pricing Matrix
Captive semiconductor production at Intel Corporation and Taiwan-based foundries anchors supply positions for edge AI chips while simultaneously constraining pricing flexibility for device vendors downstream. This integration pattern concentrates margin capture at the wafer-fabrication tier, forcing hardware assemblers to absorb pass-through volatility or surrender share to vertically integrated competitors.
Pricing Analysis
Input-cost pass-through from advanced-node wafer shortages feeds directly into hardware bill-of-materials, with sub-7nm neural processing units commanding premium placement in FDA-cleared medical devices. Pricing stratifies across premium certified tiers, standard industrial grades, and economy consumer implementations, with CE-MDR and FDA software-as-medical-device pathways adding certification-driven premiums of substantial magnitude. Cost compression in mid-tier sensor modules is intensifying because 5G RedCap modem commoditization erodes wireless connectivity margins. Government agencies exhibit lowest price sensitivity due to compliance-locked procurement, while consumer electronics companies face acute margin pressure from semiconductor scarcity.
Supply Chain Analysis
Domestic-content mandates under Japan's METI industrial IoT security standards and South Korea's MFDS certification pathways are reshaping sourcing toward regional chip packaging and final assembly. Geographic supply concentration centers on Taiwan for leading-edge foundry capacity, South Korea for memory and advanced logic, and China for sensor module integration and ultra-wideband positioning chip fabrication. Raw material dependencies draw from rare earth elements for magnetics, silicon carbide substrates for power electronics, and lithium-ion cell formats for battery-powered ambient sensors. Single-source vulnerability at Taiwan Semiconductor Manufacturing Company creates systemic exposure for edge AI architectures. Distribution runs through specialized electronics distributors serving industrial automation and medical device verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in pervasive computing technology rests on algorithm licensing unbundling from hardware sales, with subscription-based predictive analytics commanding recurring revenue premiums that offset semiconductor input volatility.
For Market Incumbents: Deploy federated learning architecture licensing as a defensive moat against cloud-hyperscaler encroachment into edge analytics. Consolidate position through backward integration into ultra-wideband positioning chip design, capturing spatial-awareness functionality that Bluetooth beacon vendors cannot replicate. Anticipate EU AI Act algorithmic documentation requirements extending certification timelines to 24 months, freezing out undercapitalized competitors. For New Entrants and Emerging Players: The premium-economy pricing gap in ambient intelligence for Japan's aging-in-place infrastructure offers accessible entry points without FDA or CE-MDR compliance burdens. Target government-subsidized smart home retrofits in Osaka and Tokyo prefectures, where non-intrusive fall detection systems face limited incumbent saturation. Pursue white-label partnerships with South Korean apartment developers bundling pervasive sensing as standard amenities, leveraging 5G RedCap modem cost-down curves for connectivity architecture. For Investors and Strategic Acquirers: Roll-up economics work for regional system integrators serving localized compliance requirements because EU AI Act, GDPR, and MFDS certification fragmentation prevents global vendors from achieving scale efficiencies. Five-to-ten year viability favors specialists with embedded firmware security expertise and hardware-level cryptography capabilities. Monitor CE-MDR technical documentation backlogs as an inflection signal—vendors with pre-positioned clinical evidence libraries will accelerate past certification-constrained competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies sensor hardware with algorithm subscription layers for US hospital procurement committees. |
| Regulatory Certification Pathway | CE-MDR and FDA software-as-medical-device clearance unlocks Medicare reimbursement-linked health system contracts. |
| Strategic Partnership | Cisco Systems enterprise networking alliances accelerate ambient intelligence deployment in German smart hospitals. |
| Acquisition of Specialist Firm | Ultra-wideband positioning chip designers consolidate real-time location services revenue from German automotive suppliers. |
| Geographic Expansion | South Korean smart factory deployments under METI-aligned standards open industrial automation sensor volumes. |
Research Methodology
Bottom-up healthcare and industrial automation modeling reconciled against top-down semiconductor supply tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital GPO contracts managers, industrial IoT platform architects, and edge AI chip procurement leads at device manufacturers were validated against secondary sources including FDA 510(k) filings, EUDAMED medical device registrations, METI industrial security standard publications, and hyperscaler edge computing capex disclosures. Triangulation across these data streams ensures segmentation integrity across deployment models and end-user categories.
Historical trendline analysis of wireless sensor network shipments and context-aware computing software licensing established baseline growth trajectories across the projection horizon. The forecasting framework segments by technology layer, application vertical, deployment architecture, and regional regulatory cluster, with CAGR derivation anchored in procurement cycle analysis for hospital systems and smart factory retrofit timelines. Edge AI chip power-efficiency curves and 5G RedCap modem adoption rates served as industry-specific demand drivers in the quantitative model.
Caveats apply where Taiwan foundry concentration disruptions, EU AI Act enforcement intensity variations, or Medicare reimbursement rule modifications could materially shift the outlook. Forecasts reflect documented assumptions regarding certification timeline stability and wireless protocol standardization momentum. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IIOT Gateway for Utility Market
Internet of Things (IoT)
IoT in BFSI Market
Internet of Things (IoT)
Global IoT Based Asset Tracking and Monitoring Market
Internet of Things (IoT)
Global IoT Solutions and Services Market
Internet of Things (IoT)
Smart Sound and Gateway Market
Internet of Things (IoT)
Marine Internet of Things Market
Internet of Things (IoT)
Internet of Things in BFSI Market
Internet of Things (IoT)
Industrial Internet of Things (Iiot) Market
Internet of Things (IoT)
Automotive Internet of Things (IoT) Market
Internet of Things (IoT)
Global IoT in Smart Cities Market
Internet of Things (IoT)
IoT Gateway Devices Market
Internet of Things (IoT)
Satellite IoT Market
Internet of Things (IoT)
Wi-Fi Smart Scale Market
Internet of Things (IoT)
IoT in Warehouse Management Market
Internet of Things (IoT)
IoT Middleware Market
Internet of Things (IoT)
Private Narrowband IoT Market