
 IoT Operating System Market | 2026-2036
IoT Operating System Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Operating System Market Intelligence
Subscription-based licensing for software-defined features is decoupling the operating system from the initial hardware sale, creating long-term revenue streams. This model allows platform providers to monetize updates, security patches, and premium functionalities over a device's lifecycle. Microsoft leverages its extensive Azure IoT ecosystem to bundle OS services. Amazon Web Services sustains its market position through its FreeRTOS and broad cloud integration, while BlackBerry Limited specializes in high-security, certified OS solutions for critical systems like connected vehicles.
An IoT operating system is a specialized software platform engineered to manage hardware resources, network stacks, and application execution on connected devices. These systems are characterized by their minimal memory footprint and real-time processing capabilities, essential for functioning on power- and processing-constrained hardware. The market for operating system types shows strong demand for Real-Time OS (RTOS) variants in applications requiring deterministic execution. Concurrently, the Smart Manufacturing end-user industry is a primary consumer, demanding high-reliability OS for factory automation and predictive maintenance.
Data security and privacy mandates shape the development and deployment of IoT operating systems. Regulations such as the EU's GDPR and the California Consumer Privacy Act (CCPA) impose strict rules on data handling, forcing OS developers to integrate robust security features. Concurrently, standards from bodies like the US National Institute of Standards and Technology (NIST) provide cybersecurity frameworks that influence OS architecture. Stakeholders must therefore decide whether to prioritize the flexibility of open-source platforms or the integrated security and compliance support of proprietary OS ecosystems.
Market Dynamics
The central dynamic is the tension between the demand for open, interoperable platforms that foster innovation and the non-negotiable requirement for secure, certifiable operating systems compliant with increasingly stringent data privacy and cybersecurity regulations worldwide.
Growth Catalysts
- Edge Computing Expansion:The proliferation of 5G networks and edge computing infrastructure necessitates sophisticated operating systems capable of managing distributed, low-latency applications.
- Industrial Automation Initiatives:National programs, such as Germany's Industry 4.0, accelerate demand for real-time operating systems in smart manufacturing for robotics and predictive maintenance.
- Regulatory Mandates:Frameworks like the EU AI Act create demand for OS platforms with built-in data governance, security, and transparency features.
Market Restraints
- Device and Protocol Fragmentation:The vast diversity of IoT hardware, processor architectures, and communication protocols complicates OS development, testing, and long-term maintenance.
- High Security Overhead:Implementing and maintaining robust, end-to-end security for resource-constrained devices introduces significant development cost and performance overhead for OS vendors.
- Bare-Metal Substitution:For extremely simple, high-volume applications, developers may opt for bare-metal programming or minimal schedulers over a full-featured IoT OS to reduce costs.
Strategic Opportunities
- Connected Healthcare Devices:The growing market for remote patient monitoring and smart medical devices creates an opportunity for certified, high-reliability OS platforms.
- AI and ML Convergence:Integrating machine learning inference capabilities directly into the OS kernel enables real-time, on-device intelligence without reliance on cloud connectivity.
- Emerging Industrial Economies:Industrial automation efforts in nations like India and Brazil present an underpenetrated market for ruggedized, real-time operating systems for factory floors.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of embedded systems engineers with expertise in both real-time programming and modern cybersecurity principles constrains development.
- Legacy System Integration:Integrating new IoT devices with decades-old operational technology (OT) systems in industrial environments presents significant technical and security hurdles.
- Lengthy Certification Cycles:Achieving safety and security certifications from bodies like NIST or for specific verticals is a time-consuming and expensive process.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Operating System Market |
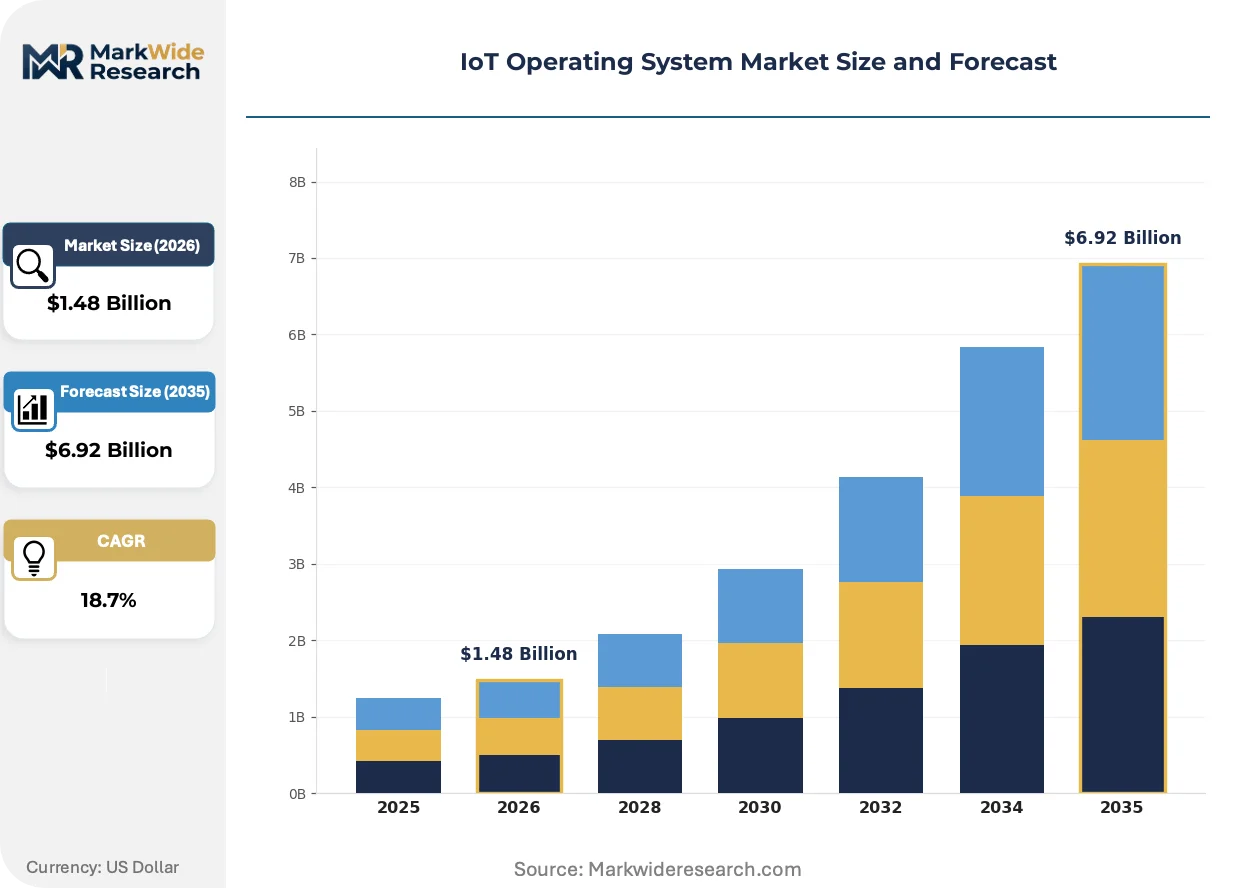
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $6.92 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premise, Hybrid, Edge-Enabled, Distributed Operating System Type: Real-Time OS, Linux-Based OS, Lite OS, Proprietary OS, Open Source OS End User Industry: Smart Manufacturing, Connected Vehicles, Smart Agriculture, Smart Cities, Wearables Connectivity Protocol: Wi-Fi, Bluetooth, ZigBee, LoRaWAN, NB-IoT, 5G |
| Companies Covered | Microsoft Corporation, Google, Apple Inc., ARM Limited, Amazon Web Services, Canonical Group Limited, Wind River Systems, BlackBerry Limited, eSol Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Operating System Market Strategic Shifts & Innovations
Virtualization and containerization technologies, once confined to data centers, are extending to the network edge, reshaping how software is deployed, managed, and secured on resource-constrained IoT devices across their entire lifecycle.
Containerization provides lightweight, isolated user-space environments for applications on a shared OS kernel. Industrial automation and smart infrastructure sectors are adopting this approach to separate critical functions from non-critical ones. This technology is consolidating disparate software dependencies and application stacks onto a unified, hardware-agnostic platform, simplifying fleet management and updates.
China's Cybersecurity Law and Data Security Law impose stringent requirements for network operators and processors of critical data. These regulations mandate security assessments and data localization for systems operating within the country. Consequently, the industrial control and public infrastructure segments are most affected, requiring OS vendors to architect platforms that meet these specific compliance demands.
A fundamental shift in purchasing behavior involves moving from perpetual OS licenses to subscription-based access for software-defined features. This model decouples the OS value from the initial hardware sale, disrupting traditional embedded system procurement. The transition is most visible in enterprise IoT and connected vehicle ecosystems, particularly in North America and Europe.
IoT Operating System Market Segmentation
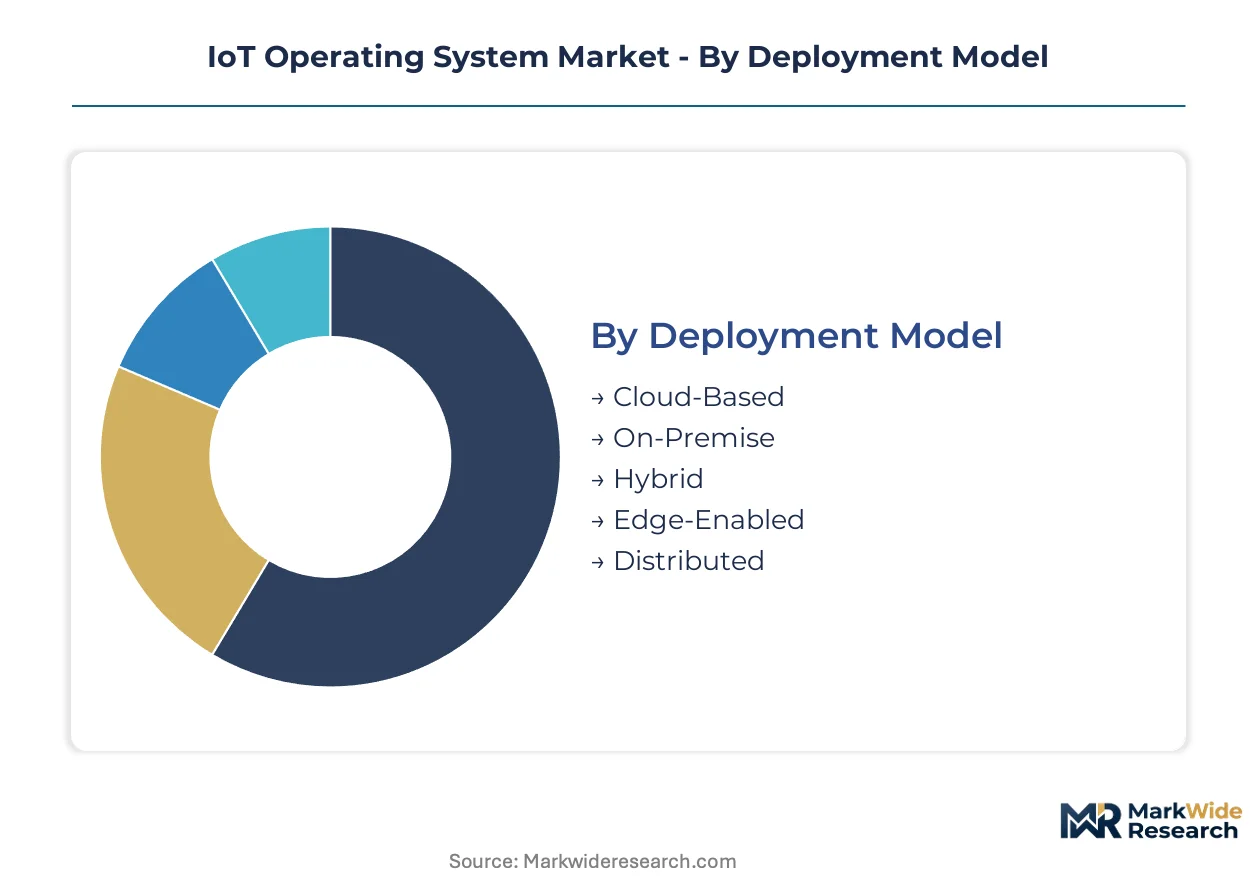
The IoT operating system market segments based on technical specifications and end-user requirements, reflecting the diverse landscape of connected devices. Understanding these distinctions is crucial for identifying areas of concentrated demand and technological innovation within the ecosystem.
Deployment Model:
Buyers in the IoT OS market differentiate their deployment strategies based on latency requirements and data sovereignty needs.
- Cloud-Based:These systems rely on remote servers for computation and storage, offering scalability and reduced local hardware demands. Demand is concentrating in smart city applications, driven by the need for centralized data management across vast sensor networks.
- Edge-Enabled:Operating systems designed for processing data closer to the source, minimizing latency and bandwidth use. Industrial automation in Germany utilizes edge OS for real-time control of robotics and predictive maintenance systems.
- On-Premise:This model involves deploying and managing IoT OS infrastructure directly within the user's physical location, often for enhanced security or regulatory compliance.
- Hybrid:Combining elements of cloud and on-premise deployments, this model offers flexibility in data processing and storage.
- Distributed:This deployment model spreads processing and storage across multiple interconnected nodes, enhancing resilience and scalability for large-scale IoT networks.
On-Premise leads volumes today; Edge-Enabled is gaining share fastest.
Operating System Type:
The choice of IoT operating system type reflects the critical balance between performance, resource efficiency, and development flexibility required for specific applications.
- Real-Time OS:These operating systems guarantee execution of tasks within specific time constraints, essential for mission-critical applications. Smart manufacturing in Japan demands RTOS for precise control of assembly lines and robotic systems.
- Linux-Based OS:Leveraging the open-source Linux kernel, these OS variants offer flexibility, broad hardware support, and a large developer community. Connected vehicles in North America frequently employ Linux-based systems for infotainment and telematics.
- Lite OS:Designed for extremely resource-constrained devices, these operating systems feature minimal memory footprints and power consumption.
- Proprietary OS:Developed and owned by specific vendors, these systems often provide integrated security and tailored features for their hardware ecosystems.
- Open Source OS:These operating systems allow for community-driven development and customization, fostering innovation and reducing licensing costs.
Real-Time OS solutions dominate mission-critical applications, while open-source variants are experiencing the steepest expansion trajectory.
End User Industry:
End-user industries select IoT operating systems based on their operational environment's reliability, security, and real-time processing demands.
- Smart Manufacturing:This sector requires robust, real-time operating systems for factory automation, predictive maintenance, and quality control. National initiatives like Germany's Industry 4.0 drive significant OS demand.
- Connected Vehicles:OS platforms in this segment manage infotainment, advanced driver-assistance systems (ADAS), and vehicle-to-everything (V2X) communication. Regulatory bodies like the EU AI Act influence OS design for autonomous features.
- Smart Agriculture:IoT OS supports precision farming, livestock monitoring, and automated irrigation systems, enhancing resource efficiency.
- Smart Cities:These operating systems manage urban infrastructure, public safety, and environmental monitoring, integrating diverse sensor networks.
- Wearables:Power-efficient and compact OS solutions enable functionality in smartwatches, fitness trackers, and health monitoring devices.
Smart Manufacturing remains a foundational consumer, with connected vehicles exhibiting significant growth potential.
Connectivity Protocol:
Connectivity protocol selection hinges on range, power consumption, data throughput, and environmental resilience for various IoT deployments.
- 5G:Offering high bandwidth and ultra-low latency, 5G is crucial for industrial automation, real-time analytics, and connected vehicle applications. Demand is particularly strong in countries investing heavily in smart factories, such as China.
- LoRaWAN:This low-power, wide-area network protocol is ideal for long-range, low-data-rate applications, such as smart agriculture and environmental monitoring. Deployments in remote agricultural regions of Brazil leverage LoRaWAN for sensor communication.
- Wi-Fi:A ubiquitous standard for local area networking, Wi-Fi supports high-bandwidth data transmission over shorter distances.
- Bluetooth:Primarily used for short-range device-to-device communication, Bluetooth is common in wearables and personal IoT devices.
- ZigBee:A low-power, mesh networking protocol, ZigBee is frequently employed in smart home automation and building management systems.
- NB-IoT:Narrowband IoT is a cellular LPWAN technology designed for extremely low-power devices requiring extended battery life and broad coverage.
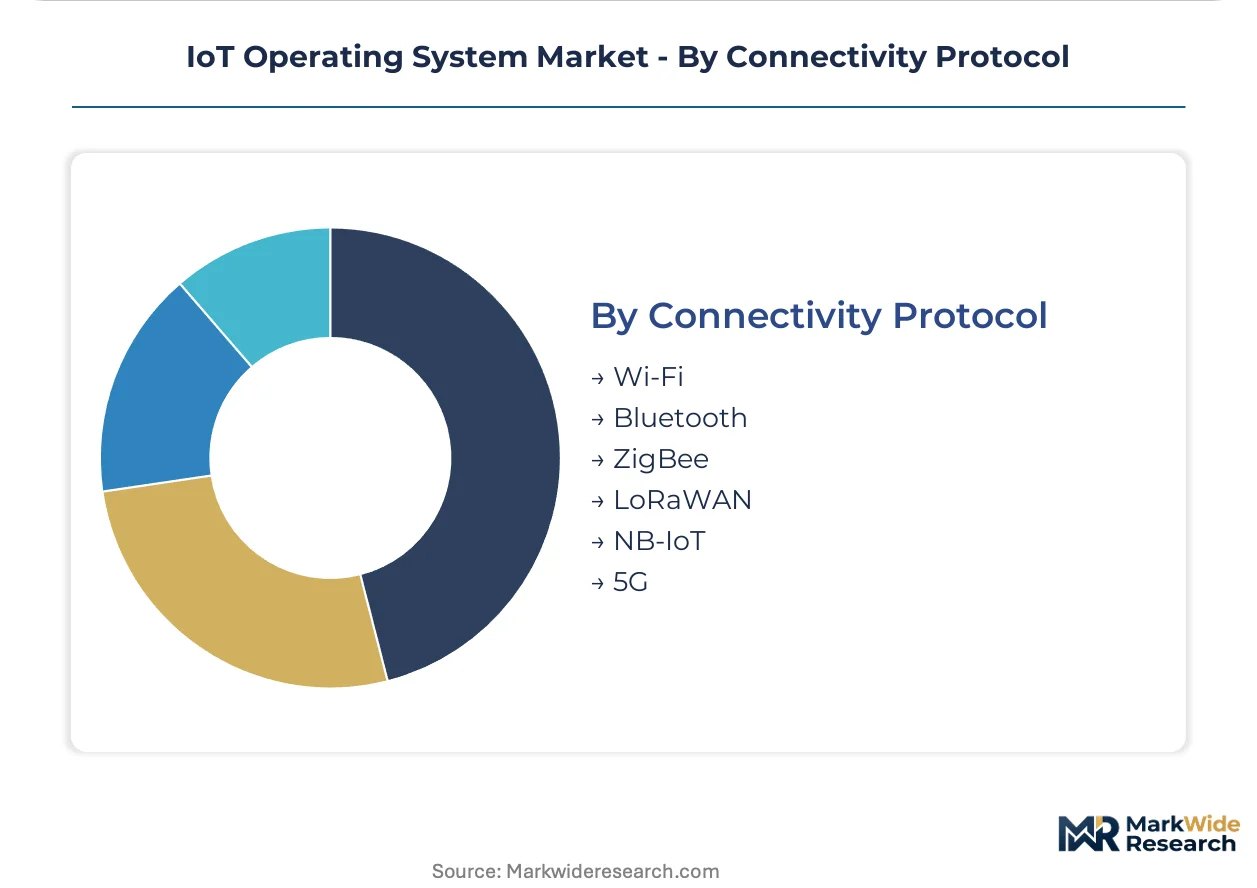
Wi-Fi holds extensive adoption for local networks, while 5G is rapidly expanding into high-bandwidth industrial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The demand for IoT operating systems in industrialized nations like Germany contrasts with emerging market opportunities in countries such as Brazil. Germany's focus on advanced manufacturing drives sophisticated OS requirements. Brazil's agricultural sector utilizes more specialized, low-power solutions, reflecting varied stages of industrialization.
Germany
Germany's robust industrial sector drives significant demand for real-time operating systems in factory automation and predictive maintenance. The country's Industry 4.0 initiative actively promotes advanced OS for smart manufacturing. The Ruhr area, a historical industrial heartland, deploys high-reliability OS in modernized production facilities.
United States
United States enterprises increasingly adopt IoT operating systems for connected vehicles and smart city applications. Regulatory bodies like the National Institute of Standards and Technology (NIST) influence cybersecurity frameworks for OS architecture. Silicon Valley in California remains a hub for developing and deploying advanced IoT OS solutions for diverse applications.
China
China exhibits strong demand for IoT operating systems, particularly within its smart factory initiatives and public infrastructure projects. The nation's Cybersecurity Law and Data Security Law mandate specific compliance features for OS vendors. The Yangtze River Delta region integrates advanced OS into its vast network of automated production lines.
Japan
Japanese smart manufacturing operations require highly deterministic Real-Time OS for precise control of robotics and assembly lines. The Ministry of Economy, Trade and Industry (METI) supports initiatives for industrial digitalization, impacting OS development. Industrial clusters around Nagoya implement advanced IoT OS to enhance efficiency in automotive and electronics production.
Brazil
Brazil's agricultural and emerging industrial sectors create new demand for ruggedized and low-power IoT operating systems. The country's national digital transformation strategies encourage IoT adoption across various industries. The state of São Paulo, a leading industrial region, sees increased deployment of IoT OS in its growing manufacturing base.
IoT Operating System Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the IoT operating system market. The competitive landscape is characterized by a tiered structure, with established technology giants competing alongside specialized embedded OS providers. Key strategic archetypes include cloud-platform integrators, high-security OS developers, and open-source ecosystem enablers. Companies primarily focus on strategic partnerships and technology licensing to expand their market reach and integrate diverse hardware platforms.
Among the cloud-platform integrators, Microsoft Corporation anchors a significant portion of the market through its extensive Azure IoT ecosystem, bundling OS services with its comprehensive cloud offerings. Similarly, Amazon Web Services sustains its market position with FreeRTOS and broad cloud integration capabilities, appealing to a wide developer base. BlackBerry Limited, a Canadian-based entity, exemplifies the high-security OS developer archetype, specializing in certified solutions for critical systems such as connected vehicles and industrial control applications.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Apple Inc. |
| ARM Limited |
| Amazon Web Services |
| Canonical Group Limited |
| Wind River Systems |
| BlackBerry Limited |
| eSol Co. |
| Others |
Cost & Logistics Intelligence
Specialized embedded systems engineers concentrated in industrial hubs like Germany influence premium pricing for high-reliability IoT operating systems. Their expertise drives labor-cost differentials directly impacting pricing tiers for custom solutions.
Pricing Analysis
Capacity additions in open-source development communities are reshaping price floors for basic IoT operating systems. Subscription-based licensing dominates, decoupling OS value from initial hardware sales. Price differentiation stems from certification levels for critical applications and the degree of customization for specific hardware. Pricing pressure stems from the availability of robust open-source alternatives. Small-scale developers and startups are the most price-sensitive buyers, while large enterprises prioritize integrated security and compliance support.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for pre-integrated IoT OS solutions. The supply chain for advanced IoT operating systems draws from specialized microcontroller manufacturers in Taiwan and software development talent in the United States and Germany. Raw material dependencies include advanced microprocessors and specialized embedded hardware components. Geopolitical tensions affecting semiconductor supply represent a significant structural risk. Distribution for open-source variants primarily runs through community platforms and cloud provider marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IoT operating system market acts as a regulatory compounder. The EU AI Act, for instance, drives demand for OS platforms with built-in data governance and transparency features.
For Market Incumbents:Anticipate the need for deeper integration with hyperscale cloud ecosystems to bundle OS services effectively. Acquire niche firms specializing in real-time operating systems for critical applications to counter fragmentation from new entrants. Invest heavily in certifications from bodies like NIST to maintain a competitive edge in regulated sectors. Control over the hardware-software interface becomes a key lever against commoditization. Consolidate offerings around secure, compliant platforms.
For New Entrants and Emerging Players:Launch via open-source models offering premium support and customization services for specific verticals. Target underpenetrated segments like connected healthcare devices, leveraging the demand for certified, high-reliability OS platforms. Focus on integrating AI/ML inference capabilities directly into the OS kernel for real-time edge intelligence. The most penetrable segment remains industrial automation in emerging economies seeking cost-effective, ruggedized solutions. Pursue strategic partnerships with hardware startups.
For Investors and Strategic Acquirers:Cloud-platform integrators are the most active acquirers in this space, seeking to expand their IoT ecosystem capabilities. The market demonstrates long-term viability as digital transformation initiatives continue over the next decade. Target acquisition archetypes include specialized RTOS developers and companies with strong IP in secure, certified OS solutions for critical infrastructure. The signal to watch is the increasing consolidation of smaller OS vendors by larger technology companies.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI/ML at OS kernel level | Enables real-time, on-device intelligence for industrial applications without cloud reliance. |
| Pursue specialized security certifications | Ensures compliance for critical infrastructure and connected vehicles, meeting regulatory demands. |
| Expand subscription-based licensing models | Generates recurring revenue streams beyond initial hardware sales, enhancing financial predictability. |
| Form strategic partnerships with hardware manufacturers | Optimizes OS performance and broadens device compatibility across diverse IoT ecosystems. |
| Develop robust virtualization and containerization support | Simplifies fleet management and secure application deployment on resource-constrained devices. |
Research Approach
Direct dialogue with IoT platform architects, embedded systems engineers, IT procurement officers, and regulatory compliance specialists informed this analysis. Primary interviews were triangulated with extensive secondary research, including SEC 10-K filings, NIST cybersecurity frameworks, EU AI Act legislative documents, and relevant academic research. This approach enabled comprehensive bottom-up and top-down validation of market dynamics.
The quantitative model generated volume and value outputs by segmenting the market across deployment model, OS type, end-user industry, connectivity protocol, and regional adoption patterns. Compound annual growth rates were derived from historical trends and projected growth drivers across the projection horizon. Key forecast inputs included 5G network expansion rates and industrial automation investment figures, providing a robust analytical foundation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of rapid technological obsolescence or unforeseen regulatory shifts. All forecasts reflect assumptions documented throughout the study. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global Internet of Things (IoT) Defence Market
Internet of Things (IoT)
IoT in Chemical Industry Market
Internet of Things (IoT)
Asia-Pacific Massive IoT Market
Internet of Things (IoT)
IoT Middleware Market
Internet of Things (IoT)
Automotive Internet of Things (IoT) Market
Internet of Things (IoT)
Edge Computing in IoT Market
Internet of Things (IoT)
Smart Connected Device Market
Internet of Things (IoT)
Global IoT Routers Market
Internet of Things (IoT)
Global Military IoT Market
Internet of Things (IoT)
Iot-Enabled Devices Market
Internet of Things (IoT)
IoT Device Management Market
Internet of Things (IoT)
IoT in Automotive Market
Internet of Things (IoT)
Internet of Medical Things (Iomt) Market
Internet of Things (IoT)
Global IoT Elevators Market
Internet of Things (IoT)
Global IoT Node and Gateway Market
Internet of Things (IoT)
Asia-Pacific IoT Device Market