
 Global IoT Based Asset Tracking and Monitoring Market | 2026-2036
Global IoT Based Asset Tracking and Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global IoT Based Asset Tracking and Monitoring Market Outlook
Buyer concentration in fleet management is expanding as logistics operators consolidate vendor relationships across multi-modal networks. Samsara Inc. leverages cloud-native architecture to anchor enterprise fleet contracts in North America. Quectel Wireless Solutions Co., Ltd dominates cellular module supply for asset trackers across Asia-Pacific manufacturing corridors. Nordic Semiconductor ASA specializes in ultra-low-power Bluetooth chipsets that sustain battery-operated tracking devices in cold-chain pharmaceutical applications.
IoT based asset tracking and monitoring encompasses sensor-embedded hardware, wireless connectivity protocols, and cloud analytics platforms that transmit geolocation, condition, and status data from physical assets to centralized dashboards. Cellular and GPS technologies lead deployment in long-haul transportation and maritime containers, while Bluetooth and RFID segments capture higher-margin opportunities in retail inventory and healthcare equipment tracking where proximity precision matters. Cloud deployment models absorb the majority of new enterprise subscriptions, though edge computing architectures are gaining traction in manufacturing floors requiring sub-second latency for automated quality alerts.
The EU AI Act imposes algorithmic transparency requirements on predictive maintenance systems, while FDA traceability rules mandate serialized tracking for medical devices and pharmaceuticals moving through US distribution channels. Japan's METI promotes IoT standards alignment through JIS certification programs for industrial sensor networks. Stakeholders must monitor how diverging data localization requirements across the European Union, United States, and China reshape platform architecture decisions and cross-border service delivery models.
Market Dynamics
Fleet operators in Germany, the United States, and Japan are consolidating multi-modal visibility contracts while cellular module supply concentrates among Asian contract manufacturers, compressing margins for hardware-agnostic platform vendors.
Growth Catalysts
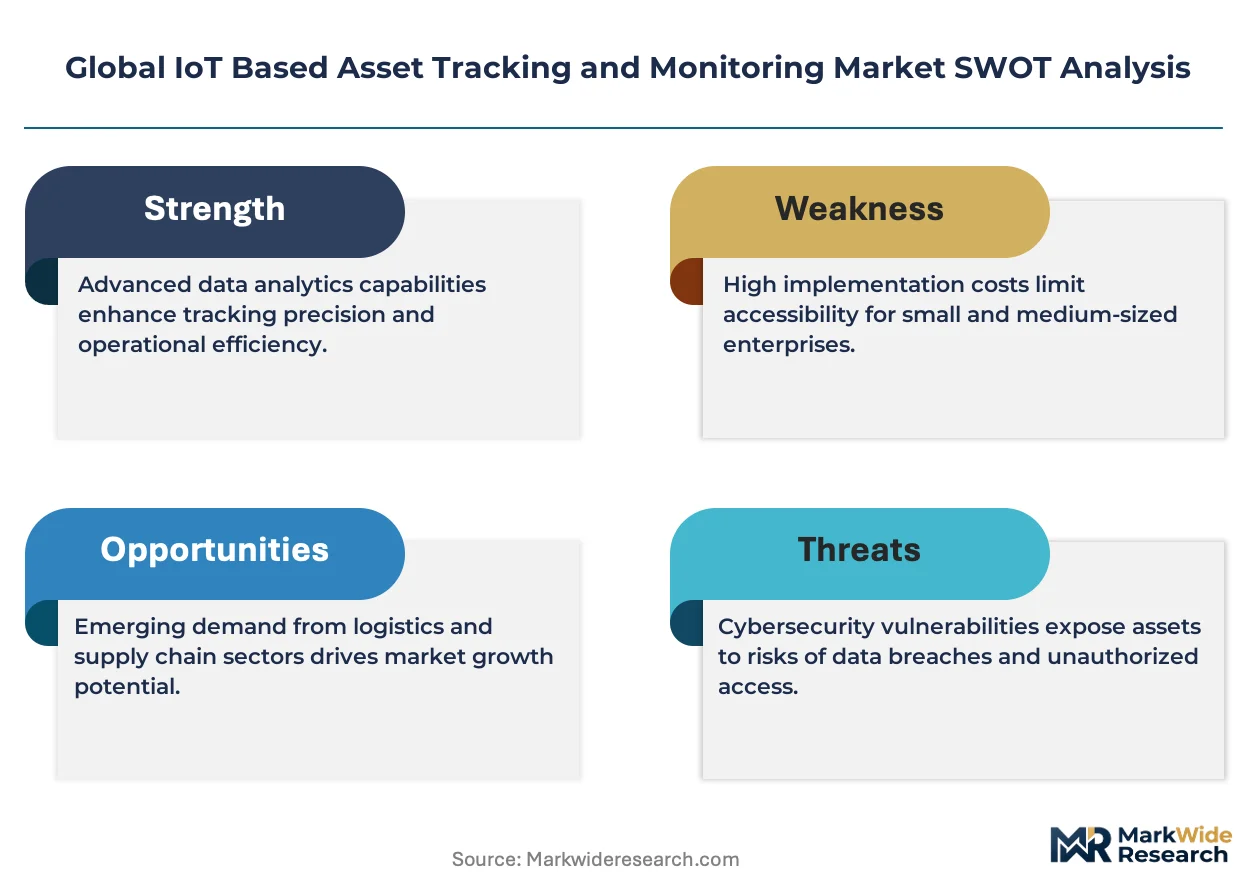
- EU AI Act algorithmic transparency mandates:Predictive maintenance systems in cold-chain logistics must document decision pathways, accelerating demand for auditable sensor-to-cloud architectures in pharmaceutical distribution.
- Manufacturing reshoring in Germany and Japan:Factory floor IoT deployments are expanding real-time asset visibility programs as production lines repatriate from low-cost regions.
- Bluetooth Low Energy 5.3 chipsets:Ultra-low-power consumption is extending battery life in pharmaceutical cold-chain trackers, opening higher-margin healthcare equipment monitoring applications.
Market Restraints
- Lithium-ion cell price volatility:Battery-operated trackers face input cost pressure as cathode material supply concentrates in Chinese processing facilities.
- Cellular module supply concentration:Asia-Pacific contract manufacturers control 70-plus percent of NB-IoT and Cat-M1 module production, creating single-source vulnerability for North American and European hardware vendors.
- GPS signal jamming in maritime corridors:Geolocation accuracy degrades in contested shipping lanes, forcing redundant sensor fusion that raises unit costs.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Cellular module assembly incentives are attracting tracker hardware production away from incumbent Asian hubs.
- Edge-to-cloud convergence in Japanese automotive:METI-funded JIS certification programs are accelerating sub-second latency architectures for automated quality alerts in just-in-time parts tracking.
- Serialized medical device traceability:FDA UDI mandates are creating subscription revenue pools for cloud platforms managing pharmaceutical distribution chain-of-custody records.
Industry Challenges
- Embedded systems firmware engineering scarcity:Ultra-low-power optimization for Bluetooth trackers requires specialized talent concentrated in Nordic and German semiconductor clusters.
- Cross-border data localization friction:Diverging EU GDPR, Chinese PIPL, and US state privacy laws are fragmenting cloud platform architectures and raising compliance engineering overhead.
- Legacy ERP integration complexity:Manufacturing execution systems from the 1990s lack API-native connectivity, forcing expensive middleware development for brownfield IoT deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IoT Based Asset Tracking and Monitoring Market |
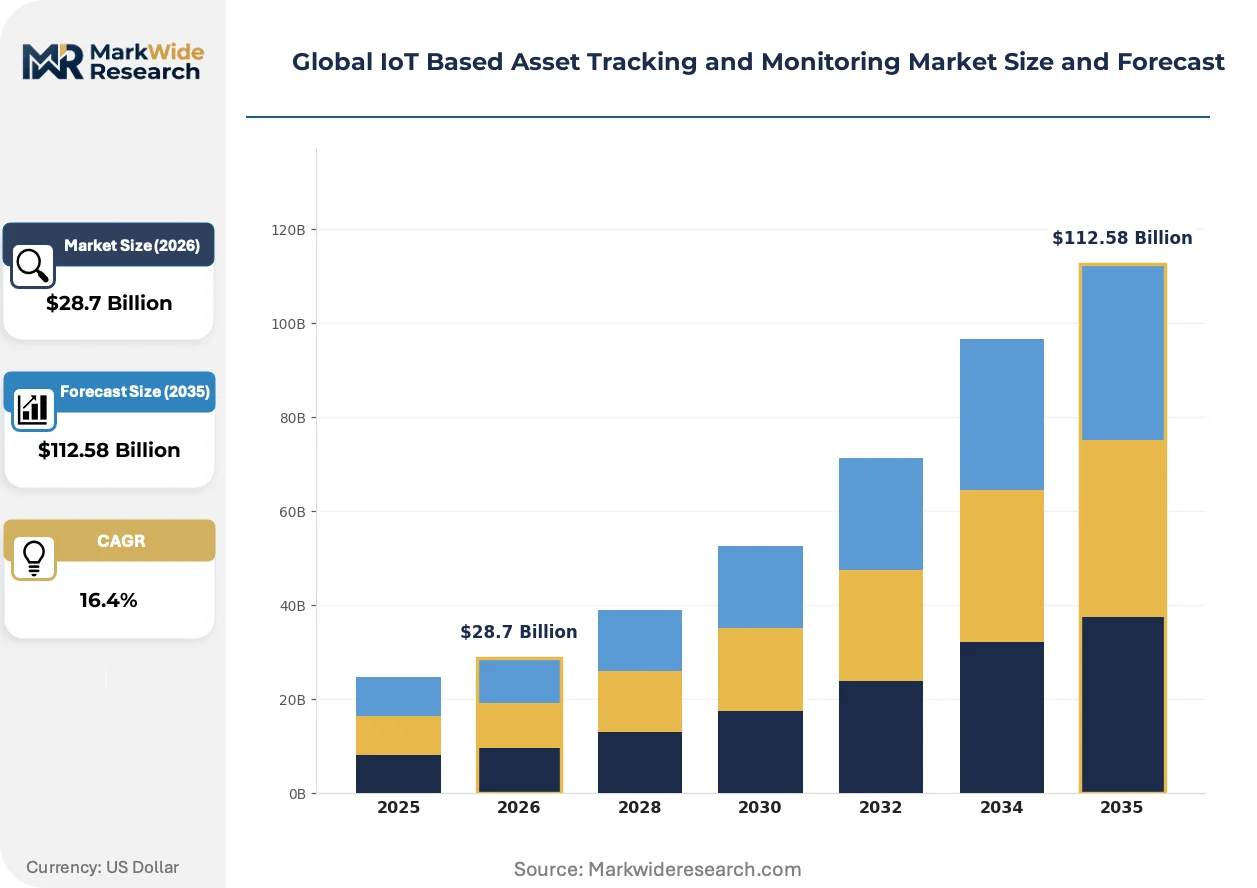
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $112.58 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Bluetooth, GPS, RFID, Cellular Deployment: On-Premise, Cloud, Hybrid, Edge End User: Healthcare, Transportation, Retail, Manufacturing Application: Inventory Management, Fleet Management, Asset Monitoring, Supply Chain |
| Companies Covered | Quectel Wireless Solutions Co., Ltd, u-blox AG, Fibocom Wireless Inc., Semtech Corporation, Samsara Inc., Telit, Analog Devices, Inc., Nordic Semiconductor ASA, SEQUANS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IoT Based Asset Tracking and Monitoring Market Strategic Shifts
Low-power wide-area network architectures and algorithmic auditability requirements are compressing hardware margins while expanding software subscription attach rates across transportation and healthcare verticals.
Dual-mode cellular-satellite connectivity modules are electrifying asset tracking in maritime and remote mining applications where terrestrial coverage gaps previously forced expensive manual reconciliation. Container operators in the North Sea and Gulf of Mexico are piloting these hybrid devices for uninterrupted visibility across transoceanic routes. The technology is electrifying competitive positioning among platform vendors by collapsing the addressable market gap between premium satellite-only and economy cellular-only service tiers.
Japan's METI has mandated JIS Q 15001 alignment for industrial IoT sensor networks handling sensitive operational data, forcing foreign platform vendors to establish local certification partnerships. The framework requires documented encryption standards and incident response protocols that add six to nine months to market entry timelines. Automotive parts suppliers in Aichi Prefecture are prioritizing domestic-certified platforms over faster-to-deploy international alternatives.
Subscription-based visibility pricing is displacing perpetual hardware licensing in North American fleet management as operators seek to match technology costs to asset utilization cycles. Logistics buyers in the United States are unbundling device procurement from data analytics services, treating connectivity and cloud software as separate line items in vendor evaluations. This unbundling is most visible among refrigerated trucking operators managing seasonal capacity fluctuations.
Global IoT Based Asset Tracking and Monitoring Market Segmentation
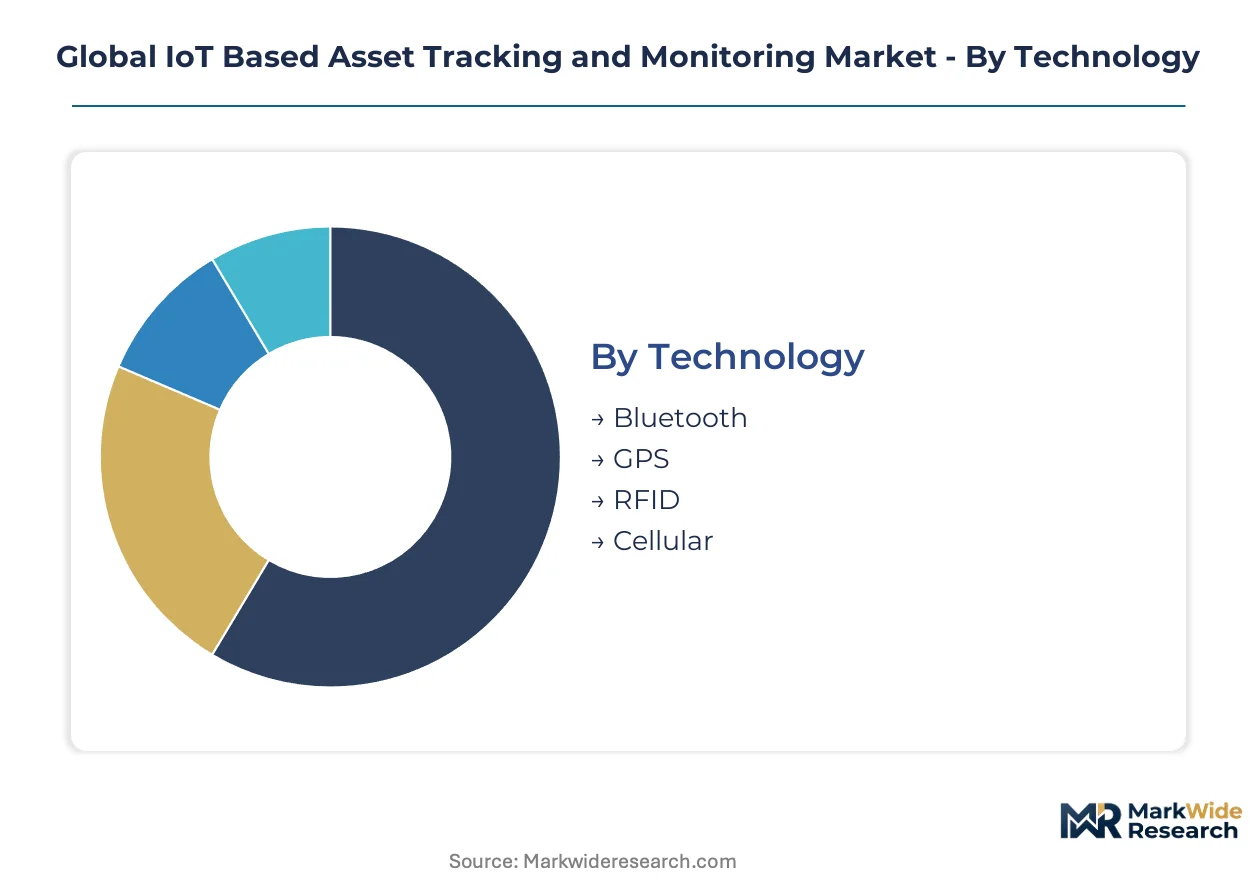
Technology refresh cycles in IoT asset tracking are compressing as fleet operators demand multi-protocol flexibility. Hardware upgrade decisions now hinge on backward compatibility with legacy sensor networks and forward readiness for satellite-cellular convergence.
Technology:
Replacement timelines vary sharply across connectivity standards, with cellular modules facing the shortest obsolescence windows due to 2G/3G sunsetting.
- Cellular:NB-IoT and Cat-M1 modules dominate long-haul transportation visibility, with German automotive logistics operators mandating redundant connectivity for cross-border fleet compliance. Procurement concentrates among Asian contract manufacturers, creating single-source vulnerability for North American hardware vendors.
- Bluetooth:Low-energy chipsets from Nordic Semiconductor clusters sustain battery-operated pharmaceutical cold-chain trackers through sub-microamp sleep modes. Japanese METI-certified deployments in Aichi Prefecture prioritize JIS Q 15001 alignment for sensitive operational data handling.
- GPS:Geolocation modules face signal degradation in contested maritime corridors, forcing sensor fusion architectures that raise unit costs for container operators.
- RFID:Passive tag systems capture retail inventory proximity precision where millimeter-range accuracy matters more than real-time transmission.
Volume placements concentrate in Cellular; the faster expansion belongs to Bluetooth.
Deployment:
Cost-tier differentiation separates enterprise cloud subscriptions from capital-intensive edge installations requiring localized compute hardware.
- Cloud:Subscription models absorb the majority of new enterprise fleet contracts in the United States, with refrigerated trucking operators unbundling device procurement from analytics services. AWS and Azure regions face data localization friction under diverging GDPR and state privacy laws.
- Edge:Sub-second latency architectures serve Japanese automotive just-in-time parts tracking through METI-funded JIS certification programs. Local compute nodes process automated quality alerts without round-trip cloud dependency.
- Hybrid:Split architectures balance sensitive manufacturing execution system data on-premise with fleet visibility dashboards in public cloud instances.
- On-Premise:Legacy brownfield deployments persist in 1990s-era manufacturing execution systems lacking API-native connectivity, forcing expensive middleware development.
Cloud captures the dominant revenue share; edge deployments are climbing the fastest.
End User:
Application maturity varies by sector compliance burden, with FDA traceability mandates accelerating healthcare platform subscriptions.
- Transportation:Fleet operators in Germany and the United States consolidate multi-modal visibility contracts across refrigerated trucking and maritime container networks. Seasonal capacity fluctuations drive preference for subscription pricing over perpetual hardware licensing.
- Healthcare:FDA UDI mandates for serialized medical device tracking create subscription revenue pools for cloud platforms managing pharmaceutical distribution chain-of-custody records. Bluetooth trackers extend battery life in cold-chain applications.
- Manufacturing:Reshoring production lines in Germany and Japan expand factory floor IoT deployments for real-time asset visibility. Legacy ERP integration complexity slows brownfield sensor deployment.
- Retail:Inventory proximity tracking demands millimeter-precision RFID and Bluetooth beacon networks for omnichannel fulfillment optimization.
Transportation leads absolute deployment volume; healthcare shows the steepest expansion trajectory.
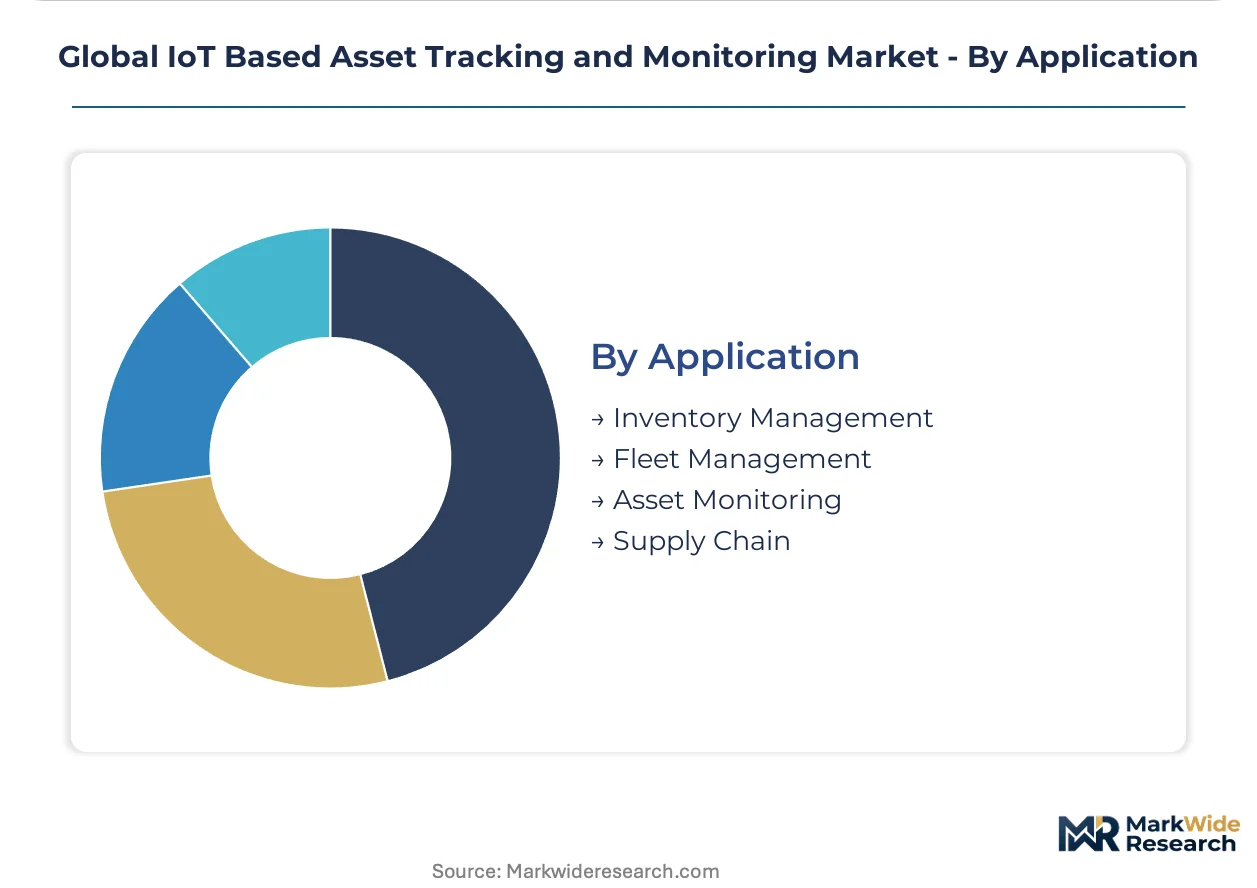
Application:
Margin structures diverge between commoditized fleet visibility and high-margin pharmaceutical chain-of-custody compliance.
- Fleet Management:Real-time geolocation and condition monitoring for long-haul trucking and maritime containers. Dual-mode cellular-satellite modules are electrifying competitive positioning in North Sea and Gulf of Mexico pilot programs.
- Supply Chain:End-to-end serialization for pharmaceutical distribution under FDA traceability rules. EU AI Act algorithmic transparency mandates accelerate demand for auditable sensor-to-cloud architectures.
- Asset Monitoring:Predictive maintenance systems in German manufacturing floors face EU AI Act documentation requirements for decision pathway auditability.
- Inventory Management:Retail and healthcare equipment tracking where proximity precision outweighs real-time transmission needs.
Fleet management holds the largest installed base; supply chain applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, the United States, and Japan where manufacturing reshoring and fleet digitization programs are accelerating sensor deployment across factory floors and logistics networks.
United States
FDA UDI mandates for serialized medical device traceability are expanding subscription revenue pools for cloud platforms managing pharmaceutical distribution chain-of-custody records. Fleet operators across refrigerated trucking corridors are unbundling device procurement from analytics services to match technology costs with seasonal capacity fluctuations. Dallas-Fort Worth logistics hubs anchor multi-modal visibility contract consolidation among enterprise fleet operators.
Germany
Automotive logistics operators are mandating redundant NB-IoT and Cat-M1 connectivity for cross-border fleet compliance as production lines repatriate from low-cost regions. EU AI Act algorithmic transparency requirements impose documentation burdens on predictive maintenance systems in cold-chain distribution. Baden-Württemberg manufacturing clusters are expanding factory floor IoT deployments for real-time asset visibility in just-in-time parts tracking.
Japan
METI-funded JIS Q 15001 certification programs are accelerating sub-second latency edge architectures for automated quality alerts in automotive parts supply chains. Bluetooth Low Energy 5.3 chipsets from Nordic Semiconductor clusters are sustaining battery-operated pharmaceutical cold-chain trackers through sub-microamp sleep modes. Aichi Prefecture automotive suppliers are prioritizing domestic-certified platforms over faster-to-deploy international alternatives.
China
Cellular module supply concentrates among Asia-Pacific contract manufacturers controlling 70-plus percent of NB-IoT and Cat-M1 production, creating single-source vulnerability for North American and European hardware vendors. MIIT standards alignment pressures are reshaping platform architecture decisions for cross-border service delivery. Yangtze River Delta manufacturing corridors anchor module assembly and tracker hardware production.
India
PLI scheme incentives for electronics manufacturing are attracting cellular module assembly away from incumbent Asian hubs toward domestic production facilities. TRAI spectrum allocations for LPWAN networks are expanding addressable market coverage for asset tracking in logistics and agriculture applications. Gujarat and Tamil Nadu industrial corridors are emerging as alternative assembly locations for battery-operated tracking devices.
Global IoT Based Asset Tracking and Monitoring Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue satellite-cellular convergence and edge-native architectures. The vendor base stratifies across three tiers: cloud-native platform operators anchoring enterprise fleet contracts, cellular module specialists supplying Asia-Pacific manufacturing corridors, and ultra-low-power chipset designers serving pharmaceutical cold-chain applications. Consolidation pressures are intensifying as hardware margins compress and software subscription attach rates become the primary value capture mechanism. Dominant competitive moves include backward integration into captive module supply and geographic expansion through local certification partnerships.
Among cellular module specialists, Quectel Wireless Solutions Co., Ltd and u-blox AG occupy positions within the Asia-Pacific and European supply tiers respectively. Samsara Inc. exemplifies the cloud-native platform archetype anchoring enterprise fleet contracts in North America. Nordic Semiconductor ASA represents the ultra-low-power design specialization sustaining battery-operated pharmaceutical applications.
| Leading Market Players |
|---|
| Quectel Wireless Solutions Co., Ltd |
| u-blox AG |
| Fibocom Wireless Inc. |
| Semtech Corporation |
| Samsara Inc. |
| Telit |
| Analog Devices, Inc. |
| Nordic Semiconductor ASA |
| SEQUANS |
| Others |
Value Chain & Pricing Dynamics
Backward integration into captive cellular module production anchors supply security and pricing power for platform vendors facing Asia-Pacific contract manufacturer concentration. This upstream control buffers against raw material volatility while enabling subscription-tier differentiation through bundled hardware-software offerings.
Pricing Analysis
Volume placements in cellular-based fleet management compress margins, while Bluetooth-enabled pharmaceutical cold-chain trackers command premium positioning through FDA UDI compliance bundling. Price differentiation hinges on certification grade—JIS Q 15001 alignment in Japan and EU AI Act auditability in Germany—and after-sales service depth for legacy ERP integration. Cost compression in standard-tier hardware intensifies as Asian module assembly scales, though enterprise buyers in refrigerated trucking show lowest price sensitivity due to seasonal capacity fluctuation matching needs.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for battery-operated tracking devices away from Yangtze River Delta concentrations. Cellular module assembly draws from China, South Korea, and emerging Gujarat facilities, with lithium-ion cathode processing and Nordic Semiconductor Bluetooth chipsets as critical inputs. Single-source vulnerability in NB-IoT and Cat-M1 production creates tariff exposure risk for North American hardware vendors. Distribution runs through Asia-Pacific contract manufacturers to platform integrators in Germany, the United States, and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellular-satellite dual-mode connectivity is displacing legacy cellular-only architectures in maritime and remote mining applications, compressing the addressable market gap between premium satellite and economy cellular tiers.
For Market Incumbents: To counter margin erosion from hardware commoditization, Samsara-type platform operators should deepen captive module supply through India's PLI scheme assembly partnerships. Certification investment in METI JIS Q 15001 alignment secures automotive parts supplier lock-in against faster-to-deploy international alternatives.
For New Entrants and Emerging Players: Mid-sized refrigerated trucking operators in Dallas-Fort Worth corridors represent an underserved buyer archetype seeking unbundled device procurement from analytics services. Edge-native latency architectures for Japanese automotive just-in-time tracking offer the most penetrable segment, with channel partnerships through domestic-certified platform integrators as the go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in cloud-native platform operators with enterprise fleet contract anchoring and software subscription attach rates above hardware revenue. Long-term viability favors vendors controlling both sensor-to-cloud architecture and regulatory compliance documentation layers. The signal to watch is EU AI Act enforcement intensity accelerating demand for auditable predictive maintenance systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Cellular-Satellite Module Integration | Dual-mode connectivity collapses coverage gaps for North Sea container operators. |
| JIS Q 15001 Certification Investment | METI alignment secures Aichi Prefecture automotive supplier preference. |
| Backward Integration into Module Supply | Captive production buffers Quectel-dominated Asia-Pacific concentration risk. |
| Subscription Pricing Unbundling | Refrigerated trucking operators match technology costs to seasonal utilization. |
| Edge-to-Cloud Convergence | Sub-second latency architectures serve German automotive quality alert automation. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving fleet operations directors, cellular module procurement leads, cloud platform engineers, and pharmaceutical supply chain compliance officers. FDA UDI submission databases, METI JIS certification registries, EU AI Act implementation guidance, and India PLI scheme beneficiary disclosures provided segmentation benchmarks. Bottom-up unit economics triangulated against top-down market sizing across connectivity technology tiers.
Granularity-level modeling deployed country-specific adoption curves for Germany, the United States, Japan, China, and India, with technology segmentation spanning cellular, Bluetooth, GPS, and RFID protocols. Deployment mode differentiation—cloud, edge, hybrid, on-premise—intersected with end-use verticals including transportation, healthcare, manufacturing, and retail. CAGRs derived from regression analysis against manufacturing reshoring indices and fleet digitization program announcements throughout the projection horizon. Input variables included cellular module price indices, lithium-ion cell cost trajectories, and regulatory compliance timeline accelerations.
Revisions become necessary when EU AI Act enforcement intensity, FDA traceability rule expansion, or India PLI scheme extension timelines materialize outside baseline assumptions. Geopolitical disruptions to Asia-Pacific module supply corridors or GPS signal degradation in contested maritime lanes could compress hardware margin forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Telecom Internet of Things (IoT) Market
Internet of Things (IoT)
North America and Europe IoT Gateway Market
Internet of Things (IoT)
Internet of Things (IoT) in Manufacturing Market
Internet of Things (IoT)
Maritime Internet of Things Market
Internet of Things (IoT)
Consumer IoT Market
Internet of Things (IoT)
IoT Data Governance Market
Internet of Things (IoT)
Wi-Fi Smart Scale Market
Internet of Things (IoT)
Airline IoT Market
Internet of Things (IoT)
North America IoT Device Market
Internet of Things (IoT)
Global Internet of Things Technology Market
Internet of Things (IoT)
Global IoT Devices Market
Internet of Things (IoT)
Private Narrowband IoT Market
Internet of Things (IoT)
Global IoT in Aerospace and Defense Market
Internet of Things (IoT)
Wireless Connected Devices Market
Internet of Things (IoT)
IoT Lpwans Market
Internet of Things (IoT)
North America Narrowband-Internet of Things (NB-IoT) Market