
 Internet of Things (IoT) in Manufacturing Market | 2026-2036
Internet of Things (IoT) in Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Internet of Things (IoT) in Manufacturing Market Analysis
Edge-to-cloud orchestration is reconfiguring how discrete manufacturers orchestrate production workflows. Siemens leverages its digital twin portfolio to anchor high-complexity automation environments across European automotive plants. Cisco Systems competes on network resilience, sustaining factory-floor connectivity through hardened industrial ethernet switches. Rockwell Automation specializes in programmable logic controllers that dominate North American food and beverage processing lines.
Internet of Things in Manufacturing denotes sensor-embedded industrial infrastructure that transmits operational telemetry via OPC UA, MQTT, or Time-Sensitive Networking protocols to centralized or distributed analytics layers. Its primary purpose is to convert machine-state data into actionable production intelligence, reducing unplanned downtime and material waste. Predictive Maintenance applications command the largest installed base, though Quality Control segments are expanding fastest as computer-vision inspection modules replace manual sampling regimes. Smart Sensors occupy mature margin pools, while Data Analytics offerings capture expanding value as pharmaceutical manufacturers deploy batch-process optimization algorithms.
FDA's 21 CFR Part 11 electronic records requirements shape validation protocols for IoT systems in pharmaceutical manufacturing, while the EU AI Act imposes conformity obligations on autonomous quality-inspection algorithms. Germany's KBA enforces functional-safety standards for connected production equipment, restricting market access for uncertified control systems. Stakeholders must weigh regulatory certification timelines against deployment velocity when selecting platform architectures for multi-jurisdictional operations.
Market Dynamics
Edge-to-cloud orchestration is reconfiguring discrete manufacturing workflows by collapsing latency between sensor data generation and production decision layers. Automotive OEMs now synchronize assembly-line throughput with real-time demand signals through distributed computing architectures.
Growth Catalysts
- EU AI Act Conformity Mandates:Risk-classification protocols for autonomous manufacturing systems are pushing vendors toward certified edge platforms, expanding addressable market for compliant infrastructure providers.
- Germany's Industrie 4.0 Corridor:Mittelstand firms anchor sensor-to-cloud integration projects, creating dense reference deployments that accelerate cross-border technology transfer.
- Predictive Maintenance Algorithms:Pharmaceutical manufacturers deploy batch-process optimization to reduce unplanned downtime, generating recurring analytics revenue streams for platform vendors.
Market Restraints
- Semiconductor Supply Concentration:Industrial sensor and edge-computing chip fabrication concentrates in East Asian foundries, exposing European and North American manufacturers to geopolitical disruption risk.
- FDA 21 CFR Part 11 Validation Burden:Electronic records requirements for pharmaceutical IoT systems extend certification timelines by 12-18 months, compressing deployment velocity.
- Legacy PLC Protocol Fragmentation:Proprietary industrial communication standards from incumbent automation vendors create integration friction that slows brownfield retrofit adoption.
Strategic Opportunities
- Computer-Vision Quality Inspection:Autonomous visual defect detection modules replace manual sampling regimes in automotive stamping and electronics assembly, opening fastest-expanding application segment.
- India's PLI Scheme for Manufacturing:Production-linked incentives for advanced manufacturing are attracting greenfield IoT-native facility investments from multinational industrial conglomerates.
- Time-Sensitive Networking Convergence:IEEE 802.1 standards integration with 5G private networks enables deterministic control over wireless infrastructure, unlocking cable-free production reconfiguration.
Industry Challenges
- OT-IT Security Skill Scarcity:Manufacturing enterprises face acute shortages of engineers capable of bridging operational technology and information security domains for hardened edge deployments.
- Multi-Jurisdictional Certification Timelines:Stakeholders must sequence EU AI Act, FDA Part 11, and Germany KBA functional-safety approvals, creating complex project management overhead for global rollouts.
- Interoperability Testing Costs:OPC UA and MQTT protocol validation across heterogeneous vendor stacks consumes 15-20% of integration budgets without guaranteed compatibility outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet of Things (IoT) in Manufacturing Market |
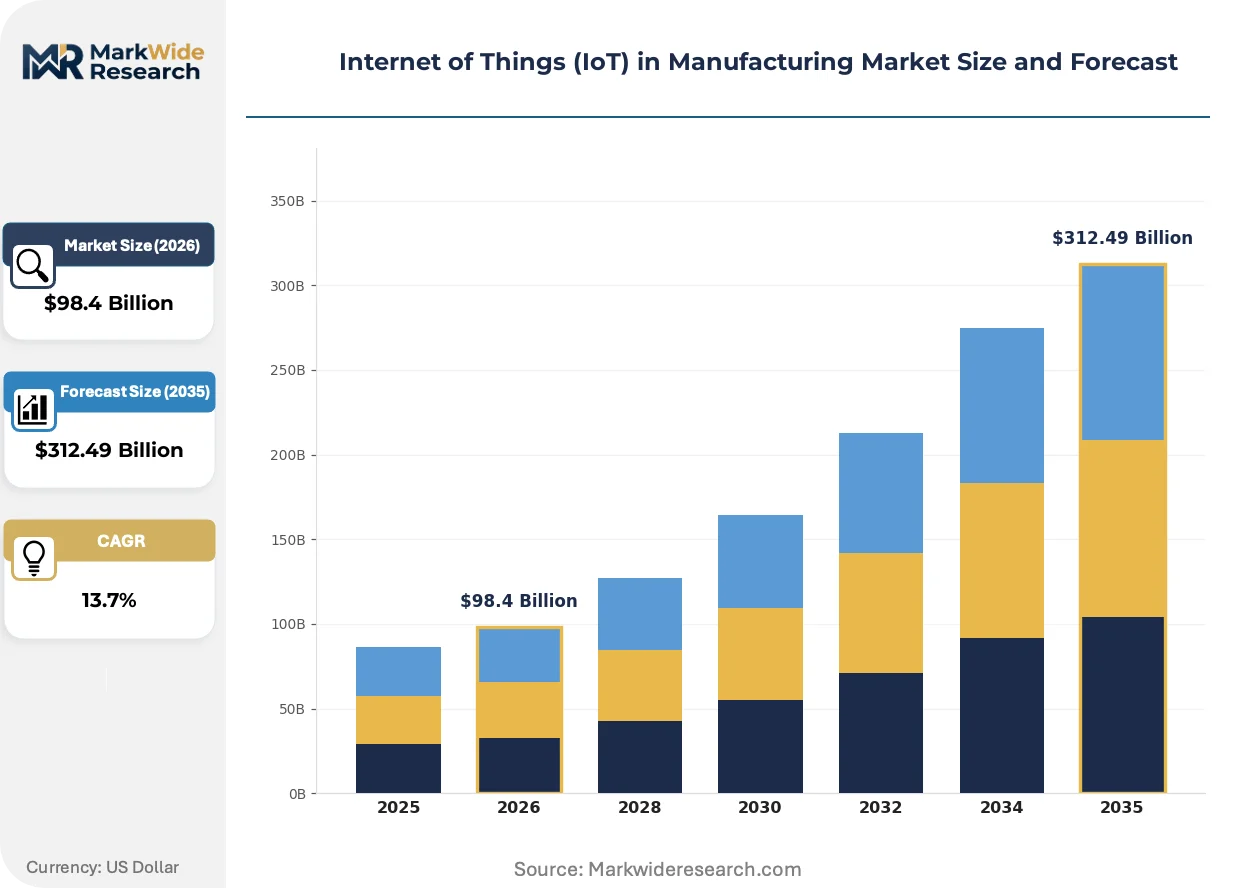
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $312.49 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Sensors, Connected Devices, Industrial Automation, Data Analytics Technology: Edge Computing, Cloud Computing, Machine Learning, Network Protocols Application: Predictive Maintenance, Asset Tracking, Quality Control, Supply Chain Management End User: Aerospace, Automotive OEMs, Electronics, Pharmaceuticals |
| Companies Covered | Siemens, Cisco Systems, Rockwell Automation, General Electric, SAP SE, Schneider Electric, PTC, Honeywell, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet of Things (IoT) in Manufacturing Market Emerging Trajectories
Digital twin architectures are compressing the feedback loop between physical production assets and simulation environments. Three concurrent developments are accelerating this transformation.
Digital twin software is digitizing how automotive and aerospace manufacturers validate process changes before physical implementation. Tier-1 suppliers in Germany and Japan now deploy virtual commissioning for 60-70% of new production lines. This capability is digitizing capital expenditure planning by reducing prototype tooling iterations and accelerating time-to-volume.
EU AI Act risk-classification frameworks are mandating conformity assessment procedures for autonomous quality-inspection systems. High-risk manufacturing AI applications must demonstrate robustness, accuracy, and human oversight protocols before CE marking. Pharmaceutical and medical device manufacturers face the steepest compliance burden, driving consolidation toward vendors with pre-certified edge platforms.
Subscription-based analytics licensing is displacing perpetual software ownership in mid-market manufacturing. Food and beverage processors in North America now favor per-line-month pricing for predictive maintenance dashboards over upfront capital purchases. This shift concentrates vendor risk in retention metrics while lowering customer switching costs.
Internet of Things (IoT) in Manufacturing Market Segmentation
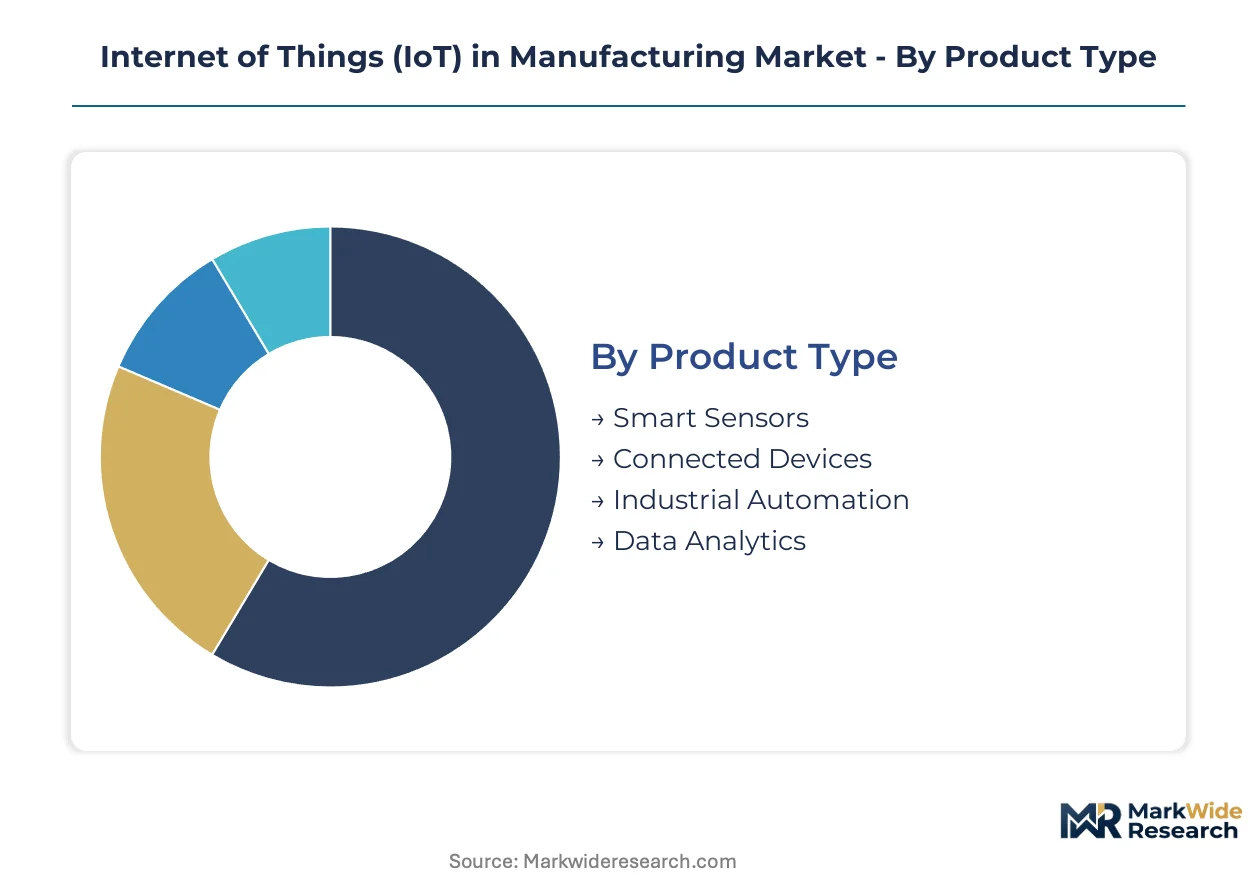
IoT manufacturing deployments fragment across hardware, software, and service layers that demand distinct integration competencies. Procurement patterns diverge sharply between capital-intensive sensor hardware and recurring analytics subscriptions, reshaping vendor-customer relationships across industrial verticals.
Product Type:
After-sales service intensity varies dramatically across product categories, with sensor hardware requiring periodic calibration contracts while analytics platforms demand continuous technical support.
- Smart Sensors:Temperature, pressure, vibration, and proximity transducers embed OPC UA or MQTT communication stacks for direct edge-gateway transmission. Automotive OEMs in Germany's Industrie 4.0 corridor deploy these at machine-tool spindles to capture thermal drift patterns, though semiconductor supply concentration in East Asian foundries creates procurement vulnerability for European manufacturers.
- Data Analytics:Cloud-native and edge-deployed algorithm suites convert operational telemetry into maintenance scheduling and quality predictions. Pharmaceutical manufacturers facing FDA 21 CFR Part 11 validation requirements favor pre-certified platforms that compress deployment timelines for batch-process optimization.
- Connected Devices:Ruggedized tablets, wearable safety monitors, and mobile diagnostic tools bridge human operators with digital workflows.
- Industrial Automation:Programmable logic controllers, distributed control systems, and robotic workcells with embedded IoT connectivity.
By volume, Smart Sensors leads. By growth pace, Data Analytics is ahead.
Technology:
Deployment cost tiers separate proof-of-concept pilots from scaled production implementations, with edge infrastructure commanding premium pricing against cloud-native alternatives.
- Edge Computing:Localized processing nodes execute inference workloads within 10-millisecond latency budgets for real-time control loops. EU AI Act conformity mandates for autonomous manufacturing systems are accelerating certified edge platform procurement, particularly among Mittelstand firms in Germany's Industrie 4.0 corridor.
- Machine Learning:Supervised and unsupervised algorithms for anomaly detection, defect classification, and demand forecasting. Quality Control applications in automotive stamping and electronics assembly are expanding most quickly as computer-vision modules replace manual sampling regimes.
- Cloud Computing:Centralized data lakes and scalable compute resources for historical analysis and cross-facility benchmarking.
- Network Protocols:Time-Sensitive Networking, 5G private networks, and industrial ethernet standards enabling deterministic communication.
Edge Computing captures the largest installed base. Machine Learning shows the steepest expansion trajectory.
Application:
Customer maturity levels determine solution complexity, with predictive maintenance dominating early adopters while quality control attracts digitally advanced manufacturers.
- Predictive Maintenance:Algorithm-driven failure anticipation using vibration analysis, thermal imaging, and oil particulate monitoring. North American food and beverage processors generate recurring analytics revenue for platform vendors through per-line-month subscription licensing.
- Quality Control:Automated visual inspection and dimensional verification using computer-vision systems. India's PLI scheme for advanced manufacturing is attracting greenfield IoT-native investments where autonomous defect detection replaces manual sampling.
- Asset Tracking:Real-time location systems for work-in-progress inventory, tooling, and finished goods.
- Supply Chain Management:Demand sensing, logistics optimization, and supplier visibility platforms.
Predictive Maintenance holds the deepest penetration. Quality Control is climbing the fastest.
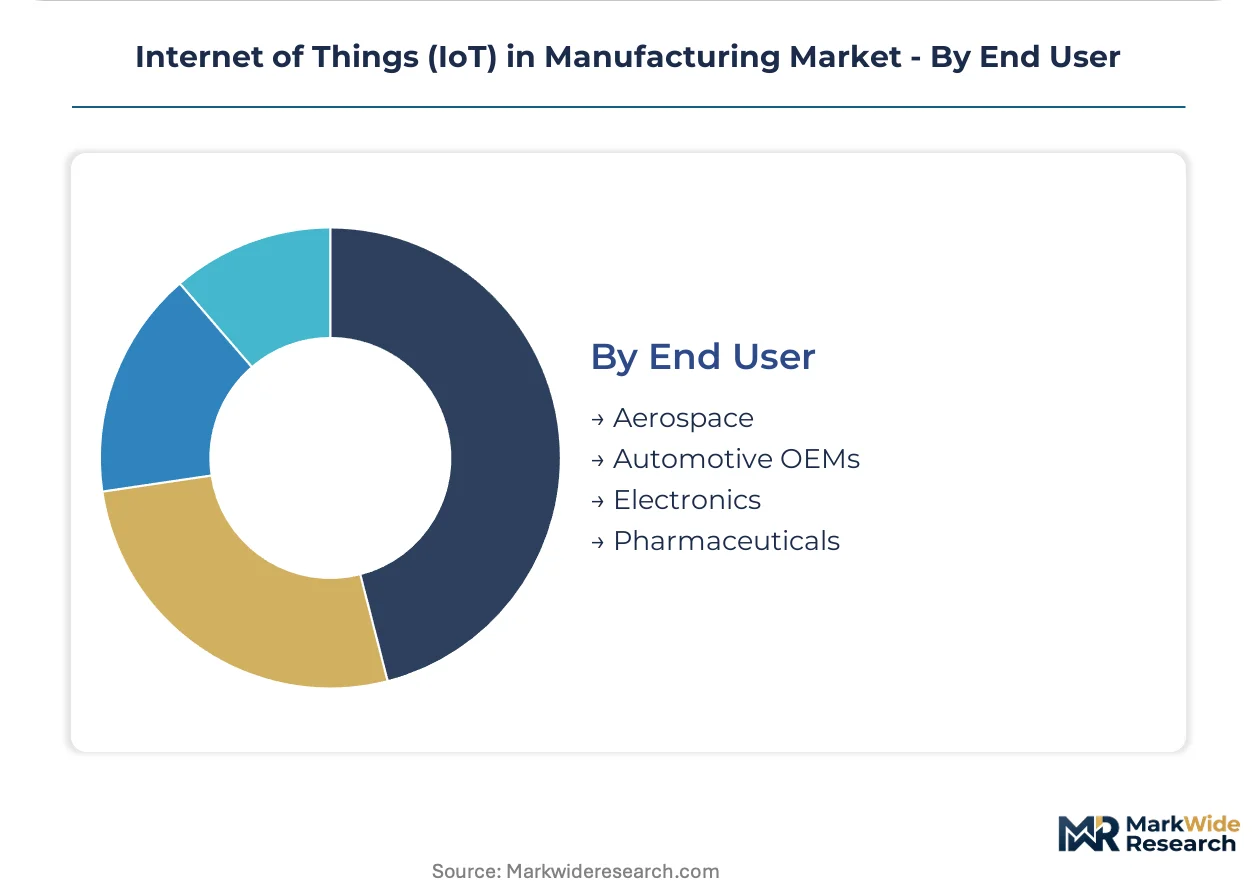
End User:
Application requirements shape technology selection, with pharmaceutical and aerospace sectors demanding validated systems against automotive and electronics priorities for throughput optimization.
- Automotive OEMs:Assembly-line synchronization and paint-shop quality systems. Real-time demand signal integration through distributed computing architectures is reconfiguring production workflows across European plants.
- Pharmaceuticals:Batch-process optimization and electronic records compliance. FDA 21 CFR Part 11 requirements extend certification timelines, compressing deployment velocity for IoT system rollouts.
- Aerospace:Digital twin validation and precision machining monitoring for safety-critical components.
- Electronics:Cleanroom environmental controls and semiconductor wafer tracking.
Automotive OEMs anchor the largest project scale. Pharmaceuticals is gaining share fastest on regulatory-driven platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports industrial automation systems to automotive assembly plants across the United States, China, and Eastern Europe, anchoring transatlantic and Eurasian technology corridors for IoT-enabled manufacturing infrastructure.
United States
Automotive OEMs in Michigan and Ohio deploy edge-computing nodes to synchronize assembly-line throughput with dealer inventory signals. FDA 21 CFR Part 11 requirements extend certification timelines for pharmaceutical IoT rollouts in New Jersey and North Carolina. The Southeast manufacturing belt spanning Georgia and Tennessee attracts greenfield investments in predictive maintenance platforms for food processing.
Germany
Mittelstand firms in Baden-Württemberg anchor sensor-to-cloud integration projects for precision tooling. KBA functional-safety standards restrict market access for uncertified control systems deployed across Bavarian automotive plants. The Industrie 4.0 corridor linking Stuttgart, Munich, and Wolfsburg generates dense reference deployments that accelerate cross-border technology transfer into Poland and Czechia.
China
MIIT industrial internet initiatives drive edge-platform procurement for electronics assembly in Shenzhen and Dongguan. GB standards mandate interoperability testing for connected production equipment deployed across Yangtze River Delta manufacturing zones. Shanghai and Suzhou host the highest concentration of computer-vision quality inspection deployments for semiconductor packaging.
India
PLI scheme incentives attract IoT-native facility investments from multinational conglomerates in Maharashtra and Gujarat. BIS certification requirements shape validation protocols for smart sensors deployed across Tamil Nadu automotive clusters. Karnataka's Bengaluru-Tumkur industrial corridor anchors pharmaceutical batch-process optimization projects serving export markets.
Japan
METI Society 5.0 frameworks accelerate digital twin adoption for precision machining in Aichi Prefecture. JIS standards govern functional-safety certification for autonomous quality-inspection systems in Kansai electronics assembly. Toyota City and Nagoya anchor high-complexity automation environments where virtual commissioning reduces prototype tooling iterations.
Internet of Things (IoT) in Manufacturing Market Vendor Landscape
On the supply side, the industry is consolidating around platform vendors with pre-certified edge architectures and industrial automation specialists with hardened hardware portfolios. The vendor base separates into three strategic archetypes: diversified conglomerates spanning automation and software, network infrastructure specialists, and pure-play analytics platforms. Dominant competitive moves include strategic partnerships between sensor manufacturers and cloud providers, plus vertical integration into edge-computing silicon to secure supply chains.
Within the diversified conglomerate tier, Siemens and ABB exemplify European-based industrial automation incumbents with digital twin portfolios. Cisco Systems occupies a position among network infrastructure specialists competing on factory-floor connectivity resilience. Rockwell Automation anchors the North American programmable logic controller segment serving food and beverage processing lines.
| Leading Market Players |
|---|
| Siemens |
| Cisco Systems |
| Rockwell Automation |
| General Electric |
| SAP SE |
| Schneider Electric |
| PTC |
| Honeywell |
| ABB |
| Others |
Supply Flow & Price Mechanics
East Asian foundry concentration for industrial sensor and edge-computing chip fabrication concentrates upstream margin capture, forcing downstream vendors to compete on software-layer differentiation and certification bundling rather than hardware cost leadership. This structural asymmetry elevates pricing power for semiconductor suppliers while compressing margins for system integrators serving European and North American manufacturing end users.
Pricing Analysis
Current-generation certified edge platforms command substantial premiums over prior-generation uncertified alternatives, while next-generation AI-native architectures are pre-announced at further markups. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act pre-certified platforms from basic connectivity modules and entry-level sensor hardware. Price differentiation hinges on certification grade and volume scale, with pharmaceutical manufacturers facing FDA 21 CFR Part 11 validation requirements showing least price sensitivity due to compliance-driven procurement mandates. Cost compression in mid-market analytics subscriptions is intensifying because subscription-based licensing is displacing perpetual ownership, forcing vendors to absorb churn risk.
Supply Chain Analysis
Tariff exposure between East Asian fabrication centers and European assembly facilities dominates supply chain risk planning for industrial automation vendors. Geographic supply concentration centers on Taiwan, South Korea, and China for advanced sensor silicon and edge-computing processors. Raw material dependencies rest on rare earth elements for magnetic sensors, specialty substrates for MEMS devices, and high-purity silicon wafers. Single-source vulnerability for 7nm and below process nodes creates procurement fragility. Distribution runs through authorized industrial distributors with certified calibration capabilities, plus direct OEM relationships for large-scale automotive and pharmaceutical deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capital expenditure cycles in automotive and pharmaceutical manufacturing are entering a recovery phase as deferred Industry 4.0 investments resume following regulatory clarity from the EU AI Act. This cyclical upturn favors vendors with pre-certified platforms and established Mittelstand reference deployments.
For Market Incumbents: Insulate core revenue streams by deepening backward integration into edge-computing silicon design to reduce foundry dependency exposure. Prioritize certification investment for EU AI Act high-risk system categories before smaller competitors achieve conformity, locking in pharmaceutical and automotive OEM procurement decisions. Channel control through exclusive distribution partnerships with industrial automation specialists remains essential for defending installed base positions against cloud-native entrants. For New Entrants and Emerging Players: Build out white-space presence in India's PLI scheme corridors where greenfield IoT-native facilities lack legacy protocol baggage and prefer subscription-based analytics over capital-intensive hardware procurement. Target quality control applications in electronics assembly as the fastest-expanding segment with lowest incumbent lock-in. A vertical-specific go-to-market angle through pre-integrated computer-vision modules accelerates reference customer acquisition without requiring full platform breadth. For Investors and Strategic Acquirers: Capital is best deployed toward pure-play analytics platforms with pharmaceutical validation credentials and recurring revenue concentration above industry medians. Long-term viability over the coming decade hinges on regulatory moat sustainability rather than feature velocity alone. The signal to watch as inflection indicator is consolidation velocity among Mittelstand system integrators, whose acquisition by global platforms would foreclose independent distribution channels for remaining independents.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Pre-certified edge platforms capture pharmaceutical and automotive OEM procurement decisions before competitors achieve conformity. |
| Backward Integration into Edge Silicon | In-house processor design reduces foundry dependency and secures supply continuity for high-complexity automation deployments. |
| Subscription Analytics Licensing | Per-line-month pricing models align vendor incentives with customer uptime outcomes while lowering switching barriers. |
| Computer-Vision Quality Inspection Partnerships | Pre-integrated defect detection modules accelerate deployment timelines for electronics and automotive stamping customers. |
| India PLI Corridor Expansion | Greenfield facility investments by multinational conglomerates create reference deployments for sensor-to-cloud integration at scale. |
Methodological Framework
A spread of perspectives from plant engineers, automation procurement leads, regulatory affairs specialists, and aftermarket service heads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings, EU AI Act implementation guidance, FDA 21 CFR Part 11 inspection observations, and customs trade data for industrial automation equipment. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for manufacturing capital formation across the analysis window.
Demand-supply balance dynamics anchored the forecast framework, with capacity expansion timelines for East Asian foundries matched against European and North American manufacturing automation project pipelines. Segmentation dimensions modeled include product type, deployment technology, application maturity, and end-user regulatory intensity. CAGRs were derived from slope analysis of historical penetration curves adjusted for regulatory inflection points. Industry-specific forecast inputs incorporated EU AI Act implementation schedules and FDA validation timeline benchmarks.
Stress conditions across semiconductor supply disruption severity, regulatory certification timeline extensions, and pharmaceutical capital expenditure contraction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology adoption curves and competitive dynamics. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Internet of Everything Market
Internet of Things (IoT)
Narrowband IoT Enterprise Application Market
Internet of Things (IoT)
Global Military IoT Market
Internet of Things (IoT)
Internet of Things (IoT) Market
Internet of Things (IoT)
Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
Automotive Internet of Things (IoT) Market
Internet of Things (IoT)
Solar Based Internet of Things (IoT) Market
Internet of Things (IoT)
Global IoT in Automobile Market
Internet of Things (IoT)
Massive IoT Market
Internet of Things (IoT)
IoT Platform Market
Internet of Things (IoT)
IoT Data Management Market
Internet of Things (IoT)
Lora and Lorawan IoT Connectivity Market
Internet of Things (IoT)
IoT in Energy Market
Internet of Things (IoT)
Global Internet of Things (IoT) Software Market
Internet of Things (IoT)
IoT for Cold Chain Monitoring Market
Internet of Things (IoT)
IoT Device Management Market