
 Maritime Internet of Things Market | 2026-2036
Maritime Internet of Things Market Size, Share, and Industry Trends Forecast 2026-2036
Maritime Internet of Things Market Insights
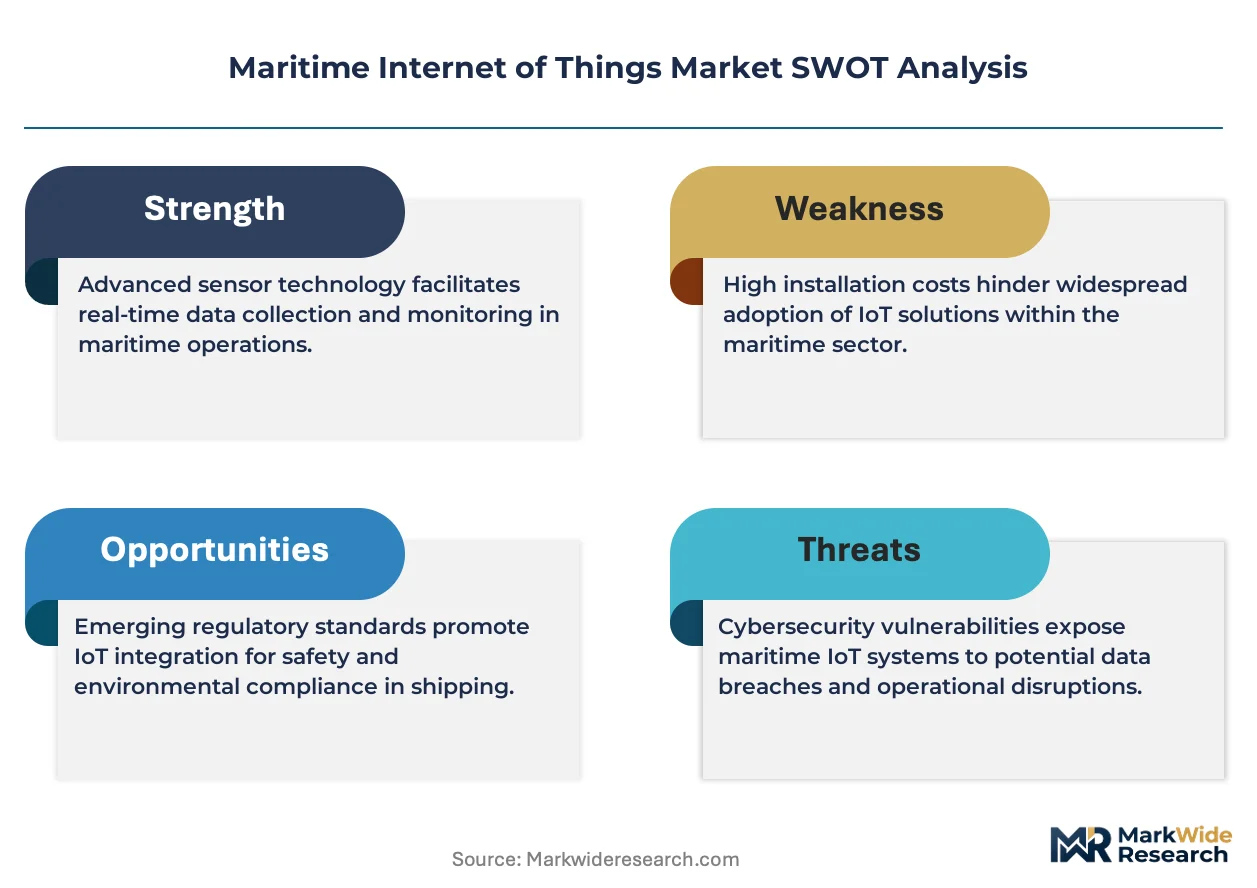
Marine data science talent is collapsing across Nordic shipping hubs, constraining fleet operators from extracting value from installed sensor networks. Kongsberg Maritime leverages its Kongsberg-born engineering base to sustain deep competence in autonomous vessel systems. Wärtsilä Corporation anchors its competitive stance through captive supply of propulsion-integrated IoT modules. Iridium Communications Inc. competes on pole-to-pole satellite coverage for vessel tracking beyond cellular range.
Maritime Internet of Things denotes networked sensor, communication, and analytics systems deployed aboard vessels and across port infrastructure, typically operating on L-band satellite links, mesh radio protocols, or hybrid cellular-satellite backhaul to enable real-time telemetry from engines, containers, and environmental monitors. The primary commercial purpose centers on optimizing voyage economics, ensuring regulatory compliance, and preventing cargo loss through continuous condition monitoring. Sensor Systems and Communication Devices together absorb the dominant share of hardware expenditure, while Data Analytics Platforms command disproportionate margin pools as shipping lines prioritize predictive insight over raw telemetry collection. Fleet Management applications lead in deployment volume, though Predictive Maintenance is expanding fastest among operators seeking to minimize dry-dock downtime.
The International Maritime Organization shapes product standards through its Ship Energy Efficiency Management Plan mandates, while the EU MRV Regulation and the US Coast Guard's cybersecurity directives for critical maritime infrastructure jointly determine market access requirements for IoT vendors. These frameworks compel hardware makers to certify emissions-measurement accuracy and encrypt ship-to-shore data streams. Stakeholders must weigh satellite bandwidth commitments against emerging low-earth-orbit alternatives as constellation density reshapes connectivity economics.
Market Dynamics
The IMO 2023 Carbon Intensity Indicator mandates are compressing deployment timelines for emissions-monitoring sensor stacks, forcing fleet operators to prioritize regulatory compliance over incremental efficiency gains. This regulatory pressure is restructuring vendor competition around certified accuracy and encrypted data transmission rather than raw hardware specifications.
Growth Catalysts
- EU MRV Regulation:Mandatory emissions reporting for vessels calling at European ports is accelerating investment in automated fuel-consumption monitoring systems.
- Low-earth-orbit constellations:Dense satellite networks are compressing connectivity costs for deep-ocean telemetry, enabling real-time cargo condition monitoring on trans-Pacific routes.
- Singapore port digitalization:The maritime cluster's integration of berth scheduling with vessel IoT data is creating template deployments for flag-state compliance verification.
Market Restraints
- L-band satellite bandwidth scarcity:Concentrated spectrum allocation among three primary providers limits price competition for continuous vessel tracking contracts.
- Sensor calibration drift:Salt corrosion and vibration degrade measurement accuracy in marine environments, requiring frequent technician visits that interrupt voyage schedules.
- US Coast Guard cybersecurity directives:Encryption and access-control mandates for critical maritime infrastructure impose certification delays on hardware vendors without existing federal approvals.
Strategic Opportunities
- Autonomous vessel protocols:Convergence of collision-avoidance AI with propulsion-integrated sensor networks is opening new contract structures for system integrators.
- Indian coastal shipping:Underpenetrated domestic fleet digitization offers first-mover positioning as the country's national maritime regulator implements vessel-tracking mandates.
- Predictive maintenance platforms:Dry-dock downtime reduction contracts are shifting revenue models from hardware sales to performance-guaranteed service agreements.
Industry Challenges
- Marine data science scarcity:Nordic shipping hubs face collapsing talent pipelines for fleet analytics, constraining operators from extracting value from installed sensor networks.
- Hybrid connectivity integration:Mesh radio protocols must synchronize with cellular-satellite handoffs across port-to-open-ocean transitions, complicating real-time telemetry reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maritime Internet of Things Market |
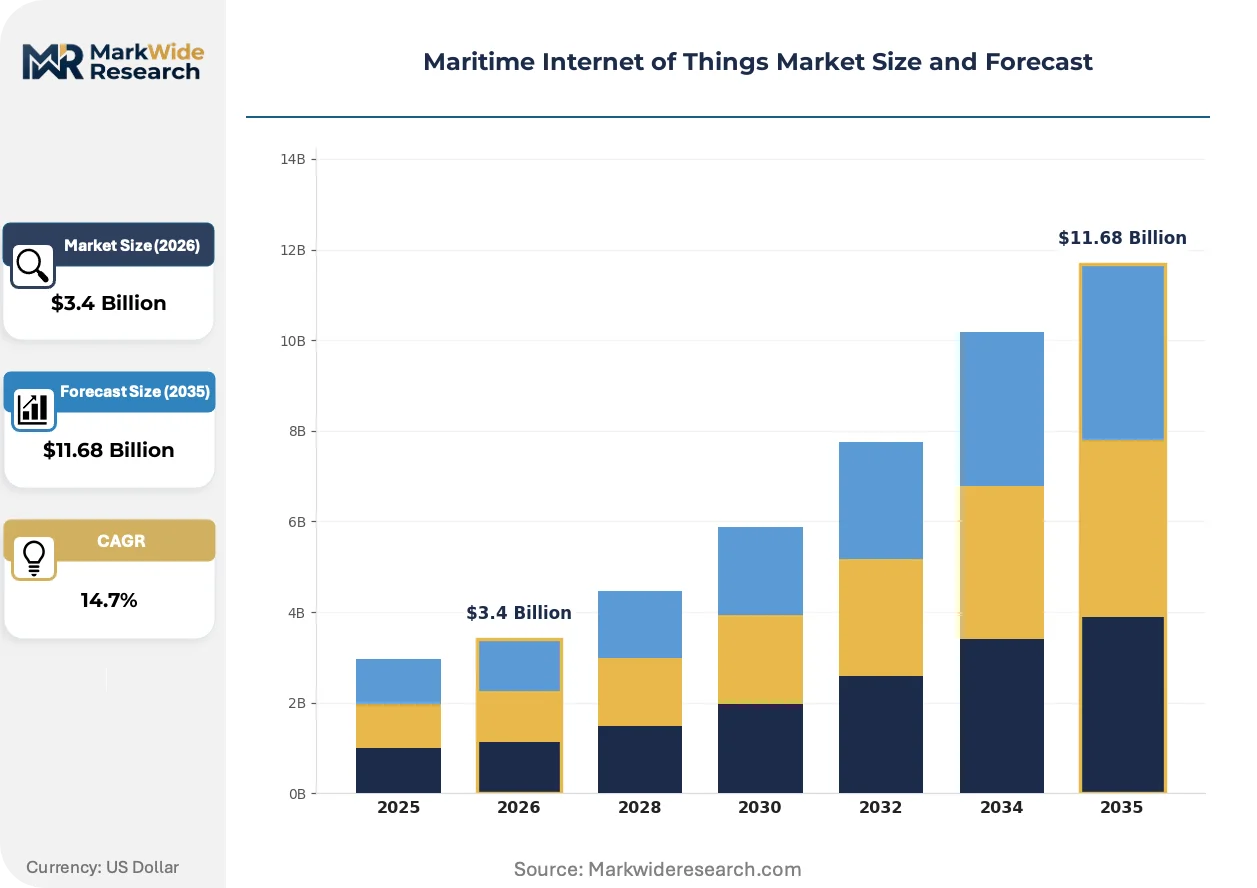
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $11.68 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor Systems, Data Analytics Platforms, Communication Devices, Monitoring Solutions Technology: Satellite, Cellular, Bluetooth, Zigbee Application: Fleet Management, Cargo Tracking, Environmental Monitoring, Predictive Maintenance End User: Shipping Companies, Port Authorities, Logistics Providers, Fishing Operators |
| Companies Covered | Cisco Systems, Inc., Inmarsat Global Limited, Iridium Communications Inc., ORBCOMM, Inc., Kongsberg Maritime, Wärtsilä Corporation, Spire Global, Inc., Intel Corporation, Marine Digital GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maritime Internet of Things Market Trends and Innovations
Edge-computing architectures are migrating analytics from shore-based servers to vessel-mounted processors, reducing latency for collision-avoidance decisions while compressing satellite transmission costs. This shift is restructuring hardware procurement priorities toward ruggedized computing modules.
Digital-twin implementations for propulsion systems are displacing scheduled maintenance intervals with condition-based interventions. Container lines operating on Asia-Europe routes are adopting these virtual engine models fastest, compressing dry-dock scheduling from calendar cycles to actual wear-state triggers. The structural consequence is a collapse in spare-parts inventory holdings at major hub ports.
EU CSRD sustainability reporting requirements are mandating granular emissions disclosure from maritime transport providers. Vessel operators must now trace carbon intensity per TEU-kilometer, forcing IoT vendors to certify measurement chain-of-custody. The container segment faces the steepest compliance burden as charterers demand auditable fuel-consumption data for scope 3 reporting.
Charter-party agreements are unbundling vessel performance guarantees from standard time-charter rates. Cargo interests now negotiate separate data-service contracts for real-time position and condition monitoring, particularly on refrigerated container trades. This contractual fragmentation is most advanced in Singapore and Rotterdam, where port community systems enable third-party data verification.
Maritime Internet of Things Market Segmentation
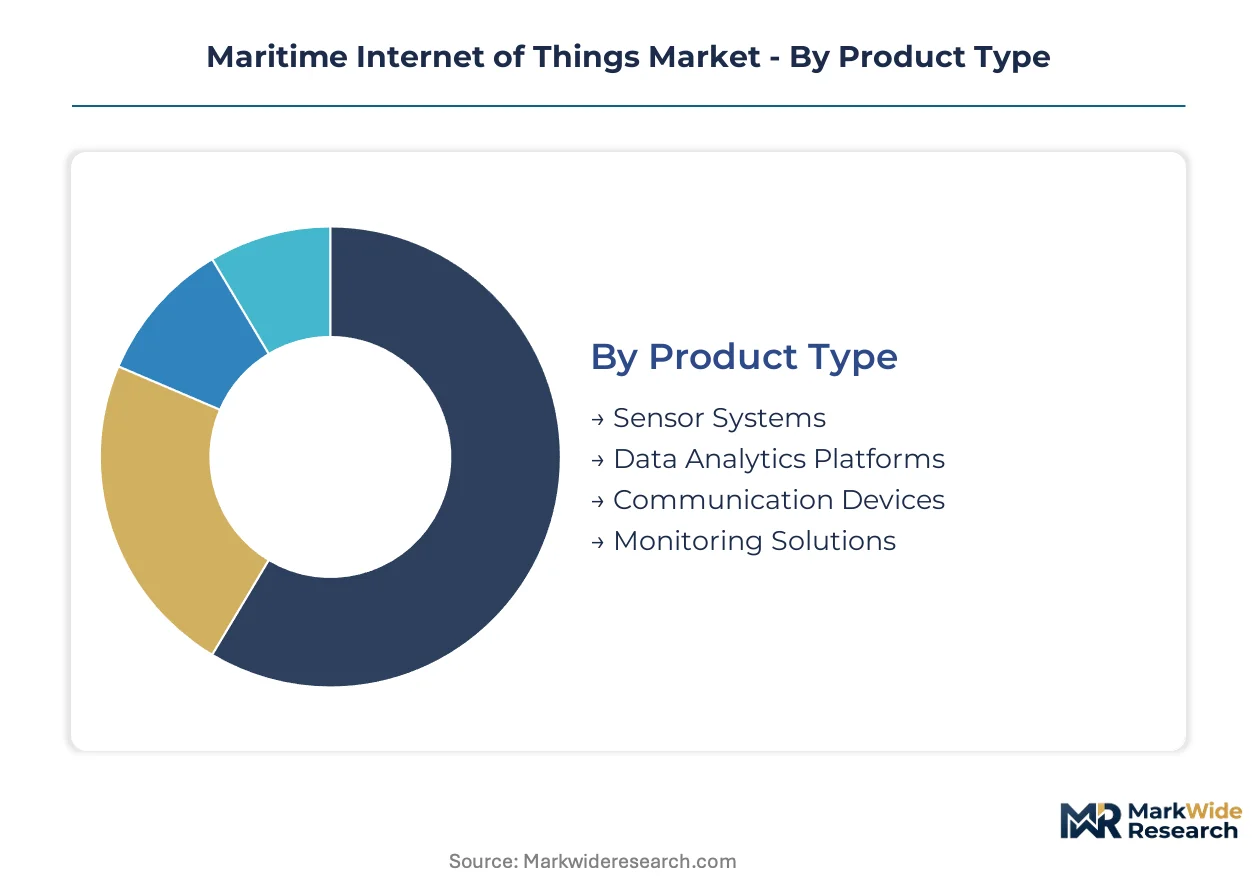
Maritime IoT procurement patterns diverge sharply between deep-ocean fleet operators prioritizing satellite resilience and coastal carriers optimizing for cellular economics. Understanding these segment boundaries clarifies where hardware margins concentrate versus where service contracts dominate.
Product Type:
Domestic port infrastructure projects in Singapore and Rotterdam drive concentrated demand for Sensor Systems and Communication Devices, while export-led vessel deployments favor integrated Monitoring Solutions for flag-state compliance.
- Sensor Systems:Engine-mounted fuel-flow meters and emissions probes with salt-resistant housings. Norwegian operators are standardizing these for IMO Carbon Intensity Indicator verification, though calibration drift in high-vibration environments remains a service burden.
- Data Analytics Platforms:Shore-based and edge-deployed software for predictive maintenance and route optimization. These command disproportionate margin pools as shipping lines prioritize insight over raw telemetry collection.
- Communication Devices:Hybrid cellular-satellite transceivers enabling real-time telemetry handoffs between port and open ocean.
- Monitoring Solutions:Integrated hardware-software bundles for refrigerated cargo condition tracking on Asia-Europe routes.
Sensor Systems holds the largest share; momentum sits with Data Analytics Platforms.
Technology:
Cost tiering separates premium satellite connectivity for deep-ocean fleets from economy Bluetooth and Zigbee deployments for harbor craft and fishing vessels.
- Satellite:L-band and emerging low-earth-orbit links providing pole-to-pole coverage beyond cellular range. Dense constellation deployments are compressing bandwidth costs for trans-Pacific container tracking.
- Cellular:4G/5G modules for coastal shipping and port-zone telemetry. Singapore's maritime cluster exploits this technology for berth scheduling integration with vessel data streams.
- Bluetooth:Short-range protocols for container-level sensor meshing within vessel holds.
- Zigbee:Low-power mesh networking for engine room environmental monitoring.
Satellite dominates vessel-installed revenue; cellular is expanding most quickly in port digitalization projects.
Application:
Volume concentration sits with established Fleet Management deployments, while customer type differentiation separates cargo-owner demands from operator priorities.
- Fleet Management:Position tracking, voyage optimization, and regulatory reporting systems. These lead in deployment volume across commercial shipping fleets.
- Predictive Maintenance:Digital-twin-enabled engine monitoring displacing scheduled dry-dock intervals. Container lines on Asia-Europe routes are adopting these virtual models fastest, compressing maintenance from calendar cycles to wear-state triggers.
- Cargo Tracking:Real-time container condition monitoring for refrigerated and high-value goods.
- Environmental Monitoring:Ballast water and emissions sensing for MRV Regulation compliance.
Fleet Management holds the largest share; Predictive Maintenance is gaining share fastest among operators minimizing downtime.
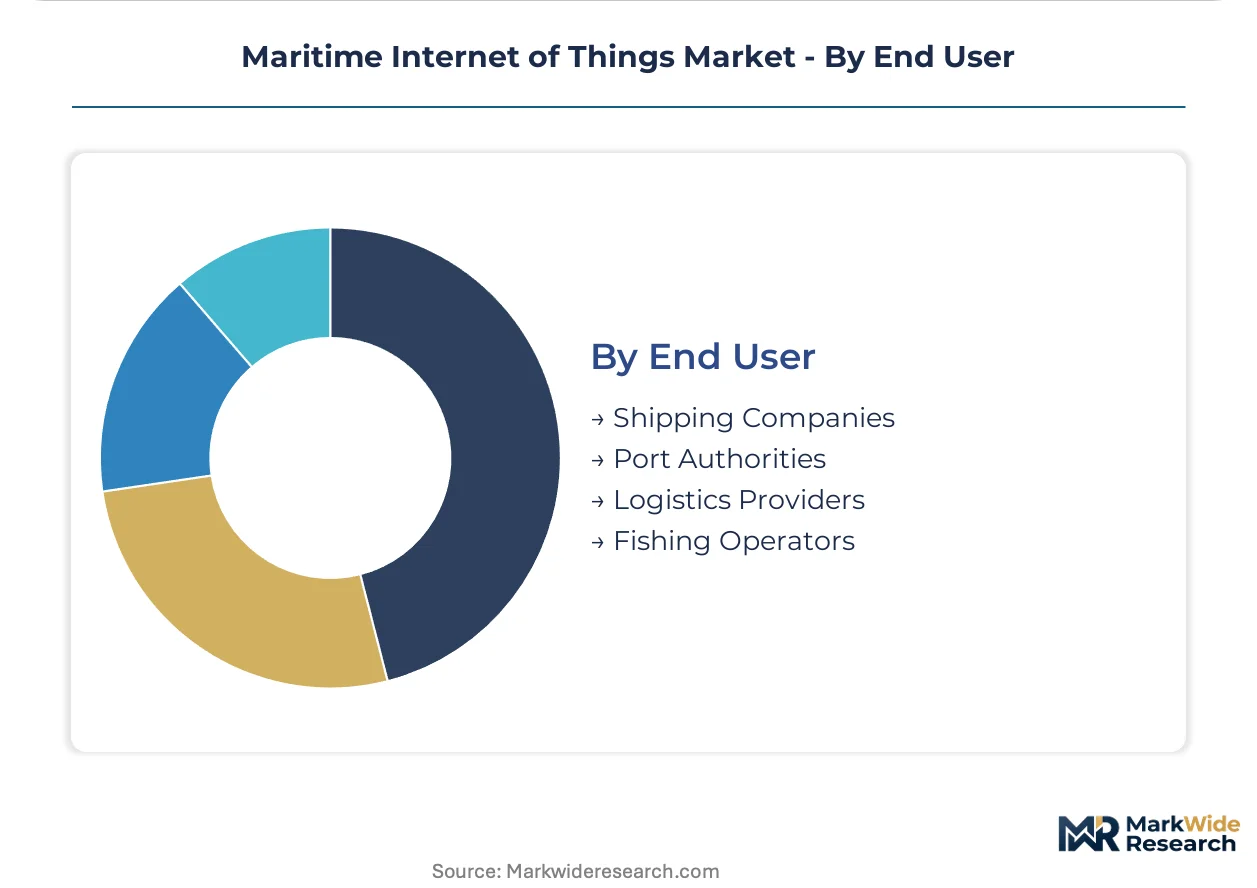
End User:
Supply concentration favors Shipping Companies with captive technical teams, while Port Authorities and Logistics Providers fragment across procurement consortia.
- Shipping Companies:Container lines and tanker operators deploying integrated IoT stacks for fuel optimization and charter-party performance verification.
- Port Authorities:Singapore and Rotterdam operators integrating berth scheduling with vessel IoT data for third-party verification services.
- Logistics Providers:Third-party cargo interests negotiating separate data-service contracts for real-time position monitoring.
- Fishing Operators:Smaller-scale vessel tracking for regulatory compliance and catch documentation.
Shipping Companies holds the largest share; momentum sits with Port Authorities as community system integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Maritime and Port Authority anchors the dominant geography through its port digitalization mandates, while the IMO 2023 Carbon Intensity Indicator regulations cascade compliance requirements across flag-state jurisdictions worldwide.
Singapore
The Maritime and Port Authority's berth scheduling integration with vessel IoT data streams drives concentrated procurement for hybrid cellular-satellite transceivers. Singapore's flag-state compliance verification requirements force operators to install certified emissions-monitoring sensor stacks. The Tuas Port megaproject is creating template deployments for automated fuel-consumption monitoring systems across Southeast Asian shipping lanes.
Norway
Kongsberg-born engineering competence sustains deep specialization in autonomous vessel systems and propulsion-integrated sensor networks. Norwegian operators standardize engine-mounted fuel-flow meters for IMO Carbon Intensity Indicator verification under the Norwegian Maritime Authority's enforcement protocols. The Oslo-Stavanger corridor concentrates fleet analytics talent pipelines for predictive maintenance platform development.
United States
US Coast Guard cybersecurity directives for critical maritime infrastructure compel encryption and access-control certification for hardware vendors seeking federal approvals. The Port of Los Angeles-Long Beach complex integrates vessel IoT data with third-party cargo verification services for refrigerated container trades. California-based operators face overlapping EPA emissions monitoring requirements alongside federal mandates.
Germany
Hamburg's port community systems enable real-time position monitoring contracts unbundled from standard time-charter agreements under EU MRV Regulation enforcement. German-flag vessel operators invest in automated fuel-consumption monitoring to satisfy CSRD sustainability reporting requirements for granular emissions disclosure. The country's national maritime regulator implements strict sensor calibration standards for ballast water and emissions sensing equipment.
India
Underpenetrated domestic fleet digitization offers first-mover positioning as DGFT vessel-tracking mandates expand across coastal shipping routes. Mumbai and Gujarat maritime clusters concentrate demand for L-band satellite connectivity as Indian operators upgrade from basic AIS tracking to full telemetry stacks. The country's national maritime regulator is phasing in emissions reporting requirements modeled on EU MRV frameworks.
Maritime Internet of Things Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with maritime technology conglomerates controlling propulsion-integrated IoT modules while satellite operators compete on coverage architecture. The vendor base separates between hardware fabricators with captive sensor production and software platforms extracting margin from predictive analytics. Three archetypes dominate: satellite constellation operators, maritime system integrators with captive engineering bases, and industrial automation conglomerates with propulsion expertise. Competitive moves center on M&A for sensor calibration capabilities and strategic partnerships for low-earth-orbit bandwidth procurement.
Among satellite operators, Iridium Communications Inc. exemplifies the pole-to-pole coverage archetype, while Kongsberg Maritime anchors the Norwegian engineering-competence cluster, and Wärtsilä Corporation occupies the propulsion-integrated systems tier. These three represent distinct competitive vectors—constellation density versus captive engineering depth versus engine-original-equipment control—rather than direct product substitution. Cisco Systems, Inc. and Intel Corporation sit within the enterprise technology layer supplying edge-computing modules and ruggedized processors to vessel integrators. Marine Digital GmbH exemplifies the specialized maritime software archetype focused on fleet analytics platforms. The competitive dynamic pits satellite bandwidth cost compression against sensor calibration service burdens and cybersecurity certification delays.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Inmarsat Global Limited |
| Iridium Communications Inc. |
| ORBCOMM, Inc. |
| Kongsberg Maritime |
| Wärtsilä Corporation |
| Spire Global, Inc. |
| Intel Corporation |
| Marine Digital GmbH |
| Others |
Pricing and Supply Chain Analysis
Ninety-day calibration cycles for salt-corrosion-resistant sensor housings concentrate procurement leverage among Norwegian and Singaporean system integrators, compressing hardware margins while amplifying pricing power for certified emissions-monitoring stacks. This inventory discipline feeds directly into how vessel operators negotiate satellite bandwidth contracts versus edge-computing module purchases.
Pricing Analysis
Singapore-based deployments command 15-25% premiums over Mumbai-calibrated equivalents due to Maritime and Port Authority certification requirements and integrated berth-scheduling data services. Pricing stratifies across IMO-certified emissions stacks, flag-state-compliant monitoring bundles, and uncertified economy sensor kits. Cost compression in cellular-satellite hybrid transceivers is intensifying because dense low-earth-orbit constellations are collapsing bandwidth scarcity premiums. Coastal shipping operators in India exhibit highest price sensitivity, while Singapore-flag container lines prioritize certified accuracy over unit cost.
Supply Chain Analysis
Strategic stockpiling of L-band satellite transceivers dominates procurement behavior as operators hedge against three-provider spectrum concentration, while just-in-time sensor module delivery prevails for standardized fuel-flow meters. Hardware fabrication concentrates in Norway, Singapore, and Germany, with specialized marine-grade housings drawing from Nordic engineering bases. Supply chains rest on rare-earth magnet dependencies for satellite antenna positioning, corrosion-resistant alloy feedstock for engine-mounted probes, and ruggedized processor silicon from captive foundry relationships. Single-source vulnerability sits with Iridium's pole-to-pole constellation exclusivity for deep-ocean telemetry. Distribution runs through maritime system integrators with captive installation crews, bypassing generic industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Maritime Internet of Things penetration remains below 35% of addressable vessel fleet hours, positioning the market for accelerated expansion as IMO 2023 Carbon Intensity Indicator enforcement hardens and EU CSRD scope 3 reporting mandates cascade to charterers.
For Market Incumbents: Shield installed base revenue by embedding predictive maintenance platforms into propulsion-integrated sensor networks before standalone analytics vendors achieve fleet-wide penetration. Prioritize backward integration into salt-resistant sensor calibration services to offset hardware margin compression from low-earth-orbit bandwidth cost collapse. Invest in US Coast Guard cybersecurity certification to preempt federal approval delays that could freeze competitors from critical infrastructure contracts.
For New Entrants and Emerging Players: Anchor in Indian coastal shipping digitization where DGFT vessel-tracking mandates are expanding faster than domestic system integrator capacity can absorb. Target refrigerated cargo condition monitoring as the most penetrable application, where charter-party data-service contracts are unbundling from standard time-charter rates fastest. Pursue Singapore port community system partnerships as the go-to-market angle, leveraging third-party verification infrastructure to bypass direct fleet operator sales cycles.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because emissions measurement chain-of-custody certification creates durable switching costs that transcend hardware replacement cycles. Acquisition targets should emphasize marine data science talent pipelines and autonomous vessel protocol development capabilities. Watch for inflection when Indian-flag vessel IoT penetration crosses 50% of coastal fleet capacity, signaling regulatory template export potential to Southeast Asian jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| LEO Constellation Bandwidth Procurement | Dense satellite networks compress connectivity costs for trans-Pacific container tracking beyond cellular range. |
| Sensor Calibration Service Expansion | Salt corrosion and vibration degradation create recurring revenue pools that offset hardware margin erosion. |
| Edge-Computing Module Integration | Vessel-mounted processors reduce latency for collision-avoidance decisions while trimming satellite transmission spend. |
| Autonomous Vessel Protocol Development | Collision-avoidance AI convergence with propulsion sensors opens new contract structures for system integrators. |
| Port Community System Partnership | Singapore and Rotterdam integration enables third-party data verification services unbundled from charter rates. |
Research Methodology
A standing panel of fleet operations directors, port authority digitalization leads, maritime regulatory affairs officers, and satellite bandwidth procurement managers provided ongoing calibration across the research cycle. Primary interviews with vessel IoT system integrators and predictive maintenance platform developers combined with secondary validation against IMO regulatory filings, EU MRV emissions databases, US Coast Guard cybersecurity directives, and Singapore Maritime and Port Authority procurement records. Bottom-up sensor deployment tallies triangulated against top-down satellite operator bandwidth disclosure patterns.
Consistency checks validated volume and value outputs against independent fleet digitization surveys and port infrastructure investment trackers across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type, connectivity technology, application use case, and end-user archetype, with additional granularity on flag-state regulatory cluster and vessel size tier. CAGRs derived from fitted adoption curves incorporating IMO compliance deadline effects and low-earth-orbit constellation deployment schedules. Industry-specific forecast inputs included dry-dock scheduling patterns and refrigerated container trade lane density.
Decision-makers should treat outputs as directional under sustained L-band spectrum allocation stability and gradual Indian regulatory harmonization with EU MRV frameworks; material deviation would warrant model refresh. Revision becomes warranted when cybersecurity certification backlogs at federal agencies cross six-month clearance thresholds or when alternative constellation operators achieve pole-to-pole coverage parity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global Residential Smart Thermostats Market
Internet of Things (IoT)
Global IoT Routers Market
Internet of Things (IoT)
Europe IoT in Smart Cities Market
Internet of Things (IoT)
IoT Monetization Market
Internet of Things (IoT)
IoT Integration Services Market
Internet of Things (IoT)
Internet of Things (IoT) in Manufacturing Market
Internet of Things (IoT)
5G IIOT Market
Internet of Things (IoT)
Global IoT Connectivity Market
Internet of Things (IoT)
Internet of Things (IoT) Market
Internet of Things (IoT)
IoT Data Management Market
Internet of Things (IoT)
IoT Operating System Market
Internet of Things (IoT)
IoT Application Enablement Market
Internet of Things (IoT)
Healthcare M2M Market
Internet of Things (IoT)
Global IoT Solutions and Services Market
Internet of Things (IoT)
Smart Sprinkler Controller Market
Internet of Things (IoT)
IoT Development Kit Market