
 Wi-Fi Smart Scale Market | 2026-2036
Wi-Fi Smart Scale Market Size, Share, and Industry Trends Forecast 2026-2036
Wi-Fi Smart Scale Market Insights
China is reconfiguring regional supply dynamics through expanded electronics manufacturing clusters in Shenzhen and Dongguan. Withings leverages French design heritage and medical-grade certification to anchor premium positioning in European markets. Xiaomi sustains aggressive ecosystem bundling, embedding smart scales within its Mi Health platform to drive cross-device retention. Garmin differentiates through athletic-performance segmentation, targeting triathletes and runners with advanced body-composition metrics.
A Wi-Fi smart scale is a connected weighing device that measures body mass and typically additional biometrics such as body fat percentage, muscle mass, bone density, and water content through bioelectrical impedance analysis, transmitting data wirelessly to cloud-based health platforms for longitudinal tracking. Its primary purpose serves both consumer wellness management and clinical remote monitoring, enabling healthcare providers and individuals to observe metabolic trends without in-person measurement. Body composition functionality commands the dominant margin pool as consumers trade up from basic weight measurement to multi-metric health intelligence. Bluetooth-enabled units retain volume leadership due to lower power requirements and simpler pairing protocols, though Wi-Fi connectivity is gaining traction among households seeking seamless multi-user data synchronization without smartphone proximity.
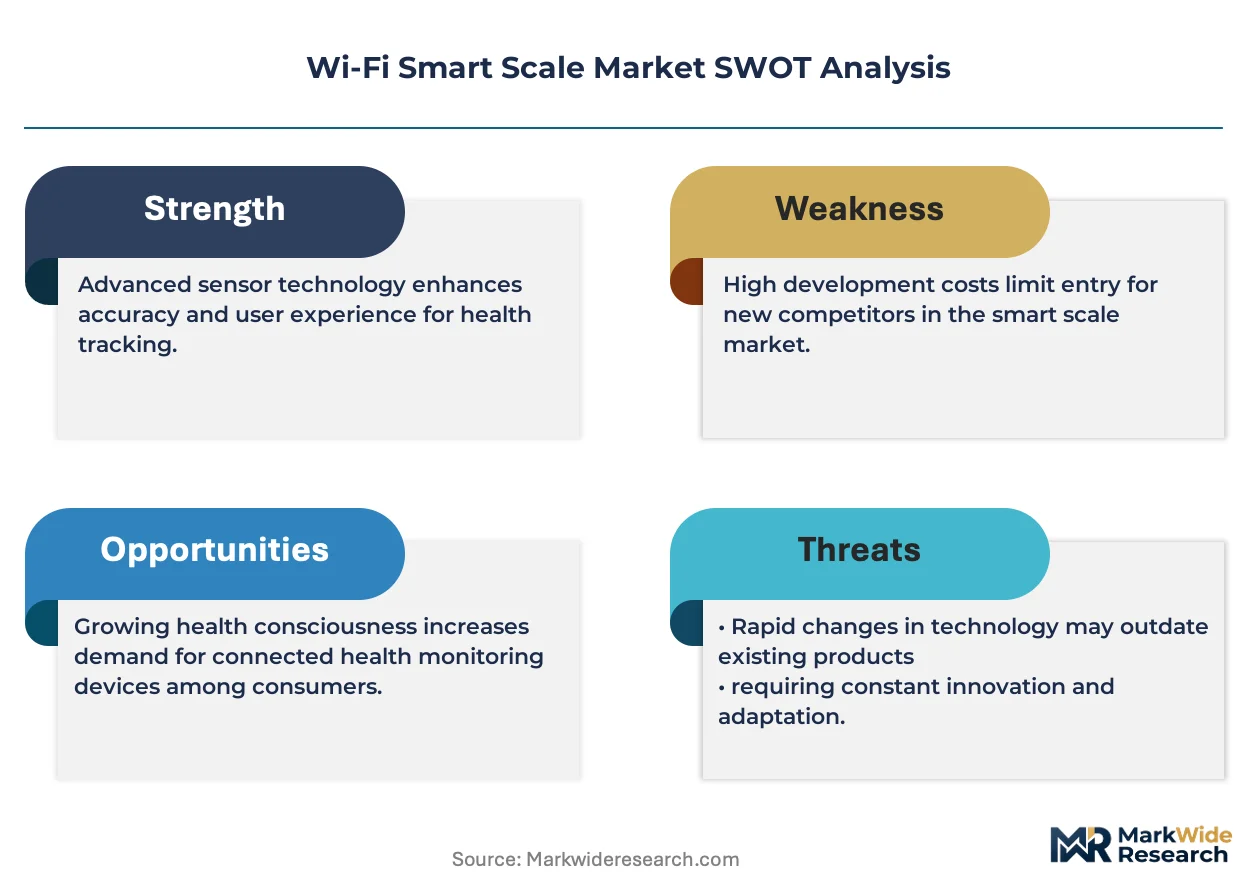
The FDA regulates smart scales making specific medical claims as Class II medical devices in the United States, requiring 510(k) clearance for metrics beyond basic weight measurement. The EU MDR and GDPR collectively reshape product architecture, mandating clinical-validation standards for body-composition algorithms while restricting cross-border health-data flows. China's SAMR enforces GB standards for wireless transmission and measurement accuracy in domestic sales. Stakeholders must monitor evolving interoperability requirements between proprietary health platforms and emerging open-standard ecosystems as the decisive battleground for customer lock-in.
Market Dynamics
Corporate wellness mandates are restructuring procurement patterns for connected body-composition devices, as employers integrate biometric monitoring into preventive health benefits and insurance premium calculations.
Growth Catalysts
- GDPR-MDR compliance convergence:European data-privacy and medical-device frameworks are creating certification barriers that favor established manufacturers with clinical-validation capabilities.
- Employer-sponsored health initiatives:Fortune 500 companies are deploying Wi-Fi scales within employee wellness portals to reduce insurance claims through metabolic trend detection.
- Shenzhen-Dongguan electronics clusters:Concentrated PCB and sensor manufacturing in China's Pearl River Delta is compressing component costs for bioelectrical impedance modules.
Market Restraints
- Electrode corrosion vulnerability:Bioimpedance sensors require periodic replacement due to sweat and humidity degradation, elevating lifetime ownership costs.
- FDA 510(k) timeline friction:Class II medical device clearance for body-fat algorithms extends product launch cycles by 18-24 months versus basic weight-only devices.
- Bluetooth substitution pressure:Lower-power BLE protocols dominate price-sensitive consumer segments, limiting Wi-Fi premium capture in emerging markets.
Strategic Opportunities
- Remote patient monitoring integration:CMS reimbursement codes for chronic disease management are opening clinical procurement channels previously closed to consumer wellness brands.
- Multi-sensor fusion architectures:Convergence of pressure sensors with photoplethysmography is enabling single-device capture of weight plus cardiovascular metrics.
- Direct-to-employer distribution:BYOD wellness programs bypass retail margin compression through bulk corporate contracts with centralized fleet management.
Industry Challenges
- Algorithm validation expertise scarcity:Clinical biostatistics talent for demonstrating body-composition accuracy against DEXA reference standards commands premium compensation.
- Interoperability fragmentation:Proprietary health platforms resist open API standards, forcing manufacturers to maintain multiple cloud integration pipelines.
- Supply chain reconfiguration costs:Relocating final assembly from China to Vietnam or Mexico to mitigate tariff exposure requires requalification of wireless certification testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wi-Fi Smart Scale Market |
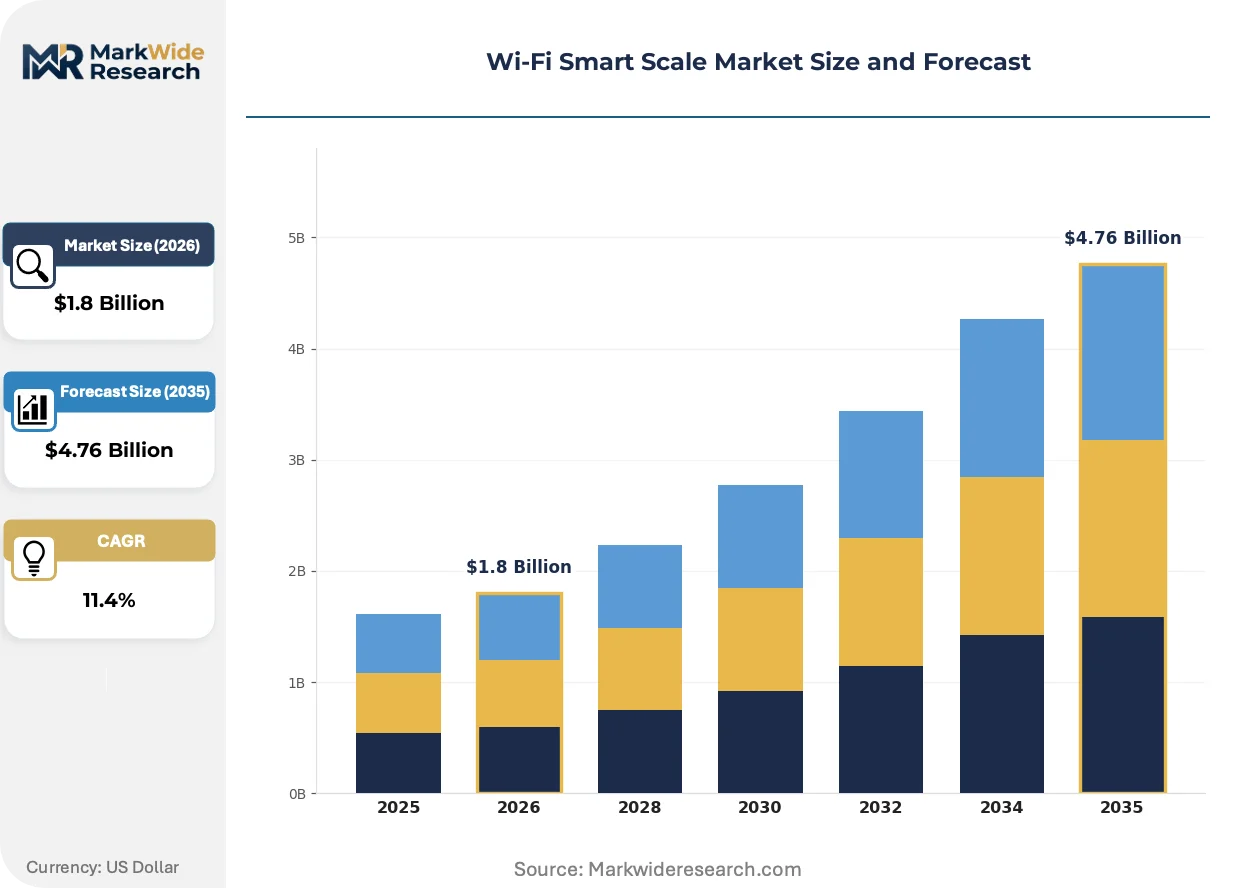
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Body Composition, Bathroom Scale, Smart Scale, Digital Scale Technology: Bluetooth, Wi-Fi, NFC, LAN User Category: Fitness Enthusiasts, Diabetics, Seniors, Health-Conscious Consumers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Fitbit, Withings, Xiaomi, Garmin, RENPHO, Tanita, iHealth Labs, Qardio, Beurer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wi-Fi Smart Scale Market Trends and Innovations
Multi-frequency bioelectrical impedance analysis is replacing single-frequency measurement, while regulatory pressure on health-data portability accelerates platform unbundling.
Multi-frequency bioelectrical impedance analysis transmits alternating currents at 5-1000 kHz to distinguish intracellular from extracellular water, yielding superior muscle-mass precision. Athletic-performance segments in North America and Western Europe are adopting this capability fastest. Single-frequency 50 kHz legacy designs are rendering obsolete in premium positioning as consumers demand clinical-grade accuracy.
The EU AI Act's risk-classification framework now captures algorithmic health recommendations from connected devices, mandating conformity assessments for body-composition coaching outputs. Manufacturers must document training data provenance and bias mitigation for cloud-based metabolic insights. European market entry now requires parallel GDPR data-governance and AI Act technical documentation.
Subscription unbundling is separating hardware from analytics revenue, with buyers increasingly rejecting mandatory cloud-service fees after device purchase. Direct retail channels and employer procurement desks are favoring API-accessible raw data exports over walled-garden platforms. This pattern concentrates in Germany and the Netherlands, where consumer-protection sentiment favors data portability.
Wi-Fi Smart Scale Market Segmentation
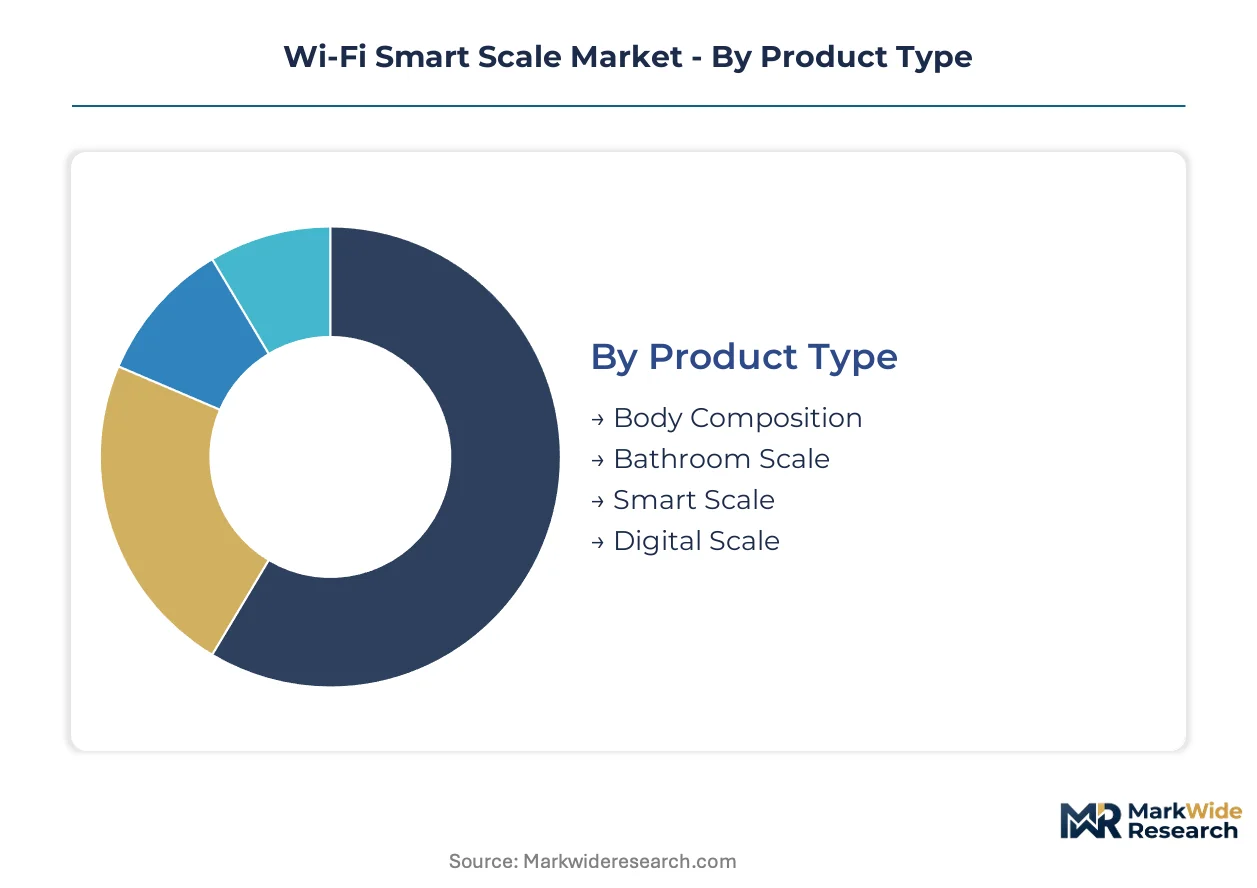
Segmentation in the Wi-Fi smart scale market determines both hardware specifications and recurring revenue potential. Manufacturers configure electrode arrays, connectivity modules, and cloud APIs differently across user profiles and sales channels.
Product Type:
After-sales-service intensity varies sharply by product type, with body-composition units requiring periodic electrode replacement and algorithm recalibration that basic bathroom scales never demand.
- Body Composition:Multi-frequency bioelectrical impedance devices measure intracellular water, muscle mass, and bone density through segmented electrode arrays. Demand concentrates in employer wellness programs across Germany and the Netherlands, where insurance premium incentives reward metabolic trend documentation. Replacement electrode costs and cloud subscription fees sustain manufacturer margins beyond initial hardware sale.
- Smart Scale:Connected devices integrate Wi-Fi or Bluetooth telemetry with proprietary health platforms for longitudinal weight tracking. Athletic-performance segments in North America adopt these fastest, driven by triathletes and marathon runners seeking training-load correlation with body-mass fluctuations.
- Bathroom Scale:Basic weight-measurement units with minimal connectivity features dominate price-sensitive retail channels in India and Southeast Asia.
- Digital Scale:Non-connected electronic weighing devices with LCD displays serve residual demand from consumers avoiding cloud data storage.
Body composition holds the largest share; momentum sits with smart scales.
Technology:
Connectivity technology determines power architecture, bill-of-materials cost, and synchronization reliability across multi-user households.
- Wi-Fi:Continuous cloud connectivity enables automatic data upload without smartphone proximity, supporting seamless multi-user household synchronization. Premium positioning in the United States and United Kingdom leverages this convenience for family health tracking and remote patient monitoring integrations.
- Bluetooth:Low-energy protocols dominate volume production from Shenzhen and Dongguan manufacturing clusters, where component cost compression favors simpler radio modules. Fitness-enthusiast segments accept pairing friction in exchange for extended battery life and lower retail pricing.
- NFC:Tap-to-pair functionality serves clinical environments requiring rapid patient identification without permanent network association.
- LAN:Ethernet-connected scales address enterprise wellness deployments with restricted wireless spectrum policies.
Bluetooth captures the greatest volume; Wi-Fi is climbing the fastest.
User Category:
User category shapes regulatory pathway, clinical-validation requirements, and reimbursement eligibility for connected body-composition monitoring.
- Diabetics:Remote glucose and weight correlation monitoring qualifies for CMS reimbursement codes under chronic disease management protocols in the United States. Endocrinology clinics prescribe FDA-cleared devices with 510(k) clearance for body-fat algorithms, extending sales cycles but opening clinical procurement channels.
- Seniors:Fall-risk assessment and sarcopenia screening drive adoption in Japanese assisted-living facilities and Medicare Advantage plans. Large-button interfaces, voice feedback, and caregiver dashboard access differentiate hardware specifications.
- Fitness Enthusiasts:Athletic-performance segmentation demands multi-frequency impedance analysis and third-party platform integration with Strava, TrainingPeaks, and Apple Health.
- Health-Conscious Consumers:General wellness tracking represents the broadest addressable market, with purchase decisions driven by ecosystem bundling from smartphone and wearable manufacturers.
Health-conscious consumers constitute the largest addressable base; diabetics offer the steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin structure, customer-acquisition cost, and data-ownership terms in employer-sponsored deployment models.
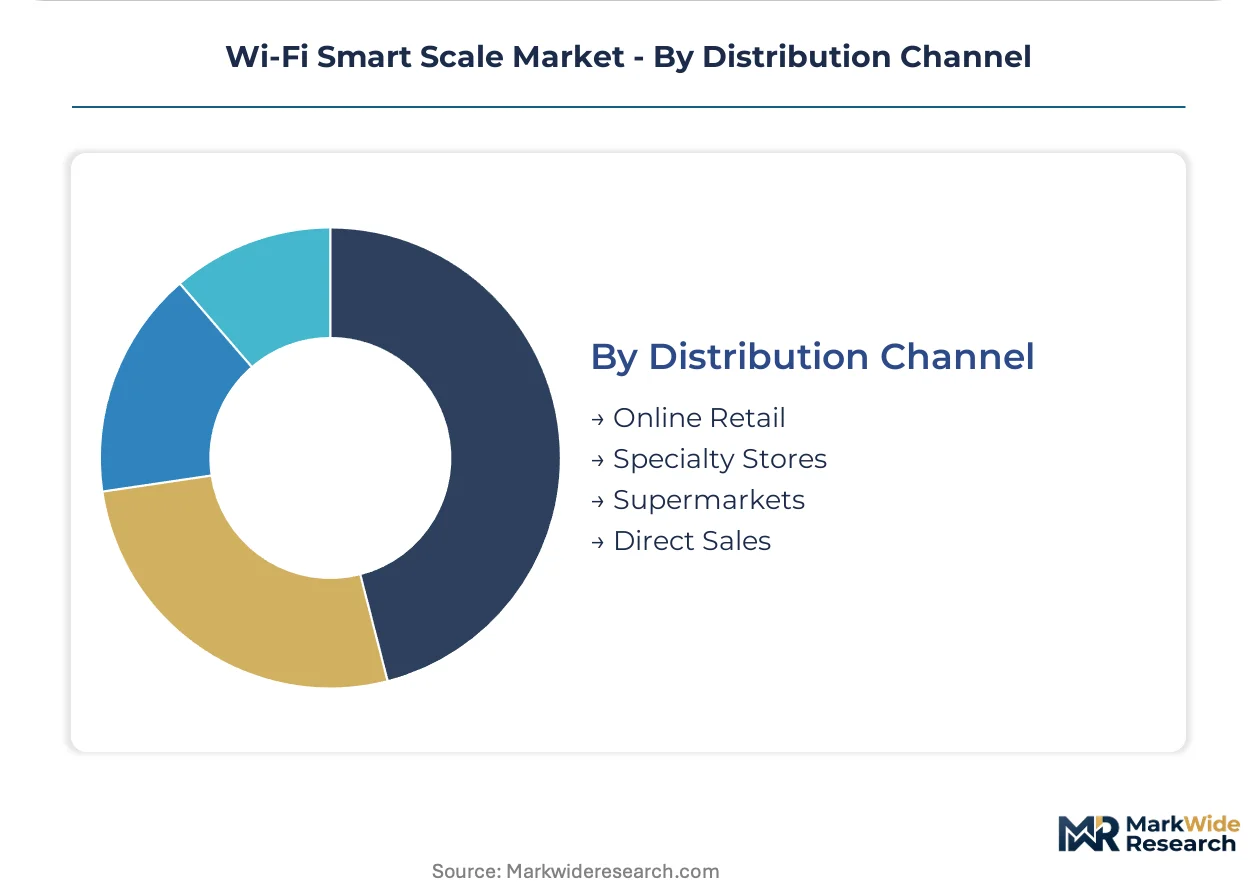
- Direct Sales:Corporate wellness contracts bypass retail margin compression through bulk fleet procurement with centralized device management and API-accessible raw data exports. Fortune 500 human-resources departments in the United States and Germany favor this channel for population-health analytics.
- Online Retail:E-commerce platforms concentrate consumer reviews and comparison shopping, intensifying price transparency and subscription unbundling pressure in the Netherlands and Nordic markets.
- Specialty Stores:Sporting-goods and medical-equipment retailers provide hands-on demonstration and clinical-credibility signaling for premium body-composition devices.
- Supermarkets:Mass-merchandise placement drives impulse purchases of basic digital and Bluetooth scales with minimal feature differentiation.
Online retail commands the highest volume; direct sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Class II medical device clearance requirements shape product architecture for manufacturers targeting the United States, while GDPR-MDR convergence in Europe and SAMR GB standards in China create divergent compliance pathways across major demand centers.
United States
Employer-sponsored wellness programs and Medicare Advantage reimbursement codes drive procurement of FDA-cleared body-composition devices. The FDA 510(k) pathway mandates clinical validation against DEXA reference standards for metrics beyond basic weight. Silicon Valley health-tech clusters and Boston-area medical device corridors concentrate algorithm development and biostatistics talent.
Germany
Insurance premium incentives for metabolic trend documentation accelerate adoption in corporate wellness and direct-to-consumer channels. The EU MDR and GDPR impose parallel clinical-validation and data-governance requirements on connected health devices. Bavarian medical technology clusters around Munich and Erlangen anchor precision sensor manufacturing.
China
Integrated health-ecosystem bundling from domestic smartphone manufacturers compresses hardware margins while driving volume. SAMR enforces GB standards for wireless transmission accuracy and measurement precision in domestic sales. Shenzhen and Dongguan electronics manufacturing clusters dominate PCB and bioelectrical impedance module production.
Japan
Aging demographics and sarcopenia screening protocols in assisted-living facilities sustain demand for senior-optimized interfaces with voice feedback. METI guidelines on health-data interoperability influence platform architecture for domestic market entry. Tokyo-Osaka medical device corridors concentrate distribution partnerships with healthcare providers.
Netherlands
Consumer-protection sentiment and subscription unbundling pressure favor API-accessible raw data exports over proprietary cloud platforms. The EU AI Act risk-classification framework captures algorithmic health recommendations from body-composition coaching outputs. Eindhoven-region health-tech incubators support validation studies against European reference standards.
Wi-Fi Smart Scale Market Competitive Landscape
Ecosystem-integrated consumer electronics conglomerates and medical-grade specialty manufacturers split the market into divergent margin structures. The competitive terrain exhibits tiered concentration, with a handful of platform-anchored players commanding premium positioning while commodity assemblers compete on component cost. Three archetypes dominate: smartphone ecosystem bundlers leveraging cross-device retention, clinical-validation specialists pursuing FDA and MDR certifications, and athletic-performance brands targeting segmented training metrics. Geographic expansion through direct-to-employer distribution and backward integration into sensor manufacturing represent the dominant competitive moves.
Within the ecosystem-bundler tier, Xiaomi exemplifies volume-driven positioning through integrated health-platform pricing. Among medical-grade specialists, Withings occupies a position anchored by French design heritage and European regulatory compliance. Garmin sits within the athletic-performance vector, representing segmentation around triathlete and marathon-runner use cases with advanced body-composition metrics.
| Leading Market Players |
|---|
| Fitbit |
| Withings |
| Xiaomi |
| Garmin |
| RENPHO |
| Tanita |
| iHealth Labs |
| Qardio |
| Beurer |
| Others |
Pricing and Supply Chain Analysis
Tariff exposure on Chinese-assembled PCB modules determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic reconfiguration of final assembly operations. Manufacturers relocating production to Vietnam or Mexico to mitigate duty exposure face wireless certification requalification costs that compress margins in the mid-tier segment while elevating premium positioning for FDA-cleared devices with captive sensor production.
Pricing Analysis
Retail pricing spreads widest between Shenzhen-sourced Bluetooth scales and FDA-cleared Wi-Fi body-composition units sold through U.S. medical channels. Premium-mid-economy pricing differentiation rests on clinical-validation grade and after-sales electrode replacement bundling. Cost compression in the Bluetooth tier is intensifying because Xiaomi ecosystem bundling absorbs hardware margins for platform retention. Employer-sponsored wellness programs exhibit the lowest price sensitivity; Southeast Asian retail channels demonstrate the highest.
Supply Chain Analysis
Export controls on precision analog-to-digital converters from U.S. and Japanese suppliers constrain bioimpedance module architecture for certain manufacturers. Component sourcing centers on China's Pearl River Delta for PCB fabrication, South Korea for MEMS pressure sensors, and Taiwan for wireless connectivity chipsets. Single-source vulnerability sits with medical-grade electrode suppliers qualified for FDA submissions. Distribution runs through direct-to-employer fleet contracts, online retail platforms, and medical-equipment specialty channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as CMS reimbursement codes for remote patient monitoring unlock clinical procurement channels previously closed to consumer wellness brands.
For Market Incumbents: Pre-empt Bluetooth substitution pressure by accelerating Wi-Fi multi-user synchronization patents and securing backward integration into bioimpedance electrode manufacturing. FDA 510(k) clearance timelines favor established players with clinical biostatistics teams already validated against DEXA reference standards.
For New Entrants and Emerging Players: Japanese assisted-living facilities for sarcopenia screening represent the most penetrable white-space target, with voice-feedback interfaces and caregiver dashboards still underdeveloped by existing suppliers. A direct-to-employer distribution angle through BYOD wellness programs bypasses retail margin compression entirely.
For Investors and Strategic Acquirers: EU AI Act risk-classification for algorithmic health recommendations reshapes the acquisition landscape toward targets with documented training-data provenance and bias-mitigation protocols. The long-term viability window favors clinical-validation specialists over commodity assemblers. Watch CMS reimbursement code expansion for chronic disease management as the decisive inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Unlocks clinical procurement channels and Medicare Advantage reimbursement eligibility. |
| CE Marking Pathway | Enables EU MDR compliance for body-composition algorithms under medical-device classification. |
| Hospital System Partnership | Integrates remote patient monitoring with EHR platforms for metabolic trend documentation. |
| Software Companion Development | Separates hardware from analytics revenue amid subscription unbundling pressure in Europe. |
| Reimbursement Strategy | Aligns product claims with CMS codes for chronic disease management coverage. |
Research Methodology
A spread of perspectives from connected health platform engineers, FDA regulatory consultants, corporate wellness procurement directors, and biomedical sensor manufacturers converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation, SAMR GB standard registrations, and hospital GPO contract databases. Bottom-up demand modeling and top-down market sizing triangulated volume and value estimates.
Demand-supply balance dynamics anchored the analytical framework across the analysis window. Segmentation dimensions included connectivity technology, user category, product type, and distribution channel. CAGRs derived from weighted adoption curves across employer wellness, clinical remote monitoring, and consumer fitness segments. Forecast inputs incorporated reimbursement code expansion trajectories and multi-frequency bioimpedance adoption rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by smartphone ecosystem bundlers into clinical-grade certification would shift outcomes. Material shifts in FDA Class II clearance timelines or EU AI Act enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Internet of Things in BFSI Market
Internet of Things (IoT)
M2M Communication Market
Internet of Things (IoT)
Internet of Things in Energy Market
Internet of Things (IoT)
5G IIOT Market
Internet of Things (IoT)
Global Embedded Security for Internet of Things Market
Internet of Things (IoT)
IoT Connected Machines Market
Internet of Things (IoT)
Industrial IoT Platform Market
Internet of Things (IoT)
Satellite IoT Market
Internet of Things (IoT)
North America IoT Node and Gateway Market
Internet of Things (IoT)
IoT in Manufacturing Market
Internet of Things (IoT)
IoT Communication Protocol Market
Internet of Things (IoT)
Middle East and Africa IoT Node and Gateway Market
Internet of Things (IoT)
Solar Based Internet of Things (IoT) Market
Internet of Things (IoT)
IoT for Cold Chain Monitoring Market
Internet of Things (IoT)
IoT in Automotive Market
Internet of Things (IoT)
Smart Sound and Gateway Market