
 North America IoT Device Market | 2026-2036
North America IoT Device Market Size, Share, and Industry Trends Forecast 2026-2036
North America IoT Device Market Insights
Device-as-a-service leasing and subscription-based hardware financing is reshaping competitive entry barriers across the North America IoT Device Market. Cisco Systems leverages its networking infrastructure dominance to bundle connectivity with hardware deployments. Amazon Web Services anchors cloud-integrated edge computing offerings that reduce upfront capital requirements for mid-sized buyers.
A North America IoT Device encompasses networked physical objects embedded with sensors, actuators, and communication modules that transmit data over protocols such as Wi-Fi, Bluetooth, Zigbee, or cellular networks to enable automated monitoring, control, and analytics. These devices typically operate on low-power microcontrollers with memory configurations ranging from kilobytes to megabytes and serve industrial, commercial, and consumer applications requiring real-time data exchange. Industrial Sensors within the Device Type category occupy the deepest margin pools due to stringent reliability requirements and extended replacement cycles. Smart Cities applications command accelerating deployment velocity as municipal budgets shift toward operational technology infrastructure.
The FCC governs spectrum licensing and unlicensed band rules that determine which connectivity protocols IoT devices may legally employ across the United States. Health Canada and the FDA jointly influence Health Monitoring device standards through data privacy and medical accuracy requirements that shape product design cycles. Industry participants must monitor evolving cybersecurity certification mandates from NIST and sector-specific bodies to maintain market access.
Market Dynamics
FCC spectrum reallocation for unlicensed bands is compressing connectivity costs and redrawing competitive boundaries across device categories. The shift from licensed cellular toward Wi-Fi 6E and LoRaWAN is virtualizing network infrastructure investment requirements for mid-market buyers.
Growth Catalysts
- Healthcare RPM mandates:CMS reimbursement codes for remote patient monitoring are accelerating hospital system deployments of connected diagnostic peripherals.
- Smart grid modernization:FERC Order 2222 enables distributed energy resource aggregation, pulling industrial sensors and smart meters into utility procurement cycles.
- CBRS private networks:FCC mid-band spectrum access is allowing manufacturing facilities to deploy campus-wide IoT without carrier dependency.
Market Restraints
- Semiconductor supply concentration:Advanced microcontroller fabrication concentrates in Taiwan and South Korea, exposing North American device OEMs to single-source risk.
- Battery chemistry constraints:Lithium-thionyl chloride cell shortages limit ultra-low-power sensor deployment timelines for environmental monitoring applications.
- NIST cybersecurity certification friction:Mandatory compliance timelines for IoT device labeling create product launch delays and engineering cost overruns.
Strategic Opportunities
- Canadian smart city underpenetration:Municipal infrastructure budgets in Toronto, Vancouver, and Montreal lag US deployment intensity by 3-5 years, creating first-mover windows.
- Edge-AI convergence:On-device inference chips paired with 5G mmWave modules enable real-time predictive maintenance without cloud round-trips.
- Device-as-a-service channel innovation:Hardware leasing through systems integrators replaces capital purchase models for mid-sized manufacturing buyers.
Industry Challenges
- Embedded firmware talent scarcity:Shortage of engineers proficient in real-time operating systems and hardware security modules delays product development cycles.
- Multi-protocol integration complexity:Enterprise deployments require seamless handoff between Zigbee, Thread, and cellular networks, straining systems integration capabilities.
- UL certification timeline compression:Accelerated product release schedules conflict with 12-18 week safety testing windows for industrial-rated devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America IoT Device Market |
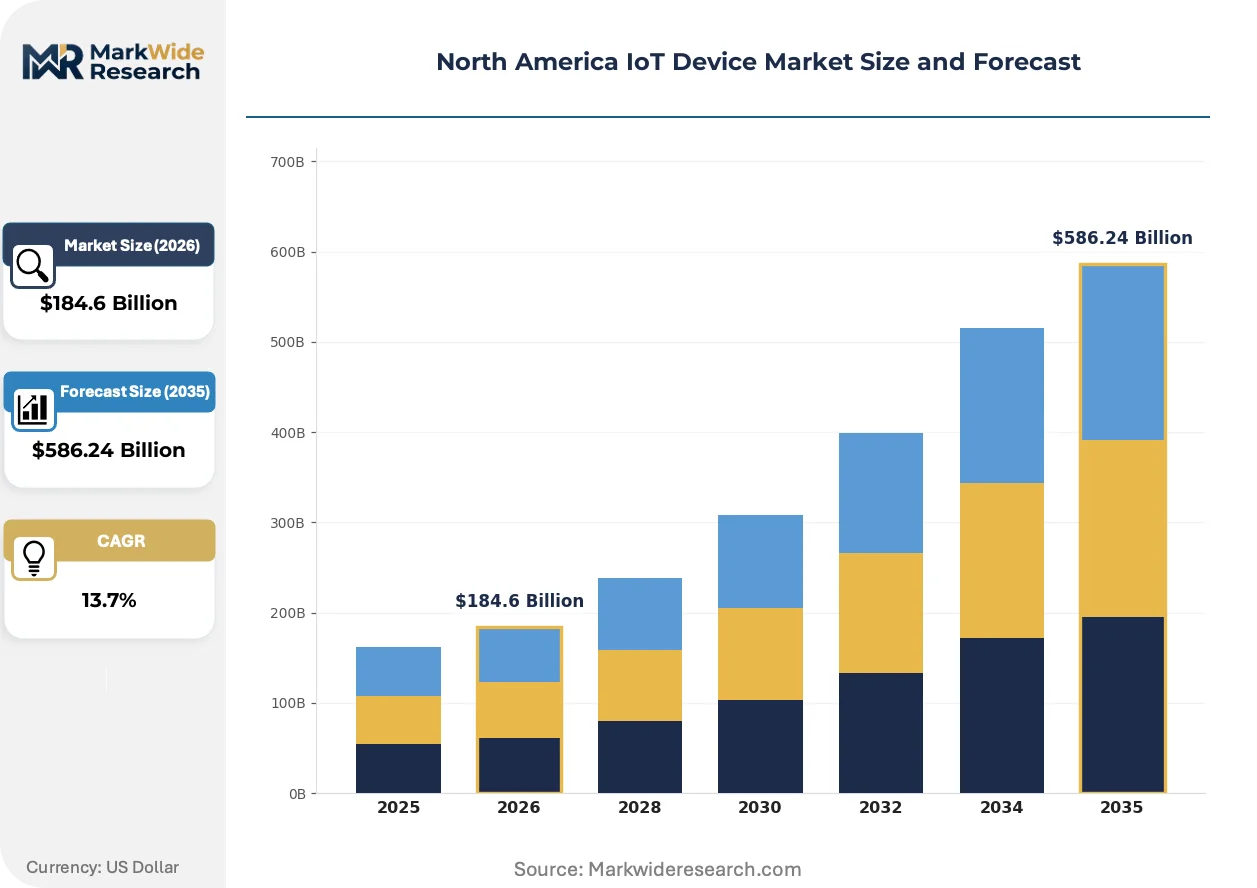
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $586.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smart Home, Wearable Technology, Industrial Sensors, Health Monitoring Application: Smart Cities, Healthcare, Agriculture, Automotive Connectivity: Wi-Fi, Bluetooth, Zigbee, Cellular End User: Consumer Electronics, Industrial Automation, Healthcare Providers, Retailers |
| Companies Covered | Cisco Systems, Intel Corporation, Microsoft Corporation, Amazon Web Services, Honeywell International, Qualcomm Incorporated, IBM Corporation, General Electric, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America IoT Device Market Trends and Innovations
Software-defined radio architectures and AI-at-the-edge chipsets are collapsing traditional hardware boundaries between connectivity standards. Device manufacturers are reconfiguring product roadmaps around programmable rather than fixed-function silicon.
Software-defined radio transceivers are replacing discrete cellular, Wi-Fi, and Bluetooth modules with reconfigurable RF front-ends. Automotive telematics suppliers and agricultural equipment OEMs are adopting these platforms to reduce SKU complexity across regional variants. The technology is virtualizing hardware differentiation, compressing margins for single-protocol specialists while expanding addressable markets for programmable platform vendors.
NIST's Cybersecurity for IoT Program is mandating software bill of materials disclosure and vulnerability disclosure timelines for federal procurement eligibility. Device OEMs must restructure firmware development workflows and third-party component vetting processes. Industrial control and healthcare monitoring categories face the steepest compliance cost escalation, with manufacturers absorbing engineering overhead or exiting federal contract channels.
Subscription-based hardware financing is displacing outright purchase models among mid-sized manufacturing and commercial real estate buyers. Systems integrators and telecom carriers are capturing device margin through bundled connectivity-service contracts. The shift is most visible in US industrial automation and Canadian building management verticals, where capex constraints favor operational expenditure treatment for sensor networks.
North America IoT Device Market Segmentation
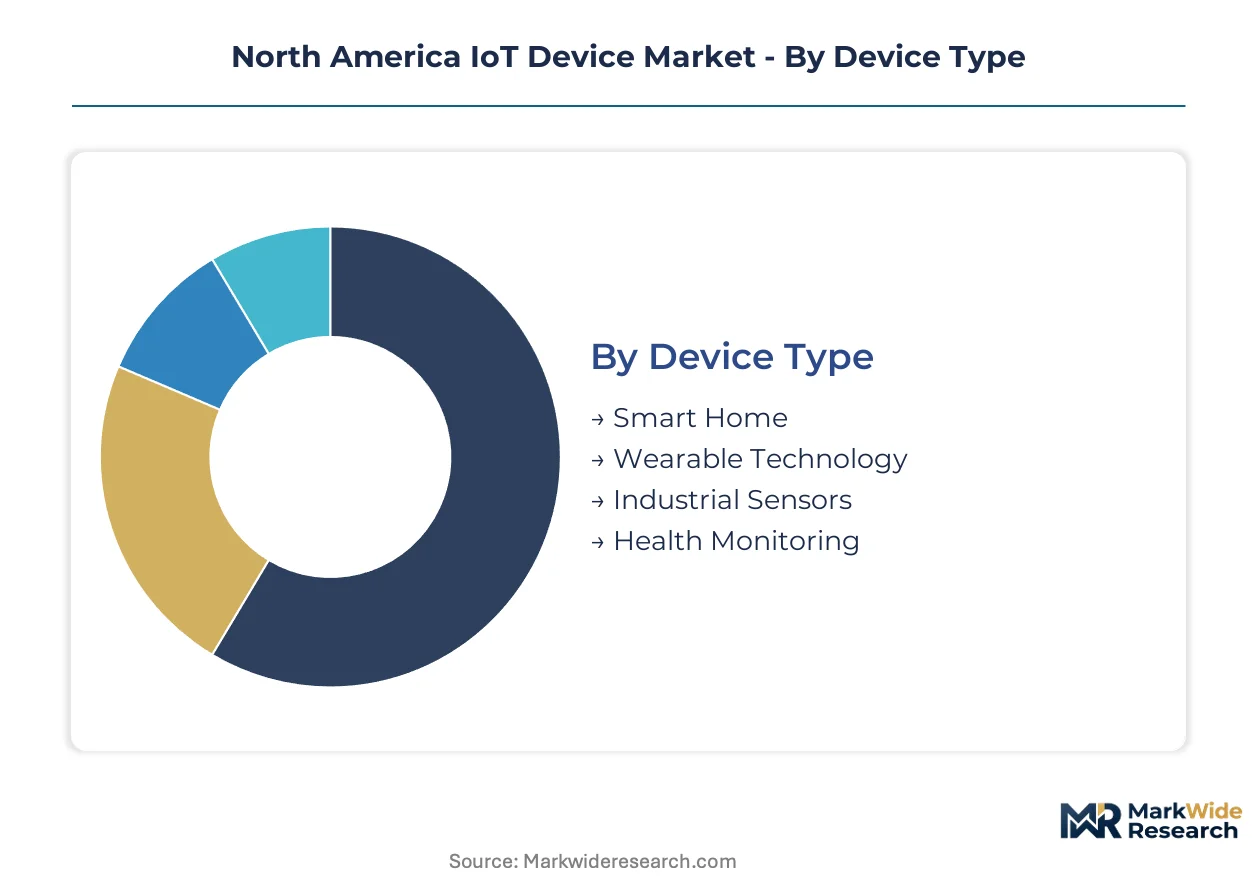
Segmentation reveals divergent replacement cycles across the North America IoT Device Market. Hardware refresh timelines stretch from months for consumer wearables to decades for embedded industrial infrastructure, reshaping vendor revenue predictability and service attachment strategies.
Device Type:
Replacement velocity varies dramatically: consumer-facing hardware turns over fastest while industrial installations persist longest.
- Industrial Sensors:Ruggedized units with IP67+ sealing and extended temperature tolerance operate 10-15 years in manufacturing environments. Demand clusters in Texas and Ohio petrochemical corridors where OSHA process safety mandates drive continuous emissions monitoring deployments.
- Health Monitoring:FDA-cleared diagnostic peripherals with biometric validation layers command premium positioning. Hospital systems in California and New York are expanding remote patient monitoring fleets under CMS reimbursement expansion.
- Smart Home:Voice-activated hubs and connected appliances refresh every 3-5 years as interoperability standards evolve.
- Wearable Technology:Fitness bands and smartwatches face 18-24 month consumer replacement cycles driven by fashion and battery degradation.
Industrial Sensors dominate installed base. Health Monitoring is where expansion concentrates.
Application:
Margin profiles stratify sharply across use cases, with regulated verticals capturing value through compliance barriers.
- Healthcare:Connected diagnostic and therapeutic devices face FDA 510(k) clearance requirements that extend development timelines. Mayo Clinic and Cleveland Clinic networks are standardizing on interoperable platforms for remote chronic disease management.
- Smart Cities:Municipal procurement cycles favor operational technology vendors with proven cybersecurity frameworks. Toronto and Vancouver lag US deployment intensity, creating first-mover windows for integrated sensor-software providers.
- Automotive:Connected vehicle telematics modules integrate with NHTSA safety systems and insurance data exchange protocols.
- Agriculture:Precision farming sensors in California Central Valley and Iowa corn belts optimize irrigation and nutrient application through soil moisture telemetry.
Healthcare captures the steepest margin premiums. Smart Cities are climbing the fastest.
Connectivity:
Protocol selection determines power budget, range, and carrier dependency, with trade-offs hardening at scale.
- Cellular:Licensed spectrum modules with SIM-based authentication enable nationwide mobility without infrastructure ownership. Manufacturing facilities in Michigan and South Carolina deploy CBRS private networks to bypass carrier dependency.
- Wi-Fi:Wi-Fi 6E expansion in the 6 GHz band is reducing congestion for high-density sensor deployments in commercial real estate.
- Zigbee:Mesh networking protocol dominates smart home ecosystems through Thread interoperability and low-power sleep modes.
- Bluetooth:Short-range personal area networking persists in wearable-to-phone pairing and indoor positioning beacons.
Wi-Fi anchors consumer volume. Cellular is gaining share fastest in industrial migration.
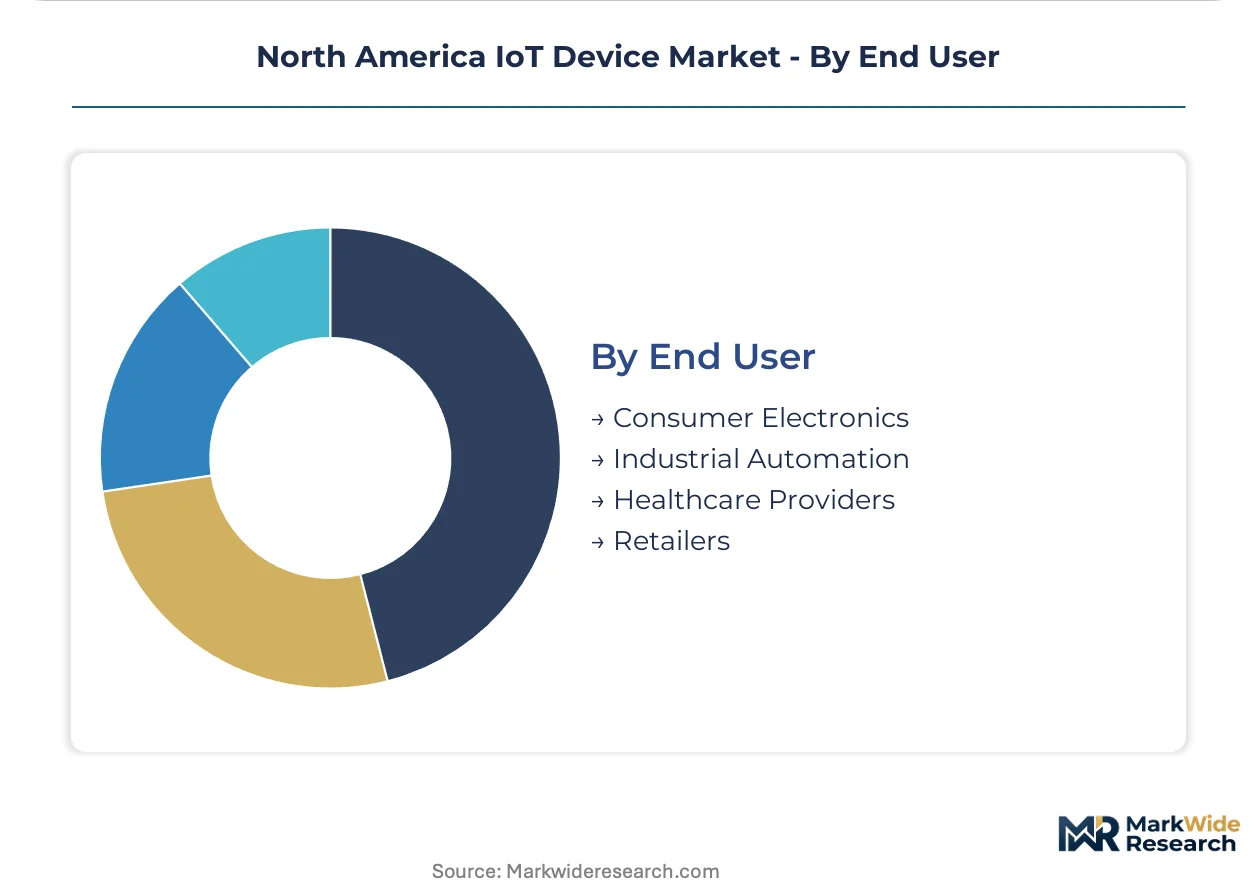
End User:
Procurement sophistication separates enterprise buyers with systems integration capabilities from consumer self-service channels.
- Healthcare Providers:Hospital networks and physician practice groups require HIPAA-compliant data architectures with business associate agreement frameworks. Kaiser Permanente and Intermountain Healthcare are consolidating vendor relationships around platform players.
- Industrial Automation:Discrete and process manufacturers demand OPC-UA interoperability and NIST cybersecurity certification. Automotive OEMs in Tennessee and battery producers in Nevada drive sensor network standardization.
- Consumer Electronics:Retail channels and direct-to-consumer brands compete on price and ecosystem lock-in.
- Retailers:Inventory tracking and cold chain monitoring applications leverage RFID and environmental sensors for loss prevention.
Industrial Automation dominates capital deployment. Healthcare Providers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North America runs a structural deficit in IoT device manufacturing, importing the majority of advanced microcontrollers and RF modules from Asian foundries while exporting specialized industrial sensors and healthcare diagnostics. This trade imbalance concentrates value capture in design, software, and systems integration rather than fabrication.
United States
Hospital networks in California and New York are scaling remote patient monitoring fleets under expanded CMS reimbursement codes. The FCC governs spectrum allocation for unlicensed bands that determine connectivity economics for device deployments. Manufacturing corridors in Michigan and South Carolina leverage CBRS private networks to bypass carrier dependency for campus-wide sensor networks.
Canada
Municipal infrastructure budgets in Toronto, Vancouver, and Montreal lag US smart city deployment intensity by three to five years. Health Canada and the FDA jointly influence health monitoring device standards through data privacy and medical accuracy requirements. Ontario and Quebec host emerging clusters of industrial automation integrators serving cross-border automotive supply chains.
Mexico
Maquiladora facilities in Baja California and Chihuahua assemble connected automotive components for export to US OEMs. Mexican telecommunications regulators align equipment certification with FCC frameworks to streamline cross-border product flows. Guadalajara's electronics manufacturing corridor specializes in consumer IoT device assembly and firmware localization.
North America IoT Device Market Competitive Landscape
On the supply side, the industry is consolidating around platform players with integrated hardware-software-cloud stacks. Tier-one technology conglomerates and specialized industrial automation vendors divide the competitive landscape. Two strategic archetypes dominate: networking infrastructure incumbents bundling connectivity with hardware deployments, and cloud hyperscalers anchoring edge-computing offerings that reduce upfront capital requirements. Competitive moves center on strategic partnerships between device OEMs and systems integrators, plus portfolio diversification into subscription-based hardware financing models.
Within the networking infrastructure tier, Cisco Systems exemplifies the bundled connectivity-hardware archetype through its dominance in enterprise routing and switching equipment. Amazon Web Services occupies a position representing cloud-integrated edge computing, while Intel Corporation anchors the semiconductor layer supplying microcontrollers and connectivity chipsets to downstream device manufacturers.
| Leading Market Players |
|---|
| Cisco Systems |
| Intel Corporation |
| Microsoft Corporation |
| Amazon Web Services |
| Honeywell International |
| Qualcomm Incorporated |
| IBM Corporation |
| General Electric |
| Siemens AG |
| Others |
Pricing and Supply Chain Analysis
Taiwanese foundry concentration for advanced microcontrollers and RF modules concentrates margin capture in semiconductor packaging and systems integration tiers rather than device assembly. North American OEMs face asymmetric pricing power where upstream scarcity in 5nm and 7nm fabrication nodes transmits directly to downstream hardware costs, compressing assembly margins while expanding design and firmware service premiums.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels that stratifies by UL certification grade and NIST cybersecurity compliance tier. Price differentiation hinges on IP67 sealing ratings and FCC Part 15 pre-certification status, with premium tiers commanding substantial markups for medical-grade FDA 510(k) clearance. Cost compression in the standard tier is intensifying because Taiwanese foundry allocation prioritizes automotive and smartphone volumes over industrial IoT batches. Healthcare providers exhibit the lowest price sensitivity due to CMS reimbursement coverage, while mid-sized manufacturing buyers face acute capital constraints favoring operational expenditure treatment.
Supply Chain Analysis
Silicon wafer feedstock draws from Taiwan, South Korea, and the United States for advanced microcontroller fabrication, with lithium-thionyl chloride battery cells sourcing primarily from China and Japan. Raw material dependencies center on 300mm silicon wafers, gallium arsenide RF substrates, and cobalt-free cathode formulations for extended-life sensor deployments. Single-source vulnerability concentrates in TSMC's Arizona fab ramp delays and Samsung's Pyeongtaek memory complex, exposing North American device OEMs to allocation rationing during demand spikes. Distribution runs through tier-one electronics distributors with regional stocking facilities in Texas and California, supplemented by direct fulfillment from systems integrators for enterprise-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America IoT Device Market is emerging from a cyclical trough as FCC spectrum reallocation and CMS reimbursement expansion reset demand baselines. Semiconductor supply normalization and private network infrastructure buildouts provide the cyclical justification for strategic repositioning.
For Market Incumbents: Harden firmware development workflows against NIST Cybersecurity for IoT Program compliance deadlines by embedding software bill of materials automation and vulnerability disclosure pipelines into CI/CD architectures. Consolidate channel control through exclusive systems integrator partnerships in Canadian smart city verticals where municipal procurement sophistication lags US benchmarks by three to five years. Vertical integration into edge-AI inference chip design represents a critical defensive lever against cloud hyperscaler encroachment on device margin pools. For New Entrants and Emerging Players: Build out device-as-a-service financing capabilities targeting mid-sized manufacturing buyers in Michigan and South Carolina industrial corridors where capex constraints favor operational expenditure treatment. Canadian municipal infrastructure budgets in Toronto and Vancouver offer the most penetrable geography, with first-mover windows for integrated sensor-software providers. A channel-led go-to-market angle through telecom carriers bundling connectivity-service contracts captures recurring revenue streams while bypassing direct hardware margin competition. For Investors and Strategic Acquirers: Capital is best deployed toward programmable platform vendors with software-defined radio architectures that virtualize hardware differentiation across multiple connectivity protocols. Long-term viability over a five-to-ten year window favors vendors with demonstrated federal procurement eligibility and established UL certification track records. The signal to watch is CBRS private network deployment velocity in manufacturing facilities, which indicates enterprise buyer willingness to bypass carrier dependency and invest in campus-wide sensor infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Platform Development | Reconfigurable RF front-ends collapse SKU complexity for automotive telematics and agricultural OEMs. |
| NIST Cybersecurity Certification Investment | Federal procurement eligibility requires software bill of materials disclosure and structured vulnerability timelines. |
| Device-as-a-Service Channel Partnership | Systems integrators capture hardware margin through bundled connectivity-service contracts with mid-market buyers. |
| CBRS Private Network Deployment | FCC mid-band spectrum access enables manufacturing facilities to bypass carrier dependency for campus coverage. |
| Edge-AI Inference Chip Integration | On-device processing paired with 5G mmWave modules enables real-time predictive maintenance without cloud latency. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with IoT platform architects, hospital biomedical engineers, industrial automation procurement leads, and FCC regulatory affairs specialists. Secondary validation drew from SEC 10-K filings of semiconductor and networking equipment vendors, FCC equipment authorization databases, CMS Medicare reimbursement bulletins, and GPO hospital procurement contracts. Bottom-up unit shipment estimates across device categories were triangulated against top-down addressable market sizing derived from industrial automation capex disclosures and smart city municipal budget allocations.
Calibration against historical replacement cycles and connectivity protocol migration patterns shaped the analytical framework across the analysis window. Segmentation dimensions modeled include device type ruggedization tier, application vertical regulatory intensity, connectivity protocol power budget, and end-user procurement sophistication. CAGRs were derived from regression analysis of semiconductor content per device trends and cloud infrastructure capex elasticity. Industry-specific forecast inputs incorporated FCC spectrum auction timelines and Health Canada equipment certification harmonization progress.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud hyperscalers into edge hardware or Chinese module vendors into North American distribution channels would shift outcomes substantially. Quarterly review of foundry allocation announcements, CMS reimbursement code expansions, and municipal RFP issuance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT in BFSI Market
Internet of Things (IoT)
Europe IoT Device Market
Internet of Things (IoT)
Smart Remote Market
Internet of Things (IoT)
North America and Europe IoT Gateway Market
Internet of Things (IoT)
Europe Industrial IoT Market
Internet of Things (IoT)
Europe Massive IoT Market
Internet of Things (IoT)
Global Pervasive Computing Technology Market
Internet of Things (IoT)
Aviation IoT Solutions Market
Internet of Things (IoT)
Lora and Lorawan IoT Connectivity Market
Internet of Things (IoT)
Internet of Things (IoT) Connected Cars Market
Internet of Things (IoT)
Internet of Things (IoT) in Healthcare Market
Internet of Things (IoT)
Location of Things Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
IoT Smart Poles Market
Internet of Things (IoT)
Healthcare M2M Market
Internet of Things (IoT)
UK IoT Software Market