
 Global Equipment Monitoring Market | 2026-2036
Global Equipment Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Equipment Monitoring Market Analysis
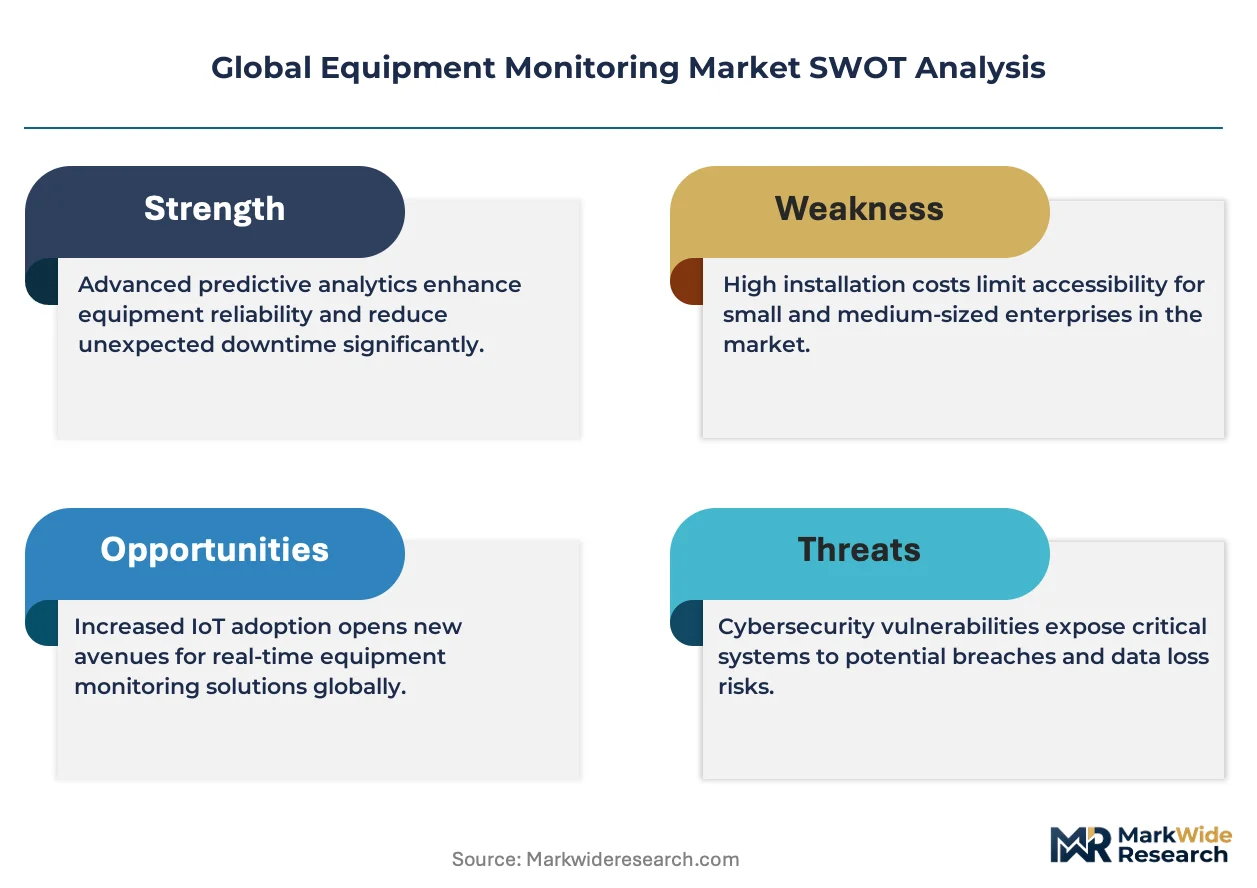
ISO 17359 condition monitoring certification is bifurcating the vendor landscape into qualified system integrators and unverified software providers. Emerson Electric Co. leverages its Plantweb digital ecosystem to anchor large-scale petrochemical deployments. SKF AB specializes in vibration-to-cloud analytics for rotating machinery, competing primarily on sensor hardware reliability.
Equipment monitoring encompasses sensor networks, edge computing gateways, and analytics platforms that collect real-time operational data from industrial assets to detect degradation before functional failure. Systems typically sample vibration at 10–20 kHz, process thermal signatures at 0.05°C resolution, and stream diagnostics through IoT protocols to centralized dashboards. Cloud-based deployment is capturing the fastest expansion as manufacturers abandon capital-intensive on-premises server farms for subscription analytics. Vibration analysis retains the largest installed base but faces margin compression from commoditized MEMS accelerators.
FDA 21 CFR Part 11 shapes validation requirements for pharmaceutical equipment monitoring, while EU MDR imposes traceability mandates on medical device manufacturers using predictive maintenance. OSHA machine guarding standards in the US and Japan METI's smart factory directives further tighten compliance scope. Stakeholders must weigh certification costs against the risk of exclusion from regulated procurement channels.
Market Dynamics
Cloud-based predictive analytics is compressing capital deployment cycles as manufacturers abandon on-premises server infrastructure for subscription diagnostics, forcing incumbents to restructure pricing architectures around recurring revenue streams rather than perpetual licenses.
Growth Catalysts
- EU Green Deal industrial emissions mandates:Asset-intensive sectors in Germany and France face binding continuous monitoring requirements for carbon-intensive equipment, accelerating retrofit programs across chemical and steel production facilities.
- MEMS accelerometer cost curves:Semiconductor foundries in Taiwan and South Korea have driven vibration sensor unit economics below $15, democratizing condition monitoring for mid-sized manufacturing operations previously priced out of piezoelectric systems.
- Automotive electrification:Battery gigafactories in Hungary and Poland require thermal runaway detection systems with 0.05°C resolution, creating dedicated demand for multi-parameter monitoring platforms.
Market Restraints
- Edge computing hardware concentration:GPU and FPGA supply for real-time signal processing concentrates among three Taiwanese semiconductor packaging houses, exposing deployment timelines to foundry allocation volatility.
- ISO 17359 certification friction:The 18-24 month auditor qualification timeline for system integrators creates a bottleneck for vendor market entry, particularly affecting software-only providers without hardware calibration capabilities.
- Cloud data egress cost structures:Continuous 10-20 kHz vibration streaming generates petabyte-scale transfer volumes, with hyperscaler bandwidth pricing eroding subscription margins for multi-site deployments.
Strategic Opportunities
- India PLI scheme manufacturing corridors:The country's production-linked incentive program for advanced cell chemistry and specialty steel creates greenfield monitoring demand without legacy infrastructure replacement costs.
- FDA 21 CFR Part 11 validation services:Pharmaceutical equipment monitoring in the US requires electronic record integrity frameworks, opening specialized consulting and software qualification revenue streams.
- Digital twin convergence with physics-based modeling:Coupling real-time sensor feeds with finite element analysis enables remaining useful life prediction for critical rotating machinery, commanding premium pricing in petrochemical maintenance contracts.
Industry Challenges
- Vibration analyst certification scarcity:ISO 18436-2 Category III and IV credentials require 36+ months of supervised field experience, with examination pass rates below 40% constraining deployment velocity for complex turbomachinery.
- Legacy PLC integration complexity:Brownfield manufacturing sites running 1990s-era control architectures lack native IoT protocol support, necessitating costly gateway retrofits and protocol translation middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Equipment Monitoring Market |
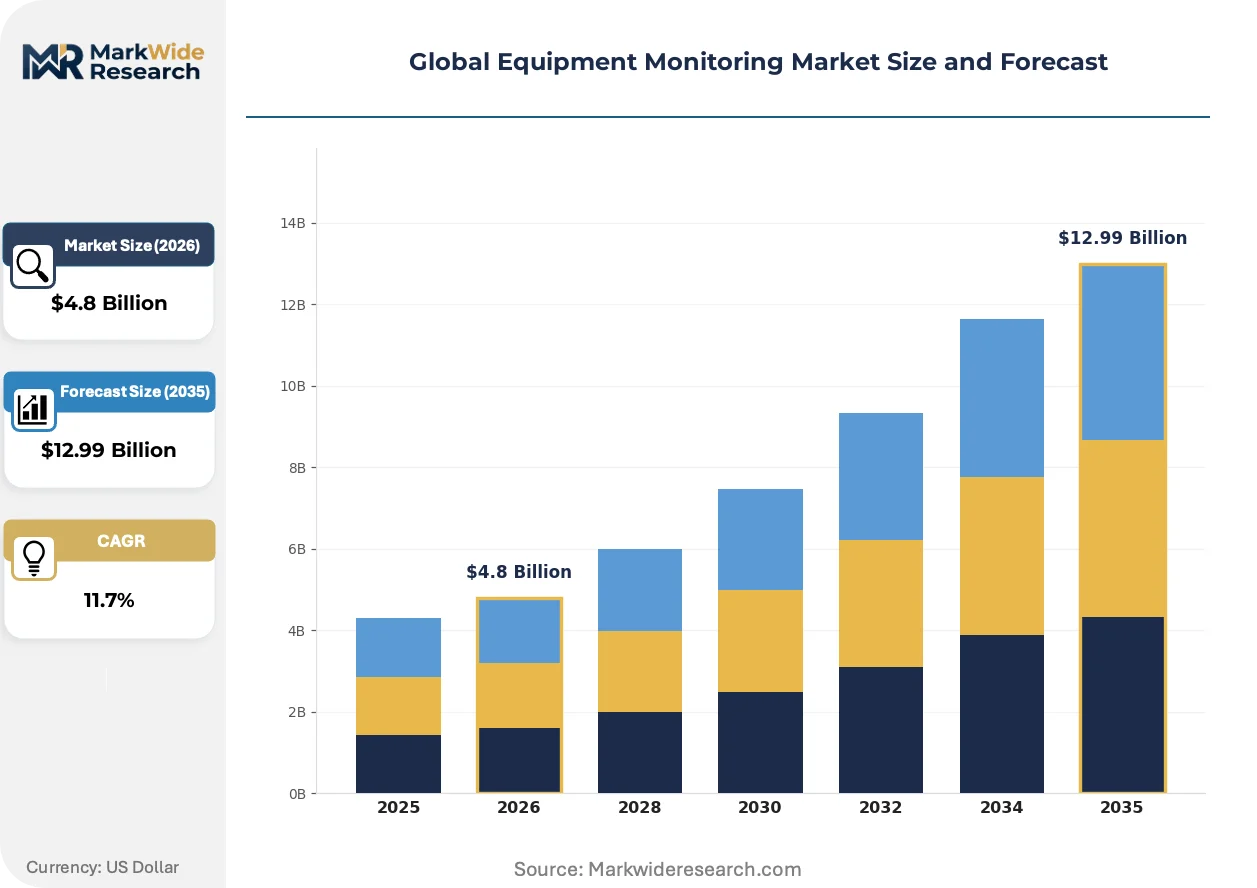
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, Vibration Analysis, Thermal Imaging, Ultrasonic Testing Application: Predictive Maintenance, Condition Monitoring, Asset Optimization, Performance Monitoring End User: Manufacturing, Oil & Gas, Transportation, Power Generation Deployment: On-premises, Cloud-based, Hybrid, Managed Services |
| Companies Covered | Emerson Electric Co., General Electric Co., Honeywell International Inc., SKF AB, National Instruments Corp., Parker Hannifin Corp., Rockwell Automation Inc., Siemens, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Equipment Monitoring Market Emerging Trajectories
Wireless mesh networking protocols are eliminating cable installation costs in hazardous environments, while edge AI inference chips enable localized anomaly detection without cloud dependency. These shifts are redistributing value capture from centralized software platforms toward distributed hardware intelligence.
Time-synchronized mesh networking based on IEEE 802.15.4e is displacing wired accelerometer installations in rotating machinery applications. Petrochemical operators in the US Gulf Coast and Rotterdam port complexes are adopting battery-powered vibration nodes at 40% faster deployment velocity than cabled alternatives. This wireless architecture is displacing traditional system integrator revenue models built around conduit routing and junction box engineering.
EU AI Act high-risk system classifications are mandating explainability requirements for predictive maintenance algorithms deployed in energy and transport infrastructure. Equipment monitoring vendors must now document feature importance weights and decision thresholds for regulatory inspection. German automotive suppliers and French nuclear maintenance providers are restructuring model development workflows to incorporate SHAP value logging and audit trail generation from initial training data.
Asset-as-a-service contracting is compressing equipment ownership cycles and bundling monitoring subscriptions into lease rate calculations. Compressor and pump OEMs in Italy and Japan are unbundling hardware sales from performance guarantees, transferring operational risk to manufacturers who internalize predictive maintenance costs. This model concentrates procurement authority among fleet managers rather than plant engineering departments, altering vendor sales channel structures and technical support requirements.
Global Equipment Monitoring Market Segmentation
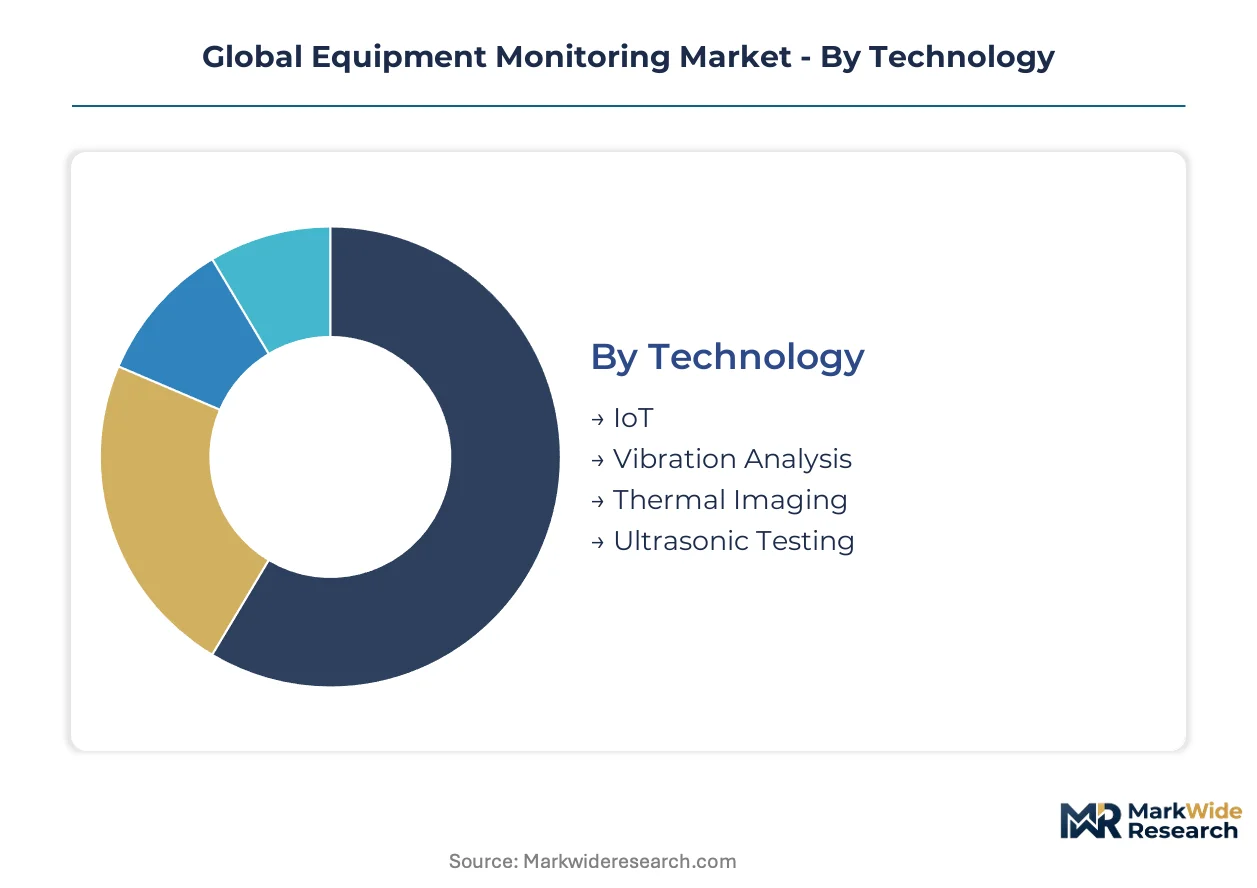
Equipment monitoring vendors structure portfolios around distinct technical architectures and operational contexts. Segment boundaries determine pricing models, certification requirements, and sales channel selection across industrial verticals.
Technology:
IoT and vibration analysis segments serve predominantly domestic manufacturing bases, while thermal imaging and ultrasonic testing equipment flows through export channels to emerging industrial corridors.
- IoT:Sensor networks with edge gateways stream operational data through MQTT and OPC-UA protocols. German automotive suppliers and Hungarian battery manufacturers anchor demand for multi-parameter connected platforms requiring continuous 10–20 kHz sampling.
- Vibration Analysis:Piezoelectric and MEMS accelerometers detect bearing degradation and shaft misalignment in rotating machinery. Taiwan semiconductor foundries have compressed MEMS unit economics below $15, democratizing access for mid-sized French and Italian metalworking operations.
- Thermal Imaging:Infrared cameras with 0.05°C resolution identify electrical hot spots and insulation failures.
- Ultrasonic Testing:High-frequency acoustic emission detects crack propagation and corrosion under insulation.
Vibration analysis commands the established base. The steepest expansion runs through IoT-enabled multi-sensor platforms.
Application:
Cost tiering separates premium predictive analytics suites from standardized condition monitoring dashboards, with asset optimization occupying the mid-market intersection.
- Predictive Maintenance:Machine learning algorithms forecast remaining useful life from degradation patterns. US petrochemical operators and German chemical producers purchase these capabilities through subscription models, abandoning perpetual licenses for recurring revenue arrangements.
- Condition Monitoring:Real-time threshold alerting prevents catastrophic failure without prognostic capabilities. Japanese automotive suppliers and South Korean steel mills deploy these systems for regulatory compliance with ISO 17359 certification requirements.
- Asset Optimization:Performance tuning extends equipment lifetime and reduces energy consumption.
- Performance Monitoring:Operational efficiency tracking aligns output metrics with production targets.
Condition monitoring retains the largest installed footprint. Predictive maintenance is climbing the fastest as cloud analytics compress deployment cycles.
End User:
Volume concentration varies sharply: manufacturing and power generation drive unit scale, while oil and gas commands premium pricing per installation.
- Manufacturing:Discrete and process industries deploy sensor networks across machining centers, conveyors, and packaging lines. Polish and Czech automotive component suppliers lead greenfield installations without legacy PLC integration burdens.
- Oil & Gas:Explosive atmosphere certifications and SIL-rated safety systems dominate procurement criteria. US Gulf Coast refineries and Rotterdam port complexes specify wireless mesh nodes for hazardous area vibration monitoring.
- Transportation:Fleet-wide equipment tracking spans rail rolling stock and maritime propulsion systems.
- Power Generation:Turbine and generator monitoring ensures grid stability and renewable asset uptime.
Manufacturing generates the highest unit volumes. Oil and gas delivers the steepest margin expansion through specialized hazardous environment certifications.
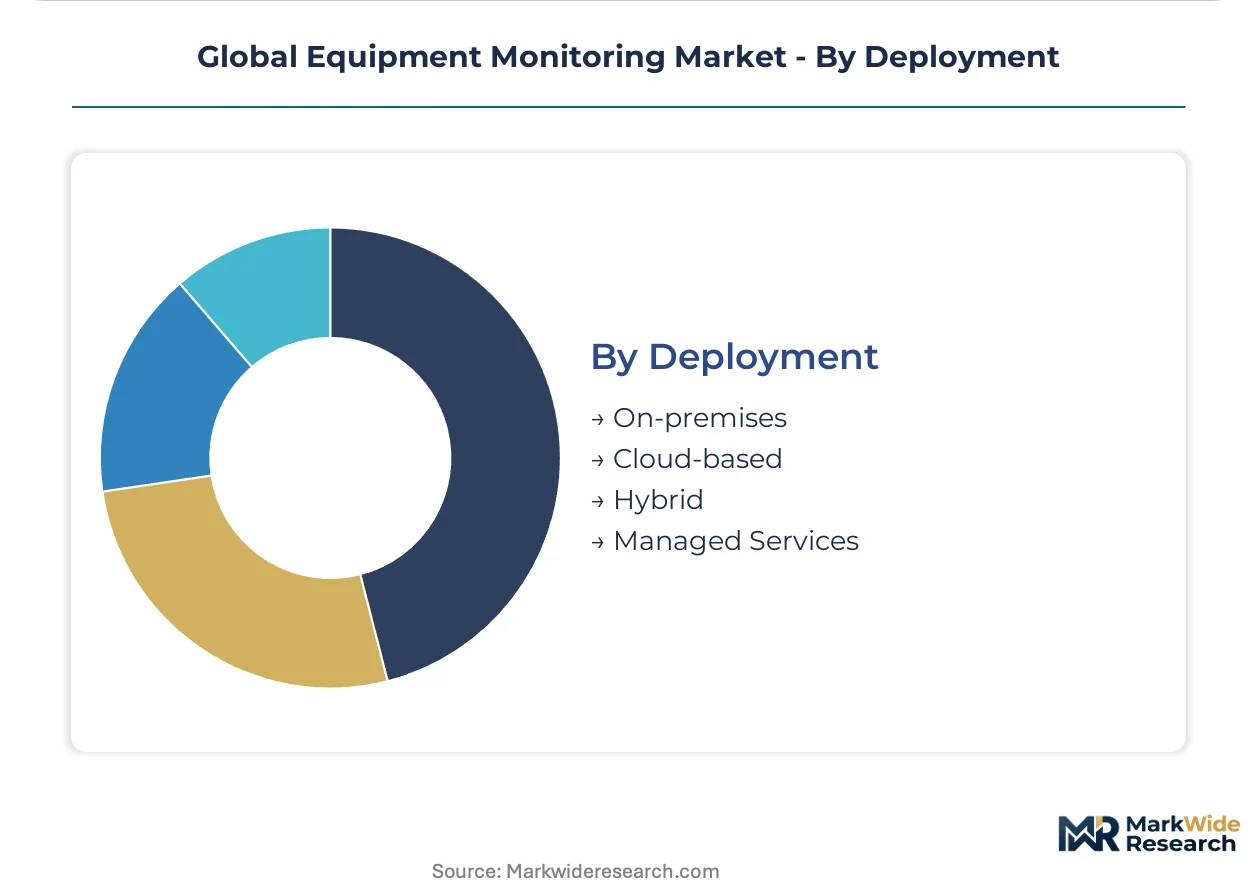
Deployment:
Customer type stratification separates capital-constrained mid-market manufacturers from enterprise accounts with dedicated IT infrastructure teams.
- On-premises:Local server farms process sensitive operational data behind facility firewalls. Japanese and German defense-adjacent suppliers mandate this architecture for cyber-physical security compliance with national industrial directives.
- Cloud-based:Hyperscaler-hosted analytics eliminate capital expenditure and enable multi-site visibility. Indian PLI scheme manufacturing corridors adopt this model exclusively, bypassing legacy infrastructure investment.
- Hybrid:Edge preprocessing with cloud aggregation balances latency and scalability requirements.
- Managed Services:Outsourced monitoring operations transfer analyst staffing burdens to vendors.
On-premises retains regulatory-mandated niches. Cloud-based deployment is gaining share fastest as subscription economics displace perpetual licensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's EU Green Deal implementation and India's PLI scheme for advanced manufacturing anchor regional demand concentration, with automotive electrification and industrial emissions mandates reshaping procurement patterns across asset-intensive sectors.
Germany
Automotive and chemical producers drive retrofit programs for continuous emissions monitoring under EU Green Deal binding requirements. German automotive suppliers in Bavaria and Baden-Württemberg deploy multi-parameter IoT platforms with 0.05°C thermal resolution for battery gigafactory quality assurance.
United States
OSHA machine guarding standards and FDA 21 CFR Part 11 validation requirements shape pharmaceutical and petrochemical monitoring procurement. US Gulf Coast refineries specify wireless mesh vibration nodes for hazardous area deployment, compressing installation timelines versus cabled alternatives.
India
The PLI scheme for advanced cell chemistry and specialty steel creates greenfield monitoring demand without legacy PLC integration burdens. Manufacturing corridors in Gujarat and Tamil Nadu adopt cloud-based deployment exclusively, bypassing capital-intensive on-premises infrastructure investment.
Japan
METI smart factory directives tighten compliance scope for discrete manufacturers. Japanese automotive suppliers deploy ISO 17359-certified condition monitoring systems for regulatory adherence, with Kanto region machining centers leading vibration-to-cloud analytics adoption.
Poland
Battery gigafactories in Lower Silesia and Greater Poland require thermal runaway detection systems, generating dedicated demand for multi-parameter monitoring platforms. Polish automotive component suppliers execute greenfield installations without brownfield gateway retrofit complexity.
Global Equipment Monitoring Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with captive sensor hardware capabilities, creating tiered competition between full-stack platform providers and specialized analytics software vendors. Market structure concentrates around three strategic archetypes: integrated automation conglomerates with digital ecosystems, bearing specialists with vibration hardware heritage, and pure-play analytics vendors with cloud-native architectures. Dominant competitive moves include portfolio diversification through edge AI chip integration and geographic expansion into India PLI scheme manufacturing corridors.
Within the integrated automation tier, Emerson Electric Co. and Siemens occupy positions exemplifying platform-centric competitive strategy, leveraging digital ecosystems to anchor large-scale petrochemical and automotive deployments. SKF AB represents the hardware-specialist archetype, with vibration-to-cloud analytics capabilities competing primarily on sensor reliability metrics. These three companies illustrate the bifurcation between qualified system integrators meeting ISO 17359 certification requirements and unverified software-only providers facing auditor qualification bottlenecks.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| General Electric Co. |
| Honeywell International Inc. |
| SKF AB |
| National Instruments Corp. |
| Parker Hannifin Corp. |
| Rockwell Automation Inc. |
| Siemens |
| ABB |
| Others |
Supply Flow & Price Mechanics
Long-term subscription contracts with embedded hardware refresh cycles lock in supply access for cloud-based predictive analytics platforms while stabilizing price visibility across multi-site manufacturing deployments. These arrangements concentrate procurement leverage among German automotive suppliers and US Gulf Coast petrochemical operators who bundle vibration sensor networks with recurring software licenses.
Pricing Analysis
Certification level creates the primary spread between ISO 17359-qualified system integrators and unverified software-only providers. Three-tier pricing structure across premium, standard, and economy levels stratifies by auditor qualification status, with premium tiers commanding 40-60% markups for pharmaceutical-grade FDA 21 CFR Part 11 validation. Price erosion runs through MEMS accelerometer tiers as Taiwanese foundry output saturates mid-market demand. Small and mid-sized French metalworking operations exhibit highest price sensitivity, while German chemical producers prioritize certification compliance over unit cost.
Supply Chain Analysis
Strategic stockpiling of GPU and FPGA edge computing hardware dominates procurement behavior as foundry allocation volatility extends lead times for real-time signal processing components. Semiconductor packaging concentrates in Taiwan, South Korea, and Japan, with MEMS accelerometer wafers drawing from the same foundry pool as consumer electronics. Single-source vulnerability in Taiwanese semiconductor houses exposes deployment timelines to geopolitical disruption. Distribution runs through authorized system integrator channels for ISO-certified deployments, with direct OEM relationships capturing cloud-native software subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The equipment monitoring market is recovering from capital expenditure compression as automotive electrification and EU emissions mandates restart deferred retrofit programs. Manufacturing facility reopening rates and battery gigafactory construction permits serve as cyclical confirmation signals.
For Market Incumbents: Compound platform stickiness through captive edge AI chip integration and backward integration into MEMS sensor fabrication. Defend against pure-play analytics vendors by accelerating ISO 17359 auditor qualification programs to maintain procurement channel access. Prioritize certification investment as the primary lever for margin defense against commoditized vibration hardware.
For New Entrants and Emerging Players: Lead with wireless mesh networking deployments in hazardous environment applications where installation cost advantages bypass incumbent conduit engineering relationships. Target India's PLI scheme manufacturing corridors for greenfield cloud-based deployments without legacy PLC integration burdens. Pursue pharmaceutical validation services as the most penetrable segment given FDA 21 CFR Part 11 consulting demand.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated platform providers with captive sensor hardware and certified system integrator networks. Long-term viability rests on recurring revenue conversion and edge computing silicon differentiation. Watch battery gigafactory thermal runaway detection procurement volumes as the inflection indicator for multi-parameter platform demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Chip Integration | Enables localized anomaly detection without cloud dependency for Rotterdam port complexes. |
| ISO 17359 Auditor Qualification | Unlocks regulated procurement channels in German automotive and French nuclear maintenance. |
| Wireless Mesh Certification | Accelerates hazardous area deployment velocity 40% above cabled alternatives in US refineries. |
| FDA 21 CFR Part 11 Validation Services | Captures specialized consulting revenue from pharmaceutical electronic record integrity requirements. |
| India PLI Corridor Expansion | Bypasses legacy infrastructure replacement costs in Gujarat and Tamil Nadu manufacturing zones. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads across German automotive suppliers and US Gulf Coast refineries; and secondary validation through SEC 10-K filings, customs and trade data, ISO certification registries, and hyperscaler capex disclosures. Bottom-up unit economics triangulated against top-down sector spend estimates to anchor volume and value outputs.
Across the analysis window, the forecasting framework modeled technology segments by deployment architecture, end-user vertical concentration, and regional regulatory cluster intensity. CAGRs derived from segment-level growth rate reconciliation against macro industrial production indices. Industry-specific inputs included battery gigafactory construction permitting data and EU ETS emissions compliance timelines for asset-intensive sectors.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor foundry allocation stability or abrupt EU Green Deal policy reversal would require recalibration. Forecasts reflect documented assumptions regarding MEMS cost curve trajectories and wireless mesh protocol adoption rates. Revision becomes warranted when edge computing hardware lead time volatility crosses 6-month thresholds or when ISO auditor qualification backlogs exceed 30-month durations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
In-Counter Barcode Scanners Market
Sensors
Vibration Monitoring Market
Sensors
Weigh-In-Motion System Market
Sensors
Eye Tracking Market
Sensors
Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market
Sensors
2D Barcode Reader Market
Sensors
Residential Water Leak Detection System Market
Sensors
Machine Health Monitoring Market
Sensors
Real Time Location System Market
Sensors
Digital Olfaction Products Market
Sensors
Smart Barcode Readers Market
Sensors
India Asset Tracking Market
Sensors
Mobile Mapping Systems Market
Sensors
Indoor Location Market
Sensors
Location-Based Ambient Intelligence Market
Sensors
Robot Sensor Market