
 IoT Lpwans Market | 2026-2036
IoT Lpwans Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Lpwans Market Analytics
Germany's industrial corridor is narrowing the gap between pilot LPWAN deployments and scaled production networks across its automotive and machinery sectors. Semtech Corporation leverages its LoRa semiconductor portfolio to dominate the chipset layer of European utility metering projects. Sigfox sustains its ultra-narrowband service model through dedicated network infrastructure in France and Spain. Actility anchors its competitive position with carrier-grade IoT platform deployments serving smart city and industrial verticals.
IoT LPWANs are low-power, wide-area wireless communication networks operating in unlicensed sub-GHz spectrum bands or licensed LTE frequencies, designed to transmit small data payloads across distances exceeding ten kilometers while consuming microamperes of standby current. Their primary purpose is enabling battery-operated sensor networks for telemetry, tracking, and remote monitoring where cellular power budgets and costs prove prohibitive. LoRaWAN technology leads in private network deployments across European manufacturing facilities due to its open protocol stack and gateway interoperability. Smart Metering applications command the deepest utility investment cycles, while Asset Tracking segments in logistics and cold chain represent the fastest-expanding margin pool as enterprises seek granular shipment visibility.
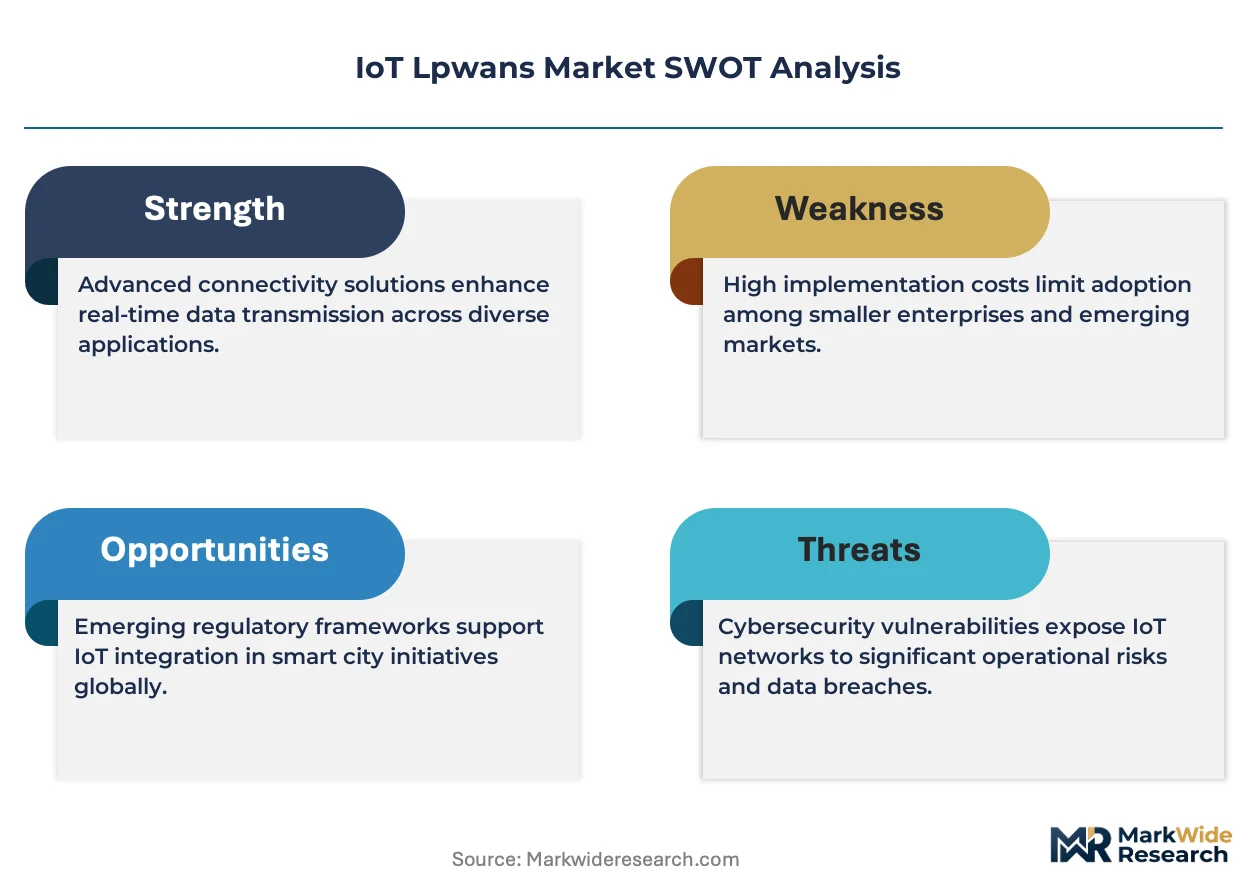
The European Commission's Radio Equipment Directive and the EU Cybersecurity Act shape device certification timelines and data protection requirements for cross-border LPWAN service providers. Germany's Federal Network Agency and France's ANFR regulate spectrum allocation in the 868 MHz band, directly constraining network capacity and device density in urban deployments. Stakeholders must monitor evolving national spectrum auctions and harmonized cybersecurity standards to determine whether public network subscriptions or private infrastructure investments deliver superior total cost of ownership across their target use cases.
Market Dynamics
LoRaWAN's open protocol stack is fragmenting competitive control across European industrial corridors, as private network deployments accelerate faster than carrier-managed subscriptions can provision coverage.
Growth Catalysts
- EU Cybersecurity Act:Harmonized certification timelines are compressing cross-border deployment friction for device manufacturers seeking multi-country market access.
- Predictive maintenance platforms:Automotive and machinery OEMs in Germany's industrial corridor are integrating LPWAN telemetry to reduce unplanned downtime and extend asset lifecycles.
- Smart city infrastructure:Street lighting and waste management systems across France and Spain are driving module volume as municipalities consolidate vendor relationships.
Market Restraints
- Spectrum congestion in 868 MHz:Germany's Federal Network Agency and France's ANFR impose strict duty-cycle limits that constrain device density in urban deployments.
- Silicon supply concentration:LoRa chipset fabrication depends on a narrow foundry base in East Asia, exposing module makers to geopolitical logistics volatility.
- Cellular NB-IoT pricing pressure:Licensed LTE-M alternatives from mobile network operators are undercutting unlicensed LPWAN economics in high-data-rate applications.
Strategic Opportunities
- Cold chain logistics:Asset tracking in pharmaceutical and food distribution represents an underpenetrated vertical where granular temperature visibility commands premium subscription pricing.
- EU Green Deal alignment:Energy efficiency mandates for building automation are creating procurement pull for sub-metering networks that LPWAN architectures serve cost-effectively.
- Edge-AI convergence:On-device inference combined with LPWAN backhaul is enabling predictive models at sensor nodes without continuous cloud connectivity.
Industry Challenges
- RF engineering talent scarcity:Sub-GHz antenna design and propagation modeling expertise is concentrating among legacy telecom suppliers, constraining in-house network planning for industrial end-users.
- Multi-protocol integration complexity:Enterprises operating mixed LoRaWAN, Sigfox, and cellular fleets face fragmented management platforms that delay operational scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Lpwans Market |
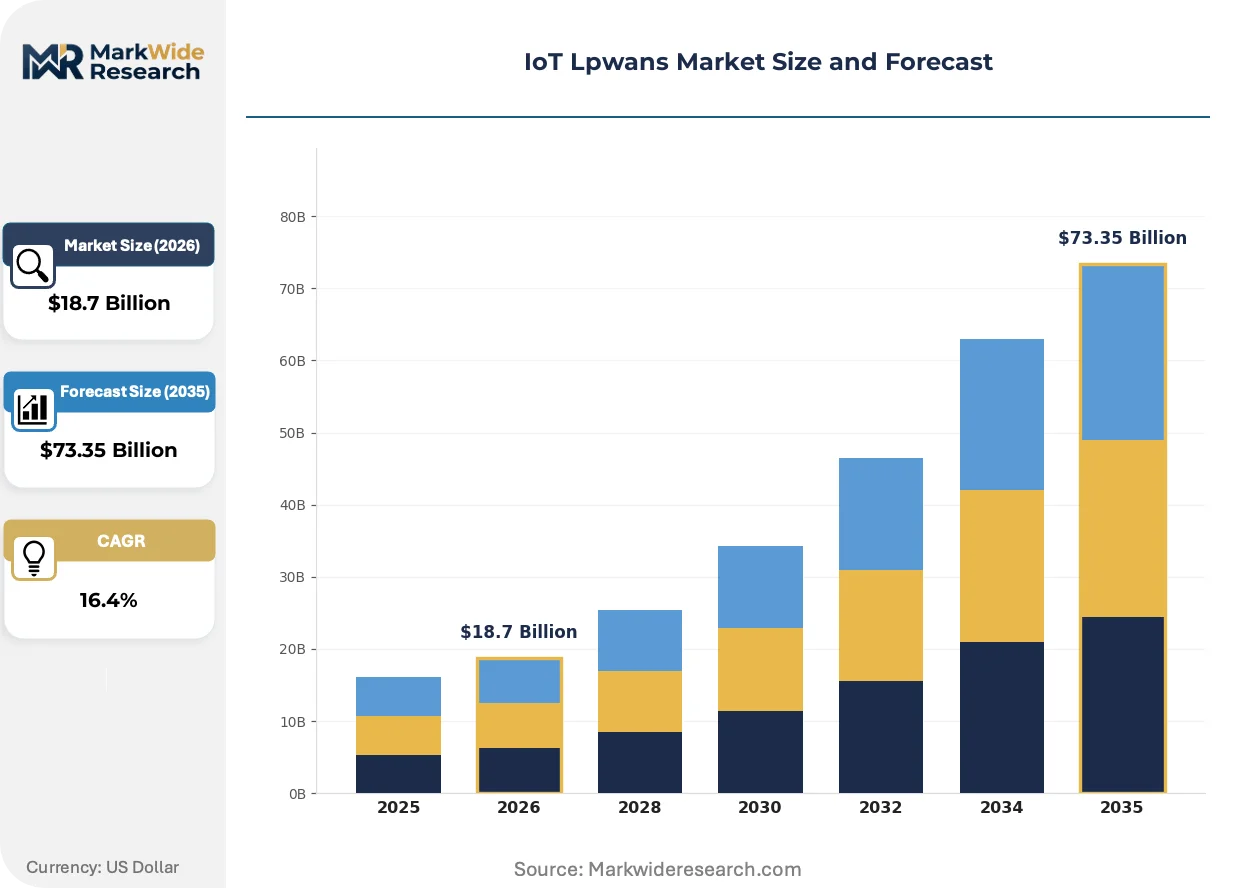
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Narrowband IoT, Sigfox, LoRaWAN, Weightless Application: Smart Metering, Industrial Automation, Environmental Monitoring, Asset Tracking End User: Utilities, Manufacturing, Agriculture, Smart Cities Deployment: Public Network, Private Network, Hybrid Network, Managed Services |
| Companies Covered | Semtech Corporation, Sigfox, Actility, Vodafone Group Plc, Verizon Communications Inc., Qualcomm Technologies, Inc., AT&T Inc., Kerlink, Link Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Lpwans Market Evolving Landscape
Radio hardware and network software are decoupling faster than carrier business models can adapt, shifting value capture toward semiconductor and platform layers.
LoRa chipsets are migrating from proprietary modulation stacks toward open RISC-V cores with software-defined radio front-ends. Industrial automation buyers in Germany are piloting these flexible architectures to future-proof against protocol obsolescence. This migration from fixed-function silicon is compressing replacement cycles and eroding incumbent semiconductor margin structures.
REACH substance restrictions and RoHS recast directives are tightening material compliance for battery-powered devices deployed in EU member states. Manufacturers must now document full supply chain substance flows for coin-cell and energy-harvesting power modules. Smart metering OEMs are responding by qualifying alternative chemistries and redesigning power architectures to eliminate restricted materials.
Enterprise procurement teams are consolidating LPWAN subscriptions under multi-year framework agreements with single-source platform providers. Systems integrators and industrial distributors are losing direct device margin to these consolidated buying channels. This pattern is most visible in France and Spain, where utility-scale smart city rollouts favor centralized procurement over fragmented vendor relationships.
IoT Lpwans Market Segmentation
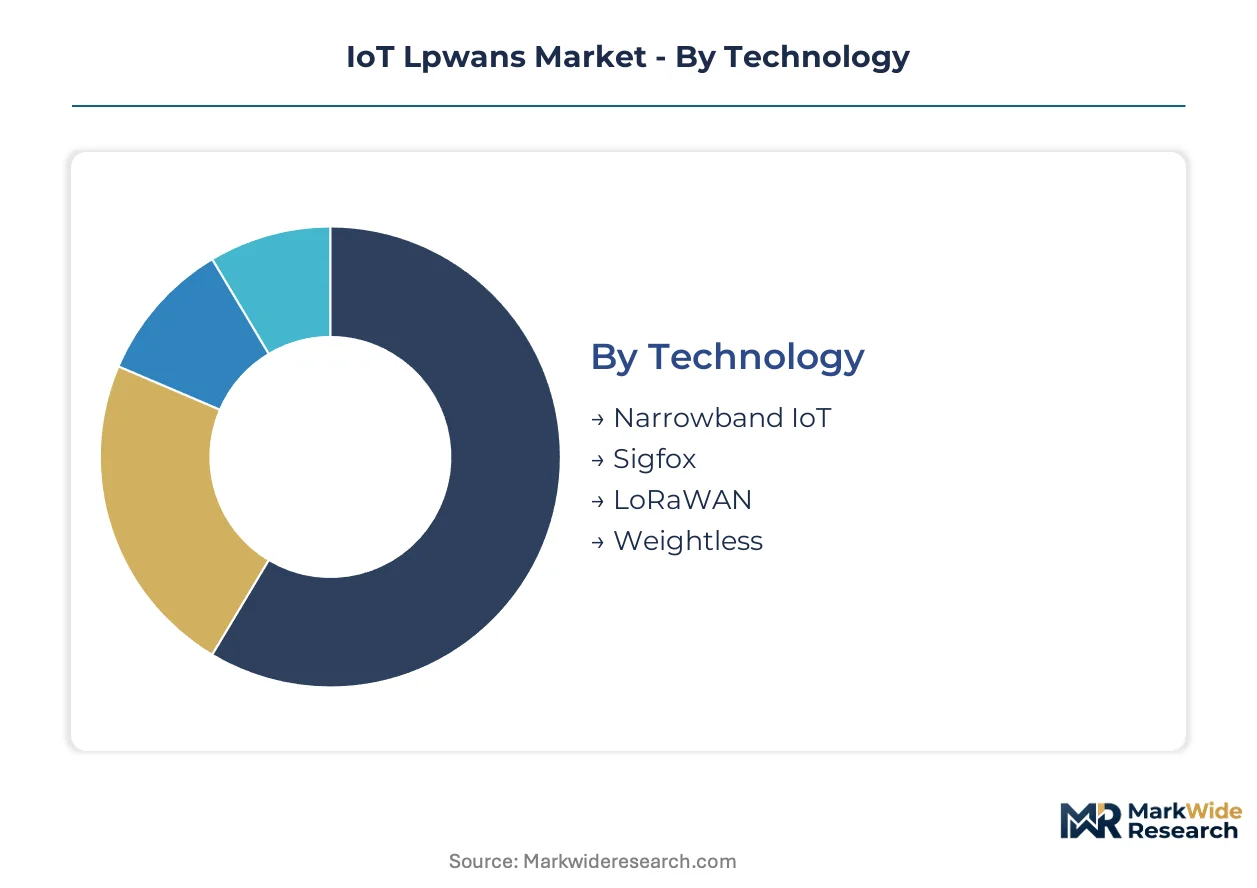
LPWAN procurement patterns diverge sharply across technology layers and operational contexts. Buyers optimize for spectrum licensing costs, payload frequency, and integration complexity rather than throughput alone.
Technology:
Protocol selection determines power budgets, gateway density, and long-term vendor lock-in exposure.
- LoRaWAN:Open protocol stack operating in sub-GHz unlicensed spectrum with adaptive data rate modulation. Germany's automotive suppliers favor private LoRaWAN deployments for predictive maintenance telemetry due to gateway interoperability and no recurring carrier fees.
- Narrowband IoT:Licensed LTE spectrum technology delivering deep indoor penetration through 200 kHz channel bandwidth. France's water utilities are migrating smart metering infrastructure to NB-IoT as mobile operators bundle connectivity with guaranteed service-level agreements.
- Sigfox:Ultra-narrowband proprietary network with national coverage obligations in select European markets.
- Weightless:Open-standard technology optimized for television white space spectrum utilization.
LoRaWAN commands the established base. The steepest expansion runs through Narrowband IoT.
Application:
Use case economics vary by data payload size, transmission frequency, and regulatory compliance burden.
- Smart Metering:Periodic telemetry from electricity, gas, and water meters requiring decade-long battery life and tamper-evident enclosures. Spain's regional utilities are consolidating vendor relationships around unified AMI platforms that integrate LPWAN backhaul.
- Asset Tracking:Location and condition monitoring for mobile equipment and shipment containers. Pharmaceutical distributors in Germany's Rhine-Main corridor are deploying temperature-logging trackers with granular cold chain visibility commanding premium subscription tiers.
- Industrial Automation:Machine health monitoring and environmental sensing in manufacturing facilities.
- Environmental Monitoring:Air quality, noise, and radiation sensors deployed in urban and remote settings.
Smart Metering absorbs the largest capital deployment cycles. Asset Tracking is gaining share fastest among new LPWAN subscriptions.
End User:
Procurement sophistication and integration complexity separate enterprise buyers from municipal adopters.
- Utilities:Regulated infrastructure operators with decade-long asset replacement cycles and cybersecurity certification requirements. Germany's Federal Network Agency mandates specific encryption standards for grid-connected telemetry devices.
- Smart Cities:Municipal aggregators consolidating street lighting, waste management, and parking sensors under unified platform contracts. French municipalities are favoring framework agreements with single-source providers over fragmented vendor relationships.
- Manufacturing:Industrial facilities integrating sensor networks into existing SCADA and ERP systems.
- Agriculture:Farm operators deploying soil moisture and livestock tracking across dispersed rural geographies.
Utilities anchor the revenue base. Smart Cities are climbing the fastest as EU Green Deal funding accelerates municipal digitization programs.
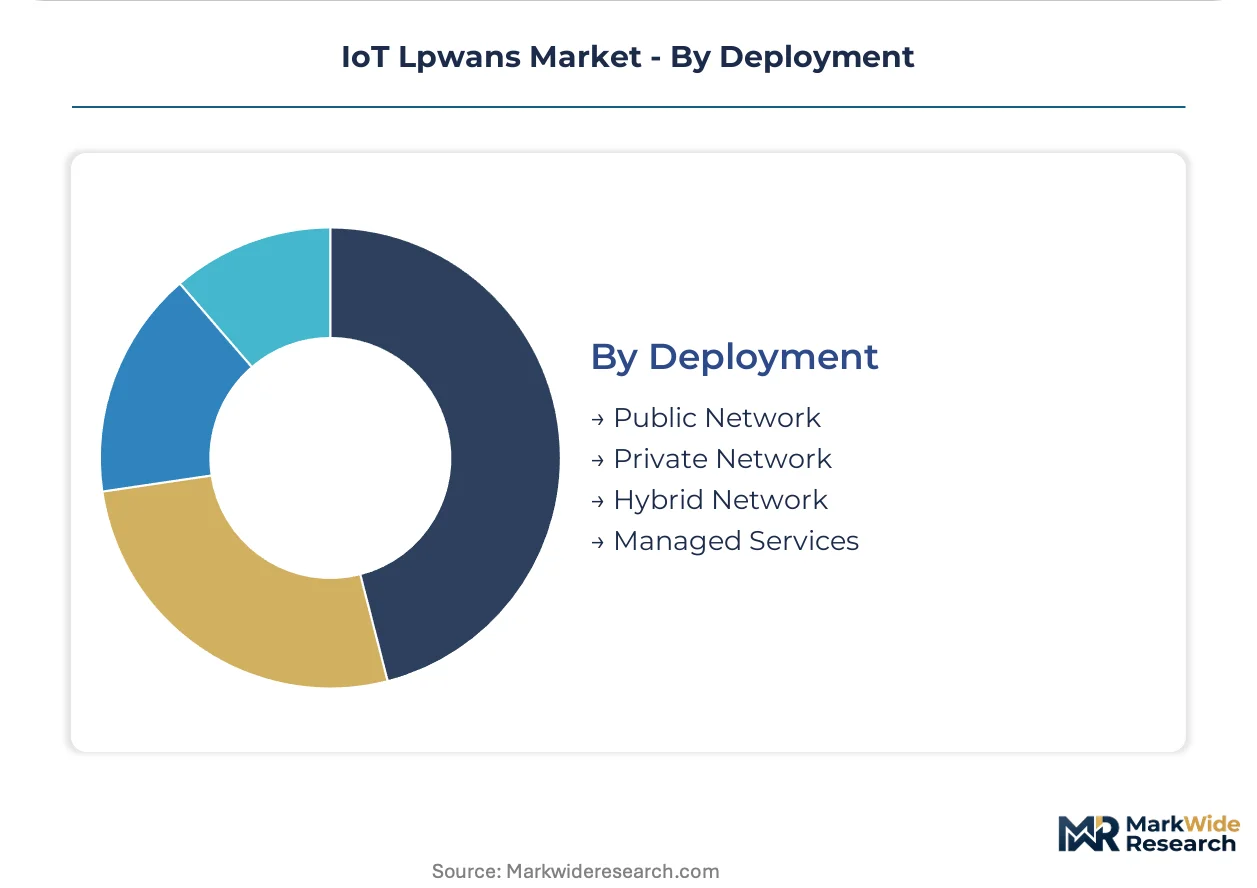
Deployment:
Ownership models determine capital intensity, operational control, and total cost of ownership trajectories.
- Private Network:Enterprise-owned gateway infrastructure with dedicated spectrum access and no per-device subscription fees. Germany's machinery OEMs are deploying factory-floor LoRaWAN networks to isolate operational technology traffic from public internet exposure.
- Public Network:Carrier-managed subscriptions with national coverage and standardized service terms.
- Hybrid Network:Combined private gateway clusters with public roaming for geographic redundancy.
- Managed Services:Outsourced network operations including device provisioning, firmware updates, and security patching.
Public Network subscriptions retain volume leadership. Private Network deployments are expanding most quickly among security-sensitive industrial buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main corridor's freight rail intermodal terminals underpin Germany's LPWAN logistics density. France's high-speed TGV network enables rapid field service deployment for smart city infrastructure. Spain's Mediterranean port complex at Valencia-Barcelona anchors cold chain tracking volume for pharmaceutical exports.
Germany
Automotive OEMs in Stuttgart and Munich integrate LoRaWAN telemetry into predictive maintenance platforms for machinery fleets. The Federal Network Agency enforces strict 868 MHz duty-cycle limits that constrain urban device density. Factory-floor private networks in Bavaria isolate operational technology traffic from public internet exposure.
France
ANFR spectrum management enables national Sigfox coverage obligations while municipalities consolidate vendor relationships under unified smart city contracts. The EU Cybersecurity Act harmonizes certification timelines for cross-border device deployment. Water utilities in the Paris basin migrate metering infrastructure to NB-IoT as mobile operators bundle guaranteed service-level agreements.
Spain
Regional utilities consolidate advanced metering infrastructure around unified platforms integrating LPWAN backhaul for electricity and gas networks. The European Commission's Radio Equipment Directive reduces cross-border certification friction for device manufacturers. Street lighting deployments in Barcelona and Madrid drive module volume as municipalities favor framework agreements over fragmented procurement.
United States
Verizon and AT&T leverage licensed LTE-M spectrum to undercut unlicensed LPWAN economics in high-data-rate industrial applications. FCC Part 15 regulations govern unlicensed sub-GHz deployments for private manufacturing networks. Cold chain logistics operators in the Chicago-Detroit corridor deploy temperature-logging trackers with granular pharmaceutical visibility commanding premium subscription tiers.
China
MIIT spectrum allocation in sub-GHz bands supports massive NB-IoT deployments for smart metering and agricultural monitoring. GB standards compliance requirements shape device certification timelines for domestic and export markets. Manufacturing clusters in the Yangtze River Delta pilot edge-AI convergence with LPWAN backhaul for predictive models at sensor nodes.
IoT Lpwans Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The vendor base separates into carrier-managed service providers, semiconductor modulation houses, and carrier-grade software platforms. Three archetypes dominate: licensed spectrum operators bundling connectivity with SLAs, unlicensed protocol enablers licensing chipsets and software stacks, and pure-play network infrastructure vendors deploying gateways and management tools. Consolidation pressure runs through carrier-operator partnerships and silicon foundry capacity commitments.
Within the semiconductor archetype, Semtech Corporation exemplifies the modulation-focused licensing model for unlicensed spectrum deployment. Sigfox occupies a position representing the dedicated ultra-narrowband infrastructure approach with national coverage obligations. Actility anchors the carrier-grade platform tier serving smart city and industrial verticals through outsourced network operations. These three patterns illustrate how value capture shifts between chipset, network, and service layers as radio hardware and software decouple.
| Leading Market Players |
|---|
| Semtech Corporation |
| Sigfox |
| Actility |
| Vodafone Group Plc |
| Verizon Communications Inc. |
| Qualcomm Technologies, Inc. |
| AT&T Inc. |
| Kerlink |
| Link Labs |
| Others |
Value Network & Pricing Analysis
LoRa chipset foundry undercapacity in East Asia is compressing module margins while forcing European device manufacturers to accept extended lead times and volume-commitment contracts. This utilization squeeze simultaneously hardens pricing power at the semiconductor layer and accelerates buyer migration toward alternative NB-IoT subscriptions where carrier economics prove more predictable.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates module procurement, with differentiation driven by certification grade (CE marking tier) and volume scale. Pricing pressure stems from cellular NB-IoT bundle discounts that undercut unlicensed LPWAN economics in high-data-rate applications. Municipal smart city buyers exhibit highest price sensitivity due to consolidated framework agreements, while pharmaceutical cold chain operators accept premium tiers for guaranteed service-level agreements.
Supply Chain Analysis
Supply-chain finance facilities with 90-day payment terms have become standard for gateway manufacturers sourcing from Taiwanese foundries and South Korean memory suppliers. The LPWAN hardware stack draws from concentrated semiconductor fabrication in Taiwan, China, and South Korea, with critical dependencies on sub-GHz RF front-ends, LoRa baseband processors, and energy-harvesting power modules. Single-source vulnerability around Semtech's modulation IP concentration creates procurement risk. Distribution runs through industrial distributors and systems integrators losing margin to consolidated enterprise procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LPWAN market is approaching a platform-economics inflection where open RISC-V cores and software-defined radio front-ends are decoupling hardware from protocol lock-in, eroding incumbent semiconductor margin structures and enabling new interoperability plays.
For Market Incumbents: Harden gateway interoperability certification to defend against protocol-agnostic silicon entrants. Deepen backward integration into captive foundry capacity in Taiwan or South Korea to secure wafer supply against geopolitical logistics volatility. Prioritize investment in edge-AI convergence capabilities where on-device inference combined with LPWAN backhaul creates switching costs.
For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical cold chain asset tracking where granular temperature visibility commands premium subscription pricing and incumbent coverage gaps persist. Target Germany's industrial corridor for private LoRaWAN deployments where machinery OEMs seek operational technology isolation from public networks. Lead with managed services positioning that bundles device provisioning, firmware updates, and security patching to bypass fragmented multi-protocol integration complexity.
For Investors and Strategic Acquirers: Capital is best deployed toward carrier-grade software platform providers with existing smart city framework agreements in France and Spain, where municipal procurement consolidation favors scaled operators over point-solution vendors. Long-term viability hinges on interoperability across LoRaWAN, NB-IoT, and emerging satellite-IoT protocols. Watch for edge-AI inference deployment rates at sensor nodes as the signal indicating whether LPWAN remains pure transport or captures analytics value.
| Strategic Initiative | Industry Significance |
|---|---|
| Protocol Stack Open-Source Migration | RISC-V core adoption in LoRa chipsets fragments Semtech's modulation IP control and compresses replacement cycles. |
| Carrier-Grade Platform Consolidation | Single-source framework agreements with French and Spanish municipalities displace fragmented vendor relationships. |
| Edge-AI Inference Integration | On-device predictive models with LPWAN backhaul reduce cloud connectivity costs for German automotive OEMs. |
| Foundry Capacity Securement | Taiwanese and South Korean wafer commitments insulate module makers from geopolitical logistics volatility. |
| Cold Chain Premium Service Tiering | Granular temperature visibility in pharmaceutical distribution commands subscription pricing multiples above standard asset tracking. |
Research Methodology
A standing panel of network operations directors at European utilities, smart city procurement leads in French municipalities, industrial automation engineers at German automotive OEMs, and semiconductor product managers at modulation houses provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders against secondary validation from EU Cybersecurity Act implementation documents, Federal Network Agency spectrum allocation rulings, ANFR coverage obligation filings, and customs data tracking module import flows. Bottom-up device shipment estimates and top-down carrier subscription revenue analysis were triangulated to converge on market sizing.
Scenario-bracketing around regulatory acceleration, silicon supply disruption, and cellular pricing aggression bounded high and low growth paths across the projection horizon. Segmentation modeling incorporated technology protocol, application use case, end-user procurement sophistication, and deployment ownership structure. CAGRs were derived from fitted adoption curves calibrated against historical smart metering rollout patterns and industrial IoT penetration benchmarks. Forecast inputs included spectrum auction timelines, EU Green Deal funding disbursement schedules, and REACH substance restriction implementation phases.
Stress conditions across 868 MHz duty-cycle enforcement severity, Taiwanese foundry utilization rates, and NB-IoT bundle discount depth were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about protocol migration rates and municipal procurement consolidation velocity. Macroeconomic contraction, cybersecurity certification delays, or breakthrough satellite-IoT coverage would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Internet of Things (IoT) Market
Internet of Things (IoT)
Global Internet of Behaviors Market
Internet of Things (IoT)
IoT Integration Market
Internet of Things (IoT)
Cellular IoT Module Market
Internet of Things (IoT)
Marine Internet of Things Market
Internet of Things (IoT)
Industrial IoT Platform Market
Internet of Things (IoT)
Internet of Medical Things (Iomt) Market
Internet of Things (IoT)
Maritime Internet of Things Market
Internet of Things (IoT)
Massive IoT Market
Internet of Things (IoT)
Global 5G Industrial IOT Market
Internet of Things (IoT)
Non-Terrestrial IoT Gateway Hardware and Software Market
Internet of Things (IoT)
Global IoT Solutions and Services Market
Internet of Things (IoT)
Qatar Internet of Things (IoT) Market
Internet of Things (IoT)
Global IoT Managed Services Market
Internet of Things (IoT)
Airport Internet of Things Market
Internet of Things (IoT)
Global Open IoT Platform Market