
 Wireless Connected Devices Market | 2026-2036
Wireless Connected Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Connected Devices Market Outlook
Semiconductor foundry expansion in Taiwan is realigning component availability for wireless module producers. Samsung Electronics leverages its captive display and memory supply to dominate premium wearable assembly. Qualcomm Incorporated anchors cellular connectivity licensing across automotive and industrial tiers. Broadcom Inc. specializes in Wi-Fi 7 silicon, controlling the performance tier for enterprise access points.
Wireless connected devices are electronic systems that transmit data without physical cabling, typically operating across radio frequency bands from sub-1 GHz to 6 GHz and integrating microcontrollers with protocol stacks for mesh, star, or point-to-point network topologies. Their primary purpose is to enable real-time sensing, actuation, and telemetry across distributed environments where wired infrastructure is impractical or cost-prohibitive. Wearables and health monitoring applications command the highest margin pools due to regulatory certification barriers and recurring software subscription attach rates. Home automation and smart sensors compete on volume scale, with Zigbee and Thread protocol convergence reducing silicon fragmentation for OEMs.
The FCC in the United States governs spectrum allocation and device emission limits, while the EU AI Act and GDPR impose algorithmic transparency and data residency requirements on connected health and smart home platforms. ETSI standards in Europe mandate interoperability testing that extends product development cycles but reduces aftermarket replacement friction. Stakeholders must monitor spectrum reallocation proceedings and cybersecurity labeling programs to anticipate compliance cost shifts and certification timeline changes.
Market Dynamics
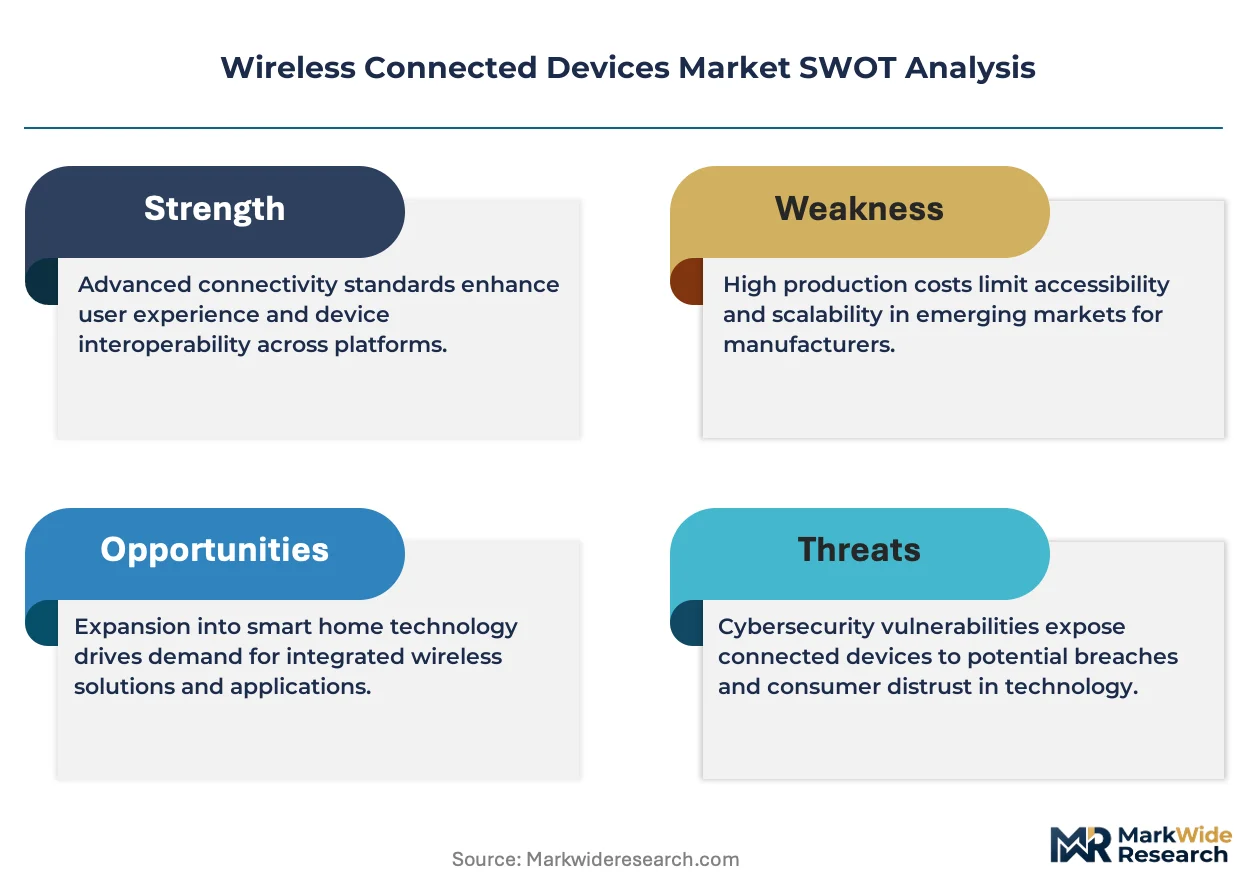
Protocol convergence between Zigbee and Thread is collapsing silicon fragmentation for OEMs, while EU AI Act compliance requirements are extending certification timelines and reshaping competitive positioning in health monitoring segments.
Growth Catalysts
- Remote Patient Monitoring:Healthcare providers are deploying connected wearables for chronic disease management, with FDA clearance pathways for Software as a Medical Device accelerating deployment in US hospital systems.
- EU AI Act:Algorithmic transparency mandates for connected health platforms are creating certification moats that protect incumbents with established compliance infrastructure.
- Factory Automation:Germany's industrial corridor is accelerating investment in wireless sensor networks for predictive maintenance, pulling demand for industrial-grade mesh topology modules.
Market Restraints
- Spectrum Fragmentation:Regional allocation differences for sub-1 GHz and 6 GHz bands force module manufacturers to maintain multiple SKUs, inflating inventory carrying costs.
- Foundry Concentration:Taiwan's semiconductor fabrication dominance creates single-source vulnerability for wireless SoC production, with geopolitical friction threatening supply continuity.
- GDPR Data Residency:Connected health platforms face architectural constraints requiring EU-localized cloud infrastructure, raising operational complexity for US-based platform vendors.
Strategic Opportunities
- India Manufacturing:PLI scheme incentives for electronics assembly are attracting wireless module producers to establish captive production for domestic and export markets.
- Wi-Fi 7 Enterprise:Enterprise access point refresh cycles are creating demand for tri-band silicon supporting 320 MHz channel bandwidth and multi-link operation.
- Matter Protocol:Smart home interoperability standardization is collapsing ecosystem silos, enabling cross-platform device sales previously locked to single-vendor hubs.
Industry Challenges
- RF Engineering Talent:Scarcity of mmWave antenna design expertise is compressing product development timelines for 6 GHz device certification.
- ETSI Interoperability Testing:Extended validation cycles for European market entry are delaying revenue recognition by 4-6 months relative to FCC-only certification paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Connected Devices Market |
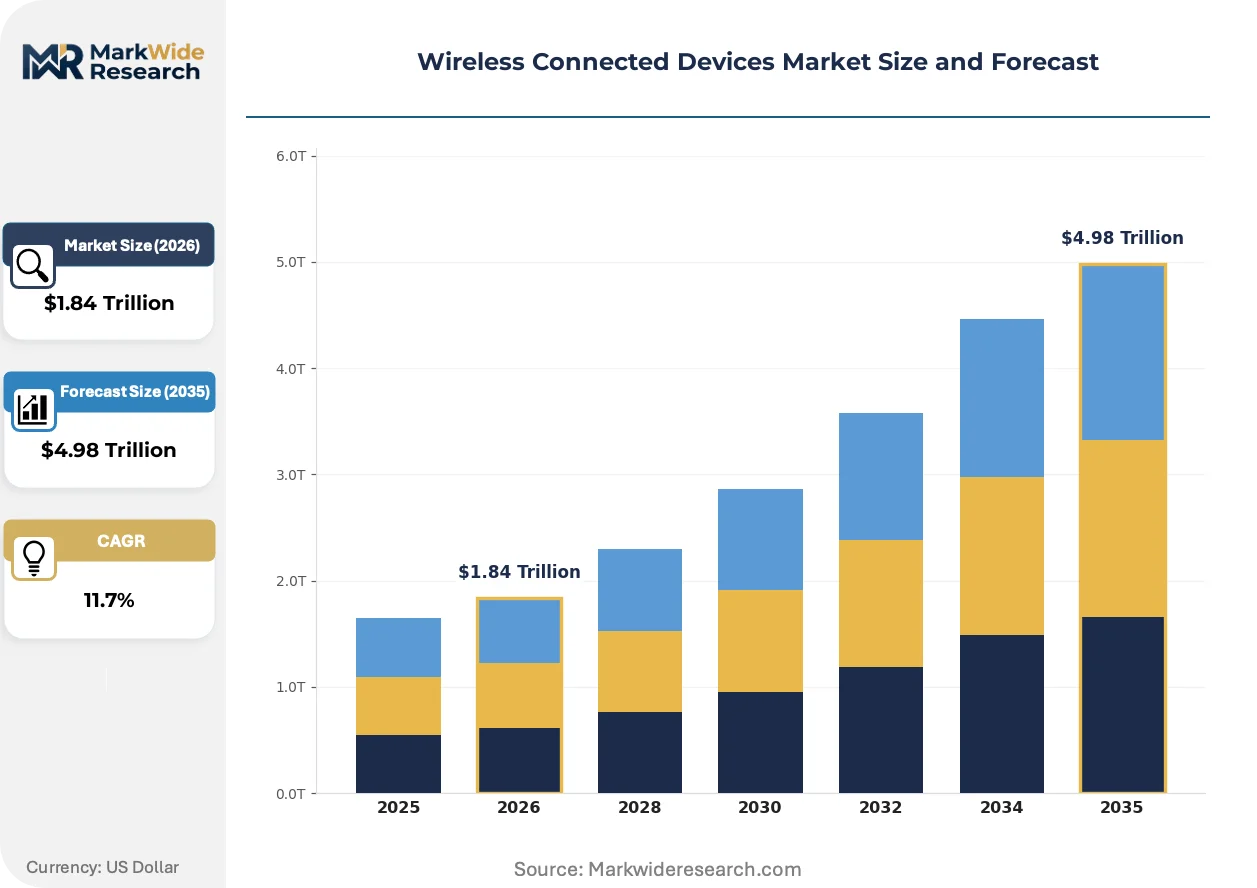
| Market Size in 2026 | $1.84 Trillion |
| Market Size in 2035 | $4.98 Trillion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearables, Home Automation, Smart Sensors, Health Monitoring Technology: Bluetooth, Wi-Fi, Zigbee, NFC End User: Consumers, Enterprises, Healthcare Providers, Industrial Users Application: Smart Homes, Healthcare, Industrial Automation, Wearable Fitness |
| Companies Covered | Apple Inc., Samsung Electronics, Huawei Technologies Co., Ltd, Qualcomm Incorporated, Intel Corporation, Texas Instruments Incorporated, Broadcom Inc., Lenovo, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Connected Devices Market Strategic Shifts
Edge AI inference on battery-constrained endpoints is redistributing computational architecture away from cloud dependency, while regulatory fragmentation across major economies is forcing platform-level compliance investments.
Ultra-wideband (UWB) positioning technology is enabling centimeter-accurate spatial awareness for asset tracking and hands-free access control. Automotive OEMs are integrating UWB into digital key systems at model-year 2024-2025 refresh cycles. This capability is decentralizing proximity-based authentication from smartphone-centric architectures toward distributed device ecosystems.
The EU AI Act's risk-based classification system is mandating conformity assessments for high-risk connected health devices before market placement. Manufacturers must maintain technical documentation and post-market monitoring systems subject to notified body audit. Germany and France are seeing the steepest compliance cost increases as their health platforms process biometric data requiring algorithmic transparency.
Hospital procurement departments are consolidating vendor relationships around integrated platform contracts rather than point-device purchases. Medical device distributors are losing share to direct manufacturer agreements with health system GPOs. This concentration is most pronounced in US integrated delivery networks exceeding 50 hospital facilities.
Wireless Connected Devices Market Segmentation
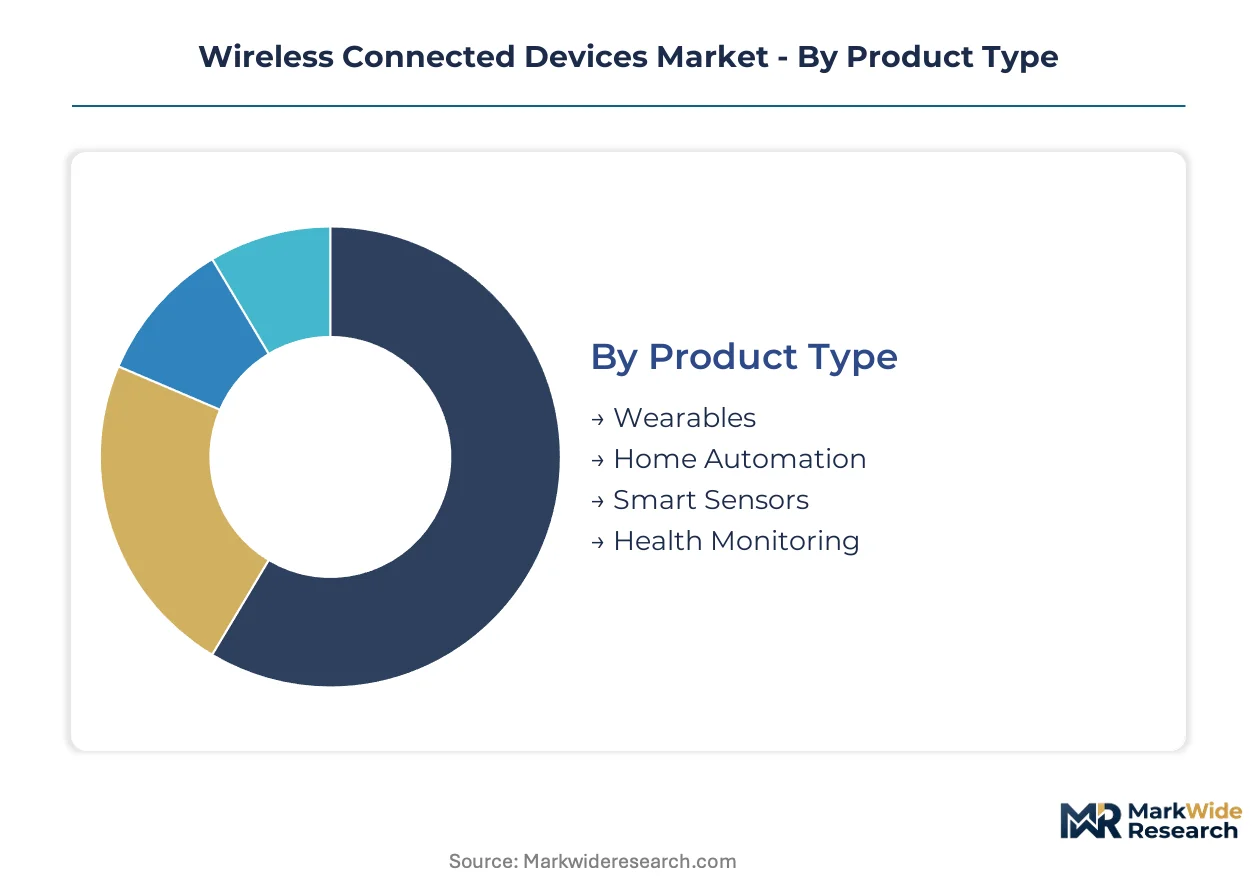
Wireless connected devices fragment across four structural dimensions that determine pricing power, certification burden, and supply chain configuration. Product type and technology choices lock manufacturers into specific margin pools, while end-user and application segments dictate distribution channel requirements and regulatory exposure.
Product Type:
Integration depth varies sharply: wearables and health monitoring operate as standalone consumer endpoints, while home automation and smart sensors embed into broader system architectures.
- Wearables:Battery-powered wrist and body-worn devices integrating biometric sensors with Bluetooth Low Energy stacks. Demand concentrates in premium consumer electronics retail, where FDA-cleared health features command subscription attach rates.
- Health Monitoring:Clinical-grade devices for remote patient management, including continuous glucose monitors and pulse oximeters. Hospital procurement departments in the United States favor integrated platform contracts with GPOs over point-device purchases.
- Home Automation:Smart hubs, lighting controllers, and climate systems operating on mesh topologies. Matter protocol convergence is collapsing ecosystem silos previously locked to single-vendor architectures.
- Smart Sensors:Distributed environmental and occupancy monitors for building management. Germany's industrial corridor pulls demand for predictive maintenance deployments in factory automation settings.
Wearables lead volumes today; health monitoring is gaining share fastest.
Technology:
Protocol selection determines range, power budget, and interoperability certification costs, with cellular and Wi-Fi variants anchoring high-throughput tiers while mesh protocols dominate battery-constrained sensing.
- Bluetooth:Dominates wearable and personal area connectivity through Low Energy and Auracast audio streaming variants. Samsung Electronics leverages captive integration with display and memory supply to dominate premium assembly tiers.
- Wi-Fi:Enterprise access point refresh cycles drive tri-band silicon demand for 320 MHz channel bandwidth. Broadcom Inc. controls the performance tier for Wi-Fi 7 enterprise infrastructure.
- Zigbee:Mesh networking protocol for home automation and industrial sensor networks. Thread convergence is reducing silicon fragmentation for OEMs previously maintaining separate development tracks.
- NFC:Proximity authentication and payment tokenization in smartphones and access control systems. Automotive OEMs are expanding deployment for digital key systems at model-year refresh cycles.
Bluetooth leads volumes today; Wi-Fi is expanding most quickly in enterprise refresh cycles.
End User:
Procurement authority and compliance infrastructure separate consumer impulse purchases from enterprise RFP processes and healthcare regulatory pathways.
- Consumers:Individual purchasers selecting devices through retail and direct-to-consumer channels. EU AI Act algorithmic transparency requirements are reshaping competitive positioning for connected health platforms.
- Enterprises:Corporate IT departments specifying wireless infrastructure for campus and branch deployments. ETSI interoperability testing mandates extend European market entry timelines.
- Healthcare Providers:Hospital systems and integrated delivery networks consolidating vendor relationships. FDA clearance pathways for Software as a Medical Device accelerate deployment in US facilities exceeding 50 hospitals.
- Industrial Users:Factory operators deploying wireless sensor networks for predictive maintenance. Taiwan semiconductor foundry concentration creates single-source vulnerability for wireless SoC supply continuity.
Consumers lead volumes today; healthcare providers are climbing the fastest on remote patient monitoring adoption.
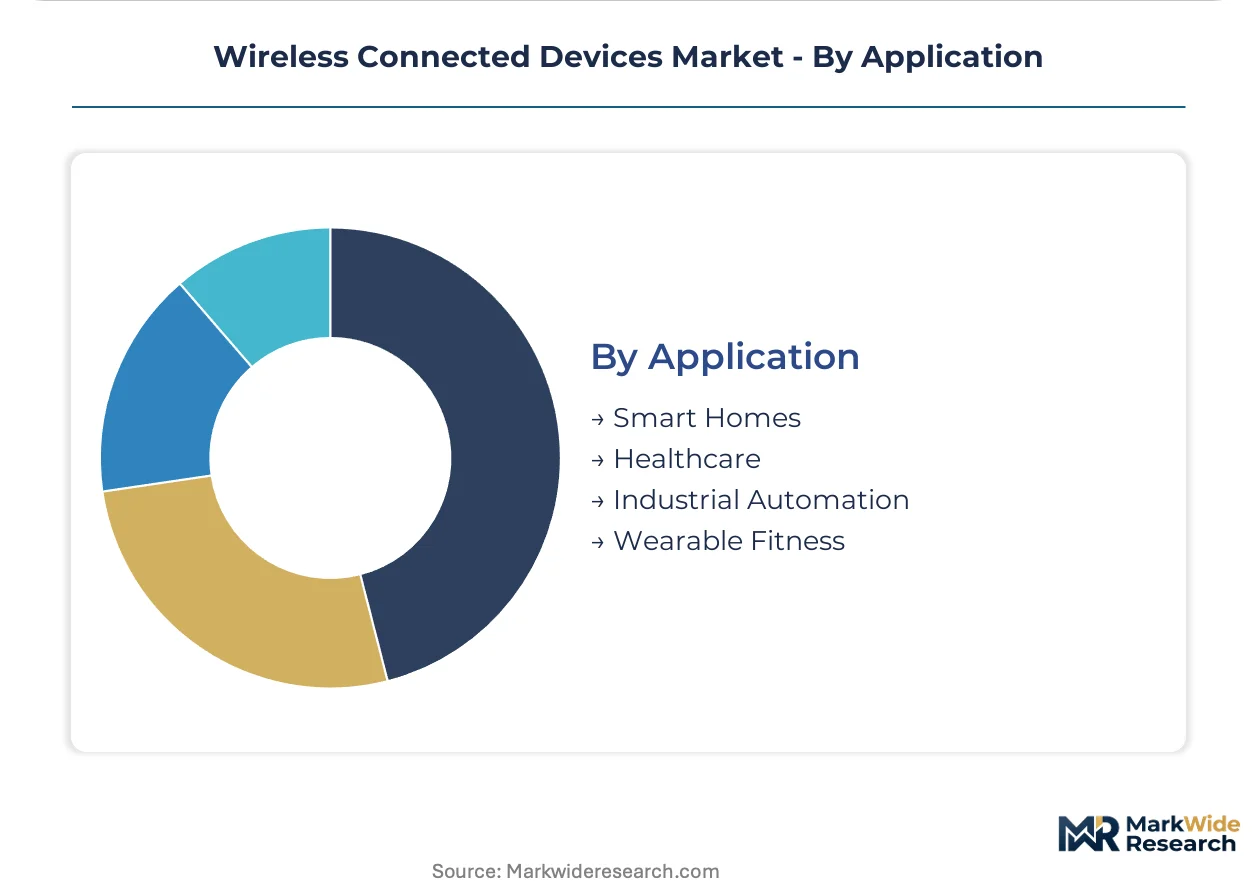
Application:
Use-case environments determine ruggedization requirements, latency tolerance, and whether devices operate in controlled indoor settings or distributed outdoor infrastructure.
- Smart Homes:Residential automation spanning lighting, security, and climate control. Matter protocol standardization enables cross-platform device sales previously locked to single-vendor hubs.
- Healthcare:Clinical and home-based patient monitoring with regulatory certification requirements. GDPR data residency mandates force EU-localized cloud infrastructure, raising operational complexity for US-based platform vendors.
- Industrial Automation:Factory floor wireless sensor networks for condition monitoring and asset tracking. Ultra-wideband positioning technology enables centimeter-accurate spatial awareness for hands-free access control.
- Wearable Fitness:Consumer fitness tracking and wellness monitoring devices. Edge AI inference on battery-constrained endpoints is redistributing computational architecture away from cloud dependency.
Smart homes lead volumes today; healthcare shows the steepest expansion trajectory on chronic disease management deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is shifting production footprints as manufacturers weigh EU AI Act compliance costs against India's PLI scheme incentives and US spectrum allocation stability. Cost-of-compliance gaps between jurisdictions are accelerating facility relocation decisions.
United States
FDA clearance pathways for Software as a Medical Device are accelerating hospital system deployments of remote patient monitoring tools. FCC spectrum reallocation proceedings for 6 GHz bands are extending certification timelines for Wi-Fi 7 device manufacturers. Greater Boston's health technology cluster anchors connected health platform development, with integrated delivery networks exceeding 50 hospital facilities consolidating vendor relationships.
Germany
Factory automation investment in the industrial corridor is pulling demand for industrial-grade mesh topology modules and predictive maintenance sensors. ETSI interoperability testing mandates extend European market entry timelines by 4-6 months relative to FCC-only certification paths. Baden-Württemberg's automotive supply base is integrating ultra-wideband positioning for digital key systems at model-year refresh cycles.
China
MIIT spectrum allocation for sub-1 GHz industrial IoT bands is enabling wireless sensor network deployment in manufacturing zones. GB standards for cybersecurity labeling are reshaping device certification requirements for domestic and export markets. The Yangtze River Delta semiconductor ecosystem is realigning component availability for wireless module producers serving global OEMs.
India
PLI scheme incentives for electronics assembly are attracting wireless module producers to establish captive production for domestic and export markets. TRAI spectrum allocation frameworks for unlicensed bands are enabling smart home device ecosystem growth. Karnataka's Bangalore-Tumkur electronics manufacturing cluster is concentrating contract assembly capacity for wearable and health monitoring devices.
South Korea
METI-aligned spectrum harmonization is accelerating Wi-Fi 7 enterprise infrastructure deployment across corporate campuses. MFDS medical device regulations are creating certification moats for connected health platforms with established compliance infrastructure. The Seoul Capital Area anchors Samsung Electronics' captive display and memory supply integration for premium wearable assembly.
Wireless Connected Devices Market Competitive Environment
Taiwan producers anchor one tier through semiconductor foundry concentration; US and South Korean specialists hold premium connectivity and system integration positions. The vendor base stratifies across captive component suppliers, modular connectivity licensors, and end-device assemblers. Three archetypes dominate: vertically integrated consumer electronics conglomerates, fabless semiconductor specialists controlling protocol stacks, and contract manufacturers scaling assembly for brand OEMs. Competitive moves center on backward integration into captive silicon supply and strategic partnerships collapsing ecosystem silos.
Within the captive integration tier, Samsung Electronics exemplifies vertical control over display, memory, and assembly operations. Among fabless connectivity specialists, Qualcomm Incorporated anchors cellular licensing across automotive and industrial application tiers. Broadcom Inc. occupies a position within the enterprise infrastructure silicon segment, with Wi-Fi 7 development controlling performance tiers for access point refresh cycles.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Huawei Technologies Co., Ltd |
| Qualcomm Incorporated |
| Intel Corporation |
| Texas Instruments Incorporated |
| Broadcom Inc. |
| Lenovo |
| LG Electronics |
| Others |
Value Chain & Pricing Dynamics
Semiconductor wafer costs cascade through wireless module production into three distinct pricing tiers for OEMs, with Taiwan foundry concentration amplifying margin pressure at the premium connectivity tier while India assembly incentives compress entry-level positioning.
Pricing Analysis
Distributor margins for health monitoring devices absorb EU AI Act compliance documentation costs before hospital GPO contracting, while direct-to-OEM discounts dominate industrial sensor procurement through platform-integrated contracts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared wearable subscriptions from uncertified fitness trackers and white-label sensor modules. Pricing pressure stems from Zigbee-Thread protocol convergence collapsing silicon differentiation for home automation OEMs. Healthcare providers show lowest price sensitivity due to reimbursement pathways, while consumer retail channels face highest sensitivity from subscription fatigue.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan's semiconductor fabrication dominance for wireless SoC production, with geopolitical friction threatening supply continuity for module manufacturers. Component sourcing draws from South Korea for memory, China for passive components, and Taiwan for RF silicon. Raw material dependencies include gallium arsenide substrates, high-purity silicon wafers, and rare earth magnets for antenna assemblies. Tariff exposure runs through US-China technology trade restrictions on advanced node semiconductors. Distribution runs through medical device distributors losing share to direct manufacturer agreements with health system GPOs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between India's PLI scheme assembly incentives and EU AI Act compliance costs creates relocation pressure for wireless module producers seeking margin preservation.
For Market Incumbents: Deepen backward integration into captive RF silicon supply to offset Taiwan foundry concentration risk. Fortify certification infrastructure against EU AI Act algorithmic transparency mandates to protect hospital GPO contract positions. Prioritize direct procurement relationships with integrated delivery networks exceeding 50 facilities to displace medical device distributors. For New Entrants and Emerging Players: Capture industrial sensor white space in Germany's factory automation corridor where predictive maintenance demand outpaces established vendor capacity. Penetrate India's domestic wearable market through PLI scheme contract assembly partnerships with Karnataka cluster producers. Lead with Matter protocol interoperability as the go-to-market angle to bypass single-vendor ecosystem lock-in. For Investors and Strategic Acquirers: Consolidation pressure builds where EU AI Act compliance documentation costs exceed $2 million per connected health platform, favoring acquisition of notified-body-certified assets over greenfield development. Target fabless connectivity specialists with established cellular licensing across automotive tiers. Watch FCC spectrum reallocation proceedings for 6 GHz band access as inflection indicator for Wi-Fi 7 enterprise infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Diversification | Dual-sourcing agreements with Taiwan and South Korea foundries reduce geopolitical supply risk for Qualcomm and Broadcom tier suppliers. |
| EU AI Act Conformity Assessment | Notified body certification creates competitive moats protecting incumbents like Samsung Electronics in connected health segments. |
| India PLI Scheme Manufacturing | Captive assembly in Karnataka's electronics cluster enables cost-competitive export positioning for wearable and sensor module producers. |
| Matter Protocol Certification | Cross-platform interoperability validation collapses ecosystem silos previously locking smart home device sales to single-vendor hubs. |
| Hospital GPO Direct Contracting | Integrated platform agreements with US health systems exceeding 50 facilities displace traditional medical device distribution layers. |
Study Parameters
Direct dialogue with semiconductor procurement executives, wireless module engineering leads, hospital GPO contracts managers, and ETSI certification specialists anchored qualitative findings, cross-validated against FCC equipment authorization databases, EU MDR notified body registries, MIIT spectrum allocation filings, and Taiwan Semiconductor Industry Association trade data. Bottom-up and top-down triangulation reconciled component-level cost structures with end-device demand aggregation.
Bottom-up volume modeling tracked wireless SoC shipments by protocol stack and foundry source, while top-down validation assessed healthcare IT capex cycles and industrial automation investment patterns across the projection horizon. Segmentation dimensions spanned product type integration depth, technology protocol selection, end-user procurement authority, and application environment ruggedization. CAGRs derived from regression against semiconductor content per device trends and regulatory timeline acceleration effects.
Foundry capacity constraints, spectrum reallocation delays, and AI Act enforcement variance are the dominant revision risks that could compress or extend forecast trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
North America Internet of Things Devices Market
Internet of Things (IoT)
IoT Cloud Platform Market
Internet of Things (IoT)
North America and Europe IoT Gateway Market
Internet of Things (IoT)
IoT Device Management Platform Market
Internet of Things (IoT)
IoT Solutions Market
Internet of Things (IoT)
IoT Software Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
Bluetooth Smart Plugs Market
Internet of Things (IoT)
Location of Things Market
Internet of Things (IoT)
Private Narrowband IoT Market
Internet of Things (IoT)
Global Residential Smart Thermostats Market
Internet of Things (IoT)
Narrowband IoT Enterprise Application Market
Internet of Things (IoT)
Internet of Things (IoT) Connected Cars Market
Internet of Things (IoT)
Satellite IoT Communication Market
Internet of Things (IoT)
Internet of Things in BFSI Market
Internet of Things (IoT)
Global IoT Node and Gateway Market