
 Asia-Pacific Thermal Spray Market | 2026-2036
Asia-Pacific Thermal Spray Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Thermal Spray Market Outlook
China's dual carbon goals and the EU Green Deal's extraterritorial supply chain requirements are shifting demand toward low-emission thermal spray processes across the Asia-Pacific region. Oerlikon Metco leverages its Swiss-Chinese manufacturing footprint to dominate plasma spray powder supply in Shanghai's aerospace corridor. Höganäs AB anchors high-purity alloy powder production for HVOF applications serving Japanese automotive OEMs. Saint-Gobain S.A. competes through its specialized ceramic feedstock lines targeting South Korean power turbine rebuilders.
Thermal spray encompasses processes that accelerate metallic, ceramic, or cermet particles to supersonic velocities, depositing 50-micron to several-millimeter thick functional layers with bond strengths exceeding 69 MPa in HVOF configurations. The technology primarily restores worn industrial components and insulates hot-section gas turbine hardware against thermal fatigue and oxidation. Plasma spray equipment commands the largest product type share due to its versatility across aerospace superalloy coatings, while cold spray represents the fastest-growing technology segment as Japanese and Australian defense contractors adopt solid-state deposition for temperature-sensitive substrates. Wear resistant coatings lead the technology category in revenue terms, though thermal barrier coatings concentrate the highest margin pool given qualification barriers for aviation turbine applications.
Japan's METI enforces JIS standards on thermal spray quality assurance, while China's MEE implements emissions controls that restrict traditional electroplating in the Yangtze River Delta. Australia's TGA regulates coating biocompatibility for medical device applications, creating differentiated compliance pathways across the region. Stakeholders must monitor evolving carbon border adjustments and substrate-specific qualification timelines as these determine which coating technologies gain preferential access to aerospace and energy sector procurement channels.
Market Dynamics
China's dual carbon goals and Japan's JIS quality mandates are compressing qualification timelines while rerouting procurement toward low-emission thermal spray processes across the Asia-Pacific manufacturing belt.
Growth Catalysts
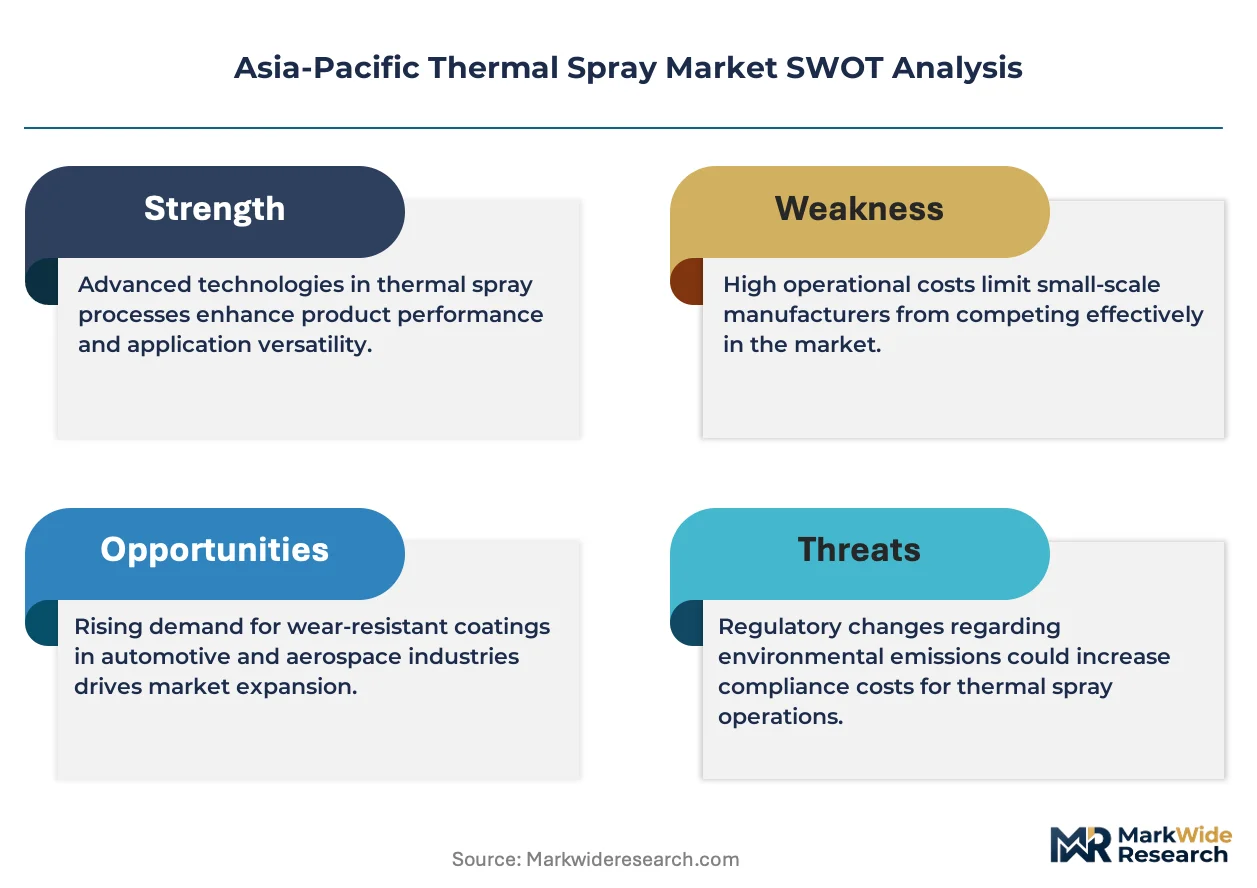
- MEE emissions controls:China's Ministry of Ecology and Environment restricts electroplating in the Yangtze River Delta, forcing manufacturers toward HVOF and plasma spray alternatives that eliminate hexavalent chromium.
- Aerospace OEM expansion:Japanese and South Korean turbine blade producers are localizing coating procurement to reduce lead times and secure supply chain resilience against geopolitical friction.
- Cold spray maturation:Australian and Japanese defense contractors now specify solid-state deposition for temperature-sensitive magnesium and aluminum substrates previously unsuitable for thermal processes.
Market Restraints
- Plasma spray powder concentration:High-purity yttria-stabilized zirconia and nickel superalloy feedstock production concentrates among Swiss and European suppliers, exposing Shanghai aerospace clusters to currency and shipping volatility.
- Capital intensity of automation:Robotic thermal spray cells with real-time coating thickness monitoring require seven-figure investments that mid-tier job shops in Vietnam and Indonesia cannot access.
- Substitute process competition:Physical vapor deposition and chemical vapor infiltration capture niche aviation applications where thermal spray cannot achieve sub-50-micron uniformity requirements.
Strategic Opportunities
- Indonesia's nascent aerospace MRO sector:Batam and Bintan Island maintenance facilities currently outsource turbine blade recoating to Singapore; captive thermal spray capacity would capture margin from expanding Southeast Asian fleet operations.
- Medical device biocompatibility:Australia's TGA and Japan's PMDA pathways for hydroxyapatite-coated orthopedic implants create differentiated revenue streams with pricing premiums above industrial wear coatings.
- Hybrid cold-spray additive manufacturing:Converging solid-state deposition with CNC machining enables near-net-shape repair of high-value titanium aerospace components without heat-affected zones.
Industry Challenges
- Certification timeline compression:Aviation turbine blade coating qualification under Japan's METI JIS standards and China's GB protocols now demands 18-24 months of thermal cycling and oxidation testing, locking working capital in pre-revenue development.
- Process control skill scarcity:Operators capable of calibrating plasma arc current, gas flow ratios, and particle velocity diagnostics across multiple substrate alloys command premiums that erode job shop margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Thermal Spray Market |
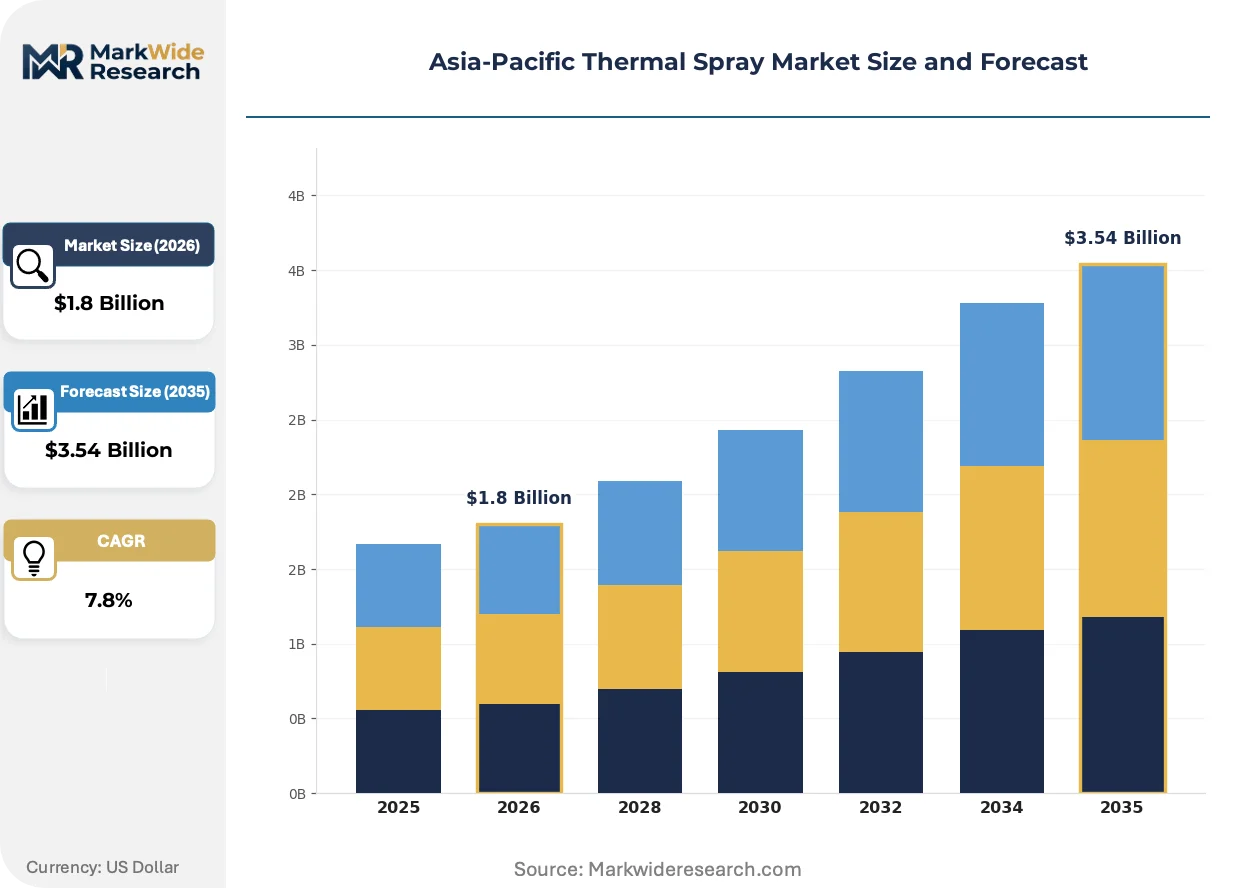
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasma Spray, Flame Spray, HVOF Spray, Cold Spray Technology: Thermal Barrier Coatings, Wear Resistant Coatings, Bond Coatings, Functional Coatings Application: Aerospace, Automotive, Medical Devices, Energy Sector End User Type: OEMs, Tier-1 Suppliers, Aftermarket Providers, Research Institutions |
| Companies Covered | Bodycote plc, Fujimi Incorporated, Oerlikon Metco, Carpenter Technology Corporation, Höganäs AB, Praxair Surface Technologies, H.C. Starck GmbH, Linde plc, Saint-Gobain S.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Thermal Spray Market Strategic Shifts
Digital process control and feedstock material science are converging to expand thermal spray into precision applications previously reserved for vacuum-based coating technologies.
Cold spray equipment is modularizing across Australian and Japanese defense supply chains. The technology deposits metallic powders at supersonic velocities without melting, preserving substrate microstructure. Naval aviation maintenance depots in Sydney and Nagoya now specify portable cold spray units for field repair of helicopter transmission housings. This capability is modularizing service offerings, allowing tier-two contractors to bid on depot-level maintenance previously requiring centralized facilities.
Japan's METI JIS H 8300 revision tightens porosity and bond strength testing protocols for thermal spray coatings in rotating machinery. The standard now mandates destructive testing samples from every production lot, not just qualification batches. South Korean power turbine rebuilders serving KEPCO utilities face the steepest compliance costs, driving consolidation among coating job shops capable of maintaining in-house metallography laboratories.
After-sales service unbundling disrupts traditional coating procurement in China's automotive belt. Shanghai and Jiangsu province manufacturers now separate coating application from equipment supply, soliciting standalone process recipes and parameter sets for in-house robotic cells. This behavior compresses margins for integrated solution providers while expanding addressable market for pure-play feedstock and software vendors serving captive coating operations at BYD and CATL suppliers.
Asia-Pacific Thermal Spray Market Segmentation
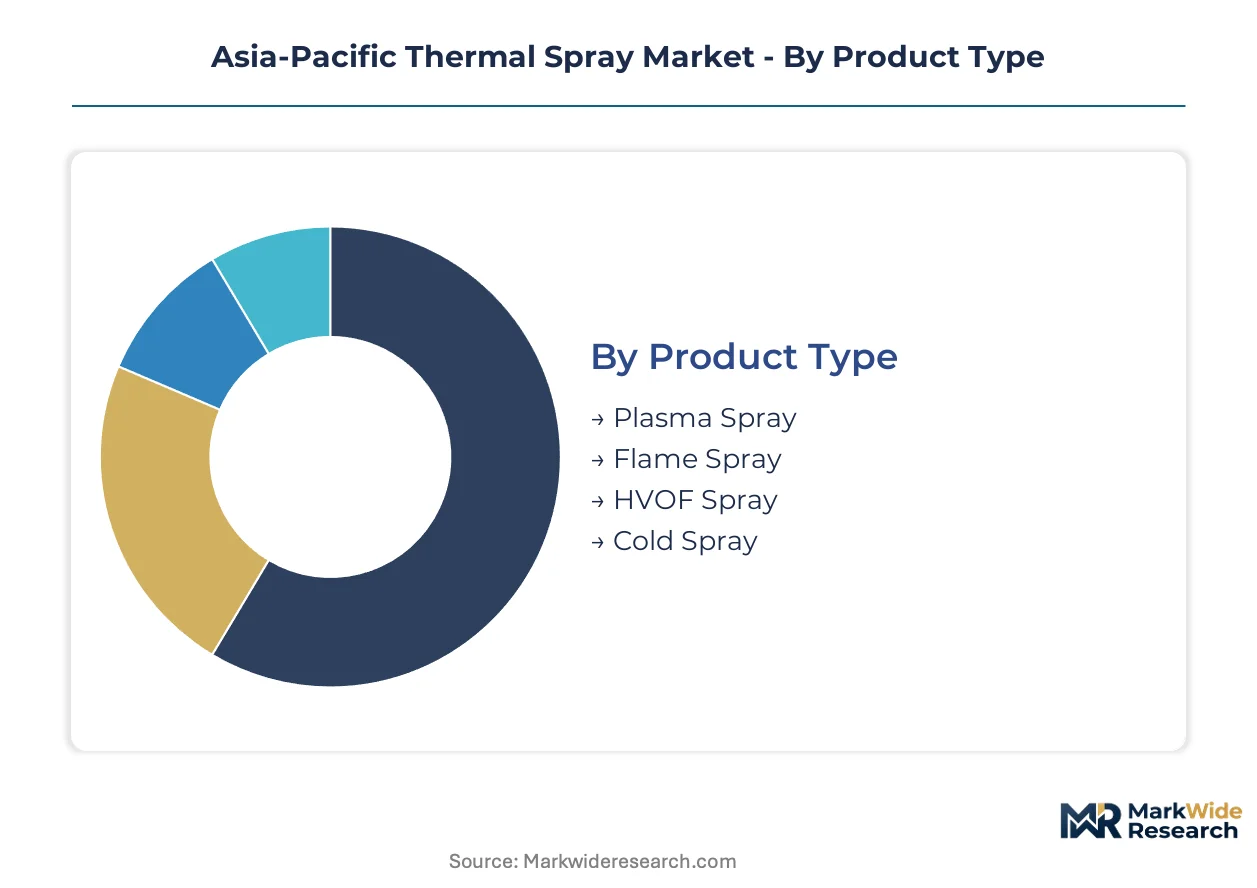
Thermal spray procurement patterns diverge sharply across equipment types, coating functions, and end-use verticals. Understanding these splits reveals where capital deployment concentrates and which technology trajectories command premium positioning.
Product Type:
Equipment replacement cycles and process upgrade timelines determine capital allocation across spray technologies, with aerospace and power generation clusters driving the most intensive refresh activity.
- Plasma Spray:Electric arc ionizes inert gas streams to achieve temperatures exceeding 15,000°C, enabling deposition of refractory ceramics and superalloys on turbine blades. Shanghai aerospace corridors and South Korean KEPCO supplier networks source plasma systems most intensively for thermal barrier coating refurbishment.
- HVOF Spray:Combustion-driven supersonic particle velocities produce dense, low-oxide metallic coatings with bond strengths exceeding 69 MPa. Yangtze River Delta automotive OEMs and Japanese precision machinery manufacturers specify HVOF for crankshaft and hydraulic rod restoration as MEE emissions rules restrict hexavalent chromium electroplating.
- Flame Spray:Acetylene-oxygen combustion remains the entry-level thermal spray configuration for mid-tier job shops. Vietnamese and Indonesian repair facilities deploy wire-fed flame systems for agricultural equipment and general industrial restoration where specification tolerances permit higher porosity.
- Cold Spray:Solid-state deposition accelerates metallic powders without melting, preserving substrate microstructure in temperature-sensitive magnesium and aluminum alloys. Australian naval aviation depots and Japanese defense contractors specify portable cold spray units for field-level transmission housing repairs.
Volume placements concentrate in Plasma Spray; the faster expansion belongs to Cold Spray.
Technology:
Coating function determines margin structure, with qualification-intensive applications commanding pricing premiums over commoditized wear protection.
- Thermal Barrier Coatings:Yttria-stabilized zirconia ceramic layers insulate gas turbine hot-section components against thermal fatigue and oxidation. Japanese METI JIS H 8300 qualification requirements and Chinese GB aerospace standards lock in 18-24 month certification timelines, creating steep barriers that protect incumbent suppliers serving IHI and Mitsubishi Heavy Industries turbine programs.
- Wear Resistant Coatings:Tungsten carbide-cobalt and chromium carbide-nickel chromium composites restore dimensional tolerances on rotating and sliding machinery. Jiangsu province automotive clusters and South Korean shipbuilding yards generate the highest throughput volumes for cylinder liner, piston ring, and propeller shaft refurbishment.
- Bond Coatings:MCrAlY (M = Ni, Co, or Ni+Co) interlayers anchor ceramic topcoats to superalloy substrates while providing oxidation resistance. Aerospace OEMs in Japan and South Korea specify bond coat thickness tolerances within 25 microns for blade coating durability.
- Functional Coatings:Electrical, biomedical, and corrosion-resistant layers serve specialized applications outside mechanical restoration. Australia's TGA-regulated hydroxyapatite coatings for orthopedic implants and China's electric vehicle battery contact plating represent emerging specification categories.
Revenue concentration sits with Thermal Barrier Coatings; Wear Resistant Coatings capture the highest unit volumes.
Application:
End-use sector dictates coating specification stringency, with aviation and medical applications imposing qualification regimes that industrial sectors do not replicate.
- Aerospace:Turbine blade thermal barrier systems, landing gear wear coatings, and engine component restoration dominate coating procurement value. Japanese and South Korean OEMs localize coating capacity to compress lead times and secure supply chain resilience.
- Automotive:Engine block cylinder liners, transmission synchronizer rings, and electric motor shaft coatings drive process standardization. Shanghai and Jiangsu manufacturing belts source captive HVOF and plasma capacity from BYD and CATL supplier ecosystems.
- Medical Devices:Hydroxyapatite-coated orthopedic implants and surgical instrument wear layers require biocompatibility validation under Japan's PMDA and Australia's TGA pathways. Pricing premiums exceed industrial coating tiers by substantial margins.
- Energy Sector:Power turbine blade recoating, nuclear component corrosion protection, and renewable energy infrastructure restoration generate recurring maintenance demand. KEPCO utility specifications and Chinese state-grid equipment standards shape regional procurement patterns.
Capital deployment tilts toward Aerospace; Medical Devices deliver the steepest margin expansion.
End User Type:
Customer organizational structure determines whether coating procurement flows through integrated supply chains or fragmented job shop networks.
- OEMs:Original equipment manufacturers in Japanese turbine production and Chinese electric vehicle manufacturing operate captive coating cells for production-line integration and quality control. METI JIS and GB standards compliance requires in-house metallography and destructive testing capabilities.
- Tier-1 Suppliers:Subcontracted component fabricators source coating services from qualified job shops or deploy robotic cells under license. South Korean automotive supplier networks and Australian mining equipment fabricators represent the densest tier-1 coating procurement clusters.
- Aftermarket Providers:Maintenance, repair, and overhaul operations perform blade recoating and component restoration outside original manufacturing channels. Indonesian Batam and Bintan Island facilities currently outsource turbine work to Singapore; captive capacity expansion would capture margin from Southeast Asian fleet growth.
- Research Institutions:National laboratories and university engineering departments validate novel feedstock formulations and process parameters. Australia's CSIRO and Japan's NIMS conduct cold spray and hybrid additive manufacturing research with defense funding support.
Procurement volume aggregates at Tier-1 Suppliers; OEMs are consolidating captive capacity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the Asia-Pacific thermal spray procurement network, with aerospace and automotive clusters in eastern China's manufacturing belt driving concentrated equipment and feedstock demand.
China
Yangtze River Delta automotive OEMs and Shanghai aerospace corridors source captive HVOF and plasma spray capacity for electric vehicle powertrains and turbine blade refurbishment. MEE emissions controls restrict hexavalent chromium electroplating across Jiangsu and Zhejiang provinces. BYD and CATL supplier ecosystems in Shenzhen and Ningbo deploy robotic coating cells under unbundled process recipes.
Japan
IHI and Mitsubishi Heavy Industries turbine programs demand thermal barrier coating qualification under METI JIS H 8300 protocols. Nagoya naval aviation depots specify portable cold spray units for field-level transmission housing repairs. Kansai and Chubu manufacturing belts concentrate aerospace OEM captive coating capacity to compress supply chain lead times.
South Korea
KEPCO utility specifications drive power turbine blade recoating demand among Seoul-based maintenance providers. MFDS pharmaceutical pathways create biocompatibility requirements for orthopedic implant coatings. Busan-Ulsan shipbuilding yards generate high-throughput wear coating volumes for propeller shaft and cylinder liner restoration.
Australia
CSIRO-funded defense contractors in Sydney adopt solid-state cold spray deposition for temperature-sensitive magnesium substrates. TGA-regulated hydroxyapatite coating pathways for orthopedic implants command pricing premiums above industrial tiers. Western Australian mining equipment fabricators source HVOF wear protection for dragline and shovel components.
Indonesia
Batam and Bintan Island MRO facilities currently outsource turbine blade recoating to Singapore suppliers. Captive thermal spray capacity expansion would capture margin from Southeast Asian commercial fleet growth. Jakarta-based tier-one automotive suppliers represent latent demand as domestic EV assembly scales.
Asia-Pacific Thermal Spray Market Competitive Environment
The competitive structure tilts toward diversified materials conglomerates with integrated feedstock-to-equipment portfolios. Swiss and European powder specialists dominate high-purity yttria-stabilized zirconia and nickel superalloy supply, exposing Asia-Pacific aerospace clusters to currency volatility. Three archetypes define positioning: captive coating cell operators serving OEM production lines, independent job shops qualifying under JIS and GB protocols, and modular cold spray service providers for defense field maintenance. Geographic expansion through licensed process recipes and backward integration into alloy powder production represent the dominant competitive moves.
Among diversified European materials groups, Oerlikon Metco and Höganäs AB exemplify the integrated feedstock archetype, anchoring plasma spray powder and high-purity alloy supply respectively. Saint-Gobain S.A. occupies a position within the specialized ceramic feedstock tier, serving power turbine rebuilders with thermal barrier coating materials. These three entities represent the concentration points through which Asia-Pacific coating demand flows.
| Leading Market Players |
|---|
| Bodycote plc |
| Fujimi Incorporated |
| Oerlikon Metco |
| Carpenter Technology Corporation |
| Höganäs AB |
| Praxair Surface Technologies |
| H.C. Starck GmbH |
| Linde plc |
| Saint-Gobain S.A. |
| Others |
Value Chain & Pricing Dynamics
Yttria-stabilized zirconia powder costs cascade through three distinct pricing tiers as Swiss and European suppliers anchor plasma spray feedstock production for Shanghai aerospace corridors and Japanese turbine OEMs.
Pricing Analysis
Turbine blade coating uptime guarantees anchor value-based pricing for thermal barrier systems serving IHI and Mitsubishi Heavy Industries programs. Price differentiation separates METI JIS H 8300-qualified production lots from uncertified job shop output, with bond strength testing protocols adding substantial compliance overhead. Cost compression in standard wear coatings intensifies as Yangtze River Delta automotive OEMs unbundle equipment supply from process recipes. Tier-1 suppliers in South Korean shipbuilding exhibit the highest price sensitivity, while medical device coatings under Australia's TGA pathways show the least.
Supply Chain Analysis
Regional distribution centers in Shanghai, Nagoya, and Seoul operate hub-and-spoke patterns for plasma spray powder and HVOF alloy feedstock. Supply concentrates in Switzerland, Sweden, and Germany for high-purity yttria-stabilized zirconia and nickel superalloy inputs. Raw material dependencies on cobalt, tungsten, and rare earth stabilizers expose coating job shops to commodity volatility. Single-source vulnerability from European powder specialists threatens aerospace cluster procurement. Distribution runs through captive OEM warehouses for automotive and turbine production lines, with independent job shops sourcing through authorized distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma spray powder production capacity constraints in Europe prop pricing power for qualified coating suppliers serving Asia-Pacific aerospace OEMs.
For Market Incumbents: Acquire metallography laboratory capabilities to compress JIS H 8300 and GB aerospace qualification timelines. Secure backward integration into nickel superalloy powder production to reduce currency exposure from Swiss suppliers. Defensive positioning requires channel control over robotic coating cell distribution in Jiangsu province automotive clusters against emerging domestic Chinese equipment vendors. For New Entrants and Emerging Players: The gap between premium METI-qualified thermal barrier coatings and economy-tier flame spray restoration opens entry paths for mid-tier HVOF job shops. Target Indonesian Batam and Bintan Island MRO facilities currently outsourcing turbine work to Singapore. Go-to-market leverage rests on portable cold spray service models for Australian and Japanese defense field maintenance contracts. For Investors and Strategic Acquirers: Cold spray equipment modularization reaching naval aviation depots in Sydney and Nagoya is the leading indicator that solid-state deposition will capture temperature-sensitive substrate applications. Long-term viability favors vertically integrated feedstock-to-equipment platforms with established aerospace qualification pathways. Acquisition screening should prioritize job shops with in-house destructive testing and existing IHI or KEPCO supplier status. Watch for MEE emissions enforcement tightening across Zhejiang province as signal for HVOF demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Powder Production | Captive nickel superalloy supply secures margin against Swiss currency volatility for Shanghai aerospace clusters. |
| Portable Cold Spray Service Deployment | Modular field repair units unlock Australian and Japanese defense maintenance contracts previously requiring centralized facilities. |
| METI JIS H 8300 Certification Investment | Destructive testing capability per production lot creates steep barriers protecting incumbent turbine blade coating suppliers. |
| Indonesian MRO Capacity Buildout | Batam and Bintan captive thermal spray captures margin from Southeast Asian commercial fleet expansion. |
| Hybrid Cold-Spray Additive Manufacturing | Near-net-shape titanium repair without heat-affected zones penetrates high-value aerospace component restoration. |
Study Parameters
Trade statistics from Japan Customs, EU export databases, and China General Administration of Customs formed the secondary backbone for feedstock flow analysis. Primary interviews with thermal spray equipment manufacturers, coating job shop operators, aerospace OEM procurement teams, and metallography laboratory directors combined with secondary validation across METI technical bulletins, JIS standard revisions, and MEE emissions filings. Bottom-up and top-down triangulation reconciled equipment shipment data with end-use demand estimates from turbine blade production and automotive coating cell deployment.
Bottom-up modeling built from individual spray technology segments while top-down cross-checks validated aggregate market scale against industrial coating services revenue. Segmentation dimensions included product type, coating function, end-use vertical, and customer organizational structure across the projection horizon. CAGRs derived from historical equipment replacement cycles and process upgrade timelines, with specific inputs from aerospace OEM localization trends and MEE regulatory enforcement patterns.
Inputs from Chinese provincial environmental bureaus and Japanese standards committees were available through the study window; gaps in real-time coating job shop capacity utilization introduce uncertainty bands around aftermarket service revenue estimates. Forecasts reflect documented assumptions regarding qualification timeline compression and cold spray technology maturation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Concrete Floor Coatings Market
Coatings
Solar Reflective Film Market
Coatings
Global Metal Coatings Market
Coatings
South Korea Protective Coatings Market
Coatings
Flexible Waterproof Coating Market
Coatings
North America Hydrocarbon Fire Intumescent Coating Services Market
Coatings
BPA-Free Coatings Market
Coatings
Global Conformal Coatings Market
Coatings
Global Pipe Coatings Market
Coatings
PACVD-Based Coatings Market
Coatings
Hull Coatings Market
Coatings
Russia Architectural Coatings Market
Coatings
Global Hydrophobic Coating Market
Coatings
Mexico Protective Coatings Market
Coatings
Protective Coatings Market
Coatings
Acrylic Coating Market