
 Global Conformal Coatings Market | 2026-2036
Global Conformal Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Conformal Coatings Market Foresight
The EU Green Deal is realigning material specifications across European electronics supply chains. Henkel AG & Co. KGaA leverages its adhesive chemistry heritage to dominate silicone-based formulations for automotive control modules. Dow anchors North American supply through captive silane feedstocks and integrated resin production. Shin-Etsu Chemical Co. Ltd differentiates via ultra-purity parylene deposition systems serving semiconductor packaging lines.
Conformal coatings are thin polymeric films applied to printed circuit boards and electronic assemblies, typically 25-250 microns thick, that cure to form dielectric barriers against moisture, ionic contamination, and thermal cycling. Acrylic formulations remain the volume leader due to low cost and simple solvent removal for rework, while parylene occupies the premium tier where vacuum-deposited pinhole-free coverage justifies unit costs tenfold above spray alternatives. Aerospace fabricators and defense contractors concentrate demand for urethane and epoxy systems that withstand MIL-STD-810G environmental stress screening.
REACH restricts certain isocyanate precursors in polyurethane coatings sold into Europe, forcing reformulation toward waterborne or UV-curable chemistries. The EPA governs volatile organic compound emissions from coating operations in the United States under NESHAP standards for electronics manufacturing. China's MEE enforces GB standards on hazardous substance limits in imported coatings for domestic electronics assembly. Stakeholders must track evolving substance restrictions while qualifying alternative chemistries that preserve adhesion and thermal performance under accelerated life testing protocols.
Market Dynamics
EU F-Gas Regulation solvent limits are forcing reformulation investments across European supply chains, compressing margins for acrylic and urethane producers while accelerating waterborne chemistry qualification timelines.
Growth Catalysts
- Avionics Reliability Mandates:Aerospace fabricators in Germany and France are expanding MIL-STD-810G-qualified coating procurement for next-generation flight control electronics.
- REACH-Driven Chemistry Innovation:Restrictions on isocyanate precursors are pulling polyurethane formulators toward UV-curable alternatives with equivalent thermal cycling performance.
- Parylene Deposition Scale-Up:Semiconductor packaging lines in Japan and South Korea are adopting ultra-purity vacuum deposition systems for pinhole-free barrier protection.
Market Restraints
- Captive Silane Feedstock Concentration:North American resin production depends on integrated silane supply controlled by a handful of petrochemical complexes along the US Gulf Coast.
- Acrylic Solvent Cost Volatility:Fluctuating petrochemical feedstock prices for methyl methacrylate monomers destabilize coating cost structures for electronics assemblers.
- Parylene Unit Cost Premium:Vacuum deposition equipment and dimer raw material costs sustain price multiples tenfold above spray-applied alternatives, limiting addressable market expansion.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for domestic PCB assembly are creating first-mover advantage for coating formulators establishing local technical service laboratories.
- UV-Curable Convergence:Combination of LED curing hardware and cationic epoxy formulations enables inline processing for automotive control module lines.
- China Dual Carbon Alignment:MEE enforcement of GB hazardous substance limits is advantaging low-VOC waterborne coatings in imported electronics assembly applications.
Industry Challenges
- Accelerated Life Testing Bottlenecks:Qualification protocols for new chemistries under thermal cycling and humidity stress require 12-18 month validation cycles, delaying revenue recognition.
- Application Technician Scarcity:Selective coating programming for robotic spray systems demands cross-trained automation specialists that contract manufacturers struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Conformal Coatings Market |
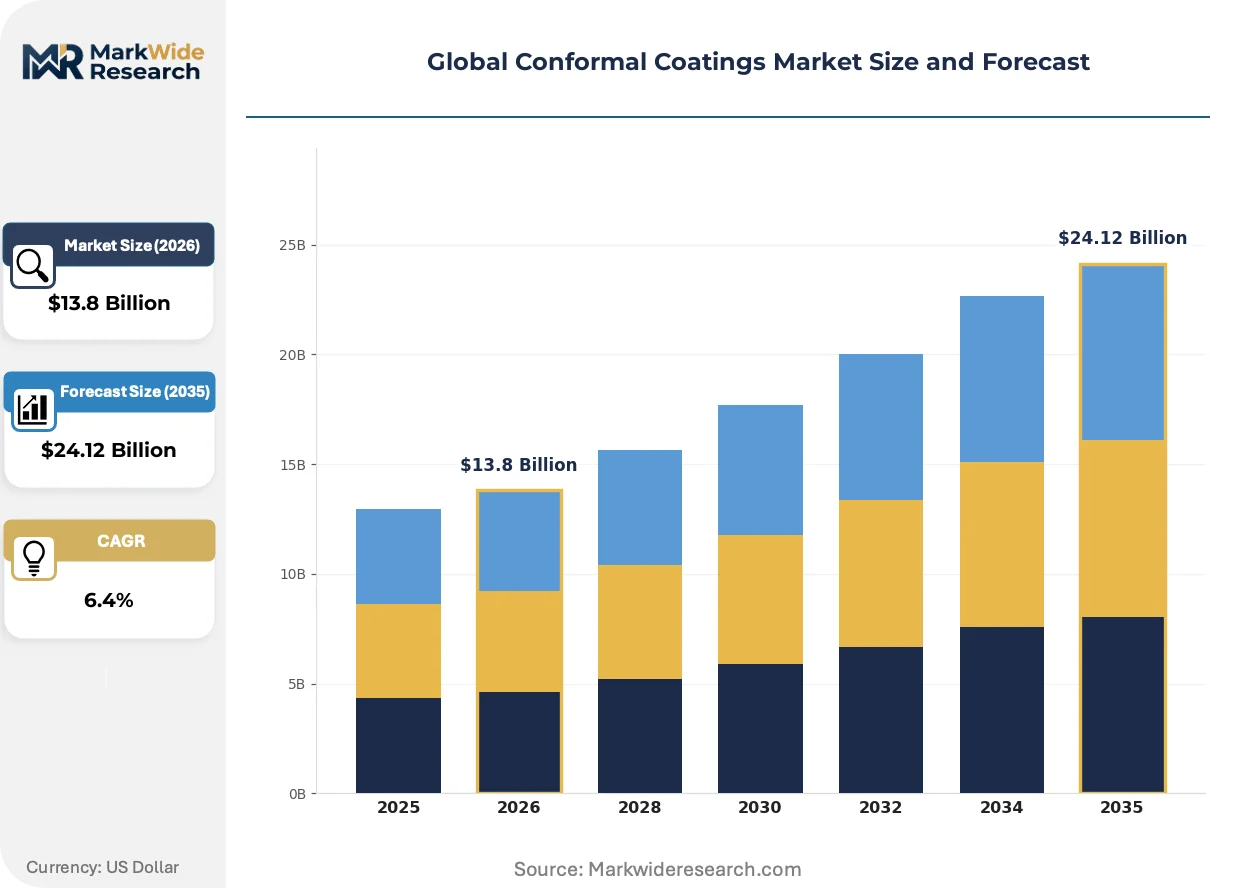
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Silicone, Urethane, Epoxy, Parylene, Polyurethane Application: Electronic Protection, Moisture Resistance, Corrosion Prevention, Insulation, Temperature Resistance, Chemical Shielding End User: Consumer Electronics, Aerospace Fabricators, Industrial Manufacturers, Defense Contractors, Telecommunications Providers, Instrumentation Makers Distribution Channel: Direct Sales, Distributors, E-Commerce Platforms, Contractors, OEM Partnerships, Retail Outlets |
| Companies Covered | H.B. Fuller Company, Illinois Tool Works, Henkel AG & Co. KGaA, Specialty Coating Systems, Dymax Corporation, Dow, Chase Corporation, Electrolube, Shin-Etsu Chemical Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Conformal Coatings Market Shifts & Advancements
Material science advances are compressing the performance gap between spray-applied and vapor-deposited coatings while regulatory chemistry restrictions are reshaping formulation priorities across all price tiers.
Nano-filled acrylic dispersions are converging with conventional solvent-borne systems to deliver moisture barrier performance approaching parylene levels at spray-application cost structures. Automotive Tier-1 suppliers in Germany are piloting these hybrid formulations for engine compartment control modules. The technology is converging with existing capital equipment to avoid deposition infrastructure replacement.
EPA NESHAP standards for electronics manufacturing VOC emissions are tightening permissible solvent content in coating operations across US-based PCB assembly facilities. Fabricators are responding by retrofitting spray booths with carbon capture systems or converting to waterborne acrylics with extended cure schedules. Defense contractors with MIL-spec legacy qualifications face the steepest compliance timelines.
Consolidated buying by automotive electronics assemblers is compressing supplier qualification cycles and unbundling technical service from material supply contracts. Tier-1 module suppliers now demand coating formulators maintain captive application engineering staff at their production facilities. This pattern is most pronounced in Germany's industrial electronics corridor and Michigan's automotive sensor manufacturing cluster.
Global Conformal Coatings Market Segmentation
Coating chemistry selection determines integration depth with substrate protection requirements. Application method and end-use reliability standards further stratify procurement patterns across electronics supply chains.
Product Type:
Standalone spray-applied systems dominate high-volume electronics assembly, while vapor-deposited films serve embedded semiconductor packaging where pinhole-free coverage is mandatory.
- Acrylic:Solvent-borne or waterborne polymethyl methacrylate formulations cure rapidly at ambient temperatures. Consumer electronics assemblers in China's Pearl River Delta specify acrylics for cost-sensitive smartphone PCB protection where reworkability outweighs thermal performance.
- Silicone:Elastomeric polydimethylsiloxane networks deliver operating temperature ranges from minus sixty-five to two hundred degrees Celsius. Automotive control module fabricators in Germany's industrial electronics corridor specify silicone for engine compartment thermal cycling endurance.
- Urethane:Cross-linked polyurethane films provide abrasion resistance for industrial automation equipment.
- Epoxy:Rigid thermoset barriers serve military avionics requiring MIL-STD-810G qualification.
- Parylene:Vacuum-deposited poly-para-xylylene delivers conformal coverage at micron-scale thickness for implantable medical devices.
- Polyurethane:Aliphatic formulations resist UV degradation in outdoor telecommunications infrastructure.
Acrylic leads volumes today; parylene is gaining share fastest in semiconductor packaging applications.
Application:
Functional requirements stratify by environmental exposure severity, with moisture and corrosion protection commanding premium formulation specifications.
- Electronic Protection:Dielectric barriers prevent short circuits from conductive contamination on densely populated PCBs. Aerospace fabricators in France mandate electronic protection coatings for flight control systems subject to MIL-STD-810G salt fog testing.
- Moisture Resistance:Hydrophobic surface chemistry blocks water vapor ingress to solder joints. Industrial manufacturers in Japan's automotive sensor cluster specify moisture-resistant silicone for humidity chamber reliability validation.
- Corrosion Prevention:Ionic contamination barriers protect copper traces in harsh chemical environments.
- Insulation:High dielectric strength coatings separate high-voltage traces in power electronics.
- Temperature Resistance:Thermal stability preserves film integrity across engine compartment thermal cycles.
- Chemical Shielding:Solvent-resistant barriers protect against fuel and hydraulic fluid exposure.
Electronic protection leads volumes today; moisture resistance is expanding most quickly in electric vehicle battery management systems.
End User:
Reliability certification requirements create tiered procurement patterns, with defense and aerospace mandating qualification protocols that exclude commodity formulations.
- Consumer Electronics:High-volume smartphone and wearable manufacturers prioritize reworkable acrylics with rapid cure cycles. Assembly lines in South Korea's Gyeonggi Province specify spray-applied coatings compatible with existing capital equipment.
- Aerospace Fabricators:Avionics OEMs require traceable lot control and thermal cycling documentation. Germany's flight control electronics suppliers specify urethane and epoxy systems qualified to MIL-STD-810G environmental stress screening.
- Industrial Manufacturers:Automation equipment builders specify abrasion-resistant formulations for factory floor exposure.
- Defense Contractors:Long-term storage stability requirements favor epoxy chemistries with decades-long shelf life validation.
- Telecommunications Providers:Outdoor infrastructure demands UV-stable aliphatic polyurethane for base station electronics.
- Instrumentation Makers:Laboratory and medical device manufacturers specify ultra-low outgassing parylene for sensitive optical assemblies.
Consumer electronics leads volumes today; aerospace fabricators show the steepest expansion trajectory for high-reliability qualified materials.
Distribution Channel:
Technical service integration separates direct supply relationships from transactional procurement, with complex formulations requiring application engineering support.
- Direct Sales:Coating formulators maintain captive technical service teams at major automotive Tier-1 facilities. Henkel's direct sales organization stations application engineers at BMW and Mercedes-Benz control module suppliers in Bavaria.
- Distributors:Regional inventory stocking supports just-in-time delivery for contract electronics manufacturers. Distributors in Michigan's automotive sensor cluster maintain local acrylic and silicone inventories for rapid line replenishment.
- E-Commerce Platforms:Standardized commodity formulations move through digital procurement for small-batch electronics prototyping.
- Contractors:Turnkey coating service providers operate selective spray equipment at customer facilities.
- OEM Partnerships:Strategic supply agreements align formulation development with next-generation product roadmaps.
- Retail Outlets:Aerosol can packaging serves maintenance and repair operations in industrial facilities.
Direct sales leads volumes today; e-commerce platforms are climbing the fastest for prototype and low-volume production procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Conformal coatings manufacturing originated in post-war US aerospace clusters before migrating to German automotive electronics corridors and East Asian semiconductor packaging hubs. Today production concentrates in four distinct national ecosystems shaped by regulatory chemistry constraints and end-use reliability mandates.
United States
Aerospace fabricators in Texas and California drive MIL-STD-810G-qualified urethane procurement for next-generation flight control systems. EPA NESHAP standards govern VOC emissions from coating operations across PCB assembly facilities in the Southwest. Defense contractors in Arizona face compressed compliance timelines for legacy epoxy qualifications.
Germany
Automotive Tier-1 suppliers in Bavaria specify silicone formulations for engine compartment thermal cycling endurance. EU F-Gas Regulation solvent limits force acrylic and urethane producers toward waterborne chemistry investments. Henkel stations captive application engineers at BMW and Mercedes-Benz control module suppliers across the industrial electronics corridor.
China
Consumer electronics assemblers in the Pearl River Delta specify reworkable acrylics for smartphone PCB protection. MEE enforces GB standards on hazardous substance limits in imported coatings for domestic assembly. Semiconductor packaging lines in Shanghai and Suzhou pilot ultra-purity deposition systems for pinhole-free barrier protection.
Japan
Automotive sensor manufacturers in Aichi Prefecture specify moisture-resistant silicone for humidity chamber reliability validation. METI industrial standards align with REACH-equivalent substance restrictions on coating precursors. Shin-Etsu anchors supply of vacuum deposition equipment serving semiconductor packaging lines in Kyushu.
South Korea
Electronics assemblers in Gyeonggi Province specify spray-applied coatings compatible with existing smartphone manufacturing capital equipment. MFDS chemical safety regulations track EU REACH substance restrictions for imported formulations. Samsung and LG display module suppliers concentrate demand for parylene deposition scale-up in Suwon.
Global Conformal Coatings Market Competitive Landscape
Premium-margin players sit above commodity-margin players across chemistry complexity and qualification documentation depth. The vendor base separates into three tiers: integrated petrochemical houses with captive silane feedstocks, specialized coating formulators with adhesive chemistry heritage, and deposition equipment specialists serving semiconductor packaging lines. Consolidation pressures concentrate among acrylic producers facing solvent cost volatility, while parylene deposition remains structurally fragmented. Dominant competitive moves include backward integration into resin production and captive technical service staffing at automotive Tier-1 facilities.
Within the integrated chemistry tier, Dow represents North American supply anchoring through captive silane feedstocks and resin production. Among European formulators, Henkel AG & Co. KGaA exemplifies the adhesive heritage archetype dominating silicone-based automotive specifications. At the deposition technology vector, Shin-Etsu Chemical Co. Ltd occupies a position serving ultra-purity semiconductor packaging requirements.
| Leading Market Players |
|---|
| H.B. Fuller Company |
| Illinois Tool Works |
| Henkel AG & Co. KGaA |
| Specialty Coating Systems |
| Dymax Corporation |
| Dow |
| Chase Corporation |
| Electrolube |
| Shin-Etsu Chemical Co. Ltd |
| Others |
Supply & Pricing Matrix
Application technician scarcity in Germany's industrial electronics corridor widens labor-cost differentials between premium parylene deposition and commodity spray-application tiers, compressing mid-market urethane margins while amplifying price spreads across qualification-grade segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates vacuum-deposited parylene systems from solvent-borne acrylics and waterborne hybrids. Price differentiation hinges on MIL-STD-810G certification depth and captive technical service bundling. Cost compression in mid-tier urethane formulations is intensifying because EU F-Gas Regulation solvent limits force reformulation investments. Consumer electronics assemblers in China's Pearl River Delta exhibit highest price sensitivity, while aerospace fabricators in France accept premium multiples for traceable lot documentation.
Supply Chain Analysis
India's PLI scheme local-content mandates are reshaping sourcing patterns for coating formulators establishing technical service laboratories in domestic PCB assembly corridors. Resin production concentrates in the United States, Germany, and Japan, with silane feedstock supply anchored in Gulf Coast petrochemical complexes. Raw material sourcing draws from methyl methacrylate monomers, polydimethylsiloxane precursors, and poly-para-xylylene dimers. Single-source vulnerability around captive silane supply creates structural risk for North American automotive Tier-1 procurement. Distribution runs through direct sales relationships with captive application engineers at major control module suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in conformal coatings rests on parylene deposition scale-up in semiconductor packaging and UV-curable chemistry substitution displacing solvent-borne systems facing regulatory restriction.
For Market Incumbents: Deepen backward integration into resin production to secure silane feedstock access against Gulf Coast supply concentration risk. Expand captive technical service staffing at automotive Tier-1 facilities in Germany's industrial electronics corridor to defend against unbundling pressure. Prioritize UV-curable formulation R&D to offset REACH-driven isocyanate precursor restrictions compressing polyurethane margins. For New Entrants and Emerging Players: Capture first-mover positioning in India's PLI scheme corridors by establishing local technical service laboratories ahead of domestic PCB assembly scale-up. Target moisture-resistant silicone specifications for electric vehicle battery management systems as the most penetrable premium segment. Lead with waterborne acrylic formulations aligned with China MEE GB hazardous substance enforcement to bypass incumbent solvent-borne legacy qualifications. For Investors and Strategic Acquirers: Specialized coating formulators with adhesive chemistry heritage are the most active acquirer targets in this space, given their dominance in automotive silicone specifications and direct sales channel control. Long-term viability favors deposition equipment specialists serving semiconductor packaging lines over commodity acrylic producers facing petrochemical feedstock volatility. Watch parylene unit cost convergence with nano-filled spray alternatives as the inflection signal for premium-tier displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive silane supply secures margin control against Gulf Coast petrochemical concentration. |
| UV-Curable Chemistry Qualification | REACH-compliant alternatives preserve polyurethane thermal cycling performance for automotive modules. |
| Captive Technical Service Expansion | Henkel-style application engineering staffing at BMW and Mercedes-Benz suppliers defends direct sales relationships. |
| Parylene Deposition Scale-Up | Ultra-purity vacuum systems serve Samsung and LG display module packaging in Suwon. |
| Waterborne Acrylic Transition | China MEE GB alignment advantages low-VOC formulations in imported electronics assembly. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with coating formulator R&D directors, automotive Tier-1 procurement leads, aerospace fabricator quality managers, and electronics contract manufacturer plant engineers. Secondary validation draws from EPA NESHAP filings, ECHA REACH substance restriction updates, MEE GB standard publications, and SEC 10-K disclosures from listed chemical companies. Bottom-up demand modeling triangulates against top-down supply-side capacity assessments across integrated petrochemical houses and specialized formulators.
Granularity-level modeling disaggregates volume and value across chemistry type, application method, end-use reliability tier, and regional regulatory cluster throughout the forecast period. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs include MIL-STD-810G qualification pipeline tracking, parylene deposition equipment installation counts, and PLI scheme beneficiary lists for India electronics manufacturing.
Feedstock price volatility, regulatory chemistry restriction acceleration, and qualification timeline extension are the dominant revision risks for coating demand projections across the analysis window. A small set of named triggers—EU F-Gas Regulation enforcement tightening, China dual carbon alignment pace, and semiconductor packaging line capex cycles—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Battery Coating Market
Coatings
FBE Coatings Market
Coatings
Camouflage Coatings Market
Coatings
Anti-Graffiti Coatings Market
Coatings
OEM Coatings Market
Coatings
Silicone Coating Market
Coatings
Global Fusion Bonded Epoxy Coatings Market
Coatings
Germany Protective Coatings Market
Coatings
E-Coat Market
Coatings
Global Photocatalytic Coatings Market
Coatings
Electrical Insulation Coatings Market
Coatings
Coating Binders Market
Coatings
Coating Thickness Gauge Market
Coatings
United Kingdom Automotive OEM Coatings Market
Coatings
Global Coated Steel Market
Coatings
Waterproof Coating Market