
 Physical Vapor Deposition (PVD) Coatings Market | 2026-2036
Physical Vapor Deposition (PVD) Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Physical Vapor Deposition (PVD) Coatings Market Analytics
Modular equipment configurations are decoupling capital expenditure from production scale in PVD system procurement. Veeco Instruments Inc. leverages its thin-film deposition expertise to anchor positions in electronics and data storage applications. Applied Materials, Inc. sustains technology leadership through R&D intensity across sputtering and evaporation platforms. Oerlikon Balzers competes through geographic dominance in Central European automotive and tooling markets.
Physical Vapor Deposition (PVD) coatings constitute thin-film layers deposited through vacuum-based processes where solid material transitions to vapor and condenses onto substrates, typically achieving thicknesses between 0.5 and 5.0 micrometers with exceptional adhesion and uniformity. These coatings primarily serve to enhance surface hardness, reduce friction, improve corrosion resistance, and extend component lifecycles across precision manufacturing sectors. Sputtering technology leads in electronics and semiconductor applications where film purity and step coverage command premium positioning, while hard coatings dominate cutting tool and aerospace segments where wear resistance drives replacement cycles and service intervals. Decorative coatings occupy mature margin pools in consumer goods and luxury automotive trim, though hybrid processes represent the fastest-growing technology category as manufacturers combine ion plating with evaporation to achieve multifunctional surface properties.
REACH regulations in Europe restrict hexavalent chromium and certain precursor chemicals in coating formulations, redirecting R&D investment toward compliant alternative materials. EPA emissions standards in the United States govern volatile organic compound releases from coating operations, while FDA device regulations classify PVD-coated surgical instruments under stringent biocompatibility protocols for medical applications. ISO 9001 and sector-specific quality certifications function as de facto market access requirements across aerospace and defense supply chains. Stakeholders must monitor evolving chemical restriction lists and qualification timelines to align capital deployment with regulatory trajectories.
Market Dynamics
Hybrid PVD process architectures are compressing equipment utilization rates while expanding addressable substrate geometries, forcing capital planners to recalibrate throughput assumptions against modular system configurations.
Growth Catalysts
- EU Green Deal emissions mandates:REACH-compliant chromium-free formulations are redirecting tooling and automotive coating contracts toward PVD alternatives in Germany's precision engineering corridor.
- Turbine blade thermal barrier demand:Aerospace component manufacturers in the United States are specifying PVD ceramic topcoats for next-generation gas turbine architectures.
- Ion plating integration:Hybrid deposition processes combining arc evaporation with magnetron sputtering are unlocking multifunctional surface properties for medical instrument manufacturers.
Market Restraints
- Precious metal input volatility:Titanium and zirconium target material prices fluctuate with aerospace alloy demand, compressing margin predictability for job-shop coaters.
- German equipment supply concentration:High-vacuum pump and power supply manufacturing clusters around Stuttgart create single-source vulnerability for system integrators.
- Hexavalent chromium substitution timelines:REACH Annex XVII restrictions on legacy hard chrome plating extend qualification periods for safety-critical aerospace components.
Strategic Opportunities
- Indian medical device manufacturing:CDSCO biocompatibility protocols for surgical instruments are creating first-mover advantage for PVD nitride coating specialists.
- China dual carbon goals:MIIT energy-efficiency mandates for cutting tool production are accelerating electric arc PVD adoption over chemical vapor deposition.
- Additive manufacturing convergence:Post-processing PVD of 3D-printed titanium aerospace brackets addresses surface roughness limitations without machining.
Industry Challenges
- Vacuum technician skill scarcity:Specialized plasma diagnostics and thin-film metrology expertise concentrates among German and Japanese equipment OEM training programs.
- ISO 9001 aerospace certification timelines:Nadcap accreditation for coating suppliers requires 18-24 month qualification cycles that delay contract commencement.
- Legacy ERP integration friction:Real-time thickness monitoring data from modern PVD chambers conflicts with established MES architectures at tier-two automotive suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Physical Vapor Deposition (PVD) Coatings Market |
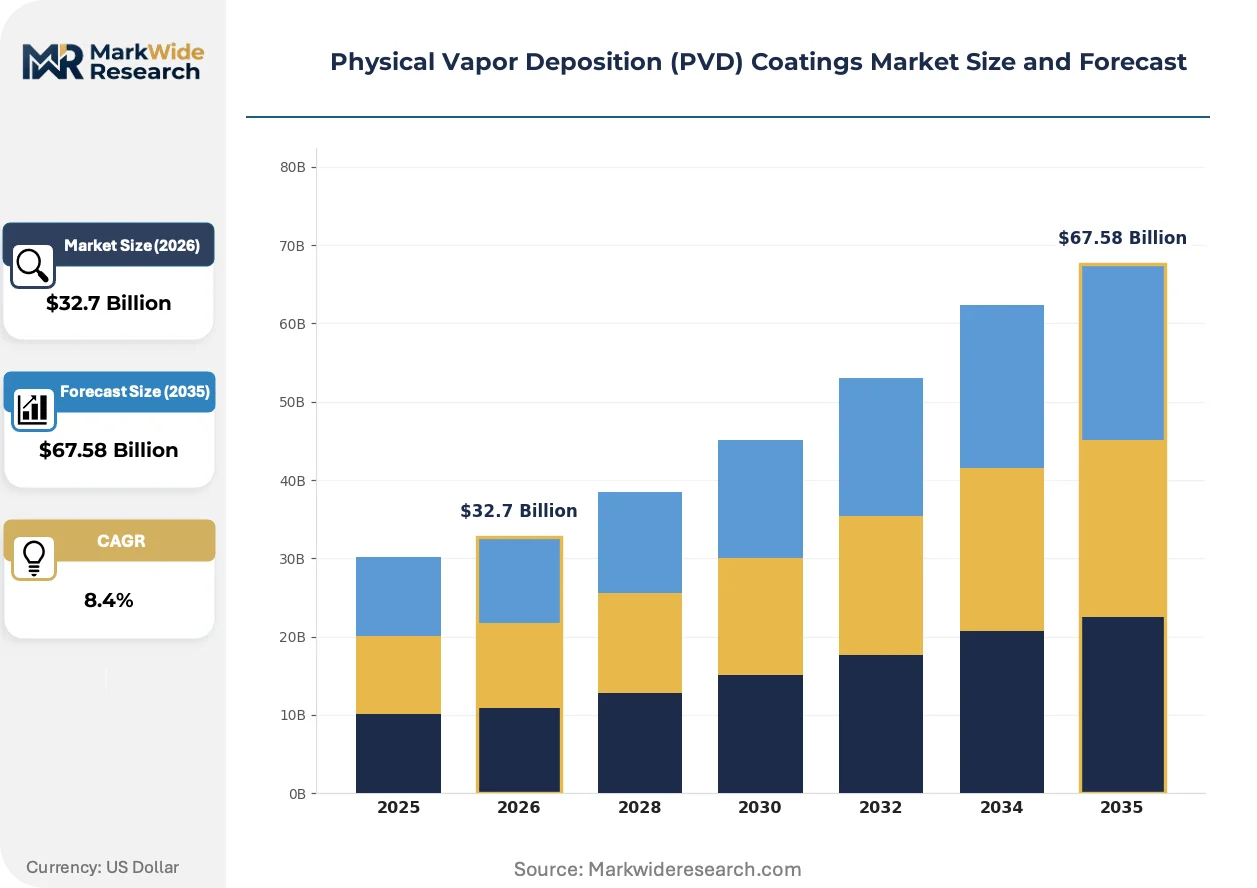
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $67.58 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
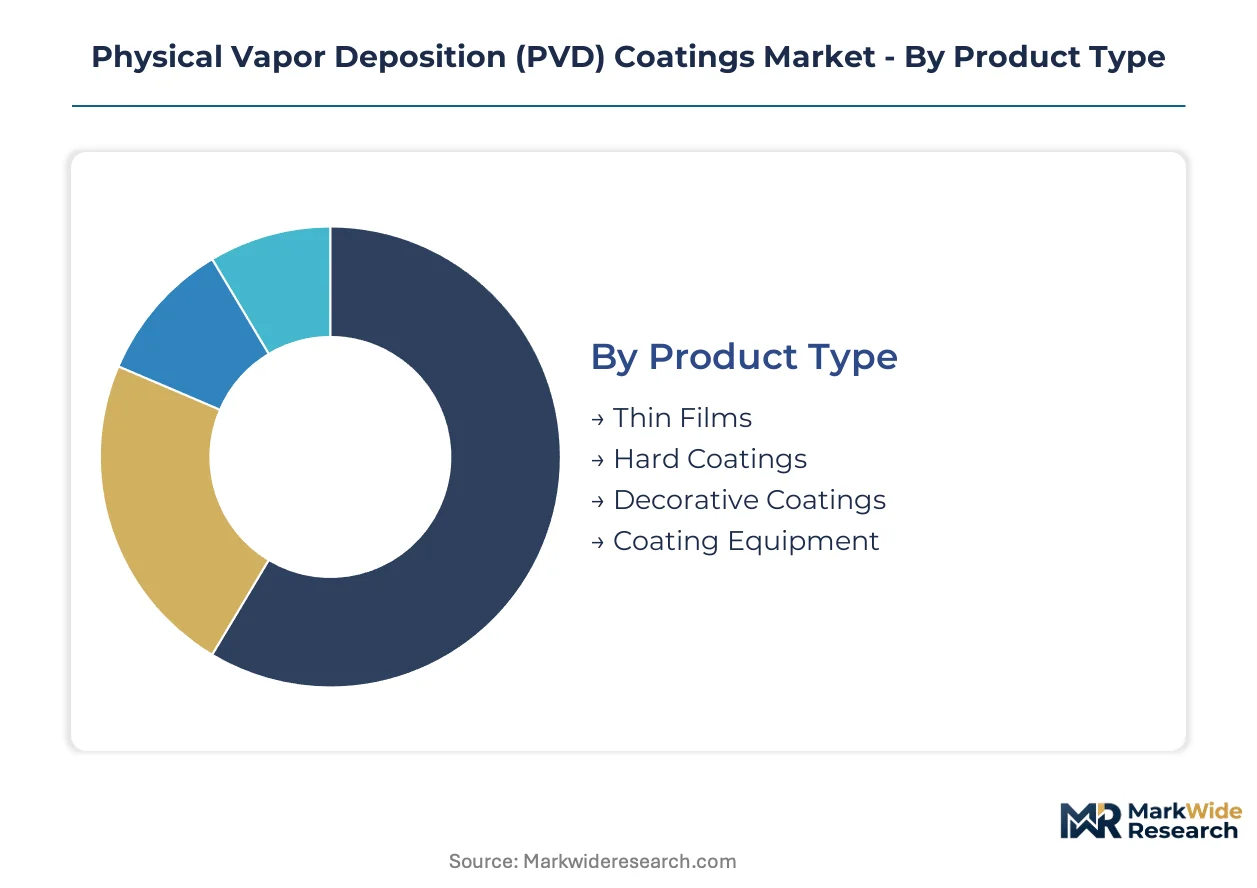
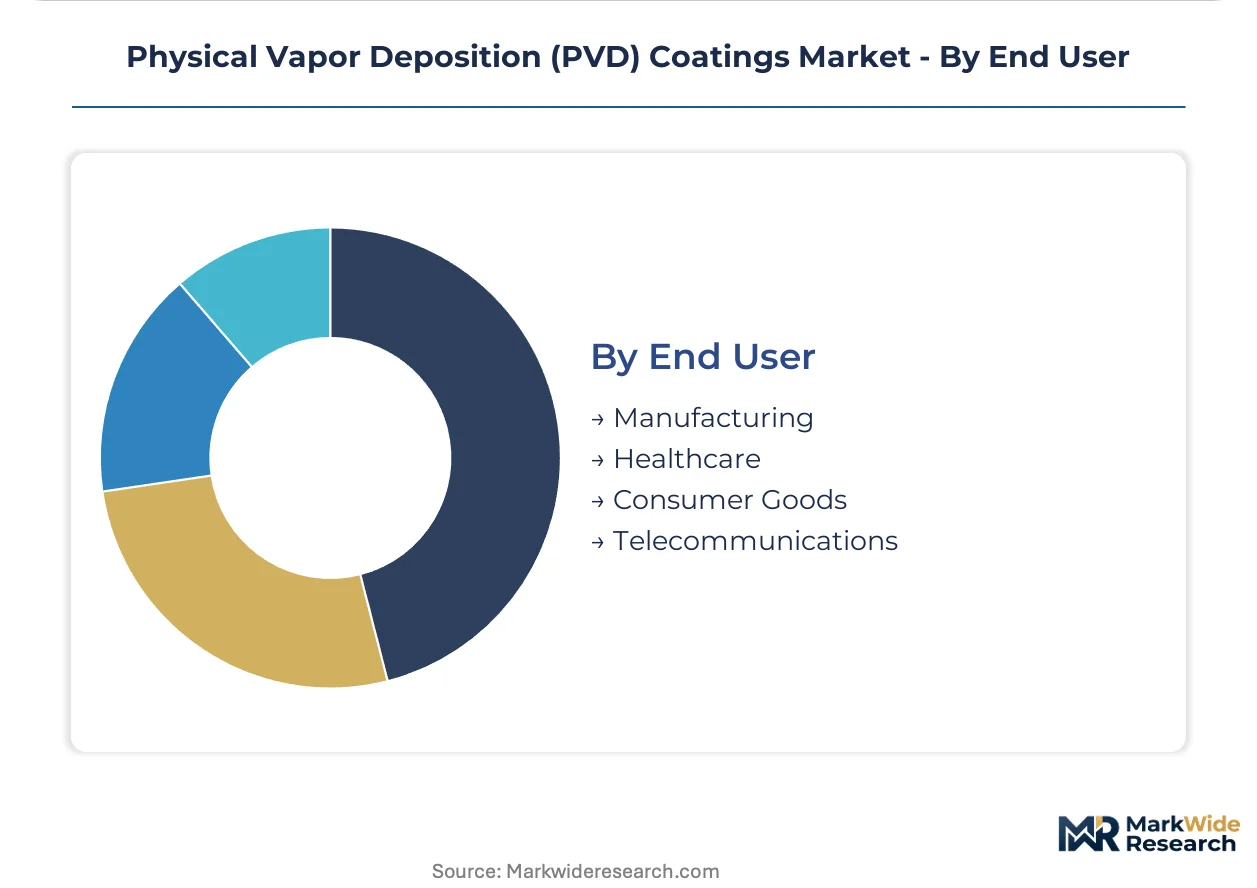
| Segmentation | Product Type: Thin Films, Hard Coatings, Decorative Coatings, Coating Equipment Application: Aerospace, Electronics, Automotive, Medical Devices Technology: Sputtering, Evaporation, Ion Plating, Hybrid Processes End User: Manufacturing, Healthcare, Consumer Goods, Telecommunications |
| Companies Covered | Veeco Instruments Inc., Advanced Energy Industries, Inc., Applied Materials, Inc., Denton Vacuum, Intevac, Inc., Oerlikon Balzers, Lam Research Corporation, Impact Coatings AB, ULVAC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Physical Vapor Deposition (PVD) Coatings Market Evolving Landscape
Process control digitization and substrate material diversification are collapsing traditional boundaries between decorative, functional, and protective coating categories.
High-power impulse magnetron sputtering (HiPIMS) is converging with conventional DC magnetron architectures to deliver ionized metal flux densities previously achievable only in cathodic arc systems. Cutting tool manufacturers in Japan and Germany are retrofitting existing production lines with HiPIMS sources to deposit aluminum chromium nitride coatings with superior oxidation resistance. This technology convergence is compressing the performance gap between premium and standard coating tiers while extending tool life benchmarks in high-speed machining applications.
EPA emissions standards governing volatile organic compound releases from coating operations are tightening enforcement protocols for hexavalent chromium electroplating facilities in the United States. Surface finishing shops serving automotive and aerospace supply chains face capital allocation decisions between emission control retrofits and PVD process conversion. The regulatory pressure is accelerating equipment replacement cycles most visibly among Midwestern US job shops supplying drivetrain components to Detroit-based OEMs.
Specification-driven procurement is consolidating vendor relationships among tier-one aerospace suppliers who now require coating partners to maintain Nadcap accreditation alongside ISO 9001 certification. Long-term service agreements with guaranteed thickness uniformity and adhesion test protocols are displacing transactional spot-buying for turbine blade and landing gear contracts. This contracting model shift concentrates procurement authority at Boeing and Airbus tier-one facilities in Toulouse, Hamburg, and Charleston.
Physical Vapor Deposition (PVD) Coatings Market Segmentation
PVD coating procurement decisions diverge sharply across segment boundaries, with aerospace and medical applications demanding Nadcap and FDA-validated workflows while decorative and consumer segments prioritize throughput economics. Understanding these certification tiers enables equipment vendors to configure pricing and service models that align with customer qualification burdens.
Product Type:
Certification requirements intensify with coating functional criticality—thin films for semiconductors face ISO 14644 cleanroom protocols, while hard coatings for cutting tools navigate REACH substance restrictions.
- Thin Films:Aluminum, titanium nitride, and oxide layers deposited at sub-micron thicknesses for semiconductor interconnects and optical filters. Demand concentrates in South Korean memory fabs and Taiwanese foundries where film purity dictates yield economics and equipment qualification cycles extend 12-18 months.
- Hard Coatings:Multilayer ceramic stacks of titanium aluminum nitride and chromium nitride engineered for extreme wear resistance. German automotive tool manufacturers in Stuttgart and Munich specify these for high-speed machining centers, with REACH Annex XVII chromium restrictions accelerating substitution away from electroplated alternatives.
- Decorative Coatings:Titanium nitride and zirconium nitride finishes for luxury watch cases and automotive trim.
- Coating Equipment:Vacuum chambers, magnetron sources, and process control systems.
Leading the category by volume: Hard Coatings. Growing fastest: Thin Films.
Application:
End-use margins determine acceptable coating cost thresholds, with medical and aerospace tolerating 10-20x per-unit costs versus automotive decorative applications.
- Aerospace:Thermal barrier ceramics and erosion-resistant superalloy coatings for turbine blades and combustion hardware. US engine manufacturers in Connecticut and Ohio specify electron beam PVD for thermal protection systems, with FAA airworthiness certification requiring 24-36 month material qualification protocols.
- Electronics:Copper seed layers, diffusion barriers, and magnetic thin films for data storage and interconnects. Japanese hard disk drive manufacturers in Nagoya and Chinese semiconductor packaging facilities in Suzhou drive sputtering equipment demand where film uniformity specifications measure in angstroms.
- Automotive:Wear-resistant coatings for fuel injection components and decorative finishes for interior trim.
- Medical Devices:Biocompatible nitride and oxide coatings for surgical instruments and implants.
Aerospace commands premium pricing per square centimeter. Electronics generates highest absolute equipment demand.
Technology:
Capital intensity and operator skill requirements stratify technology selection, with arc evaporation dominating high-volume tooling and sputtering controlling precision electronics.
- Sputtering:Momentum-transfer deposition from magnetron-confined plasma discharges delivering exceptional film density and composition control. Magnetron configurations in Japanese and German equipment anchor semiconductor and data storage manufacturing where step coverage over high-aspect-ratio features determines device performance.
- Evaporation:Thermal or electron-beam vaporization of source materials in high-vacuum environments. Chinese cutting tool manufacturers adopt electric arc evaporation for titanium aluminum nitride deposition, with MIIT energy-efficiency mandates favoring PVD over chemical vapor deposition alternatives.
- Ion Plating:Plasma-assisted deposition with energetic ion bombardment for enhanced adhesion.
- Hybrid Processes:Combined arc and sputter architectures for multifunctional coatings.
Sputtering retains technology leadership in value terms. Hybrid Processes climbing the fastest as medical instrument manufacturers seek combined wear and biocompatibility properties.
End User:
Procurement authority centralizes differently across end-user categories—healthcare consolidates through group purchasing organizations while manufacturing fragments across tiered supply chains.
- Manufacturing:Cutting tool producers, precision component fabricators, and industrial equipment OEMs integrating coatings into production workflows. German machine tool builders in Baden-Württemberg specify coating service partnerships with guaranteed 48-hour turnaround for insert reconditioning.
- Healthcare:Surgical instrument manufacturers and orthopedic implant suppliers requiring biocompatibility validation. Indian medical device producers in Ahmedabad and Pune navigate CDSCO registration requirements for nitride-coated instruments, with first-mover coating specialists capturing contract manufacturing relationships.
- Consumer Goods:Watchmakers, eyewear manufacturers, and luxury automotive trim suppliers.
- Telecommunications:Optical component and RF device manufacturers.
Manufacturing dominates absolute coating consumption. Healthcare presents steepest expansion trajectory as surgical instrument outsourcing accelerates in India and Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures the majority of high-vacuum PVD equipment while the United States and China consume the largest coating volumes. Production clusters in Stuttgart and Munich export systems worldwide. Demand concentrates in aerospace hubs and electronics manufacturing corridors.
United States
Connecticut and Ohio aerospace manufacturers specify electron beam PVD for turbine blade thermal barriers. FAA airworthiness certification mandates 24-36 month material qualification protocols that delay new coating adoption. Pratt & Whitney and GE Aviation facilities in Hartford and Cincinnati anchor the domestic thermal barrier coating supply chain.
Germany
REACH Annex XVII restrictions on hexavalent chromium redirect automotive tooling contracts toward PVD alternatives. The EU Green Deal tightens permissible emissions from coating processes in precision engineering corridors. Stuttgart and Munich host concentrated clusters of high-vacuum pump and power supply manufacturers serving global system integrators.
China
MIIT energy-efficiency mandates for cutting tool production accelerate electric arc PVD adoption over chemical vapor deposition. Dual carbon goals pressure manufacturers to reduce process energy intensity. Suzhou semiconductor packaging facilities and Nagoya-connected hard disk drive suppliers drive sputtering equipment demand for magnetic thin films.
Japan
Hard disk drive manufacturers in Nagoya specify magnetron sputtering configurations where film uniformity measures in angstroms. METI industrial technology roadmaps prioritize thin-film deposition advances for data storage applications. Chubu region equipment vendors supply precision sputtering systems to Taiwanese foundries and South Korean memory fabs.
India
CDSCO biocompatibility protocols for surgical instruments create first-mover advantage for PVD nitride coating specialists. Medical device producers in Ahmedabad and Pune navigate registration requirements for coated instruments. Contract manufacturing relationships consolidate around coating service providers with validated FDA-equivalent workflows.
Physical Vapor Deposition (PVD) Coatings Market Competitive Landscape
The competitive structure tilts toward diversified equipment manufacturers with thin-film deposition heritage. Market positions stratify across three tiers: integrated semiconductor equipment conglomerates, specialized vacuum coating system builders, and regional service-focused coaters. Technology licensing agreements and modular equipment configurations constitute the dominant competitive moves as vendors decouple capital expenditure from production scale.
Among diversified instrumentation specialists, Veeco Instruments Inc. and Applied Materials, Inc. exemplify archetypes with established electronics and data storage positioning. Oerlikon Balzers occupies a position within the European precision coating tier, representing geographic concentration in Central European automotive and tooling markets. These three anchors illustrate how heritage in adjacent deposition technologies translates into PVD market presence without requiring pure-play specialization.
| Leading Market Players |
|---|
| Veeco Instruments Inc. |
| Advanced Energy Industries, Inc. |
| Applied Materials, Inc. |
| Denton Vacuum |
| Intevac, Inc. |
| Oerlikon Balzers |
| Lam Research Corporation |
| Impact Coatings AB |
| ULVAC |
| Others |
Value Network & Pricing Analysis
Tier-one aerospace suppliers in Connecticut and Ohio command contract-based long-term offtake pricing with guaranteed thickness uniformity protocols, while job-shop coaters in the Midwest face transactional spot-buying pressure from Detroit-based OEMs. This buyer concentration bifurcation creates divergent margin structures across the coating service landscape.
Pricing Analysis
Margin tightening in standard hard coatings reflects titanium and zirconium target material volatility tied to aerospace alloy demand. Three-tier pricing structure across Nadcap-accredited premium, ISO 9001-certified standard, and uncertified economy levels separates aerospace contracts from automotive decorative work. Cost-down pressure on economy-tier decorative finishes accelerates because Chinese manufacturers flood consumer goods segments with titanium nitride alternatives. Medical device manufacturers exhibit lowest price sensitivity due to FDA biocompatibility validation requirements, while automotive trim suppliers negotiate aggressively on per-unit coating costs.
Supply Chain Analysis
Nadcap and FDA-equivalent qualification gating concentrates certified coating capacity among German equipment OEMs and Japanese magnetron source manufacturers. High-vacuum pump fabrication clusters in Stuttgart, power supply production in Munich, and sputtering target refining in Japan feed global system integrators. Raw material dependencies on titanium sponge, chromium metal, and rare-earth magnet materials rest on aerospace alloy demand cycles. Single-source vulnerability in German vacuum component manufacturing threatens equipment lead times. Distribution runs through direct equipment sales for large semiconductor fabs and regional service networks for job-shop coaters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII restrictions and FAA airworthiness certification timelines are consolidating procurement authority among accredited suppliers, forcing unqualified coaters toward exit or acquisition.
For Market Incumbents: Acquire specialized vacuum technician training programs to lock in scarce plasma diagnostics expertise before Japanese and German OEMs expand certification capacity. Deepen backward integration into titanium target material refining to offset aerospace alloy demand volatility. Secure long-term service agreements with Boeing and Airbus tier-one facilities in Toulouse, Hamburg, and Charleston before qualification cycles extend further.
For New Entrants and Emerging Players: Launch via contract manufacturing partnerships with Indian medical device producers in Ahmedabad and Pune navigating CDSCO biocompatibility protocols. Target surgical instrument coating white space where FDA-equivalent validation creates barrier-protected margin pools. Penetrate through hybrid process specialization combining arc evaporation with magnetron sputtering for multifunctional medical surfaces.
For Investors and Strategic Acquirers: The window for entry favors mid-cap coating specialists with existing Nadcap accreditation and unfilled capacity in aerospace corridors. Long-term viability hinges on qualification moats extending 18-36 months that deter new competition. Watch for MIIT energy-efficiency mandate acceleration in China as signal for electric arc PVD equipment demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Target Material Refining | Captive titanium sponge supply insulates margins from aerospace alloy demand swings. |
| Nadcap Accreditation Investment | FAA-mandated qualification protocols lock out unaccredited competitors from turbine blade contracts. |
| Hybrid Process Technology Licensing | Medical instrument manufacturers seek combined wear resistance and biocompatibility properties. |
| Regional Service Network Expansion | 48-hour turnaround guarantees for German machine tool builders in Baden-Württemberg capture reconditioning volume. |
| CDSCO-Compliant Workflow Development | First-mover coating specialists capture contract manufacturing relationships with Indian surgical instrument exporters. |
Research Methodology
Multi-period observation of equipment utilization rates, certification backlog durations, and target material price indices anchored the trend analysis, supplemented by interviews with vacuum chamber OEM technical directors, coating service plant managers, aerospace tier-one procurement leads, and semiconductor fab process engineers. Secondary validation drew from SEC filings of deposition equipment manufacturers, ECHA REACH restriction updates, FAA airworthiness directives, and customs data on vacuum pump imports. Bottom-up coating volume estimates triangulated against top-down equipment shipment values.
The input-output matrix mapped sputtering source configurations to substrate throughput capacities across thin-film, hard coating, and decorative applications. Segmentation dimensions included coating functional criticality, end-use certification tier, technology capital intensity, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and substitution elasticity modeling. Forecast inputs incorporated MIIT energy-efficiency mandate compliance timelines and REACH Annex XVII restriction phase-in schedules.
Raw material price volatility, regulatory qualification timeline extensions, and vacuum technician labor scarcity are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding equipment modularity adoption rates and hybrid process technology diffusion. A model refresh is warranted upon material change in FAA or EASA airworthiness certification protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Silicate Coatings Market
Coatings
Solvent Borne Coatings Market
Coatings
Glazes Market
Coatings
Global Heat Resistant Coatings Market
Coatings
Epoxy Surface Coatings Market
Coatings
Global Industrial Floor Coatings Market
Coatings
United States Automotive OEM Coatings Market
Coatings
ASEAN Automotive OEM Coatings Market
Coatings
Global Diamond Coatings Market
Coatings
South Korea Automotive OEM Coatings Market
Coatings
Global Graphite Coatings Market
Coatings
North America Powder Coatings Market
Coatings
Vinyl Surface Coatings Market
Coatings
Automotive Conformal Coatings Market
Coatings
Technical Coil Coatings Market
Coatings
Egyptian Protective Coatings Market