

Conductive Shielding Coatings for Battery Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Conductive Shielding Coatings for Battery Management Systems Market Insights
Electric vehicle battery packs is expanding as the dominant application vertical, displacing consumer electronics batteries as the primary demand anchor. Henkel AG & Co. KGaA leverages its adhesive-coating hybrid portfolio to dominate European OEM supply chains. 3M sustains technology leadership in multi-layer electromagnetic interference shielding formulations. PPG Industries anchors North American production through captive supply of thermal management coatings for Detroit-based vehicle assemblers.
Conductive shielding coatings for battery management systems are thin-film conductive layers, typically 25–100 microns thick, comprising silver, copper, or carbon-filled polymer matrices applied via spray, dip, or selective deposition processes to suppress electromagnetic radiation and electrostatic discharge in high-voltage battery architectures. Their primary purpose is ensuring signal integrity and thermal stability in densely packed lithium-ion cell configurations where parasitic currents threaten BMS reliability. Silver coatings occupy the premium tier due to unmatched conductivity and oxidation resistance, while carbon-based coatings represent the fastest-growing category as battery manufacturers seek cost-effective shielding for mass-market EV platforms. Electromagnetic interference shielding technology leads in revenue contribution, though thermal management coating is concentrating margin pools as pack energy densities climb.
The FCC enforces electromagnetic compatibility thresholds for electronics sold in the United States, directly shaping coating performance specifications that BMS suppliers must certify. REACH and the EU AI Act impose substance restriction and supply chain transparency requirements that filter raw material sourcing decisions across European coating value chains. China's GB standards and MIIT technical regulations mandate shielding effectiveness testing for domestically manufactured battery systems, creating a tri-regional compliance burden that coating formulators must navigate simultaneously. Stakeholders must monitor divergence between regional electromagnetic compatibility test protocols, as misalignment threatens to fragment product platforms and inflate qualification costs for multinational battery programs.
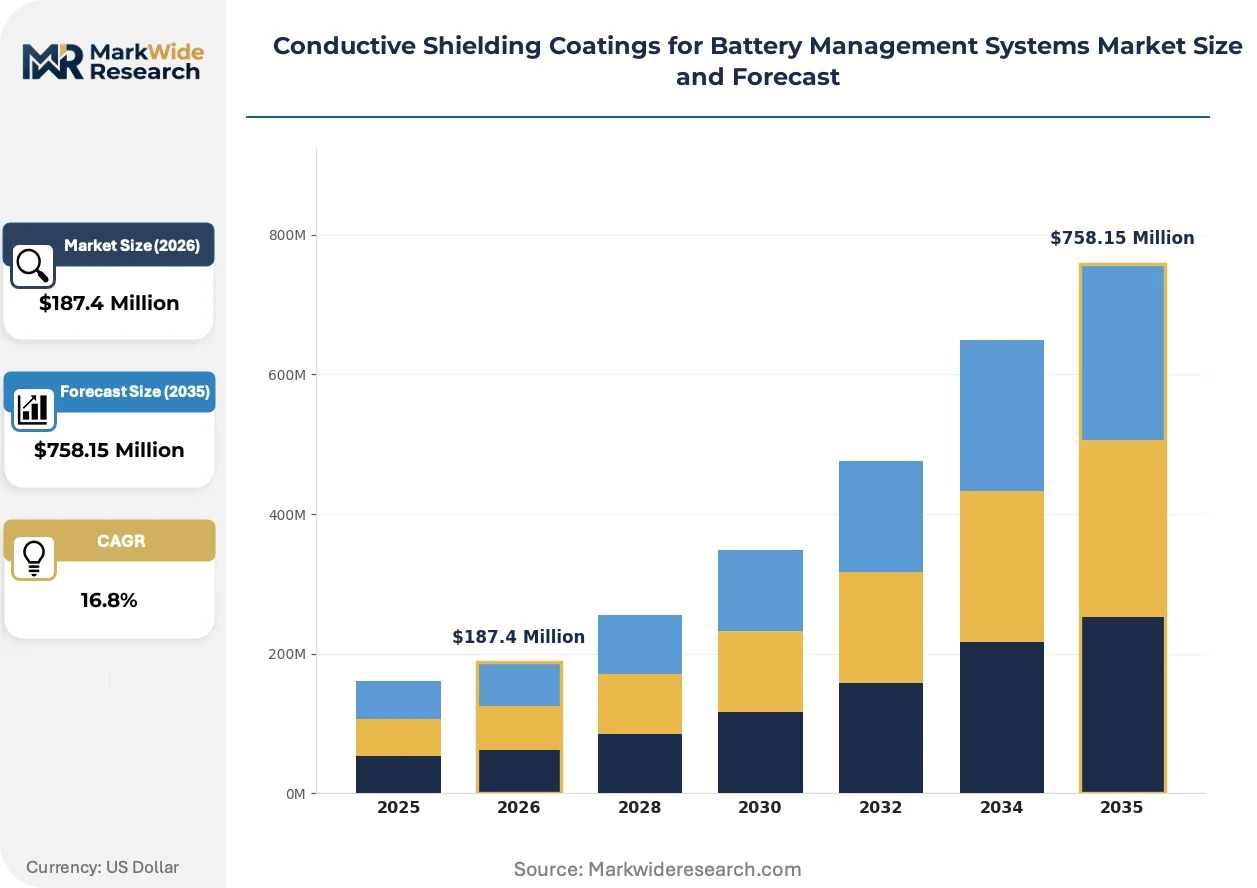
Market Dynamics
Electromagnetic compatibility mandates from the FCC and EU AI Act are forcing simultaneous coating platform upgrades across multinational battery programs, compressing qualification timelines while expanding performance specification ranges.
Growth Catalysts
- EV platform scaling:Battery pack architectures for export-bound electric vehicles are driving volume demand for shielded BMS configurations, particularly from Chinese domestic manufacturers expanding production capacity.
- REACH substance transparency:European supply chain disclosure requirements are filtering raw material sourcing decisions toward certified coating formulators with documented substance compliance.
- Silver coating performance tiers:Unmatched conductivity and oxidation resistance in silver-filled polymer matrices are sustaining premium positioning for high-reliability applications despite carbon-based alternatives entering mass-market segments.
Market Restraints
- Silver price volatility:Precious metal input costs fluctuate with commodity markets, compressing margin predictability for premium coating tiers and forcing hedging overhead.
- Supply concentration in East Asian chemical precursors:Carbon nanotube and specialized polymer resin production clusters in China and South Korea create geographic single-point vulnerability for carbon-based coating formulations.
- Tri-regional test protocol divergence:Misalignment between FCC electromagnetic compatibility thresholds, EU AI Act transparency mandates, and China's GB standards fragments product platforms and inflates multinational qualification costs.
Strategic Opportunities
- India battery manufacturing:PLI scheme incentives for domestic cell and pack production are creating first-mover advantage for coating suppliers establishing local application partnerships.
- Thermal-management coating convergence:Integration of electromagnetic interference suppression with active thermal regulation functions addresses climbing pack energy densities in a single deposition process.
- Direct OEM technical partnerships:Bypassing traditional tiered distributor networks through captive R&D collaboration agreements accelerates specification lock-in and reduces competitive bidding exposure.
Industry Challenges
- Multi-regulatory certification timelines:Simultaneous FCC, REACH, and GB standard qualification processes extend product launch cycles and strain technical documentation resources.
- Deposition equipment capex intensity:Selective deposition and precision spray systems for micron-thick conductive layers require substantial capital commitment before volume contracts materialize.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conductive Shielding Coatings for Battery Management Systems Market Trends and Innovations
Coating technology is absorbing functional integration pressures as battery architectures demand simultaneous electromagnetic, thermal, and mechanical performance from single-layer deposition systems.
Carbon-filled polymer matrices are absorbing cost-reduction mandates from mass-market EV platforms while maintaining shielding effectiveness targets. Tier-two battery manufacturers in China and Southeast Asia are adopting these formulations at accelerating rates. The technology is absorbing volume that silver coatings previously captured, compressing premium-tier addressable market scope.
REACH substance restriction expansions are compelling reformulation of legacy conductive fillers across European coating value chains. ECHA candidate list updates are triggering supply chain audits and alternative material qualification programs. Battery pack assemblers serving EU export markets are responding by consolidating supplier bases toward formulators with pre-certified substance portfolios.
Buyer concentration among top-tier EV OEMs is compressing coating procurement into multi-year framework agreements with technical performance guarantees. Traditional spot-market purchasing through chemical distributors is retreating to aftermarket and repair segments. This pattern is most visible in Germany and South Korea, where domestic vehicle assemblers have established captive coating supply relationships with technical co-development clauses.
Conductive Shielding Coatings for Battery Management Systems Market Segmentation
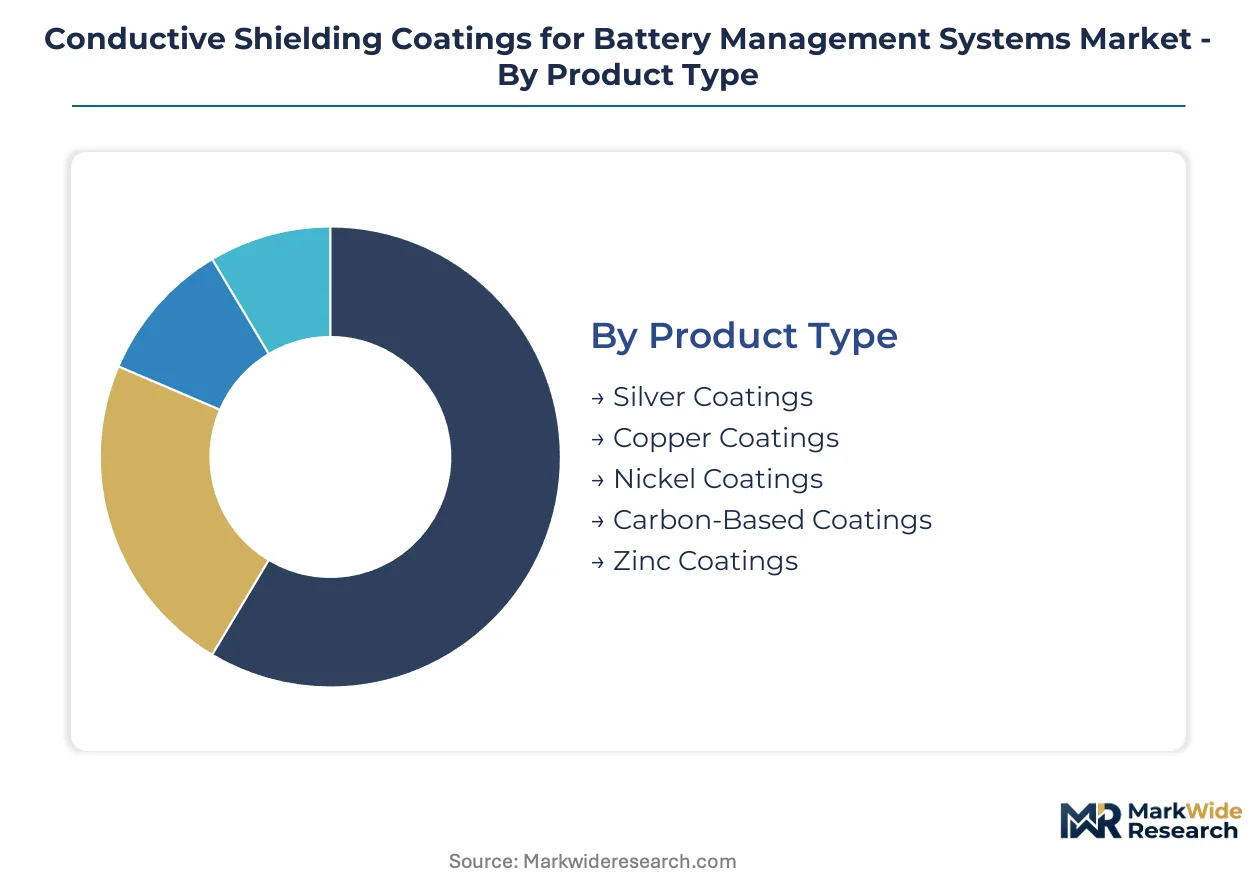
Segmentation in conductive shielding coatings reveals how technical specifications fragment across battery architectures. Each dimension—material chemistry, functional technology, application environment, and supply chain position—carries distinct qualification requirements and margin structures that shape supplier strategies.
Product Type:
Integration depth varies sharply: silver and copper formulations embed directly into high-voltage BMS architectures as primary shielding layers, while nickel and zinc variants serve secondary protection roles or standalone retrofit applications.
- Silver Coatings:Polymer matrices loaded with silver flakes deliver conductivity exceeding 10^5 S/m alongside oxidation resistance in humid cell environments. OEMs in Germany and South Korea specify these for premium EV platforms where BMS signal integrity failures carry catastrophic warranty exposure.
- Copper Coatings:Lower-cost metallic fillers achieve conductivity within one order of magnitude of silver at substantially reduced material cost. Chinese battery manufacturers deploy copper-based formulations across export-bound pack architectures where FCC electromagnetic compatibility certification is mandatory.
- Nickel Coatings:Magnetic permeability properties suit specific frequency-range interference suppression in industrial power modules.
- Carbon-Based Coatings:Carbon nanotube and graphene-filled polymers are climbing fastest as mass-market EV producers prioritize cost reduction over peak conductivity performance.
- Zinc Coatings:Sacrificial corrosion protection dominates marine and harsh-environment energy storage installations.
Volume placements concentrate in copper formulations; the faster expansion belongs to carbon-based alternatives.
Technology:
Cost tiers separate these technologies: electromagnetic interference shielding and thermal management coating command premium pricing through multi-function integration, while electrostatic discharge and anticorrosion variants compete on per-unit coating cost.
- Electromagnetic Interference Shielding:Multi-layer deposition systems suppress radiated emissions across 30 MHz to 6 GHz ranges per FCC Part 15 and EU EMC Directive thresholds. MIIT certification requirements for China's domestic battery exports are expanding specification complexity for multinational coating programs.
- Thermal Management Coating:Phase-change materials and ceramic-filled polymers integrate heat dissipation with electromagnetic suppression in single deposition passes. Pack energy densities above 300 Wh/kg in next-generation EV architectures are making this convergence mandatory rather than optional.
- Electrostatic Discharge Shielding:Surface resistivity control prevents catastrophic spark damage during cell assembly operations.
- Anticorrosion Coatings:Barrier protection extends pack service life in coastal and chemically exposed installations.
- Dielectric Shielding:Electrical isolation layers prevent arcing between high-voltage busbars and grounded pack enclosures.
Revenue concentration sits with electromagnetic interference shielding; thermal management coating is gaining share fastest through functional integration mandates.
Application:
Customer type determines specification rigor: electric vehicle battery packs and aerospace power systems demand OEM-direct technical collaboration, while energy storage and consumer electronics flow through tiered distributor channels.
- Electric Vehicle Battery Packs:Cell-to-pack architectures eliminate module housings and concentrate shielding burden on BMS circuit boards and high-voltage interconnects. Chinese manufacturers including CATL and BYD are scaling dedicated coating application lines for export-bound production.
- Energy Storage Systems:Utility-scale battery installations require decade-plus service life guarantees that drive specification toward silver and nickel formulations with proven field degradation profiles.
- Consumer Electronics Batteries:Smartphone and laptop BMS units prioritize minimal coating thickness to preserve volumetric energy density.
- Industrial Power Modules:Forklift and stationary machinery batteries tolerate thicker, lower-cost shielding layers.
- Aerospace Power Systems:FAA certification requirements and extreme temperature cycling narrow qualified supplier pools to pre-approved coating formulators.
Procurement volume clusters in electric vehicle battery packs; energy storage systems are expanding most quickly as grid-scale installations multiply.
End User:
Supply chain position dictates contracting structure: OEMs and vehicle assemblers lock multi-year framework agreements, while tier-1 suppliers and aftermarket providers operate on spot-market purchasing with shorter qualification cycles.
- OEMs:Technical co-development clauses embed coating suppliers early in battery platform design, creating specification lock-in before competitive bidding opens. German and South Korean vehicle assemblers have established captive R&D partnerships with Henkel and 3M respectively.
- Tier-1 Suppliers:Delphi, Bosch, and Continental source coatings through approved vendor lists with documented REACH substance compliance, consolidating procurement toward formulators with pre-certified material portfolios.
- Battery Manufacturers:CATL, LG Energy Solution, and SK On operate captive coating application facilities with direct raw material purchasing from chemical precursor suppliers.
- Aftermarket Providers:Repair and refurbishment segments purchase through distributor channels with minimal technical specification beyond basic electromagnetic compatibility.
- Vehicle Assemblers:Detroit-based and Stuttgart-based final assembly plants specify coatings at pack integration stage, creating late-stage supplier qualification windows.
Contract value concentrates with OEMs; tier-1 suppliers are gaining procurement influence as battery pack integration shifts upstream from vehicle assembly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's battery manufacturing special economic zones concentrate coating demand through CATL and BYD expansion corridors. Germany's automotive clusters anchor European specification development. The United States, South Korea, and Japan complete the pentagonal demand structure through distinct regulatory and supply chain configurations.
China
CATL and BYD scaling export-bound pack production drives volume demand for shielded BMS architectures. MIIT technical regulations and GB standards mandate shielding effectiveness testing for domestically manufactured battery systems. The Yangtze River Delta coating application corridor absorbs capacity expansion from carbon-based formulation suppliers serving mass-market EV platforms.
Germany
Premium EV OEMs in Stuttgart and Munich specify silver-filled polymer matrices for high-reliability BMS signal integrity. REACH substance transparency requirements and ECHA candidate list updates filter raw material sourcing toward pre-certified formulators. The Bavarian adhesive-coating hybrid cluster embeds technical co-development clauses into multi-year framework agreements.
United States
Detroit-based vehicle assemblers anchor North American thermal management coating procurement through captive supply relationships. FCC electromagnetic compatibility thresholds directly shape coating performance specifications for electronics sold domestically. The Midwest battery pack integration corridor creates late-stage supplier qualification windows at final assembly plants.
South Korea
LG Energy Solution and SK On operate captive coating application facilities with direct precursor purchasing from chemical suppliers. Domestic vehicle assemblers have established R&D partnerships with electromagnetic interference shielding formulators. The Seoul Capital Area concentrates multi-layer deposition system deployment for next-generation cell-to-pack architectures.
Japan
Automotive electronics specialists drive specification rigor for densely packed lithium-ion cell configurations. METI industrial standards and JIS certification frameworks narrow qualified supplier pools for high-voltage battery architectures. The Nagoya industrial corridor integrates electromagnetic suppression with active thermal regulation in single deposition passes.
Conductive Shielding Coatings for Battery Management Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with adhesive-coating hybrid portfolios dominating European OEM supply chains while multi-layer electromagnetic interference formulators sustain technology leadership. The vendor base concentrates around three strategic archetypes: diversified chemical conglomerates with coating divisions, pure-play electromagnetic shielding specialists, and automotive-tier suppliers with captive formulation capabilities. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with direct OEM technical collaboration accelerating specification lock-in.
Among diversified chemical conglomerates, Henkel AG & Co. KGaA and Dow occupy positions exemplifying the adhesive-coating hybrid archetype, while 3M represents the multi-layer electromagnetic interference technology vector. These three entities anchor distinct competitive positioning within the premium formulation tier, with geographic origin and company structure reflecting their respective European and North American heritage.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M |
| PPG Industries |
| Akzo Nobel |
| Dow |
| MG Chemicals |
| Acheson |
| Axalta Coating Systems |
| The Sherwin-Williams Company |
| Others |
Pricing and Supply Chain Analysis
Multi-year framework agreements from German and South Korean vehicle assemblers are compressing procurement into performance-guaranteed contracts, forcing coating formulators to absorb silver price volatility through hedging overhead while carbon-based suppliers capture volume in China's mass-market EV corridors. This buyer consolidation pattern fragments spot-market liquidity and stratifies pricing power between captive supply relationships and distributor-channel spot purchases.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with OEMs paying substantial markups for certified silver formulations deliverable within compressed qualification windows versus standard-cycle carbon-based alternatives. Three-tier pricing structure across premium, standard, and economy levels separates FCC-certified silver coatings from MIIT-compliant copper variants and uncertified carbon-based economy grades. Price differentiation hinges on electromagnetic compatibility certification tier and raw material input cost, with silver-filled polymers commanding substantial premiums over carbon nanotube alternatives. Cost compression in carbon-based tiers is intensifying because Chinese battery manufacturers are consolidating procurement toward domestic formulators with captive precursor supply. Tier-1 suppliers exhibit highest price sensitivity due to approved vendor list constraints, while OEMs with technical co-development clauses demonstrate lowest sensitivity to per-unit coating costs.
Supply Chain Analysis
FCC, REACH, and GB standard qualification gates fragment qualified supplier pools, extending certification timelines and concentrating procurement toward pre-certified formulators with documented substance compliance portfolios. Geographic supply concentration centers on China for carbon nanotube and specialized polymer resin production, South Korea for multi-layer deposition equipment, and Germany for adhesive-coating hybrid formulation expertise. Raw material dependencies draw from silver flake suppliers in Mexico, copper precursor producers in Chile, and graphene feedstock processors in China. Single-source vulnerability in East Asian chemical precursor clusters threatens carbon-based coating supply continuity during trade restriction episodes. Distribution runs through direct OEM technical partnerships for premium tiers, approved vendor lists for tier-1 suppliers, and chemical distributor networks for aftermarket retrofit segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where coating formulators pursue captive precursor supply to defend margin position against commodity price volatility and qualification cost inflation.
For Market Incumbents: Deploy captive R&D collaboration agreements to lock specification windows before competitive bidding opens, embedding Henkel and 3M-style technical co-development clauses into multi-year framework agreements with Stuttgart and Munich-based OEMs. Add selective deposition capacity in the Yangtze River Delta to serve CATL and BYD expansion corridors, defending against emerging Chinese carbon-based formulators with state-backed precursor supply. Carbon nanotube price volatility and REACH substance restriction expansions constitute dual threats requiring simultaneous hedging and reformulation investment. For New Entrants and Emerging Players: Tier-2 battery manufacturers in India offer the most penetrable entry corridor, with PLI scheme incentives creating first-mover advantage for coating suppliers establishing local application partnerships before incumbent qualification cycles complete. Target thermal-management coating convergence as the white-space application, integrating electromagnetic interference suppression with active thermal regulation functions that next-generation cell-to-pack architectures demand. Direct technical partnerships with domestic cell producers bypass entrenched distributor relationships and accelerate specification lock-in. For Investors and Strategic Acquirers: The window for entry favors mid-cap coating specialists with pre-certified REACH substance portfolios and established MIIT testing relationships, positioning for acquisition by diversified chemical conglomerates seeking electromagnetic shielding capability. Long-term viability hinges on functional integration depth across electromagnetic, thermal, and mechanical performance dimensions. Watch for divergence between FCC and EU AI Act electromagnetic compatibility test protocols as the inflection signal—misalignment that fragments product platforms and inflates multinational qualification costs favors consolidated formulators with tri-regional certification infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive silver flake and carbon nanotube sourcing insulates margin position against commodity volatility from Mexican and Chinese suppliers. |
| Multi-Regional Certification Infrastructure | Simultaneous FCC, REACH, and GB standard qualification capability captures multinational battery program procurement. |
| Thermal-Electromagnetic Convergence R&D | Phase-change material integration addresses 300+ Wh/kg pack energy densities in next-generation EV architectures. |
| Direct OEM Technical Partnerships | Bypassing tiered distributor networks accelerates specification lock-in with Stuttgart and Detroit-based vehicle assemblers. |
| India Manufacturing Footprint Establishment | PLI scheme incentives for domestic cell production create first-mover positioning before incumbent qualification cycles complete. |
Research Methodology
Document review covered SEC filings from diversified chemical conglomerates, ECHA substance restriction updates, and MIIT technical regulation releases, complemented by interviews with coating formulator R&D directors, Tier-1 battery supplier procurement managers, and electromagnetic compatibility testing laboratory technicians. Secondary validation drew from FCC electromagnetic compatibility enforcement databases, REACH candidate list publications, and Chinese customs trade data for conductive polymer precursor imports. Bottom-up volume estimates from individual coating application line deployments were cross-referenced against top-down battery pack production forecasts to establish triangulated market sizing.
Historical qualification timeline patterns were cross-referenced against panel input from OEM platform engineers to model adoption curve trajectories across the projection horizon. Segmentation modeling incorporated material chemistry tiers, functional technology convergence patterns, application environment specification rigor, and supply chain position contracting structures. CAGRs were derived from volume-weighted average of individual segment growth trajectories, with specific inputs including cell-to-pack architecture penetration rates and pack energy density escalation curves.
Caveats apply where silver commodity price spikes, REACH substance restriction expansions, or tri-regional test protocol divergence could materially shift the outlook for premium versus carbon-based formulation demand mix. Forecasts reflect assumptions regarding continued OEM consolidation toward multi-year framework agreements and sustained China export-bound EV production scaling. A model refresh is warranted upon material change in electromagnetic compatibility regulatory alignment or battery pack integration architecture standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.