
 Global Construction Paints and Coatings Market | 2026-2036
Global Construction Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Construction Paints and Coatings Market Analysis
The EU Green Deal is decoupling European construction material procurement from high-emission coating supply chains. PPG Industries leverages its water-based technology portfolio to sustain specification wins across Nordic public housing tenders. AkzoNobel anchors its position through in-house resin production that controls raw material variability. Nippon Paint Holdings dominates East Asian infrastructure coatings through localized manufacturing scale.
Construction paints and coatings comprise pigmented liquid or powder formulations applied to building substrates for protection, decoration, or functional performance, with film thickness typically ranging from 25 to 150 microns depending on exposure severity and substrate porosity. Water-based coatings lead volume globally due to regulatory phase-outs of aromatic solvent systems, while powder coatings represent the fastest-growing structural segment as automated electrostatic lines penetrate commercial facade prefabrication. Specialty coatings command premium positioning in infrastructure anti-corrosion and intumescent fire-protection applications where performance certification creates margin concentration.
EPA VOC rules in the United States, REACH chemical registration in Europe, and China's MEE emission standards collectively reshape product formulation roadmaps and factory compliance investments for multinational suppliers. The EU AI Act introduces emerging traceability requirements for automated coating inspection systems used in large-scale construction. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and certification timelines.
Market Dynamics
Water-based formulation technology is compressing solvent-borne capacity as EU Green Deal chemical restrictions cascade through import compliance frameworks across Southeast Asian manufacturing hubs.
Growth Catalysts
- REACH chemical registration:European import standards are accelerating reformulation investments in Vietnamese and Indonesian coating plants serving Nordic public housing tenders.
- Urban corridor infrastructure:India's Delhi-Mumbai Industrial Corridor and dedicated freight corridors are generating sustained demand for anti-corrosion and intumescent fire-protection systems.
- Powder coating automation:Electrostatic application lines in commercial facade prefabrication are displacing liquid spray systems in German and Japanese manufacturing facilities.
Market Restraints
- Titanium dioxide volatility:Pigment feedstock concentration in Chinese sulfate-process capacity creates margin compression for water-based decorative coating producers.
- Resin supply concentration:Epoxy and acrylic resin manufacturing clusters in the US Gulf Coast and Rotterdam-Antwerp corridor expose formulators to hurricane and logistics disruption risk.
- Technical limitation in extreme climates:Water-based exterior coatings face performance gaps in high-humidity monsoon zones where solvent-borne systems retain substrate adhesion advantages.
Strategic Opportunities
- Vietnam industrial park construction:Northern provinces around Hai Phong and Bac Ninh offer underpenetrated specification channels for high-performance concrete protection coatings.
- EU AI Act traceability:Automated coating inspection systems in large-scale construction create first-mover advantage for suppliers integrating machine-vision quality verification.
- Retrofit building stock:Germany's building energy renovation mandates and France's RE2020 environmental regulations are opening renovation-specific coating specification windows.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in low-VOC resin synthesis and bio-based additive integration is concentrating among a narrow cohort of European and Japanese technical centers.
- Certification timeline compression:Multi-jurisdiction fire-rating approvals for intumescent coatings are extending product launch cycles by 18-24 months across US, EU, and Gulf markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Construction Paints and Coatings Market |
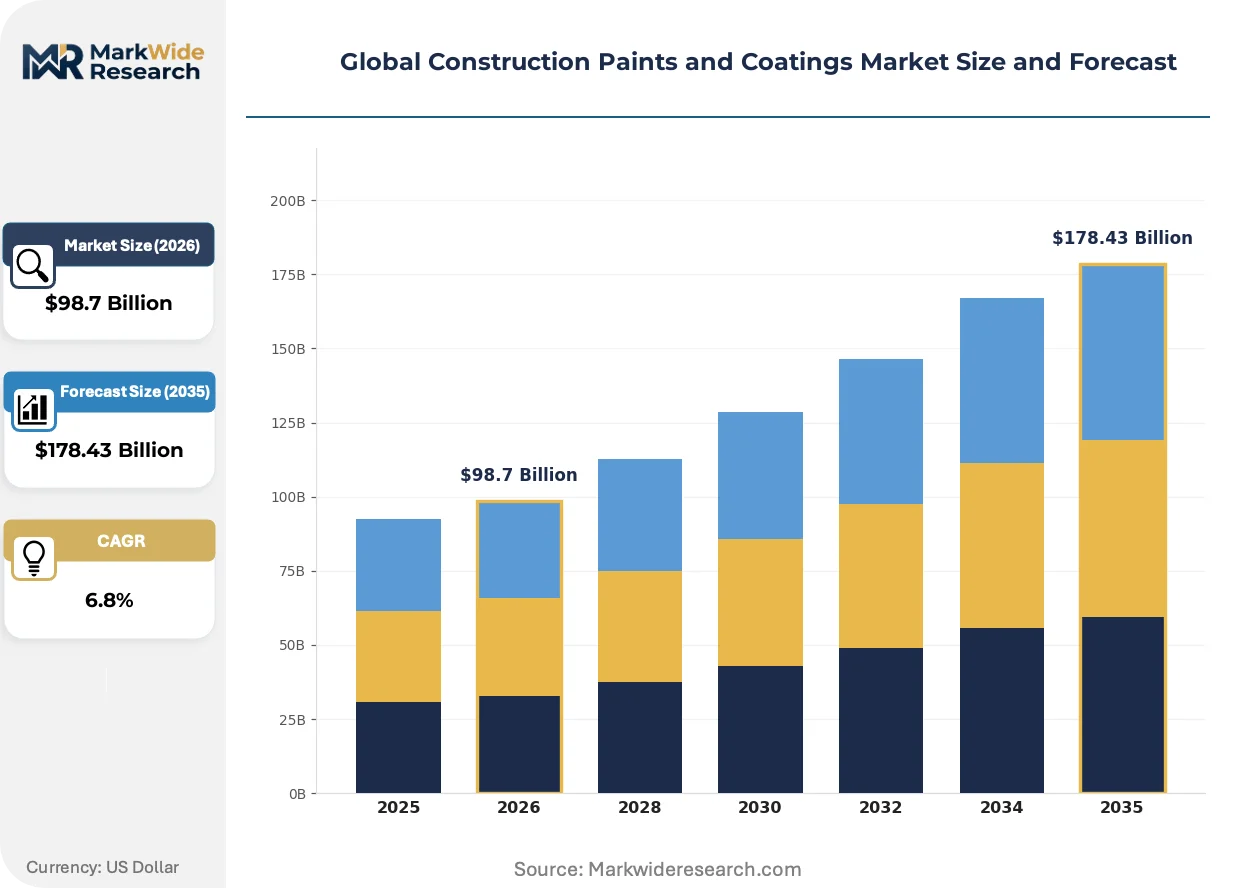
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Coatings, Solvent-Based Coatings, Powder Coatings, Specialty Coatings End User: Residential, Commercial, Industrial, Infrastructure Application: Interior Walls, Exterior Facades, Roofs, Floors Material: Oil, Alkyd, Acrylic, Epoxy |
| Companies Covered | The Sherwin-Williams Company, PPG Industries, AkzoNobel, Nippon Paint Holdings, Asian Paints, RPM International, BASF, Axalta Coating Systems, Jotun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Construction Paints and Coatings Market Emerging Trajectories
Digital specification tools and bio-based raw material platforms are restructuring how coating performance is validated and how supply chains decarbonize. These shifts are compressing traditional technical service models.
Self-healing polymer coatings incorporating microencapsulated repair agents are overtaking conventional maintenance-cycle coatings in offshore infrastructure and bridge deck applications. North Sea wind farm operators are specifying these systems to reduce access-platform recoating frequency. The technology is compressing lifetime maintenance cost models that previously dominated tender evaluations.
China's MEE emission standards are forcing solvent-borne capacity consolidation in Shandong and Jiangsu provinces. Provincial environmental bureaus are denying permit renewals for non-compliant coating facilities. Water-based and powder coating lines are capturing displaced volume in architectural metal finishing and wood furniture manufacturing.
Building information modeling integration is reshaping specification workflows for commercial facade coatings. German and Dutch architectural practices are embedding coating performance data directly into digital twin assets. This behavior is disintermediating traditional technical sales relationships in Northern European commercial construction procurement.
Global Construction Paints and Coatings Market Segmentation
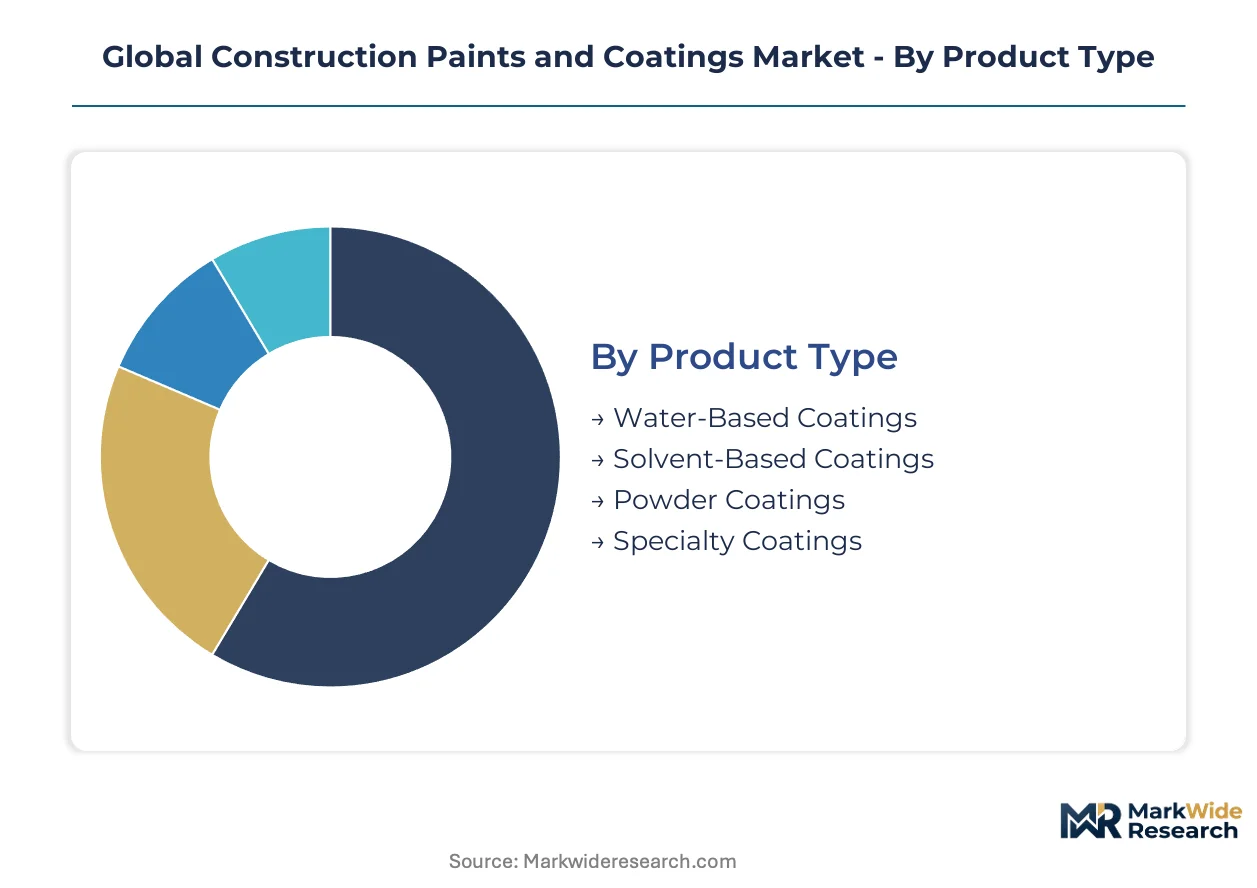
Segmentation in construction coatings reveals how formulation chemistry, end-use durability requirements, and substrate specifications create distinct procurement channels. Buyers prioritize different performance attributes across residential decoration, industrial corrosion protection, and infrastructure fire safety applications.
Product Type:
Buyers differentiate primarily by compliance burden and application method, with regulatory jurisdiction dictating permissible chemistry.
- Water-Based Coatings:Acrylic and polyurethane dispersions in aqueous carriers dominate architectural decorative applications. India's urban corridor projects and Vietnam's industrial park construction are expanding procurement of low-VOC formulations as EU Green Deal import standards tighten chemical compliance requirements for exported building materials.
- Powder Coatings:Thermosetting resin systems applied via electrostatic spray deliver 100% solids with zero VOC emissions. Automated electrostatic lines in German and Japanese commercial facade prefabrication facilities are displacing liquid spray systems, with commercial metal finishing driving volume concentration.
- Solvent-Based Coatings:Aromatic and aliphatic hydrocarbon carriers retain substrate adhesion advantages in high-humidity monsoon zones where water-based exterior coatings face performance gaps.
- Specialty Coatings:Intumescent fire-protection and anti-corrosion systems command premium positioning where performance certification creates specification barriers.
Volume sits with water-based formulations; growth tilts toward powder coatings.
End User:
Project scale and specification authority determine margin capture, with public infrastructure tenders demanding certified performance documentation.
- Residential:Single-family and multi-family housing drives decorative interior and exterior volume, with color trend cycles influencing repurchase frequency.
- Commercial:Office, retail, and hospitality construction specifies facade coatings with digital twin compatibility for building information modeling integration in German and Dutch architectural practices.
- Industrial:Manufacturing facilities and warehouses demand chemical-resistant floor coatings and structural steel protection, with epoxy systems dominating heavy-traffic environments.
- Infrastructure:Bridges, tunnels, and transportation corridors require anti-corrosion and intumescent fire-protection coatings with extended maintenance intervals; North Sea wind farm operators are specifying self-healing polymer systems to reduce access-platform recoating frequency.
Revenue concentrates in infrastructure; specification activity is expanding most quickly in commercial facade digitization.
Application:
Exposure severity and accessibility constraints dictate film thickness requirements and recoating cycle economics.
- Interior Walls:Low-sheen and matte decorative finishes dominate residential and commercial spaces, with washability and stain resistance driving premium tier differentiation.
- Exterior Facades:Elastomeric and ceramic coatings manage thermal expansion and moisture intrusion in commercial building envelopes.
- Roofs:Reflective and waterproof membrane coatings reduce thermal load and extend structural lifespan in commercial and industrial buildings.
- Floors:Epoxy and polyurethane systems provide chemical resistance and abrasion protection in manufacturing, warehousing, and healthcare facilities.
Unit volume flows through interior walls; value capture is climbing the fastest in roof restoration and cool-roof specifications.
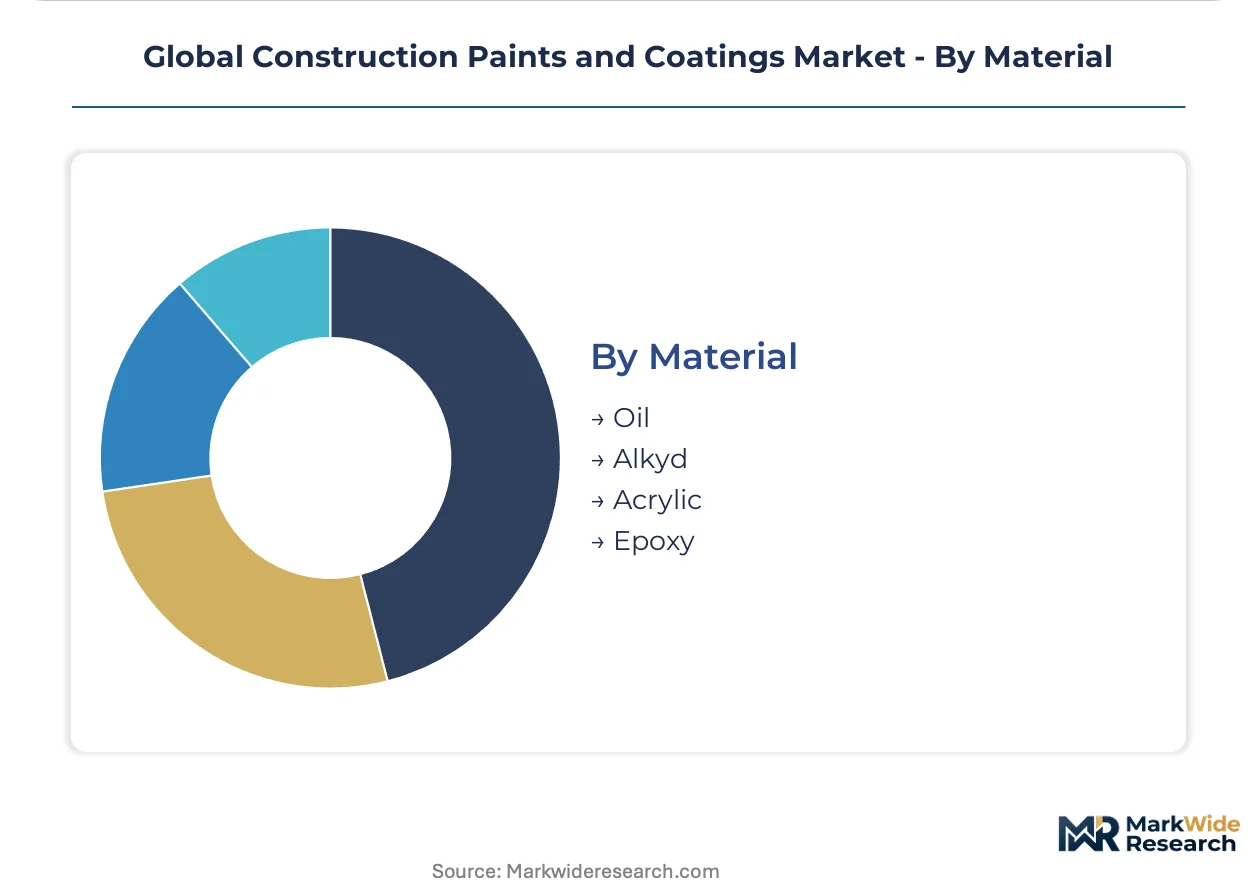
Material:
Resin backbone chemistry determines adhesion, durability, and regulatory compliance profiles across substrate categories.
- Acrylic:Water-dispersible polymers dominate architectural decorative coatings, offering UV resistance and color retention for exterior applications.
- Epoxy:Two-part thermosetting systems provide chemical resistance and mechanical durability for industrial floors and infrastructure protection.
- Alkyd:Oil-modified polyester resins retain solvent-borne application in maintenance coatings and trim applications where brushability and flow are prioritized.
- Oil:Traditional linseed and tung oil formulations persist in specialty wood finishing and heritage restoration applications.
Production scale centers on acrylic water-borne systems; epoxy formulations are gaining share fastest in infrastructure corrosion protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hai Phong and Bac Ninh provinces anchor Vietnam's industrial coating demand as northern manufacturing zones expand concrete protection specifications. India's Delhi-Mumbai Industrial Corridor drives anti-corrosion volume. Germany's Ruhr Valley and Japan's Kansai region concentrate automated facade prefabrication capacity.
United States
Commercial facade renovation and infrastructure bridge maintenance sustain specification activity across Texas and California metro corridors. EPA VOC rules are accelerating water-based formulation adoption in architectural coatings. Houston-Gulf Coast resin manufacturing clusters expose formulators to hurricane disruption risk.
Germany
Building energy renovation mandates under the national climate program are opening retrofit-specific coating specification windows in Bavaria and North Rhine-Westphalia. REACH chemical registration requirements cascade through import compliance frameworks for Nordic public housing tenders. Ruhr Valley automated electrostatic lines are displacing liquid spray systems in commercial metal finishing.
China
Urban corridor infrastructure and industrial park construction in the Yangtze River Delta and Pearl River Delta sustain decorative and protective coating volume. MEE emission standards are forcing solvent-borne capacity consolidation in Shandong and Jiangsu provinces. Provincial environmental bureaus are denying permit renewals for non-compliant coating facilities.
India
The Delhi-Mumbai Industrial Corridor and dedicated freight corridors are generating sustained demand for anti-corrosion and intumescent fire-protection systems in Maharashtra and Gujarat. BIS standards are tightening chemical compliance requirements for imported building materials. Mumbai-Pune urban corridor projects concentrate low-VOC formulation procurement.
Vietnam
Industrial park construction in Hai Phong and Bac Ninh provinces offers underpenetrated specification channels for high-performance concrete protection coatings. EU Green Deal import standards are accelerating reformulation investments in Vietnamese coating plants serving European tenders. Northern manufacturing zones are expanding adoption of water-based architectural systems.
Global Construction Paints and Coatings Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification intensity and specification authority in public infrastructure tenders. The vendor base stratifies between multinational integrated formulators with captive resin production and regional specialists with localized manufacturing scale. Three archetypes dominate: integrated resin-coating producers controlling raw material variability, water-technology specialists capturing EU Green Deal compliance windows, and powder-coating automation providers penetrating commercial facade prefabrication. Competitive moves concentrate on backward integration into resin supply and geographic expansion through specification wins in Southeast Asian industrial corridors.
Within the integrated multinational tier, PPG Industries, AkzoNobel, and Nippon Paint Holdings occupy positions exemplifying distinct strategic anchors. PPG Industries represents water-based technology portfolio breadth sustaining specification wins across Nordic public housing tenders. AkzoNobel exemplifies in-house resin production controlling raw material variability in European markets. Nippon Paint Holdings anchors East Asian infrastructure coatings through localized manufacturing scale in Japan and regional export platforms.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries |
| AkzoNobel |
| Nippon Paint Holdings |
| Asian Paints |
| RPM International |
| BASF |
| Axalta Coating Systems |
| Jotun |
| Others |
Supply Flow & Price Mechanics
EU Green Deal chemical restrictions gate both qualified supply and premium-tier pricing access, forcing reformulation investments that stratify coating producers into compliance-certified premium suppliers and stranded commodity players. REACH-registered resin streams and low-VOC formulation capability now determine which suppliers capture Nordic public housing tenders versus competing on undifferentiated volume.
Pricing Analysis
Certified fire-protection performance anchors value-based pricing for intumescent coatings in infrastructure tenders, where extended maintenance intervals justify premium positioning over first-cost alternatives. Three-tier pricing structure across certified-premium, standard-performance, and economy-decorative levels separates specification-grade suppliers from commodity producers. Cost compression in decorative architectural tiers is intensifying because titanium dioxide feedstock volatility squeezes water-based formulation margins. Residential developers in Southeast Asian urban corridors exhibit highest price sensitivity, while North Sea wind farm operators prioritize lifetime cost models over unit pricing.
Supply Chain Analysis
Empty container repositioning and pigment returns from decentralized job sites complicate reverse-logistics flows for coating distributors serving fragmented construction markets. Epoxy and acrylic resin manufacturing clusters in the US Gulf Coast, Rotterdam-Antwerp corridor, and Japan's Keihin industrial zone concentrate upstream supply. Formulation depends on titanium dioxide from Chinese sulfate-process capacity, epoxy resins from petrochemical feedstocks, and specialty additives from German and Japanese chemical producers. Hurricane exposure at Houston-Gulf Coast resin plants creates single-source vulnerability during Atlantic storm seasons. Distribution runs through regional coating distributors with technical service capabilities, direct specification relationships with major project developers, and big-box retail channels for residential decorative volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based formulation technology is displacing solvent-borne capacity across regulatory jurisdictions, compressing legacy asset values while opening premium positioning for compliant suppliers. This transition phase rewards early movers with certified low-VOC portfolios and stranded-cost exposure for laggards.
For Market Incumbents: Hedge against titanium dioxide volatility through backward integration into in-house resin production or long-term offtake agreements with sulfate-process pigment producers. Capture specification authority in EU Green Deal-compliant tenders by accelerating REACH-registered formulation portfolios before compliance deadlines tighten. Defensive consolidation of technical service capabilities in Southeast Asian industrial corridors protects channel relationships from emerging regional competitors.
For New Entrants and Emerging Players: Capture underpenetrated specification channels in Vietnam's Hai Phong and Bac Ninh industrial parks where high-performance concrete protection coatings face limited local competition. Target powder coating automation partnerships with German and Japanese commercial facade prefabrication facilities seeking electrostatic line integration. Lead with digital specification tools that embed coating performance data into building information modeling workflows, disintermediating incumbent technical sales relationships.
For Investors and Strategic Acquirers: Provincial environmental bureau permit denials in China's Shandong and Jiangsu provinces are the leading indicator that solvent-borne capacity consolidation will accelerate water-based and powder coating market share capture. Long-term viability favors integrated resin-coating producers with captive raw material control and certified low-VOC formulation platforms. Acquisition target archetype: mid-cap specialists with localized manufacturing scale in Southeast Asian growth corridors and established relationships with industrial park developers. Monitor MEE enforcement actions and EU AI Act traceability implementation timelines for early signals of regulatory-driven supplier restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | AkzoNobel's in-house resin manufacturing controls raw material variability and margin compression risks. |
| Powder Coating Automation Partnership | Electrostatic line integration with German facade prefabrication facilities captures zero-VOC specification demand. |
| REACH-Registered Formulation Portfolio | PPG Industries leverages compliance certification to sustain Nordic public housing tender wins. |
| Digital Twin Specification Integration | Building information modeling compatibility disintermediates traditional technical sales in Dutch commercial procurement. |
| Southeast Asian Manufacturing Scale | Nippon Paint Holdings anchors East Asian infrastructure coatings through localized production and regional export platforms. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving coating plant managers, procurement leads at residential developers, distribution channel partners, and technical R&D directors. Bottom-up volume modeling triangulated against top-down expenditure analysis from construction industry databases and chemical sector disclosures. ECHA REACH registration databases, EPA VOC rulemaking dockets, and China MEE permit records provided regulatory compliance tracking.
Segmentation dimensions were modeled at formulation chemistry, end-use application, substrate material, and regional production hub granularity across the projection horizon. CAGRs derived from installed base growth, replacement cycle economics, and regulatory phase-out timelines for solvent-borne systems. Forecast inputs incorporated urban corridor infrastructure project pipelines, industrial park construction permits, and building energy renovation mandate implementation rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to titanium dioxide feedstock volatility, hurricane disruption at Gulf Coast resin clusters, and divergence between EU Green Deal and other jurisdiction chemical compliance timelines. Practitioners should monitor provincial environmental bureau enforcement actions in China, REACH authorization list updates, and powder coating line installation rates in commercial prefabrication facilities for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Polyolefin Resin Paints Market
Paints & Coatings
Industrial Paint Booth Market
Paints & Coatings
Europe Automotive Paints and Coatings Market
Paints & Coatings
Water-Borne Latex Paints Market
Paints & Coatings
Aircraft Paint Market
Paints & Coatings
Paint Mixing Market
Paints & Coatings
Decorative Paints Market
Paints & Coatings
Global Thinners and Paint Strippers Market
Paints & Coatings
Anti-Fungal and Anti-Bacterial Paints Market
Paints & Coatings
Middle East and Africa Paints and Coatings Market
Paints & Coatings
Automotive Paints and Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Market
Paints & Coatings
Water-Soluble Paints Market
Paints & Coatings
Alkyd Coatings Market
Paints & Coatings
Bituminous Paints Market
Paints & Coatings
Road Marking Paint Market