
 Optocoupler IC Market | 2026-2036
Optocoupler IC Market Size, Share, and Industry Trends Forecast 2026-2036
Optocoupler IC Market Outlook
REACH substance restrictions on halogenated flame retardants is realigning the cost-of-entry calculus for European-bound optocoupler suppliers. ON Semiconductor leverages its vertically integrated gallium arsenide LED fabrication to sustain margin control across high-reliability product lines. Renesas Electronics Corporation anchors its competitive stance through automotive-qualified isolation portfolios certified to AEC-Q100 standards. Vishay Intertechnology dominates the phototransistor segment with broad distribution reach into industrial automation channels.
An optocoupler IC is a solid-state device that transfers electrical signals between isolated circuits using a short optical transmission path, typically comprising an infrared LED emitter and a photosensitive detector such as a phototransistor or photodiode, with isolation voltages commonly rated from 2.5 kV to 5 kV depending on application safety requirements. Phototransistor-based optocouplers retain the largest volume share due to their cost efficiency in consumer power supplies and motor drives, though photodiode variants with faster switching speeds are capturing share in telecommunications and precision medical instrumentation. Solid-state relay optocouplers command premium positioning where electromechanical relay replacement demands zero-contact wear and extended operational lifecycles in energy infrastructure.
The US FDA mandates isolation barriers in patient-connected medical equipment under IEC 60601-1 collateral standards, while the EU AI Act and Machinery Directive impose functional safety requirements on autonomous industrial systems that rely on signal-isolation integrity. China's GB 4943.1 national standard for information technology equipment safety parallels international isolation specifications, creating a multi-jurisdictional compliance landscape for component vendors. Stakeholders must monitor how evolving functional safety SIL ratings and carbon-border adjustment mechanisms reshape supplier qualification timelines and geographic sourcing strategies.
Market Dynamics
IEC 60747-5-5 safety isolation standards are compressing supplier qualification timelines while electric vehicle powertrain architectures pull photodiode variants into battery management systems at unprecedented scale.
Growth Catalysts
- Automotive electrification mandates:Battery management systems in electric vehicles require galvanic isolation between high-voltage traction batteries and low-voltage control electronics. Photodiode-based optocouplers deliver the switching speeds and common-mode transient immunity these architectures demand.
- REACH substance restrictions:European halogenated flame retardant limitations are forcing material substitutions in optocoupler housings. Suppliers reformulating encapsulants gain preferential access to EU-bound industrial automation and medical device channels.
- China's semiconductor self-sufficiency policies:Domestic isolation device sourcing accelerates as MIIT localization targets redirect procurement from multinational suppliers toward indigenous fabrication capacity.
Market Restraints
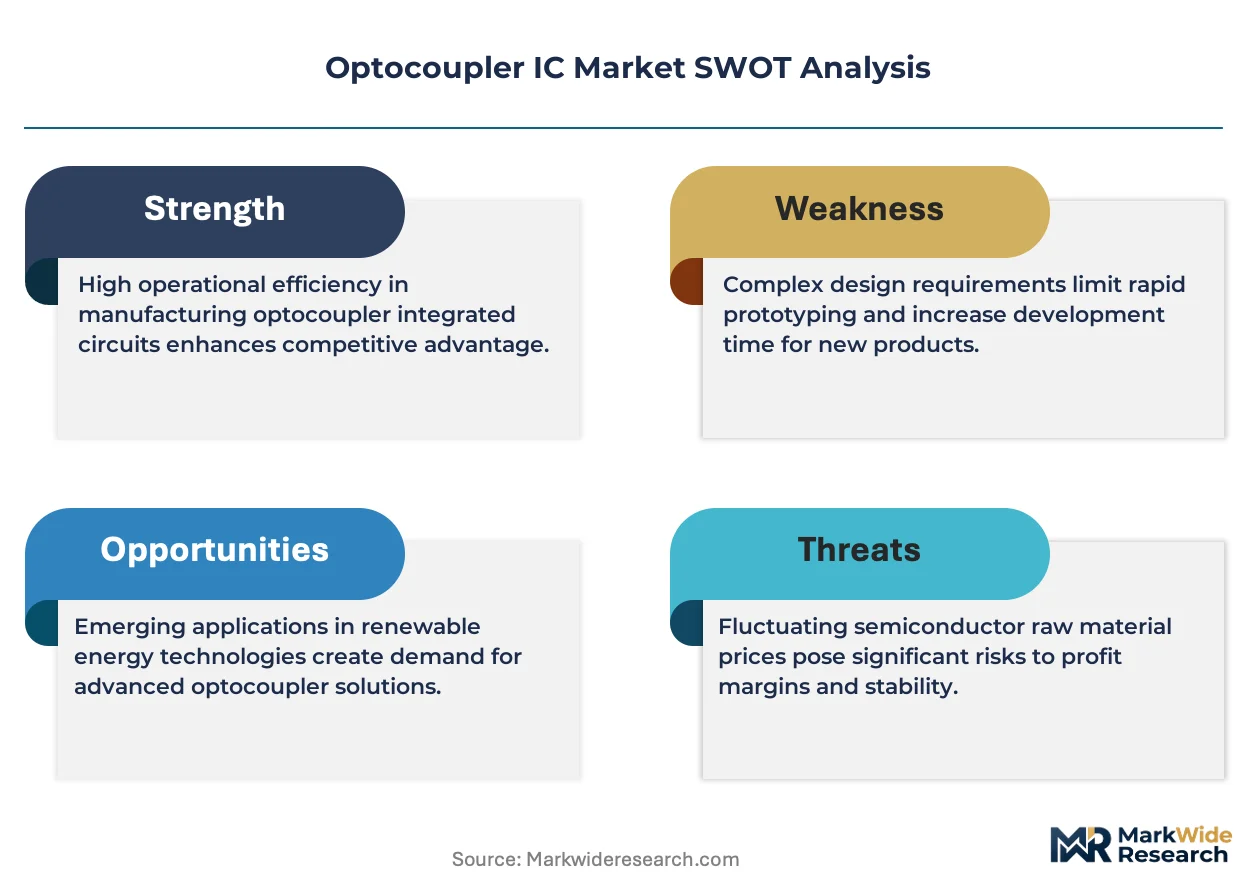
- Gallium arsenide wafer supply concentration:LED emitter substrates depend on a narrow supplier base concentrated in East Asian foundries. Price volatility in III-V compound semiconductors constrains margin flexibility for mid-tier optocoupler assemblers.
- Phototransistor speed limitations:Switching frequencies below 1 MHz restrict deployment in 5G telecommunications infrastructure and precision servo motor controls where photodiode alternatives command 3-4x price premiums.
- Multi-jurisdictional certification burden:Simultaneous compliance with IEC 60601-1 medical, IEC 60747-5-5 industrial, and AEC-Q100 automotive standards extends product development cycles and freezes engineering resources.
Strategic Opportunities
- Solid-state relay substitution:Electromechanical relay replacement in solar inverters and energy storage systems creates demand for optocoupler-based SSRs with zero-contact wear and 20-year operational lifecycles.
- India's PLI scheme for electronics:Production-linked incentives for semiconductor packaging attract optocoupler module assembly investments serving domestic appliance and automotive markets.
- Silicon carbide gate driver integration:Convergence of wide-bandgap power semiconductors with isolated driver ICs opens architectural space for optocoupler-integrated solutions in 800V electric vehicle platforms.
Industry Challenges
- Isolation coordination expertise scarcity:Engineers capable of designing creepage and clearance distances for mixed-signal systems spanning 2.5 kV to 5 kV ratings command premium compensation and extend hiring timelines.
- Legacy electromechanical system integration:Retrofitting optocoupler isolation into existing motor control and relay architectures requires custom PCB redesigns and field validation protocols that delay replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optocoupler IC Market |
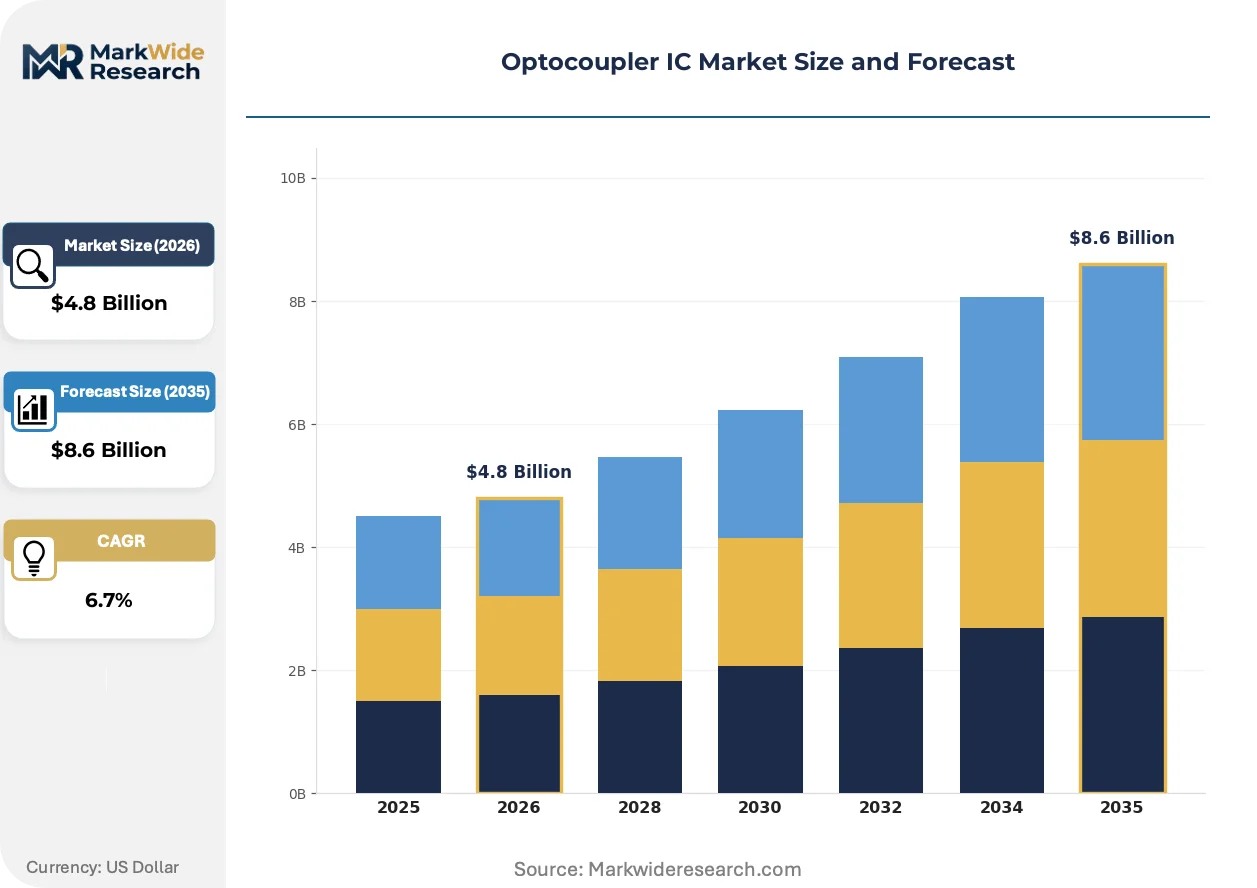
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phototransistor, Photodiode, Photomultiplier, Solid-State Relay Technology: Voltage-Controlled, Current-Controlled, Isolation Barrier, Optoelectronic Application: Industrial Automation, Consumer Electronics, Medical Devices, Telecommunications End User: Aerospace, Automotive, Energy, IT & Telecom |
| Companies Covered | ON Semiconductor, Renesas Electronics Corporation, Vishay Intertechnology, Lite-On Technology Corporation, Texas Instruments, Broadcom, Toshiba Electronic Devices & Storage Corporation, Everlight Electronics, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optocoupler IC Market Strategic Shifts
Photodiode technology is compressing switching latency benchmarks while regulatory fragmentation across medical, automotive, and industrial domains forces modular certification strategies. Procurement patterns favor suppliers offering cross-vertical qualification packages.
Digital isolators incorporating capacitive and magnetic coupling are integrating alongside traditional optocoupler architectures in hybrid signal chains. Automotive tier-1 suppliers adopt these combinations for battery management systems where AEC-Q100 Grade 0 temperature ratings are mandatory. The technology is integrating functional safety diagnostics that optical-only solutions cannot provide natively.
EU AI Act functional safety requirements are mandating signal isolation integrity in autonomous industrial systems. Machinery Directive updates impose SIL ratings on safety-related control circuits that optocouplers must demonstrably satisfy. Medical device manufacturers in Germany and France face compressed timelines as notified bodies align MDR conformity assessment with these parallel industrial standards.
Buyer concentration among automotive OEMs and industrial automation conglomerates is consolidating supplier qualification lists. Distributors report that volume commitments now precede technical evaluation, reversing traditional sampling protocols. This pattern is most pronounced in China where state-owned vehicle manufacturers centralize component procurement under MIIT-guided supplier frameworks.
Optocoupler IC Market Segmentation
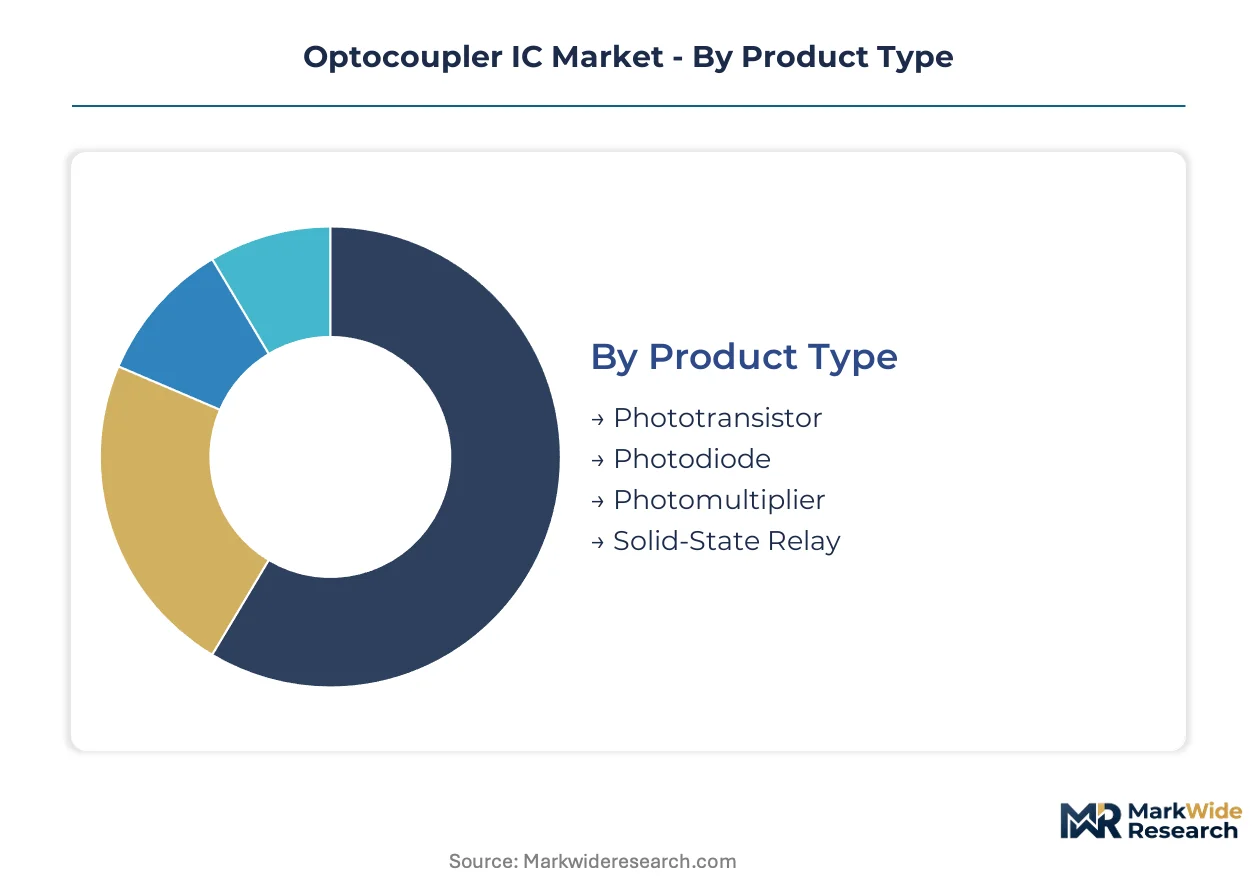
Optocoupler IC architectures fragment across signal fidelity requirements and isolation voltage ratings. Procurement teams weight switching speed against cost thresholds differently across automotive battery management and industrial motor control deployments.
Product Type:
Standardized phototransistor packages dominate high-volume consumer power supplies, while photodiode variants command customization premiums for sub-microsecond switching applications.
- Phototransistor:These devices pair infrared LED emitters with bipolar phototransistor detectors, achieving isolation voltages up to 5 kV with switching speeds typically below 1 MHz. Consumer power supply manufacturers in China source these in billion-unit annual volumes for appliance SMPS modules where cost minimization overrides speed requirements.
- Photodiode:PIN photodiode detectors deliver sub-100 nanosecond rise times with bandwidths exceeding 10 MHz, enabling deployment in electric vehicle battery management systems where AEC-Q100 Grade 0 temperature ratings and common-mode transient immunity above 25 kV/μs are mandatory.
- Photomultiplier:Vacuum-tube-derived devices with discrete dynode structures achieve single-photon sensitivity for medical imaging and radiation detection instrumentation.
- Solid-State Relay:Zero-crossing and random-phase TRIAC output configurations replace electromechanical relays in solar inverter DC-link switching where 20-year operational lifecycles eliminate contact wear failure modes.
Most installed capacity flows through Phototransistor. Expansion is steepest in Photodiode.
Technology:
Control methodology determines integration complexity and external component count across isolated power supply designs.
- Voltage-Controlled:Input-side voltage regulation simplifies feedback loop design in isolated DC-DC converters. Industrial automation OEMs in Germany specify these for PLC I/O modules where predictable transfer characteristics reduce calibration overhead.
- Current-Controlled:Current transfer ratio stability across temperature extremes suits battery management system voltage sensing where signal integrity must persist from -40°C to 150°C.
- Isolation Barrier:Reinforced insulation constructions with triple-layer dielectrics satisfy IEC 60747-5-5 safety standards for medical patient-connected equipment.
- Optoelectronic:Hybrid architectures combining GaAs LED emitters with silicon photodetector arrays enable multi-channel isolation in telecommunications line cards.
Voltage-Controlled variants hold the largest production footprint. Current-Controlled configurations are gaining share fastest in automotive-qualified portfolios.
Application:
End-use environment dictates creepage distance requirements and encapsulant material selection.
- Industrial Automation:Motor drive inverters and programmable logic controller I/O modules demand 2.5 kV to 5 kV isolation with extended temperature ranges. Factory automation retrofit cycles in Japan's automotive supplier base are accelerating replacement of legacy electromechanical relays.
- Consumer Electronics:Mobile charger and appliance power supply designs prioritize phototransistor cost efficiency over switching performance. India's PLI scheme for electronics manufacturing is attracting module assembly investments serving domestic appliance markets.
- Medical Devices:Patient-connected diagnostic and therapeutic equipment requires compliance with IEC 60601-1 collateral standards mandating isolation barriers with documented MTBF calculations.
- Telecommunications:5G base station power distribution and line card signal isolation pull photodiode variants with bandwidth exceeding 10 MHz for high-speed data path integrity.
Industrial Automation channels absorb the greatest component volume. Medical Devices applications are climbing the fastest as diagnostic equipment electrification accelerates.
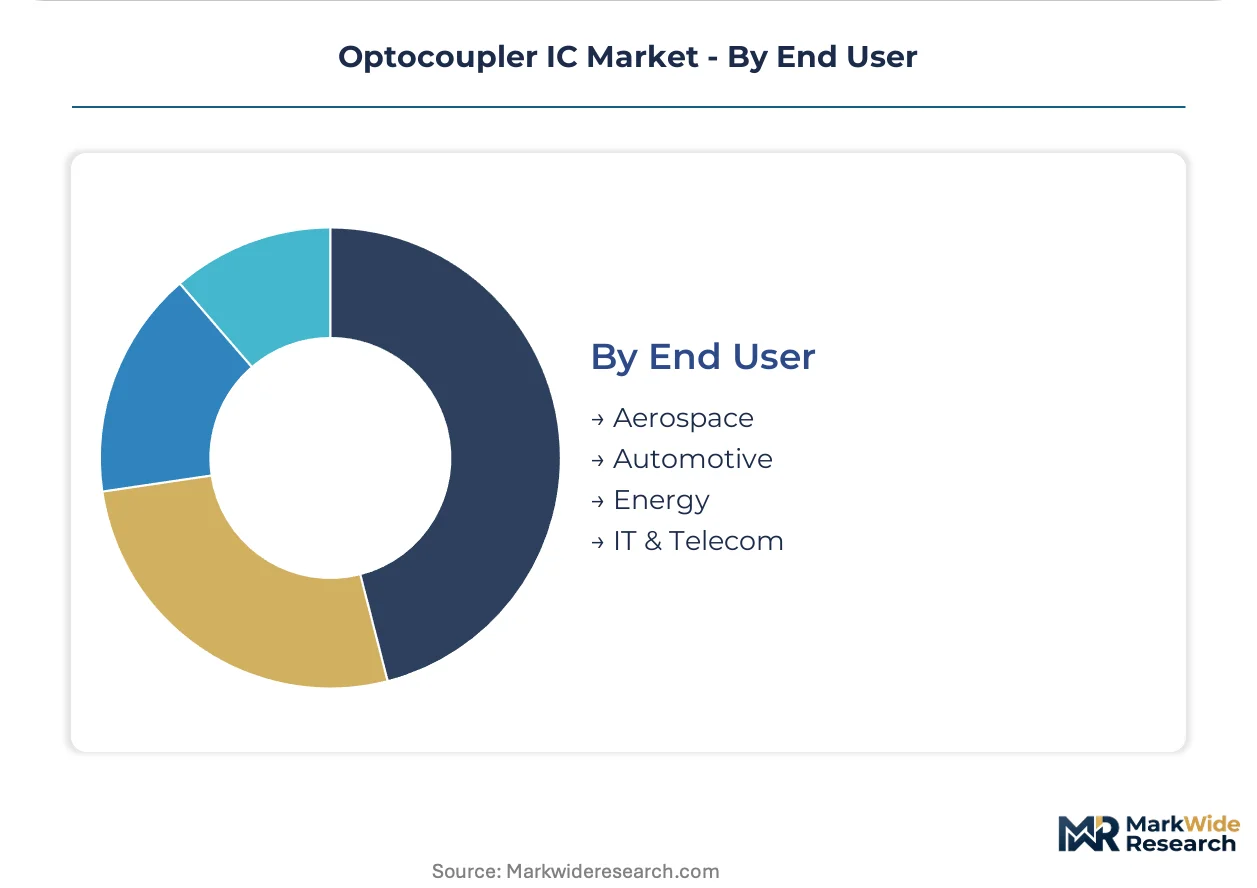
End User:
Vertical-specific certification requirements stratify supplier qualification timelines and margin structures.
- Aerospace:DO-160G environmental testing and MIL-PRF-38534 hermetic packaging specifications constrain the supplier base to radiation-hardened device specialists.
- Automotive:Battery management systems and onboard charger isolation dominate procurement volumes. China's state-owned vehicle manufacturers centralize component sourcing under MIIT-guided supplier frameworks that favor indigenous fabrication capacity.
- Energy:Solar inverters and grid-scale battery storage systems specify solid-state relay configurations for zero-contact wear in 20-year operational lifecycles.
- IT & Telecom:Datacenter power distribution units and server power supplies balance efficiency targets against isolation requirements in 48V DC bus architectures.
Automotive procurement exceeds all other verticals in annual component demand. Energy infrastructure applications are expanding most quickly as renewable deployment scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optocoupler fabrication originated in Japan's post-war electronics boom, with Tokyo-based laboratories pioneering GaAs LED emitter technology during the 1960s. This heritage established East Asian supply chain dominance that persists today.
China
MIIT localization targets redirect procurement toward domestic isolation device sourcing for electric vehicle battery management systems. GB 4943.1 national standards for information technology equipment safety create parallel compliance obligations alongside international specifications. Shenzhen and Shanghai fabrication clusters scale phototransistor output for appliance power supply modules serving both domestic and export markets.
United States
FDA mandates under IEC 60601-1 collateral standards drive isolation barrier requirements in patient-connected diagnostic equipment. NHTSA electrification targets pull photodiode variants into automotive onboard charger architectures. Texas and Arizona semiconductor corridors host backend packaging operations for industrial automation-qualified portfolios.
Germany
EU AI Act functional safety requirements impose SIL-rated signal isolation on autonomous industrial control systems. Machinery Directive updates compress optocoupler certification timelines for safety-related circuits. Bavarian automation OEMs in the Munich-Stuttgart corridor specify reinforced insulation constructions for motor drive inverters.
Japan
METI carbon neutrality roadmaps accelerate solid-state relay deployment in solar inverter DC-link switching. JIS standards for industrial equipment safety align with IEC 60747-5-5 isolation specifications. Nagoya-area automotive tier-1 suppliers concentrate procurement for battery management system photodiode integration.
South Korea
MFDS medical device regulations parallel FDA isolation requirements for diagnostic equipment exports. Government-backed semiconductor packaging investments support optocoupler module assembly for 5G telecommunications infrastructure. Seoul Capital Area fabs specialize in high-bandwidth photodiode output for base station line cards.
Optocoupler IC Market Competitive Environment
The competitive structure tilts toward diversified semiconductor conglomerates with captive LED fabrication capacity. Consolidation around vertically integrated GaAs substrate control has compressed mid-tier assembler margins. Three archetypes dominate: IDMs with in-house compound semiconductor foundries, fabless designers outsourcing to East Asian packaging houses, and industrial-component distributors leveraging broad channel reach. Capacity expansion and strategic portfolio diversification into automotive-qualified isolation products represent the dominant competitive moves.
Among diversified IDMs, ON Semiconductor, Renesas Electronics Corporation, and Vishay Intertechnology occupy positions spanning industrial automation through medical device channels. These entities exemplify the integrated fabrication archetype, with compound semiconductor substrate control supporting margin defense across high-reliability product lines. Their geographic footprints—Arizona-based, Tokyo-headquartered, and Pennsylvania-rooted respectively—mirror the tripolar supply chain configuration of optocoupler manufacturing.
| Leading Market Players |
|---|
| ON Semiconductor |
| Renesas Electronics Corporation |
| Vishay Intertechnology |
| Lite-On Technology Corporation |
| Texas Instruments |
| Broadcom |
| Toshiba Electronic Devices & Storage Corporation |
| Everlight Electronics |
| Infineon Technologies |
| Others |
Value Chain & Pricing Dynamics
Gallium arsenide wafer spot indices cascade through optocoupler fabrication tiers, compressing margins for phototransistor assemblers while reinforcing premium positioning for AEC-Q100-qualified photodiode suppliers serving automotive battery management channels.
Pricing Analysis
Three-tier pricing structure across automotive-grade, industrial-certified, and consumer-economy levels stratifies the optocoupler landscape. Automotive AEC-Q100 Grade 0 certification and IEC 60747-5-5 safety ratings drive price differentiation between tiers. Cost compression in consumer phototransistor segments is intensifying because Chinese domestic sourcing policies redirect volume toward indigenous suppliers. Industrial automation OEMs exhibit the lowest price sensitivity due to qualification timeline investments, while appliance power supply manufacturers in India and Southeast Asia remain most sensitive to unit cost.
Supply Chain Analysis
Dual-sourcing requirements from automotive Tier 1 suppliers mandate multi-fab qualification for GaAs LED emitters across Taiwan, Japan, and domestic China foundries. Compound semiconductor substrates draw from concentrated III-V wafer production anchored in East Asian chemical vapor deposition facilities. Single-source vulnerability persists in high-purity gallium refining capacity. Distribution runs through authorized component distributors serving industrial automation and medical device channels with certification documentation bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The optocoupler market functions as a regulatory compounder where IEC 60747-5-5 safety standard tightening and EU AI Act functional safety mandates generate structural demand pull across automotive and industrial verticals.
For Market Incumbents: Deploy captive GaAs substrate control to defend margin position against digital isolator substitution in battery management systems. Expand AEC-Q100 Grade 0 certification coverage for photodiode portfolios before MIIT localization targets fully redirect Chinese OEM procurement. Channel control through authorized distributor networks with bundled compliance documentation preserves qualification list positioning against emerging fabless competitors. For New Entrants and Emerging Players: Industrial automation retrofit channels in Japan and Germany offer the most penetrable white-space as legacy electromechanical relay replacement cycles accelerate. Solid-state relay configurations for solar inverter DC-link switching present second-entry opportunity with lower certification burden than automotive-qualified portfolios. Partner with semiconductor packaging houses in India's PLI scheme zones to establish cost-competitive module assembly capacity serving domestic appliance markets. For Investors and Strategic Acquirers: Asymmetric upside sits with compound semiconductor foundry specialists possessing ISO 9001 and IATF 16949 dual certification that enables cross-vertical qualification. Long-term viability hinges on architectural positioning for silicon carbide gate driver integration in 800V electric vehicle platforms. Watch for MIIT supplier framework list publication as inflection signal for indigenous Chinese sourcing acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Grade 0 Certification Investment | Unlocks procurement access to battery management systems in 800V electric vehicle platforms from state-owned Chinese OEMs. |
| GaAs LED Fabrication Capacity Expansion | Secures margin control against III-V wafer price volatility from East Asian foundry concentration. |
| REACH-Compliant Encapsulant Reformulation | Enables preferential EU market access as ECHA substance restrictions tighten on halogenated flame retardants. |
| Solid-State Relay Product Line Launch | Captures electromechanical relay replacement demand in solar inverter DC-link switching with 20-year lifecycle positioning. |
| India PLI Zone Packaging Partnership | Establishes cost-competitive module assembly serving domestic appliance and automotive markets with localized sourcing credentials. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with optocoupler product managers, automotive Tier 1 procurement leads, industrial automation OEM design engineers, and semiconductor distribution channel heads with secondary validation through IEC standard documentation, SEC 10-K filings from listed component suppliers, customs trade data for GaAs substrate flows, and MIIT policy circulars. Bottom-up build from application-level unit economics and top-down cross-check against vertical demand aggregates ensured triangulation integrity.
Historical reference periods anchored the projection horizon through documented phototransistor and photodiode shipment patterns across consumer electronics, industrial automation, automotive, and medical device end uses. Segmentation dimensions modeled included detector type, isolation voltage rating, control methodology, certification tier, and geographic sourcing cluster. CAGRs derived from regression against electric vehicle production trajectories, renewable energy deployment schedules, and factory automation capital expenditure cycles with sensitivity testing for GaAs wafer price volatility and regulatory timeline compression.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MIIT localization enforcement intensity and digital isolator technology maturation in automotive signal chains. Deviation in IEC 60747-5-5 certification timeline acceleration or gallium supply chain disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
EPON ONU Market
Optoelectronics
United States Optoelectronics Market
Optoelectronics
China Optical Detector Market
Optoelectronics
Algainp Epitaxial Wafers Market
Optoelectronics
Global Infrared Optoelectronics Market
Optoelectronics
Optoelectronic Transducers Market
Optoelectronics
Optical Emission Spectroscopy Market
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
Europe Wigig Market
Optoelectronics
Quantum Dots Market
Optoelectronics
Asia-Pacific Optoelectronics Market
Optoelectronics
Optoelectronics Market
Optoelectronics
Taiwan Optoelectronics Market
Optoelectronics
Electro-Optical/Infrared (EO/IR) Systems Market
Optoelectronics
Laser Projector Market
Optoelectronics
Gunn Diode Market