
 Pedestrian Entrance Control System Market | 2026-2036
Pedestrian Entrance Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Pedestrian Entrance Control System Market Analytics
Market Context
A wide capital-intensity divergence between full-stack platform providers and component assemblers is reorganizing competitive tiers in pedestrian entrance control. PERCo leverages in-house manufacturing of electromechanical turnstile mechanisms to sustain price competitiveness across Eastern European transit projects. Honeywell anchors its position through deep integration with building management software, while ZKTeco competes aggressively on biometric sensor cost curves across Asian commercial deployments. Dormakaba Holding differentiates through premium architectural access gates that occupy high-margin corporate headquarters segments.
Technical Definition and Segment Structure
A pedestrian entrance control system comprises electromechanical barriers, credential verification modules, and traffic management logic that regulates individual entry and exit through secured perimeters, typically processing throughput rates of 25 to 60 persons per minute depending on barrier type and authentication method. Turnstiles retain the largest installed base across transit and stadium applications, though speed gates are recording the fastest expansion in commercial buildings where aesthetic integration and high throughput converge. Biometric verification is displacing RFID systems in high-security installations, while smartphone integration is capturing retrofit opportunities as building operators seek credential-less entry without full hardware replacement.
Regulatory Environment and Outlook
The EU AI Act, GDPR, and CE marking requirements collectively constrain facial recognition deployments in European public venues, forcing vendors to architect opt-in consent workflows and local data processing. In the United States, FCC certification governs wireless credential transmission, while OSHA guidelines influence emergency egress override specifications for indoor installations. Stakeholders must monitor evolving biometric privacy legislation across multiple jurisdictions to anticipate product certification burdens and access restrictions before committing to regional manufacturing footprints.
Market Dynamics
Biometric credential verification is compressing hardware replacement cycles as airports and commercial landlords demand touchless entry workflows that integrate with existing building management infrastructure without full perimeter reconstruction.
Growth Catalysts
- EU AI Act compliance mandates:European transit authorities are accelerating procurement of GDPR-certified facial recognition modules to meet biometric processing consent requirements ahead of enforcement deadlines.
- Airport modernization programs:Hub airports in Germany, the United States, and China are deploying speed gates with integrated passenger flow analytics to reduce boarding gate congestion.
- Smartphone credential integration:Near-field communication and Bluetooth Low Energy protocols are enabling retrofit access control without replacing electromechanical barrier hardware.
Market Restraints
- Semiconductor supply concentration:Biometric sensor chip fabrication depends on Taiwan-based foundry capacity, creating lead time volatility for facial recognition module vendors.
- GDPR biometric processing restrictions:European public venue operators face opt-in consent workflow complexity that limits deployment scale in transit and stadium applications.
- Mechanical component input costs:Stainless steel and aluminum price fluctuations directly impact turnstile mechanism manufacturing margins.
Strategic Opportunities
- India transit infrastructure buildout:Metro rail expansion in Delhi, Mumbai, and Bengaluru creates demand for high-throughput speed gates with local manufacturing content requirements.
- Healthcare facility touchless entry:Hospital systems are specifying antimicrobial surface treatments and gesture-activated credential readers to reduce pathogen transmission vectors.
- 5G-enabled remote diagnostics:Predictive maintenance contracts leveraging cellular connectivity are creating recurring revenue streams for gate mechanism providers.
Industry Challenges
- Embedded systems cybersecurity certification:IEC 62443 compliance for industrial control systems is extending product development timelines for connected entrance control platforms.
- Legacy Wiegand protocol integration:Building operators with existing access control infrastructure require backward-compatible credential readers that complicate pure-IP architecture rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pedestrian Entrance Control System Market |
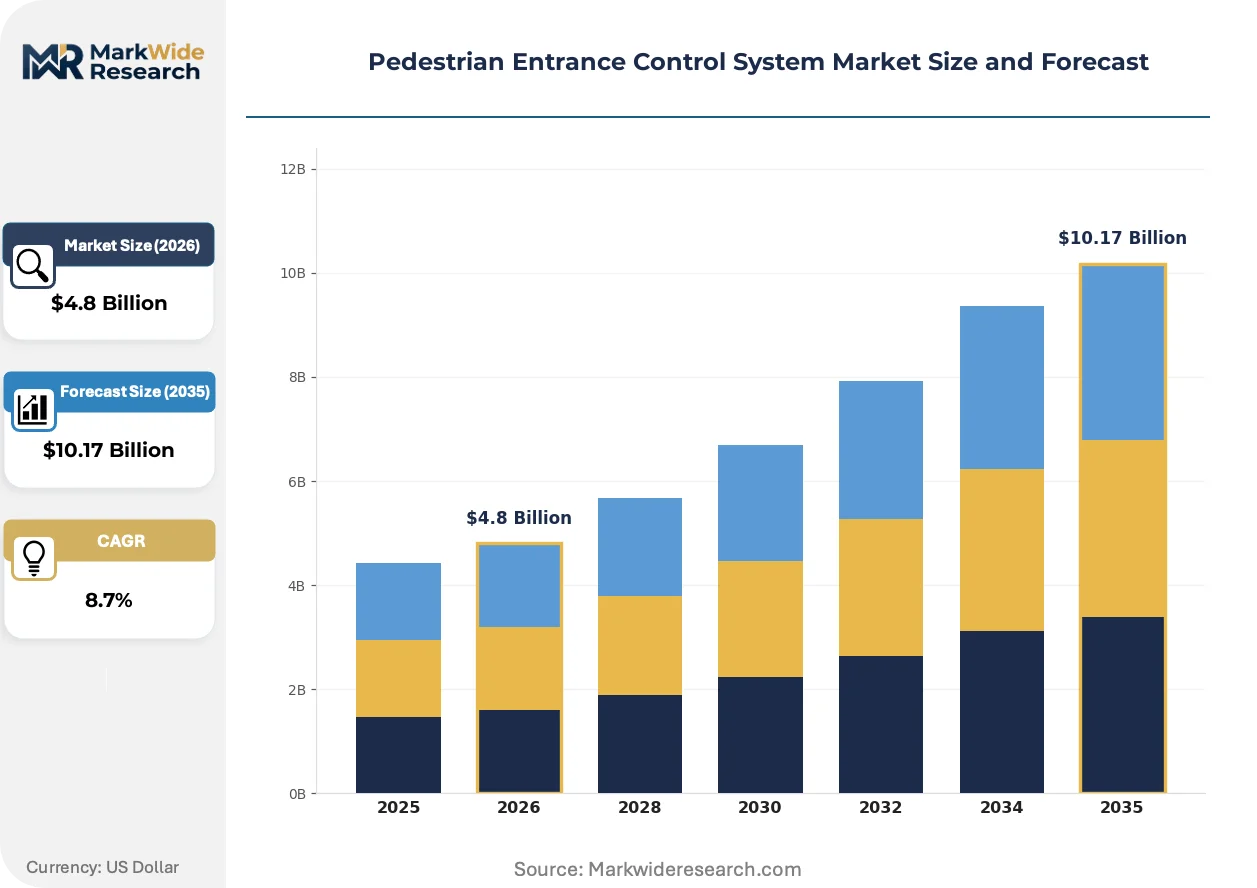
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turnstiles, Access Gates, Barrier-Free Solutions, Speed Gates Technology: Biometric Verification, RFID Systems, Keypad Entry, Smartphone Integration Installation Type: Indoor Systems, Outdoor Systems, Retrofit Solutions, New Installations End User: Commercial Buildings, Educational Institutions, Transit Stations, Public Venues |
| Companies Covered | PERCo, ZKTeco, Honeywell, Johnson Controls, Magnetic Autocontrol, Dormakaba Holding, Boon Edam, HID Global, ASSA ABLOY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pedestrian Entrance Control System Market Evolving Landscape
Three interconnected shifts are restructuring how entrance control systems are specified, procured, and operated: biometric modality diversification, regulatory-driven data localization, and the unbundling of hardware from software service layers.
Contactless palm vein recognition is displacing fingerprint sensors in high-security pharmaceutical and data center installations where hygiene protocols and spoofing resistance outweigh cost premiums. Facility managers in Singapore and Switzerland are piloting dual-factor authentication combining palm geometry with mobile credentials. This displacement is compressing demand for capacitive fingerprint modules and forcing sensor vendors to reallocate R&D toward vascular pattern algorithms.
GDPR Article 9 restrictions on special category data processing are compelling European vendors to architect edge-computing architectures that process biometric templates locally rather than transmitting to cloud servers. Germany's Federal Commissioner for Data Protection and Freedom of Information has issued guidance favoring on-device template storage for public sector deployments. System integrators are responding by specifying Linux-based gate controllers with encrypted local storage and audit logging capabilities.
Building operators are unbundling entrance control hardware procurement from software licensing and maintenance contracts, creating direct relationships with cloud-based access management platforms. Commercial real estate investment trusts in the United States are consolidating vendor relationships through portfolio-wide software subscriptions while sourcing barriers from competitive bidding processes. This bifurcation is visible most acutely in Class A office renovations in New York and Chicago where landlords prioritize interoperability with tenant experience applications over single-vendor stack integration.
Pedestrian Entrance Control System Market Segmentation
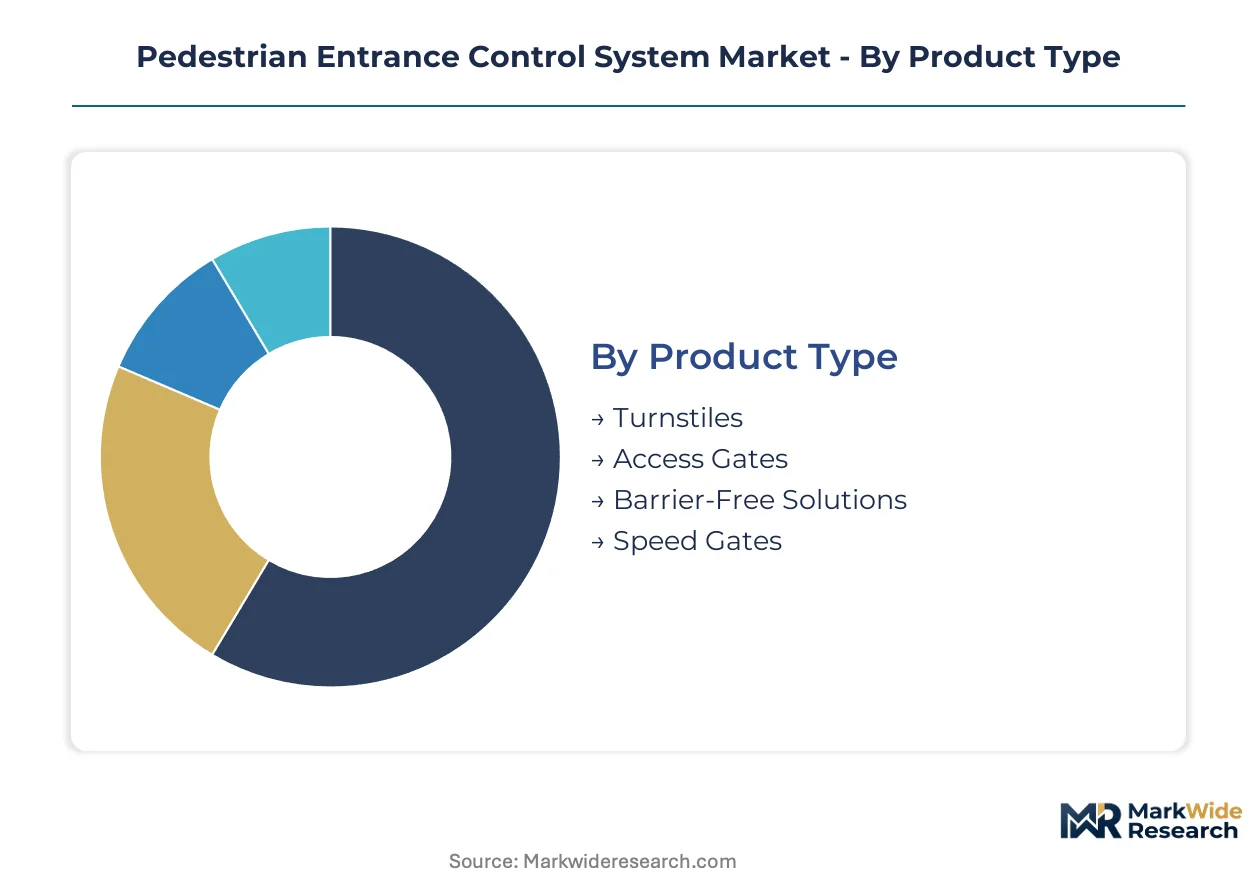
Segmentation in pedestrian entrance control reveals how procurement patterns diverge between infrastructure-heavy transit deployments and aesthetic-sensitive corporate installations. Vendors configure electromechanical platforms, credential modules, and software layers differently across these divides, creating distinct margin structures and replacement cycle dynamics.
Product Type:
Export-led demand concentrates in speed gates and access gates for airport and commercial building projects across Germany, China, and the United States. Domestic manufacturing anchors turnstile production for municipal transit authorities in Eastern Europe and India.
- Turnstiles:Tripod and full-height electromechanical barriers constructed from stainless steel housings with rotating arm mechanisms process 25-30 persons per minute. Demand concentrates in Delhi Metro, Mumbai Metro, and Eastern European stadium projects where PERCo and local vendors compete on manufacturing content compliance.
- Speed Gates:Sleek retractable-wing barriers with glass or acrylic panels achieve 40-60 persons per minute throughput while integrating with building aesthetics. Hub airports in Germany, the United States, and China specify these for passenger flow analytics integration and biometric credential compatibility.
- Access Gates:Swing or sliding barriers accommodate wheelchair access and wide-load entry in corporate headquarters and healthcare facilities.
- Barrier-Free Solutions:Optical or sensor-based detection systems monitor passage without physical obstruction, deployed in retail and hospitality environments prioritizing open sightlines.
Turnstiles command the established base across transit and stadium infrastructure. The steepest expansion runs through speed gates as commercial landlords and airports prioritize throughput with architectural integration.
Technology:
Cost tier stratification separates premium biometric modules from commodity RFID and keypad systems, with smartphone integration capturing retrofit volume at mid-tier price points.
- Biometric Verification:Facial recognition, fingerprint, and palm vein sensors process credential templates through edge-computing controllers. GDPR Article 9 compliance and EU AI Act consent requirements are forcing architectural shifts toward on-device processing in European public venues.
- Smartphone Integration:Near-field communication and Bluetooth Low Energy protocols transmit credentials from mobile devices to existing reader hardware. Building operators in New York and Chicago Class A offices deploy this for tenant experience app interoperability without full perimeter reconstruction.
- RFID Systems:Proximity and smart card readers dominate legacy building infrastructure with Wiegand protocol backward compatibility.
- Keypad Entry:PIN-based authentication persists in cost-sensitive educational and small commercial deployments.
RFID systems retain the largest installed base among legacy infrastructure. Biometric verification is gaining share fastest as airports and pharmaceutical facilities mandate touchless, high-assurance credentialing.
Installation Type:
Volume concentration favors new installations in China's urban rail expansion and India's metro buildout, while retrofit solutions capture margin in North American and European building stock upgrades.
- New Installations:Integrated electromechanical, credential, and software stacks specified during construction or major renovation. Greenfield transit projects in Delhi, Mumbai, and Bengaluru drive demand for high-throughput speed gates with local manufacturing content.
- Outdoor Systems:Weatherized housings with IP65+ ratings and heated components sustain operation in extreme temperature ranges.
- Indoor Systems:Standard-duty mechanisms deployed in climate-controlled commercial and institutional environments.
- Retrofit Solutions:Credential reader upgrades and controller replacements that preserve existing barrier hardware. Smartphone integration modules allow credential-less entry without full perimeter reconstruction.
New installations dominate revenue in emerging market infrastructure buildouts. Retrofit solutions are expanding most quickly in mature markets as building operators seek software-layer upgrades without capital-intensive hardware replacement.
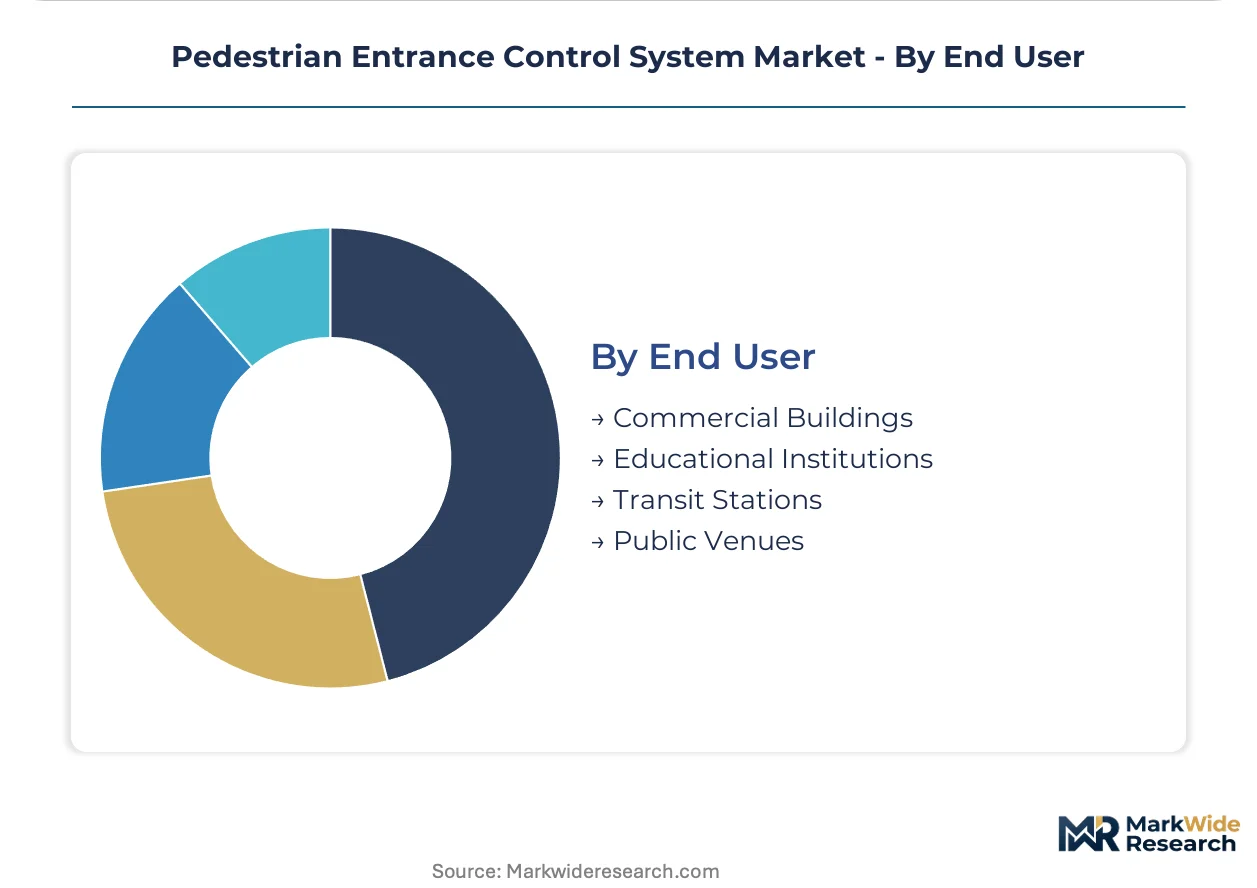
End User:
Customer type segmentation separates high-volume, price-sensitive transit procurement from premium-margin corporate and institutional deployments with aesthetic and integration requirements.
- Transit Stations:High-throughput, vandal-resistant turnstiles and speed gates with integrated fare collection and passenger analytics. Airports in Germany, the United States, and China deploy biometric-enabled gates to reduce boarding gate congestion.
- Commercial Buildings:Architecturally integrated speed gates and access gates with building management software interoperability. Class A office landlords in New York and Chicago prioritize tenant experience app integration.
- Educational Institutions:Cost-optimized turnstile and access gate configurations with basic credential verification.
- Public Venues:High-capacity, rapid-cycling barriers for stadiums and entertainment facilities with emergency egress override specifications.
Transit stations anchor volume demand through government-funded modernization programs. Commercial buildings are climbing the fastest as real estate investment trusts consolidate portfolio-wide access management platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows favor speed gate and access gate manufacturers supplying airport and commercial building projects, while domestic production anchors turnstile supply for municipal transit authorities. Germany, the United States, and China absorb the majority of high-throughput system deployments. Import dependencies concentrate in biometric sensor modules and semiconductor components.
United States
Hub airports in Atlanta, Dallas-Fort Worth, and Denver deploy biometric-enabled speed gates to reduce boarding gate congestion and integrate with CBP Traveler Verification Service. FCC certification governs wireless credential transmission protocols for commercial building retrofits. Class A office landlords in New York and Chicago consolidate portfolio-wide access management platforms through software subscription models.
Germany
Frankfurt and Munich airports scale passenger flow analytics integration with EU AI Act-compliant facial recognition modules. The Federal Commissioner for Data Protection and Freedom of Information mandates on-device template storage for public sector biometric deployments. Industrial clusters in Bavaria and Baden-Württemberg host system integrators specializing in CE-marked edge-computing gate controllers.
China
Urban rail expansion in Beijing, Shanghai, and Shenzhen drives procurement of high-throughput speed gates with integrated fare collection systems. GB standards and MIIT cybersecurity certifications shape product specifications for domestic transit authorities. Pearl River Delta manufacturers supply electromechanical mechanisms for export markets across Southeast Asia and the Middle East.
India
Metro rail buildout in Delhi, Mumbai, and Bengaluru creates demand for turnstiles and speed gates with local manufacturing content requirements under the PLI scheme. The Bureau of Indian Standards mandates safety and performance testing for electromechanical barriers in public transit. Domestic fabricators in Maharashtra and Karnataka compete with Chinese imports on price-sensitive municipal tenders.
United Kingdom
Heathrow and Gatwick airports modernize passenger processing infrastructure with GDPR-certified biometric entry systems. The Information Commissioner's Office enforces Article 9 restrictions on special category data processing in public venues. London commercial real estate investment trusts pilot smartphone credential integration across Class A office portfolios.
Pedestrian Entrance Control System Market Competitive Landscape
Concentration sits with diversified building technology conglomerates and specialized electromechanical barrier manufacturers. Full-stack platform providers compete through deep software integration with building management systems, while component assemblers compete on manufacturing scale and price positioning. Two strategic archetypes dominate: vertically integrated hardware producers with captive electromechanical fabrication, and software-centric integrators unbundling access management from barrier procurement. Competitive moves center on M&A for biometric sensor capabilities and strategic partnerships with cloud-based credential platforms.
Among diversified technology conglomerates, Honeywell International Inc. and Johnson Controls International plc exemplify the integrated building systems archetype, anchoring positions through software layer control. Specialized barrier manufacturers include PERCo and ZKTeco Co., Ltd., representing the electromechanical fabrication and biometric sensor cost curve archetypes respectively. Dormakaba Holding AG occupies a position within the premium architectural access segment. These named entities illustrate how competitive positioning stratifies across integration depth, manufacturing geography, and end-user segment specialization.
| Leading Market Players |
|---|
| PERCo |
| ZKTeco |
| Honeywell |
| Johnson Controls |
| Magnetic Autocontrol |
| Dormakaba Holding |
| Boon Edam |
| HID Global |
| ASSA ABLOY |
| Others |
Value Network & Pricing Analysis
Forty-five to sixty-day lead times for biometric sensor modules concentrate pricing power with Taiwan-based foundries while compressing margins for European system integrators facing GDPR compliance retrofit costs. This inventory-to-delivery gap separates full-stack platform providers commanding project-based premiums from component assemblers competing on stainless steel mechanism spot pricing.
Pricing Analysis
Configured-to-order pricing for airport speed gates with integrated passenger flow analytics commands 40-60% premiums over standard turnstile configurations for municipal transit. Three-tier pricing structure across premium architectural access gates, standard commercial speed gates, and economy tripod turnstiles stratifies the market by certification grade and after-sales service bundling. Cost compression in the economy tier intensifies as Indian domestic fabricators undercut Chinese imports on PLI-compliant tenders. Transit authorities in Eastern Europe exhibit highest price sensitivity, while corporate headquarters in Germany and the United States prioritize interoperability premiums over unit economics.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for facial recognition sensor chips, while China and Germany dominate electromechanical barrier mechanism production. Stainless steel housings and aluminum arm assemblies feed from foundries in the Pearl River Delta and Bavarian industrial clusters. Single-source vulnerability in biometric semiconductor supply creates lead time volatility that ripples through European airport modernization timelines. Distribution runs through system integrators specifying CE-marked edge-computing controllers for GDPR-compliant deployments, with direct procurement emerging for software-layer subscriptions decoupled from hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as commercial real estate investment trusts consolidate portfolio-wide access management platforms, shifting procurement leverage from hardware vendors to cloud-based software orchestrators. This consolidation fragments the vendor base between full-stack incumbents and unbundled component suppliers.
For Market Incumbents: Shield software layer control through deeper building management system integration, as Honeywell and Johnson Controls anchor positions against emerging cloud-native entrants. Captive electromechanical manufacturing in Eastern Europe defends margin position against Chinese cost curves. Prioritize GDPR Article 9 certification investment to maintain European public venue access against regulatory exclusion. For New Entrants and Emerging Players: Differentiate on palm vein recognition modules for pharmaceutical and data center installations where hygiene protocols justify cost premiums over fingerprint alternatives. Target India's metro rail buildout with local manufacturing content compliance under PLI scheme requirements. Pursue smartphone credential retrofit opportunities in New York and Chicago Class A offices where tenant experience app interoperability creates switching costs. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified building technology conglomerates spinning off non-core entrance control divisions to focus on software-centric platforms. Long-term viability hinges on biometric modality diversification and edge-computing architecture ownership. Watch for inflection in 5G-enabled predictive maintenance contract attach rates as recurring revenue quality signal.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Sensor Capability Acquisition | Facial recognition and palm vein modules displace RFID in high-security pharmaceutical and airport installations. |
| Edge-Computing Architecture Investment | On-device template storage satisfies GDPR Article 9 and EU AI Act consent requirements for European public venues. |
| Smartphone Credential Platform Partnership | NFC and Bluetooth Low Energy integration captures retrofit volume without full perimeter hardware replacement. |
| Local Manufacturing Footprint Expansion | PLI scheme compliance in India and CE marking capacity in Germany secure transit authority procurement access. |
| Predictive Maintenance Service Layer Development | 5G-enabled remote diagnostics create recurring revenue streams decoupled from equipment replacement cycles. |
Research Methodology
Operator-level perspectives from airport facilities managers, commercial real estate technology directors, transit authority procurement officers, and biometric system integrators anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SEC filings of building technology conglomerates, EU AI Act implementation guidance, and BIS safety certification records for Indian metro tenders. Bottom-up unit economics triangulated against top-down infrastructure investment forecasts across the analysis window.
Sensitivity analysis tested volume and value outputs against semiconductor supply disruption scenarios and regulatory enforcement timing variations. Segmentation dimensions modeled include product type, credential technology, installation context, and end-user vertical with regional regulatory cluster differentiation. CAGRs derived from installed base replacement cycles and greenfield infrastructure buildout pipelines, with biometric penetration rates and smartphone credential adoption curves as industry-specific forecast inputs.
Material uncertainties — Taiwan foundry capacity allocation, GDPR biometric processing enforcement intensity, stainless steel input cost volatility — sit outside the modeled envelope. Forecasts reflect assumptions regarding transit modernization program continuity and commercial building renovation activity levels. Recalibration cycles align with material shifts in semiconductor supply availability and European data protection regulatory guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Global Fingerprint Access Control Systems Market
Access Control Systems
Programmable Safety Systems Market
Access Control Systems
Access Control As a Service Market
Access Control Systems
Global Automatic Door Control Market
Access Control Systems
Industrial Barrier Systems Market
Access Control Systems
United States Smart Lock Market
Access Control Systems
Global Industrial Safety Gates Market
Access Control Systems
Modular Biometric Access Control Terminals Market
Access Control Systems
Role-Based Access Control (RBAC) Market
Access Control Systems
Border Security System Market
Access Control Systems
GCC Home Security Systems Market
Access Control Systems
Airport Passenger Screening System Market
Access Control Systems
Bluetooth Smart Lock Market
Access Control Systems
Padlock Smart Lock Market
Access Control Systems
Global Home Security Systems Market
Access Control Systems
Asia Pacific Access Control Software Market