
 Card-Based Electronic Access Control Systems Market | 2026-2036
Card-Based Electronic Access Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Card-Based Electronic Access Control Systems Market Analysis
Enterprise campuses is unwinding legacy reliance on small-business standalone units as multi-site corporations consolidate credential management under unified platforms. HID Global Corporation leverages its dominance in secure identity credential manufacturing to anchor high-assurance government contracts. ASSA ABLOY AB sustains channel control through its Aperio wireless lock ecosystem, competing directly against traditional hardwired retrofit projects. Allegion plc differentiates via Schlage mobile-enabled readers that bridge Bluetooth Low Energy and NFC credential formats.
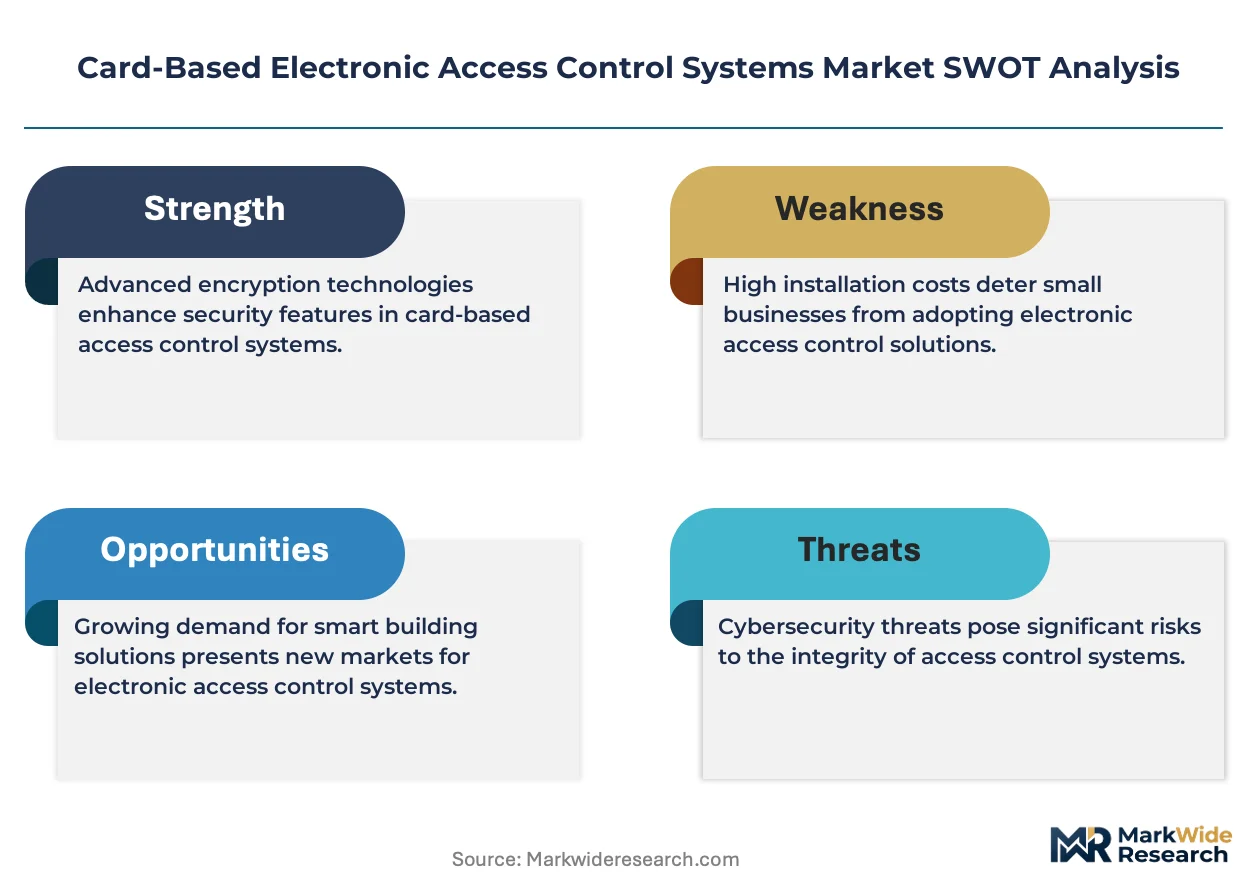
Card-based electronic access control systems comprise credential readers, encoding infrastructure, and management software that authenticate identity through stored data on plastic or composite cards, typically operating at 13.56 MHz for contactless protocols or 125 kHz for proximity legacy systems. These systems enforce perimeter security, time-bound entry rights, and audit trails across commercial and institutional facilities. Contactless smart cards lead product type demand due to AES-128 encryption standards and DESFire compatibility, while biometric cards represent the fastest-growing segment as fingerprint-on-card modules displace separate biometric terminals. Building security applications command the largest application share, though visitor management is accelerating as enterprises integrate pre-registration platforms with temporary credential issuance.
FCC certification governs radio-frequency emissions for credential readers deployed across United States commercial infrastructure, while the EU Cybersecurity Act mandates Common Criteria evaluation for government building access systems in member states. ISO/IEC 14443 and ISO/IEC 7816 standards define physical and protocol interoperability, shaping procurement specifications for multinational rollouts. Stakeholders must monitor convergence between physical access credentials and IT identity platforms, as zero-trust architectures dissolve traditional boundaries between cyber and physical security domains.
Market Dynamics
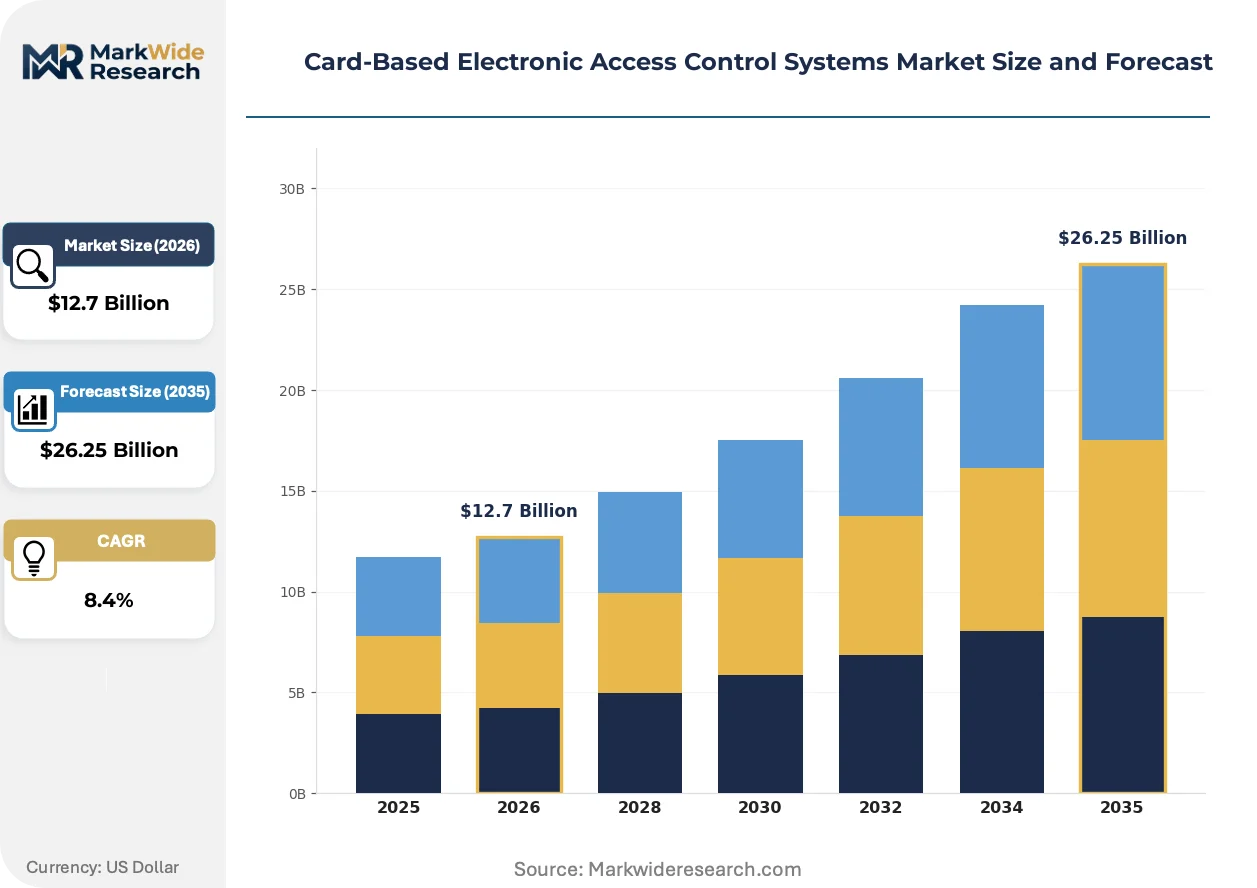
Enterprise consolidation of credential management under unified platforms is compressing vendor margins while accelerating hardware refresh cycles across multi-site campuses. This structural force favors integrated platform providers over standalone unit manufacturers.
Growth Catalysts
- EU Cybersecurity Act mandates:Common Criteria evaluation requirements for government building access systems in member states are forcing hardware upgrades across public infrastructure portfolios.
- Contactless protocol migration:Industrial facilities in Germany's Rhine-Ruhr corridor are replacing 125 kHz proximity systems with 13.56 MHz DESFire-compatible credentials for AES-128 encryption compliance.
- Visitor management platform integration:Enterprise campuses are linking pre-registration systems with temporary credential issuance, expanding addressable use cases beyond permanent employee access.
Market Restraints
- Semiconductor supply concentration:Secure element chip fabrication for contactless smart cards concentrates in Taiwan and South Korea, exposing procurement to geopolitical disruption.
- Legacy 125 kHz infrastructure lock-in:Proximity reader installed bases in North American commercial real estate create switching cost barriers for credential format upgrades.
- Biometric card module cost structure:Fingerprint-on-card sensors require specialized flex circuit substrates that carry 3-4x material cost premiums versus standard PVC laminates.
Strategic Opportunities
- Zero-trust architecture convergence:Physical access credentials are merging with IT identity platforms, creating white space for vendors bridging PACS and IAM systems.
- Temporary credential automation:Logistics hubs and event venues are adopting self-service kiosk issuance for contractor and visitor flows, opening mid-market deployment channels.
- GDPR-compliant audit trail services:Data residency requirements for access log storage are generating recurring revenue opportunities in EU member states.
Industry Challenges
- Multi-protocol reader engineering:Supporting simultaneous Bluetooth Low Energy, NFC, and legacy proximity formats strains firmware development timelines and certification cycles.
- FCC Part 15 emissions compliance:Radio-frequency credential readers require iterative testing for unintentional radiator limits, extending product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Card-Based Electronic Access Control Systems Market |
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $26.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contactless Smart Cards, Magnetic Stripe Cards, Proximity Cards, Biometric Cards End User: Commercial Offices, Educational Institutions, Healthcare Facilities, Government Buildings Technology: RFID, NFC, Bluetooth Low Energy, Biometric Authentication Application: Time and Attendance, Building Security, Event Management, Visitor Management |
| Companies Covered | Honeywell International Inc., Identiv Inc., HID Global Corporation, Siemens AG, Bosch Security Systems GmbH, ASSA ABLOY AB, Allegion plc, Suprema Inc., Johnson Controls International plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Card-Based Electronic Access Control Systems Market Emerging Trajectories
Credential format diversification is fragmenting what was historically a standardized proximity card market into multi-protocol environments. This shift demands flexible reader hardware and complicates procurement standardization for enterprise buyers.
Biometric-on-card modules are fragmenting the traditional separation between physical access and biometric identity verification. Fingerprint sensors embedded directly into credential cards eliminate separate terminal hardware for high-assurance environments. Banking and government facilities are piloting these credentials for dual-factor authentication without dedicated biometric readers.
The EU Cybersecurity Act's Common Criteria certification requirements are restructuring procurement specifications for government building access across member states. Vendors must now submit products for independent evaluation against standardized security assurance levels. German federal facilities and French administrative buildings are among the earliest adopters, with certification timelines extending vendor sales cycles by 12-18 months.
Enterprise buyers are unbundling hardware procurement from long-term software maintenance contracts, compressing vendor recurring revenue streams. Multi-site corporations are negotiating direct credential management platform licenses while sourcing readers through distribution channels. This pattern is most pronounced in US commercial real estate and UK higher education campuses, where facilities management teams prioritize capital expenditure flexibility over bundled service agreements.
Card-Based Electronic Access Control Systems Market Segmentation
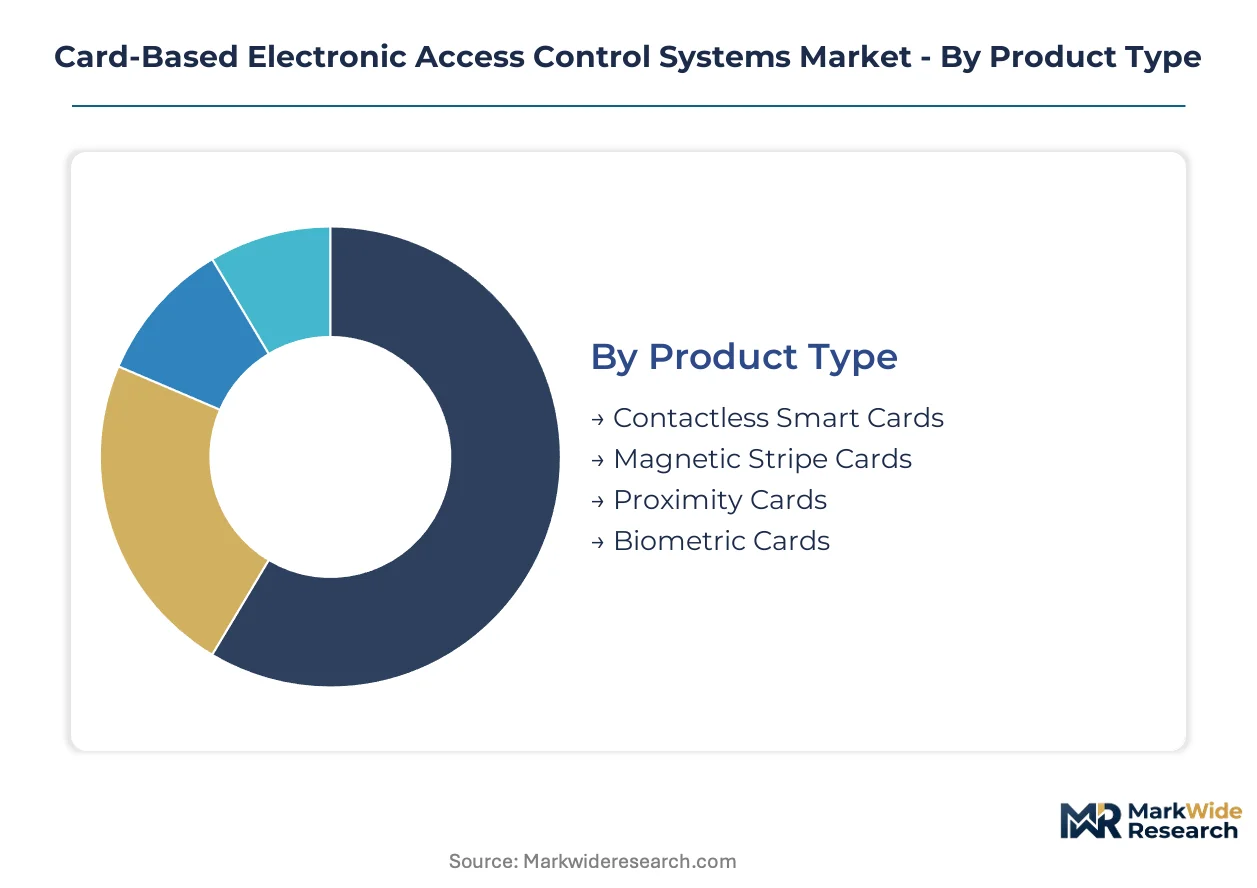
Segmentation in card-based access control reflects divergent compliance requirements across credential formats and deployment environments. Procurement specifications vary sharply between government mandates and commercial flexibility, creating distinct competitive arenas.
Product Type:
ISO/IEC 14443 and ISO/IEC 7816 standards create tiered security assurance levels that shape product positioning across credential categories.
- Contactless Smart Cards:Operating at 13.56 MHz with AES-128 encryption and DESFire compatibility, these credentials dominate enterprise campus deployments in Germany's industrial corridor. BASF and Siemens facilities drive large-scale migrations from legacy formats due to EU Cybersecurity Act mandates.
- Biometric Cards:Fingerprint-on-card modules embed capacitive sensors directly into credential substrates, eliminating separate biometric terminal hardware. Banking and government facilities pilot these for dual-factor authentication without dedicated readers, climbing the fastest among all product categories.
- Magnetic Stripe Cards:Legacy lo-co and hi-co magnetic encoding persists in cost-constrained retrofit scenarios where reader infrastructure replacement is deferred.
- Proximity Cards:125 kHz passive RF technology retains installed base lock-in across North American commercial real estate despite inferior security architecture.
Established volume favors proximity cards; emerging adoption favors biometric cards.
End User:
Capital expenditure cycles and security clearance requirements create divergent procurement rhythms across facility types.
- Government Buildings:Common Criteria evaluation under the EU Cybersecurity Act mandates hardware refresh cycles across German federal facilities and French administrative buildings, extending vendor sales timelines by 12-18 months.
- Commercial Offices:Multi-site corporations consolidate credential management under unified platforms, compressing vendor margins while accelerating hardware replacement across enterprise campuses.
- Healthcare Facilities:HIPAA audit trail requirements and patient flow management drive integration with clinical access systems.
- Educational Institutions:UK higher education campuses prioritize capital expenditure flexibility, unbundling hardware procurement from long-term software maintenance contracts.
Procurement standardization favors government buildings; contract flexibility favors educational institutions.
Technology:
Radio-frequency emissions compliance and interoperability certification fragment engineering requirements across protocol layers.
- RFID:13.56 MHz high-frequency systems achieve FCC Part 15 certification for unintentional radiator limits across United States commercial infrastructure, with iterative testing extending product launch schedules.
- NFC:ISO/IEC 14443 Type A and Type B protocols enable smartphone credential emulation, bridging physical access with IT identity platforms in zero-trust architectures.
- Bluetooth Low Energy:Schlage mobile-enabled readers leverage BLE for extended-range credential detection, competing against traditional hardwired retrofit projects.
- Biometric Authentication:Fingerprint template storage on-card or in-reader creates tiered privacy compliance obligations under GDPR data residency requirements.
Deployment maturity favors RFID; integration momentum favors NFC.
Application:
Use case complexity determines whether standalone units or integrated platform architectures prevail in system design.
- Building Security:Perimeter enforcement and time-bound entry rights command the largest application share, with multi-protocol readers supporting simultaneous NFC and legacy proximity formats.
- Visitor Management:Pre-registration platform integration with temporary credential issuance accelerates as enterprises adopt self-service kiosk deployment for contractor flows.
- Time and Attendance:Workforce tracking integration with payroll systems drives demand for audit trail granularity in logistics hubs.
- Event Management:High-volume temporary credential issuance at venues opens mid-market deployment channels distinct from permanent employee access systems.
Revenue concentration favors building security; expansion velocity favors visitor management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports card-based access control hardware to industrial facilities across France and the Netherlands, with cross-border credential standardization driving procurement alignment in the Rhine corridor.
United States
FCC Part 15 certification requirements govern radio-frequency emissions for credential readers deployed across commercial infrastructure. Multi-site corporations in Texas and California consolidate credential management under unified platforms, compressing vendor margins while accelerating hardware replacement cycles. The Pacific Northwest tech corridor pilots mobile-enabled readers bridging Bluetooth Low Energy and NFC formats.
Germany
BASF and Siemens facilities in the Rhine-Ruhr industrial corridor drive large-scale migrations from 125 kHz proximity systems to 13.56 MHz DESFire-compatible credentials. The EU Cybersecurity Act mandates Common Criteria evaluation for government building access systems, extending vendor sales timelines by 12-18 months across federal facilities. Bavaria's manufacturing clusters anchor high-assurance deployments for automotive and chemical plant security.
France
Administrative buildings in Île-de-France adopt Common Criteria-certified hardware ahead of EU-wide compliance deadlines. GDPR data residency requirements for access log storage generate recurring revenue opportunities for audit trail service providers. The Auvergne-Rhône-Alpes logistics hub integrates pre-registration platforms with temporary credential issuance for contractor flows.
United Kingdom
Higher education campuses prioritize capital expenditure flexibility, unbundling hardware procurement from long-term software maintenance contracts. London commercial real estate retains substantial 125 kHz proximity installed bases, creating switching cost barriers for credential format upgrades. Scottish government facilities accelerate hardware refresh cycles under post-Brexit security procurement frameworks.
China
GB standards and MIIT regulations shape domestic credential reader certification for commercial infrastructure. Yangtze River Delta manufacturing campuses deploy contactless smart cards with AES-128 encryption for perimeter security and workforce tracking integration. Shenzhen-based semiconductor fabrication supports secure element chip production for regional credential supply chains.
Card-Based Electronic Access Control Systems Market Vendor Landscape
Listed leaders compete with private specialists across platform integration capabilities, with market structure consolidating around multi-protocol hardware providers and fragmenting among standalone unit manufacturers. Strategic archetypes include integrated security conglomerates, wireless lock ecosystem specialists, and biometric-on-card module innovators. Dominant competitive moves encompass M&A for credential management software capabilities and strategic partnerships bridging physical access with IT identity platforms.
Within the integrated security tier, Honeywell International Inc. and Johnson Controls International plc exemplify scale-driven platform consolidation. ASSA ABLOY AB anchors wireless lock ecosystem control through channel-dominant distribution models. HID Global Corporation occupies a position representing secure identity credential manufacturing specialization for high-assurance government contracts.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Identiv Inc. |
| HID Global Corporation |
| Siemens AG |
| Bosch Security Systems GmbH |
| ASSA ABLOY AB |
| Allegion plc |
| Suprema Inc. |
| Johnson Controls International plc |
| Others |
Supply Flow & Price Mechanics
Secure element fabrication scale in Taiwan and South Korea establishes cost floors for contactless credential modules, compressing margins for reader manufacturers while concentrating procurement leverage among semiconductor foundries serving DESFire-compatible card programs.
Pricing Analysis
The 13.56 MHz contactless-to-125 kHz proximity technology-generation gap drives pricing stratification across credential tiers. Three-tier pricing structure across premium, standard, and economy levels reflects Common Criteria certification grade and AES-128 encryption compliance. Cost compression in economy-tier proximity cards intensifies because legacy installed base lock-in defends volume. Commercial real estate buyers exhibit highest price sensitivity; government facilities under EU Cybersecurity Act mandates show lowest.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for secure element chip shipments from Taiwan and South Korea. Supply concentration centers on Taiwan, South Korea, and China for NFC controller silicon, PVC laminate substrates, and flex circuit sensor modules. Raw material dependencies include copper-clad laminates, ferrite antenna cores, and cryptographic secure elements. Single-source vulnerability in Taiwan-based foundry capacity for high-assurance chips threatens continuity. Distribution runs through OEM direct contracts and security systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as EU Cybersecurity Act compliance deadlines force hardware refresh across government portfolios, accelerating replacement velocity beyond organic upgrade cycles.
For Market Incumbents: Compound platform integration advantages by acquiring credential management software specialists before mid-market competitors consolidate IAM-PACS bridge capabilities. Deepen backward integration into secure element sourcing through foundry partnerships in Taiwan to defend against semiconductor supply concentration. Prioritize Common Criteria pre-certification investments to compress 12-18 month sales timelines for German federal contracts. For New Entrants and Emerging Players: GDPR-compliant audit trail service gaps expose where incumbents under-serve EU data residency requirements, creating white-space for cloud-native compliance platforms. Target French administrative buildings and UK higher education campuses as most penetrable segments given unbundled procurement preferences and capital expenditure flexibility. Pursue channel partnerships with facilities management platforms rather than direct hardware competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biometric-on-card module innovators with fingerprint sensor integration capabilities ahead of mainstream adoption inflection. Five-to-ten year viability hinges on zero-trust architecture convergence between physical and IT security domains. Acquisition target archetype: wireless lock ecosystem specialists with Aperio-compatible channel control. Monitor DESFire EV3 certification velocity as adoption signal.| Strategic Initiative | Industry Significance |
|---|---|
| Common Criteria Pre-Certification | Accelerates vendor sales cycles by 12-18 months for German federal facility contracts. |
| Biometric-on-Card Module Development | Eliminates separate terminal hardware for banking and government dual-factor authentication pilots. |
| Zero-Trust Platform Integration | Bridges physical access credentials with IT identity management systems under unified architectures. |
| GDPR Audit Trail Service Launch | Generates recurring revenue from EU data residency requirements for access log storage. |
| Multi-Protocol Reader Engineering | Supports simultaneous BLE, NFC, and legacy proximity formats to capture fragmented upgrade cycles. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with security systems integrators, facilities management directors, and government procurement officers; and secondary validation through FCC equipment authorization databases, EU Cybersecurity Act certification registries, and SEC filings from listed security conglomerates. Bottom-up credential volume estimates triangulated against top-down platform revenue analysis.
Across the analysis window, the forecasting framework modeled segmentation by credential format, end-user facility type, and radio-frequency protocol layer. CAGRs derived from hardware replacement cycle analysis and compliance-driven refresh velocity. Industry-specific inputs included DESFire adoption curves and Common Criteria certification pipeline data.
Forecasts assume regulatory continuity in EU Cybersecurity Act implementation and FCC Part 15 emissions standards; material policy shifts would require re-modeling. Semiconductor supply disruption or tariff escalation on Taiwan-origin secure elements represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Asia Pacific Access Control Software Market
Access Control Systems
Facial Recognition Access Control Solution Market
Access Control Systems
Asia-Pacific Pin-Based Access Control Market
Access Control Systems
Japan Smart Lock Market
Access Control Systems
Access Control As a Service Market
Access Control Systems
United Kingdom Access Control Market
Access Control Systems
Access Control Market
Access Control Systems
Perimeter Intrusion Detection Systems Market
Access Control Systems
Role-Based Access Control (RBAC) Market
Access Control Systems
Electronic Cylinder Lock Credentials Market
Access Control Systems
Global Smart Lock Market
Access Control Systems
Turnstiles Access Control Systems Market
Access Control Systems
Global Barrier Systems Market
Access Control Systems
Locks Market
Access Control Systems
Canada Access Control Market
Access Control Systems
Smart Entry System Market