
 Airport Passenger Screening System Market | 2026-2036
Airport Passenger Screening System Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Passenger Screening System Market Analysis
Modular checkpoint architectures that separate passenger verification from threat detection is realigning procurement patterns across major aviation hubs. Smiths Detection leverages integrated software platforms to sustain technology leadership in computed tomography baggage scanners. Rapiscan Systems anchors its position through manufacturing scale in fixed-site explosive detection installations. OSI Systems competes by controlling service networks that extend equipment lifecycle value for government authorities.
Airport passenger screening systems comprise integrated hardware and software assemblies designed to detect prohibited items, explosives, and contraband on persons and in baggage, typically operating at throughput rates exceeding 400 passengers per hour per lane. These systems serve the primary commercial purpose of maintaining aviation security while minimizing passenger processing delays at transport nodes. Computed tomography technology leads product type investment as airports replace legacy X-ray machines with three-dimensional imaging capable of automatic threat recognition without liquid removal. Millimeter wave body scanners represent the fastest-growing technology segment, driven by privacy-compliant software upgrades that eliminate passenger-specific image storage. Fixed installations dominate the installation category, though mobile units are gaining traction among security agencies requiring rapid deployment for special events or temporary terminal expansions.
The Transportation Security Administration shapes United States demand through procurement mandates that specify detection thresholds and interoperability standards for checkpoint electronics. The European Union Aviation Safety Agency and EU Green Deal efficiency requirements jointly influence product design, pushing manufacturers toward lower-energy millimeter wave systems and reduced radiation backscatter architectures. Stakeholders must monitor how emerging artificial intelligence classification rules from multiple jurisdictions affect algorithm training data access and system certification pathways.
Market Dynamics
Automated threat recognition algorithms are compressing checkpoint staffing models while forcing hardware refresh cycles at major aviation hubs. TSA procurement mandates and EU aviation security directives are synchronizing to demand interoperable, AI-enabled screening architectures that legacy metal detectors cannot satisfy.
Growth Catalysts
- EU Aviation Security Regulation Updates:The European Union Aviation Safety Agency's cabin baggage detection standards are mandating computed tomography upgrades across Schengen airports, forcing equipment replacement timelines.
- Millimeter Wave Privacy Upgrades:Software-only enhancements to body scanners eliminate passenger-specific image storage, removing deployment barriers at privacy-sensitive jurisdictions.
- United States Hub Modernization:TSA procurement programs at Atlanta, Dallas-Fort Worth, and Denver International are consolidating demand for automated screening lanes with integrated verification.
Market Restraints
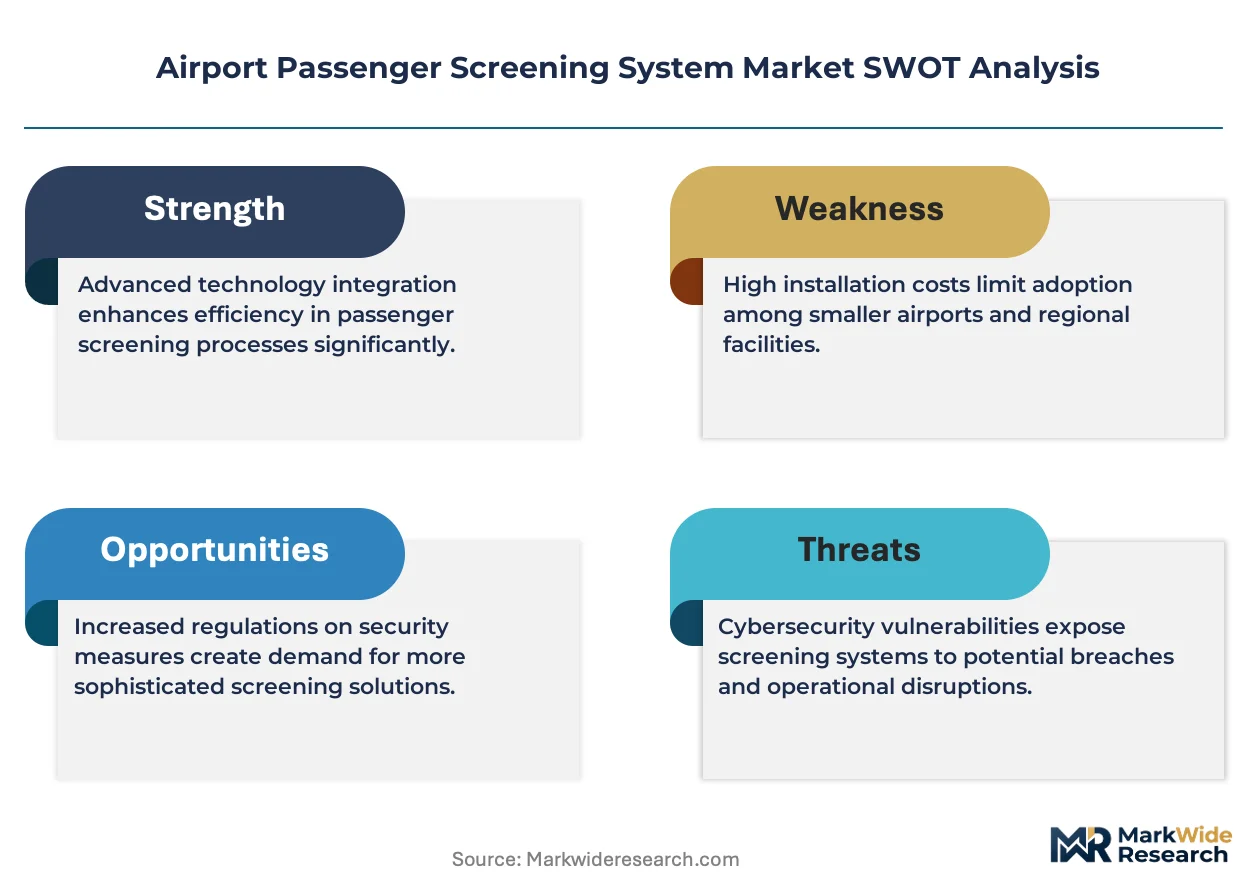
- Semiconductor Component Concentration:Advanced millimeter wave arrays and CT detector modules depend on specialized foundry capacity concentrated in East Asian supply chains, creating input vulnerability.
- Certification Timeline Friction:FAA and TSA joint certification pathways for new detection algorithms extend development-to-deployment cycles beyond typical capital planning horizons.
- Training Infrastructure Bottlenecks:Qualified technicians for CT scanner maintenance and AI system calibration remain scarce relative to installed base expansion rates.
Strategic Opportunities
- India Airport Authority Expansion:Greenfield terminal construction at Delhi, Mumbai, and Bangalore creates first-mover positioning for integrated screening platform vendors.
- EU Green Deal Efficiency Incentives:Lower-energy millimeter wave architectures qualify for accelerated depreciation under member state sustainability procurement frameworks.
- Mobile Deployment Channels:Security agencies for special events and temporary terminal expansions are creating demand for rapidly deployable screening units outside fixed-installation procurement.
Industry Challenges
- Algorithm Training Data Access:Prohibited item image libraries for machine learning model development face cross-border transfer restrictions under national security classifications.
- Legacy System Integration Complexity:New CT baggage scanners must interface with existing conveyor infrastructure and alarm resolution protocols at operational checkpoints without downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Passenger Screening System Market |
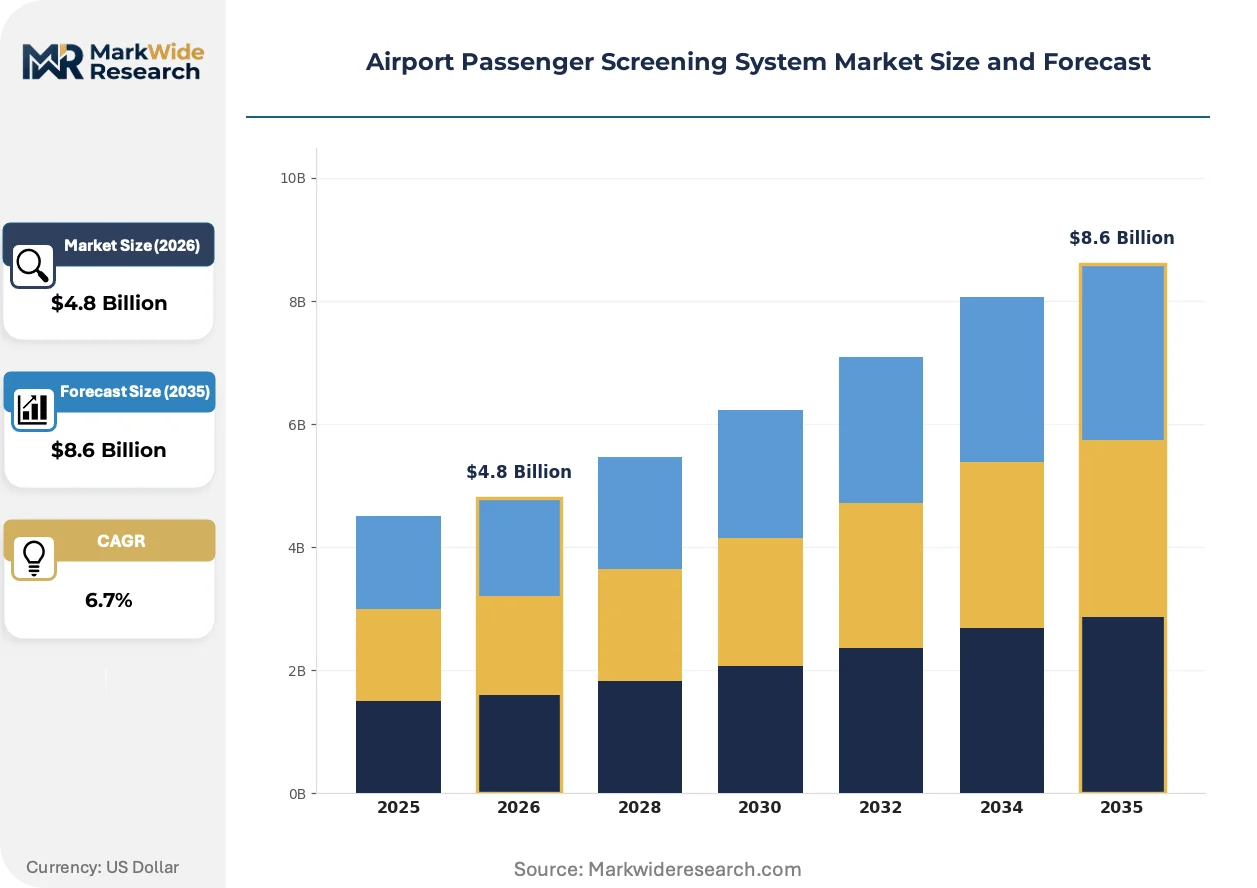
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Machines, Body Scanners, Explosive Detection Systems, Handheld Detectors Technology: Computed Tomography, Millimeter Wave, Backscatter X-Ray, Ion Mobility Spectrometry End User: Airports, Government Authorities, Security Agencies, Airlines Installation: Fixed Systems, Mobile Units, Temporary Installations, Permanent Installations |
| Companies Covered | Smiths Detection, Rapiscan Systems, Analogic Corporation, OSI Systems, L-3 Communications Security & Detection Systems, CEIA, Kromek Group, American Science and Engineering, Nuctech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Passenger Screening System Market Emerging Trajectories
Artificial intelligence classification capabilities are migrating from cloud processing to edge computing within screening hardware, reducing latency while complicating certification pathways. This architectural shift is compressing competitive differentiation around software rather than detector physics.
Deep learning-based automatic threat recognition is converging with computed tomography reconstruction algorithms to enable liquid-in-baggage detection without passenger divestiture. Major European hubs including Amsterdam Schiphol and Frankfurt are piloting these integrated systems for cabin baggage lanes. The technology is converging with passenger flow optimization software to sustain throughput above 600 bags per hour while maintaining detection thresholds.
The EU AI Act's risk classification framework for biometric and security applications is imposing documentation requirements on training data provenance and algorithmic explainability. Manufacturers must now maintain technical files demonstrating human oversight capabilities for automated threat decisions. Fixed-site explosive detection installations face the steepest compliance burden, with certification timelines extending twelve to eighteen months for systems deployed at Category A airports.
Buyer organizations are unbundling after-sales service contracts from initial equipment procurement, creating standalone multi-vendor maintenance markets. Airport authorities in the United States and Germany are separately negotiating software update subscriptions and spare parts logistics. This fragmentation is most visible among large hub operators with internal technical capabilities seeking to reduce lifecycle costs through competitive service tendering.
Airport Passenger Screening System Market Segmentation
Technology heterogeneity across checkpoint architectures creates distinct procurement profiles that reshape vendor positioning and lifecycle economics. Buyers segment their investments by throughput requirements, detection sensitivity mandates, and integration complexity with legacy infrastructure.
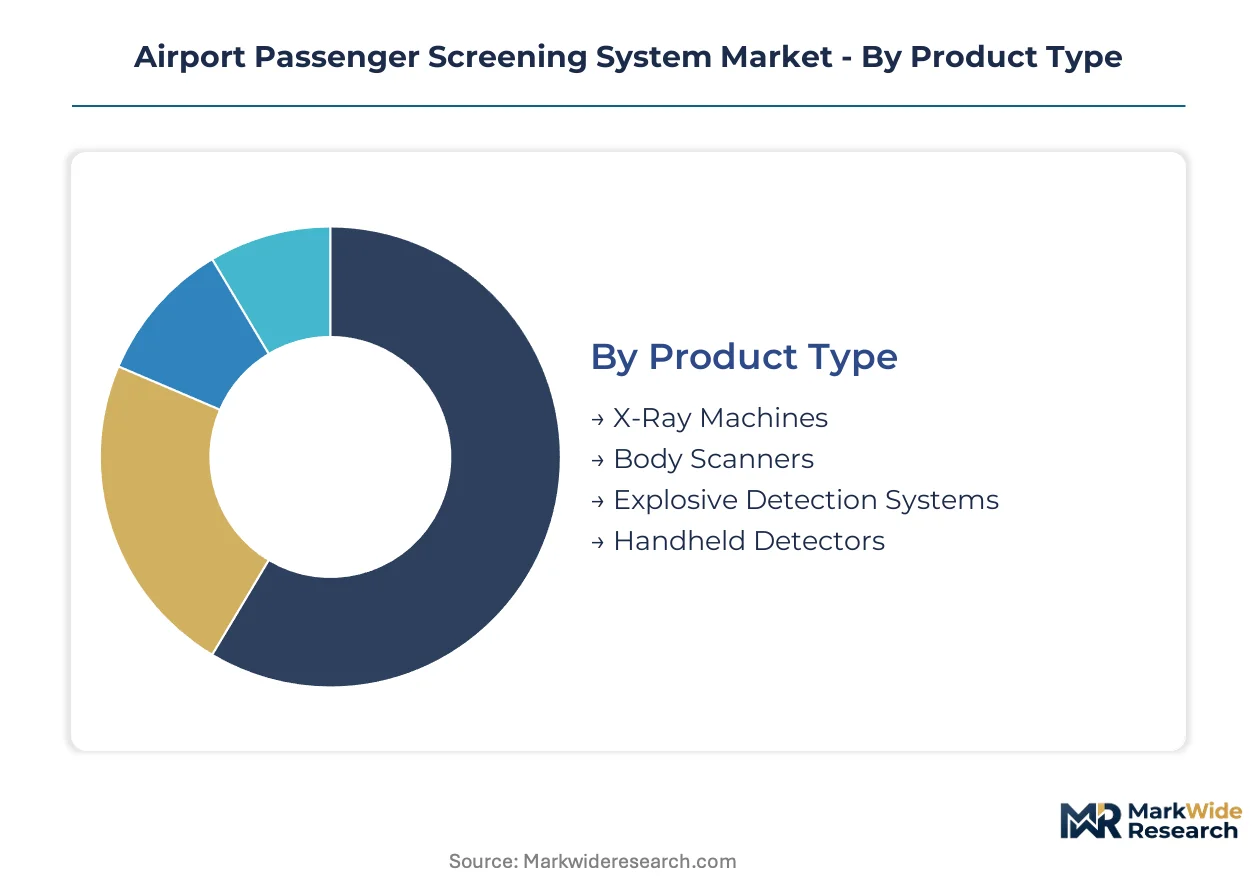
Product Type:
Procurement budgets diverge sharply between high-capital fixed installations and lower-unit-cost portable equipment, with ownership models ranging from direct purchase to long-term service contracts.
- X-Ray Machines:Legacy dual-view systems still process bulk cabin baggage at secondary checkpoints, though replacement demand concentrates in emerging markets where TSA-equivalent mandates have not yet taken effect. TSA procurement programs at Atlanta and Denver International are consolidating demand for automated screening lanes with integrated verification.
- Body Scanners:Millimeter wave architectures with privacy-compliant software upgrades eliminate passenger-specific image storage, removing deployment barriers at EU airports subject to GDPR and national data protection authority oversight. Amsterdam Schiphol and Frankfurt are piloting integrated systems for cabin baggage lanes.
- Explosive Detection Systems:Fixed-site installations anchor hold baggage screening infrastructure at Category A airports.
- Handheld Detectors:Trace explosive and narcotics detection for secondary screening protocols.
Body scanners lead volumes today; explosive detection systems are gaining share fastest in greenfield terminal construction.
Technology:
Detection physics and algorithmic sophistication determine certification pathways, with regulatory divergence between FAA-TSA joint standards and EASA efficiency mandates creating product variant complexity.
- Computed Tomography:Three-dimensional imaging with automatic threat recognition enables liquid-in-baggage detection without passenger divestiture, compressing checkpoint staffing models while forcing hardware refresh cycles at major aviation hubs. The EU's updated aviation security regulations are mandating higher detection standards for cabin baggage.
- Millimeter Wave:Active array architectures with edge-computing AI classification reduce latency while complicating certification pathways under the EU AI Act's risk classification framework for biometric applications. Software-only enhancements remove deployment barriers at privacy-sensitive jurisdictions.
- Backscatter X-Ray:Reduced radiation architectures respond to EU Green Deal efficiency requirements.
- Ion Mobility Spectrometry:Trace detection for explosive and chemical agent identification in hold baggage screening.
Computed tomography dominates current procurement; millimeter wave systems are expanding most quickly through privacy upgrade cycles.
End User:
Contracting authority and operational control arrangements segment demand between infrastructure owners, regulatory enforcers, and service providers with distinct technical specifications and interoperability requirements.
- Airports:Hub operators at Delhi, Mumbai, and Bangalore create first-mover positioning for integrated screening platform vendors through greenfield terminal construction with automated screening lanes.
- Government Authorities:National procurement programs consolidate demand for standardized detection thresholds and interoperability specifications.
- Security Agencies:Rapid deployment requirements for special events and temporary terminal expansions drive mobile unit demand outside fixed-installation procurement.
- Airlines:Premium carrier lounges and private terminal operators purchase supplemental screening capacity.
Airports account for the largest installed base; security agencies are climbing the fastest through mobile deployment channels.
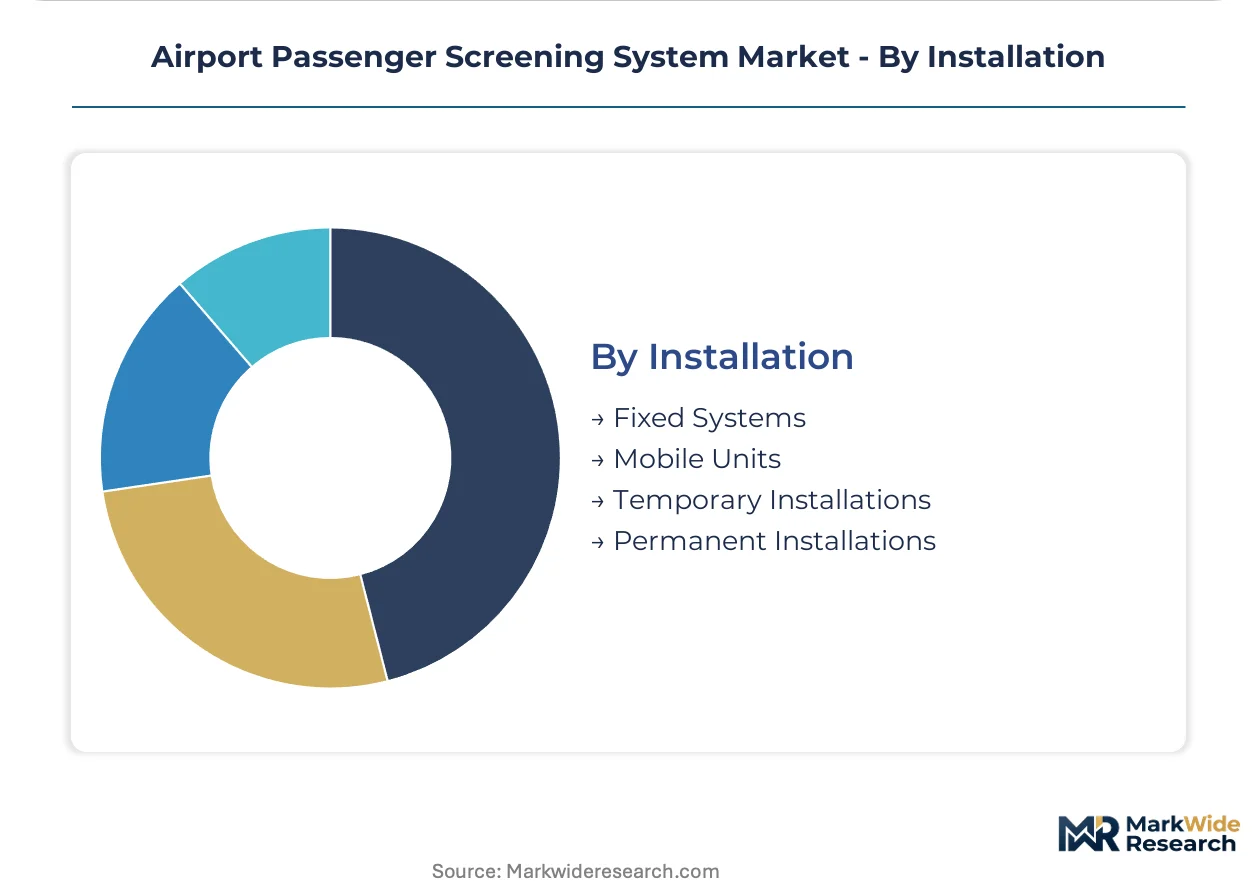
Installation:
Deployment duration and relocation flexibility determine capital treatment, depreciation schedules, and maintenance contract structures across buyer organizations.
- Fixed Systems:Permanent explosive detection installations at major hubs face the steepest EU AI Act compliance burden, with certification timelines extending twelve to eighteen months for Category A airports requiring technical files demonstrating human oversight capabilities.
- Mobile Units:Trailer-mounted screening platforms enable rapid deployment for special events, temporary terminal expansions, and emergency infrastructure replacement without foundation work or utility connections.
- Temporary Installations:Modular checkpoint architectures for construction-phase terminal operations.
- Permanent Installations:Integrated conveyor infrastructure with alarm resolution protocols at operational checkpoints.
Fixed systems lead capital deployment today; mobile units are gaining share fastest among security agencies requiring operational flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial aviation security infrastructure originated in the United States following 1970s hijacking incidents, with passenger screening protocols subsequently adopted and adapted by European and Asian regulators. The current procurement landscape reflects this historical diffusion, with national security agencies now driving divergent technical specifications across major aviation markets.
United States
The Transportation Security Administration operates the world's largest checkpoint modernization program, consolidating demand at Atlanta, Dallas-Fort Worth, and Denver International airports for automated screening lanes. FAA and TSA joint certification pathways for new detection algorithms extend development-to-deployment cycles. Major hub operators in the Southeast and Mountain West regions are separately negotiating software update subscriptions to reduce lifecycle costs.
Germany
Frankfurt and Munich airports anchor European demand for computed tomography cabin baggage systems under EASA-mandated detection standards. The EU AI Act's risk classification framework imposes twelve-to-eighteen-month certification timelines for Category A airport installations. Bavaria and North Rhine-Westphalia host the densest concentration of maintenance technician training infrastructure.
China
Beijing Capital, Shanghai Pudong, and Guangzhou Baiyun are expanding automated screening capacity to accommodate domestic passenger volume growth. The country's national aviation security regulator aligns procurement with GB standards while permitting localized algorithm development. Yangtze River Delta and Pearl River Delta clusters dominate domestic equipment manufacturing.
India
Delhi Indira Gandhi, Mumbai Chhatrapati Shivaji, and Bangalore Kempegowda greenfield terminals create first-mover positioning opportunities for integrated screening platform vendors. The Airports Authority of India specifies interoperability requirements for multi-vendor checkpoint architectures. Maharashtra and Karnataka states concentrate private terminal operator procurement decision-making.
United Arab Emirates
Dubai International and Abu Dhabi Zayed International anchor Middle Eastern demand for premium-tier passenger processing infrastructure. The General Civil Aviation Authority mandates detection thresholds equivalent to European standards without EU AI Act compliance burdens. Dubai's logistics corridor position attracts mobile screening unit procurement for special event security.
Airport Passenger Screening System Market Vendor Landscape
Premium-margin players sit above commodity-margin players across algorithm sophistication and certification breadth, with tiered pricing separating integrated platform vendors from component specialists. The vendor base organizes around three strategic archetypes: computed tomography baggage scanner integrators, millimeter wave body scanner specialists, and explosive trace detection subsystem suppliers. Dominant competitive moves include portfolio diversification into adjacent security verticals and strategic partnerships with national procurement agencies for multi-year service contracts.
Within the integrated platform tier, Smiths Detection and Rapiscan Systems exemplify scale-driven positioning, while OSI Systems occupies a service-network differentiation position. CEIA represents European specialist engineering, and Nuctech anchors Chinese state-linked manufacturing capacity. L-3 Communications Security & Detection Systems and American Science and Engineering sit within the defense-heritage archetype, with Kromek Group exemplifying detector module specialization. Analogic Corporation represents North American imaging subsystem expertise.
| Leading Market Players |
|---|
| Smiths Detection |
| Rapiscan Systems |
| Analogic Corporation |
| OSI Systems |
| L-3 Communications Security & Detection Systems |
| CEIA |
| Kromek Group |
| American Science and Engineering |
| Nuctech |
| Others |
Supply Flow & Price Mechanics
Specialized semiconductor foundry capacity for millimeter wave array chips and CT detector modules flows from East Asian fabrication centers through tiered equipment pricing that stratifies across certification-grade, performance-tier, and service-bundling levels. This input concentration grants upstream suppliers substantial leverage over downstream scanner manufacturers competing for TSA and EASA procurement contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FAA-TSA joint-certified systems with twelve-to-eighteen-month validation timelines from faster-to-deploy configurations lacking full interoperability. Price differentiation rests on algorithm sophistication and after-sales service bundling rather than hardware alone. Cost compression in standard-tier CT baggage scanners is intensifying as Indian and Chinese domestic manufacturers scale production for greenfield terminals. Government procurement authorities exhibit lowest price sensitivity due to mandate-driven replacement timelines, while private terminal operators in premium lounges negotiate hardest on lifecycle service costs.
Supply Chain Analysis
Refurbishment and remanufacturing flows for legacy X-ray systems create secondary parts markets that extend equipment lifecycles beyond original depreciation schedules, particularly at emerging-market airports awaiting regulatory upgrades. Manufacturing concentration centers on China for detector module assembly, Germany for precision engineering components, and the United States for AI classification software development. Raw material dependencies include gallium arsenide substrates for millimeter wave arrays, rare-earth scintillators for CT detectors, and specialized aluminum alloys for scanner chassis. Single-source vulnerability in advanced semiconductor foundry capacity represents the dominant structural risk. Distribution runs through national procurement agencies and direct OEM relationships with major hub operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between EU AI Act compliance burdens extending certification timelines and UAE procurement frameworks adopting equivalent detection thresholds without algorithmic documentation requirements, compressing time-to-revenue for vendors willing to prioritize Middle Eastern deployments.
For Market Incumbents: Acquire AI training data libraries and certified technician training infrastructure to defend against modular software vendors unbundling hardware from algorithm subscriptions. Backward integration into specialized semiconductor sourcing mitigates foundry concentration risk. Prioritize multi-year service contract renewals at Atlanta, Dallas-Fort Worth, and Denver International to lock out challenger maintenance providers. For New Entrants and Emerging Players: Regional system integrators in India represent the most penetrable channel partner type for greenfield terminal construction at Delhi, Mumbai, and Bangalore where interoperability mandates favor multi-vendor architectures. Target mobile deployment channels for security agencies requiring rapid special-event screening capacity outside fixed-installation procurement cycles. Lead with software-only privacy-upgrade offerings for existing millimeter wave body scanner fleets to bypass hardware certification barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where service network density determines lifecycle contract capture and standalone maintenance markets fragment across airport authorities with internal technical capabilities. Long-term viability favors platforms combining CT reconstruction algorithms with edge-computing AI classification. Monitor EU AI Act enforcement patterns and TSA algorithm approval velocity as inflection indicators for certification-timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| CT Algorithm Certification Investment | FAA-TSA joint pathways compress competitive differentiation around software rather than detector physics. |
| Mobile Unit Manufacturing Scale-Up | Security agencies for special events and temporary terminal expansions drive demand outside fixed-installation procurement. |
| India Greenfield Terminal Partnership | Delhi, Mumbai, and Bangalore construction creates first-mover positioning for integrated screening platform vendors. |
| EU Green Deal Efficiency Repositioning | Lower-energy millimeter wave architectures qualify for accelerated depreciation under member state sustainability frameworks. |
| After-Sales Service Unbundling | Large hub operators with internal technical capabilities seek competitive tendering for software updates and spare parts logistics. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with airport procurement directors, TSA program managers, EASA certification officers, and CT scanner maintenance technicians with secondary validation against FAA procurement databases, EU Official Journal contract awards, and customs trade data for screening equipment imports. Bottom-up installed base modeling and top-down procurement budget aggregation triangulated market sizing across the analysis window.
Comparable-period anchoring tied projection assumptions to historical replacement cycles at major aviation hubs and regulatory mandate implementation timelines. The analytical framework modeled technology type, installation category, end-user contracting authority, and regional regulatory cluster across the projection horizon. CAGRs derived from equipment shipment trajectories and average selling price evolution, with forecast inputs including TSA procurement program announcements and EASA detection standard revision schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply disruptions, AI Act enforcement variability, and training infrastructure bottlenecks. Practitioners should monitor foundry capacity allocation shifts and algorithm certification queue lengths for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Japan Smart Lock Market
Access Control Systems
Acousto-Magnetic (AM) Security Systems Market
Access Control Systems
Pedestrian Access Control System Market
Access Control Systems
Mobile Turnstile Market
Access Control Systems
Europe Proximity Access Control Market
Access Control Systems
China Access Control Market
Access Control Systems
US Access Control Market
Access Control Systems
North America Pin-Based Access Control Market
Access Control Systems
Europe Access Control Hardware Market
Access Control Systems
Mode Locking Device Market
Access Control Systems
North America Safety Systems Market
Access Control Systems
Digital Security Control Market
Access Control Systems
Germany Access Control Market
Access Control Systems
APAC Home Security System Market
Access Control Systems
Global Keyless Vehicle Access Control Systems Market
Access Control Systems
Industrial Barrier Systems Market