
 Fire Safety Equipment Market | 2026-2036
Fire Safety Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Safety Equipment Market Intelligence
The European Union's updated Construction Products Regulation (CPR) is repositioning the cost-of-entry calculus for manufacturers by mandating stricter performance and fire resistance classifications. Siemens leverages its extensive portfolio in building automation to integrate fire safety systems. Johnson Controls competes on the strength of its global distribution network and comprehensive service offerings. Honeywell International differentiates through its advanced sensor technologies for industrial and commercial applications.
Fire safety equipment encompasses active and passive devices designed to detect, contain, and extinguish fires in occupied structures. These systems, including sprinklers with specific activation temperatures, serve the primary purpose of protecting life, property, and business continuity. While sprinkler systems and smoke detectors are mature product segments, advanced fire alarms with IoT connectivity show significant growth potential. Application in commercial buildings and industrial plants drives market volume, governed by strict safety mandates.
Regulatory frameworks from bodies like the U.S. Occupational Safety and Health Administration (OSHA) and China's GB standards define minimum equipment requirements for workplaces. In Europe, CE marking under the Construction Products Regulation is essential for market access, verifying performance claims. Stakeholders must now decide how to invest in software and data analytics capabilities to compete in an increasingly connected and predictive safety ecosystem.
Market Dynamics
The market's primary dynamic is the tension between stringent regulatory mandates for advanced, connected safety systems and the significant capital investment required to retrofit aging building stock. This forces a market bifurcation between new construction adopting integrated solutions and existing facilities navigating phased upgrades.
Growth Catalysts
- Regulatory Modernization:India's updated National Building Code and rapid urbanization are compelling developers to install advanced fire detection and suppression systems in new high-rise residential and commercial projects.
- Industrial Asset Protection:The need to safeguard high-value equipment and ensure operational continuity in industrial plants, particularly in the oil and gas sector, drives investment in specialized suppression systems.
- IoT Integration:The adoption of IoT-enabled sensors for real-time monitoring and predictive maintenance of fire safety equipment allows for proactive risk management, which is a significant value proposition for facility managers.
Market Restraints
- High Retrofit Costs:The substantial expense and operational disruption associated with upgrading legacy fire safety systems in older commercial and residential buildings to meet modern code requirements deter many property owners.
- System Interoperability:A lack of standardization among connected devices from different manufacturers creates integration challenges, limiting the effectiveness of building-wide, unified fire safety and automation platforms.
- Complex Certification Pathways:Navigating disparate and rigorous certification processes, such as the EU's CE marking under the CPR and China's GB standards, increases product development costs and time-to-market for manufacturers.
Strategic Opportunities
- Fire-Safety-as-a-Service (FSaaS):Shifting to a service-based model offering subscription-based monitoring, maintenance, and compliance management provides a recurring revenue stream and lowers the upfront cost barrier for customers.
- Southeast Asia Expansion:Underpenetrated markets in countries like Vietnam and Indonesia, where industrialization and urban development are accelerating, present significant greenfield opportunities for fire safety equipment deployment.
- Convergence with Building Automation:Integrating fire detection systems with HVAC, access control, and emergency lighting creates intelligent buildings that can execute automated, coordinated safety protocols during an emergency.
Industry Challenges
- Skilled Technician Shortage:A persistent lack of qualified technicians who can install, service, and network sophisticated, IP-based fire alarm and suppression systems creates service delivery bottlenecks and increases labor costs.
- Legacy System Integration:The technical difficulty of connecting new, data-driven fire safety technologies with existing, non-networked analog systems in older facilities remains a significant barrier to widespread modernization.
- Data Privacy and Security:As fire safety systems become more connected, ensuring the cybersecurity of the network to prevent malicious attacks and protecting sensitive building data becomes a critical operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Safety Equipment Market |
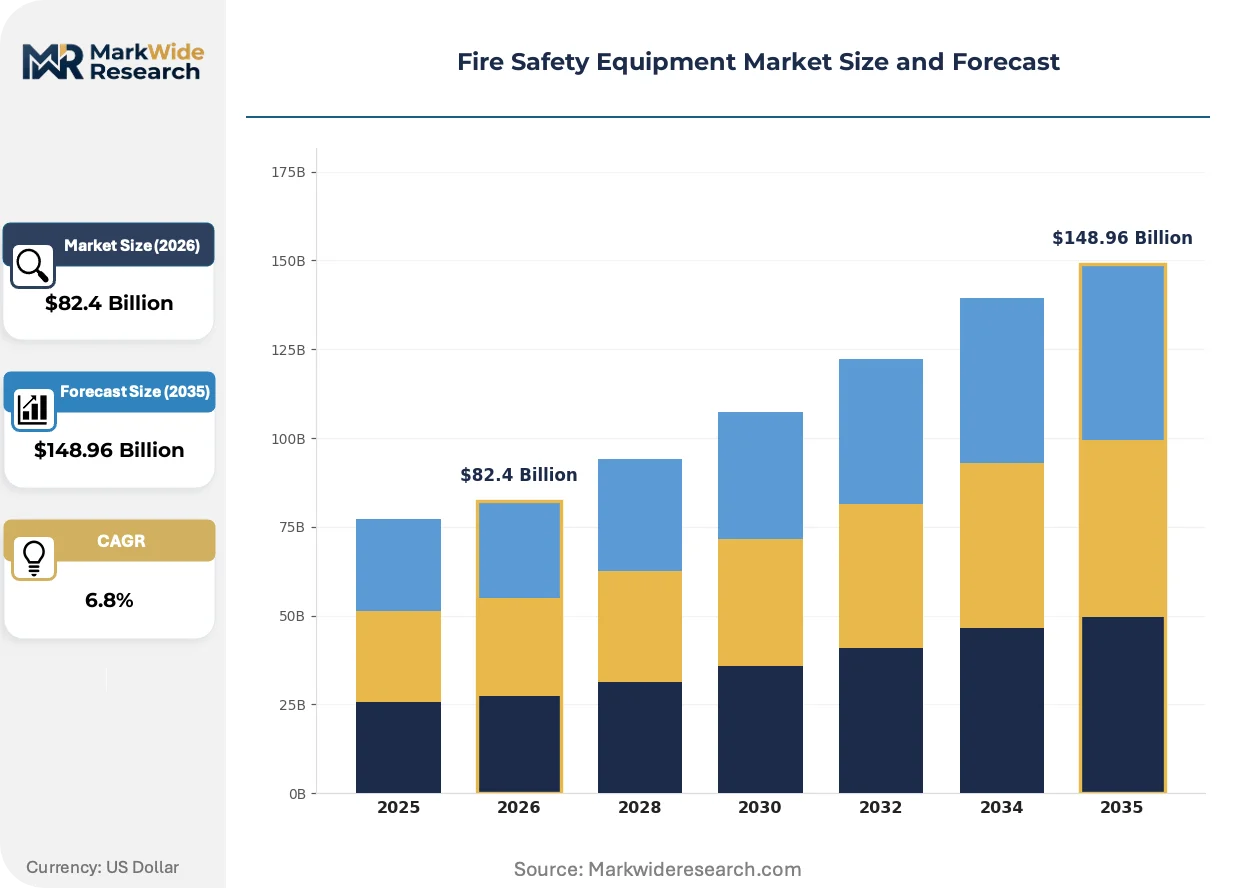
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $148.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire Extinguishers, Smoke Detectors, Fire Alarms, Sprinkler Systems, Fire Blankets, Fire Hose Reels Technology: Infrared Sensors, Ionization Sensors, Photoelectric Sensors, Thermal Sensors, Acoustic Sensors, Manual Pull Stations Application: Commercial Buildings, Industrial Plants, Educational Institutions, Transportation Facilities, Hospitality Venues, Warehousing End User: Fire Departments, Facility Management, Manufacturing Units, Government Agencies, Construction Firms, Event Organizers |
| Companies Covered | Robert Bosch, Hochiki Corporation, Johnson Controls, Carrier Global Corporation, Gentex Corporation, Honeywell International, Halma plc, Minimax Viking Group, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Safety Equipment Market Strategic Shifts & Innovations
The evolution from reactive, component-based fire protection to proactive, system-wide life safety management defines the market's current trajectory. This shift is powered by digitalization, creating intelligent environments where data analytics and connectivity predict risks before they escalate into emergencies.
Wireless fire detection sensors, which utilize mesh networking protocols for robust communication, are a key product evolution. Industrial facilities and heritage buildings are adopting this technology at a steady pace to overcome the challenges of hardwiring in complex or protected structures. This technology is modularizing system design, enabling scalable and flexible deployments that can be expanded or reconfigured with minimal structural intervention.
In the United States, the Occupational Safety and Health Administration (OSHA) enforces strict standards for fire safety in workplaces, covering equipment maintenance and clear egress paths. This regulatory pressure sustains a consistent demand for inspection, testing, and maintenance (ITM) services. The industrial manufacturing and logistics sectors are most affected, leading them to invest in digital compliance software to streamline documentation and verification.
A significant demand-side shift is the move by facility managers and real estate portfolio owners to prioritize total cost of ownership over initial equipment price. This trend is diminishing the role of one-time transactional sales in favor of comprehensive service-level agreements that bundle hardware with ongoing monitoring and compliance services. The change is most pronounced in multi-site commercial and industrial operations across North America and Europe.
Fire Safety Equipment Market Segmentation
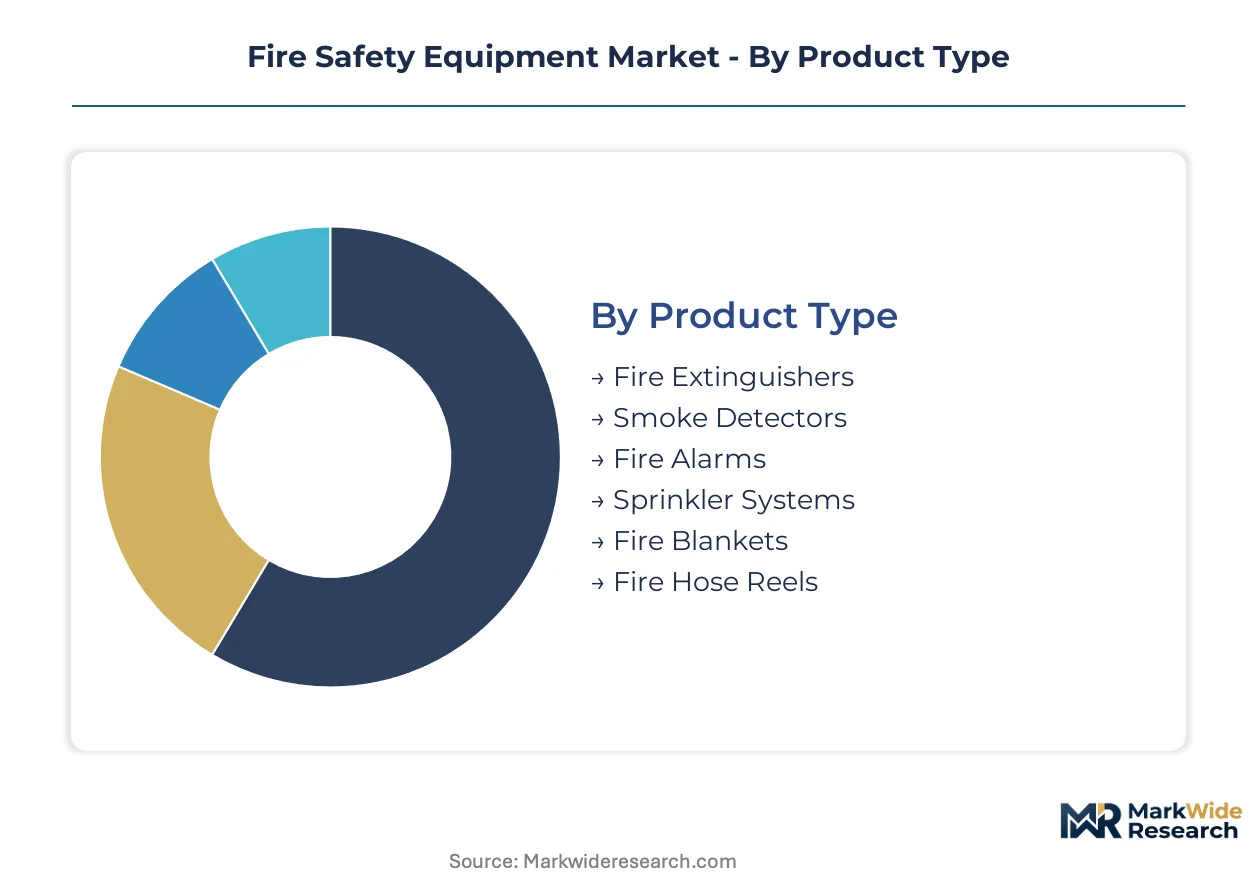
Segmentation provides a granular view of the Fire Safety Equipment Market, revealing distinct product characteristics, technological advancements, application areas, and end-user demands. Understanding these segments helps stakeholders identify specific growth pockets and tailor solutions to diverse operational needs.
Product Type:
The product type segmentation differentiates between high-volume, standardized fire protection components and more specialized, integrated systems that command a premium.
- Sprinkler Systems:These automatic fire suppression systems deploy water or chemical agents when a designated temperature is reached, crucial for protecting high-value assets in industrial plants. Demand concentrates in large commercial and industrial complexes across India, driven by updated building codes.
- Fire Alarms:Consisting of detection devices, control panels, and notification appliances, these systems alert occupants to fire incidents. Their integration with IoT sensors for real-time monitoring is gaining share in commercial buildings in the European Union.
- Fire Extinguishers:Portable devices designed to put out small fires, categorized by the type of extinguishing agent used.
- Smoke Detectors:Devices that sense smoke as an indicator of fire, typically found in residential and commercial properties.
- Fire Blankets:Non-flammable sheets used to smother small fires or wrap around a person whose clothing is on fire.
- Fire Hose Reels:Permanently installed systems providing a continuous supply of water for manual fire fighting, common in public buildings.
Mature deployment sits with Fire Extinguishers. Newer deployment is concentrated in Fire Alarms.
Technology:
Technology segmentation highlights the varying maturity levels and operational principles of detection and activation mechanisms.
- Infrared Sensors:These advanced sensors detect the infrared radiation emitted by flames, offering rapid detection in industrial environments with high ceilings or harsh conditions. Their application is expanding in oil and gas facilities due to their speed and accuracy.
- Photoelectric Sensors:Operating by detecting visible smoke particles, these sensors are highly effective at detecting smoldering fires. They are widely used in commercial buildings and residential spaces for general fire detection.
- Ionization Sensors:These sensors detect invisible combustion particles, making them suitable for fast-flaming fires.
- Thermal Sensors:Designed to detect abnormal heat levels or rapid temperature rises, often used in kitchens or areas with high ambient temperatures.
- Acoustic Sensors:These sensors identify specific sound patterns associated with breaking glass or explosions, providing early warning in specific high-risk scenarios.
- Manual Pull Stations:Devices allowing building occupants to manually initiate a fire alarm, a standard component in virtually all public and commercial structures.
Advanced detection capabilities are expanding most quickly within Infrared Sensors and Acoustic Sensors.
Application:
Application segmentation reflects the diverse environments where fire safety equipment is deployed, each with distinct regulatory requirements and risk profiles.
- Industrial Plants:These facilities, including manufacturing and processing plants, demand specialized fire suppression systems to protect high-value machinery and hazardous materials. The oil and gas sector in North America consistently invests in advanced systems due to inherent risks.
- Commercial Buildings:Encompassing offices, retail spaces, and high-rise structures, this segment requires comprehensive fire detection and suppression to protect occupants and property. Strict safety mandates in European Union cities drive demand for integrated solutions.
- Educational Institutions:Schools and universities require robust fire safety systems to ensure student and staff safety, adhering to specific local building codes.
- Transportation Facilities:Airports, train stations, and seaports utilize fire safety equipment to protect passengers and critical infrastructure.
- Hospitality Venues:Hotels, resorts, and restaurants prioritize guest safety with integrated fire alarms and sprinkler systems.
- Warehousing:Large storage facilities deploy fire safety solutions to protect inventory and prevent business interruption, often including specialized sprinkler types.
Industrial Plants and Commercial Buildings represent the most significant investment areas for fire safety equipment.
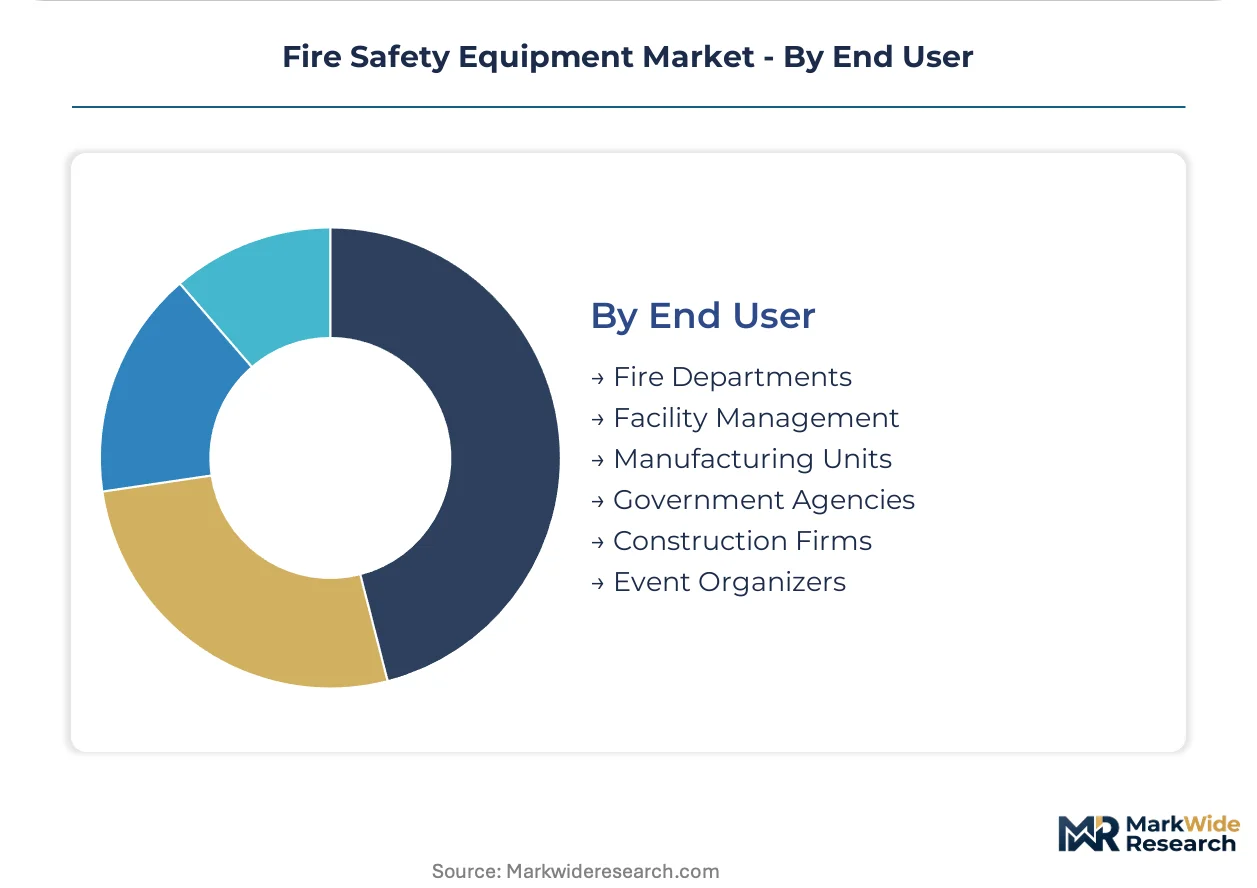
End User:
End-user segmentation outlines the primary purchasers and beneficiaries of fire safety solutions, influencing procurement patterns and service delivery models.
- Facility Management:Professionals responsible for the upkeep and operation of buildings, driving demand for integrated fire safety systems and ongoing maintenance services. They prioritize compliance and operational continuity for commercial properties.
- Manufacturing Units:Industrial entities that require fire safety equipment to protect production lines, raw materials, and finished goods, ensuring worker safety and continuous operations. Companies in Germany's automotive sector invest heavily in these systems.
- Fire Departments:Government-funded emergency services that utilize specialized equipment for fire suppression and rescue operations.
- Government Agencies:Public sector bodies that procure fire safety solutions for public buildings, infrastructure, and defense facilities, adhering to national standards.
- Construction Firms:Companies involved in building new structures, integrating fire safety systems during the construction phase to meet regulatory requirements.
- Event Organizers:Entities responsible for managing large public gatherings, requiring temporary or portable fire safety measures to ensure attendee safety.
Facility Management and Manufacturing Units are consistently driving demand for integrated fire safety solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rapid industrialization and urban development in regions like India's Special Economic Zones (SEZs) drive significant demand for advanced fire safety equipment. These zones, designed to attract investment, mandate stringent safety protocols for new manufacturing and commercial facilities. This focus accelerates the deployment of integrated fire detection and suppression systems.
India
India's rapid urbanization and infrastructure development fuel demand for advanced fire safety equipment in new constructions. The updated National Building Code mandates comprehensive fire detection and suppression systems for high-rise buildings. Major metropolitan areas like Mumbai and Delhi-NCR are witnessing substantial investment in these integrated solutions.
United States
The United States market prioritizes protecting high-value industrial assets and ensuring worker safety across diverse sectors. OSHA enforces strict standards for fire safety equipment maintenance and egress paths in workplaces. Industrial manufacturing hubs and the Gulf Coast oil and gas sector consistently upgrade specialized suppression systems.
Germany
Germany's advanced manufacturing sector and adherence to strict European building codes generate consistent demand for sophisticated fire safety solutions. CE marking under the EU's Construction Products Regulation verifies performance claims for market access. The automotive sector, particularly in Bavaria and Baden-Württemberg, invests heavily in integrated fire protection systems.
China
China's extensive industrial expansion and ongoing urban development drive substantial demand for fire safety equipment across commercial and industrial applications. The country's GB standards define minimum equipment requirements for workplaces and new constructions. Manufacturing zones in the Yangtze River Delta and Pearl River Delta are key areas for system deployment.
Vietnam
Vietnam's accelerating industrialization and urban development present significant greenfield opportunities for fire safety equipment deployment. Local building codes and safety mandates for foreign direct investment compel developers to install modern systems. Industrial parks surrounding Ho Chi Minh City and Hanoi are experiencing increased investment in advanced fire detection.
Fire Safety Equipment Market Key Industry Players
US and European producers anchor one tier, offering integrated building management solutions; Asian specialists hold positions in specific component manufacturing. The market structure exhibits a tiered approach, with global conglomerates providing comprehensive systems and regional players focusing on installation and maintenance services. Strategic archetypes include diversified industrial players, pure-play fire safety specialists, and technology-focused sensor developers. Competitive moves center on strategic partnerships for IoT integration and targeted acquisitions for portfolio diversification.
Among global industrial technology providers, Johnson Controls and Honeywell International exemplify companies leveraging extensive distribution networks and advanced sensor technologies. These firms occupy a position integrating fire safety into broader building automation platforms. Siemens, another major industrial conglomerate, anchors its fire safety offerings within its comprehensive building automation portfolio. These players represent the trend towards unified, intelligent safety ecosystems, often bundling hardware with ongoing monitoring and compliance services across commercial and industrial applications.
| Leading Market Players |
|---|
| Robert Bosch |
| Hochiki Corporation |
| Johnson Controls |
| Carrier Global Corporation |
| Gentex Corporation |
| Honeywell International |
| Halma plc |
| Minimax Viking Group |
| Siemens |
| Others |
Cost & Logistics Intelligence
Raw material costs, particularly for steel and specialized electronic components, represent a significant upstream input that directly influences the downstream pricing tiers of integrated fire safety systems. Logistics expenses further shape final product costs, especially for global distribution.
Pricing Analysis
Short lead times for specialized fire suppression systems command a premium, reflecting the critical need for rapid deployment in industrial settings. The dominant pricing model for advanced solutions is project-based, while mature components like fire extinguishers follow per-unit transactional pricing. Price differentiation stems from the level of certification, such as CE marking or UL standards, and the breadth of after-sales service agreements. Pricing pressure stems from the commoditization of standardized products, particularly in high-volume segments. Facility management teams and construction firms are often most price-sensitive regarding initial equipment costs.
Supply Chain Analysis
Single-source vulnerability sits with specialized electronic components from Asian manufacturers, critical for advanced IoT-enabled sensors. The supply chain draws from specific countries like China for high-volume components and Germany for precision-engineered systems. Key raw material dependencies include steel for structural elements, copper for wiring, and specialized chemicals for suppression agents. Commodity price volatility, particularly for metals, presents a structural supply chain risk. Distribution runs primarily through direct sales channels for integrated solutions and a network of distributors and resellers for individual components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
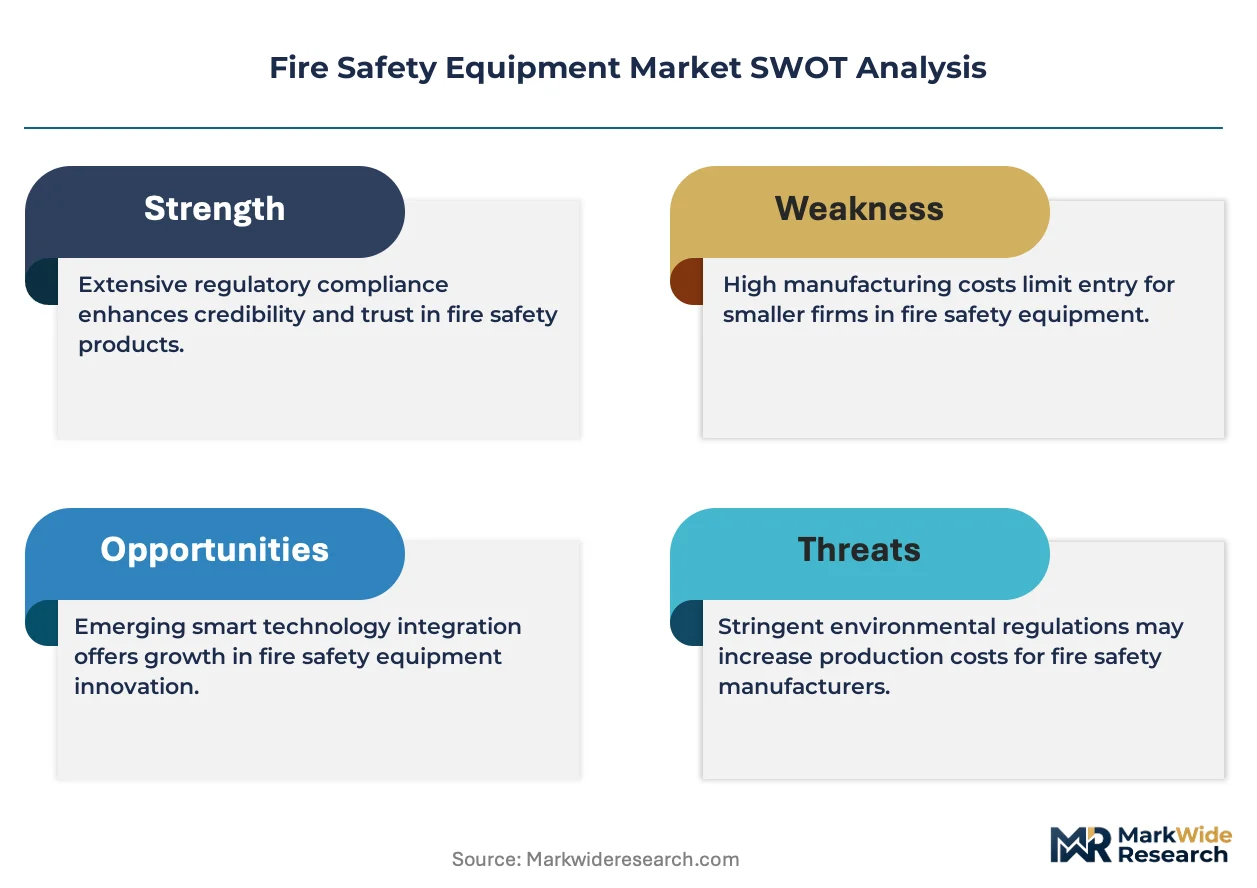
This market presents a consolidation play, as stringent regulatory compliance and the need for advanced R&D force out smaller, less capitalized players.
For Market Incumbents: Extend their comprehensive service offerings to include predictive maintenance and compliance management, creating recurring revenue streams. Acquire niche technology firms specializing in AI-driven analytics or IoT platforms to counter emerging software-focused entrants. Investment in advanced certification for new technologies, such as wireless sensor protocols, remains a critical lever against competitive threats.
For New Entrants and Emerging Players: Enter via specialized IoT-enabled fire detection solutions targeting the retrofit market in commercial buildings. The small-to-medium commercial segment in underpenetrated markets, such as Southeast Asia, presents a penetrable white space. A subscription-based Fire-Safety-as-a-Service (FSaaS) model offers a compelling go-to-market angle, lowering upfront costs for facility managers.
For Investors and Strategic Acquirers: Increased M&A activity in Fire-Safety-as-a-Service (FSaaS) platforms is the leading indicator that the market values recurring revenue and integrated solutions. The long-term viability of this sector remains robust, driven by non-discretionary regulatory mandates and asset protection needs. Acquisition targets should include software companies specializing in predictive analytics or building automation integration. Watch for significant capital investments in advanced sensor manufacturing as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnership for IoT Integration | Partnerships with tech firms accelerate the development of connected fire safety ecosystems for commercial buildings. |
| Acquisition of Specialist Firm in AI/Data Analytics | Integrating AI capabilities enables predictive risk management and enhances the value proposition for industrial plants. |
| Distribution Channel Expansion in Southeast Asia | Expanding into emerging markets capitalizes on rapid urbanization and industrialization in countries like Vietnam. |
| Investment in Wireless Sensor Technology | Developing wireless solutions addresses installation challenges in heritage buildings and complex industrial facilities. |
| Green Manufacturing Process Adoption | Adopting sustainable practices enhances brand reputation and aligns with evolving European Union environmental regulations. |
Research Approach
Document review covered national building codes, regulatory publications, and industry association reports, complemented by interviews with facility managers, industrial plant safety officers, and fire safety equipment manufacturers. Secondary validation sources included OSHA reports and company financial filings. This approach ensured robust bottom-up and top-down triangulation.
Historical market performance was cross-referenced with expert panel input to project future trends across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived from a blend of historical data analysis and expert consensus, incorporating urbanization rates and industrial capital expenditure as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen regulatory shifts or global economic downturns. Forecasts reflect assumptions regarding technological adoption and market maturity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Global Smoke Evacuation Systems Market
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
Smart Smoke Detector Market
Fire Safety & Protection
Fire Rated Cables Market
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
Fire Alarm Systems Market
Fire Safety & Protection
GCC Firefighting Foam Market
Fire Safety & Protection
Civil Combustible Gas Alarm Market
Fire Safety & Protection
Fire Protection Valves and Fittings Market
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
UAE Fire Protection System Market
Fire Safety & Protection
US Fire Safety Equipment Market
Fire Safety & Protection
High Pressure Fixed Firefighting Misting System Market
Fire Safety & Protection
Passive Fire Proofing System Market
Fire Safety & Protection
Fire Fighting Foam Market
Fire Safety & Protection
UAE Firefighting Foam Market