
 Global Industrial AR Platforms Market | 2026-2036
Global Industrial AR Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial AR Platforms Market Outlook
Enterprise-grade AR specifications with sub-millimeter spatial accuracy is rotating the Global Industrial AR Platforms Market toward mission-critical deployments. PTC leverages its CAD-anchored digital thread to dominate aerospace and automotive workflows. Scope AR sustains competitive position through specialized remote-assistance tooling for field technicians. Unity Technologies anchors its industrial push through real-time 3D engines that power design visualization pipelines.
Industrial AR platforms combine spatial computing software, optical see-through or video see-through headsets, and sensor fusion algorithms to overlay digital instructions, schematics, and telemetry onto physical equipment. These systems operate with field-of-view parameters typically spanning 40 to 50 degrees and latency thresholds below 20 milliseconds to prevent motion sickness and ensure precise alignment. Markerless technology leads solution architecture due to reduced setup friction in dynamic factory environments, while remote assistance commands the fastest expansion as distributed workforces require expert guidance without travel. Hardware solutions capture the largest revenue pool, though integration services are deepening margin concentration as enterprises demand turnkey deployment.
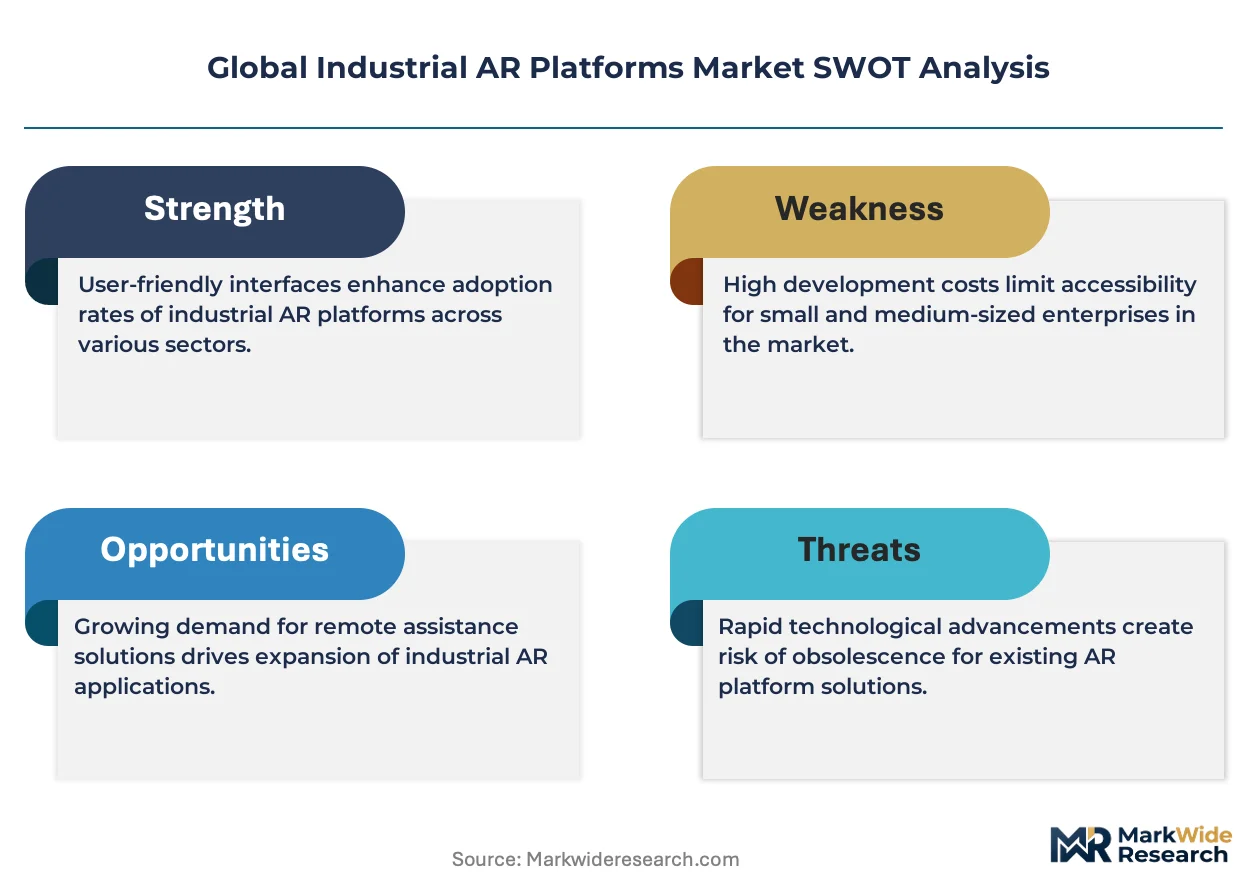
The EU AI Act imposes conformity requirements on AR systems with embedded machine vision, while FDA software-as-medical-device oversight extends to AR-guided surgical and diagnostic workflows in the United States. Germany's KBA and Japan's METI both enforce workplace safety standards that affect head-mounted display certification and operator training protocols. Stakeholders must monitor evolving liability frameworks that assign responsibility between AR software vendors and end-user operators when augmented instructions influence high-risk industrial decisions.
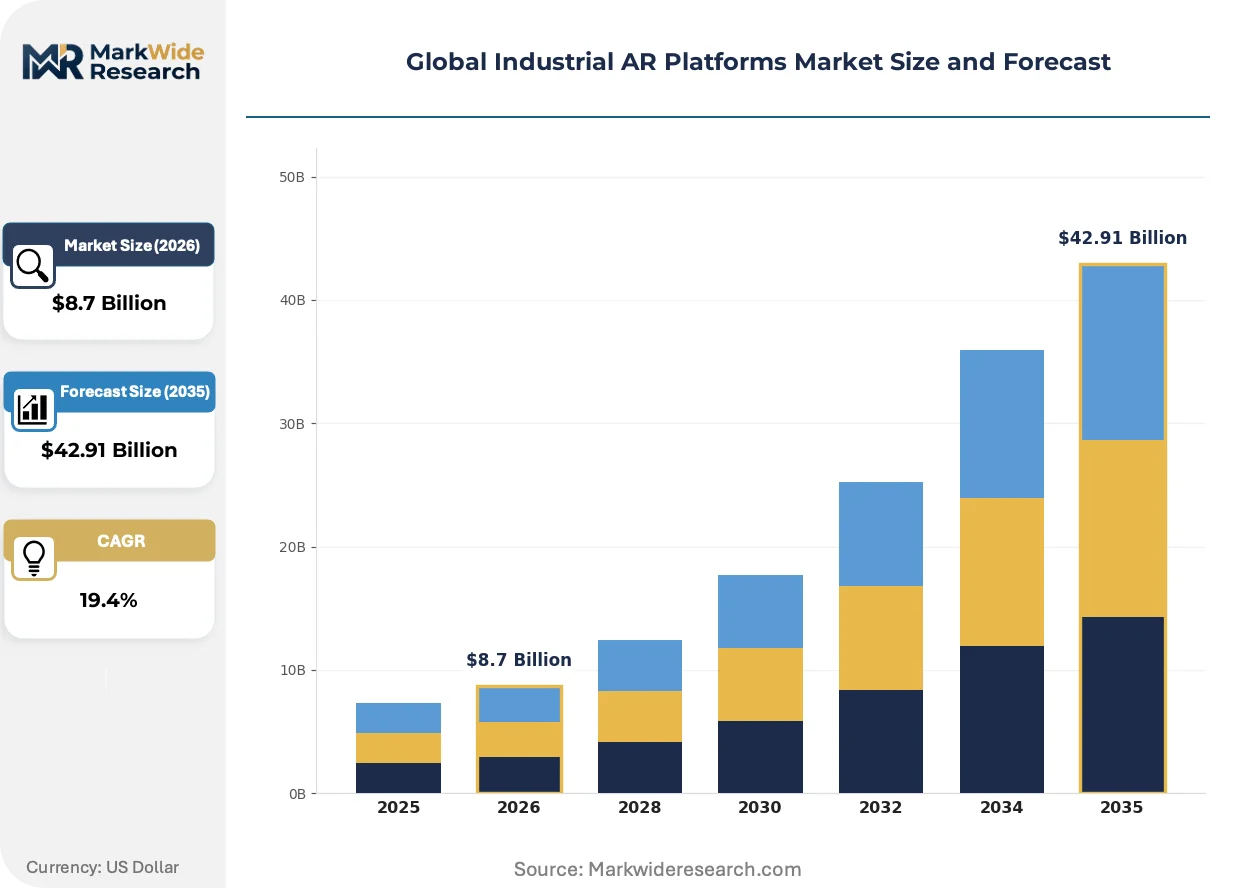
Market Dynamics
Enterprise AR adoption is bifurcating between mission-critical deployments requiring sub-millimeter spatial accuracy and cost-optimized field-assistance tools, with regulatory validation timelines now determining competitive positioning across aerospace and medical device workflows.
Growth Catalysts
- EU AI Act conformity mandates:Embedded machine vision in AR systems triggers mandatory CE marking pathways, accelerating vendor investment in pre-certified software architectures for industrial clients.
- Aerospace maintenance digitization:AR-guided repair protocols reduce aircraft downtime through real-time overlay of structural schematics and torque specifications during line maintenance operations.
- Germany's manufacturing corridor concentration:Automotive OEMs and tier-one suppliers in Bavaria and Baden-Württemberg drive demand for CAD-anchored digital thread integration.
Market Restraints
- Optical waveguide supply concentration:High-index glass substrates and diffractive optical elements rely on specialized foundries in Taiwan and South Korea, creating input cost volatility and lead time exposure.
- FDA software-as-medical-device pathway friction:AR-guided surgical workflows face 18-24 month validation timelines and predicate device requirements that compress vendor margins.
- Marker-based system displacement:Legacy fiducial-dependent AR installations face accelerated obsolescence as markerless SLAM algorithms achieve comparable accuracy without environmental preparation.
Strategic Opportunities
- US Gulf Coast energy hub expansion:Offshore platform operators in Texas and Louisiana seek AR-enabled remote expert assistance to reduce helicopter transport costs for specialized technician dispatch.
- 5G edge computing convergence:Ultra-reliable low-latency communication networks enable cloud-rendered AR content streams that eliminate onboard GPU requirements in lightweight headsets.
- Japan METI workplace safety incentives:Subsidies for human-machine interface upgrades accelerate head-mounted display adoption in precision manufacturing and nuclear decommissioning applications.
Industry Challenges
- Spatial computing talent scarcity:Shortages in computer vision engineering and sensor fusion algorithm development extend product development cycles and inflate compensation costs.
- Legacy MES integration complexity:Proprietary manufacturing execution system architectures in established automotive and pharmaceutical plants require costly middleware development for AR data exchange.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial AR Platforms Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Marker-Based, Markerless, Projection-Based, Superimposition-Based Application: Training, Maintenance, Remote Assistance, Design Visualization End User: Aerospace, Automotive OEMs, Manufacturing, Energy Solution: Software, Hardware, Consulting, Integration |
| Companies Covered | PTC, TeamViewer, Scope AR, Augmentir, XMReality, Unity Technologies, Vuzix Corporation, Fabrik, Robocortex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial AR Platforms Market Strategic Shifts
Spatial computing architectures are fragmenting into specialized stacks optimized for either precision-guided assembly or remote collaboration, with hardware-software decoupling enabling faster iteration cycles.
Video see-through headsets with pancake lens optics and micro-OLED panels are bifurcating the hardware tier. Aerospace final assembly lines in Toulouse and Hamburg adopt these systems for wire harness routing and structural alignment tasks. The technology is compressing training durations for complex manual operations while reducing error rates in safety-critical installations.
EU AI Act risk classification rules now capture AR systems with embedded diagnostic algorithms. Industrial deployments in medical device manufacturing must document training data provenance and model drift monitoring. German KBA automotive safety regulators are extending these conformity requirements to AR-guided quality inspection stations.
Buyer organizations are consolidating vendor relationships around integrated platform providers rather than point solutions. Energy sector operators in the US Gulf Coast now demand bundled hardware, software licenses, and field engineering support through multi-year agreements. This concentration is visible in upstream oilfield services where remote assistance contracts bundle AR headsets with satellite connectivity and expert staffing.
Global Industrial AR Platforms Market Segmentation
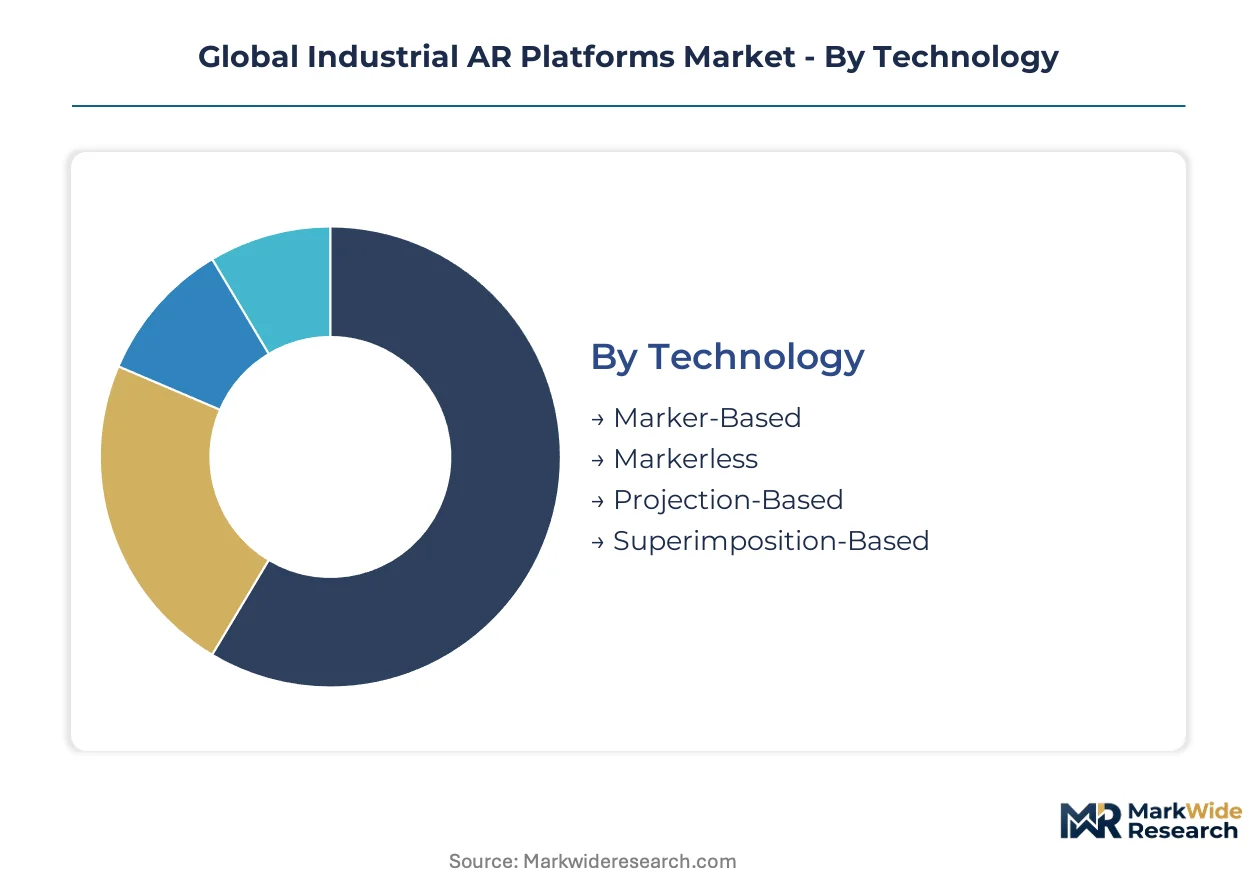
Industrial AR platforms fragment across four critical dimensions where regulatory scope, hardware intensity, and deployment complexity create distinct margin profiles. Technology choice determines validation burden under EU AI Act risk classifications. Application type governs latency requirements and headset specifications. End-user verticals impose sector-specific safety certifications. Solution architecture separates recurring software revenue from capital-intensive hardware cycles.
Technology:
EU AI Act conformity requirements differentiate these architectures through embedded machine vision risk classifications and CE marking pathways.
- Markerless:Simultaneous localization and mapping algorithms eliminate environmental preparation through real-time spatial mapping without fiducial markers. Aerospace final assembly lines in Toulouse and Hamburg deploy these systems for wire harness routing where marker placement proves impractical on unfinished airframes. The technology commands premium positioning as SLAM accuracy now matches legacy marker-dependent approaches.
- Marker-Based:Fiducial-dependent systems rely on printed or projected reference points for spatial anchoring. German automotive quality inspection stations retain these installations for torque verification protocols where environmental control permits consistent marker placement. Legacy deployments face accelerated replacement as markerless alternatives achieve price parity.
- Projection-Based:Laser or pico-projector systems cast digital overlays directly onto work surfaces without head-mounted displays. Japan's METI-subsidized precision manufacturing facilities adopt these for assembly guidance where operator mobility requirements remain limited.
- Superimposition-Based:Real-time object recognition replaces entire components with rendered alternatives for design validation. US Gulf Coast energy operators use these systems for subsea equipment mock-up reviews before offshore deployment.
Markerless systems handle the majority of new deployment throughput; projection-based configurations are gaining share fastest in fixed-station manufacturing environments.
Application:
Cost tier differentiation separates capital-intensive training installations from lightweight field-assistance tools with minimal hardware requirements.
- Remote Assistance:Real-time expert guidance through AR-enabled video streams reduces specialist travel requirements for distributed industrial assets. Offshore platform operators in Texas and Louisiana deploy these systems to eliminate helicopter transport costs for technician dispatch. The application commands the steepest expansion trajectory as 5G edge computing eliminates onboard GPU requirements.
- Maintenance:AR-guided repair protocols overlay structural schematics and torque specifications during line operations. Aerospace maintenance crews at MRO facilities deploy these systems for engine component replacement where downtime costs exceed validation investment.
- Training:Immersive skill transfer compresses proficiency timelines for complex manual operations. German automotive OEMs in Bavaria deploy these programs for electric powertrain assembly certification under KBA workplace safety oversight.
- Design Visualization:Real-time 3D rendering enables collaborative engineering review without physical prototyping. Unity Technologies anchors this segment through engine licensing to industrial design pipelines.
Maintenance applications absorb the largest capital allocation; remote assistance climbs fastest on share as connectivity infrastructure matures.
End User:
Volume concentration varies sharply by vertical, with aerospace and energy commanding unit premiums against automotive scale economies.
- Aerospace:FAA airworthiness requirements and EASA certification protocols impose rigorous validation standards on AR-guided inspection and assembly workflows. Final assembly lines in Toulouse, Hamburg, and Charleston deploy sub-millimeter accuracy systems for structural alignment tasks.
- Energy:Hazardous location classifications under OSHA and ATEX directives constrain headset specifications for upstream oilfield and downstream refinery applications. US Gulf Coast operators drive demand for intrinsically safe remote assistance configurations.
- Automotive OEMs:CAD-anchored digital thread integration dominates Bavarian and Baden-Württemberg manufacturing corridors. PTC leverages existing PLM relationships to capture workflow standardization opportunities.
- Manufacturing:General industrial applications span pharmaceutical packaging, electronics assembly, and food processing with divergent hygiene and safety requirements. FDA software-as-medical-device pathways extend to AR-guided diagnostic workflows in medical device production.
Aerospace end users contribute the highest per-deployment value; energy verticals expand most quickly as offshore digitization accelerates.
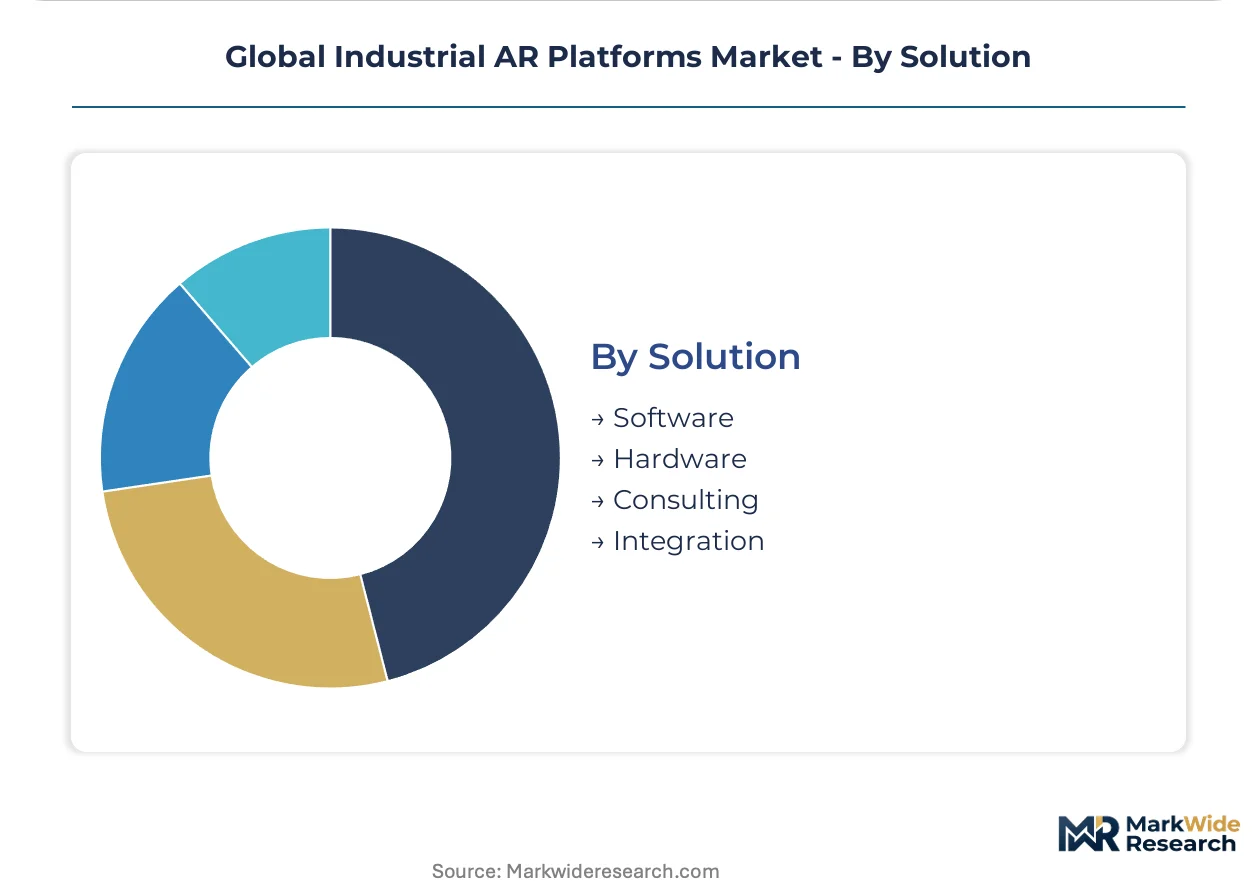
Solution:
Margin architecture separates recurring software revenue from hardware cycles and professional services intensity.
- Hardware:Optical see-through and video see-through headsets with pancake lens optics and micro-OLED panels capture the largest revenue pool. Supply concentration in Taiwanese and South Korean optical waveguide foundries creates input cost volatility.
- Software:Spatial computing platforms, sensor fusion algorithms, and enterprise integration layers generate recurring license revenue. EU AI Act documentation requirements for training data provenance and model drift monitoring inflate development overhead.
- Integration:Turnkey deployment services deepen margin concentration as enterprises demand middleware development for legacy MES connectivity. Proprietary manufacturing execution system architectures in established automotive and pharmaceutical plants require costly custom engineering.
- Consulting:Change management and operator training programs accompany platform adoption. Japan METI workplace safety incentives subsidize these services for human-machine interface upgrades in precision manufacturing.
Hardware solutions dominate absolute revenue; integration services capture expanding margin share as deployment complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. German automotive buyers absorb sub-millimeter accuracy premiums while US Gulf Coast operators prioritize total cost of ownership in hazardous environment deployments. Japanese precision manufacturers balance METI subsidies against workplace safety mandates.
United States
Aerospace MRO facilities in Charleston and Seattle drive demand for FAA-validated AR-guided inspection workflows. OSHA hazardous location classifications constrain headset specifications for upstream oilfield applications. Offshore platform operators in Texas and Louisiana deploy remote assistance systems to eliminate helicopter transport costs for specialized technician dispatch.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg anchor CAD-anchored digital thread integration at scale. KBA workplace safety regulators extend EU AI Act conformity requirements to AR-guided quality inspection stations. Stuttgart-based tier-one suppliers mandate sub-millimeter spatial accuracy for electric powertrain assembly certification.
Japan
Precision manufacturing and nuclear decommissioning applications absorb METI-subsidized human-machine interface upgrades. PMDA oversight extends to AR-guided diagnostic workflows in medical device production. Nagoya-area automotive suppliers deploy projection-based assembly guidance where operator mobility requirements remain limited.
France
Aerospace final assembly lines in Toulouse adopt video see-through headsets with pancake lens optics for wire harness routing tasks. EASA certification protocols impose rigorous validation standards on AR-guided structural alignment workflows. ANSM oversight captures AR systems with embedded diagnostic algorithms in medical device manufacturing.
South Korea
Optical waveguide foundries in specialized manufacturing clusters supply high-index glass substrates and diffractive optical elements. MFDS medical device regulations influence AR-guided surgical workflow validation timelines. Seoul-area electronics assemblers integrate markerless SLAM algorithms for dynamic factory environments without fiducial preparation.
Global Industrial AR Platforms Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Global Industrial AR Platforms Market. The vendor base consolidates around integrated platform providers rather than point solutions, with bundled hardware-software-field engineering agreements displacing transactional procurement. Three archetypes dominate: CAD-anchored digital thread specialists, real-time 3D engine licensors, and remote assistance workflow optimizers. Competitive intensity centers on strategic partnerships for 5G edge computing convergence and middleware development for legacy MES integration.
Within the CAD-anchored tier, PTC exemplifies platform consolidation through PLM relationship leverage. Among remote assistance specialists, Scope AR occupies a position emphasizing field technician tooling. At the engine licensing vector, Unity Technologies represents real-time 3D visualization pipeline anchoring. These three companies collectively illustrate how competitive positioning fragments across workflow specialization rather than converging on undifferentiated horizontal platforms.
| Leading Market Players |
|---|
| PTC |
| TeamViewer |
| Scope AR |
| Augmentir |
| XMReality |
| Unity Technologies |
| Vuzix Corporation |
| Fabrik |
| Robocortex |
| Others |
Value Chain & Pricing Dynamics
High-index glass substrate fabrication at Taiwanese foundries creates scale economies that simultaneously concentrate optical waveguide supply and establish price floors for AR headset manufacturers. This capacity utilization dynamic forces buyers into multi-year offtake agreements to secure diffractive optical element allocation, embedding supply chain rigidity directly into vendor pricing power.
Pricing Analysis
EU AI Act conformity dictates the pricing tier structure across industrial AR platforms, separating CE-marked systems with embedded machine vision from uncertified alternatives. Three-tier pricing structure across mission-critical, enterprise-standard, and field-assistance levels reflects validation burden and spatial accuracy specifications. Cost compression in the mid-tier is intensifying because markerless SLAM commoditization erodes hardware differentiation. Energy sector operators in the US Gulf Coast exhibit highest price sensitivity due to total cost of ownership scrutiny in hazardous environment deployments, while German automotive OEMs absorb sub-millimeter accuracy premiums under KBA workplace safety mandates.
Supply Chain Analysis
Trans-Pacific container availability fluctuations and port congestion at Busan and Kaohsiung inject lead time volatility into optical component procurement for headset assembly. High-index glass substrates, micro-OLED panels, and pancake lens optics draw from specialized foundries in Taiwan, South Korea, and Japan. Single-source vulnerability concentrates in diffractive optical element manufacturing where only two foundries maintain production-qualified capacity. Distribution runs through direct OEM relationships for aerospace and automotive tier-one suppliers, while energy sector deployments channel through systems integrators bundling satellite connectivity and field engineering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial AR platform demand tracks aerospace maintenance cycle recovery and offshore energy capital expenditure normalization, with equipment utilization rates at MRO facilities and drilling contractors serving as the cyclical anchor.
For Market Incumbents: Compound platform stickiness through deeper CAD-anchored digital thread integration and pre-certified EU AI Act software architectures that extend validation timelines for challengers. Vertical integration into optical waveguide sourcing from Taiwanese foundries defends margin position against input cost volatility. Certification investment in FDA software-as-medical-device pathways creates regulatory moats around surgical and diagnostic workflow segments. For New Entrants and Emerging Players: Legacy MES integration complexity at established automotive and pharmaceutical plants represents a service-layer gap where middleware development capabilities are under-deployed. White-space concentration sits in consulting and change management programs accompanying platform adoption, particularly in Japan where METI workplace safety incentives subsidize human-machine interface upgrades. Target precision manufacturing facilities in Nagoya and nuclear decommissioning applications through projection-based assembly guidance offerings that bypass headset hardware competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors remote assistance workflow optimizers with 5G edge computing partnerships already deployed, as connectivity infrastructure maturity eliminates capital-intensive onboard GPU requirements. Long-term viability over the next decade hinges on software recurring revenue share expansion relative to hardware cycles. Acquisition target archetype: sensor fusion algorithm specialists with automotive or aerospace validation credentials. Watch FAA and EASA certification timeline compression as the inflection signal indicating regulatory pathway standardization.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification Investment | CE marking pathways for embedded machine vision accelerate vendor selection in German automotive corridors. |
| Optical Waveguide Supply Agreement | Multi-year offtake contracts with Taiwanese foundries secure diffractive optical element allocation against lead time volatility. |
| Legacy MES Middleware Development | Proprietary manufacturing execution system integration unlocks pharmaceutical and automotive incumbent accounts. |
| 5G Edge Computing Partnership | Ultra-reliable low-latency networks enable cloud-rendered AR streams eliminating onboard GPU requirements. |
| FDA Software-as-Medical-Device Pathway | Validation investment in surgical workflow applications creates regulatory moats in high-margin healthcare verticals. |
Study Parameters
Initial hypotheses were tested against primary input from aerospace maintenance directors, automotive plant engineers, AR platform product managers, and energy sector procurement leads and refined through secondary validation. Primary fieldwork encompassed structured interviews across MRO facilities in Charleston and Hamburg, tier-one supplier operations in Bavaria, and offshore platform operators in Texas and Louisiana. Secondary sources included EASA certification filings, FDA software-as-medical-device submissions, EU AI Act conformity documentation, customs trade data for optical component flows, and hyperscaler 5G edge computing capex disclosures. Bottom-up deployment estimates triangulated against top-down industrial automation spend projections.
Variance decomposition across technology, application, end-user, and solution dimensions structured the analytical framework over the projection horizon. Modeled segmentation captured markerless versus marker-based architectures, remote assistance versus maintenance versus training applications, aerospace versus energy versus automotive verticals, and hardware versus software versus integration revenue splits. CAGRs were derived from fitted growth curves against equipment utilization and capital expenditure cycle indicators. Industry-specific inputs included aerospace fleet age profiles, German automotive electric powertrain transition timelines, and US Gulf Coast offshore drilling permit activity.
Underlying assumptions cover regulatory pathway stability, optical waveguide foundry capacity expansion, and 5G network deployment cadence, with deviation risk concentrated in EU AI Act enforcement intensity and Taiwan Strait logistics continuity. Practitioners should keep alternative scenarios live as aerospace maintenance cycle amplitude and offshore energy capital allocation priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
AR in Education Market
Virtual Reality (VR) and Augmented Reality (AR)
Mixed Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality Display Market
Virtual Reality (VR) and Augmented Reality (AR)
Mobile Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Telepresence Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Enterprise AR Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual and Augmented Reality in Tourism Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Visor Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Ski Machines Market
Virtual Reality (VR) and Augmented Reality (AR)
VR All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
VR in Sports Market
Virtual Reality (VR) and Augmented Reality (AR)
Global AR and VR Smart Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Tour Market