
 Virtual Tour Market | 2026-2036
Virtual Tour Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Tour Market Analysis
North America is narrowing its lead in virtual tour infrastructure deployment as cloud rendering capacity expands across the United States and Canada. Matterport sustains dominance through proprietary 3D capture hardware and SaaS platform integration. 3DVista differentiates by specializing in desktop-based authoring tools for offline hospitality deployments. Nodalview navigates the European real estate photography segment with mobile-native capture workflows.
A virtual tour constitutes an interactive digital reconstruction of physical spaces, assembled through photogrammetry, 360-degree videography, or LiDAR point clouds, then delivered via web browsers, mobile applications, or head-mounted displays for remote exploration and decision-making. The technology dimension segments across Virtual Reality, Web-Based Platforms, Mobile Applications, and Gamification, with Web-Based Platforms currently anchoring the largest addressable user base due to zero-install accessibility. Interactive Tours within the product type category command premium pricing from luxury real estate marketers seeking bespoke branding overlays, while 360-Degree Tours occupy the volume tier through template-driven production.
The Federal Trade Commission scrutinizes deceptive property representations in digital listings, while the EU AI Act imposes algorithmic transparency obligations on automated tour personalization systems. ISO standards for digital imaging quality and accessibility compliance shape procurement criteria for educational and government contracts. Stakeholders must weigh hardware-agnostic capture against platform-locked distribution as the primary strategic tension over the forecast horizon.
Market Dynamics
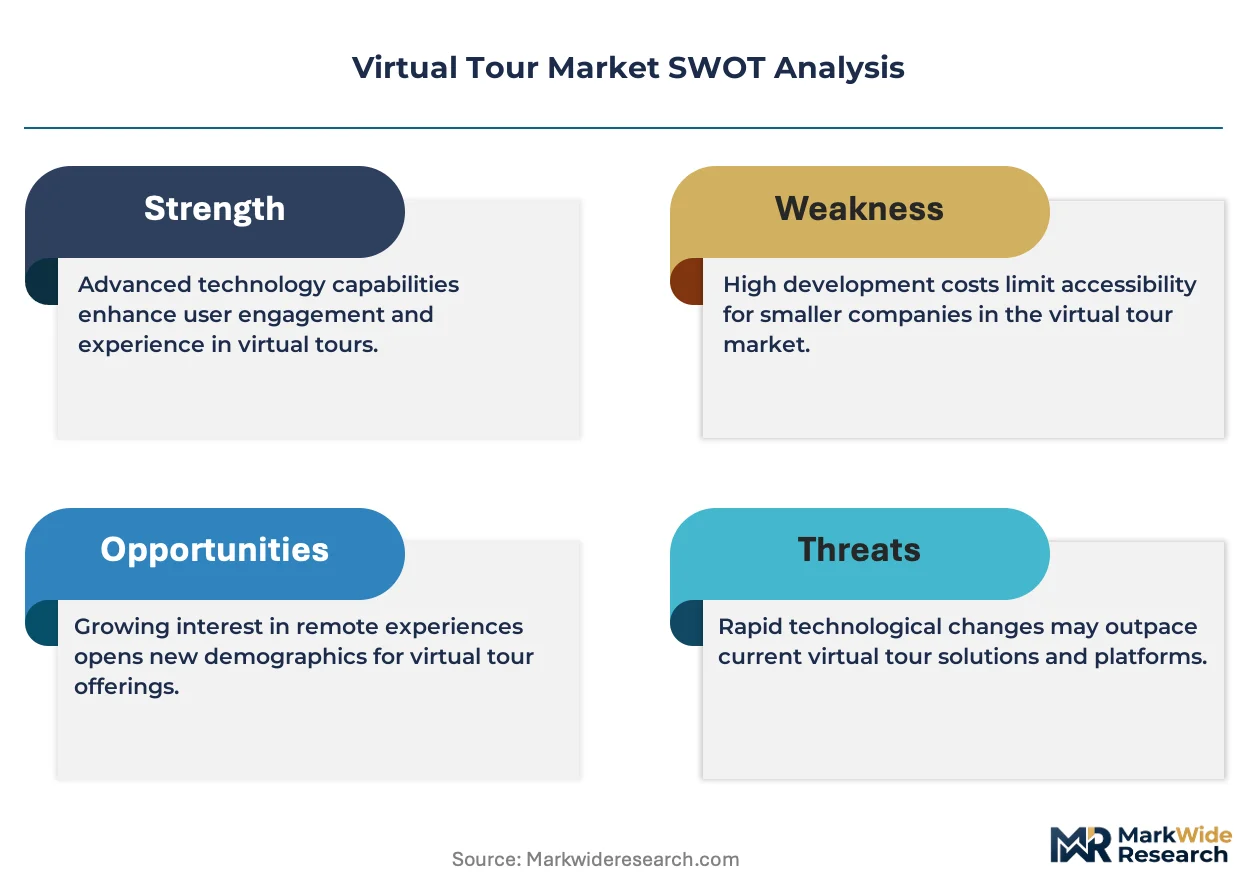
The virtual tour market pivots on a hardware-agnostic capture versus platform-locked distribution tension, as vendors weigh proprietary 3D camera ecosystems against open-standard spatial data formats that threaten margin capture.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Automated tour personalization systems in European real estate marketing now require explainable recommendation engines, creating compliance-driven demand for auditable SaaS platforms.
- Proptech adoption in US residential brokerage:Multiple Listing Service platform integrations have normalized immersive property walkthroughs as standard listing infrastructure, pulling enterprise subscriptions from independent agents.
- Photogrammetry automation:Cloud-based neural reconstruction pipelines reduce manual stitching labor, compressing production timelines for high-volume hospitality and commercial real estate portfolios.
Market Restraints
- LiDAR sensor cost volatility:Solid-state scanning component prices fluctuate with automotive sector demand cycles, squeezing hardware margins for dedicated 3D capture device manufacturers.
- GDPR spatial data processing restrictions:European vendors face fragmented national interpretations of biometric and location analytics prohibitions, complicating cross-border user behavior tracking.
- Template-driven 360-degree tour commoditization:Low-code authoring tools democratize basic panoramic production, eroding pricing power in volume-tier real estate segments.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Domestic assembly incentives for camera modules and edge computing hardware could localize cost structures for Asia-Pacific market entry.
- Healthcare facility digital twin integration:Hospital construction and renovation workflows increasingly specify as-built spatial documentation for facility management handover, opening architectural-engineering-construction demand.
- Convergence of NeRF neural radiance fields with WebGL delivery:Browser-native volumetric rendering without plugin dependencies enables photorealistic walkthroughs on commodity smartphones.
Industry Challenges
- Spatial data scientist talent scarcity:The intersection of computer vision, computational geometry, and real-time graphics programming commands premium compensation, constraining vendor R&D scaling.
- ISO 19136 geographic markup language certification timelines:Geospatial data interoperability standards for government and educational procurement extend sales cycles by 6-12 months.
- Legacy CAD-BIM integration complexity:Retrofitting existing architectural datasets into immersive tour pipelines requires manual geometry cleanup, inflating project costs for heritage building documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Tour Market |
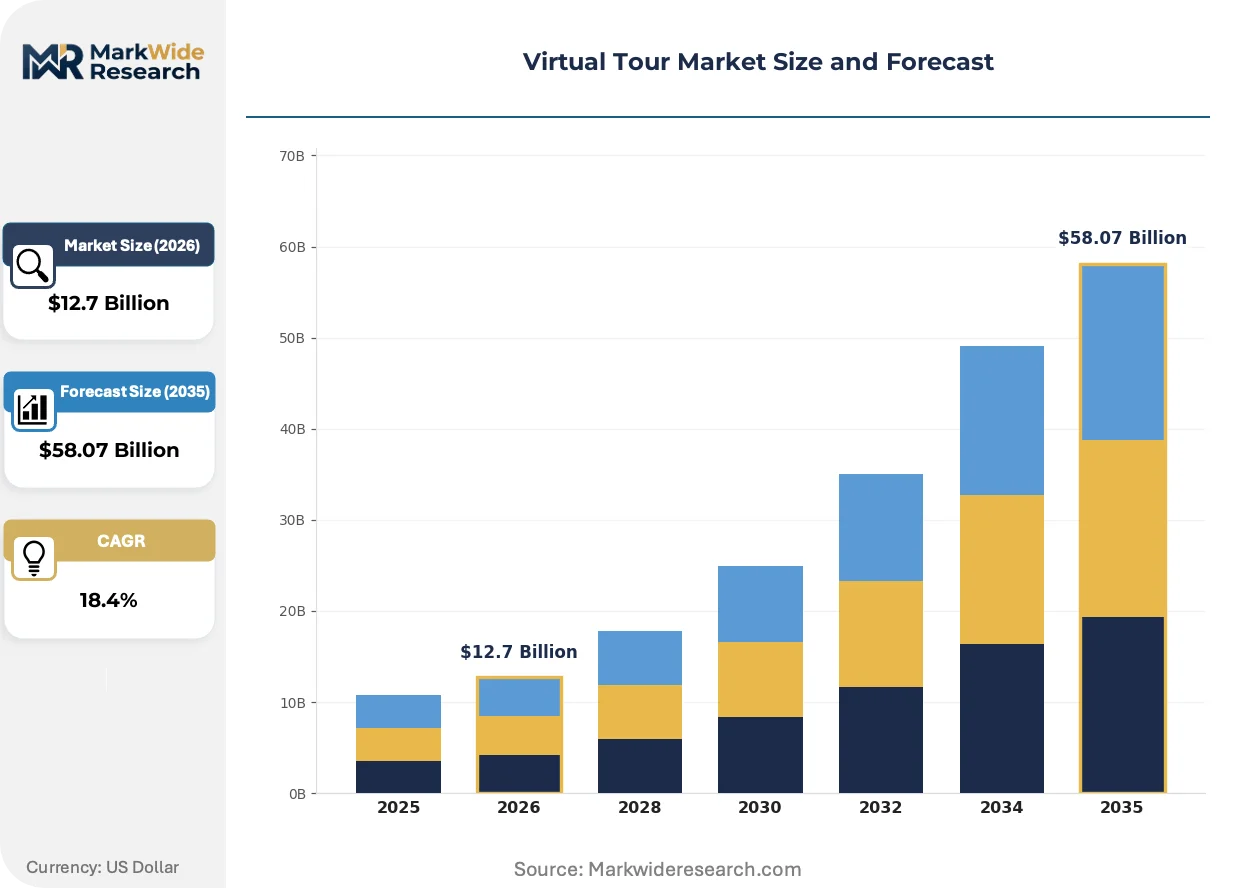
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $58.07 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 360-Degree Tours, Interactive Tours, Augmented Reality Tours, Video Tours End User: Real Estate, Travel Agencies, Educational Institutions, Retail Stores Technology: Virtual Reality, Web-Based Platforms, Mobile Applications, Gamification Application: Tourism Promotion, Property Showcasing, Remote Learning, Event Planning |
| Companies Covered | VirtualTourEasy, My360, Matterport, Nodalview, Tourbuzz, 3DVista, Lapentor, ImmersiVision, Tourweaver, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Tour Market Emerging Trajectories
Neural reconstruction methods and browser-native rendering standards are compressing production-to-delivery pipelines, while regulatory frameworks on algorithmic transparency reshape how personalization engines operate across jurisdictions.
Gaussian splatting is collapsing the computational barrier between photogrammetry capture and real-time volumetric display. Luxury real estate marketers in Dubai and Singapore adopt this technique for smartphone-accessible photorealism without headset requirements. The technology is collapsing hardware dependencies that previously gated premium immersive experiences to high-end VR installations.
GDPR Article 22 automated decision-making provisions now extend to tour recommendation algorithms that filter property sequences based on inferred user preferences. European vendors retrofit explainability layers into their ranking systems, prioritizing human-overridable suggestion logic. Interactive tour products with bespoke branding overlays face the steepest compliance retrofit costs due to embedded personalization engines.
Subscription fatigue among small-scale real estate photographers drives unbundling of capture hardware from SaaS platform commitments. Freelance operators in Texas and Florida increasingly rent 3D cameras through equipment-sharing marketplaces while mixing outputs across multiple hosting platforms. This behavior fragments vendor lock-in strategies and elevates interoperability of spatial file formats as a purchasing criterion.
Virtual Tour Market Segmentation
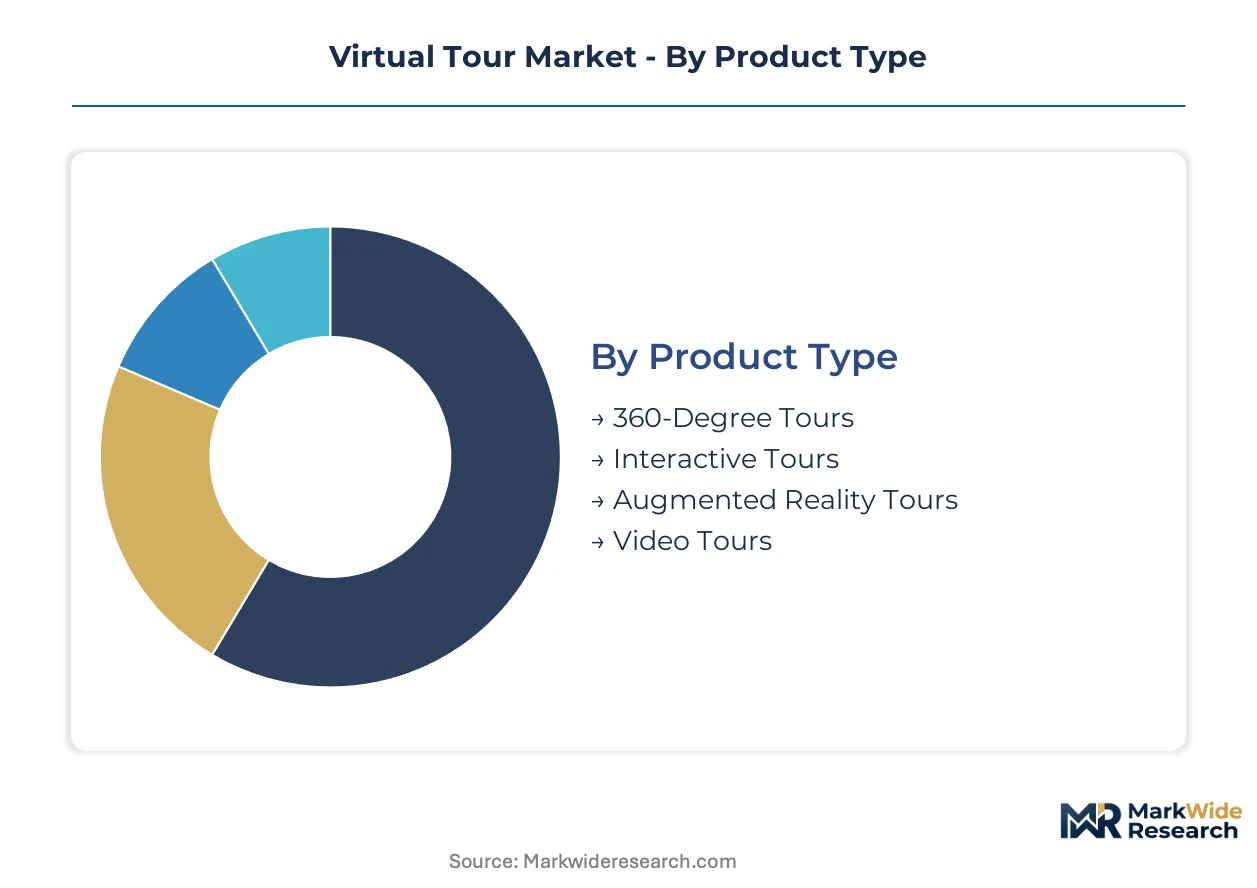
Virtual tour vendors architect product lines around capture complexity, distribution channel, and end-use workflow integration. Segmentation discipline separates volume-driven template offerings from premium immersive experiences commanding differentiated pricing power.
Product Type:
Mature panoramic formats anchor mainstream real estate marketing, while emerging volumetric technologies reshape luxury hospitality positioning.
- 360-Degree Tours:Template-driven panoramic stitching dominates residential brokerage listings through MLS platform integrations. Photographers in Texas and Florida deploy these for rapid turnaround on high-volume property portfolios where cost efficiency outweighs immersive depth.
- Interactive Tours:Bespoke navigation layers with embedded hotspots and branding overlays command premium subscriptions from Dubai and Singapore luxury marketers. GDPR Article 22 compliance costs inflate development timelines for European deployments due to explainable recommendation engine requirements.
- Augmented Reality Tours:Spatial anchoring of digital overlays onto physical environments through smartphone cameras.
- Video Tours:Linear walkthrough cinematography with limited user control, prevalent in entry-level real estate marketing.
360-Degree Tours handle the majority of throughput; Interactive Tours are gaining share fastest among premium hospitality deployments.
End User:
Cost tier separation runs from enterprise subscription contracts to freelance operator pay-per-use arrangements.
- Real Estate:Brokerage networks and independent agents constitute the largest addressable base, with MLS platform normalization pulling enterprise subscriptions from individual operators. Proptech adoption in US residential markets has standardized immersive walkthroughs as mandatory listing infrastructure.
- Educational Institutions:Campus virtual tours and remote laboratory access drive procurement from universities and K-12 districts. ISO standards for digital imaging quality and accessibility compliance extend sales cycles by 6-12 months for government-funded contracts.
- Travel Agencies:Destination pre-visualization for cruise and resort bookings.
- Retail Stores:Showroom digitization for furniture and automotive sectors.
Real Estate captures the dominant revenue share; Educational Institutions are climbing fastest as accessibility mandates harden procurement criteria.
Technology:
Application context dictates hardware requirements, from browser-native accessibility to headset-dependent immersion.
- Web-Based Platforms:Zero-install accessibility through standard browsers anchors the largest user base. Cloud rendering capacity expansion across the United States and Canada narrows infrastructure deployment gaps relative to mobile-native alternatives.
- Virtual Reality:Headset-dependent immersion targets architectural visualization and high-end property marketing. NeRF neural radiance field convergence with WebGL delivery is collapsing hardware dependencies that previously gated photorealistic experiences.
- Mobile Applications:Native app distribution for offline hospitality deployments and guided museum experiences.
- Gamification:Achievement systems and exploratory mechanics layered onto spatial navigation.
Web-Based Platforms command the broadest deployment; Virtual Reality is expanding most quickly as browser-native volumetric rendering eliminates plugin friction.
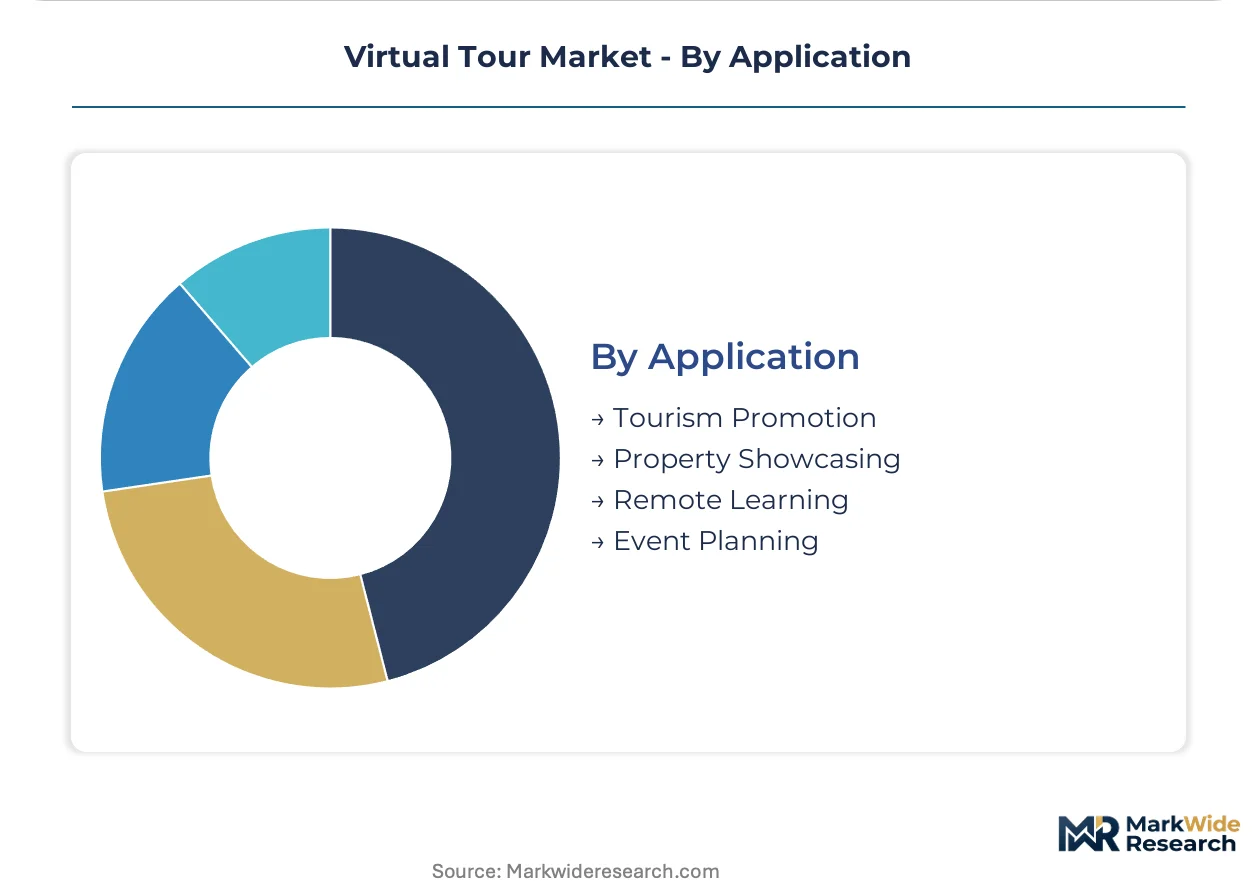
Application:
Volume concentration varies by sales cycle length and content refresh frequency.
- Property Showcasing:Residential and commercial real estate marketing drives recurring content production with standardized capture workflows. Photogrammetry automation through cloud-based neural reconstruction compresses production timelines for portfolio-scale deployments.
- Remote Learning:Virtual campus tours and laboratory simulations address accessibility requirements and enrollment marketing. Healthcare facility digital twin integration is opening architectural-engineering-construction demand for as-built spatial documentation.
- Tourism Promotion:Destination marketing organization contracts for pre-trip visualization.
- Event Planning:Venue scouting for corporate and wedding segments.
Property Showcasing generates the highest transaction velocity; Remote Learning is seeing the steepest expansion trajectory as educational procurement criteria evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FTC disclosure rules on digital property representations anchor United States market governance, while EU AI Act algorithmic transparency mandates reshape European vendor operations. Cloud rendering capacity expansion narrows infrastructure deployment gaps across North American and Asian markets.
United States
Multiple Listing Service platform integrations have normalized immersive property walkthroughs as mandatory listing infrastructure, pulling enterprise subscriptions from independent agents. FTC scrutiny of deceptive property representations in digital listings elevates compliance costs for automated tour personalization systems. Proptech adoption concentrates in Texas and Florida, where freelance photographers deploy high-volume capture workflows for residential brokerage networks.
Germany
Automotive sector demand cycles for solid-state LiDAR components create input cost volatility for dedicated 3D capture device manufacturers. KBA technical standards influence hardware certification timelines for spatial documentation tools used in commercial real estate marketing. Industrial clusters in Bavaria and Baden-Württemberg host precision optics manufacturers supplying photogrammetry equipment to European hospitality developers.
United Kingdom
Educational procurement criteria for campus virtual tours extend sales cycles through ISO standards compliance requirements for digital imaging quality and accessibility. The Information Commissioner's Office enforces GDPR spatial data processing restrictions on cross-border user behavior tracking. London-based luxury real estate marketers command premium pricing for bespoke interactive tours with embedded branding overlays.
India
Domestic assembly incentives under the PLI scheme for electronics manufacturing could localize cost structures for camera modules and edge computing hardware. Bureau of Indian Standards certification requirements shape procurement criteria for government and educational virtual tour contracts. Karnataka and Maharashtra host emerging proptech clusters where mobile-native capture workflows penetrate tier-2 city real estate markets.
Singapore
Luxury hospitality marketers adopt Gaussian splatting techniques for smartphone-accessible photorealism without headset requirements. The Personal Data Protection Commission enforces algorithmic transparency obligations on automated tour recommendation engines. Marina Bay and Sentosa development corridors drive demand for architectural-engineering-construction digital twin integration in facility management handover workflows.
Virtual Tour Market Vendor Landscape
Hardware-anchored platform providers and software-native authoring specialists split the market along the capture-versus-distribution tension. Matterport sustains dominance through proprietary 3D camera ecosystems and SaaS integration, while 3DVista and Nodalview occupy distinct positioning through desktop-based hospitality tools and mobile-native real estate workflows respectively. Strategic moves concentrate on interoperability lobbying for open-standard spatial data formats and unbundling of capture hardware from platform commitments to address subscription fatigue among freelance operators.
Among the named vendors, Matterport exemplifies the vertically integrated hardware-platform archetype, Nodalview occupies the mobile-first capture specialist position, and 3DVista represents the desktop authoring tool tradition. VirtualTourEasy, My360, and Tourbuzz sit within the template-driven volume tier where low-code production tools democratize basic panoramic creation. Lapentor and Tourweaver anchor the Asia-Pacific origin cluster, while ImmersiVision and Tourweaver exemplify emerging entrants competing on neural reconstruction delivery methods. The competitive terrain rewards vendors that resolve the hardware-agnostic capture versus platform-locked distribution tension through flexible subscription architectures.
| Leading Market Players |
|---|
| VirtualTourEasy |
| My360 |
| Matterport |
| Nodalview |
| Tourbuzz |
| 3DVista |
| Lapentor |
| ImmersiVision |
| Tourweaver |
| Others |
Supply Flow & Price Mechanics
Shanghai-to-Rotterdam container freight corridors transmit cost volatility from solid-state LiDAR component shortages through to European hardware vendors, compressing margins for Matterport-class capture device manufacturers while amplifying price differentiation between subscription-anchored SaaS tiers and freelance pay-per-use arrangements.
Pricing Analysis
Price spreads between Dubai luxury hospitality deployments and Texas residential brokerage volume tiers exceed threefold, reflecting divergent willingness-to-pay for photorealistic depth. Three-tier pricing structure across premium interactive tours, standard 360-degree panoramics, and economy template-driven offerings anchors the dominant model. Cost compression in the volume tier intensifies because low-code authoring tools democratize basic panoramic production. Freelance photographers in Florida exhibit highest price sensitivity, while Singapore facility management contractors absorb premium positioning for digital twin integration.
Supply Chain Analysis
US Commerce Department export controls on advanced photogrammetry software and neural reconstruction algorithms limit technology flows to Chinese vendors, fragmenting global component sourcing. Hardware assembly concentrates in China, Vietnam, and Mexico, drawing precision optics from Bavarian industrial clusters and edge computing chipsets from Taiwanese foundries. Single-source vulnerability runs through automotive-sector LiDAR sensor allocation, where demand cycles squeeze dedicated 3D capture device manufacturers. Distribution runs through direct-to-photographer equipment marketplaces and MLS-integrated SaaS platform subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity deepens as unbundling of capture hardware from platform commitments fragments vendor lock-in strategies, creating niche entry points for interoperability-focused specialists and equipment-sharing marketplace operators.
For Market Incumbents: Build switching-cost moats through proprietary spatial data format ecosystems that embed workflow dependencies across MLS platform integrations. Deepen backward integration into cloud rendering capacity across United States and Canadian infrastructure nodes. Counter emerging neural radiance field entrants by accelerating ISO 19136 certification timelines for government and educational procurement channels. For New Entrants and Emerging Players: Build out white-space positions in healthcare facility digital twin documentation, where architectural-engineering-construction workflows specify as-built spatial handover with limited incumbent penetration. Target tier-2 Indian city real estate markets through mobile-native capture workflows compliant with Bureau of Indian Standards certification. Anchor go-to-market through equipment-sharing marketplace partnerships that address subscription fatigue among freelance operators. For Investors and Strategic Acquirers: Hardware-agnostic SaaS platforms with open-standard spatial data interoperability represent the priority acquisition archetype for long-term viability across the next decade. These assets capture margin migration from commoditized capture devices toward workflow-embedded distribution layers. Watch for NeRF-to-WebGL delivery convergence achieving browser-native photorealism without plugin friction as the inflection signal for platform valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | MLS platform normalization in US residential brokerage pulls enterprise subscriptions from fragmented independent agents. |
| Acquisition of Specialist Firm | Neural radiance field startups compress photogrammetry-to-delivery pipelines for smartphone-accessible volumetric rendering. |
| Geographic Expansion | India PLI scheme incentives localize camera module assembly for Asia-Pacific cost structure competitiveness. |
| Strategic Partnership | Equipment-sharing marketplace alliances address subscription fatigue among Texas and Florida freelance photographers. |
| Product Launch | Gaussian splatting-enabled smartphone tours collapse hardware dependencies for Dubai and Singapore luxury marketers. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with real estate brokerage technology officers, proptech platform engineers, freelance capture specialists, and MLS integration leads; and secondary validation against SEC SaaS vendor filings, EU AI Act regulatory texts, hyperscaler cloud rendering capex disclosures, and customs records for LiDAR component trade flows. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Forecast inputs considered technology deployment model, end-use workflow integration depth, geographic regulatory cluster, and capture hardware sophistication tier across the projection horizon. CAGRs derived from segment-level adoption curve modeling and elasticity-adjusted pricing trajectory analysis. Neural reconstruction pipeline maturation and GDPR Article 22 compliance cost inflation shaped scenario-weighted outcomes.
The forecast holds incumbent behavior within observed patterns; aggressive platform unbundling moves by hardware-agnostic SaaS entrants would shift outcomes beyond modeled ranges. Material shifts in EU AI Act enforcement intensity or solid-state LiDAR automotive demand cycles would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Location-Based VR Entertainment Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Japan Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Smart Glasses for Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) in Healthcare Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Global AR and VR Smart Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Mobile Infrastructure Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive Augmented Reality (AR) HUD System Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Industrial AR Platforms Market
Virtual Reality (VR) and Augmented Reality (AR)
Canada Metaverse Market