
 Telepresence Equipment Market | 2026-2036
Telepresence Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Telepresence Equipment Market Intelligence
The talent pool for advanced telepresence system deployment is bifurcating between network engineering specialists and user experience designers. Cisco Systems, Inc. leverages its deep networking hardware legacy to offer integrated solutions. Microsoft Corporation competes by embedding its Teams platform within its broader enterprise software ecosystem. Zoom Video Communications, Inc. specializes in software-centric, user-friendly interfaces that prioritize ease of use.
Telepresence equipment encompasses a set of technologies that create a high-fidelity illusion of physical presence for remote participants. These systems integrate 4K video, multi-channel spatial audio, and low-latency IP networks to enable immersive, real-time interaction. Video conferencing systems constitute the market's core, while robotic devices are emerging as a high-growth category. Demand from corporate meetings provides volume, but specialized healthcare applications offer higher margin potential.
Data privacy regulations, including Europe's GDPR and the US HIPAA, impose strict requirements on the handling and encryption of communication data. Concurrently, certifications like CE marking in Europe and FCC approvals in the United States govern device safety and electromagnetic compatibility. Key stakeholders now face a strategic choice between on-premise systems for security control and cloud-based platforms for enhanced scalability.
Market Dynamics
The telepresence equipment market is shaped by the fundamental tension between achieving high-fidelity immersion and ensuring broad accessibility. This dynamic forces a strategic choice between specialized, hardware-intensive systems for realism and scalable, software-centric platforms for widespread deployment.
Growth Catalysts
- AI Integration:The embedding of artificial intelligence for functions like automated transcription and real-time translation enhances meeting productivity, driving adoption within large multinational corporations.
- Healthcare Demand:Specialized applications in healthcare, such as remote diagnostics and patient consultations, are creating high-margin opportunities that justify investment in premium telepresence systems.
- Remote Work Policies:Government initiatives and corporate mandates supporting remote and hybrid work models, particularly in North America and Europe, create a sustained demand for advanced collaboration tools.
Market Restraints
- High Initial Cost:The significant capital outlay required for dedicated, multi-screen room systems and their associated network infrastructure acts as a barrier for small and medium-sized enterprises.
- Network Dependency:System performance is highly sensitive to network quality, with issues of latency and insufficient bandwidth degrading the user experience, particularly outside of major urban centers.
- Data Sovereignty Rules:Regulations like Europe's GDPR impose strict data residency and processing requirements, complicating the architecture of global telepresence networks for multinational firms.
Strategic Opportunities
- Robotic Telepresence:Emerging use cases for mobile robotic telepresence in manufacturing for remote quality control and in logistics for warehouse management open new industrial revenue streams.
- Education Sector Expansion:Developing hybrid learning models in higher education provides an opportunity for dedicated telepresence classrooms that connect students and lecturers across multiple campuses.
- AR/VR Convergence:Integrating telepresence with augmented and virtual reality headsets can create fully immersive virtual meeting rooms for collaborative 3D design, simulation, and training applications.
Industry Challenges
- Talent Scarcity:A shortage of technicians with hybrid expertise in AV integration, network engineering, and UX design complicates the deployment and maintenance of sophisticated telepresence environments.
- Integration with Legacy Systems:Ensuring seamless interoperability between new telepresence platforms and existing enterprise IT infrastructure, including security protocols and older video conferencing hardware, remains a significant hurdle.
- Interoperability Standards:The lack of a universal standard for cross-platform communication can lead to vendor lock-in and a fragmented experience for users attempting to connect between different systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telepresence Equipment Market |
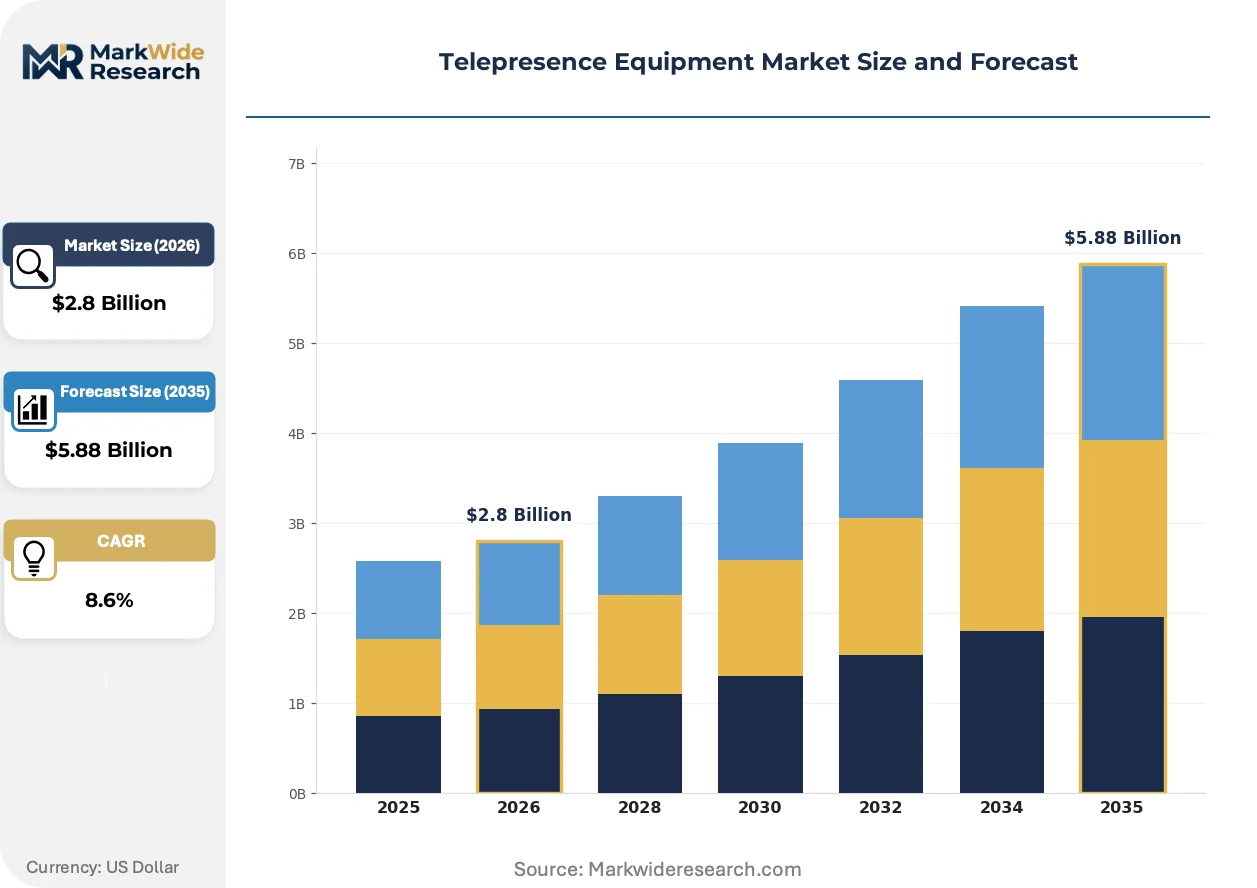
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Devices, Video Conferencing Systems, Interactive Displays, Telepresence Carts Technology: IP-based Solutions, Cloud Solutions, On-premise Systems, Web-based Platforms Use Case: Remote Collaboration, Education, Healthcare, Corporate Meetings End User: Enterprises, Educational Institutions, Healthcare Providers, Government Agencies |
| Companies Covered | Cisco Systems, Inc., Microsoft Corporation, HP, Inc., Huawei Technologies Co., Ltd., Avaya Inc., Sony Corporation, Zoom Video Communications, Inc., Enghouse Systems Limited, ZTE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telepresence Equipment Market Strategic Shifts & Innovations
The evolution of telepresence equipment is marked by a definitive shift from hardware-centric installations to intelligent, software-defined collaboration platforms. This transition is reshaping the value proposition from simple presence replication to delivering augmented and data-rich communication experiences.
Artificial intelligence is being embedded to automate tasks like meeting summaries and action item tracking. Large enterprises, particularly in the technology and financial services sectors, are adopting these features to quantify and improve meeting efficiency. This development is bifurcating the market between basic video streaming services and premium intelligent collaboration platforms.
Strict data privacy regulations, including Europe's GDPR and the US HIPAA, are now core design constraints. This is forcing vendors to engineer solutions with end-to-end encryption and region-specific data residency options as standard features. The healthcare sector is most impacted, prioritizing platforms that demonstrate auditable HIPAA compliance for telehealth services.
Enterprise procurement behavior is moving away from large, one-time capital expenditures on room systems toward flexible, subscription-based service models. This trend favors software-centric vendors and challenges the traditional channel of hardware resellers and installers. The shift is most visible in North American enterprises that prioritize operational expenditure models for scalability and agility.
Telepresence Equipment Market Segmentation
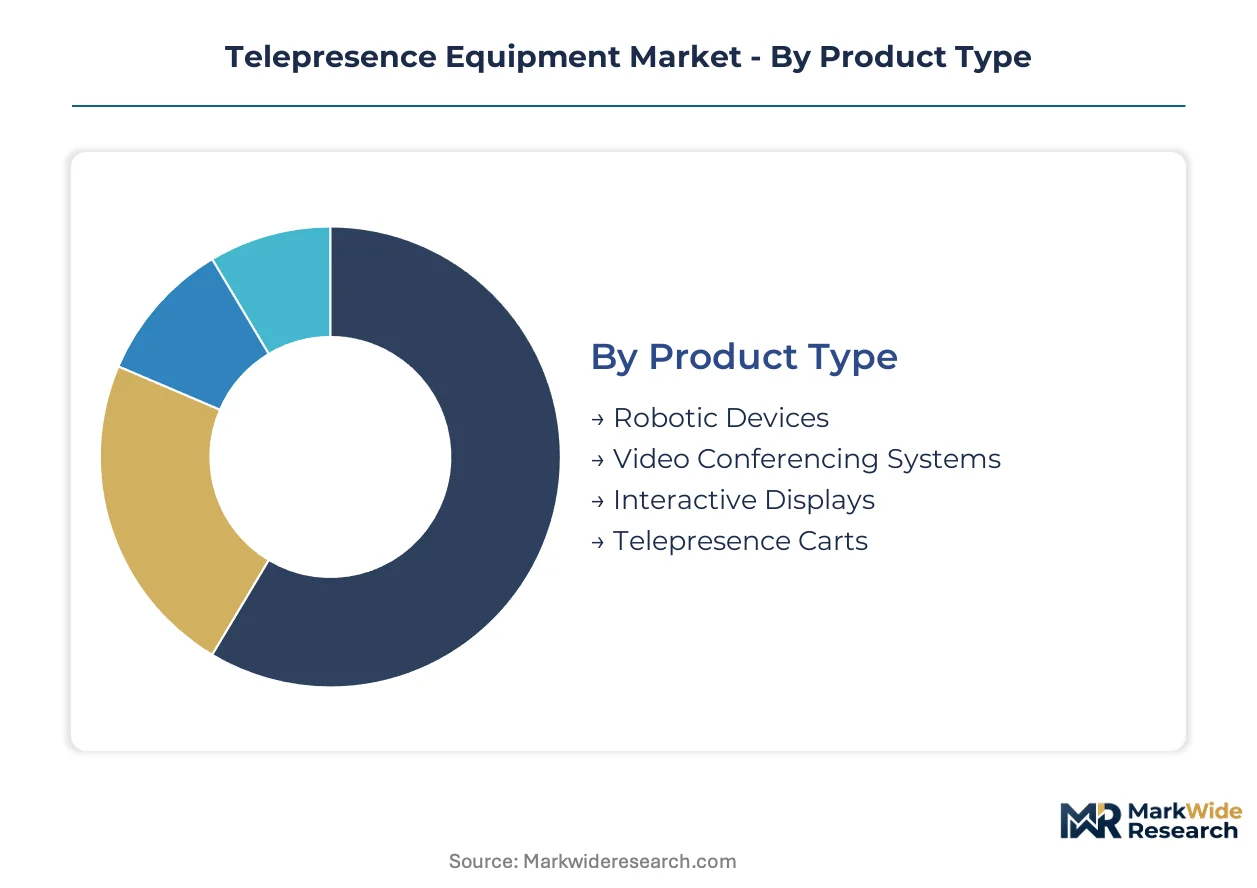
The telepresence equipment market segments across core product types, underlying technologies, diverse use cases, and varied end-user groups. Understanding these divisions clarifies demand patterns and competitive dynamics. Each segment presents unique deployment challenges and growth trajectories.
Product Type:
The deployment patterns for telepresence product types often reflect regional infrastructure capabilities and regulatory environments. Some product categories find stronger domestic demand in technologically advanced regions, while others are export-driven to emerging markets.
- Video Conferencing Systems:These core units integrate cameras, microphones, and displays to facilitate real-time visual and audio communication. Demand concentrates in corporate meetings within the United States, driven by the need for efficient cross-office collaboration.
- Robotic Devices:These mobile units allow remote users to physically navigate and interact with a distant environment, often incorporating cameras and two-way audio. Emerging use cases in manufacturing for remote quality control in Germany are expanding this segment.
- Interactive Displays:Large-format screens with touch capabilities enhance collaboration in meeting rooms and educational settings.
- Telepresence Carts:Portable, all-in-one units combine display, camera, and audio for flexible deployment in various environments.
Video Conferencing Systems holds the largest share; momentum sits with Robotic Devices.
Technology:
The technological underpinnings of telepresence systems reflect varying stages of market maturity and adoption curves. Newer, more agile solutions are gaining traction, while established technologies maintain a foundational role in enterprise infrastructure.
- Cloud Solutions:These platforms host telepresence services on remote servers, offering scalability, reduced upfront costs, and accessibility from various devices. Enterprise procurement behavior in North America is shifting towards these flexible, subscription-based models for agility.
- On-premise Systems:Hardware and software are installed and managed directly within the client's own data centers, providing maximum control over security and data residency. Large financial institutions in the EU prioritize these systems for strict GDPR compliance.
- IP-based Solutions:These systems leverage internet protocols for data transmission, forming the backbone of modern telepresence communications.
- Web-based Platforms:Accessible via standard web browsers, these solutions offer broad compatibility and ease of access for diverse users.
Cloud Solutions are expanding most quickly, while On-premise Systems maintain a significant installed base.
Use Case:
Each telepresence use case carries distinct margin profiles, with specialized applications often commanding higher value. The complexity of deployment and the criticality of the interaction influence the pricing and profitability within these segments.
- Healthcare:This segment encompasses remote patient consultations, diagnostics, and surgical assistance, demanding high-fidelity audio-visual capabilities and stringent data security. The pronounced growth in the US healthcare sector for telehealth services justifies investment in premium systems.
- Corporate Meetings:These applications support internal and external business discussions, ranging from small team huddles to large-scale conferences. Demand from multinational corporations in Europe provides significant volume for integrated telepresence solutions.
- Remote Collaboration:Facilitates team interaction and project work across dispersed geographical locations, enhancing productivity.
- Education:Supports hybrid learning models and remote lectures, connecting students and educators across multiple campuses or distant locations.
Healthcare applications are climbing the fastest, with Corporate Meetings representing the largest volume driver.
End User:
The specific requirements of each end-user segment dictate the features and scale of telepresence solutions deployed. Enterprises prioritize integration with existing IT infrastructure, while healthcare providers focus on compliance and patient privacy.
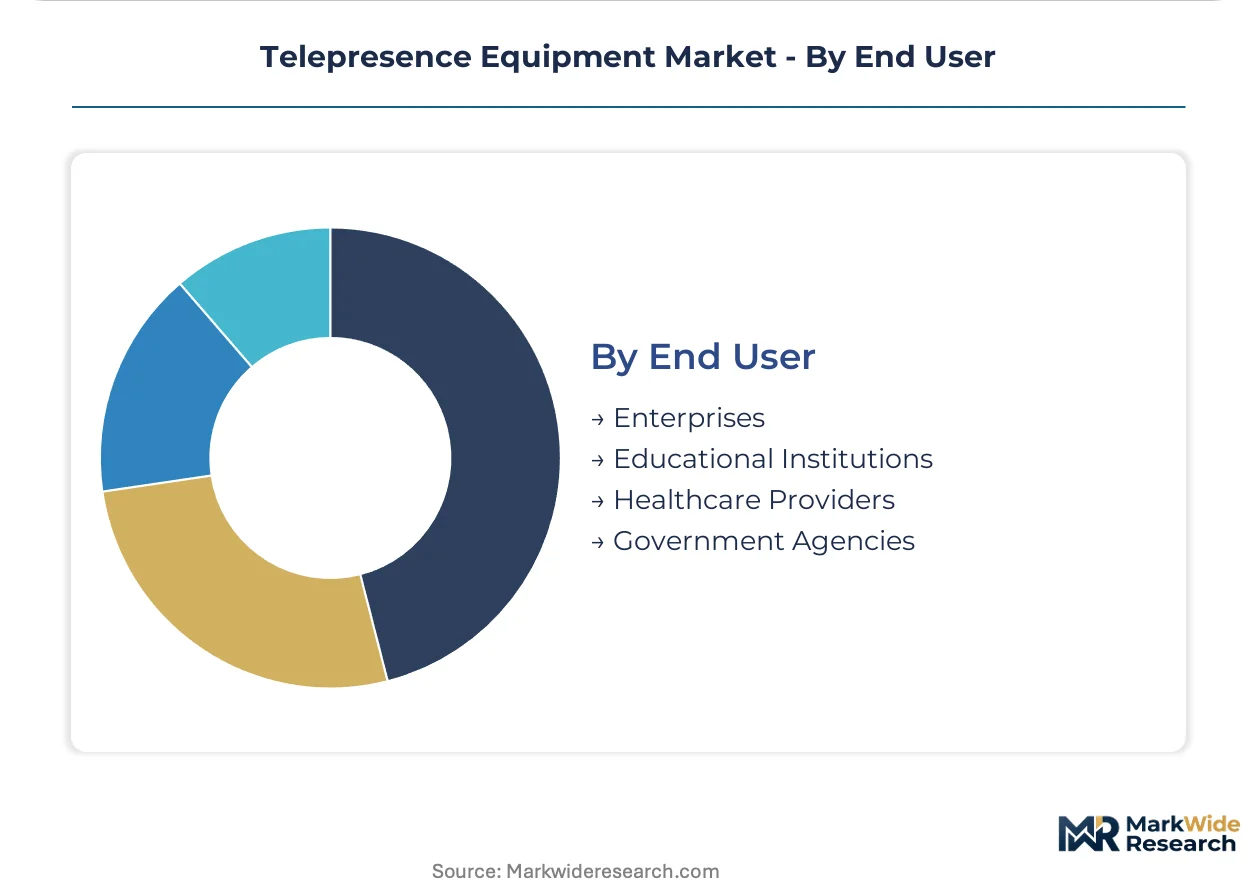
- Enterprises:Large corporations and businesses leverage telepresence for internal communication, client engagement, and global team collaboration. Demand is concentrating within technology and finance sectors in the United States, driven by multinational operational needs.
- Healthcare Providers:Hospitals, clinics, and medical practices utilize telepresence for remote diagnostics, specialist consultations, and patient monitoring. Strict HIPAA compliance requirements in the US influence platform selection for telehealth services.
- Educational Institutions:Universities and schools adopt telepresence for distance learning, virtual classrooms, and administrative meetings.
- Government Agencies:Public sector entities use telepresence for secure inter-agency communication and remote public service delivery.
Healthcare Providers are gaining share fastest, while Enterprises remain the largest revenue contributor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US HIPAA regulation significantly influences telepresence adoption in North America, particularly within the healthcare sector. Data privacy and security remain paramount for telehealth services across the region. This emphasis drives demand for compliant solutions.
United States
United States enterprises drive significant demand for telepresence in technology and finance sectors. The FCC approves device safety and electromagnetic compatibility for market entry. Silicon Valley and New York City serve as key hubs for innovation and adoption.
Germany
German manufacturing firms increasingly utilize robotic telepresence for remote quality control applications. GDPR mandates strict data residency and processing requirements for telepresence deployments. Bavaria's industrial clusters are seeing specialized system integration.
Japan
Japanese corporations value telepresence for efficient cross-office collaboration and hybrid learning models. METI promotes digital transformation initiatives that include advanced communication technologies. Tokyo's corporate headquarters and R&D centers are early adopters.
United Kingdom
United Kingdom companies show strong demand for telepresence due to remote work policies and financial services needs. The UK GDPR imposes robust data protection standards on communication platforms. London's financial district drives significant volume for integrated solutions.
China
Chinese large enterprises require advanced telepresence for vast geographical operations and global collaboration. MIIT actively supports the development of domestic technology solutions and infrastructure. Shenzhen's technology ecosystem fosters rapid innovation in telepresence hardware.
Telepresence Equipment Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the telepresence equipment market. This tiered structure includes established hardware providers, software-centric platform developers, and niche innovators focusing on specific applications. Companies engage in strategic partnerships to expand ecosystem compatibility and diversify their product portfolios.
On the premium-tier vector, Cisco Systems, Inc. exemplifies a legacy hardware and networking integration approach. Microsoft Corporation sits within the software-centric enterprise ecosystem, leveraging its Teams platform for broad adoption. Zoom Video Communications, Inc. represents a specialization in user-friendly, software-defined interfaces that prioritize accessibility.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Microsoft Corporation |
| HP, Inc. |
| Huawei Technologies Co., Ltd. |
| Avaya Inc. |
| Sony Corporation |
| Zoom Video Communications, Inc. |
| Enghouse Systems Limited |
| ZTE Corporation |
| Others |
Cost & Logistics Intelligence
Economies of scale in software platform development and hardware manufacturing shape the telepresence equipment market. This scale drives both supply concentration among a few large players and influences price floors for integrated solutions.
Pricing Analysis
Geographic price spreads for telepresence solutions vary significantly, influenced by regional demand and regulatory requirements. Subscription-based SaaS-tiered models dominate, offering flexibility for enterprises. Price differentiation stems from customization level for specific use cases and certification level, such as HIPAA compliance for healthcare providers. Pricing softness runs through basic video conferencing services due to increased competition from freemium models. Small and medium-sized businesses exhibit the highest price sensitivity, while large enterprises prioritize feature sets and integration capabilities.
Supply Chain Analysis
Inventory levels for specialized telepresence hardware are carefully managed to avoid obsolescence, given rapid technological advancements. Geographic supply concentration for core components resides in China for manufacturing and the United States for advanced software development and system integration. Raw material dependencies include 4K camera modules, low-latency IP network components, and specialized display panels. Single-source vulnerability for advanced sensor components presents a structural supply chain risk. Distribution runs through direct sales channels for large enterprise accounts and a network of value-added resellers for broader market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sophisticated telepresence deployments demand a rare blend of technical and user experience expertise, creating a capability scarcity in the market.
For Market Incumbents: Fortify existing enterprise client relationships by deepening platform integration with broader IT ecosystems. Acquire niche AI software firms to accelerate the development of automated transcription and real-time translation capabilities. This defends against fragmentation from emerging open-source collaboration tools. Investment in advanced network security certifications, like ISO 27001, serves as a critical lever for securing high-value contracts.
For New Entrants and Emerging Players: HIPAA compliance certification fast-tracks market entry into the high-margin telehealth sector. Target underpenetrated segments like remote patient monitoring in rural areas or specialized hybrid learning platforms for vocational training. A subscription-based model with tiered service levels provides an accessible go-to-market angle for small clinics and educational institutions.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated software providers with strong intellectual property in AI and immersive experiences. The long-term viability of immersive collaboration drives sustained investment in this sector. Seek out mid-cap firms with proprietary AI/VR integration capabilities and established enterprise client bases. Increased corporate R&D spending on AR/VR telepresence serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Enhances ecosystem compatibility and user stickiness for enterprise clients. |
| Strategic Partnership | Expands market reach and diversifies product portfolios through complementary offerings. |
| Acquisition of Specialist Firm | Accelerates technological advancement in AI or immersive capabilities. |
| Geographic Expansion | Captures demand in underserved regions or emerging economic hubs. |
| Product Launch | Introduces innovative features that differentiate from established competitors. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market intelligence anchors the qualitative findings of this study. Primary research involved conversations with telepresence system integrators, IT procurement officers at large enterprises, telehealth administrators in healthcare, and user experience designers. Secondary sources included SEC filings of publicly traded technology companies, technology patent databases, government telehealth policy documents, and industry association reports. A robust bottom-up and top-down triangulation approach ensured data accuracy and consistency.
Sensitivity analysis explores market responses across varying macroeconomic scenarios, providing a comprehensive understanding of potential future states. The analytical framework modeled key segmentation dimensions, including product type, underlying technology, diverse use cases, end-user groups, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected adoption rates across the analysis window. Enterprise IT spending forecasts and telehealth adoption rates served as critical industry-specific forecast inputs.
Underlying assumptions cover technological advancement rates and regulatory stability, with deviation risk concentrated in geopolitical shifts impacting supply chains. Forecasts reflect these assumptions, acknowledging that rapid technological disruption or unforeseen data privacy legislation could revise projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Smart Augmented Reality Glasses for B2B Market
Virtual Reality (VR) and Augmented Reality (AR)
Location Based VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Para-Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Immersive Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Fence Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
Mixed Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Dressing Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Fitting Room Market