
 Asia-Pacific Virtual Reality (VR) Health Market | 2026-2036
Asia-Pacific Virtual Reality (VR) Health Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Virtual Reality (VR) Health Market Outlook
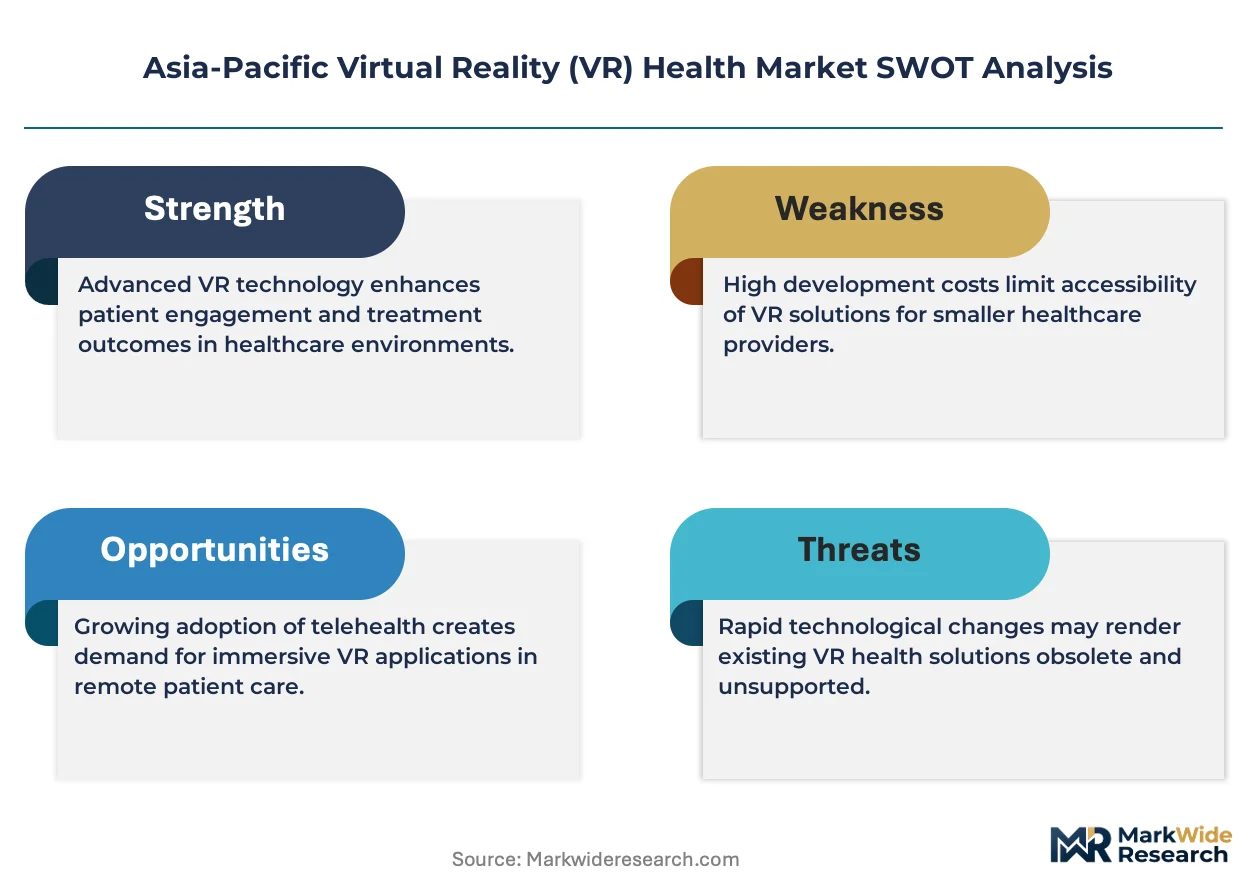
Lightweight polymer optics are displacing traditional glass lenses in VR headsets, which is rebalancing unit economics for health-grade hardware across the region. Microsoft Corporation leverages its Azure cloud backbone to anchor enterprise VR deployments in hospital systems. Sony Corporation dominates high-resolution display supply for therapeutic headsets. Samsung Electronics competes through integrated semiconductor-to-display manufacturing scale.
Asia-Pacific Virtual Reality (VR) Health comprises immersive digital systems combining head-mounted displays, spatial tracking sensors, and software platforms rendering three-dimensional clinical environments for diagnosis, therapy, or medical training. These systems operate at sub-20 millisecond motion-to-photon latency to prevent user disorientation during extended therapeutic sessions. Hardware captures the dominant revenue share as clinics and hospitals prioritize FDA- and CDSCO-compliant device procurement over fragmented software licenses. Therapeutic application leads volume adoption, while pain management represents the fastest-expanding use case as opioid-alternative protocols gain clinical traction in Australian and Japanese reimbursement frameworks.
Japan's PMDA and South Korea's MFDS enforce stringent biocompatibility and electromagnetic-safety standards for head-worn medical devices, directly shaping product development timelines for regional manufacturers. China's NMPA software-as-medical-device classification rules determine market access for AI-integrated VR diagnostic tools. Australia's TGA inclusion of immersive rehabilitation in aged-care funding schedules has unlocked institutional procurement channels. Stakeholders must monitor divergence between national medical device software frameworks and emerging cross-border data-localization requirements affecting cloud-dependent VR health platforms.
Market Dynamics
CDSCO's software-as-medical-device classification framework is compressing approval timelines for immersive diagnostic platforms, redirecting capital toward regulatory-first product architectures across China, Japan, and India.
Growth Catalysts
- Japan's PMDA biocompatibility pathway:Streamlined electromagnetic-safety certification for head-worn therapeutic devices accelerates hospital procurement cycles in Tokyo and Osaka medical networks.
- Polymer optics substitution:Lightweight lens materials are displacing glass in VR headsets, cutting per-unit weight by half and enabling extended clinical sessions without patient fatigue.
- Australia's TGA aged-care funding:Inclusion of immersive rehabilitation in national reimbursement schedules unlocks institutional purchasing power across Queensland and Victoria aged-care facilities.
Market Restraints
- Display panel concentration:High-resolution micro-OLED supply concentrates in South Korean and Japanese foundries, creating single-source vulnerability for therapeutic headset manufacturers.
- Cloud data localization mandates:China's cybersecurity law and India's data protection rules fragment platform architecture, forcing redundant infrastructure deployment.
- Motion-to-photon latency floor:Sub-20 millisecond performance requirements demand specialized ASIC design, excluding commodity chip suppliers from medical-grade supply chains.
Strategic Opportunities
- India's tier-two hospital networks:Surgical training VR remains underpenetrated outside Mumbai, Delhi, and Bangalore metro corridors, presenting first-mover expansion terrain.
- Chronic pain protocol integration:Opioid-alternative reimbursement frameworks in Australian and Japanese systems are accelerating therapeutic VR adoption in palliative care settings.
- AI-diagnostic convergence:NMPA's software-as-medical-device rules for AI-integrated VR tools create regulatory clarity for automated pathology visualization platforms.
Industry Challenges
- Clinical workflow integration:Hospital IT departments lack specialized personnel to configure VR systems within existing electronic health record architectures, extending deployment timelines.
- Cross-border certification reciprocity gaps:Divergent biocompatibility testing requirements between PMDA, MFDS, and CDSCO force duplicate validation studies for multi-country product launches.
- Semiconductor procurement lead times:Custom motion-tracking ASICs face 40-week foundry queues, constraining hardware scaling for emerging platform entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Virtual Reality (VR) Health Market |
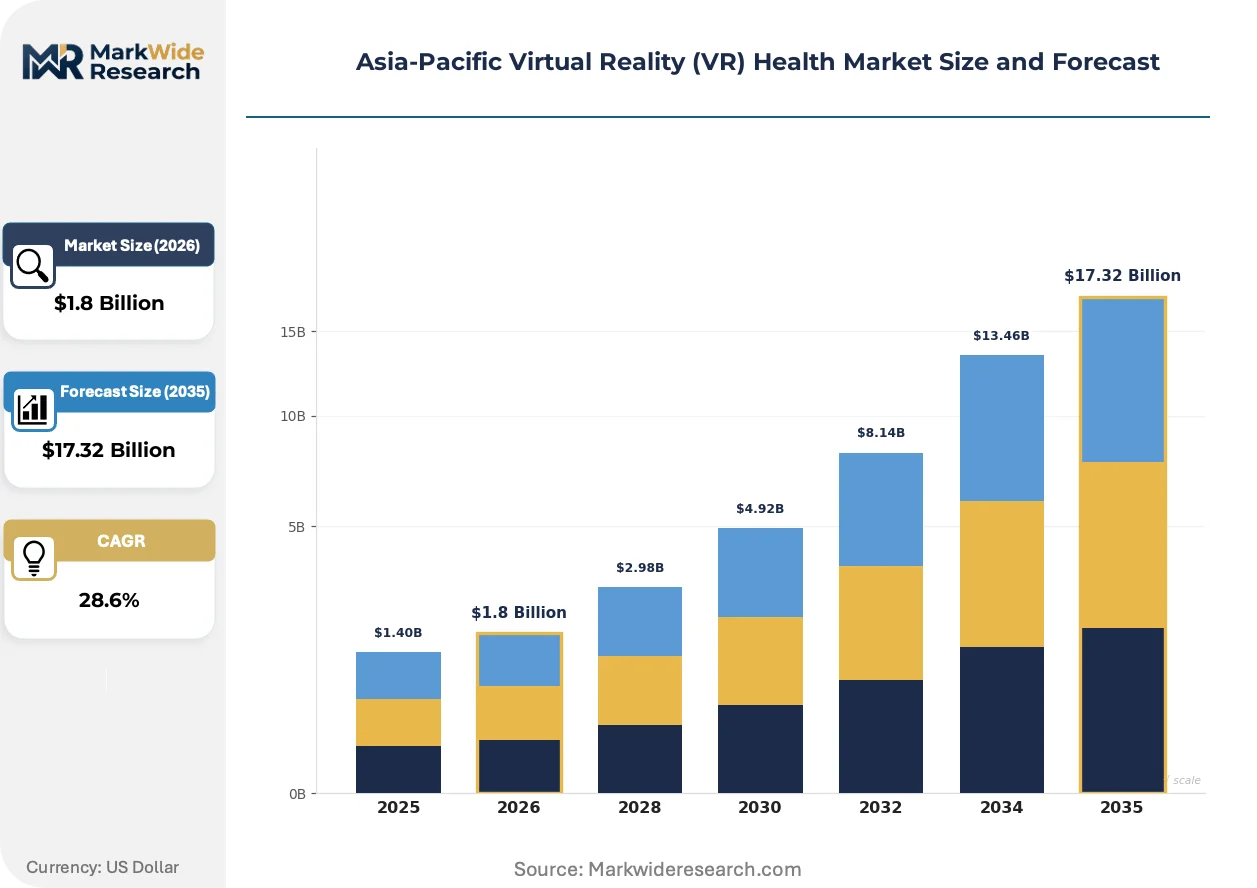
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Accessories, Content Application: Therapeutic, Rehabilitation, Training, Pain Management End User: Clinics, Hospitals, Research Institutions, Home Care Technology: 3D Simulation, Motion Capture, Haptic Feedback, Immersive Environments |
| Companies Covered | Microsoft Corporation, Koninklijke Philips N.V., Sony Corporation, CAE Healthcare Inc., Siemens Healthineers, Samsung Electronics, Google LLC, GE HealthCare, HTC Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Virtual Reality (VR) Health Market Strategic Shifts
Spatial computing architectures are redefining clinical interaction models, compressing the gap between diagnostic visualization and therapeutic intervention across Asia-Pacific hospital systems.
Foveated rendering powered by eye-tracking sensors is automating computational load distribution in therapeutic headsets. Tier-one hospitals in Shanghai and Singapore are deploying these systems for surgical simulation training. The technology is automating resolution allocation to peripheral vision zones, reducing GPU requirements by half while maintaining diagnostic image fidelity.
China's NMPA software-as-medical-device classification rules are mandating pre-market clinical validation for AI-integrated diagnostic VR platforms. Domestic manufacturers in Shenzhen and Beijing are restructuring product development cycles to accommodate prospective trial requirements. The regulation most affects radiology visualization tools, forcing partnerships between hardware OEMs and teaching hospitals for trial execution.
Subscription-based platform licensing is displacing perpetual software purchases in Australian and Japanese rehabilitation centers. Hospital procurement departments are negotiating multi-year immersive therapy access agreements with outcome-linked renewal clauses. The shift is most visible in Victoria's aged-care networks, where bundled hardware-software-service contracts now dominate tender specifications.
Asia-Pacific Virtual Reality (VR) Health Market Segmentation
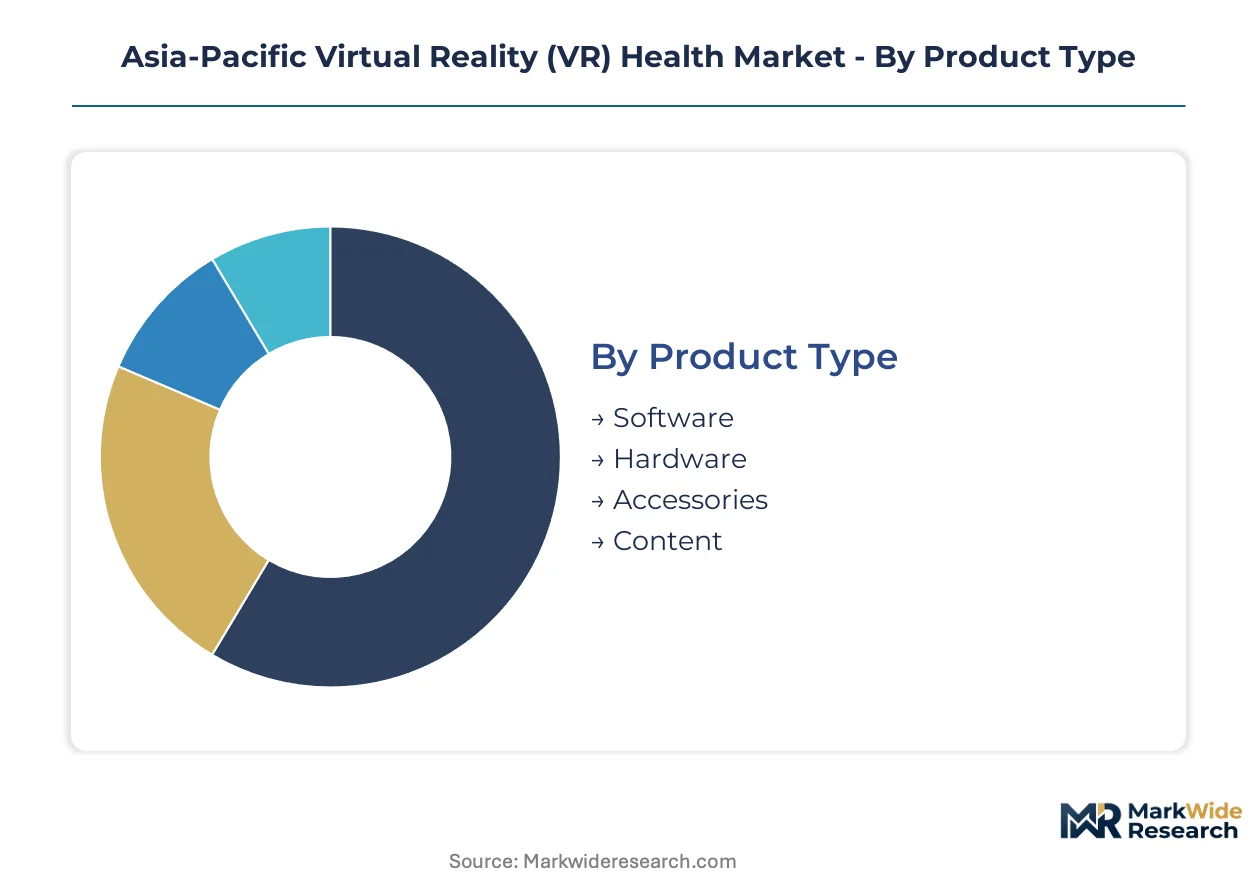
Segmentation in Asia-Pacific VR Health reveals divergent capital requirements and procurement pathways across hardware-intensive versus software-driven delivery models. Hospital procurement departments prioritize compliant device categories, while research institutions drive experimental technology adoption.
Product Type:
Hardware segments demand the heaviest upfront capital deployment, with foundry commitments and biocompatibility certification consuming 60-70% of initial investment for new entrants. Software and content categories require lighter fixed assets but heavier regulatory documentation spend.
- Hardware:Head-mounted displays, spatial tracking sensors, and compute modules constitute the revenue base. China's tier-one hospital networks in Beijing and Shanghai concentrate procurement for FDA- and CDSCO-compliant surgical training systems. NMPA electromagnetic-safety mandates extend development timelines by 8-12 months for domestic manufacturers.
- Software:Platform architectures rendering clinical environments and patient management dashboards. Australian aged-care facilities in Victoria and Queensland negotiate subscription licensing for rehabilitation protocols. TGA reimbursement inclusion accelerates institutional purchasing cycles beyond hardware refresh rates.
- Accessories:Peripheral controllers, sanitization stations, and mounting hardware for clinical deployment.
- Content:Procedure-specific simulations and therapeutic scenario libraries licensed per-seat or per-procedure.
Most installed capacity flows through Hardware. Expansion is steepest in Software.
Application:
Application segmentation maps directly to reimbursement authorization status across national health systems, determining addressable market size per use case.
- Therapeutic:Clinical interventions for anxiety disorders, PTSD, and phobia treatment using graduated exposure protocols. Japanese palliative care networks in Tokyo and Osaka deploy these systems under PMDA-cleared protocols. Opioid-alternative reimbursement frameworks accelerate adoption in chronic pain adjacencies.
- Pain Management:Distraction-based and neurofeedback interventions for acute and chronic pain conditions. Australian private insurers and workers compensation schemes now cover immersive therapy sessions, unlocking procurement in Sydney and Melbourne hospital systems. The segment climbs the fastest as regulatory clarity spreads.
- Rehabilitation:Motor function recovery and cognitive retraining for stroke and trauma patients.
- Training:Surgical simulation and procedural rehearsal for resident education.
Procurement volume concentrates in Therapeutic. Pain Management gains share fastest as reimbursement expands.
End User:
End user categories stratify by procurement sophistication, IT integration capability, and patient throughput requirements.
- Hospitals:Multi-department deployments spanning surgery, psychiatry, and rehabilitation units. China's tier-one medical networks in Guangdong and Jiangsu provinces lead capital expenditure, with 200+ bed facilities standardizing VR infrastructure. CDSCO software-as-medical-device rules compress approval timelines for diagnostic platforms.
- Clinics:Specialized outpatient facilities focusing on single-application deployments. India's metro corridor clinics in Mumbai and Delhi pilot surgical training modules under streamlined CDSCO pathways. Lower IT staffing drives preference for turnkey hardware-software bundles.
- Research Institutions:Academic medical centers conducting clinical validation trials.
- Home Care:Direct-to-patient rental and purchase models for chronic condition management.
Deployment scale peaks in Hospitals. Penetration accelerates most quickly in Clinics.
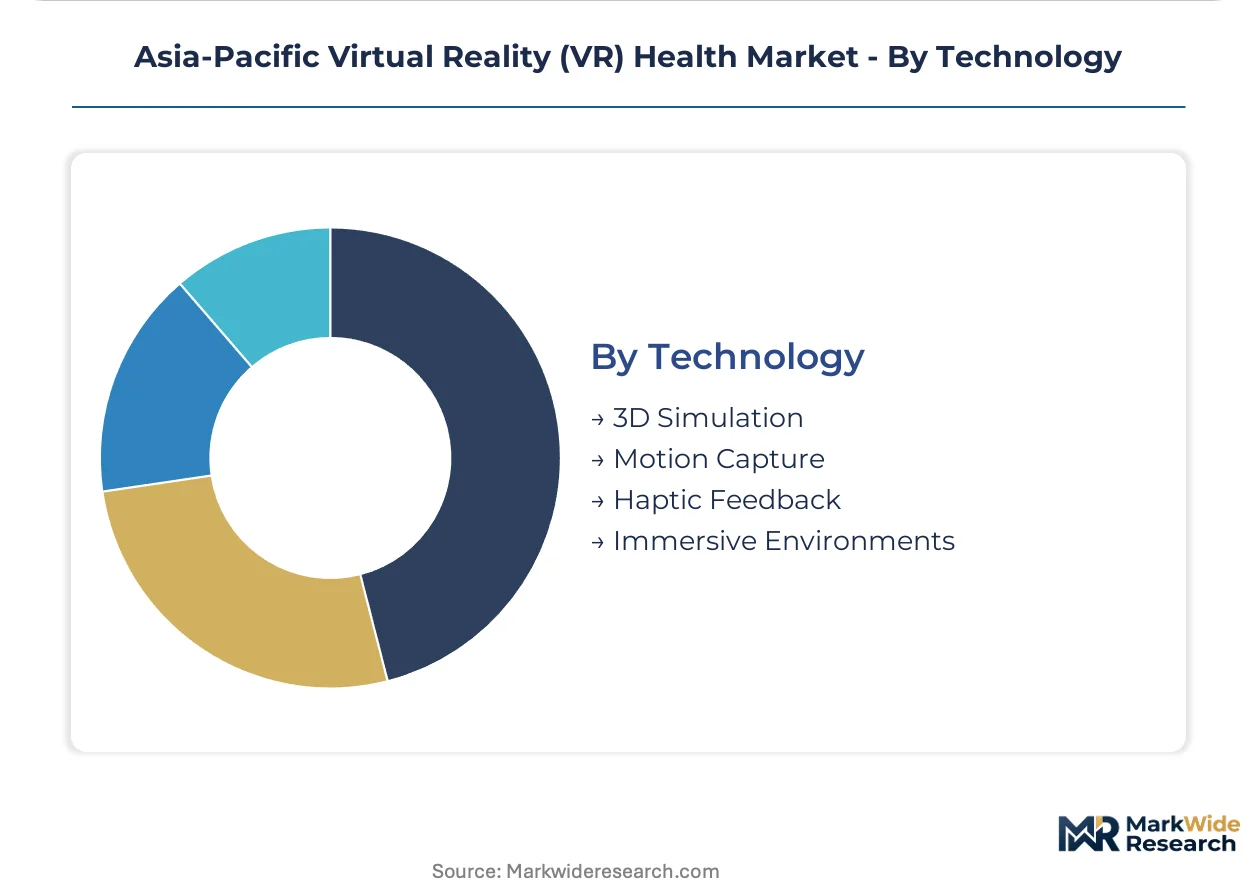
Technology:
Technology segmentation reflects the underlying sensor and compute architectures determining motion-to-photon latency performance.
- Immersive Environments:Fully rendered three-dimensional clinical spaces with six-degrees-of-freedom tracking. South Korean hospital systems in Seoul deploy these for surgical rehearsal under MFDS electromagnetic-safety certifications. Sub-20 millisecond latency requirements exclude commodity chip suppliers.
- 3D Simulation:Volumetric visualization of anatomical structures and pathological states. Chinese radiology departments in Shenzhen integrate NMPA-classified diagnostic tools with AI pathology detection. Pre-market clinical validation mandates reshape domestic product development cycles.
- Motion Capture:Optical and inertial tracking of patient movement for rehabilitation metrics.
- Haptic Feedback:Force-feedback gloves and exoskeletons for surgical training fidelity.
Clinical validation concentrates in Immersive Environments. Integration momentum is strongest in 3D Simulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's tier-one hospital networks anchor therapeutic VR procurement across the region, with China's NMPA software-as-medical-device rules compressing approval timelines for immersive diagnostic platforms. Japan's PMDA electromagnetic-safety certifications and Australia's TGA aged-care reimbursement schedules create parallel institutional demand corridors.
China
Beijing and Shenzhen medical technology clusters drive hardware manufacturing scale for surgical training systems. NMPA's pre-market clinical validation mandates for AI-integrated diagnostic VR tools force partnerships between domestic OEMs and teaching hospitals. Guangdong province's 200-plus bed facilities standardize VR infrastructure across psychiatry and rehabilitation departments.
Japan
Tokyo and Osaka palliative care networks deploy PMDA-cleared therapeutic protocols for chronic pain intervention. METI's streamlined electromagnetic-safety certification accelerates hospital procurement cycles for head-worn devices. Kansai region medical systems lead opioid-alternative reimbursement adoption for immersive therapy sessions.
Australia
Victoria and Queensland aged-care facilities negotiate bundled hardware-software-service contracts for rehabilitation VR. TGA's inclusion of immersive therapy in national funding schedules unlocks institutional purchasing power. Sydney and Melbourne hospital systems integrate distraction-based pain management into workers compensation coverage.
India
Mumbai and Delhi metro corridor clinics pilot surgical training modules under CDSCO's streamlined software-as-medical-device pathways. The regulator's classification framework redirects capital toward regulatory-first product architectures. Bangalore's medical technology startups target tier-two hospital networks outside major metros for first-mover expansion.
South Korea
Seoul hospital systems deploy MFDS-certified immersive environments for surgical rehearsal training. The regulator's biocompatibility standards shape product development timelines for regional manufacturers. Busan-Ulsan medical clusters concentrate high-resolution micro-OLED supply for therapeutic headset production.
Asia-Pacific Virtual Reality (VR) Health Market Competitive Environment
Strategic partnerships dominate the current landscape as hardware OEMs align with cloud infrastructure providers and teaching hospitals. The market exhibits tiered concentration with multinational technology conglomerates controlling display supply and cloud backbones, while specialized medical device manufacturers occupy mid-tier positions. Three archetypes define competitive positioning: cloud-anchored platform providers, integrated semiconductor-to-display manufacturers, and surgical simulation specialists. Technology licensing agreements and backward integration into custom ASIC design represent the dominant competitive moves.
Within the cloud-anchored tier, Microsoft Corporation exemplifies platform-scale positioning through Azure backbone integration. Sony Corporation and Samsung Electronics occupy the integrated manufacturing tier, with the former representing high-resolution display supply dominance and the latter exemplifying semiconductor-to-display vertical control. These three entities anchor the competitive structure without constraining maneuvering room for specialized entrants.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Koninklijke Philips N.V. |
| Sony Corporation |
| CAE Healthcare Inc. |
| Siemens Healthineers |
| Samsung Electronics |
| Google LLC |
| GE HealthCare |
| HTC Corporation |
| Others |
Value Chain & Pricing Dynamics
Optical engineering talent concentration in Shenzhen and Taipei feeds directly into tiered hardware pricing, with labor-cost differentials between these clusters and emerging Vietnamese assembly bases widening spreads between FDA-certified premium headsets and economy-grade training units.
Pricing Analysis
Input-cost pass-through from micro-OLED display panels and custom motion-tracking ASICs dominates pricing formation, with South Korean and Japanese foundry rates transmitting directly into hardware bill-of-materials. Price differentiation rests on NMPA certification grade and bundled software service levels, with PMDA-cleared therapeutic systems commanding substantial premiums over training-only configurations. Cost compression in economy-tier surgical simulation units is intensifying as domestic Chinese manufacturers scale polymer optics production. Hospital procurement committees exhibit lowest price sensitivity for pain management applications where reimbursement frameworks guarantee coverage, while tier-two clinic networks in India drive hardest bargain on hardware-only purchases.
Supply Chain Analysis
Reverse-logistics flows for head-mounted displays concentrate refurbishment operations in Dongguan and Singapore, with sanitized headset redeployment to aged-care facilities creating secondary revenue streams for platform operators. Manufacturing gravity centers on China, South Korea, and Japan, with high-resolution micro-OLED supply drawing from Busan-Ulsan foundries and precision optics sourcing from Shenzhen clusters. Single-source vulnerability in specialized ASIC design creates exposure to 40-week foundry queues. Distribution runs through hospital procurement departments and GPO contracts in tier-one medical networks, with direct-to-clinic channels gaining share in Indian metro corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific VR Health has transitioned into a late-cycle quality phase where clinical validation depth and regulatory certification breadth now determine competitive survival, with hospital procurement committees prioritizing NMPA and PMDA clearance over raw hardware specifications.
For Market Incumbents: Deepen backward integration into custom motion-tracking ASIC design to secure foundry allocation priority against fabless entrants, while expanding CDSCO regulatory affairs teams in Mumbai and Delhi to defend against streamlined approval pathway exploitation by domestic challengers. For New Entrants and Emerging Players: The mid-tier pricing gap between Sony-supplied premium headsets and unbranded Chinese surgical trainers opens viable positioning for MFDS-certified specialty manufacturers targeting Seoul and Busan hospital systems with outcome-linked subscription models. For Investors and Strategic Acquirers: Cloud infrastructure providers are the most active acquirer in this space, seeking hospital system anchoring through Azure-integrated platform deployments; long-term viability favors ASIC-design capabilities and regulatory-first product architectures over pure content plays, with NMPA software-as-medical-device trial partnerships serving as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Software-as-Medical-Device Submission | Pre-market clinical validation partnerships with Beijing teaching hospitals unlock tier-one procurement channels. |
| Polymer Optics Manufacturing Scale-Up | Shenzhen and Taipei production expansion halves per-unit weight for extended clinical sessions. |
| Azure Cloud Backbone Integration | Hospital system IT departments prioritize Microsoft-anchored enterprise deployments for EHR compatibility. |
| PMDA Electromagnetic-Safety Certification | Tokyo and Osaka palliative care networks mandate cleared protocols for chronic pain intervention. |
| TGA Reimbursement Strategy Development | Victoria and Queensland aged-care funding inclusion drives bundled hardware-software contract adoption. |
Study Parameters
Direct dialogue with hospital purchasing committee members, biomedical engineers configuring VR systems, GPO contracts managers, and CDSCO regulatory consultants grounded qualitative findings, cross-referenced against NMPA device registration databases, PMDA approval summaries, hospital procurement tender records, and CMS-equivalent reimbursement schedules across Asia-Pacific jurisdictions; bottom-up installation counts and top-down healthcare IT spending allocations were triangulated for segment sizing.
Segmented outputs across hardware, software, and content categories were generated over the projection horizon, with therapeutic, pain management, rehabilitation, and training applications modeled separately by end-user type; CAGRs were derived from installed base growth rates and average selling price trajectories, with motion-to-photon latency specifications and biocompatibility certification timelines serving as hardware demand shapers.
Caveats apply where NMPA software-as-medical-device rule revisions or cross-border data-localization mandate expansions could materially shift the outlook; practitioners should monitor CDSCO classification framework updates and Australian TGA aged-care funding schedule amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Florida Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Automotive Market
Virtual Reality (VR) and Augmented Reality (AR)
India Desktop Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
Commercial Augmented Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Mirror Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Firefighter Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Location Based VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mixed Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
VR HMD Shipment Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Glasses Market