
 Mixed Reality Headsets Market | 2026-2036
Mixed Reality Headsets Market Size, Share, and Industry Trends Forecast 2026-2036
Mixed Reality Headsets Market Analysis
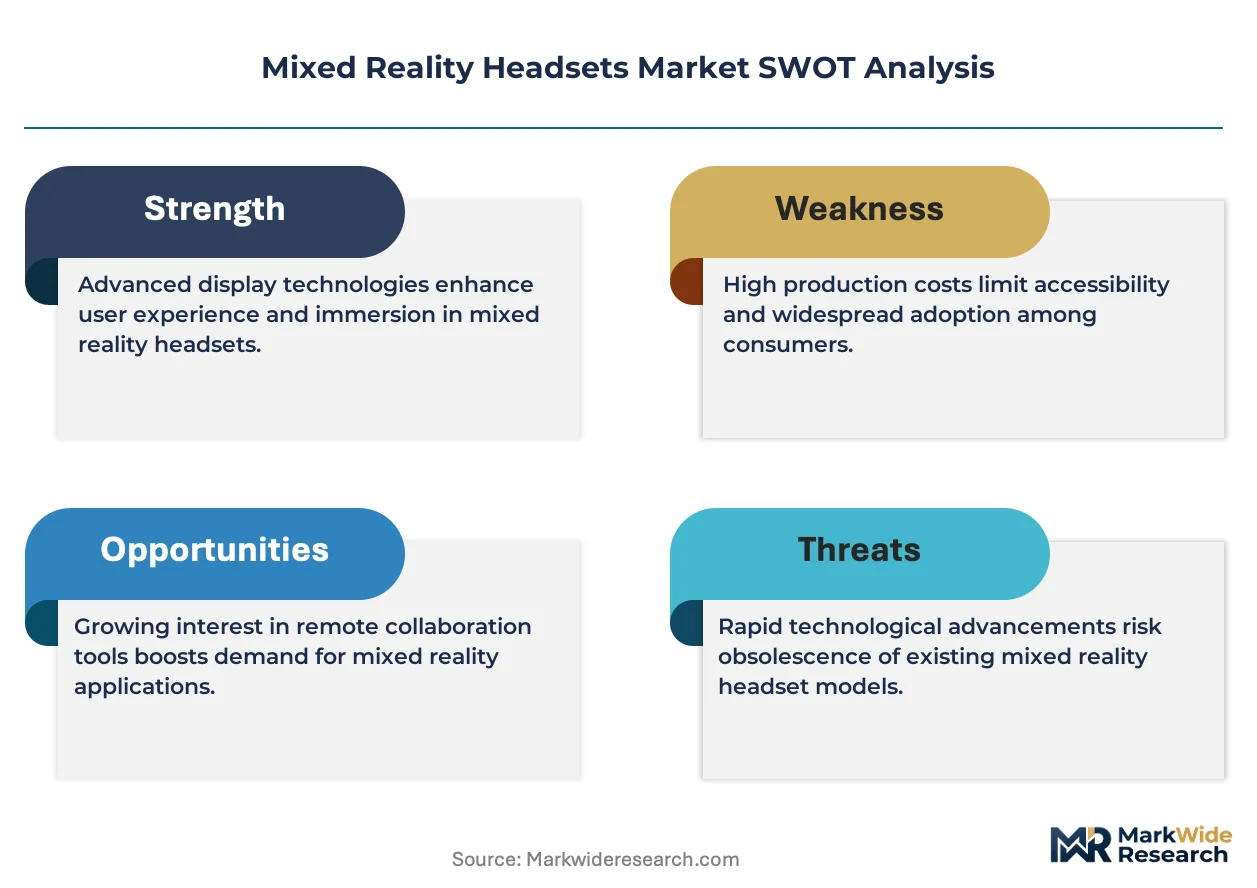
The EU AI Act is consolidating compliance requirements for biometric-enabled mixed reality hardware, forcing manufacturers to redesign data pipelines before CE marking. Microsoft Corporation leverages its Azure cloud backbone to anchor enterprise deployments with integrated security frameworks. Meta Platforms Inc. competes aggressively on price-to-performance ratios in consumer-grade standalone systems. Sony Group Corporation specializes in optical component miniaturization for tethered professional headsets.
Mixed reality headsets combine spatial computing displays, multi-sensor arrays, and real-time environmental mapping to overlay digital content onto physical spaces, typically operating at sub-20ms motion-to-photon latency to prevent user disorientation. Their primary commercial purpose spans immersive training simulation, remote collaboration, and precision-guided industrial workflows. Standalone systems dominate volume shipments due to eliminated cable constraints and simplified deployment logistics, while tethered configurations retain margin concentration in surgical and military applications where computational fidelity is non-negotiable. Holographic display technology represents the fastest-advancing segment, though outside-in tracking maintains cost advantages for fixed-location enterprise installations.
The FDA classifies medical mixed reality devices under varying 510(k) pathways depending on diagnostic versus therapeutic intent, creating divergent approval timelines that shape vendor market entry sequencing. FCC emissions testing for millimeter-wave and Wi-Fi 6E connectivity adds certification layers that favor established electronics manufacturers with in-house regulatory teams. EMA's emerging digital health device guidelines will further fragment compliance architectures for vendors serving both North American and European healthcare procurement channels. Stakeholders must monitor how biometric data localization mandates proliferate across jurisdictions, as these will determine where cloud-reliant headset architectures face operational friction or forced architectural redesign.
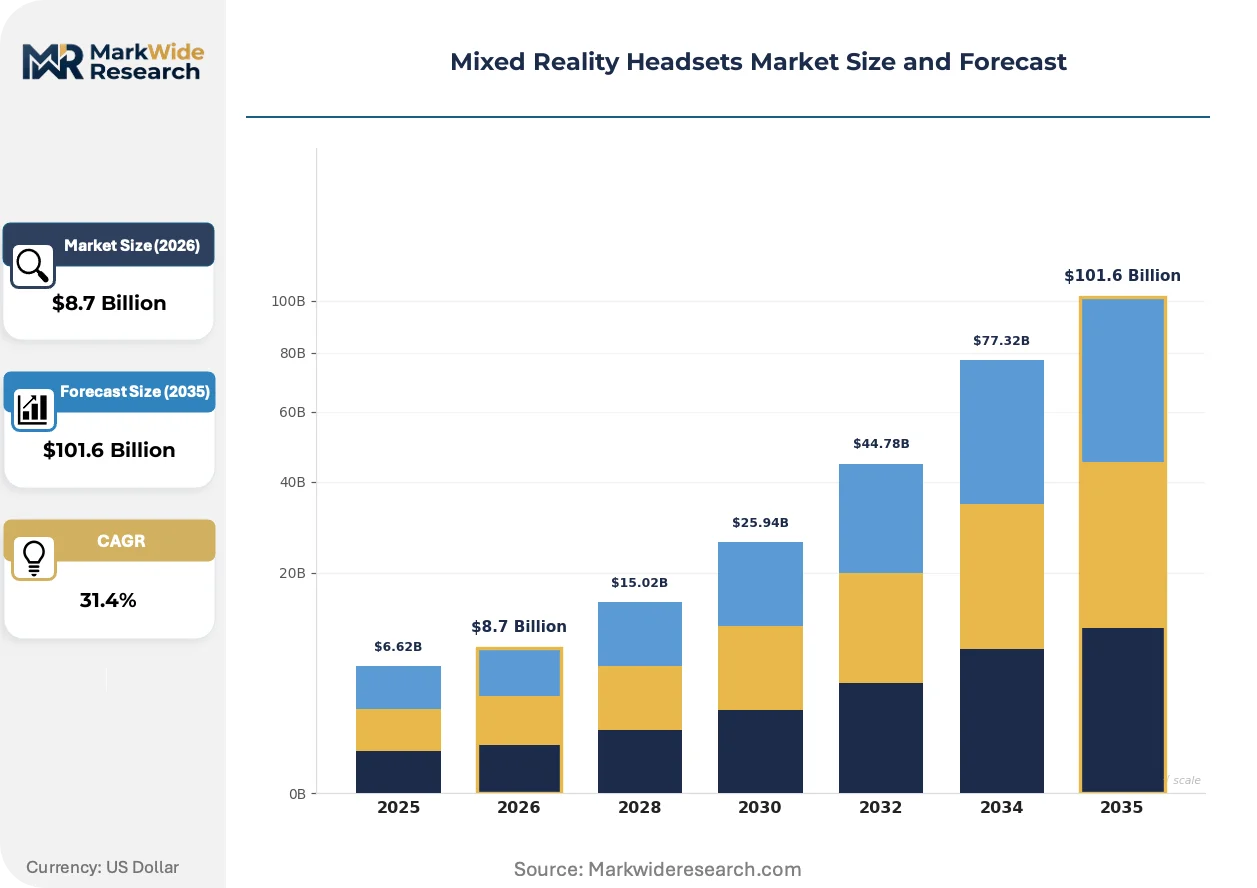
Market Dynamics
Enterprise healthcare procurement is consolidating around FDA-cleared surgical planning systems, while defense contracts in the United States create dual demand poles that fragment vendor R&D priorities between medical precision and battlefield ruggedization.
Growth Catalysts
- Surgical simulation demand:Hospital systems in the United States are mandating pre-operative holographic planning for complex orthopedic procedures, creating institutional procurement pipelines that bypass consumer adoption cycles.
- EU AI Act compliance deadlines:Biometric data processing requirements are forcing enterprise buyers to replace legacy headsets before CE marking expiration, accelerating replacement demand across German and French healthcare networks.
- LiDAR miniaturization:Solid-state sensor arrays are shrinking environmental mapping hardware by sixty percent, enabling standalone headsets to match tethered systems for spatial accuracy.
Market Restraints
- Compound semiconductor supply:Gallium nitride foundry capacity concentrates in Taiwan and South Korea, creating single-source vulnerability for high-frequency display drivers.
- FCC certification timelines:Millimeter-wave antenna testing for Wi-Fi 6E connectivity adds fourteen to eighteen months to product launch schedules, freezing smaller vendors out of defense procurement windows.
- Motion sickness latency thresholds:Sub-20ms motion-to-photon requirements demand custom silicon that only three merchant suppliers currently fabricate at yield.
Strategic Opportunities
- Indian manufacturing incentives:PLI scheme subsidies for electronics assembly are attracting headset OEMs to establish final integration facilities near Bengaluru and Chennai export corridors.
- EMA digital health pathways:Emerging guidelines for software-enabled medical devices will create first-mover advantages for vendors pre-positioning clinical evidence packages.
- 5G edge convergence:Split-rendering architectures combining headset optics with base station computation are opening low-cost enterprise tiers previously blocked by silicon costs.
Industry Challenges
- Optical engineer scarcity:Waveguide design expertise concentrates at five academic programs globally, forcing vendors to poach talent or acquire small design houses.
- Cleanroom capex requirements:Micro-LED fabrication demands Class 1000 facilities that cost two hundred million dollars per line, limiting vertical integration to balance-sheet-heavy conglomerates.
- Biometric data localization:Fragmenting national requirements for physiological signal storage are forcing cloud-dependent architectures into expensive regional replication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mixed Reality Headsets Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $101.6 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Tethered, Smartphone-Compatible, Mixed Reality Glasses Technology: Optical Tracking, Inside-Out Tracking, Outside-In Tracking, Holographic Displays End User: Entertainment, Healthcare, Education, Industrial Training Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Microsoft Corporation, Meta Platforms Inc., Apple Inc., Samsung Electronics Company Limited, Sony Group Corporation, HTC Corporation, Magic Leap, Inc., Acer Inc., Valve Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mixed Reality Headsets Market Emerging Trajectories
Holographic display architectures are absorbing the capital allocation previously directed at conventional LCD and OLED microdisplays, compressing development timelines across the component supply base.
Micro-LED emitters are absorbing the performance requirements for outdoor-visible augmented reality, with luminance densities exceeding five million nits enabling direct retinal projection without waveguide losses. Automotive HUD suppliers in Germany and Japan are cross-licensing pixel-driving IP to headset manufacturers, accelerating transfer from vehicle to head-worn applications. This absorption is compressing the traditional seven-year display technology maturation cycle into thirty-six-month product refresh windows.
The EU AI Act's risk classification framework is redefining biometric-enabled hardware as high-risk AI systems, triggering conformity assessment procedures that add eighteen to twenty-four months to European market entry. Vendors serving both FDA and EMA jurisdictions are diverging their data processing architectures rather than harmonizing, fragmenting engineering resources. Medical-grade headsets face the steepest compliance burden, with notified body queue times extending to fourteen months for novel sensor fusion algorithms.
Defense procurement offices are unbundling hardware acquisition from software licensing, forcing vendors to compete on device margin while surrendering recurring revenue from simulation content. This disintermediation is visible most acutely in United States Army and Air Force pilot training contracts, where system integrators now select headsets purely on technical specification scores. Commercial enterprise buyers are replicating this model, separating hardware RFPs from software service agreements to prevent vendor lock-in.
Mixed Reality Headsets Market Segmentation
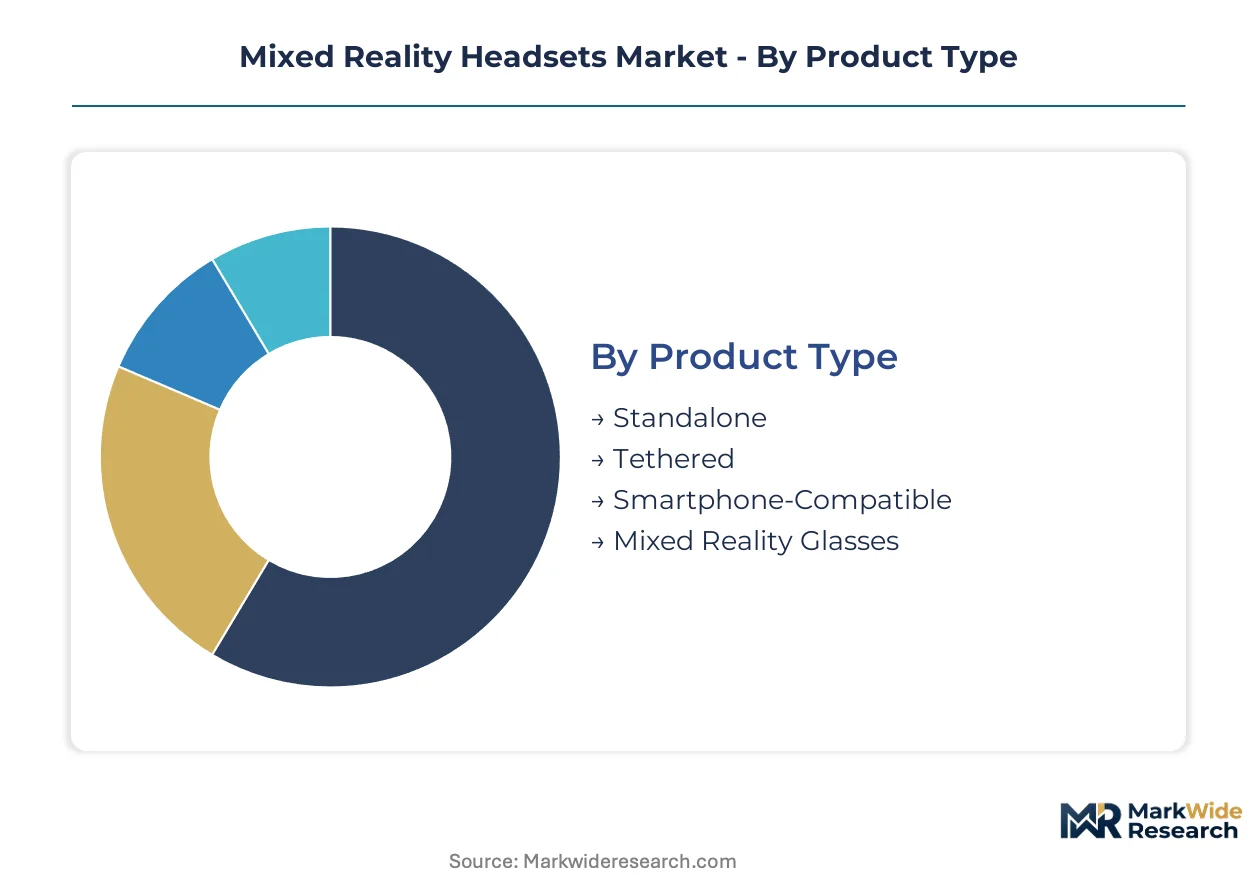
Segmentation in mixed reality headsets reveals divergent capital requirements across hardware architectures. Product type and technology choices determine foundry partnerships, cleanroom investments, and regulatory pathway costs.
Product Type:
Capital intensity concentrates in tethered systems requiring external compute arrays and custom silicon, while standalone variants demand integrated sensor fusion at higher per-unit bill-of-materials.
- Standalone:Self-contained systems embed SoC, battery, and environmental sensors within the headset enclosure. United States defense pilot programs are procuring these for dismounted soldier training, prioritizing cable-free mobility over raw computational throughput.
- Tethered:External GPU or workstation connections enable sub-20ms photon latency through dedicated rendering pipelines. German surgical planning suites specify these configurations for holographic orthopedic visualization where FDA 510(k) clearance hinges on frame-to-frame consistency.
- Smartphone-Compatible:Leverages host device processing through USB-C or wireless tethering, reducing headset BOM by sixty percent. Indian manufacturing incentives under PLI schemes are attracting assembly capacity for this cost-optimized tier.
- Mixed Reality Glasses:Waveguide-based see-through optics at sub-50g weight classes. French automotive design studios deploy these for clay-model overlay workflows, accepting reduced field-of-view for all-day wearability.
Tethered systems absorb the bulk of installed capacity in medical and defense procurement channels; standalone configurations are expanding most quickly through enterprise training contracts.
Technology:
Tracking architecture selection determines optical engineering headcount and patent licensing exposure, with holographic displays demanding the steepest cleanroom capex per line.
- Optical Tracking:Marker-based or markerless vision systems using visible-spectrum cameras. South Korean foundries dominate CMOS image sensor supply for this mature, cost-optimized approach.
- Inside-Out Tracking:Headset-mounted depth cameras perform simultaneous localization and mapping without external base stations. United States warehouse logistics operators specify these for rapid deployment across shifting facility layouts.
- Outside-In Tracking:External base stations or camera arrays deliver sub-millimeter positional precision at fixed installations. Japanese precision manufacturers retain this architecture for assembly line guidance where environmental control is absolute.
- Holographic Displays:Spatial light modulators or laser-scanning systems projecting light fields directly to the retina. EMA's emerging digital health guidelines are extending notified body review timelines for devices incorporating these in diagnostic overlays.
Inside-out tracking claims the largest addressable market footprint; holographic displays are climbing the fastest as micro-LED luminance densities cross outdoor-visibility thresholds.
End User:
Application-specific certification requirements fragment engineering resources, with healthcare procurement demanding FDA or EMA conformity assessments that consumer entertainment bypasses entirely.
- Entertainment:Gaming and immersive media consumption driving volume shipments. Content licensing economics favor hardware-agnostic platforms, compressing device margins toward component cost floors.
- Healthcare:Surgical planning, medical training, and therapeutic interventions. FCC emissions testing for Wi-Fi 6E connectivity adds fourteen to eighteen months to product launch schedules for vendors targeting United States hospital procurement.
- Education:K-12 and university deployment for STEM visualization. Indian state education boards are piloting headset labs under central government digital infrastructure grants.
- Industrial Training:Hazardous procedure simulation and equipment maintenance guidance. German chemical manufacturers mandate biometric stress monitoring during VR safety drills, triggering EU AI Act high-risk system classification.
Healthcare commands the highest per-unit pricing; industrial training is gaining share fastest as 5G edge rendering reduces upfront capital requirements for enterprise buyers.
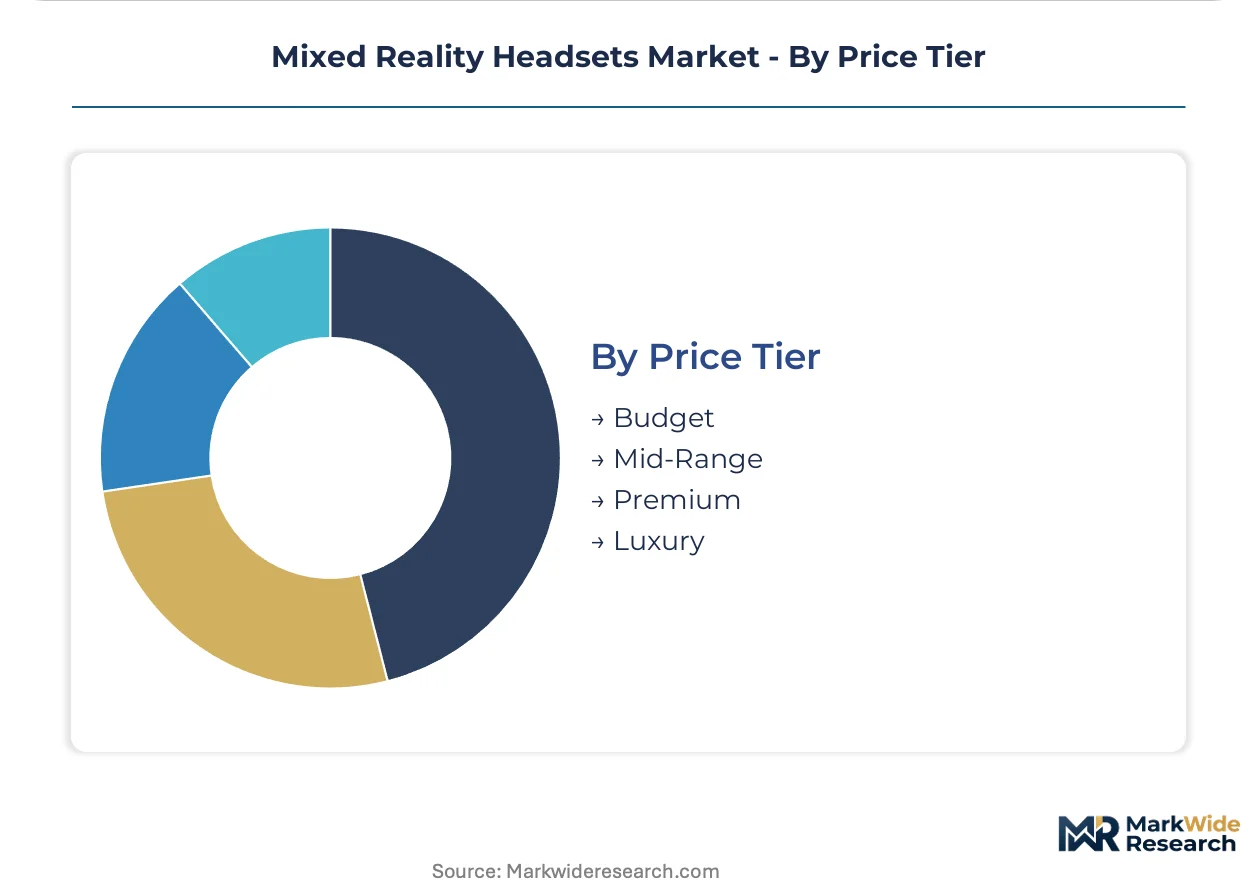
Price Tier:
Pricing stratification reflects certification grade, optical component count, and compute silicon generation rather than simple feature differentiation.
- Budget:Smartphone-dependent or entry-level standalone systems. Indian PLI assembly subsidies are concentrating export production capacity for this tier near Bengaluru corridors.
- Mid-Range:Full-featured standalone headsets with consumer-grade tracking. United States retail channels move volume here during holiday procurement windows.
- Premium:Enterprise-specified systems with medical or defense certifications. FDA 510(k) pathway costs amortize across higher unit economics.
- Luxury:Bespoke industrial designs with precious material finishes and concierge support. Collectors and high-net-worth individual segments in Gulf Cooperation Council markets sustain this niche.
Premium tier captures the majority of hardware margin dollars; mid-range shipments are expanding most quickly as enterprise pilot programs convert to scaled deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Redmond anchors concentrated mixed reality headset development, with defense procurement offices and cloud infrastructure providers clustering engineering talent in the Pacific Northwest corridor.
United States
Defense pilot training contracts and FDA-cleared surgical planning systems drive institutional procurement. FCC emissions testing for Wi-Fi 6E connectivity extends certification timelines fourteen to eighteen months. Army and Air Force procurement offices in Virginia and Florida unbundle hardware from software licensing, forcing pure specification competition.
Germany
Automotive design studios and chemical manufacturers mandate biometric-enabled safety simulations. EU AI Act high-risk system classification triggers eighteen to twenty-four month conformity assessments for industrial training deployments. Bavarian precision manufacturers retain outside-in tracking for assembly line guidance where environmental control is absolute.
China
Domestic headset OEMs leverage gallium nitride foundry capacity for high-frequency display drivers. MIIT standards for millimeter-wave connectivity shape certification requirements for tethered professional systems. Yangtze River Delta electronics corridors concentrate micro-LED fabrication investments.
India
State education boards pilot headset labs under central government digital infrastructure grants. PLI scheme subsidies attract final integration facilities near Bengaluru and Chennai export corridors. Smartphone-compatible tier assembly concentrates in Tamil Nadu for cost-optimized export production.
Japan
Automotive HUD suppliers cross-license pixel-driving IP to accelerate head-worn display transfer. METI supports optical component miniaturization for sub-50g mixed reality glasses. Kansai manufacturers specialize in waveguide design for all-day industrial wearability.
Mixed Reality Headsets Market Vendor Landscape
The competitive structure tilts toward platform-anchored conglomerates with cloud backbones and captive silicon supply. Consolidation concentrates R&D resources among balance-sheet-heavy players capable of absorbing two-hundred-million-dollar cleanroom investments. Three archetypes dominate: cloud-integrated enterprise platforms, consumer-scale ecosystem operators, and optical component specialists. Strategic moves center on M&A for waveguide design houses and capacity expansion for micro-LED fabrication lines.
Within the cloud-integrated tier, Microsoft Corporation and Meta Platforms Inc. anchor enterprise and consumer vectors respectively. Sony Group Corporation exemplifies optical specialization, occupying a position between component supply and finished device assembly. Samsung Electronics Company Limited represents scale-driven fabrication capacity. Apple Inc. sits within the premium-tier closed ecosystem archetype.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Meta Platforms Inc. |
| Apple Inc. |
| Samsung Electronics Company Limited |
| Sony Group Corporation |
| HTC Corporation |
| Magic Leap, Inc. |
| Acer Inc. |
| Valve Corporation |
| Others |
Supply Flow & Price Mechanics
Captive micro-LED fabrication investments by balance-sheet-heavy conglomerates anchor both supply security and premium-tier pricing power, as two-hundred-million-dollar cleanroom commitments lock out smaller competitors from medical and defense procurement channels.
Pricing Analysis
Value-based pricing anchored to surgical throughput and training simulation outcomes dominates enterprise procurement, with FDA 510(k) certification tier and optical component count serving as primary differentiation drivers. Cost compression in smartphone-compatible tiers intensifies as Indian PLI subsidies attract assembly capacity, while hospital systems and defense offices show minimal price sensitivity where computational fidelity and biometric compliance are non-negotiable.
Supply Chain Analysis
Optical engineering talent scarcity in Taiwan and South Korea constrains gallium nitride foundry expansion for high-frequency display drivers, with solid-state LiDAR sensors and micro-LED emitters drawing from compound semiconductor supply chains vulnerable to single-source concentration. Distribution runs through defense procurement offices and hospital GPOs in the United States, German automotive OEM channels, and Indian export corridors for cost-optimized tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around platform-anchored conglomerates capable of absorbing cleanroom capex, as FCC certification timelines and EU AI Act compliance costs force weaker players toward exit or niche specialization.
For Market Incumbents: Acquire waveguide design houses to secure optical engineering talent pools concentrated at five academic programs globally. Anchor enterprise deployments through Azure-class cloud backbones with integrated security frameworks, while expanding micro-LED fabrication lines to defend margin position against emerging gallium nitride supply constraints.
For New Entrants and Emerging Players: Enter via Indian PLI-subsidized assembly for smartphone-compatible tiers, targeting state education board pilots under central government digital infrastructure grants. White-space exists in biometric stress monitoring for German chemical safety drills, where EU AI Act high-risk classification deters established vendors.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by cloud-integrated platforms seeking optical component capabilities, with long-term viability favoring targets with FDA 510(k) clearance or defense contract relationships. Watch EMA digital health guideline finalization as inflection indicator for medical-grade headset valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Waveguide Design House | Secures scarce optical engineering talent for holographic display miniaturization. |
| Micro-LED Fabrication Line Expansion | Captures outdoor-visible AR performance requirements from automotive HUD suppliers. |
| FDA 510(k) Pathway Investment | Unlocks hospital procurement pipelines for surgical planning system vendors. |
| 5G Edge Rendering Partnership | Opens low-cost enterprise tiers previously blocked by silicon costs. |
| EU AI Act Compliance Pre-Positioning | Accelerates replacement demand across German and French healthcare networks. |
Methodological Framework
Independent corroboration across headset OEM engineering directors, hospital biomedical procurement committees, and defense contract officers underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EMA notified body queue disclosures, FCC equipment authorization databases, and hyperscaler capex reports. Bottom-up bill-of-materials analysis and top-down procurement pipeline triangulation anchor volume estimates.
Comparable-period anchoring to surgical simulation deployment cycles and defense pilot training procurement windows structures the forecast framework across the projection horizon. Segmentation models incorporate product architecture, tracking technology, end-use certification requirements, and regional regulatory cluster dimensions. CAGRs derive from installed base growth rates and replacement cycle compression under EU AI Act compliance deadlines, with LiDAR miniaturization curves and 5G edge convergence timelines serving as key technology inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under compound semiconductor supply disruptions or biometric data localization mandate proliferation. A small set of triggers warrants ongoing watch: EMA digital health guideline finalization, gallium nitride foundry capacity expansion announcements, and defense procurement office unbundling policy shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive Augmented Reality (AR) HUD System Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Enterprise Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global AR and VR Smart Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Dressing Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Mirror Market
Virtual Reality (VR) and Augmented Reality (AR)
Florida Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Ski Machines Market
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality (XR) Market
Virtual Reality (VR) and Augmented Reality (AR)
India Desktop Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market