
 Global AR and VR Smart Glasses Market | 2026-2036
Global AR and VR Smart Glasses Market Size, Share, and Industry Trends Forecast 2026-2036
Global AR and VR Smart Glasses Market Foresight
Enterprise buyer concentration is shifting from fragmented pilot programs toward multi-year fleet deployments by manufacturing conglomerates. Meta sustains technology leadership through its Reality Labs division's heavy R&D allocation toward consumer-grade spatial computing. Microsoft Corporation anchors commercial traction with its HoloLens industrial applications across aerospace and healthcare workflows. Vuzix specializes in purpose-built enterprise glasses for logistics and field service technicians, competing on durability and thermal management rather than entertainment features.
AR and VR smart glasses are wearable display systems integrating micro-displays, optical waveguides or projection engines, sensors, and compute modules to overlay or immerse users in digital visual content. Waveguide-based augmented reality glasses achieve sub-ten-millimeter optical thickness while maintaining forty-degree-plus fields of view, enabling all-day industrial wear. Optical see-through glasses capture the dominant share of enterprise spending due to their compatibility with safety regulations and existing facility lighting. Micro-LED technology represents the fastest-growing segment as emitters shrink below ten microns, enabling higher luminance at reduced power draw for outdoor-readable displays.
FCC equipment authorization requirements in the United States govern radio frequency emissions from wireless-connected glasses, while the EU AI Act imposes conformity obligations on devices deploying biometric analysis such as eye tracking. REACH chemical restrictions affect adhesive and coating selections in European-sold headsets, nudging supply chains toward halogen-free flame retardants. Stakeholders must monitor how FDA software-as-medical-device rulings reshape clinical AR applications and whether China's MIIT accelerates domestic GB standards for near-eye display safety.
Market Dynamics
Defense procurement agencies across NATO member states are consolidating mixed reality training contracts into multi-year frameworks, compressing vendor qualification timelines and favoring suppliers with existing security clearances and waveguide manufacturing capabilities.
Growth Catalysts
- REACH chemical restrictions:European adhesive regulations are accelerating halogen-free flame retardant adoption, creating first-mover advantages for compliant optical component suppliers.
- Automotive engineering workflows:BMW and Siemens deploy AR-guided assembly protocols across German manufacturing plants, validating enterprise-grade durability standards for industrial wearables.
- Micro-LED emitters:Sub-ten-micron emitter scaling enables outdoor-readable luminance at reduced power draw, expanding addressable use cases beyond controlled indoor environments.
Market Restraints
- Waveguide supply concentration:Taiwan and South Korean optical foundries control critical waveguide manufacturing capacity, creating single-source vulnerability for next-generation headset producers.
- FCC equipment authorization:Radio frequency emission testing for wireless-connected glasses adds six-to-nine-month certification delays before US commercial deployment.
- Biometric analysis restrictions:EU AI Act conformity obligations on eye-tracking systems impose documentation burdens that slow feature rollout in European markets.
Strategic Opportunities
- Clinical AR applications:FDA software-as-medical-device rulings are reshaping regulatory pathways for surgical navigation and diagnostic visualization tools.
- Logistics field service:Purpose-built enterprise glasses for warehouse picking and remote technician support remain underpenetrated relative to manufacturing assembly use cases.
- GB standards acceleration:China's MIIT near-eye display safety mandates could create domestic certification advantages for local supply chain participants.
Industry Challenges
- Optical engineering talent scarcity:Waveguide design and micro-display integration expertise concentrates among semiconductor veterans with limited mobility into wearable hardware teams.
- Legacy facility integration:AR-guided protocols require reconfiguration of existing assembly line lighting and safety marking systems, extending pilot-to-production timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global AR and VR Smart Glasses Market |
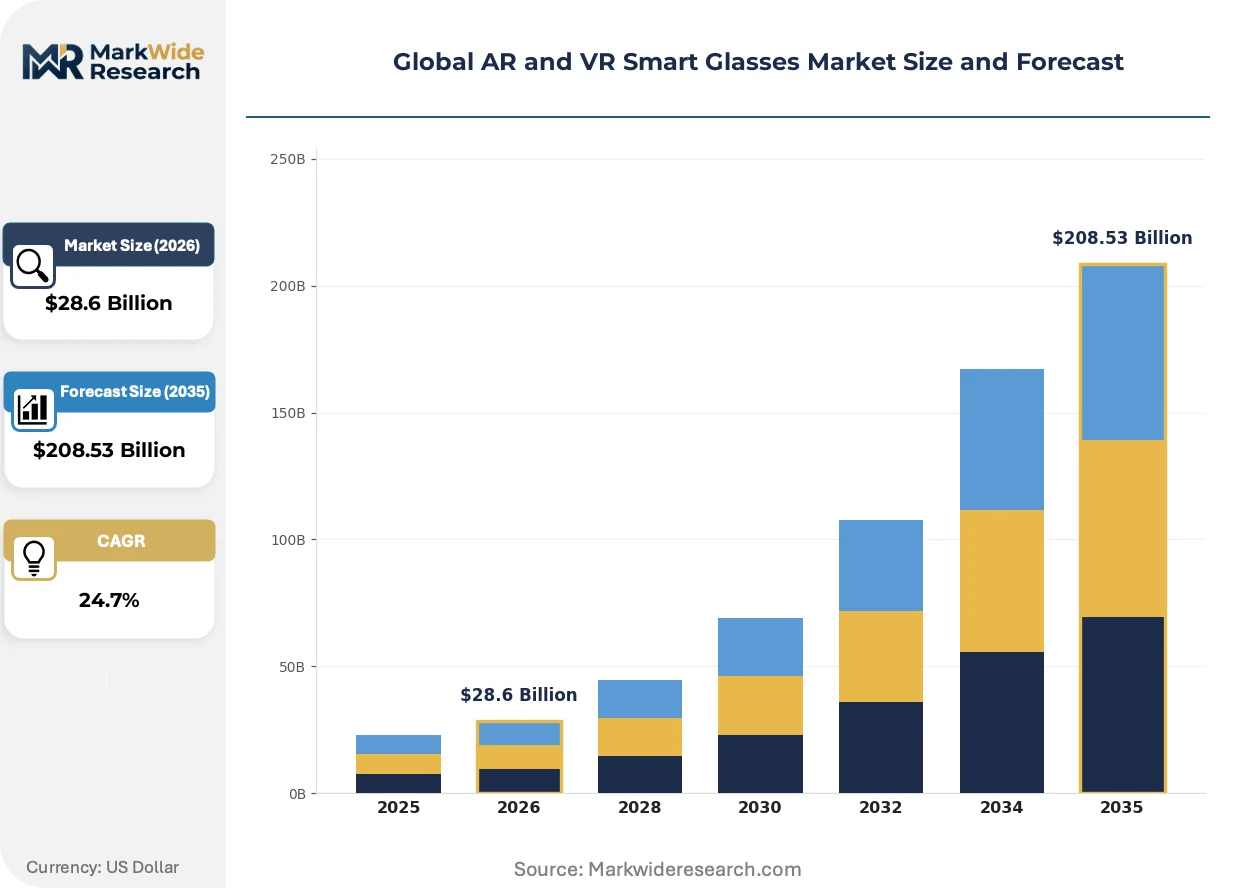
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $208.53 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Augmented Reality Glasses, Virtual Reality Headsets, Mixed Reality Glasses, Optical See-Through Glasses, Video See-Through Glasses Technology: Waveguide, Micro-LED, Projection, Sensor Fusion, Depth Sensing, Eye Tracking Use Case: Industrial Training, Entertainment, Education, Remote Assistance, Military Simulation, Retail Visualization End User: Manufacturing Operators, Gamers, Educators, Technical Consultants, Defense Personnel, Visual Merchandisers |
| Companies Covered | Meta, Seiko Epson Corporation, Microsoft Corporation, Vuzix, EssilorLuxottica, Google Inc., Samsung Group, Apple Inc., XREAL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global AR and VR Smart Glasses Market Shifts & Advancements
Spatial computing hardware is bifurcating into sealed consumer ecosystems and open industrial platforms, with optical architecture choices determining which downstream software and service revenue pools remain accessible to device vendors.
Micro-LED display technology is modularizing around standardized emitter tiles and driver ASICs. Automotive HUD suppliers and AR headset manufacturers now source from overlapping foundry partners, compressing development cycles from thirty-six to eighteen months. This convergence is eroding the historical separation between automotive projection and near-eye display supply chains.
EU AI Act biometric analysis provisions are forcing eye-tracking subsystem redesigns. Vendors must now implement on-device processing for gaze data to avoid cloud transmission restrictions, adding neural inference silicon to previously sensor-only modules. Healthcare and defense applications face the steepest compliance engineering costs.
Enterprise buyers are consolidating vendor relationships around multi-year fleet deployment contracts. Fragmented pilot programs at plant level are giving way to headquarters-negotiated master agreements covering thousands of units across manufacturing networks. This concentration is most advanced in Germany's automotive supplier base, where procurement teams now mandate five-year spare parts availability guarantees.
Global AR and VR Smart Glasses Market Segmentation
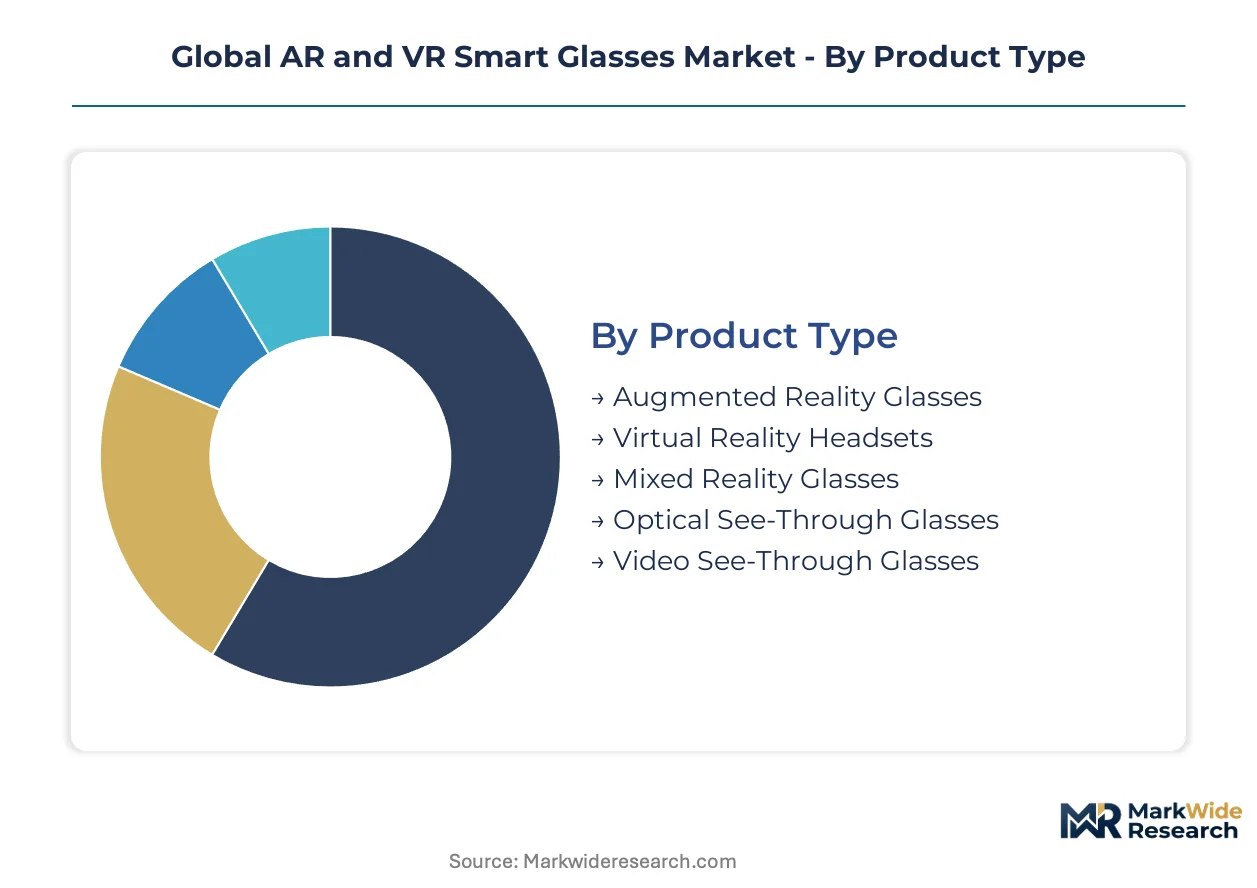
Segmentation in AR and VR smart glasses determines which regulatory pathways manufacturers must navigate. Certification requirements vary sharply across product architectures, with optical see-through designs facing lighter electromagnetic compliance burdens than video-passthrough systems requiring full FCC authorization cycles.
Product Type:
FDA software-as-medical-device rulings apply differentially across these hardware architectures, with surgical navigation systems triggering stricter premarket review than industrial training configurations.
- Augmented Reality Glasses:Waveguide-based optical engines achieve sub-ten-millimeter thickness while maintaining forty-degree-plus fields of view. Demand concentrates in German automotive assembly plants where BMW and Siemens validate all-day industrial wear protocols.
- Virtual Reality Headsets:Sealed immersive displays with integrated compute modules and six-degrees-of-freedom tracking. Gaming applications in South Korea and Japan drive volume procurement through consumer electronics retail channels.
- Mixed Reality Glasses:Spatial computing platforms blending physical and digital environments through depth-sensing arrays. Microsoft HoloLens deployments anchor enterprise traction across aerospace maintenance workflows.
- Optical See-Through Glasses:Direct view of physical environment with overlaid digital content via partially reflective waveguides. Compatibility with OSHA safety regulations accelerates factory floor adoption.
- Video See-Through Glasses:Camera-fed passthrough displays enabling full scene manipulation. FCC equipment authorization requirements add six-to-nine-month certification delays for US commercial deployment.
Leading the category by volume: Virtual Reality Headsets. Expanding most quickly: Optical See-Through Glasses.
Technology:
Component selection determines which foundry relationships dominate bill-of-materials costs, with micro-LED and waveguide manufacturing concentrating in Taiwan and South Korean optical facilities.
- Waveguide:Thin optical elements guiding light from micro-displays to eye with minimal thickness. Taiwan-based foundries control critical manufacturing capacity, creating single-source vulnerability for next-generation headset producers.
- Micro-LED:Sub-ten-micron emitters enabling outdoor-readable luminance at reduced power draw. Automotive HUD suppliers and AR manufacturers now source from overlapping semiconductor partners, compressing development cycles.
- Projection:Micro-projector engines casting images onto retinal or surface targets. Legacy automotive head-up display supply chains provide transferable manufacturing expertise.
- Sensor Fusion:Integration of accelerometer, gyroscope, and magnetometer data for spatial positioning. Required baseline for six-degrees-of-freedom tracking in industrial training applications.
- Depth Sensing:Time-of-flight and structured light modules for environmental mapping. EU AI Act biometric analysis provisions force on-device processing architectures to avoid cloud transmission restrictions.
- Eye Tracking:Infrared camera and illuminator systems measuring gaze direction and pupil dilation. Conformity obligations under European artificial intelligence regulations impose documentation burdens slowing feature rollout.
Dominant by procurement spend: Waveguide. Gaining share fastest: Micro-LED.
Use Case:
Application selection dictates which security clearance frameworks and safety certifications govern deployment, with military simulation contracts requiring NATO facility accreditation.
- Industrial Training:AR-guided assembly protocols and remote expert assistance for manufacturing operators. German automotive supplier base mandates five-year spare parts availability guarantees in procurement contracts.
- Entertainment:Immersive gaming and media consumption experiences. Meta's Reality Labs consumer-grade spatial computing investments sustain technology leadership in this segment.
- Education:Interactive visualization tools for STEM instruction and vocational skill development. Pilot programs fragment across institutional buyers lacking consolidated procurement authority.
- Remote Assistance:Real-time video overlay and annotation for field service technicians. Vuzix purpose-built enterprise glasses compete on durability and thermal management in logistics deployments.
- Military Simulation:Mixed reality combat training and equipment familiarization systems. NATO member states consolidate contracts into multi-year frameworks favoring suppliers with existing security clearances.
- Retail Visualization:Virtual try-on and spatial merchandising applications. Visual merchandiser adoption lags manufacturing use cases due to uncertain return-on-investment metrics.
Highest contract value concentration: Military Simulation. Steepest expansion trajectory: Remote Assistance.
End User:
Buyer type determines pricing tolerance and replacement cycle expectations, with defense procurement agencies accepting premium positioning for security-hardened configurations.
- Manufacturing Operators:Factory floor personnel using AR-guided protocols for assembly and quality inspection. REACH chemical restrictions affect adhesive selections in European-sold headsets, nudging supply chains toward halogen-free flame retardants.
- Gamers:Consumer enthusiasts prioritizing immersive fidelity and content ecosystem breadth. Price sensitivity concentrates demand in mid-tier hardware configurations.
- Educators:Institutional instructors deploying visualization tools for classroom and laboratory instruction. Budget constraints favor lower-cost video see-through alternatives.
- Technical Consultants:Field service engineers requiring remote collaboration capabilities. Purpose-built enterprise glasses from specialized vendors address thermal management requirements in outdoor deployments.
- Defense Personnel:Military operators utilizing simulation and tactical overlay systems. Existing security clearances and waveguide manufacturing capabilities compress vendor qualification timelines.
- Visual Merchandisers:Retail professionals creating virtual product displays and customer experiences. Adoption remains underpenetrated relative to manufacturing assembly applications.
Largest installed base: Manufacturing Operators. Fastest procurement growth: Defense Personnel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement concentrates in German automotive engineering, while defense simulation contracts expand across NATO members. Taiwan and South Korean optical foundries supply critical waveguide components. Regulatory divergence between FDA software rulings and EU AI Act biometric provisions fragments certification pathways.
United States
Defense procurement agencies consolidate mixed reality training contracts into multi-year frameworks. FCC equipment authorization requirements add six-to-nine-month certification delays for wireless-connected glasses. Boston-area aerospace clusters anchor Microsoft HoloLens deployments across maintenance workflows.
Germany
BMW and Siemens validate AR-guided assembly protocols across manufacturing plants. REACH chemical restrictions nudge supply chains toward halogen-free flame retardants in European-sold headsets. Bavarian automotive supplier procurement teams mandate five-year spare parts availability guarantees.
South Korea
Waveguide display manufacturing advances reduce optical component costs for next-generation headsets. Consumer electronics retail channels drive volume procurement of immersive gaming systems. Seoul-based optical foundries control critical capacity for micro-display integration.
China
MIIT near-eye display safety mandates could accelerate domestic GB standards for certification advantages. Yangtze River Delta electronics clusters concentrate micro-LED emitter scaling below ten microns. Local supply chain participants position for regulatory preference in clinical and industrial applications.
Taiwan
Optical foundries dominate waveguide manufacturing capacity for next-generation headset producers. Single-source vulnerability concentrates as Taiwanese facilities supply Meta and Apple supply chains. Hsinchu semiconductor veterans limit mobility into wearable hardware teams, constraining optical engineering talent pools.
Global AR and VR Smart Glasses Market Competitive Landscape
United States producers anchor consumer-grade spatial computing investments; German and French specialists hold industrial certification advantages. The vendor base stratifies into three tiers: sealed consumer ecosystems, open industrial platforms, and defense-hardened configurations. Two strategic archetypes dominate—vertically integrated technology conglomerates and purpose-built enterprise durability specialists. Competitive moves concentrate on multi-year fleet deployment contracts and optical architecture licensing partnerships.
Within the vertically integrated tier, Meta and Microsoft Corporation represent contrasting ecosystem strategies—one sustaining heavy R&D allocation toward consumer-grade hardware, the other anchoring commercial traction through industrial workflow applications. Vuzix occupies a position among purpose-built enterprise specialists, competing on thermal management and durability rather than entertainment features. Seiko Epson Corporation exemplifies the optical component-to-systems integrator archetype, leveraging legacy projection expertise into near-eye display supply chains.
| Leading Market Players |
|---|
| Meta |
| Seiko Epson Corporation |
| Microsoft Corporation |
| Vuzix |
| EssilorLuxottica |
| Google Inc. |
| Samsung Group |
| Apple Inc. |
| XREAL |
| Others |
Supply & Pricing Matrix
Defense procurement agencies across NATO member states anchor the dominant pricing model through multi-year framework contracts that compress vendor qualification timelines and favor security-cleared suppliers with captive waveguide manufacturing. This buyer concentration creates a bifurcated structure where enterprise fleet deployments command premium positioning while consumer volumes compete on manufacturing scale.
Pricing Analysis
Volume-margins split sharply between sealed consumer ecosystems and open industrial platforms. Three-tier pricing structure across premium defense-hardened, standard enterprise-grade, and economy consumer configurations separates certification-bundled offerings from bare hardware. Cost compression in micro-LED emitter sourcing is intensifying because automotive HUD suppliers and AR manufacturers now draw from overlapping foundry partners. Consumer gamers exhibit highest price sensitivity; defense personnel accept premium positioning for security-hardened configurations.
Supply Chain Analysis
Optical engineering talent scarcity in Hsinchu semiconductor clusters constrains workforce availability for waveguide design and micro-display integration teams migrating into wearable hardware. Taiwan and South Korean optical foundries anchor critical manufacturing capacity for next-generation headset producers. Bill-of-materials rests on gallium nitride substrates, precision glass wafers, and neural inference silicon for on-device gaze processing. Single-source vulnerability concentrates as Taiwanese facilities feed Meta and Apple supply chains. Distribution runs through direct enterprise fleet contracts and consumer electronics retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around optical architecture control as REACH chemical restrictions and EU AI Act conformity obligations force weaker component suppliers toward exit or acquisition.
For Market Incumbents: Anchor multi-year fleet deployment contracts through five-year spare parts availability guarantees that German automotive procurement teams now mandate. Deepen backward integration into waveguide manufacturing to offset Taiwan foundry concentration risk. Certify halogen-free flame retardant supply chains ahead of REACH enforcement timelines to capture first-mover positioning in European markets.
For New Entrants and Emerging Players: Micro-LED emitter scaling below ten microns offers a technology-first wedge into outdoor-readable industrial applications where luminance requirements exceed incumbent LCOS capabilities. Logistics field service for warehouse picking and remote technician support remains the most penetrable segment relative to manufacturing assembly saturation. Pursue purpose-built durability certification as the go-to-market angle against consumer-grade crossover competitors.
For Investors and Strategic Acquirers: The window for entry favors optical component specialists with transferable automotive HUD expertise and existing semiconductor foundry relationships. Long-term viability hinges on controlling waveguide design talent pools that concentrate among Hsinchu veterans with limited mobility. Watch FDA software-as-medical-device rulings for surgical navigation applications as the inflection signal for clinical AR valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Waveguide Manufacturing Scale-Up | Taiwanese foundry expansion reduces single-source vulnerability for NATO defense contractors. |
| On-Device Neural Inference Integration | EU AI Act biometric provisions force gaze-data processing silicon into previously sensor-only modules. |
| REACH-Compliant Adhesive Transition | Halogen-free flame retardant certification creates procurement advantages in German automotive supply chains. |
| Multi-Year Fleet Master Agreements | Headquarters-negotiated contracts replace fragmented plant-level pilots across Siemens manufacturing networks. |
| Micro-LED Automotive Crossover Sourcing | Overlapping semiconductor partnerships compress AR headset development cycles from thirty-six to eighteen months. |
Research Methodology
Independent corroboration across optical component procurement leads, defense simulation program officers, and enterprise wearable deployment managers underwrites the qualitative findings in this study. Primary fieldwork engaged waveguide design engineers, logistics field service technicians, and regulatory affairs specialists at FDA and EMA submission levels. Secondary validation drew from FCC equipment authorization filings, EU AI Act conformity documentation, REACH chemical restriction updates, and MIIT near-eye display safety mandates. Bottom-up bill-of-materials modeling triangulates against top-down procurement contract value aggregation.
Comparable-period anchoring references historical waveguide cost curves and micro-LED emitter scaling trajectories across the projection horizon. The analytical framework models segmentation across product architecture, display technology, use case penetration, and end-user procurement authority. CAGRs derive from optical component foundry capacity expansion schedules and enterprise fleet replacement cycle assumptions. Forecast inputs incorporate NATO defense procurement consolidation timelines and German automotive supplier mandate trajectories.
Several conditions sit outside the modeled scope, including unannounced platform ecosystem exclusivity agreements and sudden MIIT GB standard acceleration timelines. Forecasts reflect assumptions about waveguide manufacturing yield improvements and REACH enforcement consistency. Material deviation in FDA software-as-medical-device rulings or Taiwan semiconductor export restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
India Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive AR and VR Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Somatosensory Virtual Fitting Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality for Consumer Market
Virtual Reality (VR) and Augmented Reality (AR)
Consumer Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Tourists Virtual Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual and Augmented Reality in Tourism Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Italy Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
AR in Education Market