
 Asia-Pacific Augmented Reality Market | 2026-2036
Asia-Pacific Augmented Reality Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Augmented Reality Market Analytics
Optical waveguides are recalibrating cost structures across AR headset production as manufacturers shift from bulkier free-space optics to thinner, more efficient light-guide plates. Samsung Electronics Co., Ltd. leverages its semiconductor foundry capabilities to produce compact micro-display backplanes for partner OEMs. Huawei Technologies Co., Ltd. anchors its AR strategy around proprietary spatial computing chips and enterprise software stacks. Sony Group Corporation dominates image sensor supply for depth-sensing cameras used in markerless tracking systems.
Augmented Reality in the Asia-Pacific region overlays computer-generated visual, auditory, or haptic information onto the physical environment through transparent displays or camera-fed screens, typically operating at 60-120 Hz refresh rates with sub-20 millisecond motion-to-photon latency to prevent user disorientation. Gaming applications currently occupy the largest revenue share among consumer segments, though healthcare deployment among surgical navigation and medical training programs registers the fastest trajectory as hospitals in Australia and South Korea validate outcome metrics. Head-Mounted Displays sustain premium pricing due to optical engine complexity, while Smart Glasses compete on weight reduction and all-day battery endurance for industrial enterprise users.
China's MIIT enforces GB standards for electromagnetic compatibility and battery safety in wearable electronics, directly shaping product certification timelines for devices manufactured in Shenzhen and Dongguan export zones. South Korea's MFDS classifies certain AR-guided surgical tools as medical devices, requiring clinical validation before hospital procurement. Japan's METI promotes JIS standards for industrial AR eyewear used in hazardous manufacturing environments. Stakeholders must weigh regulatory divergence across these frameworks when designing unified product platforms for multi-country deployment.
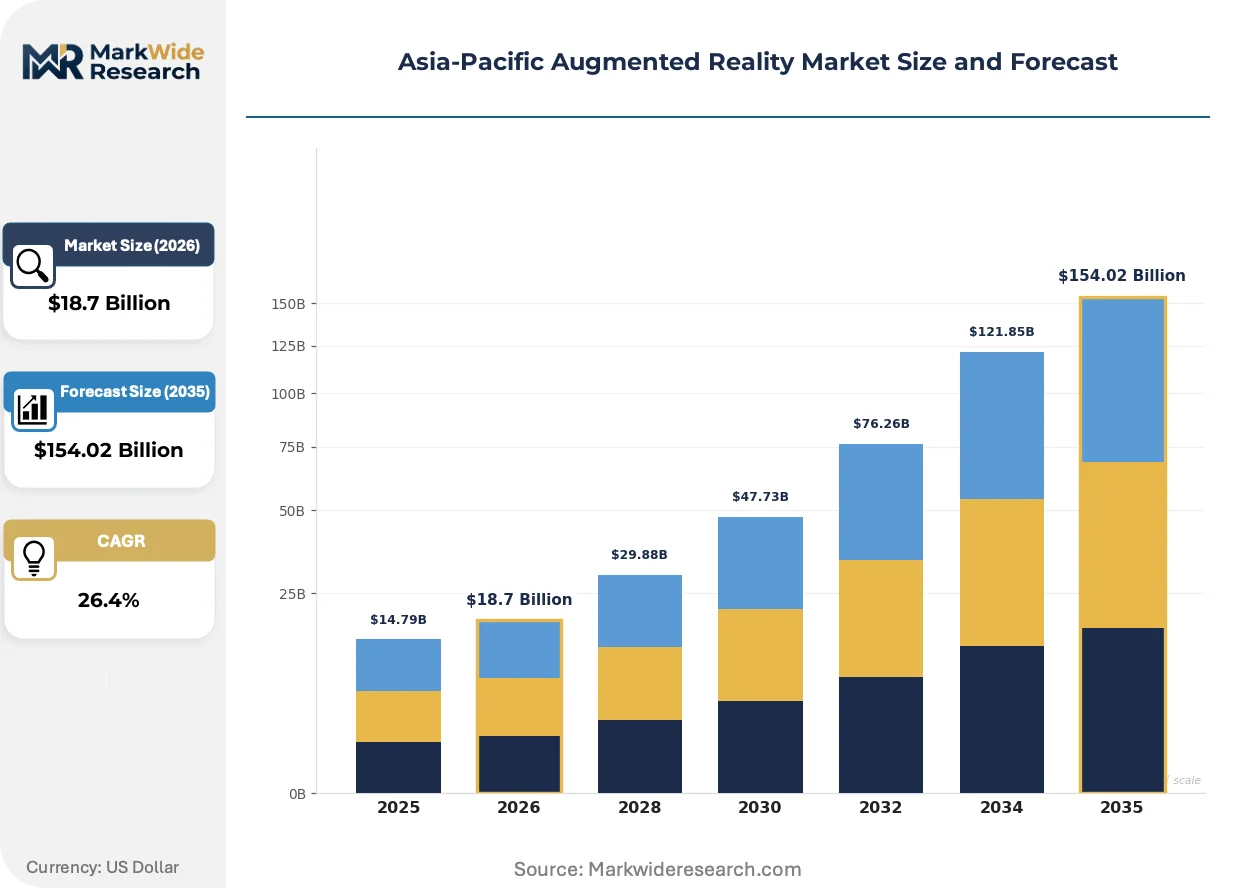
Market Dynamics
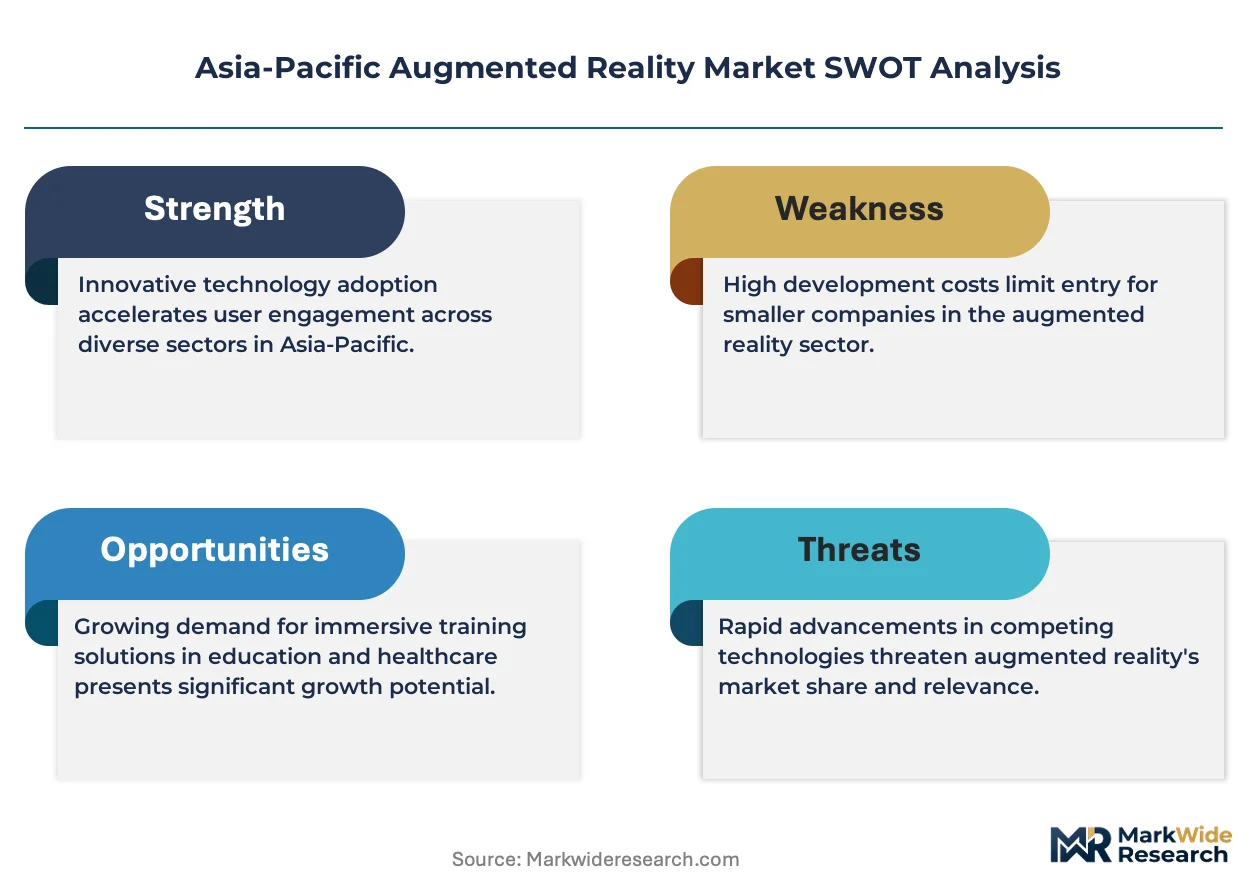
Optical waveguide adoption is compressing headset thickness and recalibrating manufacturing cost structures across Asia-Pacific assembly lines, forcing suppliers to retool from free-space optics to light-guide plate fabrication.
Growth Catalysts
- MIIT Wearable Interoperability Standards:China's GB certification framework accelerates hardware ecosystem compatibility, reducing integration friction for Shenzhen and Dongguan manufacturers.
- Enterprise Manufacturing Workflows:Japanese automotive and South Korean electronics assembly lines deploy AR-guided quality inspection systems to compress defect detection cycles.
- India PLI Electronics Manufacturing:The production-linked incentive scheme attracts display module and optical component foundries to establish captive supply near final assembly.
Market Restraints
- Micro-Display Supply Concentration:Taiwan and South Korea dominate compact OLED backplane fabrication, creating single-source vulnerability for headset makers.
- Motion-to-Photon Latency Thresholds:Sub-20 millisecond latency requirements demand specialized image signal processors, raising BOM costs for mid-tier devices.
- MFDS Medical Device Classification:South Korea's surgical AR tool regulations impose clinical validation timelines that delay hospital procurement by 18-24 months.
Strategic Opportunities
- Australia Healthcare Validation:Surgical navigation outcome studies in Sydney and Melbourne hospitals create reference sites for regional expansion.
- Spatial Computing Chip Convergence:Integration of dedicated neural processing units with optical engines enables on-device SLAM without cloud dependency.
- Industrial Smart Glasses Channel:Direct enterprise sales bypass consumer retail margin compression, targeting factory safety managers with all-day battery specifications.
Industry Challenges
- Optical Engineer Talent Scarcity:Waveguide design and freeform surface expertise concentrates in Japan and Germany, forcing regional OEMs to compete for limited specialist pools.
- Multi-Country Certification Complexity:Divergent electromagnetic compatibility testing between China's GB standards, Japan's JIS frameworks, and South Korea's KC marking fragments product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Augmented Reality Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $154.02 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Gaming, Retail, Education, Healthcare Technology: Marker-Based, Markerless, Projection-Based, Superimposition Device Type: Smart Glasses, Head-Mounted Displays, Smartphones, Tablets End User: Retailers, Educational Institutions, Healthcare Providers, Industrial Enterprises |
| Companies Covered | Samsung Electronics Co., Ltd., Sony Group Corporation, Lenovo Group Limited, Tencent Holdings Ltd., Alibaba Group Holding Limited, Huawei Technologies Co., Ltd., Rokid Corporation Ltd., Seiko Epson Corporation, Realmax Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Augmented Reality Market Evolving Landscape
Waveguide manufacturing is displacing refractive optics across premium headset tiers, while regulatory fragmentation and enterprise procurement centralization reshape competitive positioning.
Diffractive optical elements are expanding into waveguide substrates to achieve sub-3 millimeter thickness without sacrificing field-of-view. Japanese precision glass manufacturers and Chinese optical foundries in Suzhou scale etched surface production for 2025-2026 headset launches. This compression is expanding into consumer weight tolerance thresholds previously reserved for industrial smart glasses.
Japan's METI JIS standards for industrial AR eyewear in hazardous environments mandate impact resistance and chemical splash protection. Manufacturers serving automotive and chemical plants must certify to these specifications before factory safety managers approve procurement. South Korean electronics assemblers now specify JIS-compliant devices for cleanroom environments, creating cross-border standard adoption.
Enterprise buyers in China's Yangtze River Delta cluster consolidate vendor relationships through multi-year fleet deployment contracts. Procurement teams at Shanghai and Hangzhou manufacturers negotiate hardware-software bundles with centralized IT support, displacing fragmented pilot purchases. This concentration is most visible in automotive assembly, where single-source AR platform standardization reduces training overhead across multi-plant networks.
Asia-Pacific Augmented Reality Market Segmentation
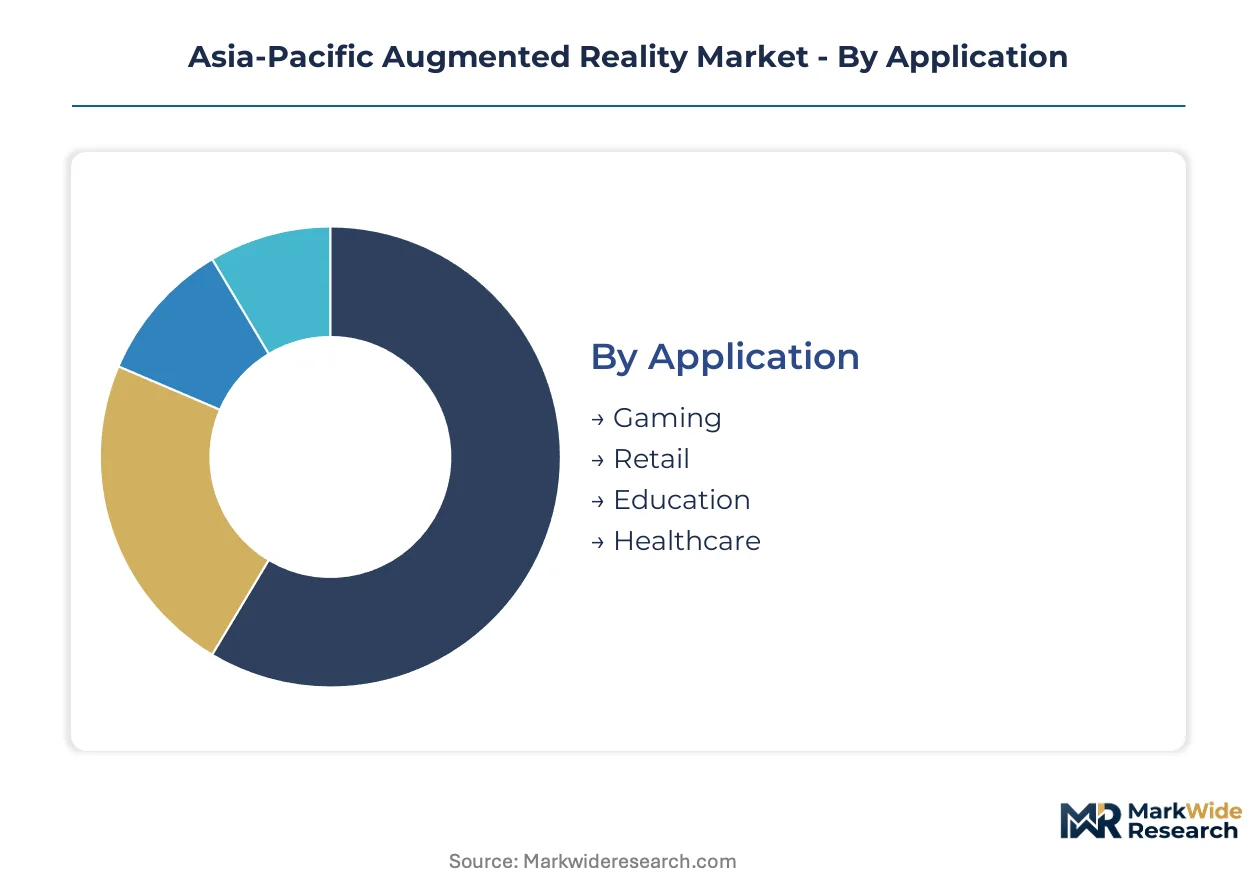
AR deployment patterns across Asia-Pacific diverge sharply by buyer sophistication, use-case criticality, and hardware tolerance. Segment boundaries matter because a surgical navigation procurement in Seoul follows entirely different technical specifications and validation timelines than a warehouse picking deployment in Shenzhen.
Application:
Gaming buyers prioritize refresh rate and field-of-view for immersion; healthcare procurement teams demand sub-millimeter tracking accuracy and clinical validation documentation.
- Gaming:Applications demand 90-120 Hz refresh rates and wide field-of-view optics to minimize motion sickness in extended sessions. Demand concentrates in China's tier-1 cities and South Korean PC bang culture, driven by 5G cloud gaming infrastructure rollouts and esports tournament sponsorships requiring spectator AR overlays.
- Healthcare:Surgical navigation and medical training applications require sub-millimeter spatial registration accuracy and electromagnetic compatibility certification for operating theater deployment. Australian hospitals in Sydney and Melbourne validate outcome metrics for regional expansion, while South Korea's MFDS imposes clinical validation timelines that delay procurement cycles.
- Retail:Virtual try-on and spatial commerce deployments focus on smartphone-based AR to avoid hardware distribution costs.
- Education:Institutional procurement emphasizes durability and content library depth over optical performance specifications.
Volume sits with Gaming; growth tilts toward Healthcare.
Technology:
Technical architecture choices determine whether deployments require controlled environments or function in variable industrial conditions.
- Markerless:Depth-sensing camera arrays and simultaneous localization and mapping algorithms enable deployment without physical fiducial markers. Sony Group Corporation dominates image sensor supply for these systems, with demand concentrating in Japanese automotive assembly lines and South Korean electronics manufacturing for quality inspection workflows.
- Marker-Based:Printed or projected fiducial tracking delivers cost-effective spatial registration for controlled environments. Chinese manufacturing facilities in the Yangtze River Delta cluster adopt these systems for assembly guidance where lighting conditions remain stable, driven by lower hardware costs and simplified calibration procedures.
- Projection-Based:Spatial light projection onto physical surfaces suits industrial workbench applications without wearable hardware.
- Superimposition:Object recognition and replacement techniques serve retail virtual try-on and architectural visualization use cases.
Markerless systems command premium pricing; marker-based deployments scale fastest in cost-sensitive industrial segments.
Device Type:
Wearable form factor selection trades optical performance against weight, battery endurance, and social acceptability thresholds.
- Head-Mounted Displays:Full-immersion headsets with waveguide or free-space optics deliver maximum field-of-view and spatial computing capability. Optical engine complexity sustains premium pricing, with demand concentrating in Japanese enterprise training programs and South Korean gaming cafes requiring high-fidelity experiences.
- Smart Glasses:Lightweight eyewear formats prioritize all-day battery endurance and ANSI Z87.1 safety compliance for industrial environments. Factory safety managers in Japan's automotive sector and China's electronics assembly plants specify JIS-compliant devices with impact resistance and chemical splash protection.
- Smartphones:Camera-fed AR through existing device penetration dominates consumer retail and casual gaming applications.
- Tablets:Larger screen formats suit collaborative design review and educational content consumption where hands-free operation is not required.
Head-Mounted Displays capture the highest revenue per unit; Smart Glasses are gaining share fastest in enterprise fleet deployments.
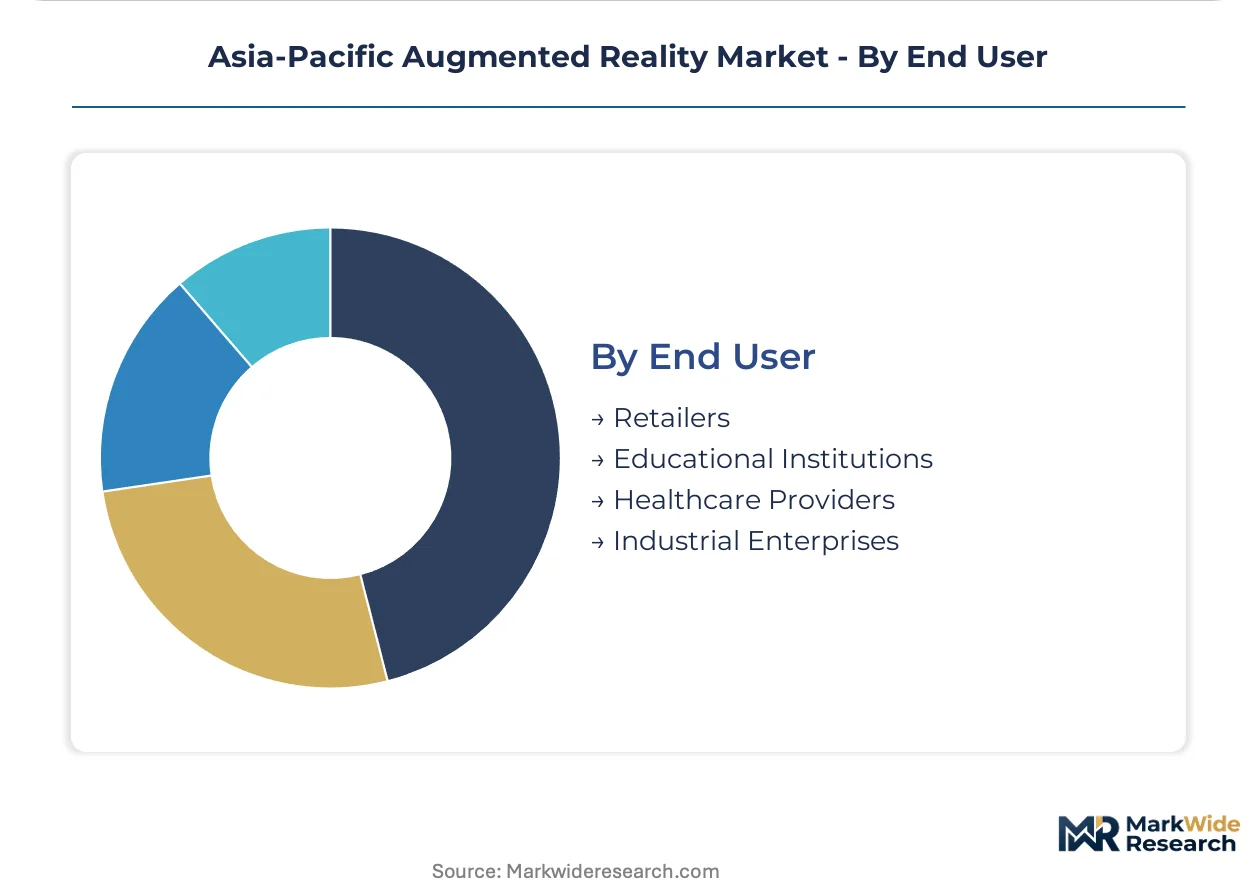
End User:
Procurement authority structures and budget cycles vary dramatically across buyer categories, from centralized IT to distributed operational budgets.
- Industrial Enterprises:Factory safety managers and operations directors control budgets for AR-guided assembly and quality inspection systems. Procurement in China's Yangtze River Delta cluster consolidates through multi-year fleet deployment contracts with hardware-software bundles, driven by single-source platform standardization across multi-plant automotive networks.
- Healthcare Providers:Hospital surgical committees and medical device procurement departments require clinical evidence and regulatory clearance. Australia's TGA validation pathways and South Korea's MFDS medical device classification create reference sites for regional expansion, though validation timelines extend procurement cycles.
- Retailers:Marketing and e-commerce teams drive smartphone-based AR investments with faster approval cycles than capital equipment.
- Educational Institutions:Ministry of Education procurement frameworks and institutional IT departments prioritize content ecosystem breadth and multi-year durability warranties.
Industrial Enterprises generate the highest contract values; Healthcare Providers show the steepest expansion trajectory as validation frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate optical component foundries and display module suppliers within 50 kilometers of final assembly plants, compressing logistics costs for AR headset production.
China
Shanghai and Suzhou house waveguide etching facilities serving domestic and export markets. MIIT enforces GB standards for electromagnetic compatibility and battery safety in wearable electronics. The Yangtze River Delta cluster spanning Hangzhou integrates optical engine suppliers with automotive AR deployment programs.
Japan
Tokyo and Osaka anchor precision glass manufacturing for diffractive optical elements. METI promotes JIS standards for industrial AR eyewear used in hazardous manufacturing environments. Nagoya automotive assembly lines deploy AR-guided quality inspection systems with sub-millimeter defect detection capabilities.
South Korea
Seoul Capital Area semiconductor foundries produce compact micro-display backplanes for partner OEMs. MFDS classifies certain AR-guided surgical tools as medical devices requiring clinical validation. Busan-Ulsan electronics manufacturers specify JIS-compliant devices for cleanroom assembly environments.
India
Bengaluru and Hyderabad software developers build enterprise AR applications for manufacturing clients. The PLI scheme for electronics manufacturing attracts display module suppliers to establish captive production. Tamil Nadu assembly plants near Chennai integrate imported optical engines with domestic plastic molding for cost-sensitive smart glasses.
Australia
Sydney and Melbourne hospitals validate surgical navigation outcome metrics for regional expansion reference sites. TGA validation pathways create clinical evidence frameworks for AR medical device procurement. Queensland mining operations pilot industrial smart glasses for remote equipment maintenance in hazardous terrain.
Asia-Pacific Augmented Reality Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated electronics conglomerates controlling component supply and software-defined specialists capturing enterprise application value. The market structure tiers into three strategic archetypes: semiconductor foundries with captive display backplane production, optical engine specialists with waveguide fabrication expertise, and enterprise software platforms with spatial computing stacks. Dominant competitive moves include backward integration into optical component supply and multi-year fleet deployment contracts with centralized IT support bundles.
Among Asia-Pacific electronics conglomerates, Samsung Electronics Co., Ltd. and Sony Group Corporation occupy positions spanning semiconductor supply and image sensor production. Huawei Technologies Co., Ltd. exemplifies the vertically integrated archetype combining proprietary spatial computing chips with enterprise software stacks. These three anchors represent distinct strategic postures: component supply dominance, sensor technology leadership, and full-stack platform integration.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Sony Group Corporation |
| Lenovo Group Limited |
| Tencent Holdings Ltd. |
| Alibaba Group Holding Limited |
| Huawei Technologies Co., Ltd. |
| Rokid Corporation Ltd. |
| Seiko Epson Corporation |
| Realmax Inc. |
| Others |
Value Network & Pricing Analysis
Electronics conglomerates with captive semiconductor foundries command upstream pricing leverage across Asia-Pacific AR headset production, compressing margins for pure-play optical engine specialists while sustaining premium positioning for integrated platform vendors.
Pricing Analysis
Short lead-time premiums of 15-25% apply to waveguide orders from Japanese precision glass manufacturers serving automotive AR programs in Nagoya. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified industrial eyewear from consumer gaming headsets and unbranded Shenzhen export units. Price differentiation hinges on GB certification tier for China market entry and volume scale for enterprise fleet contracts. Cost compression in mid-tier consumer devices intensifies as Taiwanese OLED backplane suppliers extend payment terms to anchor long-term offtake. Healthcare procurement committees in Seoul and Sydney show least price sensitivity due to clinical validation requirements, while Chinese electronics assemblers in Dongguan negotiate aggressively on per-unit hardware costs.
Supply Chain Analysis
Workforce availability for precision optics grinding and diffractive element etching concentrates in Japan's Tokyo-Osaka corridor and China's Suzhou industrial zone, creating talent competition between Sony Group Corporation's image sensor divisions and domestic waveguide startups. Geographic supply concentration centers on South Korea for micro-display backplanes, Japan for precision glass and image sensors, and China for final assembly and plastic molding. Raw material dependencies span rare-earth phosphors for micro-LED color conversion, high-index glass substrates for waveguide substrates, and specialized photoresists for diffractive optical element patterning. Single-source vulnerability runs through Taiwan and South Korea for compact OLED backplane fabrication. Distribution runs through direct enterprise sales channels for industrial fleet deployments and consumer electronics retail chains for gaming headsets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over spatial computing chips and optical engine supply determines margin capture, with Huawei Technologies Co., Ltd.'s in-house semiconductor production illustrating the downstream leverage available to full-stack platforms.
For Market Incumbents: Lock in multi-year fleet deployment contracts with centralized IT support bundles across China's Yangtze River Delta automotive networks before emerging optical engine specialists achieve scale. Backward integration into waveguide etching facilities in Suzhou or Shanghai insulates against Japanese precision glass supply constraints. Defend against substitute technologies like smartphone-based AR by emphasizing sub-20 millisecond motion-to-photon latency thresholds that mobile processors cannot yet achieve.
For New Entrants and Emerging Players: Markerless tracking algorithms optimized for variable industrial lighting conditions offer a technology-first wedge into Japanese automotive assembly lines currently dependent on marker-based systems. Australia's healthcare validation pathway for surgical navigation presents the most penetrable geography given TGA's outcome-based evidence frameworks and limited incumbent presence. Pursue direct enterprise sales to factory safety managers rather than competing through consumer retail channels where Samsung Electronics Co., Ltd. and Sony Group Corporation dominate shelf presence.
For Investors and Strategic Acquirers: Distressed-cycle entries favor optical engine specialists with waveguide fabrication expertise in Japan or Germany during periods when consumer headset demand softens and R&D budgets contract. Long-term viability over a 5-10 year window hinges on securing automotive or healthcare certification pipelines that sustain revenue through consumer cyclicality. Watch for MFDS medical device classification timeline compressions as the signal indicating hospital procurement acceleration in South Korea.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Waveguide Fabrication | Captive etching capacity in Suzhou reduces dependency on Japanese precision glass suppliers. |
| Spatial Computing Chip Convergence | On-device SLAM processing without cloud dependency addresses latency requirements in MFDS-regulated surgical tools. |
| Multi-Year Fleet Deployment Contracts | Centralized IT support bundles with Shanghai automotive manufacturers displace fragmented pilot purchases. |
| JIS Certification Investment | Impact resistance and chemical splash protection compliance unlocks procurement from Nagoya automotive safety managers. |
| Healthcare Validation Partnership | Sydney and Melbourne hospital outcome studies create reference sites for regional surgical navigation expansion. |
Research Methodology
Independent corroboration across optical component suppliers, enterprise AR deployment managers, and healthcare procurement committees underwrites the qualitative findings in this study. Primary interviews with waveguide design engineers, factory safety managers at Japanese automotive plants, hospital surgical committees in Australia, and MIIT certification specialists combined with secondary validation from SEC filings of listed electronics conglomerates, GB standards documentation, and TGA medical device registration databases. Bottom-up triangulation across component bill-of-materials estimates and top-down cross-checks against enterprise IT spending surveys anchored the market sizing.
Comparable-period anchoring to historical waveguide adoption curves and micro-display shipment data established the forecast baseline across the projection horizon. Segmentation dimensions modeled include device type, application vertical, technology architecture, and end-user procurement authority structure. CAGRs derived from fitted growth curves incorporating MIIT policy implementation timelines and PLI scheme uptake rates in India. Industry-specific forecast inputs encompass optical engineer talent pool constraints and multi-country certification complexity indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt MIIT regulatory revisions or MFDS medical device reclassification events. Forecasts reflect documented assumptions regarding waveguide yield rate improvements and enterprise fleet replacement cycles. Material deviation in sovereign technology export controls or rare-earth phosphor supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Florida Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Connected Service Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Somatosensory Virtual Fitting Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Industrial AR Platforms Market
Virtual Reality (VR) and Augmented Reality (AR)
VR HMD Shipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Location-Based VR Entertainment Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Content Creation Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Firefighter Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive Augmented Reality (AR) HUD System Market
Virtual Reality (VR) and Augmented Reality (AR)
VR All-In-One Headset Market