
 VR All-In-One Headset Market | 2026-2036
VR All-In-One Headset Market Size, Share, and Industry Trends Forecast 2026-2036
VR All-In-One Headset Market Insights
Subscription-based content ecosystems is decoupling hardware margins from long-term revenue streams in the VR all-in-one headset space. Meta leverages its social platform integration to anchor recurring software revenue alongside device sales. PICO competes through aggressive content licensing and regional storefront expansion. ByteDance sustains user engagement via short-form video-to-VR pipeline investments that differentiate its ecosystem approach.
A VR all-in-one headset integrates compute, display, battery, and tracking sensors into a single untethered wearable, typically employing pancake lenses and proprietary ASICs to achieve sub-20ms motion-to-photon latency for nausea-free immersion. Its primary commercial purpose is delivering spatial computing without external PCs or base stations, reducing deployment friction for enterprise and consumer applications. Standalone configurations now dominate volume shipments as wireless fidelity and on-device rendering improve, while healthcare and training applications within the end-user dimension command premium pricing due to compliance requirements and custom software integration. OLED technology leads in high-end segments for contrast performance, though LCD panels with local dimming are displacing premium share on cost efficiency.
FCC equipment authorization and FDA 510(k) clearances for therapeutic VR applications create dual compliance pathways that filter market entrants in the United States. EMA and EU AI Act risk classifications for biometric data processing in immersive environments add European regulatory complexity for eye-tracking and neural input features. China's MIIT radio transmission standards and NMPA medical device rules further fragment certification requirements. Stakeholders must monitor how divergent electromagnetic exposure limits and data governance frameworks reshape hardware architecture decisions and geographic rollout sequencing.
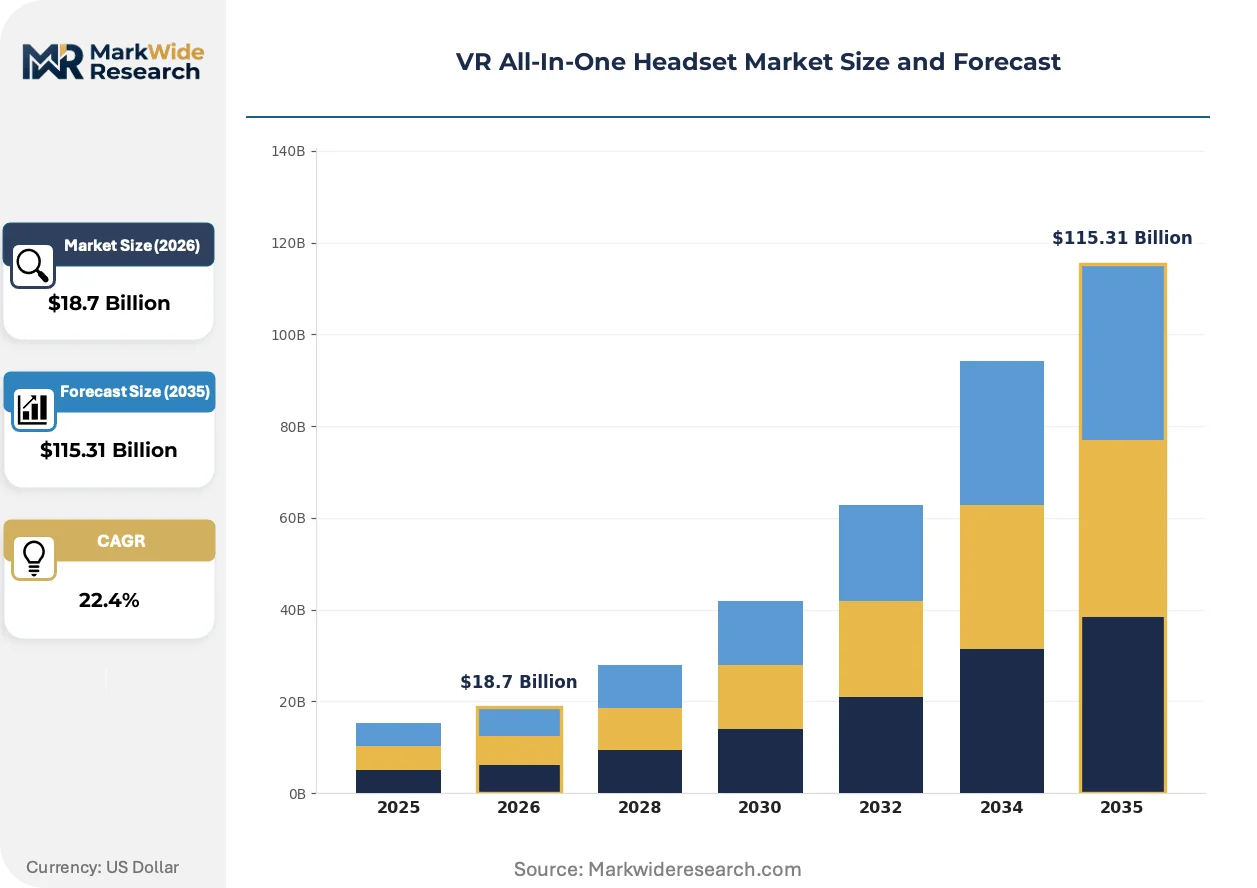
Market Dynamics
Enterprise procurement of untethered immersive systems is compressing refresh cycles as logistics and defense training programs mandate sub-20ms latency without external base stations. Shenzhen's integrated supply chains for pancake optics and custom silicon now dictate hardware certification timelines globally.
Growth Catalysts
- MIIT Near-Eye Display Standards:China's mandatory latency benchmarks and electromagnetic exposure limits are accelerating hardware refresh cycles as manufacturers redesign ASICs to meet certification thresholds.
- Pancake Optics Manufacturing:Shenzhen's captive production of folded optical paths reduces device thickness and weight, enabling multi-hour enterprise training deployments without neck strain.
- Defense Training Mandates:Military procurement specifications for standalone immersive systems are creating volume anchors that subsidize consumer-tier component costs through shared supply chains.
Market Restraints
- Custom Silicon Concentration:Proprietary ASIC design for motion-to-photon processing concentrates in two foundry clusters, creating single-source vulnerability for sub-20ms latency chipsets.
- FDA 510(k) Timeline Friction:Therapeutic VR applications require 12-18 month clearance pathways that filter smaller entrants from healthcare premium segments.
- Biometric Data Governance:EU AI Act risk classifications for eye-tracking and neural input features impose compliance costs that compress margins on mid-tier hardware.
Strategic Opportunities
- Surgical Training Simulation:Unmet demand for haptic-integrated standalone systems in accredited medical residency programs commands pricing multiples above consumer hardware.
- India PLI Scheme Eligibility:Local assembly incentives for electronics manufacturing could anchor South Asian distribution hubs with reduced import duty exposure.
- Short-Form Video Pipeline Convergence:Content ecosystems that bridge 2D mobile consumption to spatial computing are capturing first-time VR users through familiar interface metaphors.
Industry Challenges
- Optomechanical Talent Scarcity:The intersection of precision lens design and thermal management for pancake optics exceeds available engineering capacity in most hardware clusters.
- Dual Certification Burden:Simultaneous FCC equipment authorization and FDA therapeutic clearances require parallel documentation streams that extend time-to-revenue by 8-14 months.
- Legacy Enterprise Integration:Standalone headsets must interface with existing learning management systems and security protocols that predate spatial computing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR All-In-One Headset Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Tethered, Integrated, Hybrid End User: Gaming, Education, Healthcare, Training Technology: OLED, LCD, 6DoF, Spatial Audio Application: Entertainment, Therapy, Simulation, Social Interaction |
| Companies Covered | Meta, PICO, HTC, DPVR, Xiaomi, Skyworth Digital, NOLO, ByteDance, Valve, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR All-In-One Headset Market Trends and Innovations
Pancake lens architectures and proprietary motion-processing silicon are compressing form factors while regulatory fragmentation across medical and consumer pathways is reshaping certification strategies. Demand concentration in enterprise training is decoupling volume from consumer price elasticity.
Folded optical path designs using polarization-based light recycling are electrifying the transition from Fresnel to pancake lens systems. Defense contractors and medical simulation vendors are adopting these configurations within 18-month procurement windows. The technology is electrifying a segmentation between sub-250 gram enterprise headsets and legacy consumer bulk.
China's MIIT radio transmission standards and NMPA medical device rules are creating divergent electromagnetic exposure limits that force hardware architecture forks. Manufacturers now maintain separate SKU lineages for domestic Chinese therapeutic deployment versus export markets. The EU AI Act biometric data classifications are compounding this fragmentation for eye-tracking features.
Enterprise learning departments are consolidating vendor relationships through multi-year immersive training subscriptions that bundle hardware refresh guarantees. Logistics operators in North America and defense agencies in Western Europe are displacing per-unit procurement with outcome-based deployment contracts. This shift is most visible in German automotive training centers and US military maintenance simulation programs.
VR All-In-One Headset Market Segmentation
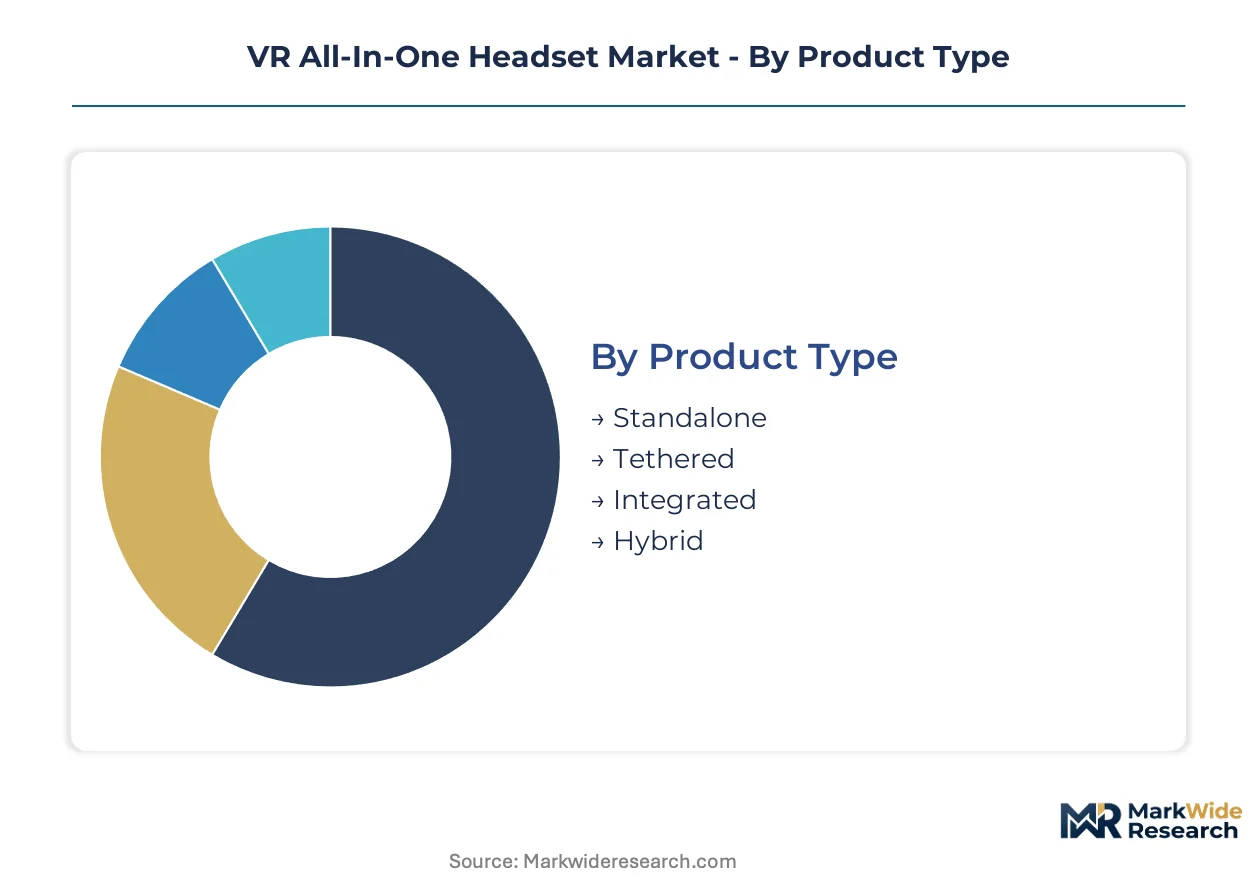
Segmentation in the VR all-in-one headset market determines which certification pathways manufacturers must navigate. Product architecture and end-use application dictate whether FDA 510(k), FCC equipment authorization, or MIIT electromagnetic standards apply.
Product Type:
FCC equipment authorization applies universally, while FDA 510(k) clearance becomes mandatory only when therapeutic claims attach to the hardware. Standalone configurations face the most stringent MIIT near-eye display latency benchmarks in China.
- Standalone:Integrated compute, display, battery, and tracking sensors eliminate external PCs or base stations. Defense training programs in the United States and logistics operators in Germany are consolidating procurement around these untethered systems to reduce deployment friction. FCC authorization and FDA therapeutic pathways run in parallel for medical variants, extending time-to-revenue.
- Tethered:Relies on external processing units via cable connection, trading mobility for rendering fidelity. Enterprise simulation vendors in France maintain legacy deployments where graphics throughput exceeds standalone capability. These configurations avoid MIIT radio transmission standards but still require electromagnetic compliance testing.
- Integrated:Embedded systems designed for fixed installations with captive power and data infrastructure. Automotive training centers in Germany specify these for assembly line simulation cells where device portability is unnecessary.
- Hybrid:Modular architectures allowing standalone or tethered operation through docked configurations. Healthcare systems in Japan favor these for flexible deployment across inpatient and outpatient therapeutic settings.
Standalone sits at the top of the volume ranking, with Hybrid climbing the fastest as healthcare systems seek deployment flexibility.
End User:
Margin structures diverge sharply across end-use categories, with healthcare and training commanding premium pricing due to compliance burdens and custom software integration.
- Gaming:Consumer entertainment applications drive shipment volume through price-sensitive mass-market channels. Content ecosystems from social platform operators subsidize hardware margins through recurring software revenue. FCC equipment authorization represents the sole regulatory hurdle for most SKUs.
- Education:K-12 and university deployments prioritize durability and content library breadth over technical specifications. State procurement frameworks in the United States favor vendors with established learning management system integrations. Pricing compresses under volume purchasing agreements.
- Healthcare:Therapeutic applications require FDA 510(k) clearance or EMA medical device certification, filtering smaller entrants from premium segments. Surgical training simulation commands pricing multiples above consumer hardware due to haptic integration requirements and accreditation standards.
- Training:Corporate and defense immersive programs mandate sub-20ms motion-to-photon latency without external infrastructure. German automotive manufacturers and United States military maintenance programs are displacing per-unit procurement with multi-year outcome-based contracts.
Training commands the steepest expansion trajectory, with Healthcare anchoring the highest average selling prices.
Technology:
Display technology selection determines thermal management complexity and supply chain sourcing, with OLED panels concentrating in high-end segments and LCD with local dimming displacing premium share on cost efficiency.
- OLED:Organic light-emitting diode panels deliver superior contrast ratios and faster pixel response times. High-end enterprise headsets for medical visualization and defense simulation specify these despite higher unit costs and shorter lifespans under continuous operation.
- LCD:Liquid crystal displays with mini-LED backlighting or local dimming zones approach OLED contrast performance at reduced cost. Shenzhen manufacturing clusters have scaled these configurations for mid-tier enterprise training deployments.
- 6DoF:Six degrees of freedom tracking enables positional movement within virtual environments through integrated cameras and IMU fusion. This capability is now baseline across enterprise procurement specifications in Western Europe.
- Spatial Audio:Head-related transfer function processing creates three-dimensional soundscapes without external speakers. Defense training simulations in the United States require these for situational awareness exercises.
LCD dominates shipment volume, with Spatial Audio gaining share fastest as immersive training applications mature.
Application:
Application category determines whether hardware ships as general consumer electronics or regulated medical devices, with therapy and simulation carrying the heaviest documentation burdens.
- Entertainment:Gaming, streaming, and social VR experiences operate under standard consumer electronics regulatory frameworks. Content licensing investments from platform operators drive ecosystem lock-in more than hardware differentiation.
- Therapy:Pain management, exposure therapy, and cognitive rehabilitation applications trigger FDA 510(k) or NMPA medical device classification. Hardware must demonstrate clinical efficacy through controlled trials, extending development cycles.
- Simulation:Flight, surgical, and maintenance training environments require precise haptic feedback and sub-20ms latency guarantees. German automotive OEMs and United States defense agencies specify these for accredited certification programs.
- Social Interaction:Virtual meeting spaces and collaborative workspaces emphasize avatar fidelity and spatial audio presence. Enterprise IT departments in Japan are piloting these for distributed engineering teams.
Entertainment holds the volume lead, with Simulation expanding most quickly as defense and industrial training budgets reallocate toward immersive systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting final assembly toward jurisdictions with streamlined electromagnetic certification pathways. Shenzhen's integrated pancake optics corridors now supply hardware destined for divergent compliance regimes across three continents.
United States
Defense training mandates from the Department of Defense and logistics operators are consolidating procurement around standalone systems with sub-20ms latency guarantees. FDA 510(k) clearance timelines for therapeutic VR applications extend 12-18 months, filtering smaller entrants from healthcare premium segments. Austin and Seattle hardware engineering clusters concentrate on haptic-integrated surgical simulation systems.
China
MIIT near-eye display standards and NMPA medical device rules are forcing hardware architecture forks between domestic and export SKUs. ByteDance and PICO anchor content ecosystem investments through short-form video-to-VR pipeline convergence. Shenzhen's captive pancake optics production and custom silicon foundry partnerships compress development cycles for both consumer and enterprise tiers.
Germany
Automotive OEM training centers specify integrated VR installations for assembly line simulation cells where device portability is unnecessary. EU AI Act biometric data classifications for eye-tracking features compound compliance costs for mid-tier hardware deployments. Bavarian industrial clusters coordinate multi-year outcome-based contracts displacing per-unit procurement.
Japan
Healthcare systems favor hybrid architectures allowing flexible deployment across inpatient and outpatient therapeutic settings. METI standards for electromagnetic exposure in near-eye displays align with PMDA medical device pathways for pain management applications. Tokyo-Osaka engineering corridors concentrate on optomechanical talent for precision lens thermal management.
India
Electronics manufacturing incentives under the PLI scheme could anchor South Asian distribution hubs with reduced import duty exposure. State procurement frameworks for educational VR prioritize durability and learning management system integrations over technical specifications. Karnataka and Tamil Nadu assembly clusters are evaluating component localization for mid-tier enterprise training hardware.
VR All-In-One Headset Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform operators capturing recurring software revenue while hardware fabricators compete on certification speed and supply chain integration. The vendor base concentrates around three strategic archetypes: social platform-anchored ecosystems, enterprise-focused hardware specialists, and contract manufacturers serving white-label demand. M&A activity targets haptic integration capabilities and therapeutic software pipelines. Vertical integration into custom silicon design is emerging as a defensive maneuver against foundry concentration risks.
Within the platform-anchored ecosystem tier, Meta and ByteDance exemplify the content-revenue model where hardware margins are subsidized by recurring software streams. PICO occupies a position representing aggressive regional storefront expansion and content licensing investments. Among hardware-centric specialists, HTC and Valve sit within the premium-tier vector emphasizing precision tracking and enterprise simulation credibility. DPVR, Xiaomi, and Skyworth Digital represent scale-driven manufacturing archetypes leveraging Shenzhen supply chain proximity for cost-efficient volume production.
| Leading Market Players |
|---|
| Meta |
| PICO |
| HTC |
| DPVR |
| Xiaomi |
| Skyworth Digital |
| NOLO |
| ByteDance |
| Valve |
| Others |
Pricing and Supply Chain Analysis
Captive integration into Shenzhen's pancake optics corridors anchors both supply security and pricing power for tier-one manufacturers, while export-market SKUs absorb certification-driven cost premiums that domestic Chinese variants avoid. This bifurcation concentrates margin leverage among vertically integrated platform operators with parallel FDA and MIIT certification pipelines.
Pricing Analysis
Distributor margins compress as direct-to-enterprise procurement displaces channel-heavy consumer sales, with defense training contracts and automotive simulation programs negotiating volume guarantees that strip retail markups entirely. Pricing stratifies across FDA-cleared therapeutic tiers, FCC-authorized enterprise tiers, and mass-market consumer tiers, with certification grade and haptic integration level as the primary price differentiation drivers. Cost compression in mid-tier LCD configurations intensifies because Shenzhen manufacturing clusters have scaled mini-LED backlighting at yields that undercut OLED premium positioning. Education sector procurement exhibits highest price sensitivity due to state framework volume purchasing, while surgical training simulation commands lowest sensitivity given accreditation requirements and haptic system bundling.
Supply Chain Analysis
Refurbishment flows for enterprise training hardware extend asset lifecycles through certified remanufacturing programs that redeploy units across secondary logistics and defense maintenance programs. Supply concentrates in China, Taiwan, and South Korea, with pancake lens substrates and custom motion-processing ASICs drawing from captive foundry partnerships in the Greater Bay Area. Single-source vulnerability for sub-20ms latency chipsets creates structural risk as proprietary designs concentrate in two foundry clusters. Distribution runs through direct OEM relationships for enterprise and defense tiers, while consumer channels leverage e-commerce platforms and electronics retail chains with regional storefront expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pancake optics yield improvements and custom silicon design maturation are compressing bill-of-materials costs, enabling margin expansion even as competitive pressure intensifies in consumer tiers.
For Market Incumbents: Acquire haptic integration specialist firms to preempt surgical training simulation entrants from locking up accredited residency program relationships. Defensive consolidation around therapeutic software pipelines filters smaller competitors from FDA 510(k) premium segments, while backward integration into custom ASIC design mitigates foundry concentration risk that threatens sub-20ms latency guarantees. For New Entrants and Emerging Players: India's PLI scheme eligibility for electronics manufacturing opens a window for South Asian assembly operations with reduced import duty exposure versus direct China-origin shipments. White-space targets include state educational procurement frameworks prioritizing learning management system integrations over technical specifications, and hybrid-architecture healthcare deployments in Japan seeking flexible inpatient-outpatient configurations. Go-to-market positioning should emphasize outcome-based training contracts that displace per-unit procurement in German automotive and US defense channels. For Investors and Strategic Acquirers: Consolidation pressure builds where optomechanical talent scarcity exceeds available engineering capacity for precision lens thermal management. Long-term viability favors platform-anchored ecosystems with recurring software revenue streams over pure hardware fabricators exposed to component cost volatility. Acquisition target archetypes include enterprise-focused specialists with established FDA 510(k) pipelines and haptic-integrated surgical simulation credibility. Signal to watch: defense procurement specification shifts toward standalone immersive systems with refresh cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Haptic Specialist | Surgical training accreditation demands integrated force-feedback systems that differentiate premium tiers. |
| Custom ASIC Design Investment | In-house motion-processing silicon mitigates single-source foundry vulnerability for latency-critical chipsets. |
| Dual Certification Pipeline | Parallel FDA 510(k) and MIIT compliance tracks filter competitors from therapeutic and Chinese domestic markets. |
| Outcome-Based Contract Transition | German automotive and US defense procurement shifts from per-unit to multi-year deployment guarantees. |
| Regional Storefront Expansion | PICO and ByteDance content licensing investments capture first-time VR users through familiar interface metaphors. |
Research Methodology
Bottom-up enterprise training procurement modeling reconciled against top-down Shenzhen manufacturing output tracking forms the analytical core of this study. Primary interviews with defense acquisition officers, automotive simulation directors, hospital biomedical engineers, and electronics manufacturing executives combined with secondary validation against MIIT certification databases, FDA 510(k) filings, and customs trade records. Triangulation across component bill-of-materials analysis and end-user deployment surveys ensures segmentation integrity across standalone, tethered, integrated, and hybrid product architectures.
Historical trendline analysis of refresh cycle compression in enterprise immersive training programs informs the projection framework across the analysis window. Segmentation dimensions modeled include product type, end-use application, display technology tier, and regional regulatory cluster, with CAGR derivation anchored in defense procurement mandate trajectories and healthcare therapeutic adoption curves. Forecast inputs incorporate pancake optics yield maturation timelines and custom silicon foundry capacity expansion patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MIIT electromagnetic standard revisions or FDA therapeutic clearance timeline extensions. Practitioners should monitor defense procurement specification shifts, PLI scheme eligibility rulings, and EU AI Act biometric data enforcement actions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR Display Market
Virtual Reality (VR) and Augmented Reality (AR)
Tourists Virtual Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Market
Virtual Reality (VR) and Augmented Reality (AR)
India Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Location-Based Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Mirror Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality Display Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Construction Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Book Market
Virtual Reality (VR) and Augmented Reality (AR)
Consumer Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) in Healthcare Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Metaverse Market